
 Chronic Lymphocytic Leukemia Market | 2026-2036
Chronic Lymphocytic Leukemia Market Size, Share, and Industry Trends Forecast 2026-2036
Chronic Lymphocytic Leukemia Market Intelligence
The availability of patent-protected targeted therapies versus off-patent chemotherapy agents is repositioning the treatment landscape for chronic lymphocytic leukemia. This shift creates distinct value tiers based on clinical efficacy and patient outcomes. AbbVie leverages its leadership in BTK inhibitors, while F. Hoffmann-La Roche specializes in monoclonal antibody combinations. AstraZeneca competes with a portfolio spanning both targeted agents and immunotherapies, navigating the complex reimbursement environment across different geographies.
Chronic lymphocytic leukemia is a hematological malignancy characterized by the proliferation of mature but dysfunctional B-lymphocytes, often expressing the CD5 surface protein. Therapeutic interventions aim to control cancer cell growth, manage symptoms, and improve progression-free survival. Targeted therapies represent the fastest-growing product type, displacing traditional chemotherapy agents due to superior efficacy and safety profiles. Within therapy areas, first-line treatment protocols increasingly incorporate these novel agents over older standards of care.
Market access is governed by stringent regulatory approvals from bodies like the US Food and Drug Administration (FDA) and the European Medicines Agency (EMA). These agencies, along with China's National Medical Products Administration (NMPA), set the standards for clinical trial data required for new drug approvals. Consequently, strategic investment in robust clinical development programs to meet diverse regulatory expectations remains critical for securing market authorization and favorable reimbursement.
Market Dynamics
The displacement of traditional chemotherapy by patent-protected targeted therapies is the central force shaping the chronic lymphocytic leukemia market. This transition redefines clinical pathways, creating a clear value distinction between novel agents and older, off-patent cytotoxic drugs.
Growth Catalysts
- Accelerated Approval Pathways:Favorable regulatory frameworks from agencies like the US FDA and EMA provide expedited routes for innovative CLL therapies that address unmet medical needs, speeding market entry.
- Genomic Profiling Advances:Increased use of next-generation sequencing helps stratify patients based on genetic markers like TP53 mutation, guiding the selection of targeted therapies for improved outcomes.
- Aging Demographics:The rising median age in developed nations like Japan and Germany increases the incident population for CLL, a disease predominantly diagnosed in older adults, thereby expanding the treatable patient pool.
Market Restraints
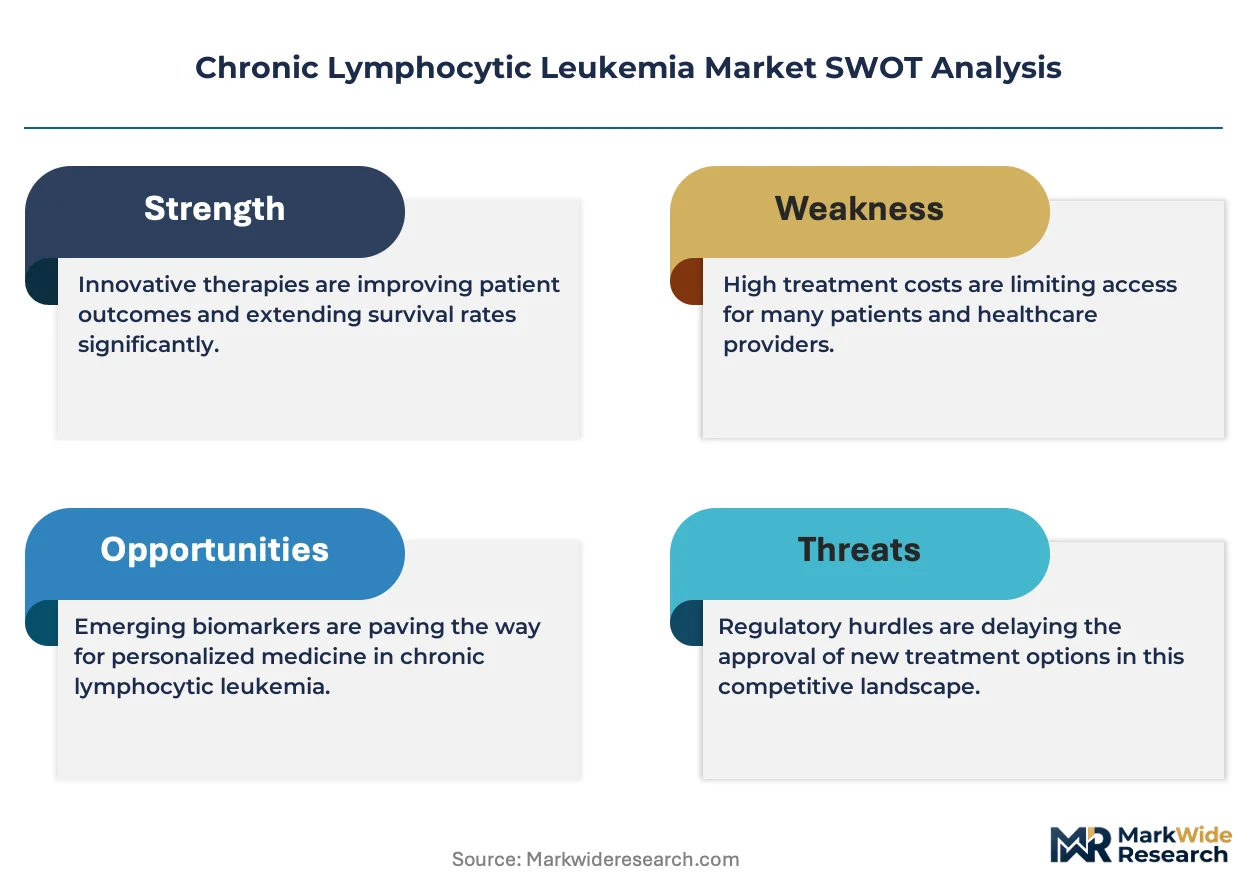
- High Treatment Costs:The substantial price of novel targeted therapies and combination regimens creates significant reimbursement hurdles and limits patient access, particularly in healthcare systems with strict budget controls.
- Acquired Drug Resistance:The eventual development of resistance to BTK inhibitors and BCL-2 inhibitors remains a significant clinical challenge, necessitating sequential therapies and further research into resistance mechanisms.
- Stringent Clinical Endpoints:Regulatory bodies require demonstration of significant improvements in progression-free or overall survival, setting a high bar for new drug approvals and increasing clinical trial complexity.
Strategic Opportunities
- Asia-Pacific Market Expansion:Significant opportunity exists in expanding access to novel therapies in large markets such as China, where rising healthcare expenditure and NMPA reforms are improving the environment for innovative drugs.
- Richter's Transformation Therapies:Developing effective treatments for Richter's transformation, an aggressive lymphoma that can arise from CLL, represents a critical unmet need and a high-value therapeutic area.
- Novel Combination Regimens:Exploring synergistic combinations of existing targeted agents, monoclonal antibodies, and emerging cell therapies offers a pathway to deeper, more durable responses.
Industry Challenges
- Specialized Talent Shortages:A scarcity of hematology-oncology specialists and clinical research associates trained in complex trial designs hinders patient recruitment and slows down the execution of pivotal studies.
- Reimbursement Negotiation Complexity:Securing favorable reimbursement and market access requires navigating disparate health technology assessment processes across European countries and among US payers.
- Intellectual Property Litigation:Heightened competition in the BTK inhibitor class is leading to an increase in patent disputes, creating legal uncertainty and potential commercial risks for manufacturers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Chronic Lymphocytic Leukemia Market |
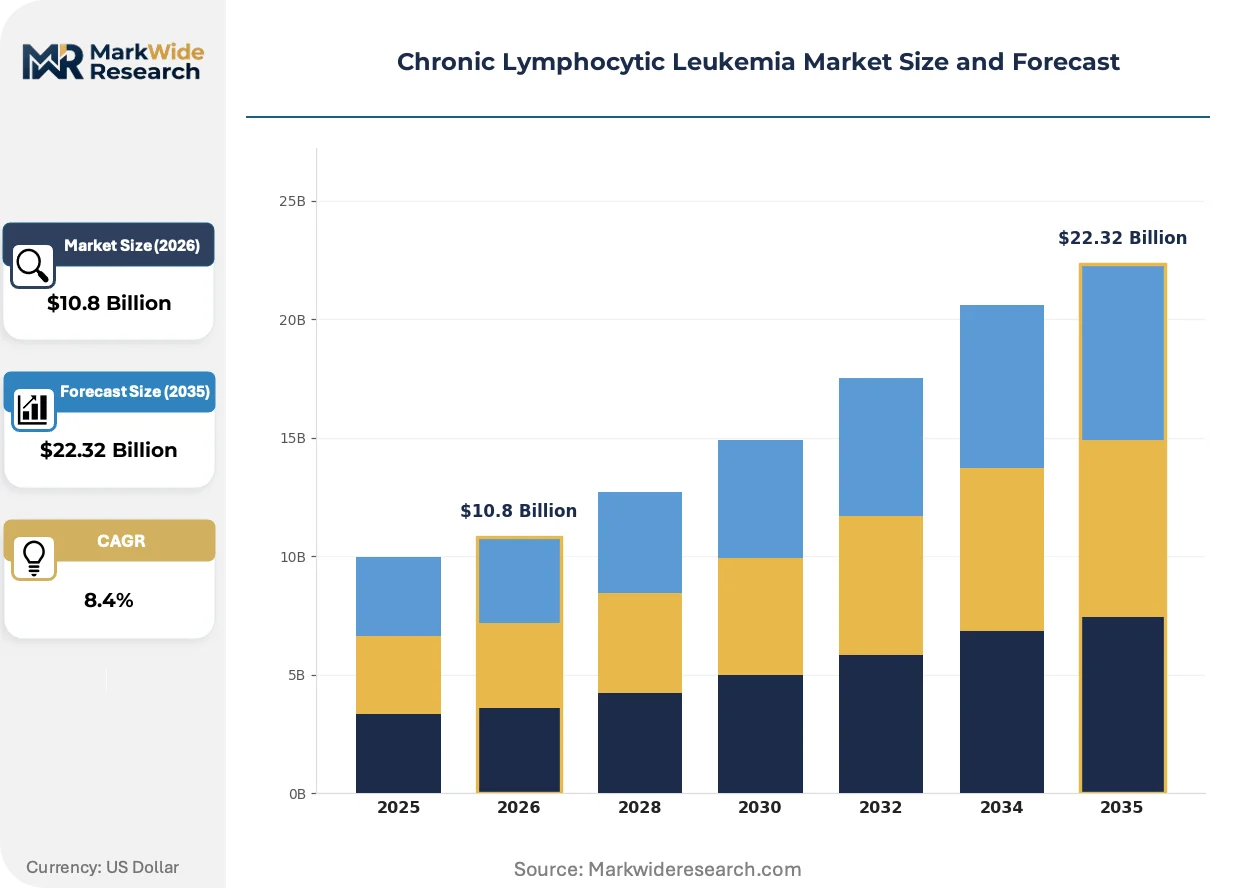
| Market Size in 2026 | $10.8 Billion |
| Market Size in 2035 | $22.32 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Chemotherapy Agents, Targeted Therapies, Immunomodulators, Hematopoietic Stem Cell Transplants Therapy Area: First-Line Treatment, Relapsed/Refractory, Maintenance Therapy, Palliative Care End User: Specialty Clinics, Academic Medical Centers, Diagnostic Labs, Research Institutions Delivery Mode: Oral Administration, Intravenous Infusion, Subcutaneous Injection, Intramuscular Injection |
| Companies Covered | AbbVie, F. Hoffmann-La Roche, AstraZeneca, Gilead Sciences, Novartis, BeiGene, Bristol Myers Squibb, Johnson & Johnson, Sanofi, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Chronic Lymphocytic Leukemia Market Strategic Shifts & Innovations
Precision medicine is fundamentally altering treatment paradigms in chronic lymphocytic leukemia. The integration of advanced diagnostics and molecular profiling enables a more personalized therapeutic approach, moving beyond a one-size-fits-all model toward patient-specific intervention strategies.
AI-powered analytical platforms interpret complex genomic and proteomic data from CLL patients. Major oncology centers and research consortia are increasingly adopting these systems to stratify patient risk profiles. This technology is automating the identification of individuals likely to experience rapid disease progression, thereby enabling earlier and more tailored therapeutic interventions.
The European Medicines Agency's PRIority MEdicines (PRIME) scheme provides early and enhanced scientific and regulatory support. This initiative accelerates the evaluation of promising drugs that target significant unmet needs in CLL. Developers of cell therapies and novel agents for relapsed/refractory patient populations are most affected, aligning clinical strategies to meet PRIME criteria.
A pronounced shift toward value-based healthcare frameworks is influencing treatment selection and procurement. Payers are moving beyond simple fee-for-service models, demanding evidence of cost-effectiveness and linking reimbursement to clinical outcomes like progression-free survival. This trend is most evident in the United States and several European Union member states.
Chronic Lymphocytic Leukemia Market Segmentation
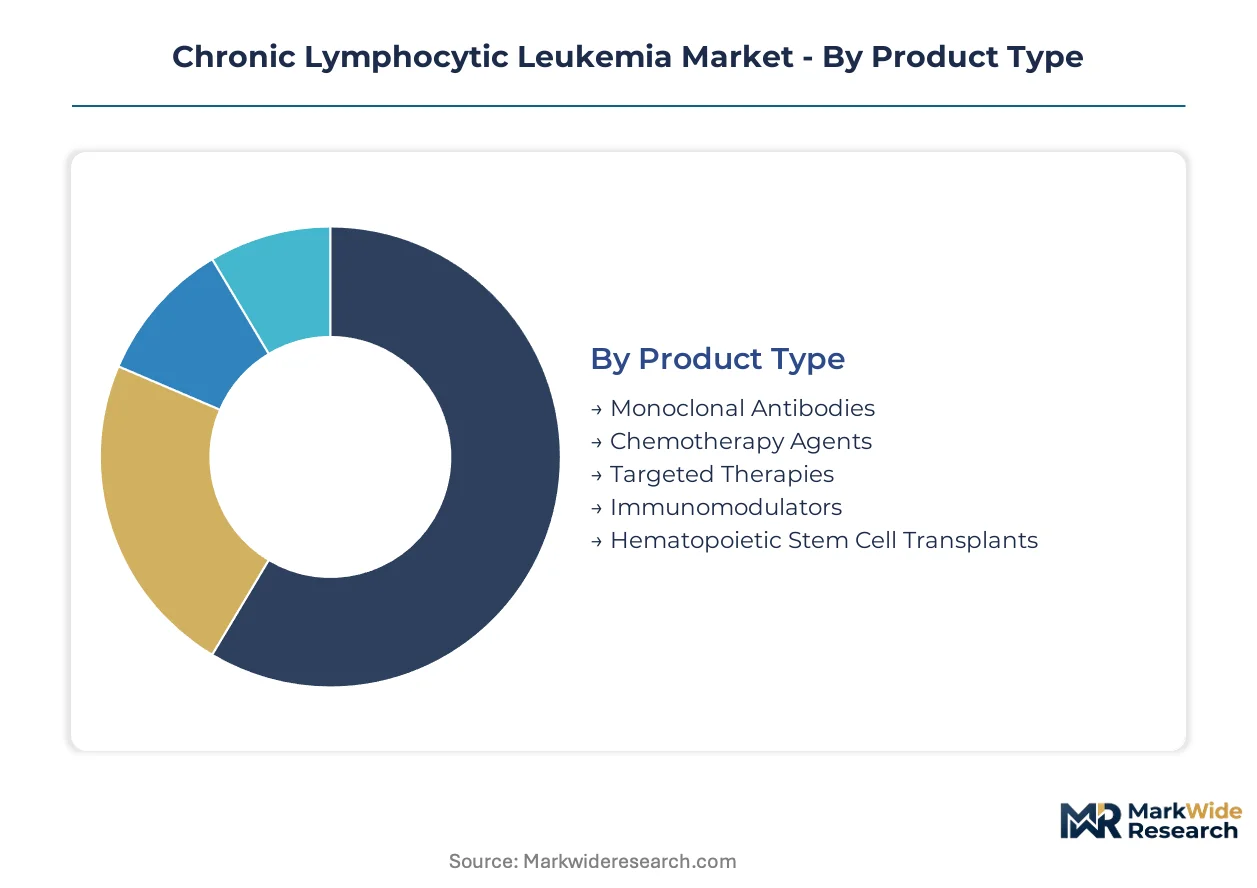
Understanding the Chronic Lymphocytic Leukemia market through segmentation highlights diverse patient needs and treatment preferences. This granular view enables pharmaceutical companies to tailor product development and market access strategies. It also assists healthcare providers in optimizing treatment protocols based on specific disease characteristics and patient profiles.
Product Type:
The choice of product type in CLL treatment is primarily driven by clinical efficacy, safety profiles, and the patient's disease stage.
- Targeted Therapies:These agents specifically block molecular pathways involved in CLL cell growth and survival, such as BTK inhibitors and BCL-2 inhibitors. Demand for these therapies is concentrating in developed markets like the United States due to their superior efficacy and improved safety over traditional chemotherapy.
- Monoclonal Antibodies:These biologics target specific proteins on CLL cells, such as CD20, leading to cell destruction through various immune mechanisms. Demand is strong in combination regimens across European healthcare systems, driven by their synergistic effects with other targeted agents.
- Chemotherapy Agents:Traditional cytotoxic drugs kill rapidly dividing cells, including CLL cells, but often come with significant side effects.
- Immunomodulators:These agents modify the immune system's response to cancer, offering alternative mechanisms for disease control.
- Hematopoietic Stem Cell Transplants:This intensive procedure replaces diseased bone marrow with healthy stem cells, typically reserved for younger patients with high-risk disease.
Targeted Therapies lead on scale; Monoclonal Antibodies lead on momentum.
Therapy Area:
Segmentation by therapy area reflects the different stages of disease progression and the clinical goals at each point of intervention.
- First-Line Treatment:This segment includes initial therapies administered after a CLL diagnosis, often incorporating novel agents for improved progression-free survival. Adoption of these novel agents is accelerating in Germany, where advanced diagnostic capabilities support early stratification.
- Relapsed/Refractory:This category addresses patients whose disease has returned or failed to respond to prior treatments, necessitating more aggressive or alternative therapeutic approaches. Clinical trials for Richter's transformation therapies are particularly focused on this challenging patient population.
- Maintenance Therapy:These treatments aim to prevent disease recurrence or progression after initial successful therapy.
- Palliative Care:This area focuses on symptom management and improving quality of life for patients with advanced or incurable CLL.
First-Line Treatment represents the largest application segment; Relapsed/Refractory treatment shows the steepest expansion trajectory.
End User:
The end-user segment delineates where CLL treatments are primarily administered, reflecting specialized care requirements and infrastructure.
- Specialty Clinics:These facilities offer specialized care for hematological malignancies, providing access to advanced diagnostics and novel therapies. Utilization of these clinics is particularly high in the United States, driven by their expertise in managing complex CLL cases.
- Academic Medical Centers:These institutions combine patient care with medical research, often leading clinical trials for new CLL treatments. These centers attract patients seeking cutting-edge therapies and participate in significant research initiatives in Japan.
- Diagnostic Labs:These facilities perform molecular profiling and other tests crucial for CLL diagnosis and treatment selection.
- Research Institutions:These organizations focus on understanding CLL biology and developing innovative therapeutic strategies.
Specialty Clinics command the largest patient volume; Academic Medical Centers are gaining share fastest due to research contributions.
Delivery Mode:
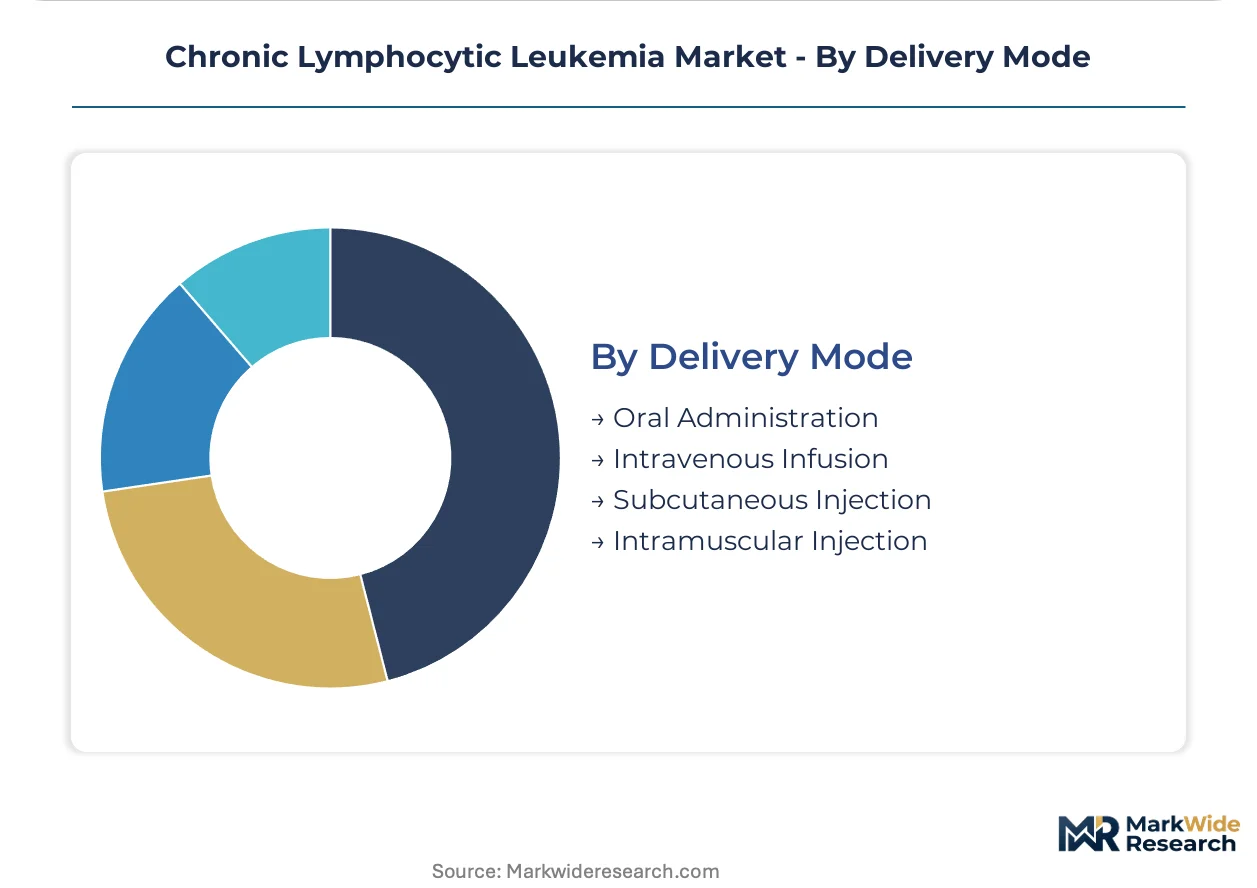
The delivery mode segment considers the method by which CLL therapies are administered, impacting patient convenience and treatment adherence.
- Oral Administration:These therapies are taken by mouth, offering significant convenience for patients and enabling at-home treatment. The shift towards oral agents is pronounced in countries like Canada, supporting patient autonomy and reducing clinic visits.
- Intravenous Infusion:These treatments are administered directly into a vein, typically requiring administration in a clinic or hospital setting. Complex monoclonal antibodies and some chemotherapy agents frequently utilize this mode of delivery in France.
- Subcutaneous Injection:These injections are given under the skin, offering a less invasive alternative to intravenous infusions for some biologics.
- Intramuscular Injection:This mode involves injecting medication into a muscle, less common for chronic CLL treatments.
Oral Administration offers the greatest patient convenience; Intravenous Infusion remains critical for complex biologics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
While the United States drives significant demand for novel CLL therapies, Germany demonstrates rapid adoption of first-line treatments. This difference reflects varying healthcare system priorities and regulatory environments. Advanced healthcare infrastructures across developed nations support the uptake of complex oncology interventions.
United States
Demand for targeted therapies concentrates in the United States due to its advanced healthcare infrastructure. The US Food and Drug Administration (FDA) facilitates quicker market access for innovative treatments through accelerated approval pathways. Specialty clinics across major metropolitan areas like New York and Boston show high utilization for complex CLL cases.
Germany
Germany accelerates the adoption of novel agents in first-line treatment protocols, supported by advanced diagnostic capabilities. The European Medicines Agency (EMA) frameworks ensure high standards for clinical trial data for new drug approvals. Academic medical centers in cities such as Heidelberg and Munich lead early patient stratification efforts.
Japan
Japan's aging demographics contribute to an expanding treatable patient pool for chronic lymphocytic leukemia. The Pharmaceuticals and Medical Devices Agency (PMDA) sets rigorous standards for drug evaluation, influencing market entry. Research initiatives in Tokyo and Kyoto academic medical centers attract patients seeking cutting-edge therapies.
China
Market expansion opportunities exist in China, driven by rising healthcare expenditure and National Medical Products Administration (NMPA) reforms. The NMPA's evolving regulatory landscape improves the environment for innovative drug approvals. Major oncology centers in Shanghai and Beijing are adopting novel therapies for a growing patient base.
France
French healthcare systems frequently utilize intravenous infusion for complex monoclonal antibodies in CLL treatment regimens. European Medicines Agency (EMA) guidelines influence drug procurement and administration protocols. Hospitals and specialized cancer centers in Paris and Lyon manage the delivery of these critical biologics.
Chronic Lymphocytic Leukemia Market Key Industry Players
Top-tier vendors anchor the chronic lymphocytic leukemia market, while specialized biotechs and mid-sized pharmaceutical firms contribute significantly to innovation. The market structure reflects a tiered landscape with distinct value propositions for novel agents versus traditional treatments. Strategic archetypes include established pharmaceutical giants, innovative biotech disruptors, and emerging cell therapy developers. Dominant competitive moves involve portfolio diversification into novel targeted agents and strategic partnerships for global market access and clinical development.
Within the established pharmaceutical giants tier, AbbVie exemplifies leadership in BTK inhibitors, reflecting a strong focus on patent-protected targeted therapies that redefine clinical pathways. F. Hoffmann-La Roche occupies a significant position through its specialization in monoclonal antibody combinations, often utilized in synergistic regimens within European healthcare systems. AstraZeneca, another major player, represents a diversified portfolio spanning both targeted agents and immunotherapies, actively navigating complex reimbursement environments across multiple geographies to secure market authorization and favorable patient access in critical markets.
| Leading Market Players |
|---|
| AbbVie |
| F. Hoffmann-La Roche |
| AstraZeneca |
| Gilead Sciences |
| Novartis |
| BeiGene |
| Bristol Myers Squibb |
| Johnson & Johnson |
| Sanofi |
| Others |
Cost & Logistics Intelligence
Large pharmaceutical corporations, with their extensive R&D investments, dictate supply behavior and pricing discipline in the chronic lymphocytic leukemia market. Patent protection for novel targeted therapies significantly influences market access and cost structures.
Pricing Analysis
Bundled diagnostic services and patient support programs increasingly complement core drug sales in the chronic lymphocytic leukemia market. Value-based pricing and long-term contract models dominate, reflecting the high clinical efficacy of novel agents. Price differentiation stems from superior safety profiles and favorable reimbursement status, especially for first-line therapies. Pricing pressure arises from payer scrutiny over high costs, with healthcare systems demonstrating the highest price sensitivity.
Supply Chain Analysis
Stringent regulatory certifications from agencies like the FDA, EMA, and NMPA gate entry and production in the chronic lymphocytic leukemia supply chain. Supply concentration centers on major pharmaceutical manufacturing hubs in the United States, Germany, and Switzerland, relying heavily on specialized biologics manufacturing inputs and high-purity small molecule APIs. Single-source API vulnerability represents a key structural risk. Distribution primarily runs through specialized pharmacy networks and hospital formularies.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The chronic lymphocytic leukemia market presents a late-cycle quality story, driven by a demand-shift toward premium targeted therapies. This transition emphasizes clinical efficacy and improved patient outcomes over traditional cytotoxic agents.
For Market Incumbents:Anticipate increased competition from novel therapies by diversifying research pipelines into next-generation BTK and BCL-2 inhibitors. Reinforce market leadership through strategic partnerships for global market access and expanded clinical development. This proactive stance mitigates threats from emerging biotech disruptors and potential patent expiry.
For New Entrants and Emerging Players:Begin with targeting unmet medical needs such as Richter's transformation or specific high-risk genetic subsets within the relapsed/refractory segment. Focus on Asia-Pacific markets, leveraging NMPA reforms for expedited approvals. A precision diagnostics integration strategy offers a strong go-to-market angle.
For Investors and Strategic Acquirers:Valuations sit cheapest among specialized biotechs with early-stage clinical assets demonstrating strong efficacy signals. The long-term viability of the CLL market hinges on sustained innovation in targeted therapies and cell therapies for an aging population. Watch for successful Phase 3 clinical trial readouts for novel mechanisms of action as a key inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Clinical Trial Advancement | Expediting pivotal studies for novel agents secures earlier market authorization from regulatory bodies. |
| Manufacturing Scale-Up | Increasing production capacity for biologics and targeted therapies meets rising global patient demand. |
| Pipeline Diversification | Investing in distinct therapeutic classes reduces reliance on single-mechanism treatments. |
| Licensing Agreement | Securing rights to promising early-stage compounds expands a company's future treatment portfolio. |
| Regulatory Approval Pathway | Navigating expedited routes like FDA's accelerated approval speeds patient access to innovative drugs. |
Research Approach
Bottom-up patient population modeling reconciled against top-down pharmaceutical manufacturer tracking forms the analytical core for this study. Primary interviews with hematology-oncology specialists, payer access managers, and pharmaceutical R&D executives provided critical insights. Secondary validation drew from FDA filings, EMA submissions, clinical trial registries, and company annual reports.
Historical trendline analysis established foundational market dynamics across the analysis window through extrapolation and regression techniques. Segmentation dimensions modeled included product type, therapy area, end user, delivery mode, and regional regulatory clusters. Compound annual growth rates were derived from weighted averages of market drivers. Disease incidence rates and evolving treatment guideline changes served as key forecast inputs.
Several conditions sit outside the modeled scope, including unforeseen global health crises or radical shifts in healthcare policy. Forecasts reflect assumptions regarding regulatory stability and sustained R&D investment. A model refresh is warranted upon material change in major clinical trial outcomes or significant regulatory changes.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Global Scleroderma Diagnostics and Therapeutics Market
Specialty Medicine
Global Autism Spectrum Disorders Market
Specialty Medicine
Global Bladder Disorders Market
Specialty Medicine
Musculoskeletal System Disorders Market
Specialty Medicine
North America Alopecia Market
Specialty Medicine
Myelofibrosis Market
Specialty Medicine
Multiple Endocrine Neoplasia Market
Specialty Medicine
Vertigo Market
Specialty Medicine
Complement 3 Glomerulopathy (C3G) Market
Specialty Medicine
Wilms Tumor Treatment Market
Specialty Medicine
Vertebral Radiculopathy Market
Specialty Medicine
Global Postmenopausal Osteoporosis Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Toxoplasmosis Treatment Market
Specialty Medicine
Nephrogenic Systemic Fibrosis (NSF) Treatment Market
Specialty Medicine
Global Epilepsy Market