
 Global Polycystic Ovarian Syndrome Treatment Market | 2026-2036
Global Polycystic Ovarian Syndrome Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Polycystic Ovarian Syndrome Treatment Market Foresight
Aftermarket patient support programs is rewriting how pharmaceutical firms capture lifetime value in hormonal therapy management. Bayer AG leverages its endocrinology heritage to sustain brand loyalty across insulin sensitizer portfolios. Teva Pharmaceutical Industries Ltd anchors its position through generic oral contraceptive scale and cost-competitive manufacturing. Sanofi competes via metabolic syndrome control combinations that integrate lifestyle intervention protocols.
Polycystic Ovarian Syndrome treatment encompasses pharmacological and non-pharmacological interventions targeting hyperandrogenism, ovulatory dysfunction, and insulin resistance in reproductive-age women; formulations range from ethinyl estradiol-progestin combinations to metformin hydrochloride and gonadotropin injectables, with dosing regimens calibrated to individual hormonal profiles and fertility objectives. The primary commercial purpose centers on restoring menstrual regularity, reducing hirsutism progression, and enabling conception for infertility patients. Insulin sensitizers command durable margin pools as first-line metabolic management expands beyond diabetes protocols into gynecology clinics. Oral contraceptives retain volume leadership through menstrual regulation prescriptions, while gonadotropins capture premium positioning within fertility center infertility management workflows.
The FDA oversees reproductive therapeutic approvals and post-market surveillance for hormonal agents, while the EMA's centralized procedure governs contraceptive and fertility drug authorizations across EU member states; REACH compliance additionally shapes excipient sourcing and manufacturing standards for European supply chains. India's CDSCO regulates domestic insulin sensitizer formulations under its pharmaceutical quality framework. Stakeholders must monitor how evolving FDA guidance on combination therapy safety profiles and EMA pharmacovigilance updates reshape clinical trial investments and label expansion strategies.
Market Dynamics
Patient stratification by metabolic phenotype is restructuring prescription protocols across gynecology and endocrinology practices, forcing pharmaceutical portfolios to align with insulin resistance severity rather than symptom severity alone.
Growth Catalysts
- FDA Reproductive Health Guidance:Accelerated approval pathways for combination hormonal therapies are compressing clinical trial timelines and expanding label indications for metabolic comorbidity management.
- Fertility Center Expansion:Specialized reproductive clinics in the United States and Germany are integrating insulin sensitizer protocols into ovarian stimulation workflows, creating dedicated prescription channels.
- Continuous Glucose Monitoring Integration:Wearable metabolic tracking devices are enabling real-time dosing adjustments for metformin and inositol formulations, improving therapeutic adherence.
Market Restraints
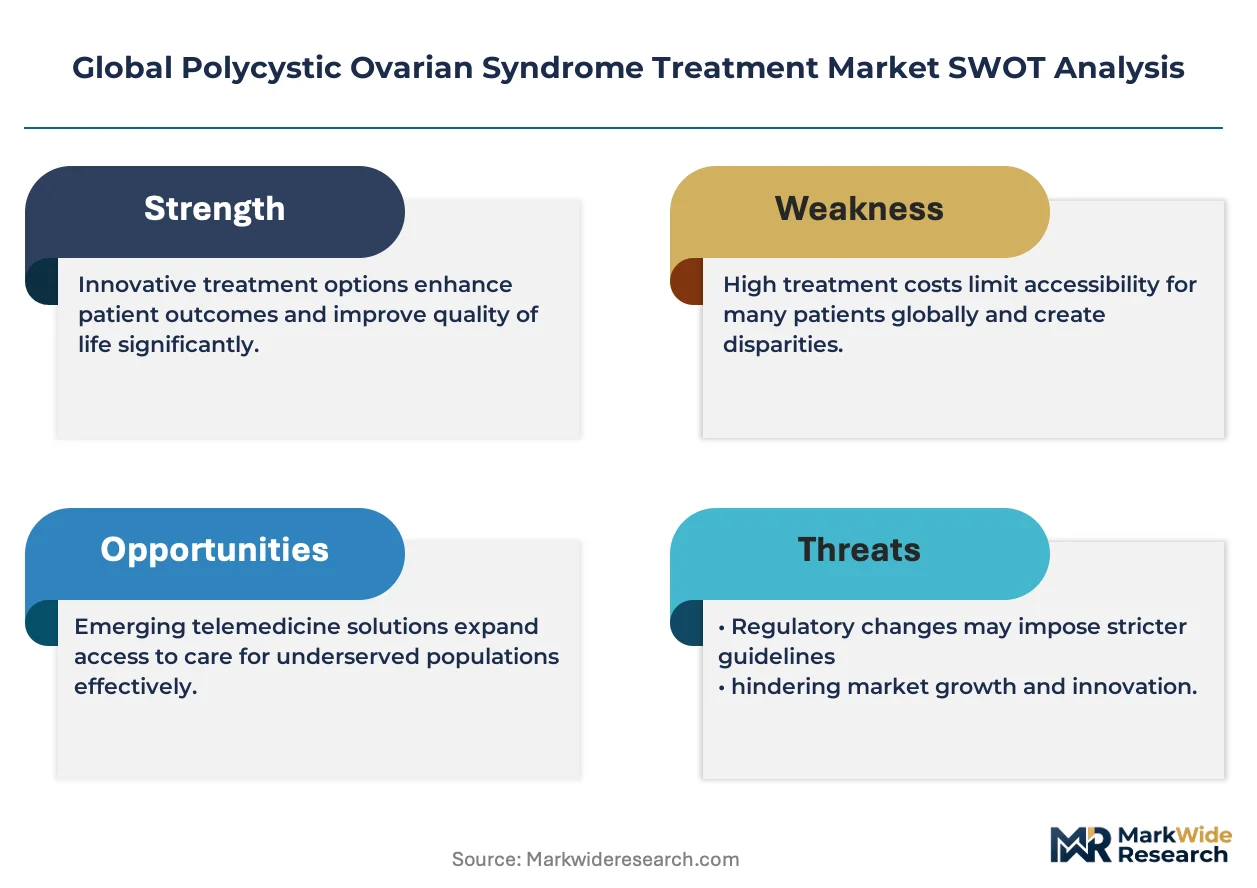
- API Concentration Risk:Metformin hydrochloride active pharmaceutical ingredient production concentrates in Chinese and Indian chemical manufacturing clusters, exposing supply chains to geopolitical friction.
- Reimbursement Fragmentation:Germany's G-BA and France's HAS maintain divergent assessment criteria for fertility drug coverage, forcing parallel health technology assessment submissions.
- Generic Oral Contraceptive Saturation:Patent-expired ethinyl estradiol-progestin combinations face price erosion from multi-source generic competition, compressing originator margins.
Strategic Opportunities
- Brazil's ANVISA Fast-Track:The regulator's priority review for women's health therapeutics offers accelerated market entry for novel insulin sensitizers targeting metabolic syndrome overlap.
- Telemedicine Prescription Channels:Virtual gynecology platforms in the United States are enabling direct-to-patient distribution of lifestyle intervention bundles paired with hormonal therapy.
- Nutraceutical-Pharmaceutical Convergence:Myo-inositol and D-chiro-inositol formulations are bridging dietary supplement and prescription boundaries, creating hybrid regulatory positioning.
Industry Challenges
- Reproductive Endocrinology Talent Scarcity:Fellowship-trained specialists capable of integrating metabolic and fertility protocols remain concentrated in academic medical centers, limiting protocol standardization.
- Multi-Jurisdiction Label Harmonization:Divergent EMA and FDA requirements for long-term cardiovascular safety data extend development timelines and increase trial costs.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Polycystic Ovarian Syndrome Treatment Market |
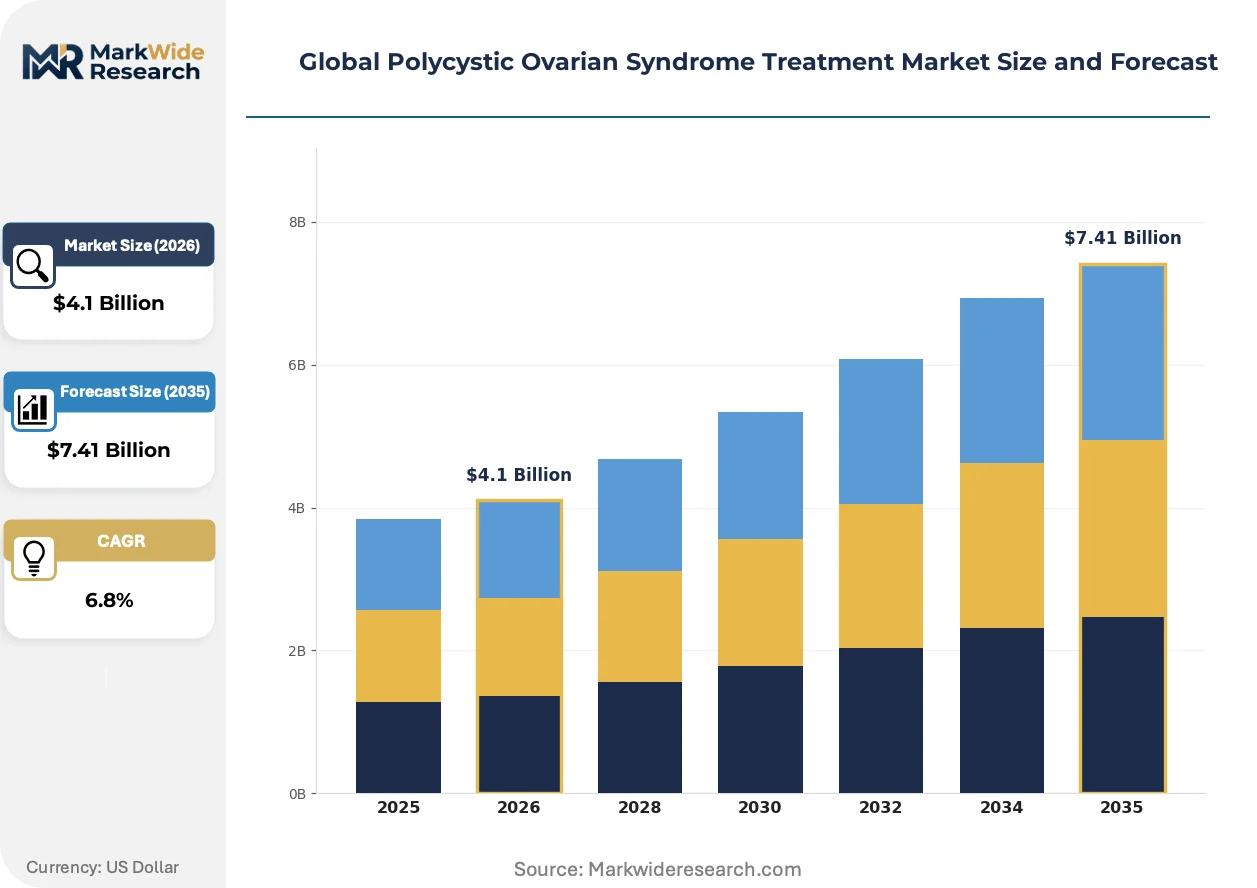
| Market Size in 2026 | $4.1 Billion |
| Market Size in 2035 | $7.41 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
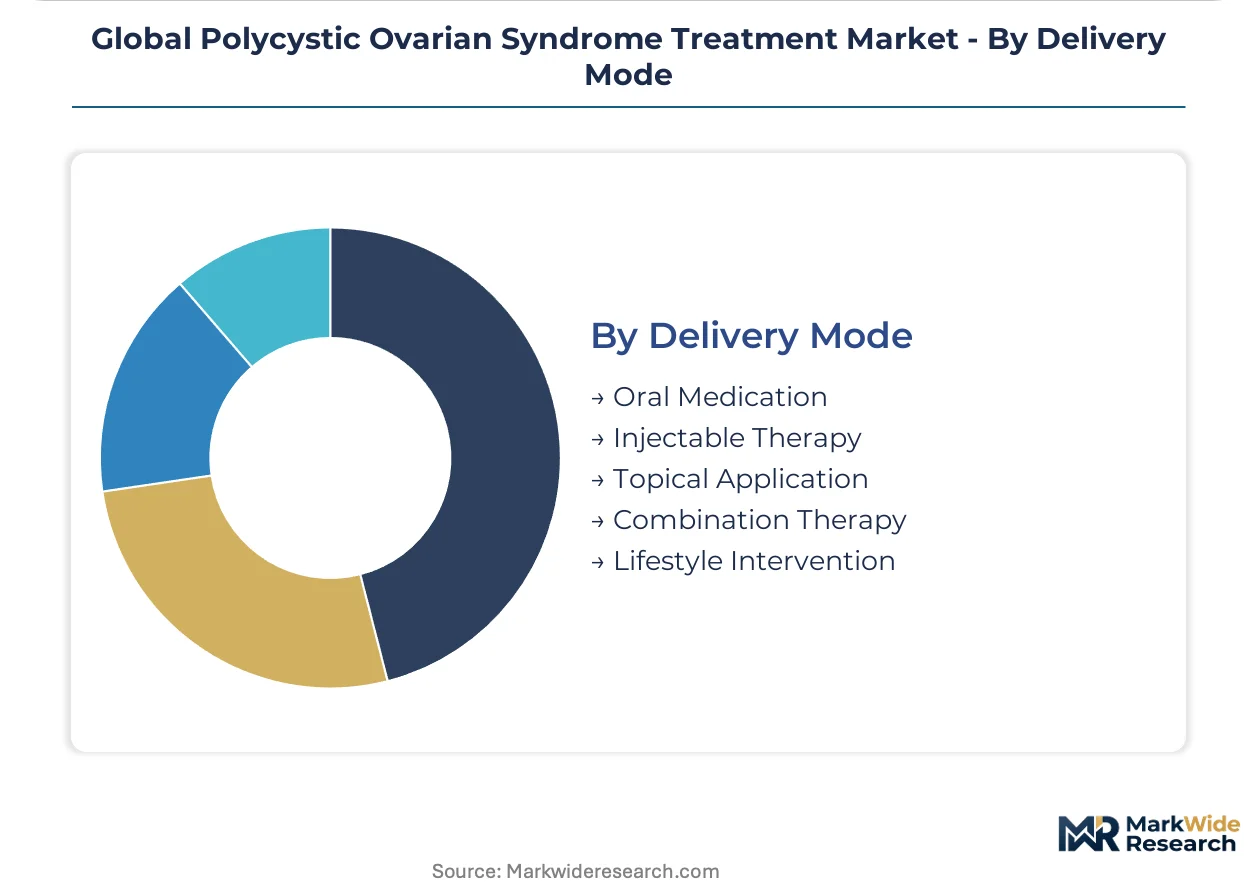
| Segmentation | Product Type: Oral Contraceptives, Insulin Sensitizers, Anti-Androgens, Clomiphene Citrate, Gonadotropins Therapy Area: Ovulation Induction, Menstrual Regulation, Hyperandrogenism, Infertility Management, Metabolic Syndrome Control End User: Gynecology Clinics, Fertility Centers, Diagnostic Laboratories, Research Institutes, Telemedicine Providers Delivery Mode: Oral Medication, Injectable Therapy, Topical Application, Combination Therapy, Lifestyle Intervention |
| Companies Covered | AstraZeneca, Bayer AG, Pfizer Inc., Abbott Laboratories, Novartis AG, Merck KGaA, Teva Pharmaceutical Industries Ltd, Sanofi, Bristol Myers Squibb Company, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Polycystic Ovarian Syndrome Treatment Market Shifts & Advancements
Digital biomarker integration and personalized hormonal profiling are displacing one-size-fits-all dosing regimens, while regulatory frameworks scramble to accommodate real-world evidence generation.
Pharmacogenomic testing for CYP450 enzyme variants is hybridizing with standard-of-care metformin prescribing. Fertility centers in the United States and the Netherlands are adopting rapid genetic screening to predict insulin sensitizer response rates. This convergence is compressing trial-and-error dosing periods and enabling earlier intervention switches.
EMA's evolving pharmacovigilance requirements for combined hormonal contraceptives are mandating enhanced thromboembolic risk surveillance across EU member states. Manufacturers must now submit periodic safety update reports with real-world data from national health registries. The requirement is most burdensome for progestin-only formulations seeking expanded metabolic indications.
Subscription-based medication management is replacing traditional pharmacy dispensing for chronic PCOS patients. United States-based digital health platforms bundle oral contraceptives, insulin sensitizers, and lifestyle coaching into recurring delivery models. This shift is most pronounced among patients aged 25-34 seeking integrated rather than episodic care.
Global Polycystic Ovarian Syndrome Treatment Market Segmentation
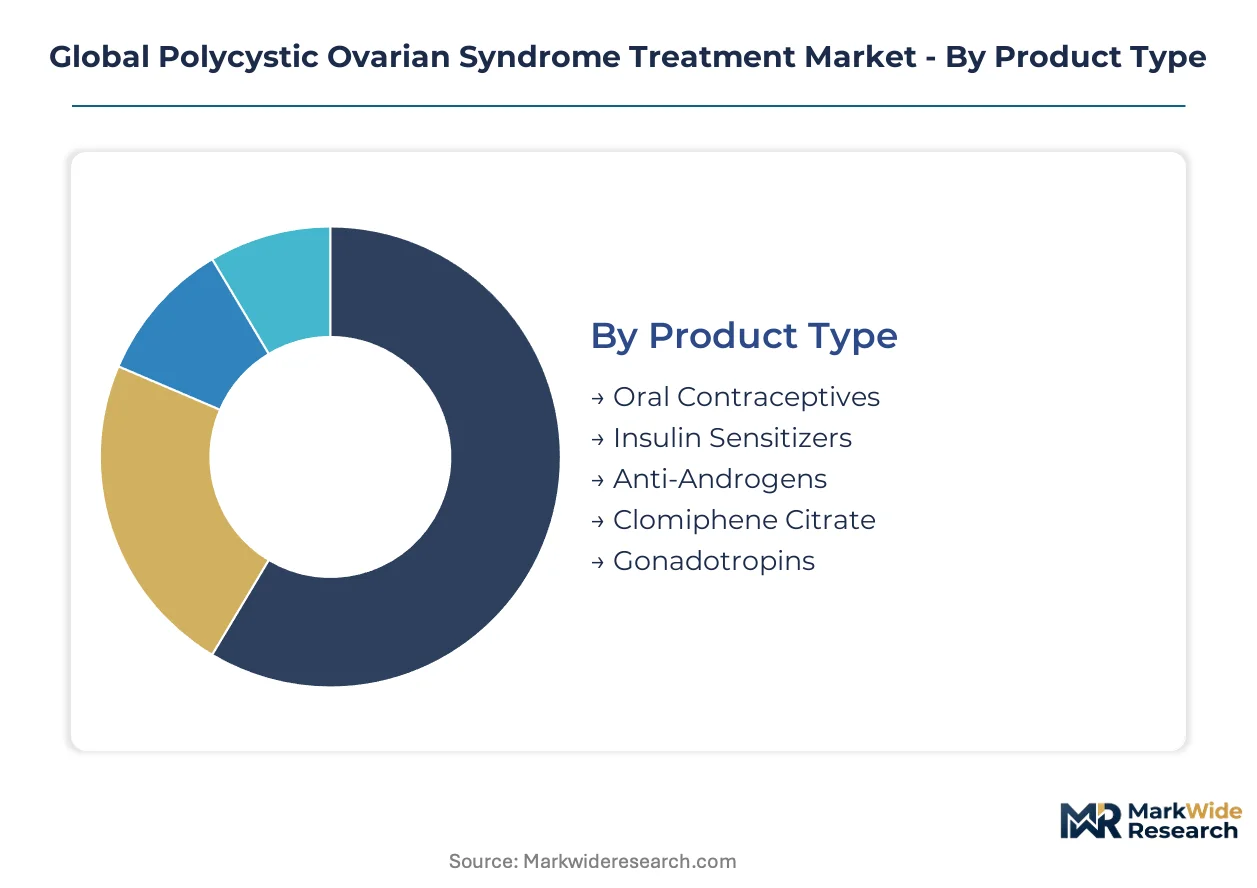
PCOS treatment segmentation reflects divergent clinical objectives across metabolic management, fertility restoration, and cosmetic symptom control. Pharmaceutical portfolios must align with distinct patient phenotypes rather than uniform diagnostic categories. Each segment carries unique regulatory pathways, reimbursement codes, and prescriber specializations that reshape commercial strategy.
Product Type:
Mature hormonal formulations dominate prescription volumes while emerging metabolic agents capture margin expansion in endocrinology practices.
- Oral Contraceptives:Ethinyl estradiol-progestin combinations suppress ovarian androgen production through hypothalamic-pituitary feedback inhibition. Demand concentrates in United States gynecology clinics where menstrual regulation prescriptions drive refill adherence. Generic saturation compresses originator pricing power.
- Insulin Sensitizers:Metformin hydrochloride and inositol derivatives improve peripheral glucose uptake and reduce hyperinsulinemia. United States fertility centers integrate these into ovarian stimulation protocols for insulin-resistant phenotypes. Pharmacogenomic screening is personalizing dosing regimens.
- Anti-Androgens:Spironolactone and finasteride block androgen receptor binding to reduce hirsutism progression.
- Clomiphene Citrate:Selective estrogen receptor modulator inducing follicular development through pituitary gonadotropin release.
- Gonadotropins:Recombinant FSH and LH preparations enable controlled ovarian hyperstimulation in assisted reproduction.
Oral contraceptives retain volume leadership; insulin sensitizers hold the steepest expansion curve.
Therapy Area:
Cost tier stratification separates chronic maintenance protocols from acute intervention cycles with divergent reimbursement structures.
- Ovulation Induction:Pharmacological restoration of cyclic follicular development through clomiphene or gonadotropin stimulation. Germany's fertility centers prioritize this intervention for anovulatory patients seeking conception. EMA pharmacovigilance requirements extend safety documentation timelines.
- Metabolic Syndrome Control:Insulin sensitizer-based management targeting cardiovascular risk reduction alongside reproductive symptom improvement. United States endocrinology practices are expanding this indication beyond traditional diabetes protocols. Continuous glucose monitoring integration enables real-time therapeutic adjustment.
- Menstrual Regulation:Hormonal cycle normalization for endometrial protection and symptom predictability.
- Hyperandrogenism:Androgen suppression targeting hirsutism, acne, and alopecia progression.
- Infertility Management:Comprehensive assisted reproduction protocols combining pharmaceutical and procedural interventions.
Menstrual regulation commands the largest patient pool; metabolic syndrome control is expanding most quickly across prescriber specialties.
End User:
Customer type fragmentation creates parallel distribution channels with distinct procurement patterns and clinical decision-making structures.
- Fertility Centers:Specialized reproductive clinics integrating hormonal therapy with assisted reproduction procedures. United States networks in California, Massachusetts, and Texas anchor prescription demand for gonadotropin and insulin sensitizer combinations. FDA reproductive health guidance accelerates protocol standardization.
- Gynecology Clinics:Generalist and subspecialty practices managing chronic PCOS maintenance across menstrual and metabolic symptoms. India's urban clinic networks in Mumbai, Delhi, and Bangalore drive oral contraceptive and metformin volumes. CDSCO quality frameworks shape domestic manufacturing standards.
- Telemedicine Providers:Virtual platforms enabling direct-to-patient prescription and lifestyle intervention bundling.
- Diagnostic Laboratories:Hormonal profiling and metabolic assessment services guiding therapeutic selection.
- Research Institutes:Academic medical centers conducting clinical trials for novel therapeutic mechanisms.
Gynecology clinics retain volume leadership; fertility centers are gaining share fastest through specialized reimbursement pathways.
Delivery Mode:
Supply concentration in oral solid dosage forms contrasts with fragmented injectable manufacturing and emerging digital-physical hybrid models.
- Oral Medication:Tablet and capsule formulations enabling patient self-administration and pharmacy dispensing scale. Chinese and Indian API clusters concentrate metformin hydrochloride production for global supply. REACH compliance shapes European excipient sourcing requirements.
- Lifestyle Intervention:Structured diet, exercise, and behavioral modification protocols integrated with pharmaceutical management. Netherlands fertility centers combine myo-inositol supplementation with metabolic tracking wearables. Subscription-based digital health platforms are commercializing bundled delivery.
- Injectable Therapy:Parenteral gonadotropin preparations requiring clinical administration.
- Topical Application:Localized anti-androgen and hormonal preparations for dermatological symptoms.
- Combination Therapy:Multi-mechanism protocols integrating pharmacological and non-pharmacological interventions.
Oral medication retains volume leadership; lifestyle intervention holds the steepest expansion trajectory through digital health integration.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Consumption patterns diverge sharply across geographies: fertility centers in the United States and Germany drive premium gonadotropin demand, while India and Brazil rely on oral contraceptives and insulin sensitizers for chronic metabolic management in generalist gynecology settings.
United States
Specialized fertility networks in California, Massachusetts, and Texas anchor gonadotropin and insulin sensitizer prescriptions. FDA reproductive health guidance accelerates protocol standardization for combination hormonal therapies. Boston-area academic medical centers pioneer pharmacogenomic screening for metformin response prediction.
Germany
Fertility centers in Bavaria and North Rhine-Westphalia prioritize ovulation induction protocols for anovulatory patients. G-BA assessment criteria shape reimbursement pathways for fertility drug coverage. Berlin-based research institutes coordinate EMA-mandated pharmacovigilance for thromboembolic risk surveillance.
India
Urban gynecology clinics in Mumbai, Delhi, and Bangalore drive oral contraceptive and metformin volumes for chronic PCOS maintenance. CDSCO quality frameworks regulate domestic insulin sensitizer manufacturing standards. Hyderabad pharmaceutical clusters concentrate API production for regional supply.
Brazil
ANVISA fast-track priority review accelerates market entry for novel insulin sensitizers targeting metabolic syndrome overlap. São Paulo fertility centers integrate lifestyle intervention bundles with hormonal therapy. Rio de Janeiro telemedicine platforms expand direct-to-patient distribution channels.
Netherlands
Fertility clinics in Amsterdam and Rotterdam adopt rapid genetic screening for insulin sensitizer response rates. EMA pharmacovigilance requirements mandate enhanced safety documentation for progestin formulations. Dutch digital health platforms commercialize subscription-based myo-inositol and metabolic tracking bundles.
Global Polycystic Ovarian Syndrome Treatment Market Competitive Landscape
Capability concentration sits with endocrinology heritage players; scale advantage sits with generic manufacturers and diversified pharmaceutical conglomerates. The market structures around three tiers: originators with FDA-approved hormonal portfolios, high-volume generic producers of oral contraceptives, and metabolic syndrome specialists integrating lifestyle protocols. Dominant competitive moves include M&A for reproductive therapeutic assets and strategic partnerships with fertility center networks.
Within the originator tier, Bayer AG leverages its endocrinology heritage to sustain brand loyalty across insulin sensitizer portfolios. Teva Pharmaceutical Industries Ltd anchors the generic scale position through cost-competitive oral contraceptive manufacturing. Sanofi occupies a metabolic syndrome control position that integrates lifestyle intervention protocols with pharmaceutical management.
| Leading Market Players |
|---|
| AstraZeneca |
| Bayer AG |
| Pfizer Inc. |
| Abbott Laboratories |
| Novartis AG |
| Merck KGaA |
| Teva Pharmaceutical Industries Ltd |
| Sanofi |
| Bristol Myers Squibb Company |
| Others |
Supply & Pricing Matrix
Hyderabad's pharmaceutical clusters concentrate metformin hydrochloride active pharmaceutical ingredient production, and their capacity utilization rates directly determine downstream pricing power for insulin sensitizer formulations across United States fertility centers and Indian gynecology clinics.
Pricing Analysis
Long-term offtake agreements between Chinese API manufacturers and European formulation houses anchor pricing stability for oral contraceptives, while spot-market purchasing dominates gonadotropin procurement. Three-tier pricing structure across premium, standard, and economy levels separates originator hormonal portfolios from authorized generics and multi-source commodity tablets. Cost compression in generic ethinyl estradiol-progestin combinations is intensifying because Indian manufacturers are expanding metformin export volumes. Fertility centers demonstrate the least price sensitivity due to specialized reimbursement pathways, while telemedicine platforms serving chronic maintenance patients exhibit the highest elasticity.
Supply Chain Analysis
Tariff exposure between China and the United States dominates supply chain risk planning for metformin hydrochloride sourcing, forcing European manufacturers to accelerate alternative supplier qualification. Active pharmaceutical ingredient production concentrates in India, China, and selected European chemical corridors. Formulation depends on ethinyl estradiol progestin compounds, recombinant gonadotropin cell lines, and inositol stereoisomer feedstocks. Single-source vulnerability persists for high-purity gonadotropin starting materials. Distribution runs through specialized cold-chain logistics for injectable fertility therapies and standard pharmaceutical wholesale for oral solid dosages.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Patient stratification by metabolic phenotype fragments demand into discrete protocol niches, creating entry points for specialists who can integrate pharmacogenomic screening with insulin sensitizer dosing.
For Market Incumbents: Entrench protocol loyalty through captive supply of myo-inositol raw materials and exclusive fertility center partnerships that lock in gonadotropin purchasing committees. Add manufacturing capacity in Germany to preempt G-BA reimbursement localization requirements. Generic oral contraceptive saturation threatens margin pools; defend through pharmacogenomic service bundling that differentiates originator metformin portfolios. For New Entrants and Emerging Players: Build out telemedicine-native distribution for subscription-based lifestyle intervention bundles paired with hormonal therapy, targeting United States patients aged 25-34 seeking integrated rather than episodic care. Brazil's ANVISA fast-track pathway offers the most penetrable regulatory entry for novel insulin sensitizers. Position through direct-to-patient metabolic tracking device integration that incumbent pharmaceutical firms lack technical capacity to replicate. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors metabolic syndrome control specialists with pharmacogenomic testing capabilities over pure-play hormonal manufacturers facing generic erosion. Five-to-ten year viability hinges on regulatory capture of lifestyle intervention reimbursement codes. Acquisition target archetype: digital health platforms with validated patient adherence data and existing fertility center partnerships. Watch for EMA pharmacovigilance rulemaking on thromboembolic risk as the inflection signal for progestin formulation portfolio valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmacogenomic Testing Integration | Boston-area academic medical centers pioneer metformin response prediction protocols that compress trial-and-error dosing periods. |
| Manufacturing Scale-Up | Hyderabad pharmaceutical clusters expand metformin hydrochloride API output to serve United States fertility center demand growth. |
| Regulatory Approval Pathway | ANVISA fast-track priority review accelerates novel insulin sensitizer entry for metabolic syndrome overlap indications in Brazil. |
| Strategic Partnership | Netherlands fertility clinics combine Amsterdam-based genetic screening with Rotterdam metabolic tracking wearable deployment. |
| Pipeline Diversification | Bayer AG leverages endocrinology heritage to sustain brand loyalty across insulin sensitizer and lifestyle intervention bundles. |
Research Methodology
A spread of perspectives from formulary directors at United States fertility networks, regulatory affairs leads at EMA-submission-stage firms, gynecology clinic procurement managers in Mumbai and Delhi, and payer access specialists converged on the working assumptions. Secondary validation drew from FDA reproductive health guidance documents, EMA centralized procedure submissions, ClinicalTrials.gov protocol registries, and CDSCO manufacturing standard filings. Bottom-up prescription volume modeling triangulated against top-down pharmaceutical expenditure estimates.
Demand-supply-balance framing anchored the analytical framework across the analysis window, with segmentation dimensions spanning product type, therapy area, end user channel, and delivery mode. CAGRs derived from patient population growth rates, protocol penetration curves, and pricing trajectory assumptions. Modeled inputs included fertility center expansion pipelines, pharmacogenomic screening adoption curves, and telemedicine prescription channel development.
Sensitivities concentrate around FDA guidance revisions on combination hormonal therapy safety profiles and EMA pharmacovigilance updates for thromboembolic risk surveillance. Forecasts reflect documented assumptions about patient awareness campaign intensity and reimbursement pathway stability. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Hypothyroidism Market
Specialty Medicine
Peripheral Neuropathy Market
Specialty Medicine
Necrotizing Fasciitis Treatment Market
Specialty Medicine
Advanced Basal Cell Carcinoma Market
Specialty Medicine
Leukocyte Adhesion Deficiency Management Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
Dural Arteriovenous Fistulas Treatment Market
Specialty Medicine
Glioma Therapeutics Market
Specialty Medicine
Megalencephaly-Polymicrogyria-Polydactyly-Hydrocephalus Syndrome Market
Specialty Medicine
Cholangiocarcinoma (CCA) Therapeutics Market
Specialty Medicine
Cutaneous B-Cell Lymphoma Treatment Market
Specialty Medicine
Atopic Dermatitis Market
Specialty Medicine
Hemifacial Spasm Market
Specialty Medicine
Neuromyelitis Optica Market
Specialty Medicine
Cervical Cancer Therapeutics Market
Specialty Medicine
Global Hypoparathyroidism Treatment Market