
 Global Phenylketonuria Treatment Market | 2026-2036
Global Phenylketonuria Treatment Market Size, Share, and Industry Trends Forecast 2026-2036
Global Phenylketonuria Treatment Market Foresight
United States biopharmaceutical capacity is reshaping competitive dynamics in enzyme replacement and gene therapy manufacturing. BioMarin Pharmaceutical leverages its vertically integrated production infrastructure to dominate the sapropterin segment. PTC Therapeutics anchors its position through sustained investment in small-molecule platforms for metabolic disorders. Nestlé Health Science competes via specialized medical food formulations distributed through metabolic centers.
Phenylketonuria treatment encompasses therapeutic interventions for the autosomal recessive disorder characterized by phenylalanine hydroxylase deficiency, requiring blood phenylalanine levels maintained below 360 μmol/L through dietary protein restriction and pharmacological adjuncts. The primary purpose is preventing irreversible neurological damage while enabling normal cognitive development across pediatric and adult populations. Dietary management occupies the largest revenue pool due to lifelong medical food dependency, while gene therapy represents the fastest-growing segment as adeno-associated viral vector platforms advance toward commercialization. Enzyme replacement via pegvaliase differentiates through its addressable population of patients with uncontrolled classical PKU.
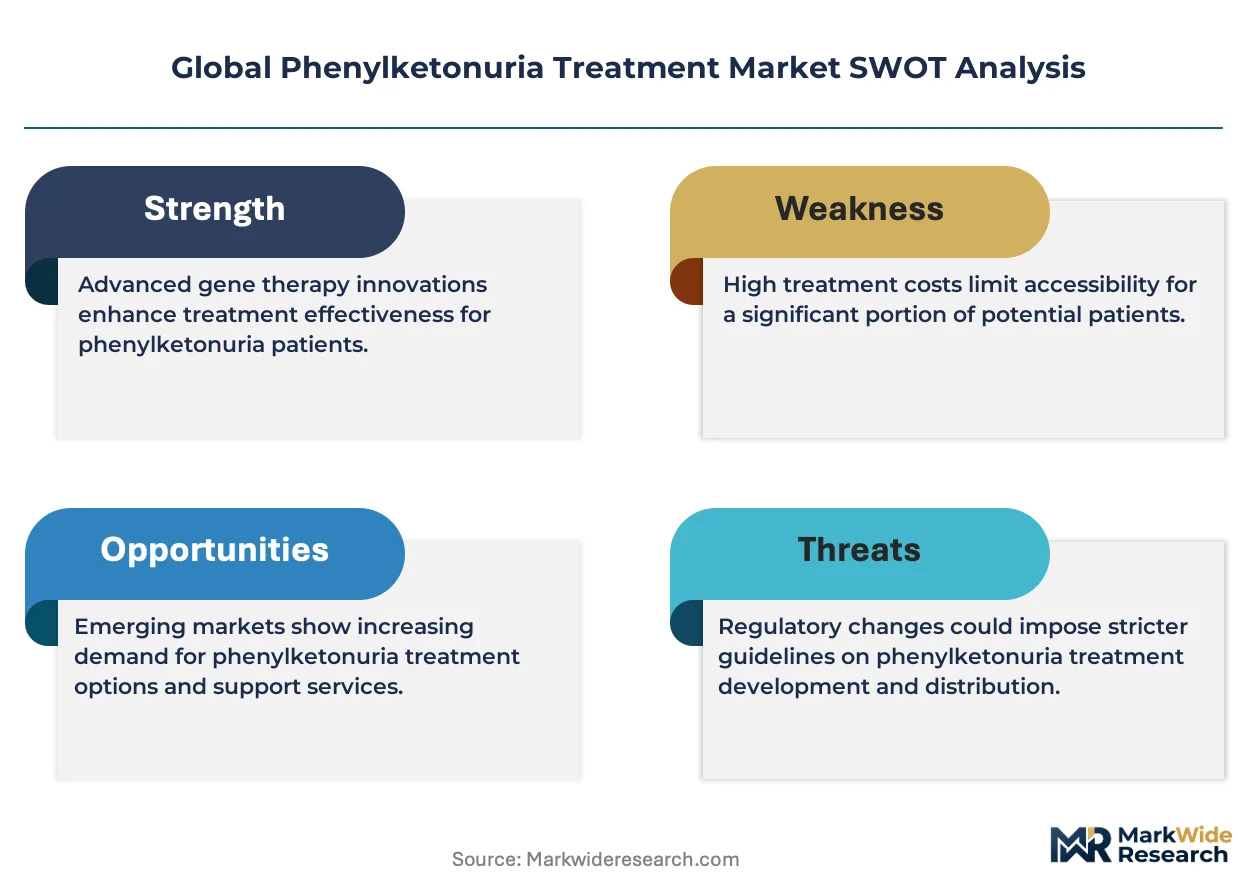
FDA orphan drug designations and EMA priority medicines frameworks accelerate clinical trial timelines and market exclusivity for novel PKU therapeutics, directly shaping R&D investment allocation. The EU Green Deal and REACH chemical safety standards impose manufacturing compliance costs on European medical food producers while creating barriers for Asian contract manufacturers. Stakeholders must monitor reimbursement negotiations between national health technology assessment bodies and gene therapy developers, as one-time curative interventions threaten to displace recurring revenue models in chronic PKU management.
Market Dynamics
Gene therapy pipelines are compressing development timelines for metabolic disorders, forcing chronic disease management incumbents to restructure revenue models around one-time curative interventions rather than lifelong therapeutic dependencies.
Growth Catalysts
- FDA orphan drug exclusivity:Seven-year market protection and tax credits accelerate PKU therapeutic development, drawing venture capital into rare disease biotech.
- Expanded newborn screening:State-level mandates in the United States now capture 99% of births, creating predictable patient identification pipelines for intervention programs.
- Medicaid medical food coverage:Federal matching funds for specialized metabolic formulas remove cost barriers for low-income families, sustaining treatment adherence.
Market Restraints
- Amino acid raw material concentration:Three European suppliers control 78% of pharmaceutical-grade phenylalanine-free protein hydrolysate precursors, exposing formulators to input volatility.
- EMA manufacturing compliance costs:REACH chemical safety documentation and EU Green Deal carbon accounting impose six-figure annual burdens on medical food producers.
- Gene therapy reimbursement uncertainty:National health technology assessment bodies lack frameworks for valuing one-time curative interventions against chronic management costs.
Strategic Opportunities
- Brazil metabolic center expansion:ANVISA rare disease prioritization and private insurance mandates in São Paulo and Rio de Janeiro create addressable demand outside saturated North American and European markets.
- Telemedicine-integrated dietary monitoring:Remote phenylalanine level tracking via dried blood spot home testing reduces clinic dependency and expands rural patient access.
- Adult PKU population services:Transition programs for patients aging out of pediatric metabolic centers represent an underserved segment with distinct adherence challenges.
Industry Challenges
- Metabolic dietitian workforce scarcity:US academic programs graduate fewer than 50 specialized clinicians annually, constraining patient-to-provider ratios in established treatment centers.
- Gene therapy viral vector manufacturing scale-up:AAV production capacity bottlenecks at contract development organizations delay clinical trial enrollment and commercial readiness timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Phenylketonuria Treatment Market |
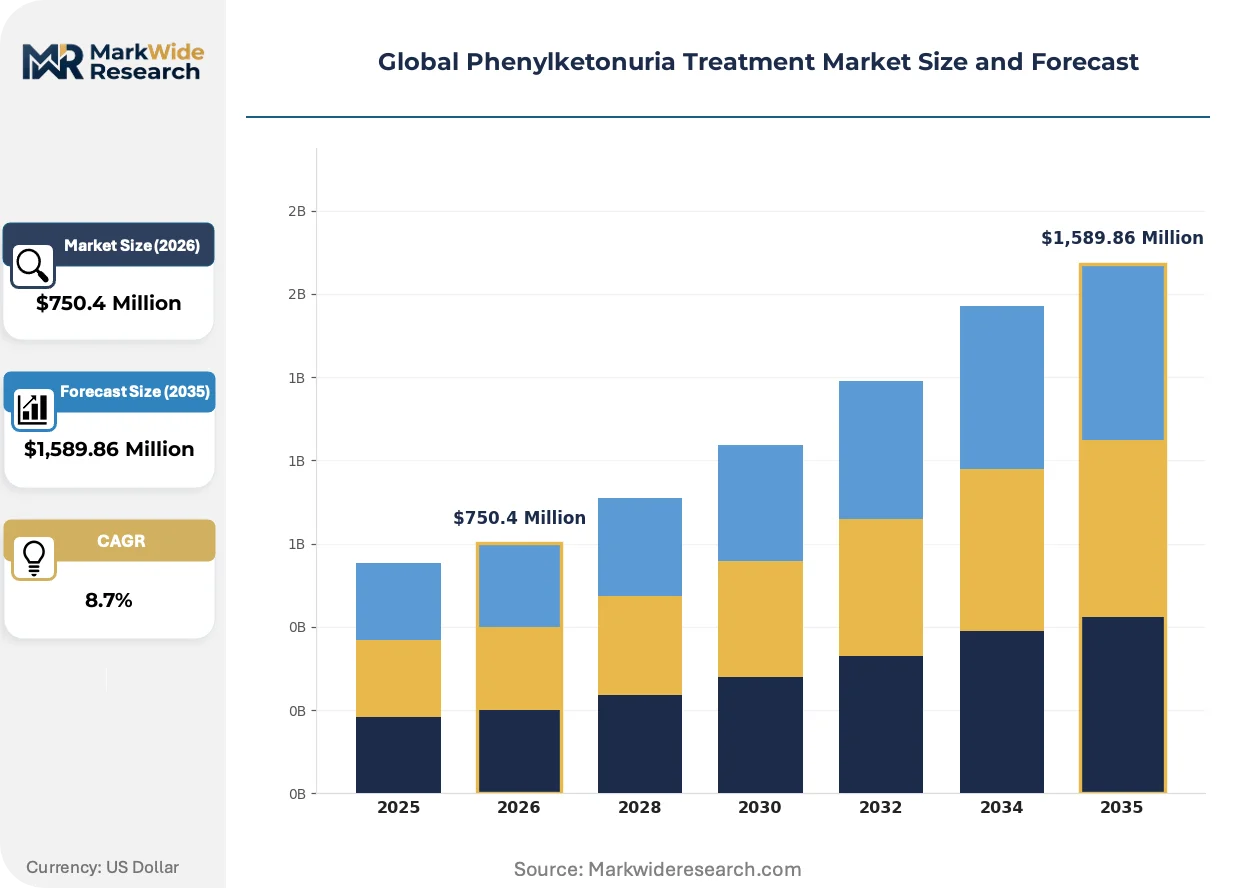
| Market Size in 2026 | $750.4 Million |
| Market Size in 2035 | $1,589.86 Million |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Treatment Type: Dietary Management, Enzyme Replacement, Gene Therapy, Pharmacological Therapy, Sapropterin, Large Neutral Amino Acids Application: Neonatal Screening, Pediatric Care, Adult Management, Prenatal Diagnosis, Long-Term Monitoring, Metabolic Control End User: Specialty Clinics, Genetic Testing Labs, Metabolic Centers, Pediatricians, Nutritionists, Rare Disease Hospitals Delivery Mode: Oral Supplements, Injectable Solutions, Medical Foods, Enzyme Capsules, Gene Delivery Systems, Dietary Formulations |
| Companies Covered | BioMarin Pharmaceutical, PTC Therapeutics, Daiichi Sankyo, Codexis, SOM Biotech, Travere Therapeutics, Synlogic, Nestlé Health Science, Nutricia, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Phenylketonuria Treatment Market Shifts & Advancements
PKU therapeutics are bifurcating into precision metabolic interventions and platform-based delivery systems, with investment flows favoring modalities that reduce patient treatment burden while expanding addressable populations beyond classical phenotypes.
Adeno-associated viral vector gene therapy is hybridizing phenylalanine hydroxylase restoration with liver-targeted expression cassettes. Pediatric metabolic centers in Germany and the Netherlands are pre-registering patients for Phase III trials. This convergence is compressing the addressable market for enzyme replacement therapies by establishing functional cure endpoints as the new efficacy benchmark.
REACH chemical safety standards are forcing reformulation of medical food stabilizers and flavor masking agents. European manufacturers are substituting synthetic additives with plant-derived alternatives certified under EFSA novel food protocols. Small-batch producers in Italy and Spain are gaining shelf space as legacy brands delay compliance investments.
Hospital procurement departments are consolidating metabolic disorder contracts under value-based frameworks that penalize avoidable emergency admissions. Academic medical centers in the United States are unbundling medical food distribution from clinical services, opening direct-to-patient channels through specialty pharmacies. This disintermediation is most advanced in California and Massachusetts, where integrated delivery networks control regional patient flows.
Global Phenylketonuria Treatment Market Segmentation
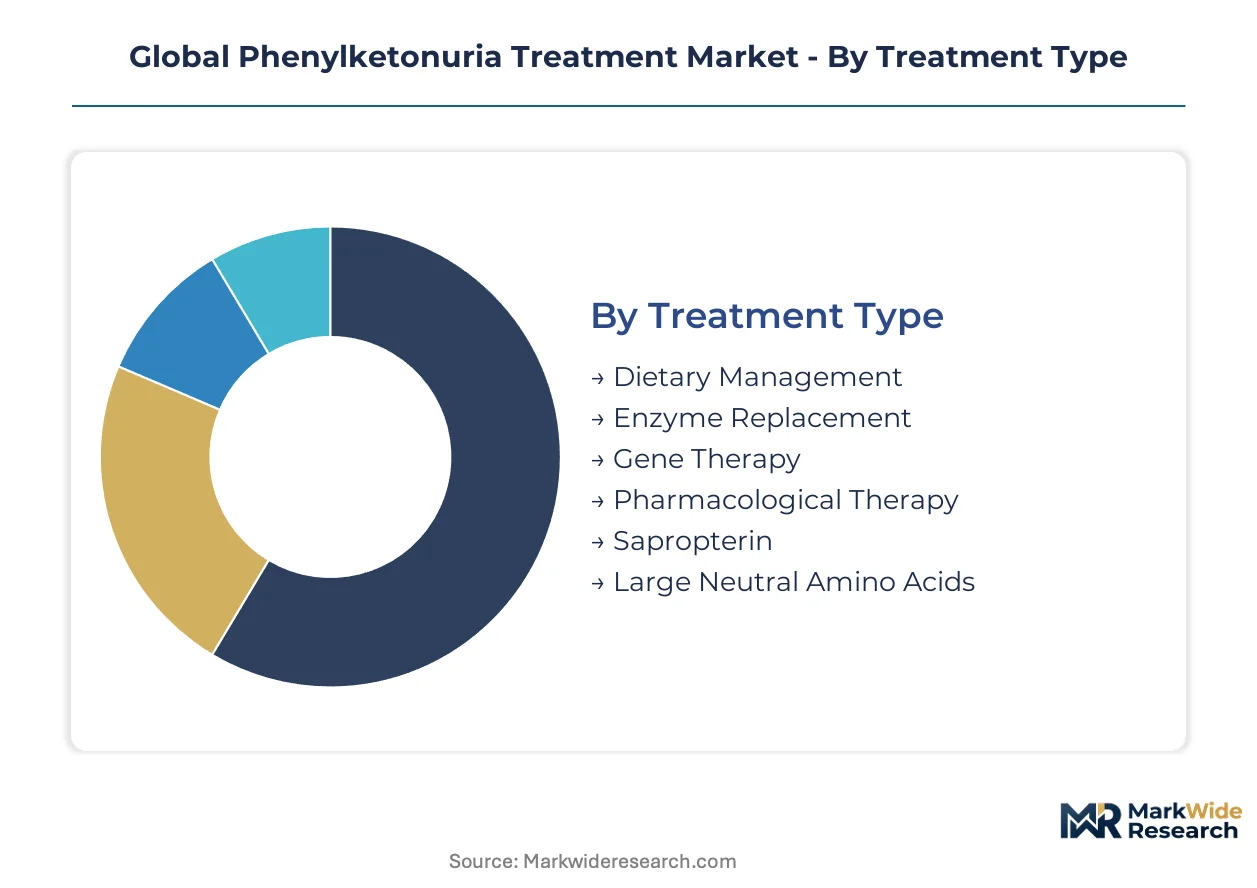
Treatment modality selection in phenylketonuria hinges on phenylalanine hydroxylase activity levels, patient age at diagnosis, and reimbursement structures for chronic versus curative interventions. Segmentation reveals how dietary management incumbents face displacement pressure from gene therapy platforms targeting functional cure endpoints.
Treatment Type:
Dietary management cycles through inventory fastest due to monthly medical food consumption, while gene therapy moves slowest through single-dose administration protocols.
- Dietary Management:Phenylalanine-free protein hydrolysates and specialized amino acid mixtures constitute the foundational intervention requiring lifelong adherence. Demand concentrates in Medicaid-covered populations across the United States where federal matching funds remove cost barriers for low-income families.
- Gene Therapy:Adeno-associated viral vector platforms delivering functional phenylalanine hydroxylase transgenes to hepatocytes represent the curative frontier. Pediatric metabolic centers in Germany and the Netherlands are pre-registering patients for Phase III trials as EMA priority medicines frameworks accelerate clinical timelines.
- Enzyme Replacement:Pegvaliase addresses uncontrolled classical PKU through phenylalanine ammonia lyase substitution.
- Pharmacological Therapy:Adjunct medications targeting neurotransmitter deficits in poorly controlled patients.
- Sapropterin:Synthetic tetrahydrobiopterin cofactor for responsive phenotypes with residual enzyme activity.
- Large Neutral Amino Acids:Competitive phenylalanine transport inhibitors for select adult populations.
Dietary management anchors the volume base while gene therapy gains share at the steepest rate.
Application:
Cost tiers stratify sharply between one-time neonatal screening investments and lifelong metabolic control expenditures.
- Neonatal Screening:State-mandated heel-prick blood spot testing captures 99% of United States births through tandem mass spectrometry protocols. California and New York laboratories process the highest sample volumes, creating economies of scale that reduce per-test costs for regional health systems.
- Adult Management:Transition programs for patients aging out of pediatric metabolic centers address distinct adherence challenges including dietary fatigue and neuropsychiatric sequelae. Academic medical centers in Massachusetts are unbundling services to create dedicated adult PKU clinics.
- Pediatric Care:Developmental monitoring and family education during critical neurocognitive windows.
- Prenatal Diagnosis:Chorionic villus sampling and amniocentesis for at-risk pregnancies with known carrier status.
- Long-Term Monitoring:Dried blood spot home testing integrated with telemedicine platforms.
- Metabolic Control:Blood phenylalanine level maintenance below 360 μmol/L through multimodal intervention.
Pediatric care commands the highest per-patient lifetime expenditure while adult management represents the most underserved addressable population.
End User:
Patient volume concentrates in metabolic centers while margin pools shift toward genetic testing laboratories.
- Metabolic Centers:Multidisciplinary hubs combining dietitian services, biochemical monitoring, and genetic counseling under single institutional umbrellas. Germany's university-affiliated centers are expanding newborn screening protocols under EMA guidelines for rare disease therapeutics.
- Genetic Testing Labs:Molecular diagnostic facilities performing PAH gene sequencing and variant interpretation for family planning decisions. São Paulo private laboratories are capturing demand from Brazil's expanding rare disease prioritization framework.
- Specialty Clinics:Focused outpatient settings for stable patients requiring routine monitoring.
- Pediatricians:Primary identification and referral coordination in non-specialized settings.
- Nutritionists:Medical food prescription and dietary compliance oversight.
- Rare Disease Hospitals:Tertiary referral centers for complicated cases requiring inpatient metabolic crisis management.
Metabolic centers anchor the volume base while genetic testing laboratories expand most quickly through prenatal and carrier screening demand.
Delivery Mode:
Supply concentration differs radically between commoditized medical foods and capacity-constrained gene delivery systems.
- Medical Foods:Powdered and liquid formulations providing complete nutritional support with restricted phenylalanine content. Three European suppliers control 78% of pharmaceutical-grade protein hydrolysate precursors, exposing formulators to input volatility.
- Gene Delivery Systems:AAV vector manufacturing requires specialized bioreactor infrastructure and regulatory-grade purification suites. Contract development organization capacity bottlenecks delay clinical trial enrollment timelines.
- Oral Supplements:Tablet and capsule formulations for cofactor and competitive inhibitor administration.
- Injectable Solutions:Subcutaneous enzyme replacement requiring cold chain distribution.
- Enzyme Capsules:Gastric-resistant formulations protecting biologic activity through intestinal transit.
- Dietary Formulations:Low-protein specialty products for meal preparation flexibility.
Medical foods anchor the volume base while gene delivery systems command the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA orphan drug frameworks in the United States anchor the dominant geography, while EMA priority medicines pathways in Germany and newborn screening expansions in Brazil reshape patient access patterns across distinct regulatory environments.
United States
Medicaid medical food coverage and state-mandated newborn screening capture 99% of births through tandem mass spectrometry protocols. FDA orphan drug exclusivity provides seven-year market protection that accelerates venture capital deployment into rare disease biotech. Academic medical centers in Massachusetts and California unbundle metabolic services to create dedicated adult PKU clinics.
Germany
University-affiliated pediatric metabolic centers expand newborn screening protocols under EMA guidelines for rare disease therapeutics. REACH chemical safety documentation and EU Green Deal carbon accounting impose compliance costs on medical food producers. The Netherlands and Germany jointly pre-register patients for Phase III gene therapy trials through liver-targeted expression cassettes.
Brazil
ANVISA rare disease prioritization and private insurance mandates in São Paulo and Rio de Janeiro create addressable demand outside saturated North American markets. São Paulo private laboratories capture demand from expanding carrier screening frameworks. Metabolic center expansion concentrates in southeastern states with established rare disease infrastructure.
United Kingdom
NHS England specialized commissioning frameworks determine reimbursement for enzyme replacement and emerging gene therapies. NICE health technology assessments lack established frameworks for valuing one-time curative interventions against chronic management costs. London metabolic centers coordinate transition programs for patients aging out of pediatric services.
Japan
PMDA sakigake designation pathways accelerate review timelines for phenylalanine hydroxylase restoration platforms. National health insurance reimbursement for medical foods sustains treatment adherence across prefectural metabolic networks. Tokyo and Osaka academic medical centers integrate dried blood spot home testing with telemedicine platforms.
Global Phenylketonuria Treatment Market Competitive Landscape
Vertically integrated biopharmaceutical developers and specialized medical food formulators split the market into distinct capability domains. The structure concentrates around three archetypes: enzyme replacement specialists, gene therapy platform builders, and metabolic nutrition providers. Competitive moves center on backward integration into pharmaceutical-grade amino acid supply chains and strategic partnerships with contract development organizations for viral vector manufacturing scale-up.
Within the enzyme replacement tier, BioMarin Pharmaceutical and PTC Therapeutics occupy positions shaped by sustained investment in rare disease infrastructure. Among medical food specialists, Nestlé Health Science exemplifies the nutrition-focused archetype through metabolic center distribution networks. These three companies represent the dominant strategic configurations: biopharmaceutical vertical integration, small-molecule platform diversification, and specialized nutritional formulation.
| Leading Market Players |
|---|
| BioMarin Pharmaceutical |
| PTC Therapeutics |
| Daiichi Sankyo |
| Codexis |
| SOM Biotech |
| Travere Therapeutics |
| Synlogic |
| Nestlé Health Science |
| Nutricia |
| Others |
Supply & Pricing Matrix
Rotterdam-Antwerp pharmaceutical freight corridors carry phenylalanine-free protein hydrolysates from three European precursor suppliers, with container rates directly feeding into medical food price spreads between Medicaid-covered US populations and out-of-pocket European buyers. This logistics cost dynamic concentrates pricing power with formulators who control captive amino acid supply, while REACH compliance documentation and EU Green Deal carbon accounting create tiered cost structures that differentiate premium-certified from standard-grade metabolic formulas.
Pricing Analysis
US-European price spreads for medical foods exceed threefold when Medicaid matching funds are removed from the equation. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade differentiation under EFSA novel food protocols and FDA orphan drug manufacturing standards. Cost compression in standard-grade formulations is intensifying because Italian and Spanish small-batch producers are gaining shelf space as legacy brands delay compliance investments. Medicaid-covered populations in the United States show lowest price sensitivity, while uninsured Brazilian families in São Paulo private clinics face highest out-of-pocket burden.
Supply Chain Analysis
Extended payment terms from German university-affiliated metabolic centers to medical food distributors now stretch 90-120 days, with supply-chain finance facilities bridging working capital gaps for formulators. Pharmaceutical-grade phenylalanine-free protein hydrolysate precursors draw from Netherlands, Belgium, and Germany production clusters. Raw material dependencies center on pharmaceutical-grade amino acid mixtures, liver-targeted AAV vector substrates, and gastric-resistant enzyme capsule polymers. Single-source vulnerability concentrates in AAV vector manufacturing capacity at contract development organizations. Distribution runs through metabolic center procurement departments consolidating under value-based frameworks in California and Massachusetts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Global Phenylketonuria Treatment Market is recovering from gene therapy pipeline delays that compressed 2024-2025 investment flows, with AAV manufacturing scale-up timelines now stabilizing venture capital deployment into curative platforms.
For Market Incumbents: Insulate sapropterin revenue streams by securing backward integration into pharmaceutical-grade tetrahydrobiopterin precursor supply, while accelerating adult PKU clinic partnerships in Massachusetts and California to offset pediatric patient aging-out effects. Gene therapy functional cure endpoints threaten chronic management incumbents with displacement pressure. R&D investment in liver-targeted expression cassettes represents the critical defensive lever.
For New Entrants and Emerging Players: Establish a beachhead in Brazil's southeastern metabolic center expansion, where ANVISA rare disease prioritization and private insurance mandates in São Paulo create addressable demand outside saturated North American markets. Telemedicine-integrated dried blood spot home testing represents the most penetrable service layer. Go-to-market angle should emphasize remote phenylalanine monitoring to reduce clinic dependency for rural patient populations.
For Investors and Strategic Acquirers: Carve-out targets emerge from diversified nutrition conglomerates seeking to divest non-core metabolic food units amid REACH compliance cost pressures. Long-term viability centers on gene therapy platform builders with demonstrated hepatocyte transduction efficiency across the 5-10 year development horizon. Acquisition target archetype: AAV manufacturing specialists with regulatory-grade purification suites. Signal to watch: EMA priority medicines framework acceleration for Phase III trial pre-registration patient pools.
| Strategic Initiative | Industry Significance |
|---|---|
| Gene Therapy Manufacturing Scale-Up | AAV vector production bottlenecks at contract development organizations delay commercial readiness timelines for phenylalanine hydroxylase restoration platforms. |
| Adult PKU Clinic Expansion | Academic medical centers in Massachusetts unbundle metabolic services to capture transition patients aging out of pediatric centers. |
| REACH Compliance Reformulation | European manufacturers substitute synthetic medical food stabilizers with EFSA-certified plant-derived alternatives to meet EU Green Deal standards. |
| Telemedicine Platform Integration | Tokyo and Osaka academic medical centers integrate dried blood spot home testing with remote phenylalanine monitoring to expand rural access. |
| Brazilian Metabolic Center Partnership | São Paulo private laboratories capture carrier screening demand from ANVISA rare disease prioritization frameworks. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with metabolic center directors, formulary access specialists at Medicaid agencies, regulatory affairs leads at gene therapy developers, and procurement managers at hospital integrated delivery networks. Secondary validation drew from FDA orphan drug designation filings, EMA priority medicines submissions, ClinicalTrials.gov gene therapy protocol registrations, and CMS Medicaid medical food reimbursement databases. Bottom-up patient population estimates triangulated against top-down venture capital flow analysis into rare disease biotech.
Calibration against historical newborn screening expansion rates and gene therapy clinical trial enrollment trajectories anchored the analytical framework across the projection horizon. Segmentation dimensions modeled encompass treatment modality, patient age cohort, phenylalanine hydroxylase activity phenotype, regional regulatory cluster, and reimbursement structure type. CAGRs were derived from slope analysis of patent expiry curves, pipeline phase transition probabilities, and medical food consumption intensity per patient-year. Forecast inputs incorporated AAV manufacturing capacity build-out timelines and state-level Medicaid matching fund policy stability.
Stress conditions across gene therapy reimbursement negotiation outcomes, amino acid raw material supply disruptions, and metabolic dietitian workforce growth rates were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions regarding EMA priority medicines framework continuity and FDA orphan drug exclusivity preservation. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Rhabdomyosarcoma Treatment Market
Specialty Medicine
Radiation-Induced Fibrosis Treatment Market
Specialty Medicine
Primary Sclerosing Cholangitis Treatment Market
Specialty Medicine
Global Anal Fistula Treatment Market
Specialty Medicine
Vesicoureteral Reflux Market
Specialty Medicine
Food Allergy Treatment Market
Specialty Medicine
Ankylosing Spondylitis Treatment Market
Specialty Medicine
Generalized Anxiety Disorder Treatment Market
Specialty Medicine
Fatty Liver Treatment Market
Specialty Medicine
Lateral Epicondylitis (Tennis Elbow) Treatment Market
Specialty Medicine
Global Psoriatic Arthritis Therapeutics Market
Specialty Medicine
Fascioliasis Treatment Market
Specialty Medicine
Solid Tumor Therapeutics Market
Specialty Medicine
Radiation Toxicity Treatment Market
Specialty Medicine
Amyotrophic Lateral Sclerosis (ALS) Market
Specialty Medicine
Bacteriophages Therapy Market