
 Respiratory Syncytial Virus (RSV) Therapeutics Market | 2026-2036
Respiratory Syncytial Virus (RSV) Therapeutics Market Size, Share, and Industry Trends Forecast 2026-2036
Respiratory Syncytial Virus (RSV) Therapeutics Market Intelligence
Multi-source biologics procurement is broadening as health systems diversify beyond single-supplier dependencies for infant prophylaxis. Sanofi leverages its established immunization infrastructure to sustain commercial reach across European and North American hospital networks. Pfizer competes through manufacturing scale in recombinant protein production, while GSK plc anchors its position with differentiated maternal immunization platforms.
Respiratory Syncytial Virus therapeutics comprise biologics and small-molecule agents engineered to prevent or treat acute lower respiratory tract infections caused by the enveloped RNA virus, with monoclonal antibodies typically requiring cold-chain distribution at two to eight degrees Celsius to preserve F-protein binding affinity. These interventions serve primarily to reduce hospitalization burdens among neonates and elderly populations during seasonal epidemic peaks. Monoclonal antibodies command the dominant margin pool due to recurring seasonal demand and premium pricing for infant prophylaxis, while vaccine candidates represent the fastest-expanding segment as maternal and older-adult immunization protocols advance through Phase III programs. Intravenous delivery dominates acute treatment settings, though subcutaneous formulations are gaining structural importance for outpatient prophylaxis programs.
FDA breakthrough therapy designation and EMA accelerated assessment pathways shape development priorities and commercial timelines for novel RSV biologics entering regulated markets. WHO prequalification standards influence procurement decisions for low- and middle-income country immunization programs, while national pediatric formularies in Germany and Japan determine reimbursement access for high-risk infant populations. Stakeholders must monitor evolving FDA guidance on immunobridging studies and real-world evidence requirements as competitive pressure intensifies between maternal vaccine and infant monoclonal antibody strategies.
Market Dynamics
FDA breakthrough therapy designations are compressing development timelines for novel RSV biologics, forcing incumbents to accelerate manufacturing scale-up before competitive antibodies reach pediatric formularies. This regulatory velocity is restructuring competitive positioning across infant prophylaxis and maternal immunization segments.
Growth Catalysts
- Pediatric formulary expansion:Germany's national reimbursement framework for high-risk infant populations is broadening prophylactic eligibility criteria, pulling demand through hospital procurement channels.
- EMA accelerated assessment:The pathway is shortening commercialization timelines for novel monoclonal antibodies, enabling faster market entry for biologics targeting neonatal populations.
- Cold-chain infrastructure maturation:Two-to-eight-degree Celsius distribution networks in Japan are stabilizing F-protein binding affinity preservation, reducing wastage rates for temperature-sensitive biologics.
Market Restraints
- Recombinant protein input volatility:CHO cell culture media costs fluctuate with serum supply concentration from South American and New Zealand sources, squeezing margin structures for antibody manufacturers.
- Single-supplier dependency:Contract manufacturing organizations in Ireland and Belgium concentrate fill-finish capacity for European distribution, creating geographic vulnerability in supply continuity.
- Immunobridging study requirements:FDA guidance on extrapolating efficacy data across infant subpopulations is extending clinical program durations, delaying label expansions for approved therapies.
Strategic Opportunities
- Older-adult immunization protocols:Phase III programs for elderly populations in the United States are opening reimbursement pathways beyond pediatric applications, diversifying revenue concentration.
- Subcutaneous formulation development:Outpatient administration is displacing intravenous delivery in prophylaxis programs, enabling pharmacy-based distribution models and reducing hospital dependency.
- WHO prequalification alignment:Low- and middle-income country procurement standards are creating access pathways for multi-source biologics, expanding addressable volume beyond established markets.
Industry Challenges
- Bioprocess engineering talent scarcity:Purification and downstream processing expertise concentrates with experienced operators in Massachusetts and Basel, constraining manufacturing expansion timelines for new entrants.
- Legacy cold-chain integration:Hospital networks in Japan and Germany require retrofitting for subcutaneous outpatient models, creating friction between product innovation and distribution infrastructure.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Respiratory Syncytial Virus (RSV) Therapeutics Market |
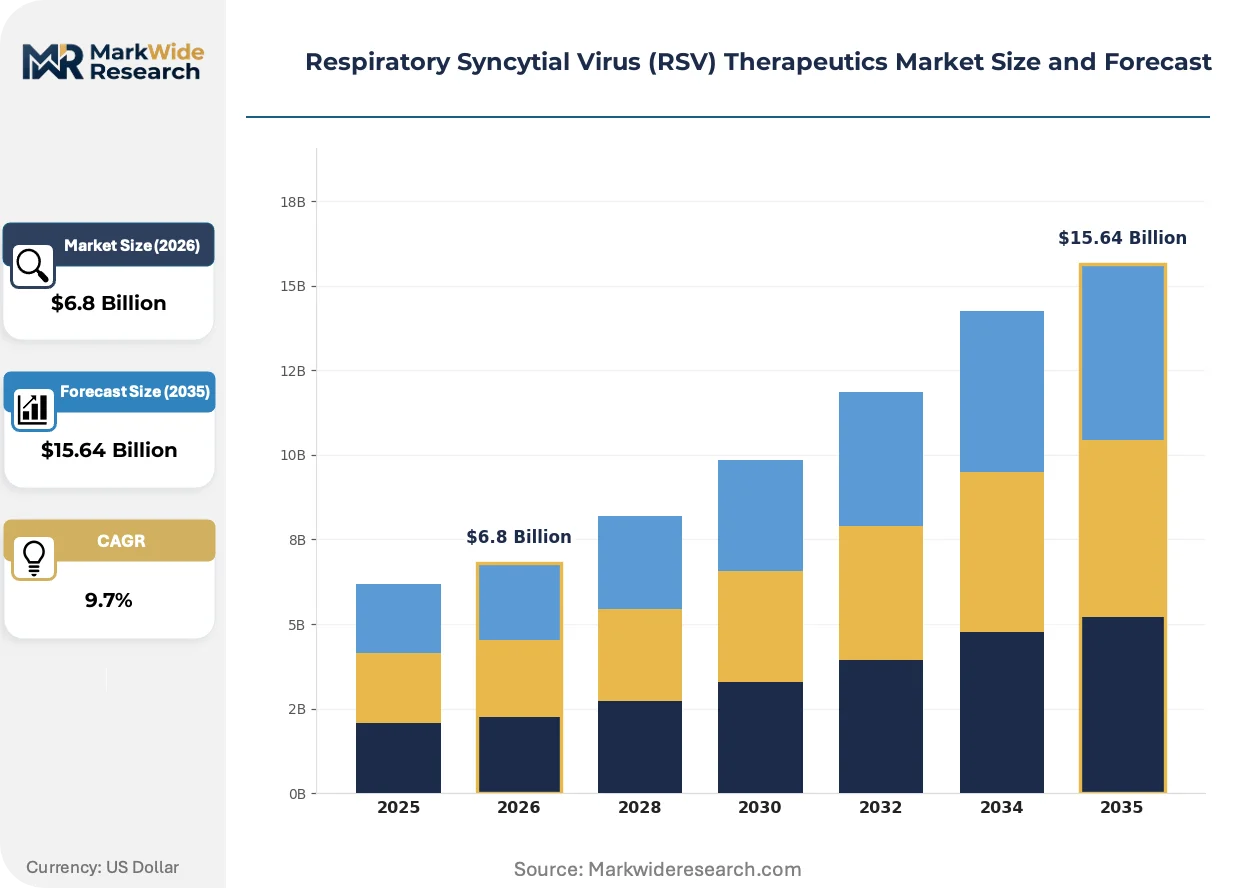
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $15.64 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Monoclonal Antibodies, Antiviral Agents, Fusion Inhibitors, Vaccine Candidates Therapy Area: Pediatric Care, Geriatric Care, Immunocompromised Conditions, Respiratory Diseases End User: Hospitals, Specialty Clinics, Research Institutes, Outpatient Facilities Delivery Mode: Intravenous, Intramuscular, Oral, Nasal Spray, Subcutaneous |
| Companies Covered | Sanofi, Moderna, AstraZeneca, Bausch Health Companies, AbbVie, Pfizer, Merck & Co, Johnson & Johnson, GSK plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Respiratory Syncytial Virus (RSV) Therapeutics Market Strategic Shifts & Innovations
Platform technologies are fragmenting the traditional antibody development paradigm, enabling smaller entities to compress discovery-to-clinic timelines. This technological democratization is reshaping competitive entry patterns across the prophylaxis landscape.
Extended half-life monoclonal antibody engineering is modularizing dosing regimens for infant prophylaxis. Pediatric care units in the United States are adopting single-injection protocols for entire RSV seasons, replacing monthly administrations. This compression is enabling outpatient program scalability and reducing nursing burden in hospital settings.
REACH-compliant manufacturing standards in the European Union are forcing solvent and reagent substitution in bioprocess workflows. Contract manufacturers are revalidating purification columns and buffer systems to meet ECHA substance restrictions. Maternal immunization platforms face the steepest compliance costs due to complex adjuvant chemistries requiring reformulation.
Hospital procurement committees are consolidating supplier relationships for seasonal biologics, shifting from multi-vendor purchasing to sole-source agreements with volume guarantees. This concentration is displacing fragmented buying patterns that characterized early monoclonal antibody adoption. The United States exhibits the most pronounced committee consolidation, with integrated delivery networks standardizing formulary decisions across member institutions.
Respiratory Syncytial Virus (RSV) Therapeutics Market Segmentation
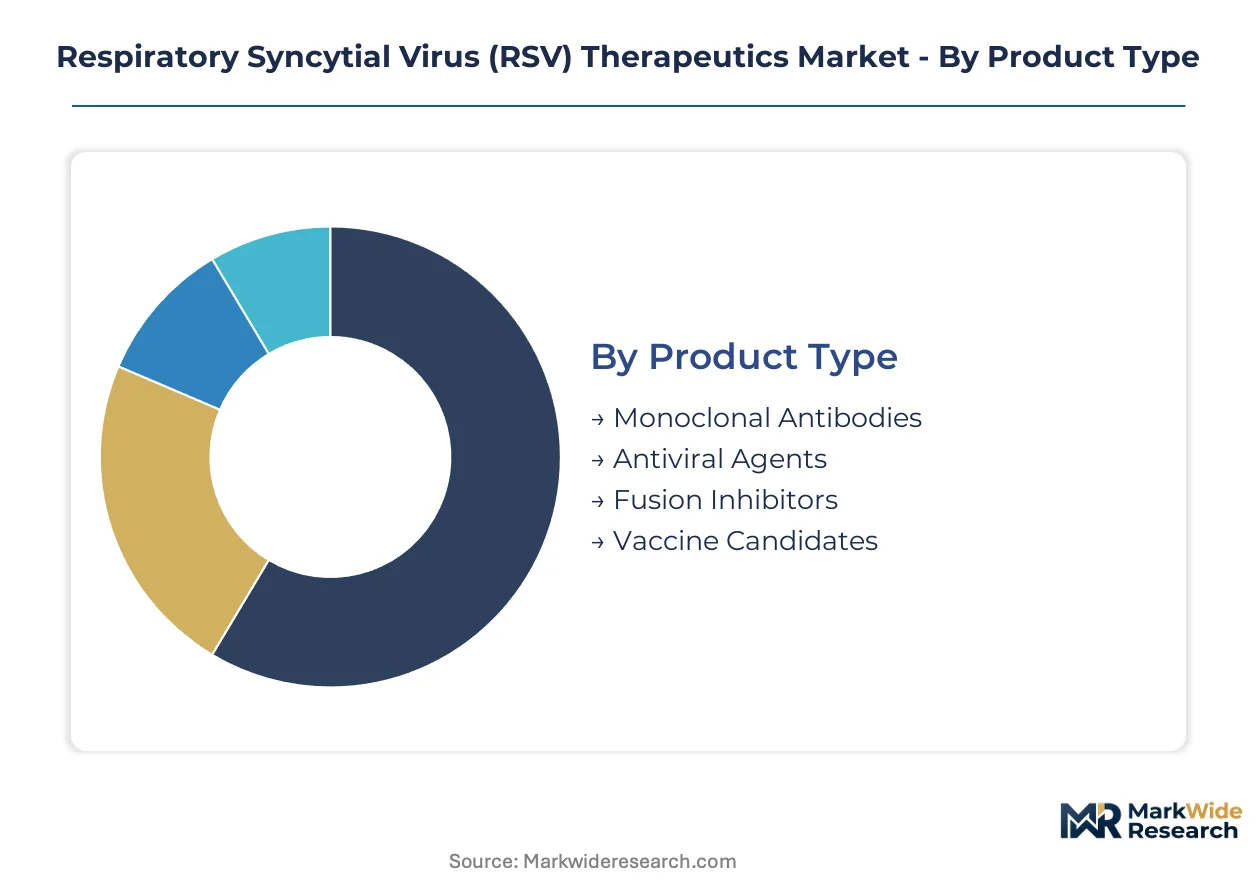
RSV therapeutics segmentation reveals distinct commercial pathways between acute treatment modalities and preventive prophylaxis systems. Product architecture and delivery infrastructure determine reimbursement eligibility, cold-chain requirements, and procurement channel access across patient populations.
Product Type:
Standalone biologics dominate hospital procurement, while combination platforms and embedded immunization systems serve outpatient networks with different technical specifications.
- Monoclonal Antibodies:Engineered immunoglobulins targeting the RSV F-protein require continuous cold-chain maintenance at two-to-eight degrees Celsius. Demand concentrates in United States pediatric intensive care units, where FDA breakthrough designations have compressed approval timelines for extended half-life formulations. Reimbursement frameworks in Germany and Japan prioritize these agents for high-risk neonatal populations.
- Vaccine Candidates:Recombinant subunit and mRNA platforms targeting maternal and older-adult immunization are advancing through Phase III programs. United States integrated delivery networks are pre-negotiating procurement contracts ahead of anticipated FDA approvals, with EMA accelerated assessment pathways enabling parallel European market entry.
- Antiviral Agents:Small-molecule polymerase inhibitors serve acute treatment settings with standard refrigeration requirements.
- Fusion Inhibitors:Peptide-based entry blockers target niche immunocompromised populations with specialized administration protocols.
Monoclonal antibodies lead volumes today; vaccine candidates are gaining share fastest.
Therapy Area:
Pediatric applications anchor revenue concentration, though demographic shifts toward aging populations are redistributing clinical trial investment across indication categories.
- Pediatric Care:Neonatal prophylaxis programs in United States children's hospitals account for the dominant share of monoclonal antibody utilization. Germany's national reimbursement framework for high-risk infant populations is expanding eligibility criteria, pulling additional volume through hospital procurement channels.
- Geriatric Care:Adults over sixty-five face rising hospitalization risk from RSV infection, driving Phase III program expansion. United States Medicare reimbursement pathways for older-adult immunization are opening commercial opportunities beyond traditional pediatric applications.
- Immunocompromised Conditions:Stem cell transplant recipients and oncology patients require extended prophylaxis duration.
- Respiratory Diseases:Patients with chronic obstructive pulmonary disease represent an emerging target population for antiviral therapy.
Pediatric care generates the highest revenue concentration; geriatric care shows the steepest expansion trajectory.
End User:
Facility type determines distribution infrastructure requirements, with inpatient settings maintaining cold-chain capabilities that outpatient networks are only now deploying.
- Hospitals:Pediatric and geriatric units in United States academic medical centers administer intravenous monoclonal antibodies with established nursing protocols. Japan's hospital networks are retrofitting infrastructure to accommodate subcutaneous outpatient models, creating transitional friction during product innovation cycles.
- Outpatient Facilities:Pharmacy-based clinics in Germany are adopting subcutaneous administration for seasonal prophylaxis programs. These settings reduce hospital dependency and enable population-scale immunization campaigns with lower per-dose administration costs.
- Specialty Clinics:Pulmonology and infectious disease centers manage complex RSV cases in immunocompromised patients.
- Research Institutes:Clinical trial sites conduct Phase I-III studies for novel therapeutic platforms.
Hospitals retain the dominant procurement volume; outpatient facilities are climbing the fastest.
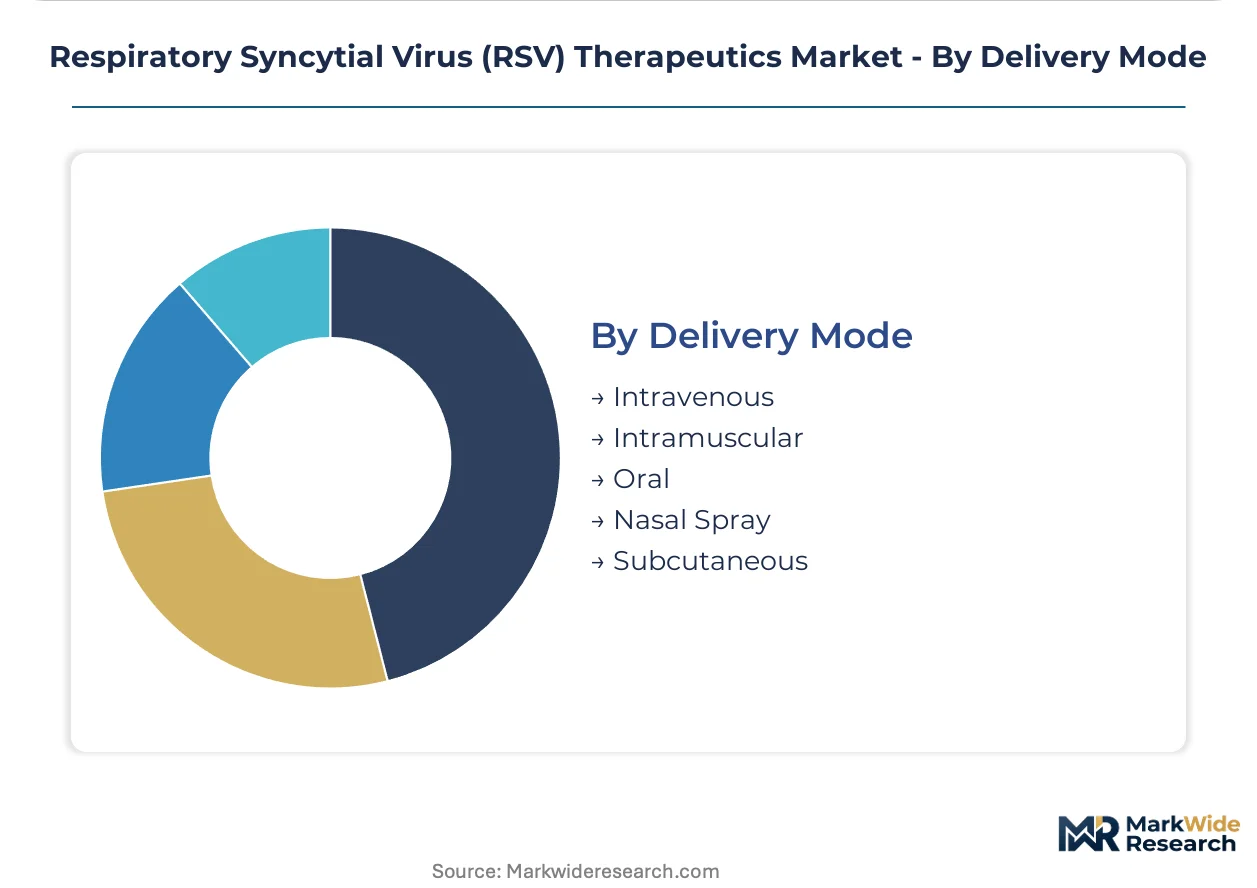
Delivery Mode:
Route of administration shapes supply chain configuration, with temperature-sensitive biologics requiring specialized handling that oral and nasal alternatives circumvent.
- Intravenous:Hospital-based infusion of monoclonal antibodies dominates acute treatment settings in United States and Japanese markets. This delivery mode requires nursing supervision and dedicated infusion chairs, constraining throughput during seasonal epidemic peaks.
- Subcutaneous:Outpatient administration is displacing intravenous delivery in prophylaxis programs, enabling pharmacy-based distribution models. United States integrated delivery networks are standardizing subcutaneous protocols across member institutions to reduce hospital burden.
- Intramuscular:Vaccine candidates utilize standard immunization infrastructure with minimal cold-chain requirements.
- Oral:Antiviral agents offer patient-administered convenience for outpatient treatment courses.
- Nasal Spray:Mucosal delivery platforms remain in early development for pediatric populations.
Intravenous delivery leads current volumes; subcutaneous formulations are expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Massachusetts anchors bioprocess engineering talent concentration for RSV monoclonal antibody manufacturing, with Basel and Cambridge forming secondary capability clusters. FDA breakthrough therapy designations and EMA accelerated assessments are compressing commercialization timelines across regulated markets. Cold-chain infrastructure maturation in Japan and reimbursement framework expansion in Germany are redistributing procurement volume geographically.
United States
Pediatric intensive care units in academic medical centers drive monoclonal antibody utilization for neonatal prophylaxis. FDA breakthrough therapy designations compress development timelines for extended half-life formulations entering pediatric formularies. The Greater Boston biotech corridor concentrates purification and downstream processing expertise, constraining manufacturing expansion timelines for new entrants.
Germany
National reimbursement frameworks for high-risk infant populations broaden prophylactic eligibility criteria through hospital procurement channels. EMA accelerated assessment pathways shorten commercialization timelines for novel monoclonal antibodies targeting neonatal populations. Bavaria's pharmaceutical manufacturing base anchors fill-finish capacity for European distribution networks.
Japan
Hospital networks retrofit infrastructure to accommodate subcutaneous outpatient models, creating transitional friction during product innovation cycles. PMDA review standards align with WHO prequalification benchmarks for regional immunization program access. The Kanto region's cold-chain distribution networks stabilize F-protein binding affinity preservation for temperature-sensitive biologics.
United Kingdom
Integrated delivery networks standardize formulary decisions across member institutions, consolidating supplier relationships for seasonal biologics. MHRA post-Brexit regulatory pathways diverge from EMA timelines, creating parallel submission requirements for market entry. The Cambridge-London corridor concentrates clinical trial site density for Phase III maternal immunization programs.
Switzerland
Swissmedic approval pathways enable early access programs for breakthrough biologics ahead of broader European market entry. Basel's bioprocess engineering talent pool supports contract manufacturing organization capacity for antibody purification workflows. The country's pharmaceutical cluster maintains legacy relationships with multi-source procurement committees across German and French hospital networks.
Respiratory Syncytial Virus (RSV) Therapeutics Market Key Industry Players
Global majors compete with regional champions across immunization infrastructure and manufacturing scale dimensions. The market structure concentrates around integrated pharmaceutical conglomerates with established pediatric formulary relationships and specialized biotech entities advancing novel platform technologies. Three archetypes dominate: legacy vaccine manufacturers leveraging distribution networks, recombinant protein specialists commanding manufacturing scale, and platform technology innovators compressing discovery timelines. Competitive moves center on manufacturing capacity expansion ahead of regulatory approvals and strategic partnerships securing cold-chain distribution access.
Within the legacy immunization infrastructure tier, Sanofi and GSK plc occupy positions anchored by established hospital network relationships across European and North American markets. Pfizer represents the manufacturing-scale archetype through recombinant protein production capabilities. These three entities exemplify competitive positioning strategies built on formulary consolidation and seasonal procurement committee engagement.
| Leading Market Players |
|---|
| Sanofi |
| Moderna |
| AstraZeneca |
| Bausch Health Companies |
| AbbVie |
| Pfizer |
| Merck & Co |
| Johnson & Johnson |
| GSK plc |
| Others |
Cost & Logistics Intelligence
Private-equity-rolled-up contract manufacturing organizations in Ireland and Belgium concentrate fill-finish capacity for European distribution, anchoring supply discipline and enabling premium pricing for temperature-sensitive biologics through controlled scarcity. This ownership pattern reinforces margin structures for monoclonal antibody producers while constraining downstream price competition.
Pricing Analysis
Input-cost pass-through from CHO cell culture media volatility determines pricing trajectories for recombinant protein manufacturers. Three-tier pricing structure across premium extended half-life formulations, standard monthly-dose antibodies, and economy-tier antiviral agents reflects F-protein binding affinity preservation and cold-chain burden. Pricing pressure stems from immunobridging study requirements extending clinical program durations. Pediatric intensive care units exhibit lowest price sensitivity due to breakthrough therapy designations, while outpatient pharmacy clinics face tightening procurement budgets.
Supply Chain Analysis
Regional distribution centers in Massachusetts, Basel, and Cambridge form a hub-and-spoke pattern for bioprocess engineering talent and purification capacity. Manufacturing concentrates in the United States, Switzerland, and Germany, drawing from South American and New Zealand serum supply sources. Single-source dependency in Irish and Belgian fill-finish operations creates geographic vulnerability. Distribution runs through hospital procurement committees consolidating toward sole-source agreements with volume guarantees.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Respiratory Syncytial Virus Therapeutics Market functions as a stable compounder, with seasonal epidemic recurrence generating predictable demand cycles for prophylactic biologics.
For Market Incumbents: Anticipate regulatory velocity from FDA breakthrough therapy designations compressing competitive windows. Defend formulary position through backward integration into CHO cell culture media supply and capacity expansion in Basel-region purification facilities. Counter emerging platform technology innovators by securing exclusive cold-chain distribution partnerships with integrated delivery networks. For New Entrants and Emerging Players: Capture white-space opportunity in subcutaneous outpatient administration models displacing intravenous delivery. Target German pharmacy-based clinics adopting seasonal prophylaxis programs with lowest incumbent penetration. Enter through WHO prequalification alignment for low- and middle-income country procurement pathways. For Investors and Strategic Acquirers: Large-cap vaccine manufacturers with established immunization infrastructure are the most active acquirers in this space. Five-to-ten year viability hinges on maternal immunization platform diversification beyond pediatric applications. Acquisition targets include platform technology innovators with extended half-life antibody engineering capabilities. Watch FDA guidance evolution on real-world evidence requirements as inflection indicator for valuation multiples.| Strategic Initiative | Industry Significance |
|---|---|
| Manufacturing Scale-Up | CHO cell culture capacity expansion in Massachusetts secures serum supply continuity for F-protein antibody production. |
| Regulatory Approval Pathway | EMA accelerated assessment enables parallel European market entry alongside FDA breakthrough designations. |
| Pipeline Diversification | Maternal immunization platforms reduce revenue concentration in seasonal pediatric prophylaxis. |
| Licensing Agreement | Subcutaneous formulation technology licensing displaces hospital-dependent intravenous administration. |
| Clinical Trial Advancement | Phase III programs for older-adult populations open Medicare reimbursement pathways beyond neonatal applications. |
Research Approach
Coverage spans the United States, Germany, Japan, and Switzerland, with primary inputs from each market cluster. Primary interviews with drug development executives, regulatory affairs leads, hospital procurement managers, and formulary directors combined with secondary validation from FDA filings, EMA submissions, ClinicalTrials.gov, and formulary databases. Bottom-up patient population modeling and top-down revenue triangulation anchored forecast construction.
Granularity-level modeling operated at the intersection of therapy area, delivery mode, and regional regulatory cluster. Segmentation dimensions included monoclonal antibodies versus vaccine candidates, pediatric versus geriatric care settings, intravenous versus subcutaneous administration, and United States-Germany-Japan-Switzerland country clusters. CAGRs derived from epidemiological trend extrapolation, reimbursement framework expansion rates, and biologics adoption curves across the projection horizon. Industry-specific inputs incorporated RSV seasonality patterns and hospitalization burden data.
Regulatory pathway delays, CHO cell culture media supply disruptions, and immunobridging study outcome variability are the dominant revision risks. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Disruptive Behavior Disorders Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Glioblastoma Multiforme Treatment (GBM) Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Abetalipoproteinemia Management Market
Specialty Medicine
Hermansky Pudlak Syndrome Therapeutics Market
Specialty Medicine
Global Calciphylaxis Treatment Market
Specialty Medicine
Global Specialty Injectable Generics Market
Specialty Medicine
Grand Mal Seizure Market
Specialty Medicine
United States Specialty Generics Market
Specialty Medicine
Scleritis Market
Specialty Medicine
Essential Thrombocythemia Market
Specialty Medicine
APOL1 Mediated Kidney Disease Market
Specialty Medicine
Barlow's Syndrome Market
Specialty Medicine
Congenital Adrenal Hyperplasia Treatment Market
Specialty Medicine
Ovarian Cysts Market