
 Gerontology/Aging Market | 2026-2036
Gerontology/Aging Market Size, Share, and Industry Trends Forecast 2026-2036
Gerontology/Aging Market Foresight
The EU Medical Device Regulation (MDR) is repositioning compliance costs for European entrants, forcing smaller device manufacturers to consolidate certification resources. Philips Healthcare leverages its sleep and respiratory portfolio to dominate European homecare channels, while Medtronic anchors its cardiac monitoring franchise through direct hospital contracting. Abbott Laboratories differentiates via continuous glucose monitoring systems tailored to diabetic elderly populations.
Gerontology and aging science encompasses the multidisciplinary study of biological, psychological, and social processes in later life, with assistive technologies typically integrating sensors, actuators, and cloud-based analytics to preserve functional independence. Monitoring systems command the largest revenue pool due to recurring subscription models and clinician workflow integration, while telehealth platforms represent the fastest-expanding distribution channel as payer reimbursement for virtual geriatric consultations broadens across jurisdictions. Skincare products occupy a mature, margin-compressed segment where pharmacy generics compete against premium dermatology brands.
The FDA governs device safety and software-as-medical-device claims for US-based elderly care technologies, while the EMA coordinates centralized market access across EU member states for novel therapeutic interventions in age-related conditions. Japan's PMDA accelerates conditional approval pathways for AI-enabled fall detection and medication adherence tools, reflecting METI's strategic prioritization of silver economy exports. Stakeholders must track divergent data localization requirements between FDA's 21 CFR Part 820 quality system mandates and GDPR-aligned health data governance in European care settings, as cross-border platform scaling depends on resolving these compliance asymmetries.
Market Dynamics
Medicare Advantage expansion is compressing reimbursement timelines for preventive geriatric services, forcing providers to restructure care delivery around remote monitoring infrastructure and value-based contracting mechanisms rather than fee-for-service billing.
Growth Catalysts
- Japan's Silver Economy Export Strategy:METI prioritizes AI-enabled fall detection and medication adherence tools through PMDA accelerated approval pathways, creating regulatory tailwinds for domestic manufacturers targeting aging populations.
- Remote Monitoring Subscription Models:Cloud-based analytics platforms integrate clinician workflow tools, generating recurring revenue streams that sustain capital deployment for sensor-actuator networks in home healthcare.
- Medicare Advantage Penetration:CMS reimbursement flexibility for virtual geriatric consultations expands payer coverage for telehealth platforms, redirecting patient volume from institutional settings.
Market Restraints
- EU MDR Compliance Burden:Smaller device manufacturers face consolidated certification costs as notified body capacity constraints delay market access for novel assistive technologies.
- Semiconductor Supply Concentration:Sensor component fabrication concentrates in East Asian foundries, exposing European and North American device assemblers to input volatility and extended lead times.
- Interoperability Technical Limitations:Proprietary data formats between competing monitoring platforms prevent seamless clinician dashboard integration, fragmenting patient record continuity.
Strategic Opportunities
- Underpenetrated Rural US Markets:Federally Qualified Health Centers in Appalachian and Great Plains regions lack specialist geriatric capacity, creating white space for asynchronous telehealth consultation platforms.
- EU AI Act Compliance Services:Risk classification requirements for AI-enabled diagnostic tools generate adjacent revenue streams for regulatory consulting and conformity assessment providers.
- Voice-User Interface Convergence:Natural language processing integration with ambient sensor networks enables hands-free emergency alerting for mobility-limited elderly populations.
Industry Challenges
- Geriatric Care Workforce Scarcity:Board-certified geriatricians per capita remains insufficient across OECD markets, constraining clinical validation and deployment oversight for new monitoring technologies.
- Legacy EHR Integration Complexity:Hospital system procurement committees demand bidirectional data exchange with existing electronic health record architectures, extending sales cycles for standalone platform vendors.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Gerontology/Aging Market |
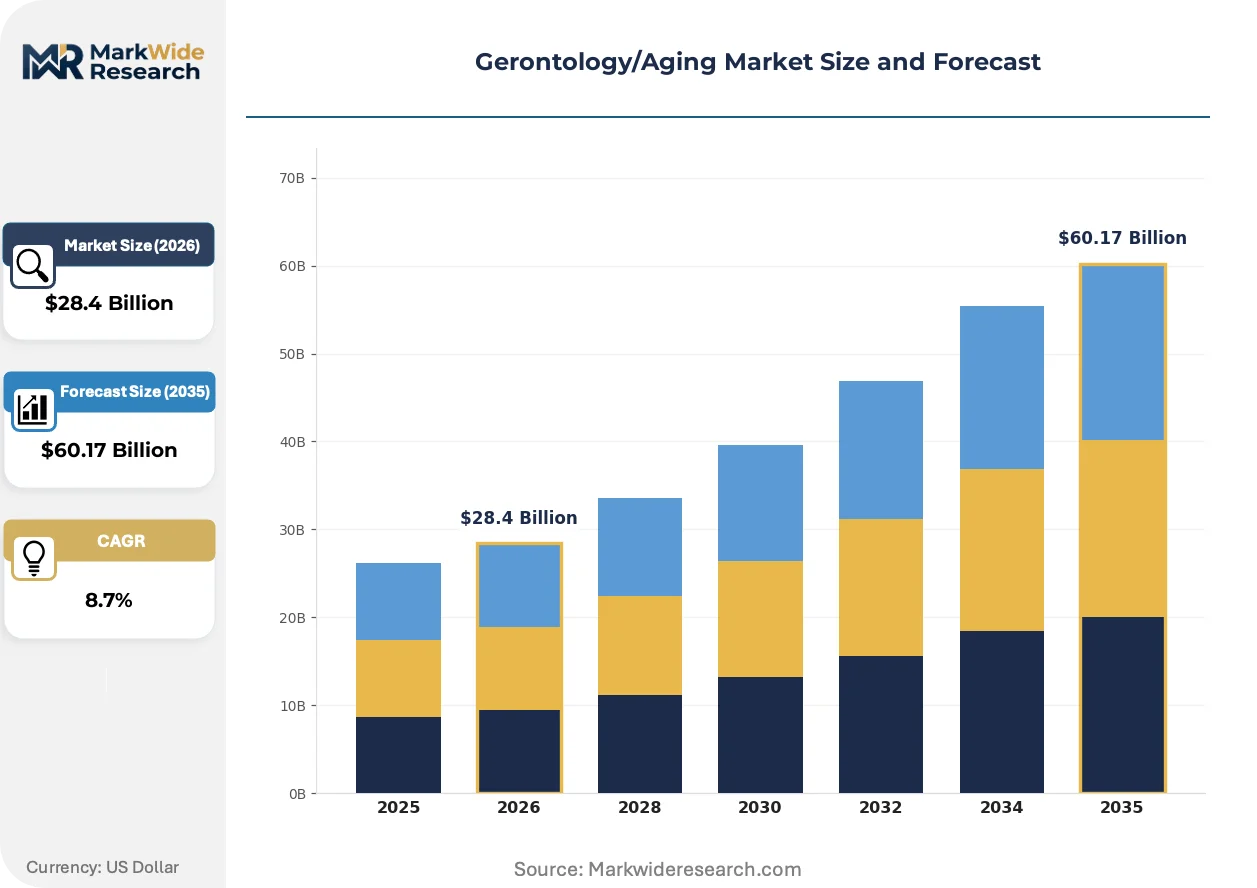
| Market Size in 2026 | $28.4 Billion |
| Market Size in 2035 | $60.17 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Assistive Devices, Nutritional Supplements, Monitoring Systems, Skincare Products, Mobility Aids Therapy Area: Cognitive Health, Bone & Joint Care, Cardiovascular Wellness, Mental Well-being, Sensory Enhancement Care Setting: Retirement Homes, In-Home Care, Daycare Centers, Rehabilitation Facilities, Private Clinics Distribution Channel: Online Pharmacies, Specialty Retailers, Hospitals & Clinics, Direct Sales, Telehealth Platforms |
| Companies Covered | Brookdale Senior Living, Amedisys, Philips Healthcare, Medtronic, Abbott Laboratories, Essity, Invacare Corporation, ResMed, McKesson Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Gerontology/Aging Market Shifts & Advancements
Sensor miniaturization and edge computing architectures are collapsing the cost curve for continuous physiological monitoring, enabling consumer-grade devices to encroach on clinical-grade diagnostic territory previously reserved for hospital-based equipment.
Passive radar and millimeter-wave sensing is electrifying non-contact fall detection and gait analysis in residential settings. Assisted living operators in Scandinavia and Japan deploy ceiling-mounted arrays to eliminate wearable compliance failures among cognitively impaired residents. This contactless architecture is compressing liability insurance premiums while reducing nighttime staffing ratios.
The EU Medical Device Regulation reclassifies software-as-medical-device claims for elderly care algorithms, mandating clinical evidence portfolios that previously applied only to hardware implants. German notified bodies report eighteen-month backlog queues for novel AI diagnostic submissions. Cardiac monitoring wearables and sleep apnea screening applications face the steepest compliance trajectory adjustments.
Family caregiver procurement patterns are fragmenting across direct-to-consumer channels, bypassing traditional durable medical equipment distributors. Adult children research and purchase monitoring subscriptions through app stores and telehealth portals rather than physician referrals. This channel rotation concentrates in US metropolitan markets where Medicare Advantage supplemental benefits cover over-the-counter device allowances.
Gerontology/Aging Market Segmentation
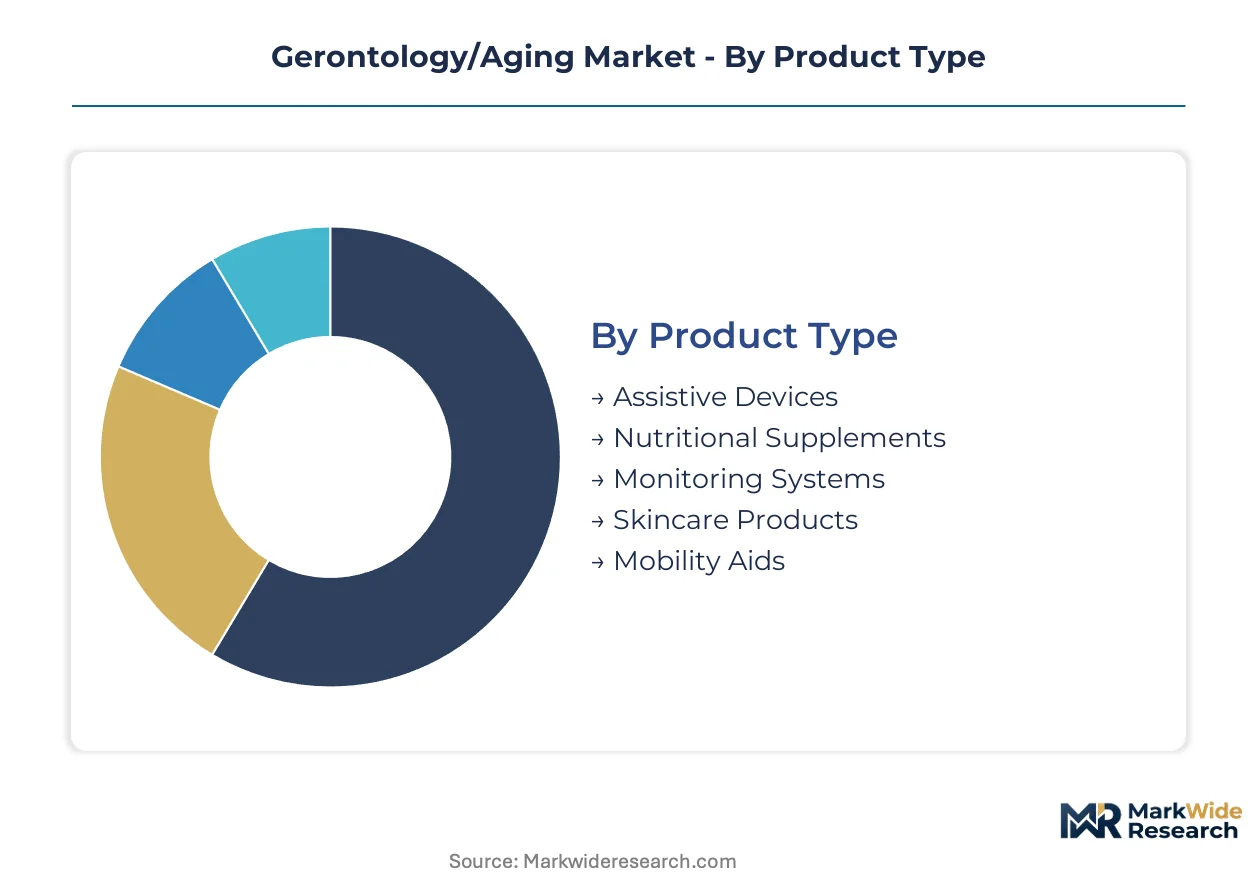
Segmentation in gerontology markets reflects divergent compliance pathways and reimbursement eligibility. Product-level FDA 510(k) clearance, EU MDR classification, and Japan PMDA accelerated tracks create tiered market access costs that reshape competitive positioning across categories.
Product Type:
Assistive devices and monitoring systems carry the heaviest certification burdens under FDA 21 CFR Part 820 and EU MDR software-as-medical-device rules, while nutritional supplements and skincare products navigate lighter regulatory frameworks through DSHEA and cosmetic directives.
- Monitoring Systems:Cloud-integrated sensor networks with clinician dashboard connectivity command premium positioning through recurring subscription economics. Demand concentrates in Japanese metropolitan corridors where METI silver economy subsidies accelerate deployment of AI-enabled fall detection infrastructure, though EU MDR eighteen-month notified body backlogs constrain European rollout velocity.
- Assistive Devices:Sensor-actuator combinations for medication adherence and emergency alerting integrate voice-user interfaces with ambient residential networks. German and Scandinavian assisted living operators drive procurement volume for ceiling-mounted passive radar arrays that eliminate wearable compliance failures among cognitively impaired residents.
- Mobility Aids:Motorized wheelchairs and transfer equipment face FDA Class II device controls with substantial equivalence requirements for novel drive systems.
- Nutritional Supplements:Protein fortification and micronutrient formulations targeting sarcopenia prevention distribute primarily through pharmacy and direct-to-consumer channels with minimal pre-market approval.
- Skincare Products:Dermatological moisturizers and barrier creams for fragile elderly skin compete in margin-compressed segments where pharmacy generics pressure premium brand positioning.
Monitoring systems sit at the top of the volume ranking, with assistive devices climbing the fastest.
Therapy Area:
Cost tier stratification separates diagnostic-grade interventions from wellness-positioned offerings, with cardiovascular and cognitive health commanding reimbursement premiums over sensory and mental well-being categories.
- Cardiovascular Wellness:Continuous arrhythmia detection and blood pressure variability monitoring integrate with Medicare Advantage remote patient monitoring billing codes. Abbott Laboratories and Medtronic anchor hospital contracting channels through cardiac wearable ecosystems that feed directly into electronic health record workflows.
- Cognitive Health:Digital therapeutics for mild cognitive impairment and dementia care face FDA breakthrough device designation pathways with accelerated review timelines. Japanese PMDA conditional approvals for AI-enabled cognitive assessment tools reflect METI export prioritization.
- Bone & Joint Care:Osteoporosis screening and fall risk assessment protocols concentrate in US Federally Qualified Health Centers with specialist geriatrician scarcity.
- Sensory Enhancement:Hearing aid amplification and vision correction devices navigate FDA Class I/II distinctions with varying clinical evidence requirements.
- Mental Well-being:Depression and anxiety interventions for elderly populations distribute through telehealth platforms with expanding payer coverage for virtual psychiatric consultations.
Cardiovascular wellness commands the steepest pricing tier, while cognitive health gains share fastest through regulatory fast-track mechanisms.
Care Setting:
Customer type fragmentation separates institutional procurement committees from family caregiver direct purchasing, with channel rotation reshaping vendor go-to-market economics.
- In-Home Care:Aging-in-place technology stacks combine remote monitoring subscriptions with asynchronous telehealth consultation platforms. US Medicare Advantage supplemental benefits increasingly cover over-the-counter device allowances, redirecting procurement through app stores and direct-to-consumer portals rather than durable medical equipment distributors.
- Retirement Homes:Scandinavian and Japanese assisted living operators deploy ceiling-mounted millimeter-wave sensing arrays for contactless fall detection, compressing liability insurance premiums while enabling nighttime staffing ratio reductions.
- Rehabilitation Facilities:Post-acute care settings drive demand for gait analysis and mobility restoration technologies with bundled payment reimbursement structures.
- Daycare Centers:Adult day services concentrate procurement on social engagement and cognitive stimulation technologies with lower acuity monitoring requirements.
- Private Clinics:Concierge geriatric practices in US metropolitan markets adopt continuous glucose monitoring and sleep apnea screening for diabetic elderly populations.
In-home care dominates current deployment volume, with retirement homes expanding most quickly through Scandinavian and Japanese operator consolidation.
Distribution Channel:
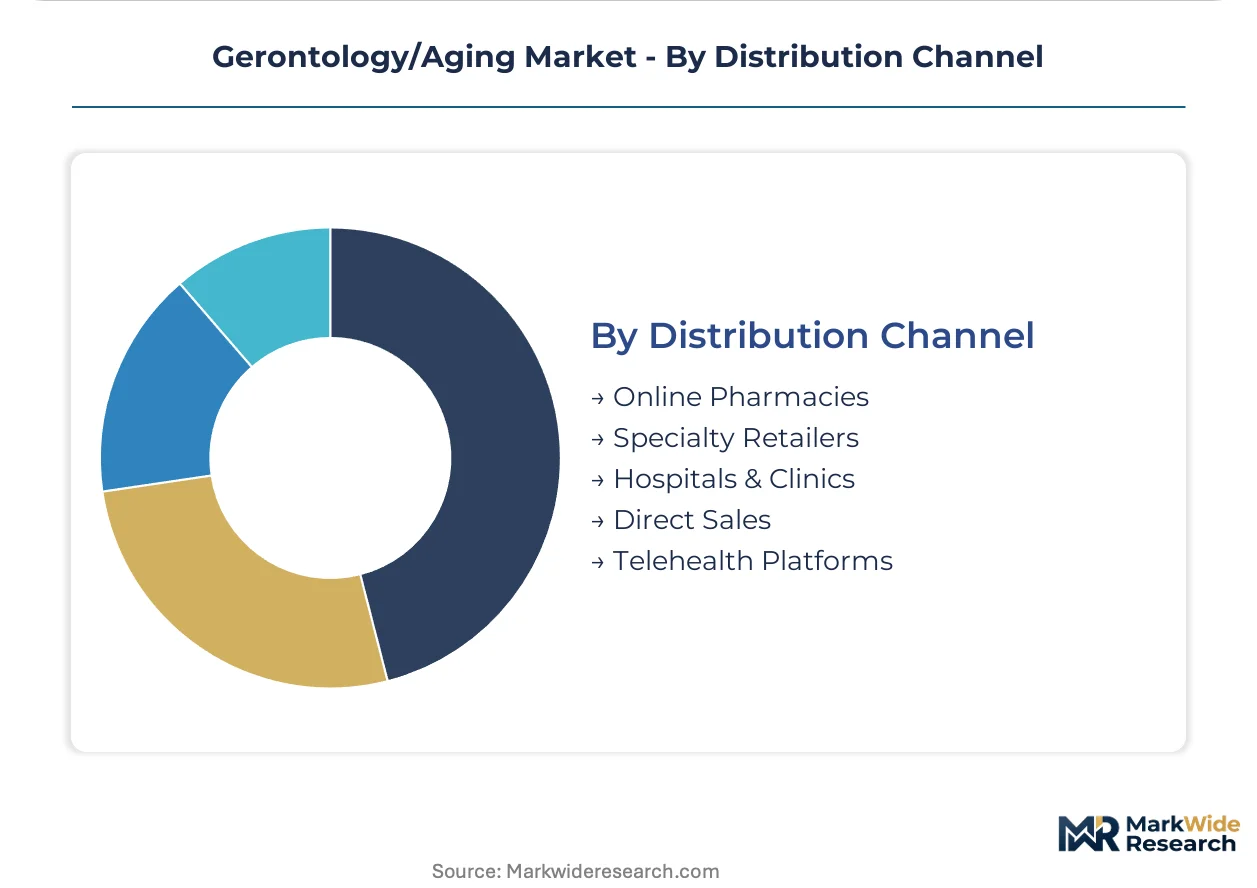
Geographic concentration of platform infrastructure determines channel viability, with telehealth reimbursement breadth varying sharply across US state Medicaid programs and EU national health systems.
- Telehealth Platforms:Virtual geriatric consultation reimbursement expansion redirects patient volume from institutional settings, with CMS flexibility for asynchronous and synchronous remote care broadening payer coverage. Platform vendors face state-by-state licensure complexity that fragments scaling economics.
- Online Pharmacies:Direct-to-consumer supplement and skincare distribution bypasses traditional pharmacy networks, concentrating in metropolitan markets with higher digital literacy among adult children caregivers.
- Hospitals & Clinics:Health system procurement committees demand bidirectional EHR integration, extending sales cycles for standalone monitoring platform vendors.
- Specialty Retailers:Hearing aid and vision correction specialists maintain geographic footprint advantages for elderly populations with limited digital access.
- Direct Sales:High-consideration mobility aid purchases retain in-home demonstration requirements for proper fitting and training protocols.
Telehealth platforms represent the steepest expansion trajectory, while hospitals and clinics retain the largest transaction values per account.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Geriatrician workforce density varies sharply across OECD markets, with Japan's super-aged demography and METI industrial policy creating the most concentrated deployment of AI-enabled eldercare infrastructure.
United States
Medicare Advantage penetration now exceeds fifty percent of eligible seniors, redirecting reimbursement toward remote patient monitoring and value-based preventive care. CMS flexibility for virtual geriatric consultations expands telehealth platform viability, though state-by-state licensure fragments scaling economics. The Southeast corridor from Florida to Georgia concentrates assisted living operator consolidation and fall-detection technology procurement.
Japan
Super-aged demographic density drives PMDA accelerated approval pathways for AI-enabled fall detection and medication adherence tools as METI prioritizes silver economy exports. Conditional regulatory tracks compress time-to-market for domestic manufacturers targeting aging populations. Tokyo-Osaka metropolitan corridors anchor robotic assistance deployment and remote monitoring infrastructure investment.
Germany
EU MDR notified body capacity constraints delay market access for novel assistive technologies, with eighteen-month backlogs reported for AI diagnostic submissions. REACH compliance adds material science burdens to sensor-actuator device certification. Bavarian and Baden-Württemberg industrial clusters concentrate medical device engineering talent and notified body proximity.
United Kingdom
NHS Long Term Plan commitments to aging-in-place shift procurement toward home healthcare technology stacks, though post-Brexit regulatory divergence from EU MDR creates parallel compliance tracks. MHRA streamlined routes for software-as-medical-device claims attract digital health vendors. London-Southeast corridor dominates telehealth platform development and venture deployment.
Sweden
Scandinavian assisted living operators pioneer ceiling-mounted passive radar and millimeter-wave sensing arrays for contactless fall detection, compressing liability insurance premiums while enabling nighttime staffing reductions. GDPR-aligned health data governance shapes platform architecture for cross-border scaling. Stockholm-Uppsala corridor concentrates health technology R&D and ambient sensor network deployment.
Gerontology/Aging Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across tiered certification and channel access vectors. Hospital system procurement committees demand bidirectional EHR integration, extending sales cycles for standalone platform vendors while favoring incumbent device manufacturers with established clinical workflow relationships. Three archetypes dominate: diversified health technology conglomerates with sleep and respiratory portfolios, cardiac monitoring specialists with direct hospital contracting franchises, and assistive device pure-plays with sensor-actuator integration capabilities. Competitive moves concentrate on M&A for regulatory certification assets and strategic partnerships for EHR interoperability.
Among diversified health technology conglomerates, Philips Healthcare and Medtronic exemplify contrasting channel strategies, with the former leveraging homecare distribution networks and the latter anchoring hospital-based cardiac monitoring ecosystems. Abbott Laboratories occupies a position bridging diagnostic-grade wearable deployment and chronic disease management for diabetic elderly populations. These three entities represent the dominant archetypes: diversified platform vendors, cardiac-focused hospital contractors, and metabolic monitoring specialists.
| Leading Market Players |
|---|
| Brookdale Senior Living |
| Amedisys |
| Philips Healthcare |
| Medtronic |
| Abbott Laboratories |
| Essity |
| Invacare Corporation |
| ResMed |
| McKesson Corporation |
| Others |
Supply & Pricing Matrix
Certification-grade divergence between FDA 510(k)-cleared clinical devices and direct-to-consumer wellness products splits both pricing power and supplier networks, with premium tiers commanding subscription economics while commodity segments compete on component sourcing efficiency. This bifurcation concentrates margin capture in cloud-integrated monitoring platforms while compressing returns for hardware-only assemblers exposed to semiconductor input volatility.
Pricing Analysis
Bundled remote monitoring subscriptions with clinician dashboard access command recurring revenue premiums against unbundled device-only transactions, with three-tier pricing structure across premium, standard, and economy levels reflecting FDA clearance status and EHR integration depth. Price differentiation stems from certification tier under EU MDR and Japan PMDA tracks alongside after-sales service bundling. Pricing pressure stems from Medicare Advantage reimbursement compression forcing providers toward value-based contracts. Family caregivers purchasing through direct-to-consumer channels exhibit highest price sensitivity, while hospital procurement committees prioritize workflow integration over unit cost.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale demand from Japanese assisted living operators and US Medicare Advantage plans, while distributor networks serve fragmented rural clinic procurement. Sensor component fabrication concentrates in Taiwan, South Korea, and Japan, with cloud infrastructure anchoring in US and EU data centers. Raw material dependencies include MEMS sensors, lithium-ion cells, and medical-grade polymers. Single-source vulnerability in East Asian foundry capacity exposes European and North American assemblers to extended lead times. Distribution runs through telehealth platforms, hospital GPOs, and durable medical equipment specialists.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play where EU MDR eighteen-month notified body backlogs create cost and timing disadvantages against Japan's PMDA accelerated approval pathways for identical AI-enabled diagnostic tools.
For Market Incumbents: To counter proprietary data format fragmentation that prevents seamless EHR integration, Philips Healthcare and Medtronic should deepen backward integration into sensor-actuator networks while acquiring regulatory certification assets in EU notified body-proximate clusters. Channel control through direct hospital contracting franchises remains the priority defensive lever against telehealth platform disintermediation.
For New Entrants and Emerging Players: Federally Qualified Health Centers in Appalachian and Great Plains regions offer the most penetrable white space, given specialist geriatrician scarcity and asynchronous telehealth platform underdeployment. Adult children caregivers researching through app stores represent a direct-to-consumer angle bypassing traditional durable medical equipment distributor gatekeepers. Target EU AI Act compliance services as an adjacent revenue stream.
For Investors and Strategic Acquirers: Consolidation pressure builds where EU MDR certification costs force smaller device manufacturers to surrender standalone market access capabilities. Long-term viability over the mid-decade horizon favors platforms with recurring subscription economics and clinician workflow integration. Acquisition target archetypes include assistive device pure-plays with voice-user interface capabilities and sensor-actuator integration. Watch PMDA conditional approval velocity versus EU MDR backlog duration as the signal for geographic portfolio reweighting.
| Strategic Initiative | Industry Significance |
|---|---|
| PMDA Accelerated Approval Pathway | Japan's METI prioritization compresses time-to-market for AI-enabled fall detection and medication adherence tools. |
| Hospital System Partnership | Direct contracting with Medicare Advantage plans secures bidirectional EHR integration and remote patient monitoring billing codes. |
| EU MDR Certification Investment | German notified body proximity reduces eighteen-month backlog exposure for cardiac monitoring wearable submissions. |
| Software Companion Development | Cloud-based analytics platforms generate recurring subscription revenue through clinician dashboard integration. |
| Reimbursement Strategy | CMS flexibility for virtual geriatric consultations expands telehealth platform payer coverage across state Medicaid programs. |
Research Methodology
Bottom-up care setting modeling reconciled against top-down regulatory pathway tracking forms the analytical core, combining primary interviews with geriatric care executives, hospital purchasing committee chairs, biomedical engineers, and GPO contracts managers with secondary validation through FDA 510(k) filings, PMDA approval databases, CMS Medicare Advantage penetration data, and EU MDR notified body submission records. Triangulation across stakeholder perspectives and documentary sources ensures segmentation integrity.
Input-output matrices map sensor component supply through device assembly to distribution channel economics, with volume and value outputs reconciled across product type, therapy area, care setting, and distribution channel dimensions throughout the forecast period. CAGRs derive from regression analysis against demographic aging curves and reimbursement policy trajectories, with Japan's super-aged density and US Medicare Advantage penetration serving as primary demand anchors.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to EU MDR notified body capacity expansion, semiconductor supply normalization, and geriatrician workforce pipeline constraints. Periodic stress-testing of base assumptions is recommended.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Specialty Medicine
Cholangiocarcinoma Market
Specialty Medicine
Pyoderma Gangrenosum Therapeutics Market
Specialty Medicine
Primary Sclerosing Cholangitis (PSC) Market
Specialty Medicine
Global Hormone Replacement Therapy Market
Specialty Medicine
Global Major Depressive Disorder (MDD) Market
Specialty Medicine
Listeriosis Treatment Market
Specialty Medicine
Global Female Sexual Dysfunction Treatment Market
Specialty Medicine
Global Attention Deficit Hyperactivity Disorder Market
Specialty Medicine
Global Pancreatic Cancer Therapeutics and Diagnostics Market
Specialty Medicine
Non Small Cell Lung Cancer (NSCLC) Therapeutics Market
Specialty Medicine
Dyschromia Therapeutics Market
Specialty Medicine
Global Gastroesophageal Reflux Disease Market
Specialty Medicine
North America Sports Medicine Market
Specialty Medicine
Global Cancer Immunotherapies Market
Specialty Medicine
Premature Ejaculation Treatment Market
Specialty Medicine
Kaposi Sarcoma Market