
 Global Carbon Nanomaterials Market | 2026-2036
Global Carbon Nanomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Global Carbon Nanomaterials Market Intelligence
The application focus for carbon nanomaterials is shifting from niche aerospace composites to high-volume energy storage systems. OCSiAl specializes in the scaled production of single-wall carbon nanotubes, enabling broader industrial use. Cabot Corporation leverages its extensive carbon manufacturing infrastructure to develop conductive additives for batteries. Concurrently, LG Chem integrates advanced nanomaterials directly into its next-generation battery cell chemistries, creating a captive demand stream.
Carbon nanomaterials are a class of carbon allotropes where at least one physical dimension is at the nanoscale, typically under 100 nanometers. These materials, including nanotubes and graphene sheets, exhibit exceptional mechanical strength, thermal conductivity, and electrical properties. Their primary industrial purpose is to function as additives that enhance the performance characteristics of base materials like polymers, metals, and ceramics. Carbon nanotubes, particularly multi-walled variants, command the largest market share by volume due to established production methods. Graphene, however, represents the fastest-growing product segment, fueled by its potential in advanced electronics and sensors.
The regulatory environment imposes significant compliance requirements on manufacturers. In Europe, the ECHA enforces REACH regulations, requiring extensive safety data for nanomaterial registration. Similarly, the US EPA governs new nanomaterials under the Toxic Substances Control Act (TSCA), scrutinizing potential health and environmental risks. These frameworks, along with China's GB standards, shape market entry strategies and material development priorities. Producers must navigate this evolving regulatory patchwork to unlock new markets in energy storage and advanced electronics.
Market Dynamics
The primary structural force shaping the carbon nanomaterials market is the immense demand from the energy storage sector. This pull, specifically for advanced lithium-ion batteries in electric vehicles, is reorienting supply chains and R&D priorities globally.
Growth Catalysts
- Battery Chemistry Evolution:The push for higher energy density and faster charging in electric vehicle batteries requires carbon nanotubes as essential conductive additives.
- Government EV Policies:China's dual carbon goals and related subsidies for electric vehicle manufacturing create a massive, concentrated demand center for battery materials.
- Advanced Electronics Miniaturization:The development of flexible sensors and next-generation semiconductors leverages graphene's unique electrical and thermal properties, opening new high-value applications.
Market Restraints
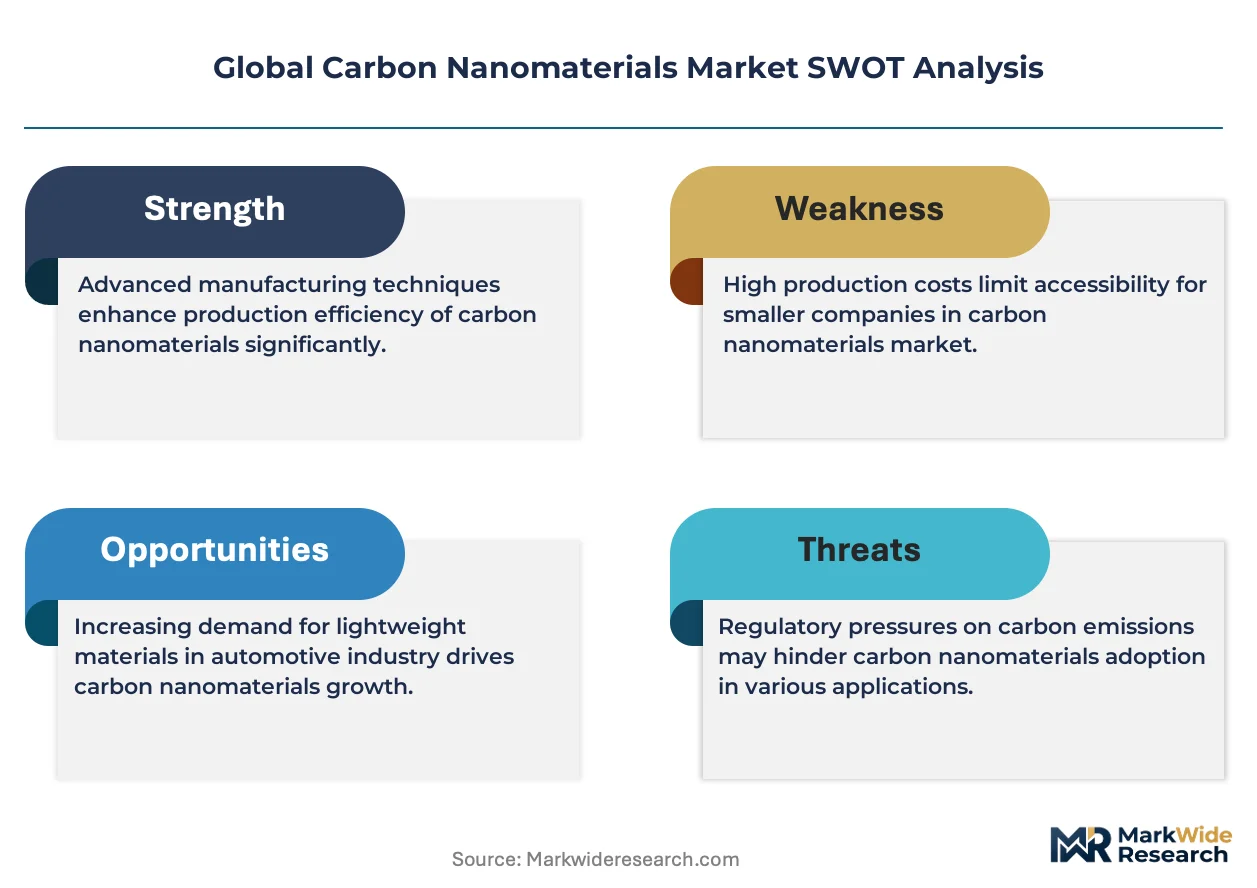
- High Production Costs:Energy-intensive synthesis of high-purity nanotubes and graphene results in high costs, limiting adoption in price-sensitive commodity applications.
- Regulatory Compliance Burden:Registration under Europe's REACH and the US's TSCA imposes significant costs and delays market access for new nanomaterial formulations.
- Material Dispersion Challenges:Achieving uniform dispersion of nanomaterials within host matrices like polymers remains a primary technical barrier affecting final product consistency.
Strategic Opportunities
- Emerging EV Hubs:India's growing electric vehicle and battery manufacturing sector is an underpenetrated market for conductive additives beyond China.
- Biomedical Applications:Functionalized carbon nanotubes in targeted drug delivery and medical imaging offer a high-value opportunity for specialized material grades.
- AI-Enabled Material Design:Using machine learning to accelerate the design of novel carbon allotropes with specific properties can create a strong competitive advantage.
Industry Challenges
- Standardization Deficit:The absence of universal standards for characterizing and grading carbon nanomaterials complicates quality control, hinders direct material comparisons, and creates procurement uncertainty for industrial end-users.
- Complex Production Scale-Up:Transitioning from laboratory synthesis to consistent, high-volume industrial production requires significant capital investment and scarce process engineering talent, slowing capacity expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Carbon Nanomaterials Market |
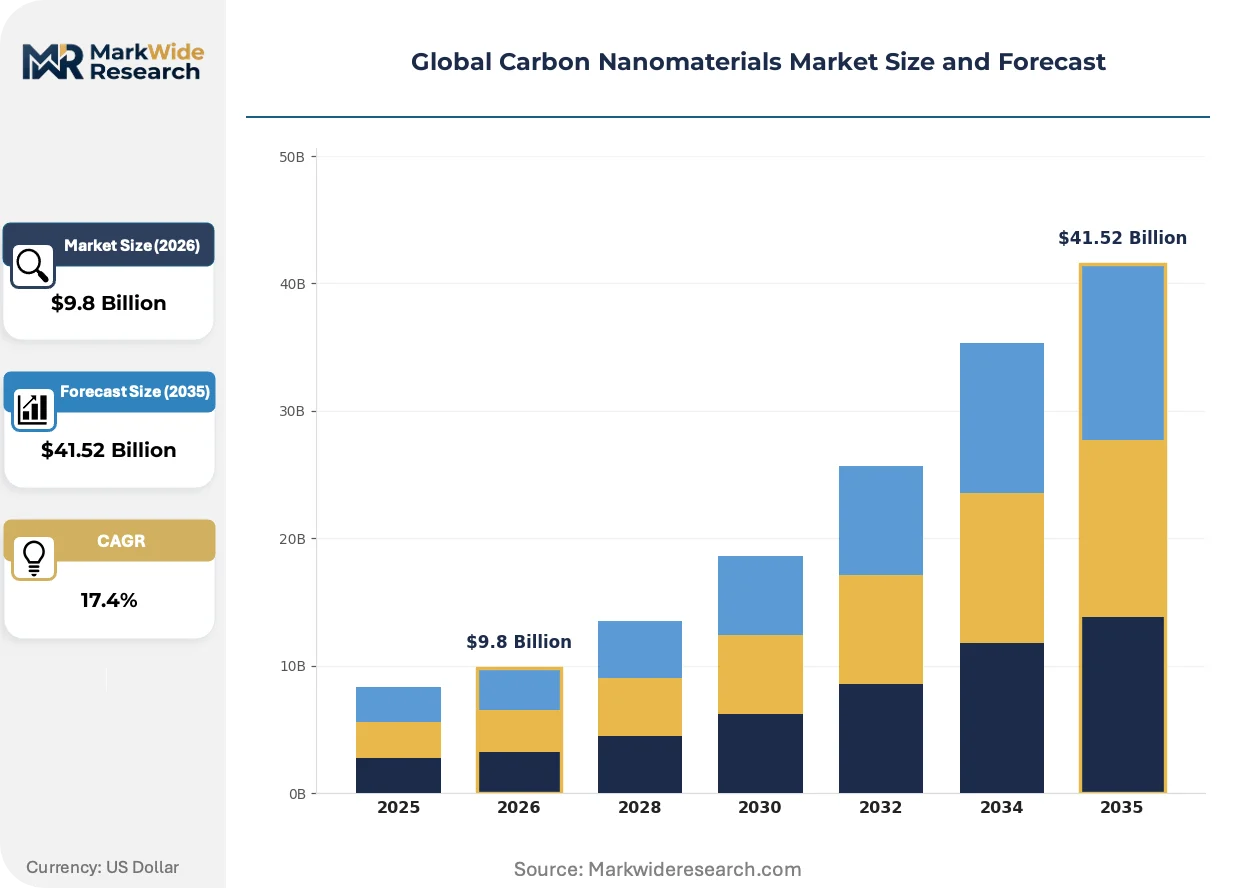
| Market Size in 2026 | $9.8 Billion |
| Market Size in 2035 | $41.52 Billion |
| CAGR (2026 – 2036) | 17.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Nanotubes, Graphene, Carbon Nanofibers, Fullerene, Carbon Quantum Dots Application: Electronics & Semiconductors, Energy Storage, Composite Materials, Sensors, Catalysis End User Industry: Consumer Electronics, Aerospace, Oilfield Services, Construction, Sports Equipment Form: Powder, Dispersion, Film, Bulk, Coating |
| Companies Covered | Jiangsu Cnano Technology, Arkema, OCSiAl, LG Chem, Cabot Corporation, CHASM Advanced Materials, Nanocyl, Nano-C, Dazhan Nanomaterials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Carbon Nanomaterials Market Strategic Shifts & Innovations
The market's evolution is marked by a transition from niche research applications to scaled industrial integration. This shift is driven by process innovations that lower costs, regulatory frameworks that clarify market access, and new demands from high-volume manufacturing sectors.
Functionalized carbon nanotubes are engineered with surface chemical groups to improve compatibility with host materials like battery electrolytes. Advanced battery and polymer composite manufacturers are adopting these materials to overcome dispersion challenges and boost performance. This material-specific engineering is converging with computational modeling to enable the design of application-specific additives, moving beyond generic grades.
Europe's REACH framework now requires nano-specific annexes with extensive characterization and safety data for market registration. This mandate increases compliance costs but also creates a competitive barrier, favoring producers with robust testing capabilities and established data dossiers. Material qualification for automotive and electronics is now highly dependent on suppliers providing these comprehensive EHS data packages.
End-users in battery and electronics manufacturing are shifting purchasing criteria from pure price to material consistency and supply chain transparency. This moves procurement away from spot-market buys toward long-term qualification programs with suppliers who guarantee batch-to-batch uniformity through certification. The trend is most visible in the automotive sector, where battery makers demand stringent quality control and traceability for all raw materials.
Global Carbon Nanomaterials Market Segmentation
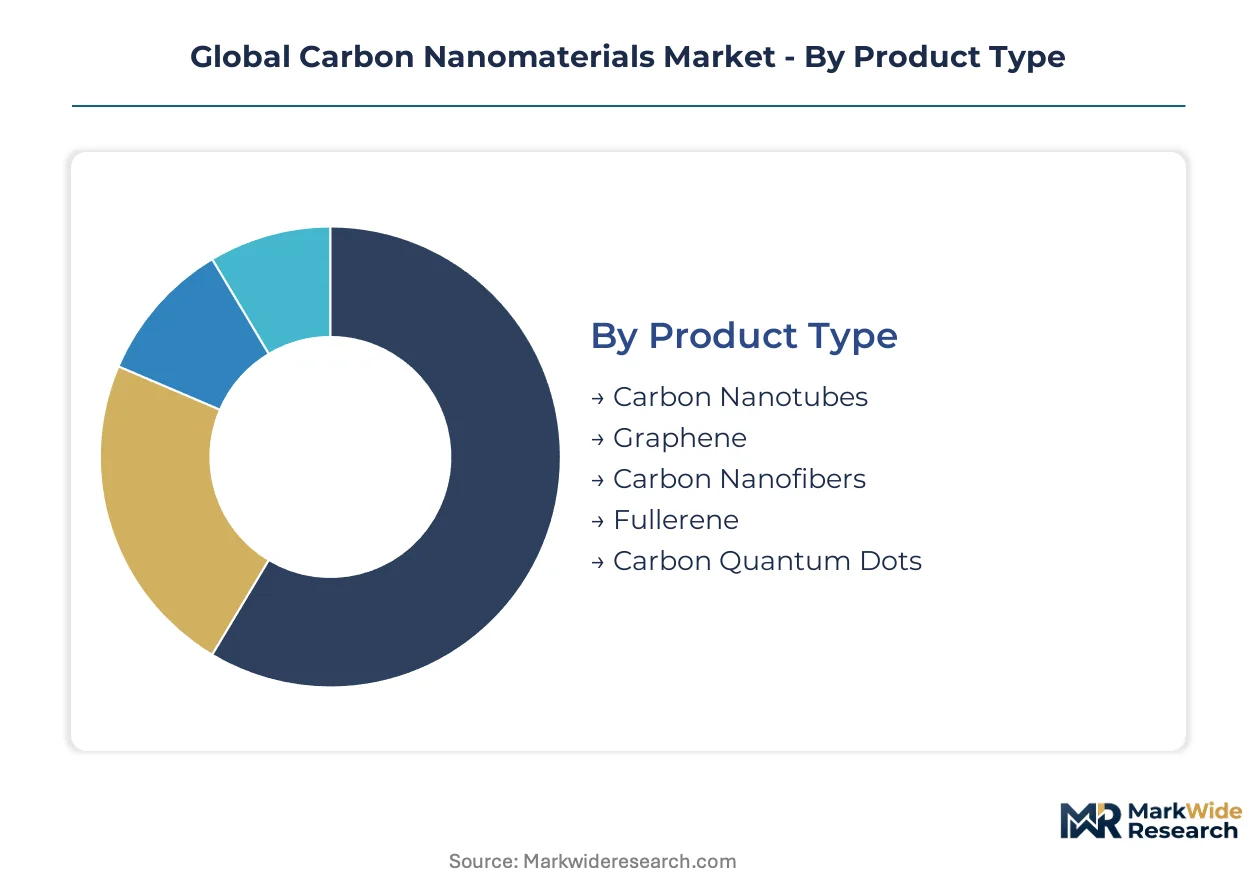
The carbon nanomaterials market structure reflects diverse material properties and end-user requirements, driving distinct demand cycles across various industry verticals. Understanding these segments is crucial for manufacturers to align product development with specific application needs and procurement cycles.
Product Type:
The upgrade cycle for existing material formulations heavily influences demand for different carbon nanomaterial types, favoring proven performance and ease of integration.
- Carbon Nanotubes:These cylindrical allotropes, including single-walled and multi-walled variants, offer exceptional electrical conductivity and mechanical strength. Demand concentrates in advanced lithium-ion batteries for electric vehicles, where they function as essential conductive additives.
- Graphene:This two-dimensional material, a single layer of carbon atoms, exhibits superior electrical and thermal properties. Demand is expanding rapidly in advanced electronics and flexible sensor technologies, enabling next-generation device miniaturization.
- Carbon Nanofibers:These materials are characterized by their high aspect ratio and good electrical conductivity, finding use in conductive plastics and filtration systems.
- Fullerene:Spherical carbon molecules with unique electronic properties, fullerenes are explored for applications in photovoltaics and pharmaceutical delivery.
- Carbon Quantum Dots:These fluorescent nanoparticles are gaining traction in bioimaging, display technologies, and advanced solar cells due to their tunable optical properties.
Volume placements concentrate in Carbon Nanotubes; the faster expansion belongs to Graphene.
Application:
Application focus determines material specifications, with different industries prioritizing specific performance attributes and integration challenges for carbon nanomaterials.
- Energy Storage:Carbon nanomaterials enhance battery performance by improving conductivity, charge rates, and cycle life in lithium-ion and next-generation battery chemistries. This application is central to electric vehicle manufacturing and grid-scale energy solutions.
- Electronics & Semiconductors:These materials provide superior thermal management and electrical conductivity for advanced microprocessors, flexible displays, and miniaturized electronic components. Miniaturization trends and increased data processing power drive material innovation here.
- Composite Materials:Carbon nanomaterials reinforce polymers, metals, and ceramics, imparting enhanced strength, stiffness, and electrical conductivity to structural components. Aerospace and automotive sectors utilize these for lightweight, high-performance parts.
- Sensors:Graphene and carbon nanotubes enable highly sensitive and selective detection capabilities in environmental monitoring, biomedical diagnostics, and industrial process control.
- Catalysis:Carbon nanomaterials serve as high surface area supports or active catalytic sites in various chemical reactions, improving efficiency and selectivity.
The bulk of innovation targets Energy Storage, while Catalysis offers specialized value.
End User Industry:
Customer type dictates procurement patterns and material qualification standards, with stringent requirements in automotive and aerospace sectors.
- Consumer Electronics:This sector integrates nanomaterials into devices for improved battery life, flexible screens, and enhanced thermal dissipation in smartphones and wearables. China's massive manufacturing base drives significant demand for these components.
- Aerospace:Carbon nanomaterials enhance the strength-to-weight ratio of aircraft components, reducing fuel consumption and extending operational lifespan. This sector prioritizes material consistency and long-term reliability.
- Oilfield Services:Nanomaterials are used in drilling fluids, coatings for pipelines, and sensors for reservoir monitoring, improving operational efficiency and material durability.
- Construction:Carbon nanomaterials enhance the mechanical properties and durability of concrete, asphalt, and lightweight structural panels.
- Sports Equipment:These materials improve the strength, lightness, and performance of gear such as tennis rackets, bicycles, and protective equipment.
Large-scale procurement characterizes Consumer Electronics; however, Aerospace commands premium pricing.
Form:
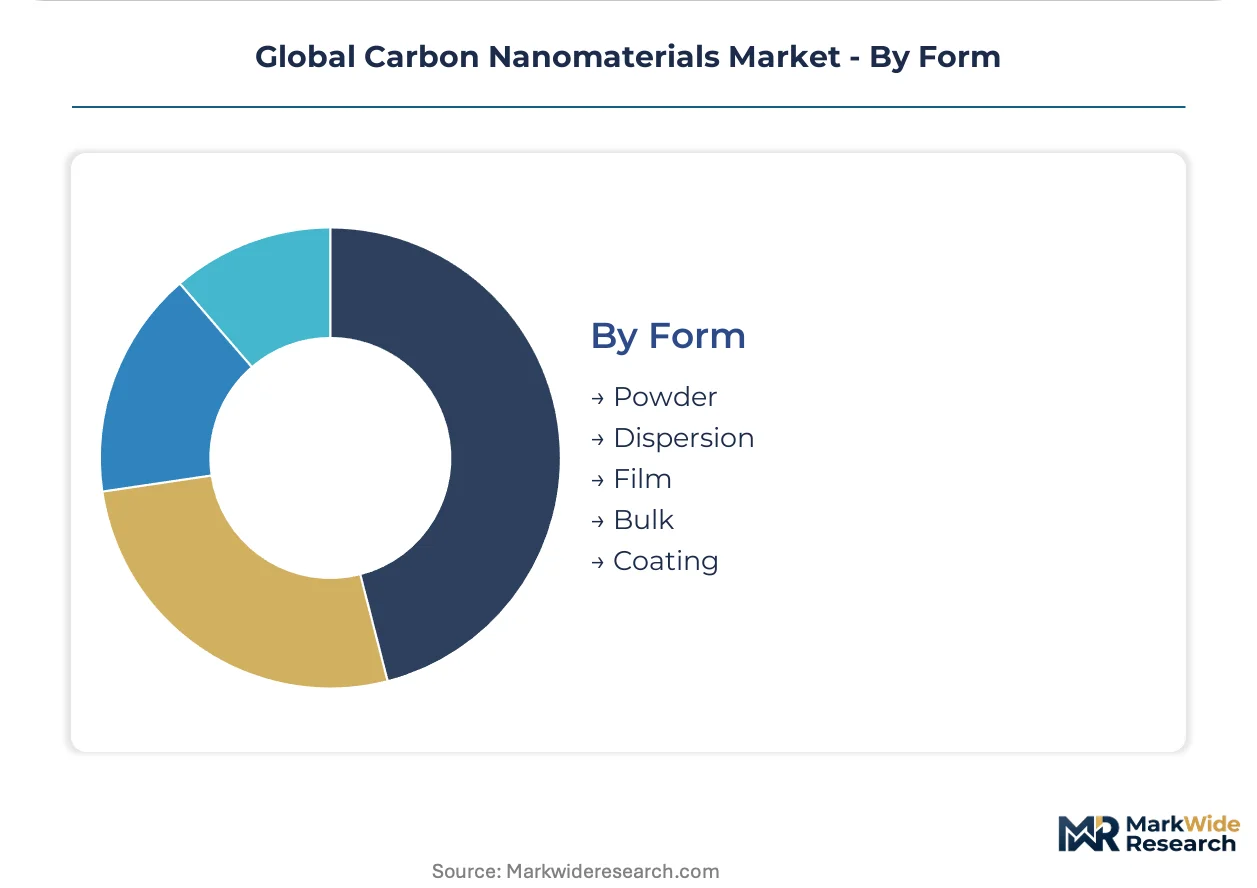
The form of carbon nanomaterials determines ease of handling, integration into host matrices, and final product performance.
- Powder:This primary form allows for versatile integration into various manufacturing processes, serving as a foundational input for many downstream applications.
- Dispersion:Nanomaterials suspended in a liquid medium facilitate uniform incorporation into polymers, paints, and battery slurries, addressing material dispersion challenges.
- Film:Thin, flexible sheets of nanomaterials are crucial for flexible electronics, transparent conductive layers, and advanced packaging solutions.
- Bulk:Consolidated forms of nanomaterials, such as foams or pellets, are used where larger quantities or specific structural integrity are required.
- Coating:Nanomaterial-based coatings provide enhanced surface properties like conductivity, corrosion resistance, or wear protection for various substrates.
Ease of handling drives adoption in Powder, while Dispersion addresses specific integration needs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's massive electronics and electric vehicle manufacturing bases, often concentrated in special economic zones, drive significant demand for carbon nanomaterials. These zones, supported by national industrial policies, enable scaled production and integration of advanced materials. This concentration reorients global supply chains for carbon nanotubes and graphene.
China
China's massive electric vehicle and consumer electronics sectors generate immense demand for carbon nanomaterials. The nation's dual carbon goals and GB standards actively shape material development and market access. Manufacturing hubs in the Yangtze River Delta integrate advanced nanomaterials into next-generation battery chemistries.
United States
The United States market for carbon nanomaterials is driven by advanced electronics and high-performance aerospace composites. US EPA regulations under TSCA govern new nanomaterial formulations, ensuring safety and compliance. Innovation clusters in Silicon Valley integrate graphene and nanotubes into next-generation devices and lightweight structures.
Germany
German automotive manufacturers and industrial machinery producers seek carbon nanomaterials for battery enhancement and lightweighting. The ECHA's REACH framework imposes stringent registration requirements for nanomaterials entering the European market. Research centers in Bavaria collaborate with industry on advanced material integration for electric vehicle components.
South Korea
South Korea's robust battery manufacturing sector and flexible display development fuel demand for graphene and carbon nanotubes. National regulatory bodies oversee material safety and environmental impact for these advanced chemistries. Major electronics and battery firms in the Seoul Capital Area, like LG Chem, integrate nanomaterials directly into their product lines.
Japan
Japanese high-performance electronics and automotive component industries utilize carbon nanomaterials for thermal management and structural reinforcement. METI provides guidance for advanced material development, while JIS standards ensure product quality. Companies in the Kanto region pursue innovations in materials for next-generation semiconductors and lightweight vehicle parts.
Global Carbon Nanomaterials Market Key Industry Players
Branded specialists and contract manufacturers split share differently across segments, reflecting the varied requirements of industrial end-users. The market structure exhibits a tiered consolidation, with established chemical giants alongside specialized nanomaterial producers. Strategic archetypes include large-scale chemical conglomerates, niche material innovators, and vertically integrated end-users. Dominant competitive moves involve strategic partnerships for application development and capacity expansion to meet rising demand.
Specialists in scaled production and material integration include OCSiAl, a privately held company focusing on single-wall carbon nanotubes for industrial use. LG Chem, a South Korean conglomerate, exemplifies a vertically integrated end-user, incorporating advanced nanomaterials directly into its battery cell chemistries. Separately, Cabot Corporation, a US-based chemical company, leverages its extensive carbon manufacturing infrastructure to develop conductive additives for batteries. These firms anchor different segments of the value chain.
| Leading Market Players |
|---|
| Jiangsu Cnano Technology |
| Arkema |
| OCSiAl |
| LG Chem |
| Cabot Corporation |
| CHASM Advanced Materials |
| Nanocyl |
| Nano-C |
| Dazhan Nanomaterials |
| Others |
Cost & Logistics Intelligence
Privately held specialists and vertically integrated chemical conglomerates define supply behavior and pricing discipline in the carbon nanomaterials market. This structure influences how production costs translate into market prices for advanced battery additives.
Pricing Analysis
Premium pricing for short lead times characterizes the carbon nanomaterials market, driven by urgent demand from automotive battery manufacturers. The dominant pricing model involves contract-based long-term offtake agreements, where prices differentiate based on material quality grade and certified batch-to-batch uniformity. Pricing pressure stems from the energy-intensive synthesis processes for high-purity nanotubes and graphene, impacting margins. Commodity applications exhibit high price sensitivity, contrasting with the lower sensitivity seen in aerospace and advanced battery sectors.
Supply Chain Analysis
Reverse logistics for carbon nanomaterials remain nascent, with current supply chains focused on forward distribution to high-volume manufacturing. Supply concentration centers in China, South Korea, and the United States, reflecting major production and consumption hubs. Raw material dependencies include high-purity carbon precursors and specialized catalysts for synthesis. Regulatory restrictions, particularly Europe's REACH framework, pose a structural supply chain risk by limiting market access for non-compliant materials. Distribution runs through direct sales channels and long-term qualification programs with large industrial end-users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The carbon nanomaterials market presents a significant cost-of-compliance story, where stringent regulations like Europe's REACH framework create a barrier-to-entry moat for established, compliant producers. This regulatory environment favors firms with robust testing capabilities and comprehensive safety data.
For Market Incumbents:Deepen investments in process engineering talent and scaled production facilities, particularly in high-demand regions like China and South Korea. This expands capacity for single-wall carbon nanotubes and graphene, countering potential supply shortages. Invest in advanced functionalization R&D to improve material compatibility, addressing dispersion challenges and enhancing performance in battery chemistries. Robust certification investment under frameworks like REACH reinforces market leadership against emerging entrants with less proven material data.
For New Entrants and Emerging Players:A price-point gap exists between high-purity, certified nanomaterials and more commoditized grades, offering entry opportunities. Target underpenetrated emerging EV hubs such as India with cost-effective conductive additives for lithium-ion batteries. Focus on specialized material grades for biomedical applications, leveraging AI-enabled material design to accelerate product development. Provide comprehensive EHS data packages tailored to specific regional regulatory requirements for market entry.
For Investors and Strategic Acquirers:Distressed-cycle entries favor vertically integrated mid-cap specialists in Europe or the United States with strong IP in functionalized carbon nanomaterials. The long-term viability of the market remains robust, driven by persistent demand from energy storage and advanced electronics sectors. Target specialized producers possessing comprehensive EHS data dossiers and proven scale-up capabilities. Successful industrial integration of next-generation nanomaterial formulations in high-volume applications serves as a critical inflection indicator.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in Asia | Secures supply for China's electric vehicle and consumer electronics manufacturing base. |
| Functionalized Material R&D | Addresses dispersion challenges, improving performance and compatibility with host matrices. |
| REACH Compliance Investment | Establishes competitive barrier for market access in the European Union. |
| AI-Enabled Material Design | Accelerates development of novel carbon allotropes with application-specific properties. |
| Long-term Supply Agreements | Ensures consistent quality and traceability for automotive battery manufacturers. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for the global carbon nanomaterials market analysis. This was complemented by primary interviews with R&D directors at chemical companies, procurement leads at battery manufacturers, and regulatory affairs specialists. Bottom-up and top-down triangulation validated volume and value data points. This approach ensured comprehensive market understanding.
Data-stream reconciliation integrated historical trends with projected market drivers to construct the forecast framework across the analysis window. Segmentation dimensions modeled included product type, application, end-user industry, form, and regulatory compliance tier. Compound annual growth rates were derived from a synthesis of market dynamics and expert insights. Electric vehicle production forecasts and battery chemistry advancements served as key input variables.
Inputs from ECHA filings and corporate disclosures were available through the study window; gaps in emerging nanomaterial safety data introduce uncertainty bands. Forecasts reflect assumptions regarding regulatory stability and technological evolution. Material deviation in electric vehicle adoption rates or unforeseen regulatory shifts warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Nanofilms Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Nanotools Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Global Nano Silver Market