
 Lipid Nanoparticles Market | 2026-2036
Lipid Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Lipid Nanoparticles Market Outlook
Phospholipid formulation expertise is bifurcating the competitive landscape into specialists and integrated suppliers. Merck KGaA leverages its electronic materials heritage to cross-apply high-purity lipid synthesis capabilities into pharmaceutical-grade production. Evonik Industries AG anchors its position through backward integration into custom lipid manufacturing for mRNA therapeutics. Avanti Polar Lipids specializes in research-grade polar lipids that feed early-stage drug development pipelines.
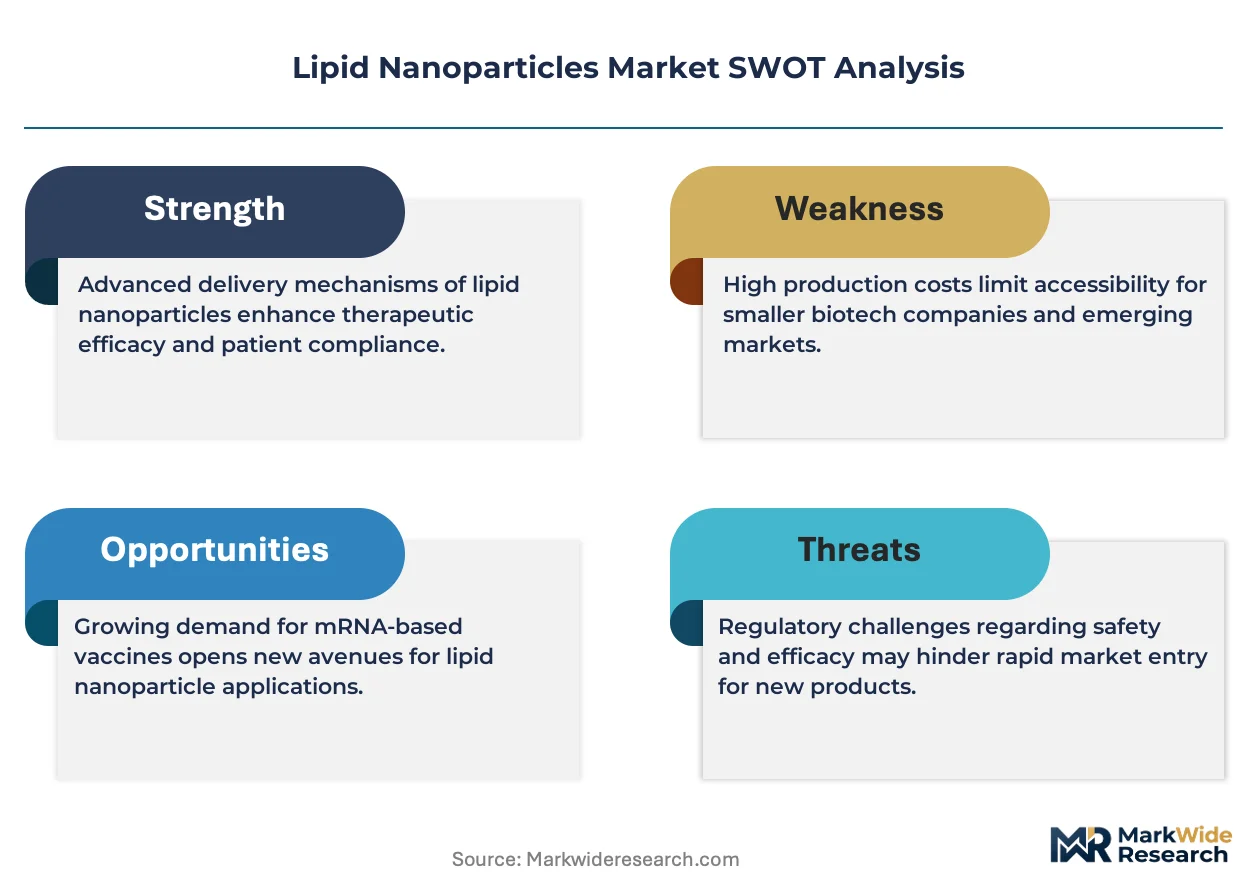
Lipid nanoparticles are submicron colloidal carriers composed of ionizable lipids, helper phospholipids, cholesterol, and polyethylene glycol-lipid conjugates, typically 50-100 nanometers in diameter, engineered to encapsulate hydrophobic or hydrophilic payloads for targeted intracellular delivery. Their primary commercial purpose centers on enabling systemic administration of nucleic acid therapeutics that would otherwise degrade in biological environments. Solid lipid nanoparticles dominate current manufacturing volumes due to established stability profiles and simpler scale-up protocols, while nanostructured lipid carriers represent the fastest-expanding category as formulators seek improved drug-loading capacity through deliberate lipid matrix disorder. Gene therapy applications command premium pricing relative to conventional drug delivery owing to complex analytical validation requirements and orphan disease targeting.
The FDA's Chemistry, Manufacturing, and Controls guidance for lipid nanoparticle drug products shapes submission requirements for new molecular entities, while the EMA's quality guidelines for nucleic acid-based medicines influence European development strategies. ISO 10993 biocompatibility testing standards govern material qualification for parenteral lipid formulations across regulated markets. Stakeholders must monitor evolving pharmacopeial monographs for novel ionizable lipids as regulatory agencies harmonize impurity thresholds and characterization methodologies.
Market Dynamics
The transition from emergency-use mRNA vaccines to chronic disease nucleic acid therapeutics is forcing lipid nanoparticle suppliers to reengineer stability profiles for repeat-dosing regimens rather than single-shot immunization.
Growth Catalysts
- BARDA manufacturing grants:The US Biomedical Advanced Research and Development Authority funds domestic lipid production facilities, de-risking capital deployment for parenteral-grade ionizable lipid synthesis.
- Orphan disease gene therapy pipelines:Pharmaceutical developers target ultra-rare monogenic disorders where lipid nanoparticle delivery of mRNA or gene-editing constructs offers curative potential.
- Self-amplifying RNA platforms:Next-generation saRNA constructs reduce required lipid doses by 50-80%, expanding addressable patient populations in cost-sensitive therapeutic areas.
Market Restraints
- Phospholipid supply concentration:High-purity synthetic phospholipid production concentrates among three specialized chemical manufacturers, creating single-source vulnerability for pharmaceutical-grade cholesterol derivatives.
- Ethanol solvent handling requirements:Large-scale lipid nanoparticle manufacturing demands explosion-proof facilities and specialized waste treatment, elevating facility capital intensity versus conventional biologics.
- Plasmid DNA template scarcity:mRNA production requires GMP-grade plasmid DNA as starting material, with qualified suppliers limited to fewer than ten global facilities.
Strategic Opportunities
- Japan's regenerative medicine regulatory sandbox:PMDA's conditional early approval pathway for nucleic acid therapies accelerates commercial proof points for novel lipid formulations in oncology applications.
- Inhaled lipid nanoparticle delivery:Pulmonary administration of mRNA for cystic fibrosis and respiratory syncytial virus bypasses liver sequestration, opening organ-specific targeting white space.
- CRISPR-guide RNA co-encapsulation:Lipid nanoparticles simultaneously delivering Cas9 mRNA and single-guide RNA enable in vivo gene editing, converging two platform technologies into one therapeutic modality.
Industry Challenges
- Process analytical technology gaps:Real-time release testing for lipid nanoparticle critical quality attributes remains underdeveloped, forcing reliance on offline chromatographic methods that extend batch release timelines.
- Cross-functional talent scarcity:Formulation scientists possessing simultaneous expertise in colloidal chemistry, nucleic acid biochemistry, and GMP manufacturing represent fewer than two hundred professionals globally.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Lipid Nanoparticles Market |
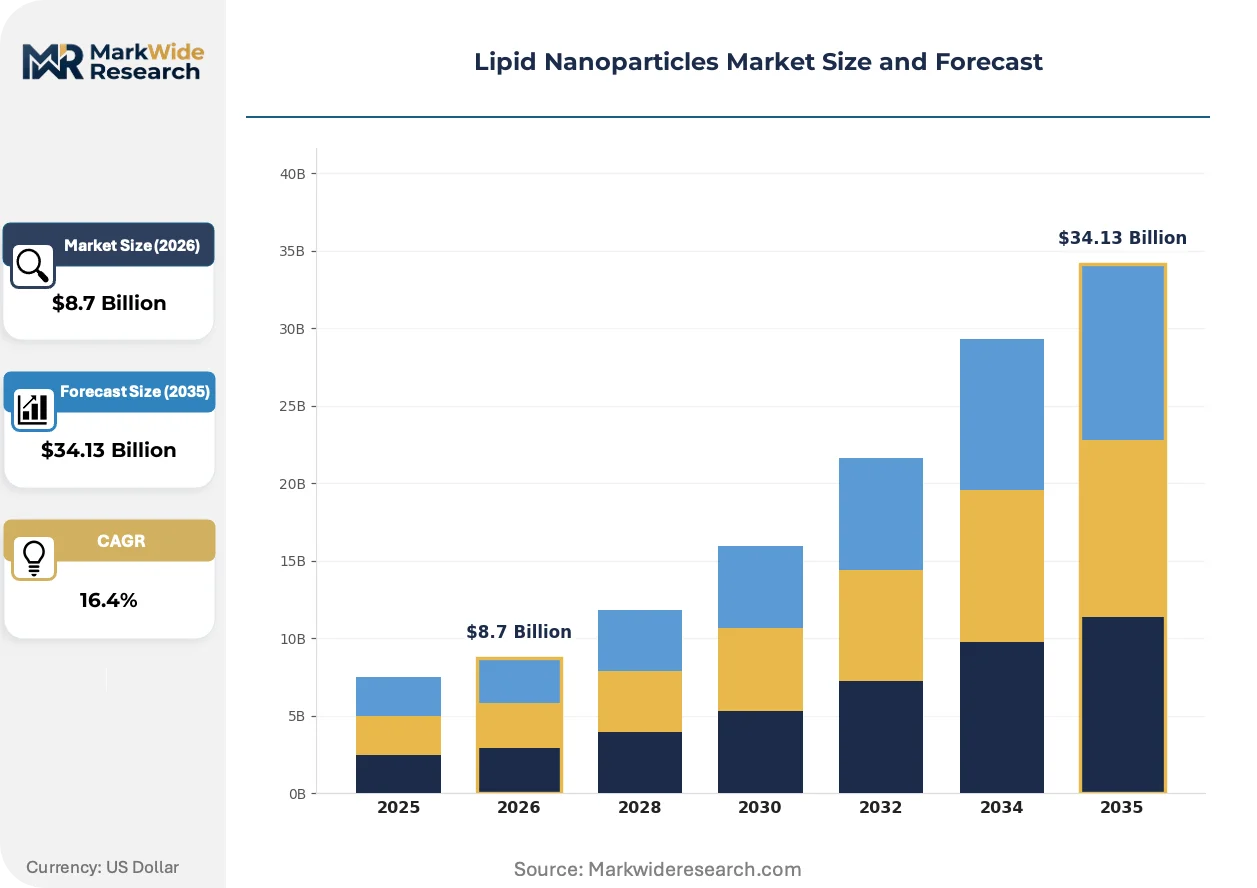
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $34.13 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Solid Lipid Nanoparticles, Nanostructured Lipid Carriers, Lipid Coated Nanoparticles, Liposomes Application: Drug Delivery, Gene Therapy, Vaccine Development, Diagnostic Imaging End User: Pharmaceutical Companies, Biotechnology Firms, Research Institutions, Contract Manufacturing Organizations Delivery Mode: Intravenous, Oral, Nasal, Transdermal |
| Companies Covered | Merck KGaA, Evonik Industries AG, Avanti Polar Lipids, NOF Corporation, Gattefosse, Precision NanoSystems, IOI Oleo GmbH, Lipoid GmbH, Croda International plc, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Lipid Nanoparticles Market Strategic Shifts
Next-generation lipid chemistries are diverging from the four-component ionizable lipid paradigm established during the pandemic, with formulators exploring biodegradable ester linkages and organ-selective tropism modifications.
Microfluidic mixing technology is fragmenting the manufacturing equipment landscape. Precision NanoSystems and Knauer have deployed single-use microfluidic cartridges that reduce process development timelines from months to weeks. Contract development organizations adopt these platforms to serve early-stage biotech clients lacking internal formulation infrastructure. The shift compresses barriers to entry for nucleic acid therapeutic startups while eroding demand for traditional bulk mixing vessels.
EMA's revised guideline on quality aspects of mRNA vaccines tightens impurity specifications for dsRNA and residual DNA templates. European manufacturers must implement additional purification steps or analytical controls to demonstrate compliance. The regulation disproportionately burdens mid-scale producers lacking dedicated quality control laboratories, accelerating consolidation toward integrated CDMOs with in-house regulatory affairs capabilities.
Pharmaceutical procurement of lipid raw materials now separates research-grade from GMP-grade supply chains entirely. Early-stage developers purchase polar lipids through distributor channels for preclinical work, then re-qualify captive suppliers for clinical manufacturing. This bifurcation forces dual vendor management and creates specification drift risks when scaling from GLP toxicology to Phase I GMP batches. The pattern is most pronounced among US-based gene therapy startups with limited chemical supply chain expertise.
Lipid Nanoparticles Market Segmentation
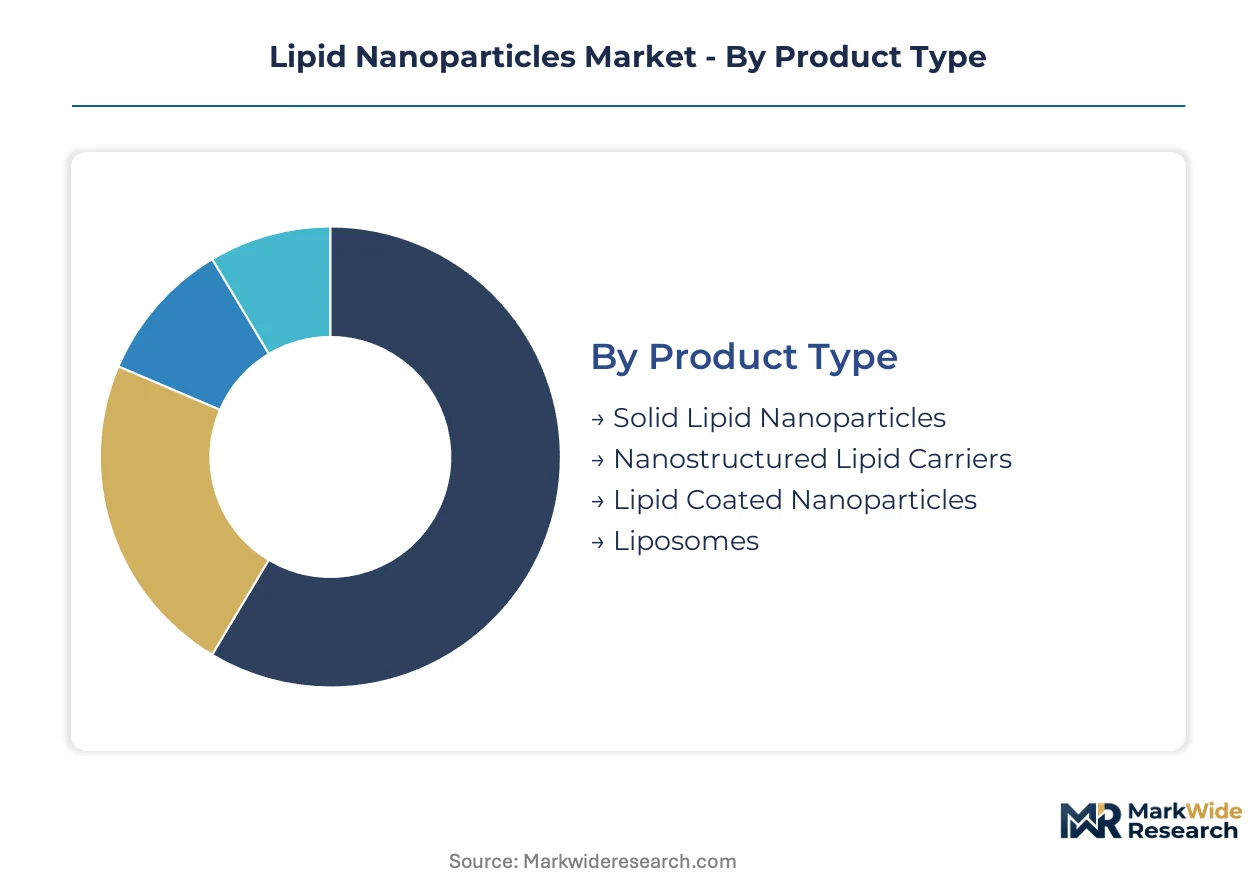
Lipid nanoparticle formulation choices directly determine manufacturing complexity, regulatory pathway, and commercial scalability. Each segmentation dimension reveals distinct supply chain configurations and customer procurement patterns that shape competitive positioning.
Product Type:
Domestic production dominates solid lipid nanoparticles and liposomes, while nanostructured lipid carriers rely heavily on imported ionizable lipids from specialized European and Asian chemical manufacturers.
- Solid Lipid Nanoparticles:Composed of solid lipids at room temperature with surfactant stabilization, these particles offer thermal stability and straightforward lyophilization. Demand concentrates in the United States among established vaccine manufacturers seeking proven scale-up protocols for nucleic acid delivery. The segment benefits from mature analytical methods and existing GMP infrastructure.
- Nanostructured Lipid Carriers:Engineered with deliberate spatial lipid disorder combining solid and liquid lipids, these carriers achieve 30-50% higher drug-loading capacity than conventional solid matrices. European pharmaceutical developers in Germany and Switzerland are driving adoption for complex small-molecule payloads requiring sustained release profiles.
- Lipid Coated Nanoparticles:Surface-functionalized cores wrapped with phospholipid bilayers enable hybrid delivery architectures. Japanese oncology-focused biotechs are the primary demand source for tumor-targeting applications.
- Liposomes:Concentric phospholipid bilayer vesicles represent the historical foundation of lipid-based delivery. Contract manufacturing organizations in India and South Korea maintain substantial production capacity for generic liposomal formulations.
Solid lipid nanoparticles hold the largest share; momentum sits with nanostructured lipid carriers.
Application:
Cost tier separation is pronounced, with gene therapy commanding premium pricing and vaccine development operating at scale-optimized economics.
- Drug Delivery:Lipid nanoparticles encapsulate hydrophobic compounds to enhance bioavailability and enable intravenous administration of poorly soluble actives. Oncology applications in the United States drive the majority of clinical-stage programs, with FDA's accelerated approval pathways shortening development timelines.
- Gene Therapy:Delivery of mRNA, siRNA, and gene-editing constructs requires precisely tuned ionizable lipid ratios for endosomal escape. Orphan disease targeting in Europe generates the highest per-patient revenue, with EMA's quality guidelines for nucleic acid-based medicines shaping formulation specifications.
- Vaccine Development:Prophylactic immunization platforms normalized lipid nanoparticle manufacturing at unprecedented scale. BARDA-funded domestic facilities in the United States supply this segment with parenteral-grade materials.
- Diagnostic Imaging:Lipid-encapsulated contrast agents enable targeted visualization of pathological tissues. Research institutions in Japan and Australia represent the primary demand concentration for preclinical and early clinical imaging studies.
Gene therapy claims the highest margins; vaccine development delivers the steepest expansion trajectory.
End User:
Customer sophistication determines procurement patterns, with pharmaceutical companies demanding integrated supply chains and research institutions accepting distributor-mediated sourcing.
- Pharmaceutical Companies:Large developers maintain captive lipid synthesis capabilities or exclusive supply agreements with qualified manufacturers. Pfizer-BioNTech and Moderna established this template, with their procurement specifications now standard across the industry.
- Biotechnology Firms:Venture-backed startups lack internal formulation infrastructure and rely on contract development organizations for lipid nanoparticle manufacturing. These customers prioritize speed over cost, accepting premium pricing for expedited process development.
- Research Institutions:Academic laboratories purchase research-grade polar lipids through distributor channels for preclinical proof-of-concept studies. NIH-funded university programs in the United States constitute the largest addressable base.
- Contract Manufacturing Organizations:CDMOs invest in microfluidic mixing platforms to serve the fragmented biotech customer segment. European CDMOs with in-house regulatory affairs capabilities are consolidating market position following EMA's tightened impurity specifications.
Pharmaceutical companies anchor volume; biotechnology firms are gaining share fastest.
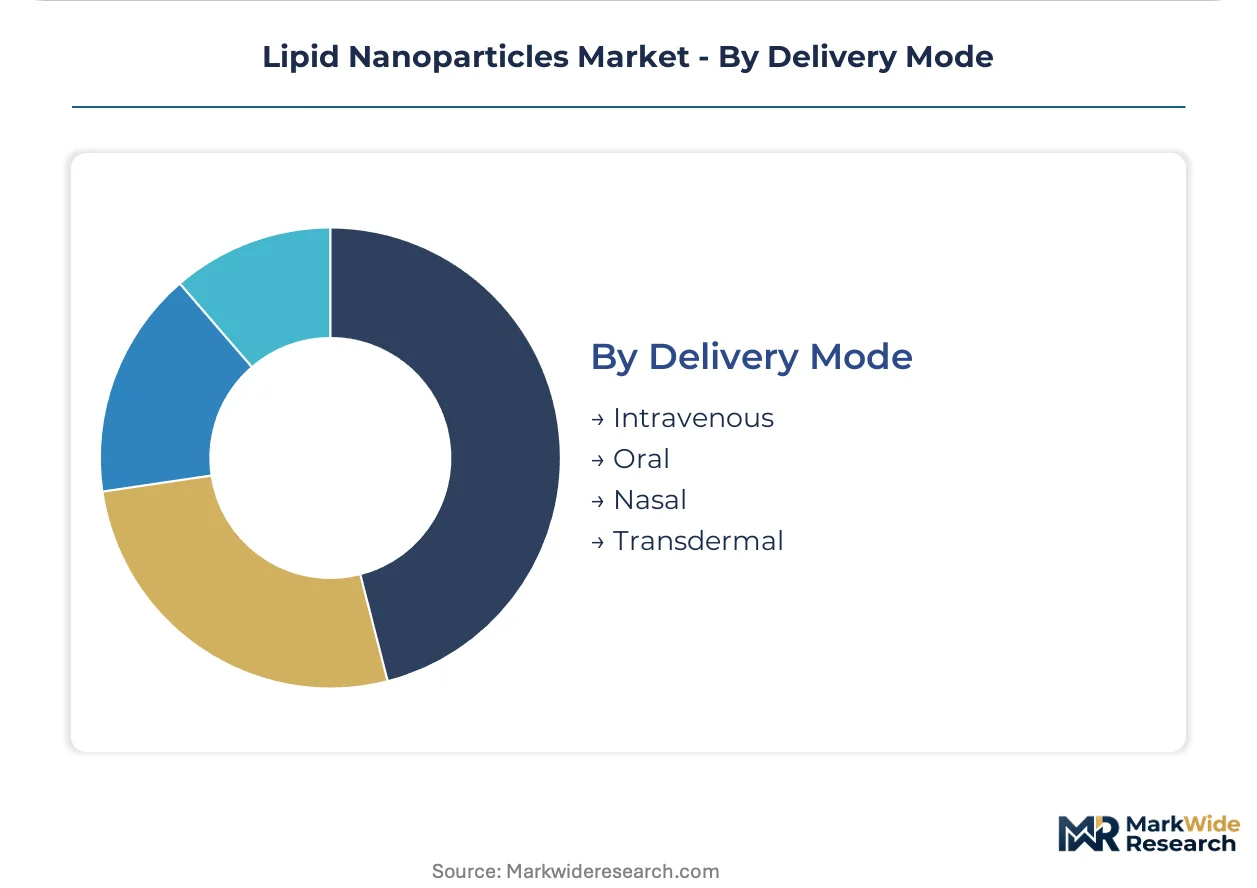
Delivery Mode:
Volume concentration favors intravenous administration, while innovation investment flows toward non-parenteral routes that bypass liver sequestration.
- Intravenous:Direct bloodstream administration enables systemic distribution and remains the validated route for all approved nucleic acid therapeutics. United States-based gene therapy developers dominate clinical programs, with FDA's Chemistry, Manufacturing, and Controls guidance establishing the regulatory benchmark.
- Oral:Gastrointestinal stability challenges have limited lipid nanoparticle applications, though intestinal lymphatic targeting for biologics is advancing in Australian and Canadian research programs.
- Nasal:Pulmonary and intranasal delivery of mRNA for respiratory indications is attracting substantial R&D investment. PMDA's conditional early approval pathway in Japan accelerates commercial proof points for this route.
- Transdermal:Microneedle-assisted lipid nanoparticle penetration offers patient-friendly administration for chronic disease management. German and Swiss dermatology-focused developers lead preclinical exploration.
Intravenous administration commands current revenue; nasal delivery shows the steepest investment trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
FDA's Chemistry, Manufacturing, and Controls guidance anchors development strategy in the United States, while EMA's quality guidelines and PMDA's conditional approval pathways shape European and Japanese market entry respectively.
United States
BARDA manufacturing grants and NIH funding ecosystems drive domestic ionizable lipid production scale-up. The FDA's accelerated approval pathways for nucleic acid therapies compress development timelines for novel formulations. Greater Boston and the Research Triangle Park host concentrated gene therapy developer clusters pursuing orphan disease indications.
Germany
Specialized chemical manufacturers in Baden-Württemberg and North Rhine-Westphalia supply high-purity synthetic phospholipids to global pharmaceutical customers. EMA's tightened impurity specifications for mRNA vaccines force additional purification investments. The Frankfurt-Rhine-Main corridor anchors contract manufacturing capacity for European nucleic acid therapeutic developers.
Switzerland
Swissmedic's alignment with EMA quality standards facilitates seamless market access for lipid nanoparticle drug products. Basel's pharmaceutical innovation cluster drives demand for research-grade polar lipids in early-stage gene therapy pipelines. Swiss chemical manufacturers specialize in custom lipid synthesis for mRNA therapeutic applications.
Japan
PMDA's conditional early approval pathway for nucleic acid therapies accelerates commercial proof points for novel lipid formulations. METI funding supports domestic microfluidic mixing technology development for scaled manufacturing. The Kanto region around Tokyo concentrates biotech startups exploring inhaled lipid nanoparticle delivery for respiratory indications.
India
CDSCO's evolving framework for nucleic acid-based medicines attracts contract manufacturing investment from Western pharmaceutical sponsors. The Hyderabad-Bengaluru corridor develops liposomal formulation capacity for generic oncology applications. Indian research institutions purchase polar lipids through distributor channels for preclinical nucleic acid delivery studies.
Lipid Nanoparticles Market Competitive Environment
Technology leadership and cost leadership are held by different player archetypes, with formulation specialists commanding premium pricing for complex ionizable lipid synthesis while integrated chemical conglomerates leverage scale in phospholipid production. The market structure tiers into three segments: multinational life science conglomerates with captive lipid capabilities, mid-scale specialists focused on GMP-grade ionizable lipids, and research-grade suppliers serving preclinical pipelines. Dominant competitive moves include backward integration into custom lipid manufacturing and strategic partnerships between formulation technology providers and nucleic acid therapeutic developers.
Among German-based chemical conglomerates, Merck KGaA and Evonik Industries AG occupy positions spanning electronic materials heritage and pharmaceutical-grade lipid production. Avanti Polar Lipids exemplifies the specialist archetype, anchoring the research-grade supply tier for polar lipids feeding early-stage drug development pipelines.
| Leading Market Players |
|---|
| Merck KGaA |
| Evonik Industries AG |
| Avanti Polar Lipids |
| NOF Corporation |
| Gattefosse |
| Precision NanoSystems |
| IOI Oleo GmbH |
| Lipoid GmbH |
| Croda International plc |
| Others |
Value Chain & Pricing Dynamics
Bio-based ionizable lipid alternatives displacing petroleum-derived formulations are simultaneously redrawing manufacturing geography and compressing cost structures for pharmaceutical-grade supply. European chemical manufacturers in Germany and Switzerland command premiums for synthetic phospholipids while Asian producers undercut on cholesterol derivatives, creating arbitrage opportunities for formulation houses with dual-qualification capabilities.
Pricing Analysis
Price spreads between United States and Asian supply sources exceed forty percent for GMP-grade ionizable lipids after accounting for import duties and cold-chain logistics. Three-tier pricing structure across premium, standard, and economy levels separates orphan disease gene therapy developers from mass-market vaccine manufacturers and preclinical research institutions. Cost compression in standard-grade lipids is intensifying because CDMOs are consolidating procurement volumes through long-term offtake agreements. Biotechnology startups exhibit highest price sensitivity; integrated pharmaceutical conglomerates absorb premiums for supply security.
Supply Chain Analysis
Port congestion at Rotterdam and Singapore has elevated inbound logistics costs for European and Asian lipid manufacturers serving United States pharmaceutical customers. Production gravity centers on Germany, Switzerland, and the United States for high-purity synthetic phospholipids, with India and South Korea supplying generic liposomal formulations. The supply chain draws from plasmid DNA templates, ethanol solvents, and specialized ionizable lipid precursors as critical inputs. Single-source vulnerability concentrates in qualified plasmid DNA facilities, with fewer than ten global sites meeting GMP standards. Distribution runs through qualified CDMOs with captive regulatory affairs capabilities rather than open-market commodity channels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The lipid nanoparticle market represents a high-growth disruption anchored by FDA's accelerated approval pathways for nucleic acid therapies, which collapsed traditional development timelines from decade-long horizons to multi-year sprints.
For Market Incumbents: Secure captive supply agreements for ionizable lipid precursors before plasmid DNA template scarcity worsens. Invest in microfluidic manufacturing platforms to defend against Precision NanoSystems and Knauer eroding traditional bulk mixing vessel demand. Consolidate regulatory affairs capabilities in-house to meet EMA's tightened impurity specifications without external dependency. For New Entrants and Emerging Players: Lead with inhaled lipid nanoparticle delivery for respiratory indications, where PMDA's conditional early approval pathway in Japan offers fastest commercial proof points. Target academic research institutions in the United States through distributor-mediated polar lipid supply before re-qualifying for GMP tiers. Differentiate via organ-selective tropism modifications that bypass liver sequestration, a white space incumbent platforms have neglected. For Investors and Strategic Acquirers: FDA's Chemistry, Manufacturing, and Controls guidance for lipid nanoparticle drug products reshapes the acquisition landscape toward CDMOs with integrated quality control laboratories and regulatory submission track records. Five-to-ten year viability hinges on exposure to chronic disease nucleic acid therapeutics rather than pandemic-era vaccine manufacturing capacity. Target acquisition archetype: mid-scale specialists possessing simultaneous expertise in colloidal chemistry and GMP manufacturing. Signal to monitor: BARDA manufacturing grant disbursement rates indicating domestic production scale-up velocity.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Custom Lipid Synthesis | Evonik Industries AG and Merck KGaA reduce dependency on external phospholipid suppliers for mRNA therapeutic manufacturing. |
| Microfluidic Mixing Platform Deployment | Precision NanoSystems enables CDMOs to compress nucleic acid formulation development timelines from months to weeks. |
| Regulatory Affairs Capability Buildout | European CDMOs consolidate position following EMA's revised guideline on quality aspects of mRNA vaccines. |
| Organ-Selective Tropism R&D Investment | Japanese biotechs in the Kanto region target pulmonary administration bypassing liver sequestration for cystic fibrosis applications. |
| Dual-Grade Supply Chain Qualification | Gene therapy startups manage research-grade distributor channels alongside GMP captive supplier relationships to prevent specification drift. |
Study Parameters
Desk research of FDA Chemistry Manufacturing and Controls guidance documents, EMA quality guidelines for nucleic acid-based medicines, and ISO 10993 biocompatibility testing standards preceded structured interviews with lipid formulation scientists, regulatory affairs directors at gene therapy developers, procurement managers at CDMOs, and NIH program officers funding nucleic acid delivery research. Primary fieldwork combined with secondary validation across ClinicalTrials.gov entries, pharmacopeial monograph drafts, and BARDA grant disbursement records. Bottom-up segmentation modeling triangulated against top-down market sizing from identified manufacturer capacity announcements.
Variance decomposition across product type, application, end user, and delivery mode segmentation dimensions drove analytical framework construction throughout the projection horizon. CAGRs derived from slope-intercept modeling of historical capacity expansion correlated with regulatory approval velocity and funding ecosystem disbursement patterns. Forecast inputs incorporated orphan disease pipeline progression rates and self-amplifying RNA platform adoption curves as industry-specific demand drivers.
The analysis sits within stated boundaries; outcomes outside sustained FDA accelerated approval pathway utilization, stable phospholipid supply concentration, and continued BARDA manufacturing grant funding would require recalibration. Forecasts reflect documented assumptions regarding nucleic acid therapeutic clinical success rates and regulatory harmonization timelines. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Platinum Nanoparticles Market