
 Global Nanofilms Market | 2026-2036
Global Nanofilms Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanofilms Market Foresight
East Asian chemical vapor deposition foundries is consolidating capacity for dielectric and barrier nanofilms. 3M Company leverages its fluoropolymer expertise to dominate protective coating formulations. DuPont de Nemours anchors high-performance polymeric nanofilm supply through advanced monomer control. Nanofilm Technologies competes in precision optical coatings with atomic layer deposition systems.
Nanofilms are engineered layers with thicknesses below 100 nanometers, typically fabricated through atomic layer deposition or chemical vapor deposition to achieve precise stoichiometric control for barrier, conductive, or optical functions. Polymeric nanofilms lead commercial volume in food packaging and flexible electronics, while inorganic nanofilms command premium positioning in semiconductor gate stacks and solar cell passivation layers where defect density below 10^10 per square centimeter determines performance. Hybrid nanofilms represent the fastest-expanding category as packaging producers and renewable energy firms seek multifunctional barriers combining moisture resistance with thermal stability.
EPA regulates perfluorinated substances in coating applications, pushing reformulation toward non-fluorinated barrier chemistries. EMA and REACH jointly constrain residual monomer thresholds in medical and food-contact nanofilms, elevating purification costs for European market access. Semiconductor fabricators must monitor evolving ISO 10993 biocompatibility extensions as nanofilm-enabled implantable electronics blur device-pharmaceutical boundaries.
Market Dynamics
Semiconductor gate-stack scaling below 3nm nodes is forcing atomic layer deposition equipment utilization rates above 90% at East Asian foundries, compressing available capacity for non-semiconductor applications and reshaping competitive access.
Growth Catalysts
- REACH Phase-Down of PFAS:ECHA restrictions on perfluorinated substances in industrial coatings are accelerating non-fluorinated barrier chemistry R&D, opening substitution windows for polymeric nanofilm suppliers with compliant formulations.
- Flexible Electronics Manufacturing:Roll-to-roll atomic layer deposition systems are enabling moisture barrier integration at polymer web speeds, pulling polymeric nanofilm volumes into foldable display supply chains.
- Japan-Taiwan-South Korea Cluster Concentration:Chemical vapor deposition foundry capacity consolidation across these three markets is creating captive demand for high-purity precursor chemicals and localized barrier nanofilm production.
Market Restraints
- Precursor Chemical Supply Concentration:High-purity organometallic precursors for atomic layer deposition concentrate among German and Japanese specialty chemical suppliers, creating single-source vulnerability for barrier nanofilm fabricators.
- ISO 10993 Biocompatibility Extension Costs:Evolving ISO standards for implantable electronics are extending certification timelines for nanofilm-enabled medical devices, elevating regulatory compliance overhead before commercialization.
- Plasma Etching Substitution:Selective area atomic layer etching is displacing some barrier nanofilm applications in advanced node patterning, compressing addressable market scope for dielectric deposition specialists.
Strategic Opportunities
- India PLI Scheme for Electronics:Production-linked incentive schemes for semiconductor and display manufacturing are attracting nanofilm equipment vendors to establish precursor supply and technical service operations in Gujarat and Tamil Nadu.
- Solar Cell Passivation Layer Expansion:Tunnel oxide passivated contact architectures in photovoltaic manufacturing are pulling atomic layer deposition alumina and silicon oxide nanofilms into gigawatt-scale production lines.
- EU Battery Regulation Material Traceability:Digital product passport requirements for lithium-ion batteries are creating demand for embedded nanofilm sensors and functional coatings that enable real-time state-of-health monitoring.
Industry Challenges
- Atomic Layer Deposition Technician Scarcity:Specialized reactor operation and precursor handling expertise concentrates among semiconductor industry veterans, constraining workforce expansion for emerging application sectors.
- Cleanroom Capital Intensity:Class 1000 or better fabrication environments for defect-sensitive optical nanofilms require nine-figure facility investments, elevating break-even thresholds for mid-scale producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanofilms Market |
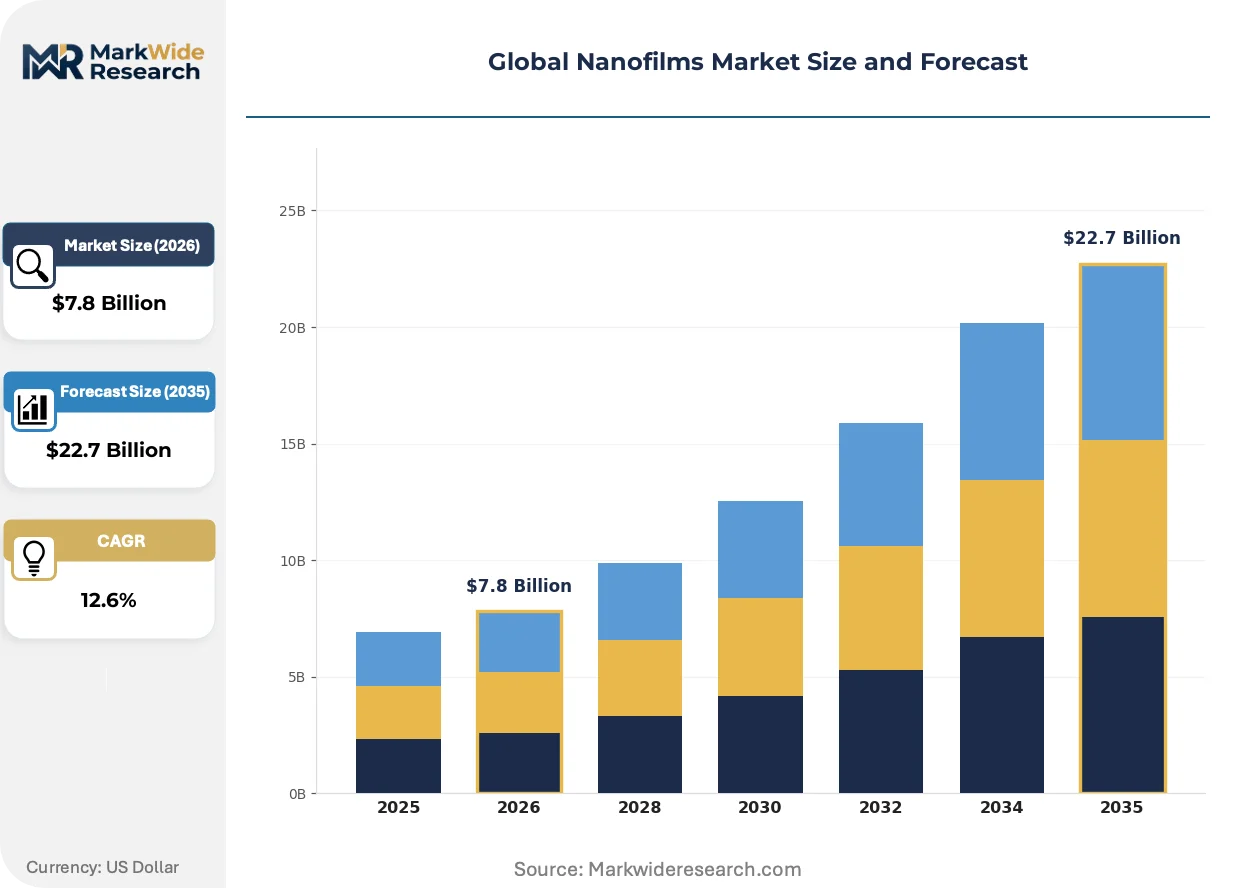
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $22.7 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Polymeric Nanofilms, Inorganic Nanofilms, Hybrid Nanofilms, Composite Nanofilms Technology: Atomic Layer Deposition, Chemical Vapor Deposition, Physical Vapor Deposition, Spin Coating Application: Water Treatment, Electronics Manufacturing, Food Packaging, Solar Cells, Protective Coatings End User Industry: Semiconductor Fabricators, Packaging Producers, Renewable Energy Firms, Environmental Engineering Firms |
| Companies Covered | Nanofilm, Nanofilm Technologies, Cosmo Films Limited, 3M Company, DuPont de Nemours, Nano Foam Technology Private Limited, Nano Therapeutics Pvt. Ltd, NanoGram Corporation, MAT-VAC Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanofilms Market Shifts & Advancements
Hybrid organic-inorganic nanofilm architectures are displacing single-material approaches across packaging and energy applications, unifying moisture barrier performance with thermal mechanical stability in single deposition sequences.
Atomic layer deposition is unifying previously separate barrier and conductive functions in flexible electronics substrates. Display manufacturers in South Korea and Japan are adopting hybrid nanolaminate stacks at production scale. This convergence is compressing equipment footprint requirements while elevating precursor purity specifications.
EPA regulation of perfluorinated substances under TSCA Section 6 is forcing coating reformulation across US-based electronics and packaging operations. Industrial nanofilm users are qualifying fluorine-free barrier chemistries ahead of enforcement timelines. Food-contact and medical device segments face the steepest requalification burdens.
Consolidated procurement of nanofilm deposition services is displacing in-house equipment ownership among mid-tier electronics assemblers. Contract manufacturers in Taiwan and Malaysia are capturing volume previously processed at captive facilities. Solar panel and battery pack producers show the fastest migration toward outsourced functional layer deposition.
Global Nanofilms Market Segmentation
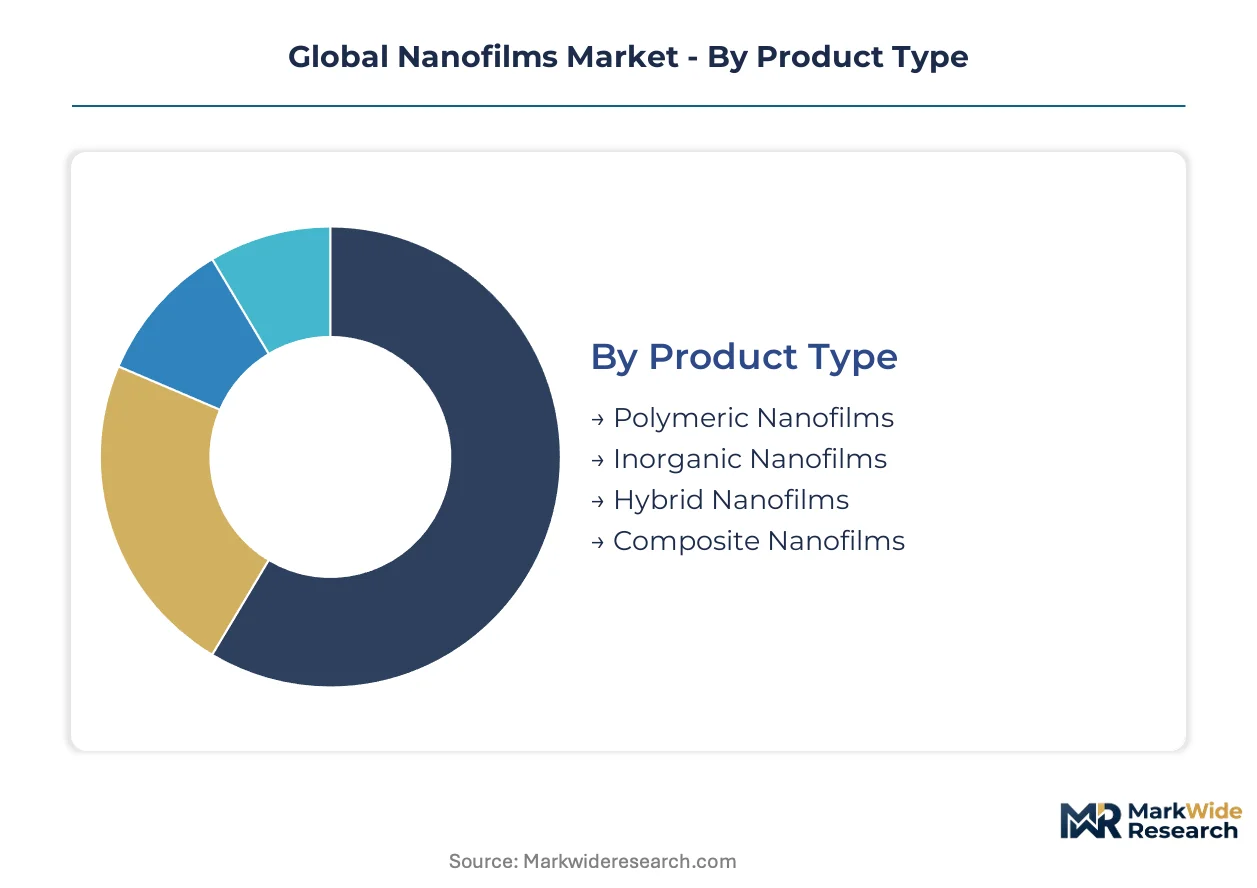
Segmentation in nanofilms reveals how material chemistry, deposition precision, and end-use specifications create distinct competitive arenas. Each dimension carries different margin profiles and technical barriers, from commodity polymeric barriers to semiconductor-grade atomic layer deposition systems.
Product Type:
Integration depth separates standalone functional layers from embedded multi-material architectures, with implications for equipment requirements and customer relationships.
- Polymeric Nanofilms:Engineered from fluoropolymers, polyimides, and barrier-grade polyesters with thickness control to ±5 nanometers. Food packaging producers in Japan and flexible display manufacturers in South Korea account for the majority of volume placements, driven by moisture transmission rate specifications below 0.01 grams per square meter per day.
- Inorganic Nanofilms:Composed of metal oxides, nitrides, and elemental metals deposited with stoichiometric precision for optical and electrical functions. Semiconductor fabricators in Taiwan and South Korea dominate procurement for gate dielectric and copper barrier applications, though precursor supply concentration among German and Japanese specialty chemical suppliers constrains expansion.
- Hybrid Nanofilms:Alternating organic-inorganic lamellar structures combining polymer flexibility with ceramic barrier performance.
- Composite Nanofilms:Nanoparticle-reinforced matrices for mechanical protection and thermal management.
Volume placements concentrate in Polymeric Nanofilms; the faster expansion belongs to Hybrid Nanofilms.
Technology:
Capital intensity and precursor chemistry requirements stratify equipment suppliers into distinct service tiers, from tool sales to full deposition-as-a-service models.
- Atomic Layer Deposition:Sequential self-limiting surface reactions enabling angstrom-level thickness control across 300mm wafers. East Asian foundries in Hsinchu and Yongin operate above 90% utilization for high-k dielectric deposition, squeezing available reactor time for solar cell and battery applications.
- Chemical Vapor Deposition:Thermally or plasma-activated gas-phase reactions for conformal coating of complex geometries. Barrier nanofilm production for flexible electronics concentrates in Japanese and Taiwanese contract manufacturers, with roll-to-roll adaptations enabling polymer web processing at meter-per-minute speeds.
- Physical Vapor Deposition:Sputtering and evaporation methods for metallic and transparent conductive layers.
- Spin Coating:Solution-based deposition for research-scale and select optical coating applications.
Capital deployment favors Atomic Layer Deposition; Chemical Vapor Deposition claims the broadest application span.
Application:
Performance specifications and regulatory exposure determine which deposition technologies penetrate each end-use sector.
- Electronics Manufacturing:Gate stack dielectrics, copper diffusion barriers, and encapsulation layers requiring defect densities below 10^10 per square centimeter. South Korean display panel producers and Taiwanese semiconductor foundries drive specification evolution, with ECHA PFAS restrictions forcing fluoropolymer encapsulant reformulation.
- Solar Cells:Surface passivation and anti-reflection layers for crystalline silicon and perovskite architectures. Tunnel oxide passivated contact cell producers in China and Southeast Asia are scaling atomic layer deposition alumina to gigawatt production lines.
- Water Treatment:Membrane selectivity layers for ion separation and desalination.
- Food Packaging:Oxygen and moisture barriers for extended shelf-life applications.
- Protective Coatings:Wear-resistant and corrosion-blocking layers for industrial components.
Electronics Manufacturing absorbs the largest equipment investment; Solar Cells are climbing the fastest.
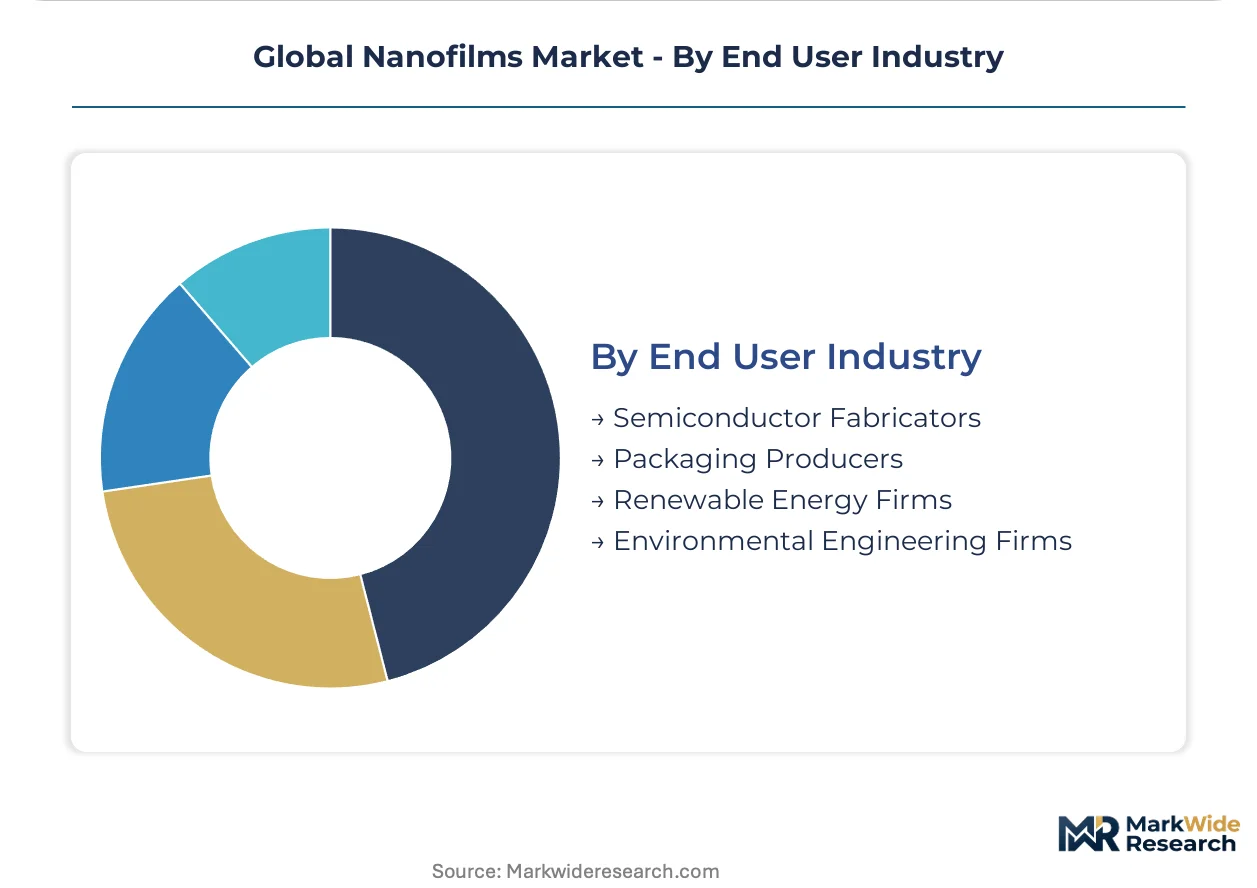
End User Industry:
Procurement sophistication and captive versus outsourced deposition capacity distinguish customer segments.
- Semiconductor Fabricators:Integrated device manufacturers and pure-play foundries operating billion-dollar cleanroom facilities. TSMC, Samsung, and SK Hynix in Taiwan and South Korea set precursor purity standards and equipment roadmaps that cascade to supplier qualification requirements globally.
- Packaging Producers:Flexible film converters and rigid container manufacturers integrating barrier layers. Japanese packaging conglomerates and emerging Indian producers under PLI schemes represent contrasting maturity levels in deposition equipment ownership.
- Renewable Energy Firms:Photovoltaic module manufacturers and battery cell producers.
- Environmental Engineering Firms:Water treatment system integrators and membrane module suppliers.
Semiconductor Fabricators command the highest specification premiums; Renewable Energy Firms are shifting most quickly toward outsourced deposition services.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity organometallic precursor production concentrates in German and Japanese specialty chemical suppliers, creating geographic dependencies that shape nanofilm fabrication economics across consuming markets.
United States
Semiconductor fabricators in Arizona and Texas drive atomic layer deposition equipment demand for sub-3nm gate stacks. EPA regulation of perfluorinated substances under TSCA Section 6 is forcing coating reformulation across electronics and packaging operations. The Southwest production corridor spanning Phoenix and Austin anchors domestic capacity expansion for dielectric nanofilms.
Germany
Precursor chemical suppliers in the Rhine-Ruhr industrial region command critical supply positions for global barrier nanofilm production. ECHA restrictions on PFAS under REACH Phase-Down accelerate non-fluorinated barrier chemistry R&D investment. Bavarian equipment manufacturers near Munich specialize in roll-to-roll chemical vapor deposition systems for flexible electronics.
Japan
Display panel producers and chemical vapor deposition foundries in the Kanto and Kansai regions generate concentrated demand for dielectric and barrier nanofilms. METI industrial policy supports domestic precursor supply chain security amid geopolitical tensions. The Kyushu semiconductor cluster anchors advanced node fabrication with captive nanofilm deposition capacity.
South Korea
Samsung and SK Hynix operations in Yongin and Icheon drive specification evolution for high-k dielectric deposition. MFDS biocompatibility extensions for implantable electronics extend certification timelines for nanofilm-enabled medical devices. The Seoul Capital Area concentration of foundry capacity operates above 90% utilization for atomic layer deposition systems.
India
Production-linked incentive schemes for semiconductor and display manufacturing in Gujarat and Tamil Nadu attract nanofilm equipment vendors to establish precursor supply operations. BIS standards for electronics manufacturing elevate local content requirements for functional coatings. The Dholera Special Investment Region anchors emerging cleanroom fabrication infrastructure for barrier nanofilm production.
Global Nanofilms Market Competitive Landscape
Global majors compete with regional champions across precursor supply, equipment manufacturing, and deposition services. The vendor base stratifies into three tiers: integrated material-equipment providers, pure-play deposition specialists, and contract manufacturing services. Strategic archetypes include fluoropolymer formulation leaders, atomic layer deposition system innovators, and roll-to-roll processing integrators. Capacity consolidation and technology licensing represent the dominant competitive moves as firms secure precursor supply agreements and expand geographic service footprints.
Within the integrated material tier, 3M Company and DuPont de Nemours occupy positions as formulation anchors with deep fluoropolymer and polyimide expertise. Nanofilm Technologies exemplifies the precision equipment archetype through its atomic layer deposition specialization. Among Asia-Pacific specialists, Cosmo Films Limited represents the flexible packaging integration model. These three anchors illustrate how competitive positioning fragments across material science, deposition technology, and end-use application expertise.
| Leading Market Players |
|---|
| Nanofilm |
| Nanofilm Technologies |
| Cosmo Films Limited |
| 3M Company |
| DuPont de Nemours |
| Nano Foam Technology Private Limited |
| Nano Therapeutics Pvt. Ltd |
| NanoGram Corporation |
| MAT-VAC Technology |
| Others |
Supply & Pricing Matrix
Atomic layer deposition technician scarcity in East Asian foundries compresses labor-cost differentials between premium semiconductor-grade and economy-tier packaging nanofilms, widening pricing spreads as qualification barriers harden.
Pricing Analysis
Warranty and preventive maintenance bundling separates premium atomic layer deposition system contracts from unbundled equipment-only sales in the nanofilm equipment tier. Three-tier pricing structure across premium, standard, and economy levels reflects certification grade and precursor purity specifications. Pricing pressure stems from REACH Phase-Down of PFAS forcing reformulation investments among European barrier nanofilm suppliers. Contract manufacturers in Taiwan and Malaysia exhibit highest price sensitivity; semiconductor fabricators in South Korea show lowest sensitivity due to captive utilization premiums.
Supply Chain Analysis
Freight costs for high-purity organometallic precursors elevate landed costs for barrier nanofilm fabricators sourcing from German and Japanese specialty chemical suppliers. Production concentrates in Japan, South Korea, and Taiwan for chemical vapor deposition foundry capacity; Germany and Japan anchor precursor supply. Raw material dependencies include trimethylaluminum, tetrakis(dimethylamino)titanium, and high-purity nitrogen carrier gases. Single-source vulnerability for organometallic precursors creates supply chain risk. Distribution runs through consolidated procurement channels with contract manufacturers capturing volume from captive facilities.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atomic layer deposition equipment utilization above 90% at East Asian foundries props pricing power across dielectric and barrier nanofilm tiers, constraining supply expansion for non-semiconductor applications.
For Market Incumbents: Extend precursor supply agreements with German and Japanese specialty chemical suppliers to lock in high-purity organometallic allocations before capacity constraints harden. Expand technical service footprints in Gujarat and Tamil Nadu under India's PLI schemes to capture emerging semiconductor fabrication demand. Vertical integration into precursor purification addresses single-source vulnerability.
For New Entrants and Emerging Players: The premium-to-economy tier price gap in polymeric nanofilms offers entry opportunity through fluorine-free barrier chemistry qualification ahead of EPA enforcement timelines. Target India's Dholera Special Investment Region for cleanroom fabrication infrastructure partnerships with PLI-backed display manufacturers. Roll-to-roll chemical vapor deposition system integration provides go-to-market angle against incumbent atomic layer deposition specialists.
For Investors and Strategic Acquirers: Re-rating potential sits with hybrid nanofilm specialists given solar cell passivation layer expansion pulling atomic layer deposition alumina into gigawatt-scale production. Long-term viability favors deposition-as-a-service contract manufacturers with equipment utilization diversification across electronics, solar, and battery end-uses. Watch atomic layer deposition technician training program scaling as inflection indicator for supply constraint easing.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captive high-purity organometallic production reduces German and Japanese supplier dependency. |
| Roll-to-Roll Chemical Vapor Deposition Scale-Up | Meter-per-minute polymer web processing enables foldable display barrier integration at volume. |
| Fluorine-Free Barrier Chemistry Qualification | EPA TSCA Section 6 compliance secures US electronics and packaging market access. |
| India PLI Scheme Technical Service Expansion | Gujarat and Tamil Nadu precursor supply operations capture semiconductor fabrication demand. |
| Hybrid Nanolaminate Stack Development | Alternating organic-inorganic architectures unify moisture barrier with thermal mechanical stability. |
Research Methodology
Trade association data, regulatory filings, and customs records anchored secondary inputs for this nanofilms market analysis. Primary interviews with atomic layer deposition equipment engineers, precursor chemical procurement managers, semiconductor fabrication planners, and flexible packaging technical directors combined with secondary validation. Secondary sources included ECHA REACH restriction documents, EPA TSCA Section 6 enforcement timelines, SEMI equipment market data, and Japan METI industrial policy releases. Bottom-up equipment shipment tracking and top-down end-use demand modeling provided triangulation.
Data-stream reconciliation across deposition technology adoption curves, precursor chemical trade flows, and end-use capacity announcements shaped the analytical framework. Segmentation dimensions modeled encompassed material chemistry, deposition precision, application performance specifications, and regional production cluster dynamics. CAGRs were derived from equipment utilization trends and capacity expansion announcements across the analysis window. Forecast inputs included semiconductor node migration roadmaps and solar cell passivation layer adoption rates.
Inputs from equipment vendors and foundry operators were available through the study window; gaps in proprietary precursor pricing and contract manufacturer margin structures introduce uncertainty bands. Forecasts reflect assumptions about REACH Phase-Down enforcement timing and India PLI scheme disbursement rates. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Nanotubes Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Nanocomposites Market