
 Nanotechnology Market | 2026-2036
Nanotechnology Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotechnology Market Intelligence
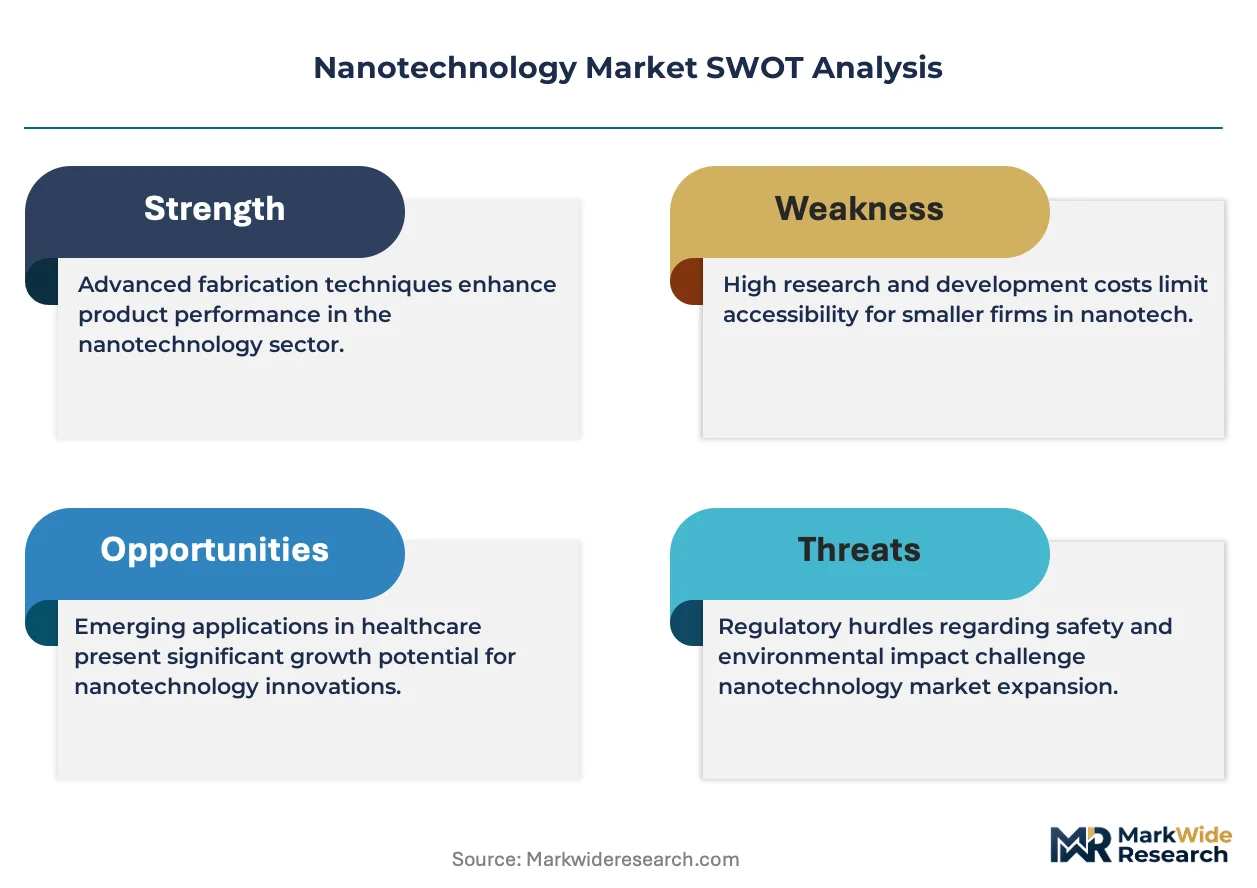
REACH is repositioning the European nanomaterial landscape by mandating extensive safety dossiers that smaller producers cannot afford. Sila Nanotechnologies leverages its silicon nanocomposite expertise to anchor premium battery supply contracts with automotive OEMs. Amprius specializes in ultra-high-energy lithium-metal cells that extend flight endurance for defense drones. Nanosys dominates quantum-dot display formulations through tight control over cadmium-free synthesis pathways.
Nanotechnology encompasses the manipulation of matter at dimensions between one and one hundred nanometers, where quantum mechanical effects and exponentially increased surface-area-to-volume ratios alter optical, electrical, and catalytic properties. Chemical vapor deposition achieves atomic-scale film uniformity critical for gate oxides in sub-3nm transistors. Nanoparticles capture the dominant revenue share in antimicrobial coatings and targeted drug delivery vectors. Energy Storage applications are pulling fastest volume growth as silicon nanowire anodes and solid-state electrolytes approach commercial scale. Nanoimprint Lithography competes with extreme ultraviolet patterning for cost-sensitive photonic device fabrication.
FDA maintains evolving guidance frameworks for nanotechnology-enabled medical products that determine clinical trial design and approval timelines. EPA regulates nanoscale pesticides and antimicrobials under FIFRA with distinct data requirements from conventional chemicals. ISO/TS 80004 terminology standards shape how patent claims and trade specifications describe nanomaterial hierarchies. Stakeholders must monitor how the EU AI Act intersects with nanosensor-enabled diagnostic platforms to anticipate compliance burdens before product development lock-in.
Market Dynamics
Silicon nanowire anodes are pulling battery manufacturers away from graphite supply chains, forcing electrode material suppliers to retool wet-chemical synthesis lines or lose automotive qualification contracts.
Growth Catalysts
- Atomic Layer Deposition:Taiwan and South Korean semiconductor fabs are expanding ALD capacity for sub-3nm gate oxides, pulling equipment and precursor chemical demand.
- EU REACH Registration:Mandatory nanomaterial safety dossiers are consolidating the supplier base toward compliant producers with in-house toxicology capabilities.
- China Battery Gigafactory Corridors:Silicon nanowire anode production is scaling to serve domestic electric vehicle cell demand, displacing imported graphite anodes.
Market Restraints
- Precursor Chemical Concentration:Organometallic ALD precursors depend on a narrow German and US supplier base, creating single-source vulnerability for Asian fabs.
- REACH Compliance Cost:ECHA registration fees and required mammalian toxicity studies price out sub-50 ton nanomaterial producers across Europe.
- Graphite Cost Arbitrage:Synthetic graphite from Chinese anode makers retains 40-60% cost advantage over silicon nanowire equivalents at equivalent energy density.
Strategic Opportunities
- India PLI Scheme:Production-linked incentives for advanced cell chemistry manufacturing are attracting silicon nanocomposite anode investments into Gujarat and Tamil Nadu.
- EU AI Act Convergence:Nanosensor-enabled diagnostic platforms face overlapping compliance requirements, creating first-mover advantage for dual-certified device developers.
- Solid-State Electrolyte Integration:Sulfide and oxide ceramic electrolytes are converging with silicon anodes to enable lithium-metal cell architectures for defense aviation.
Industry Challenges
- Atomic-Scale Metrology Talent:Cross-sectional TEM sample preparation and ALD film thickness characterization require scarce technicians with semiconductor fab experience.
- ISO/TS 80004 Certification Lag:Inconsistent terminology implementation across patent offices delays freedom-to-operate assessments and licensing negotiations.
- Legacy Wet-Chemical Asset Stranding:Graphite anode production lines face accelerated obsolescence as automotive OEMs mandate silicon content thresholds in cell specifications.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotechnology Market |
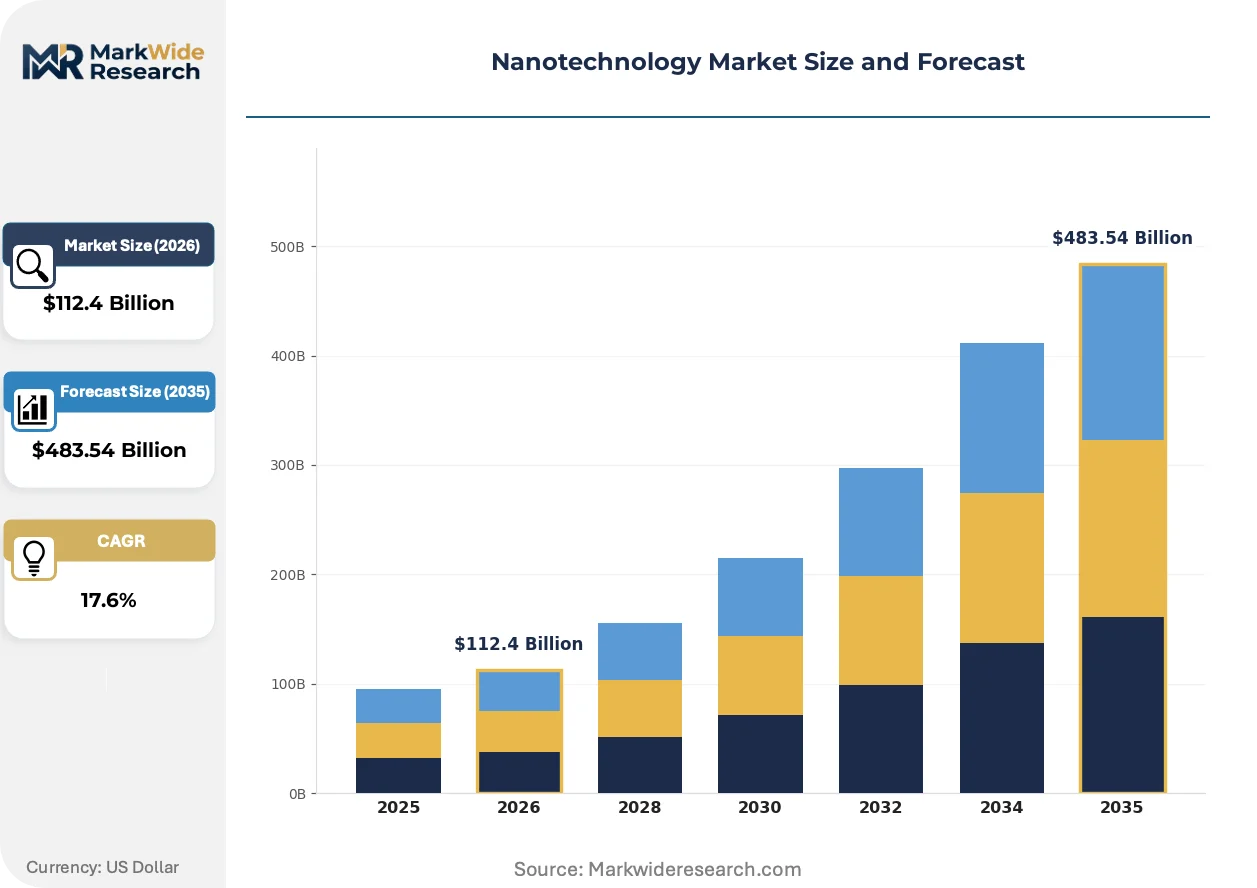
| Market Size in 2026 | $112.4 Billion |
| Market Size in 2035 | $483.54 Billion |
| CAGR (2026 – 2036) | 17.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanoparticles, Nanocomposites, Nanosheets, Nanofibers Application: Electronics, Medicine, Energy Storage, Water Treatment End User: Healthcare, Automotive, Defense, Consumer Goods Technology: Nanoimprint Lithography, Chemical Vapor Deposition, Sol-Gel Process, Ball Milling |
| Companies Covered | Forge Nano, Nanoramic Laboratories, Sila Nanotechnologies, Moleaer, INBRAIN Neuroelectronics, Group14 Technologies, Amprius, Nano Dimension, Nanosys, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotechnology Market Strategic Shifts & Innovations
Process automation and regulatory convergence are compressing development cycles, while procurement rationalization is reshaping how nanomaterial producers engage with consolidated battery and semiconductor buyers.
Self-aligned quadruple patterning is automating sub-7nm feature definition in logic and memory fabs, reducing reliance on extreme ultraviolet lithography for cost-sensitive layers. Samsung and TSMC are adopting SAQP for peripheral circuitry, cutting EUV shot count by 30-40% on non-critical layers. This is automating throughput gains in mature-node migrations where EUV tool availability constrains expansion.
ECHA's 2022 nanomaterial registration guidance is forcing reformulation of antimicrobial coatings and sunscreens across the EU single market. Downstream users now demand full substance identity and exposure assessment data before contract renewal. Cosmetic and textile formulators are responding by sourcing from REACH-registered producers exclusively, squeezing non-compliant Asian suppliers from European supply chains.
Automotive cell procurement is consolidating around long-term offtake agreements with silicon anode specialists, displacing spot-market graphite purchasing. Battery makers are locking five-to-seven year supply contracts directly with nanowire producers, bypassing traditional anode material traders. This concentration is most visible in China's Yangtze River Delta, where CATL and BYD are vertically integrating into silicon nanowire synthesis through equity stakes in Jiangsu-based suppliers.
Nanotechnology Market Segmentation
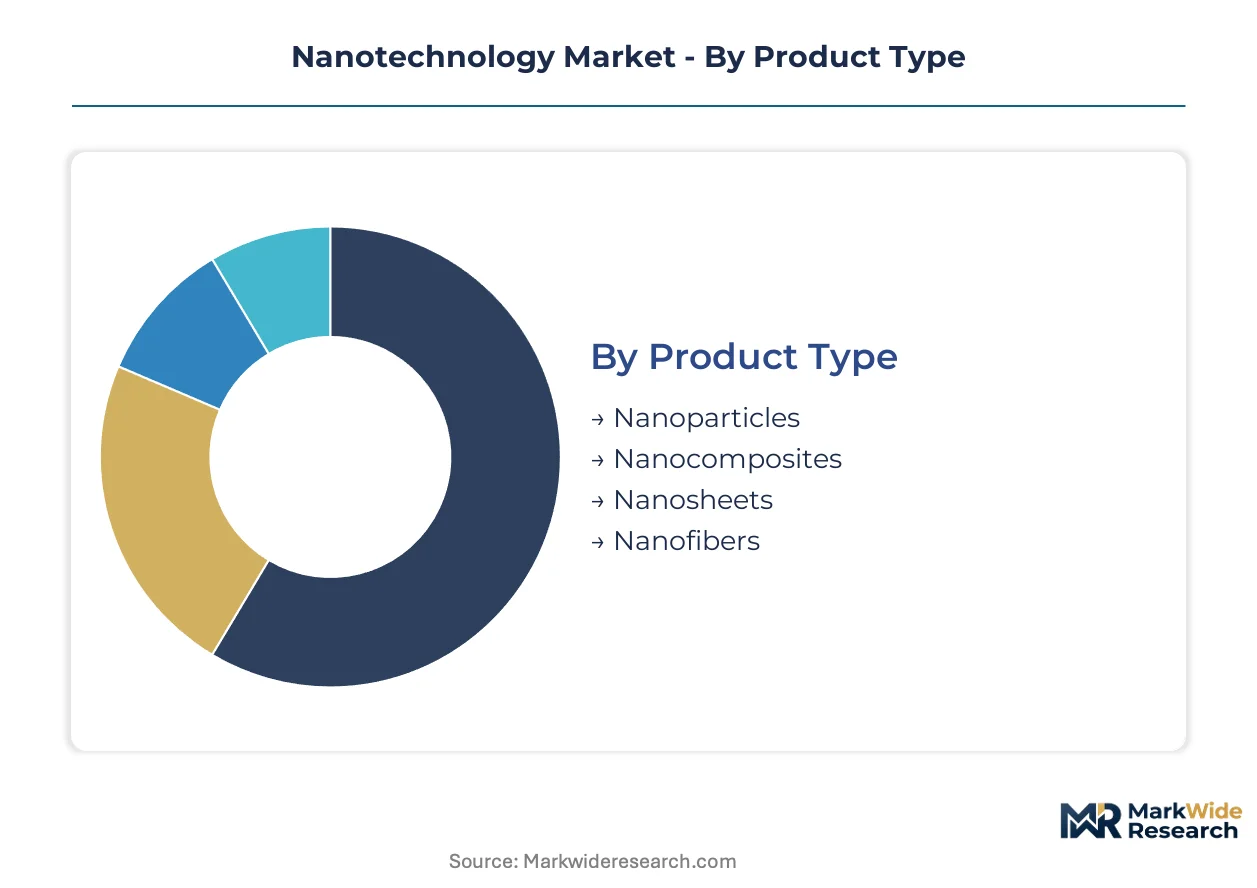
Nanotechnology markets fragment across multiple technical and commercial dimensions. Product form determines manufacturing scale and margin structure. Application focus shapes regulatory exposure and customer concentration risk.
Product Type:
Buyers differentiate by surface-area-to-volume ratio requirements and dispersion stability needs in their target matrices.
- Nanoparticles:Discrete 1-100nm units with quantum confinement effects dominating optical and catalytic behavior. Antimicrobial coatings and drug delivery vectors in Germany and the US pull volumes, constrained by ECHA registration thresholds that filter out sub-scale suppliers.
- Nanocomposites:Hybrid structures embedding nanoscale reinforcements within polymer or ceramic matrices. Silicon-carbon anode formulations for China's battery gigafactories concentrate procurement, displacing conventional graphite as automotive OEMs mandate energy density thresholds.
- Nanosheets:Two-dimensional materials with single-atom thickness enabling gate dielectric and barrier film applications. Graphene and transition metal dichalcogenide variants serve semiconductor fabs in Taiwan and South Korea.
- Nanofibers:Filamentary structures with diameters below 100nm providing high porosity and mechanical strength. Air filtration media and wound dressings absorb production from electrospinning lines in Japan and the US.
Nanoparticles lead volumes today; nanocomposites are gaining share fastest.
Application:
End-use selection determines whether customers prioritize purity certification, biocompatibility dossiers, or electrochemical performance metrics.
- Electronics:Sub-3nm transistor gate oxides and quantum-dot display formulations demand atomic-scale thickness control. Taiwan's foundry sector pulls ALD precursor volumes while Samsung and TSMC compete on patterning density.
- Medicine:Targeted delivery vectors and diagnostic imaging agents require FDA or EMA master file submissions. Liposomal and polymeric nanoparticle formulations face distinct sterilization and stability validation protocols.
- Energy Storage:Silicon nanowire anodes and solid-state electrolyte interfaces approach commercial scale. China's Yangtze River Delta cell manufacturers lock long-term offtake agreements directly with anode specialists.
- Water Treatment:Photocatalytic membranes and adsorptive nanoparticles address contaminant removal. Municipal utilities in India and the Middle East pilot titanium dioxide and iron oxide systems for arsenic and heavy metal capture.
Electronics commands the largest revenue pool; energy storage climbs the fastest.
End User:
Procurement sophistication varies from centralized R&D sourcing to fragmented commodity purchasing across these verticals.
- Healthcare:Pharmaceutical and medical device manufacturers demand batch consistency documentation and sterilization validation. CDSCO and FDA submission requirements extend development timelines for nanotechnology-enabled therapeutics.
- Automotive:Cell producers and OEMs specify silicon content thresholds in battery anodes, forcing electrode material suppliers to retool synthesis lines or lose qualification status.
- Defense:Ultra-high-energy lithium-metal cells for drone endurance and lightweight armor composites prioritize performance over cost. US and European defense agencies fund classified development programs with restricted supplier pools.
- Consumer Goods:Cosmetics and textiles source antimicrobial and UV-blocking additives through spot-market purchasing. REACH-registered producers capture EU share as formulators abandon non-compliant Asian suppliers.
Healthcare generates premium pricing; automotive pulls volume expansion most aggressively.
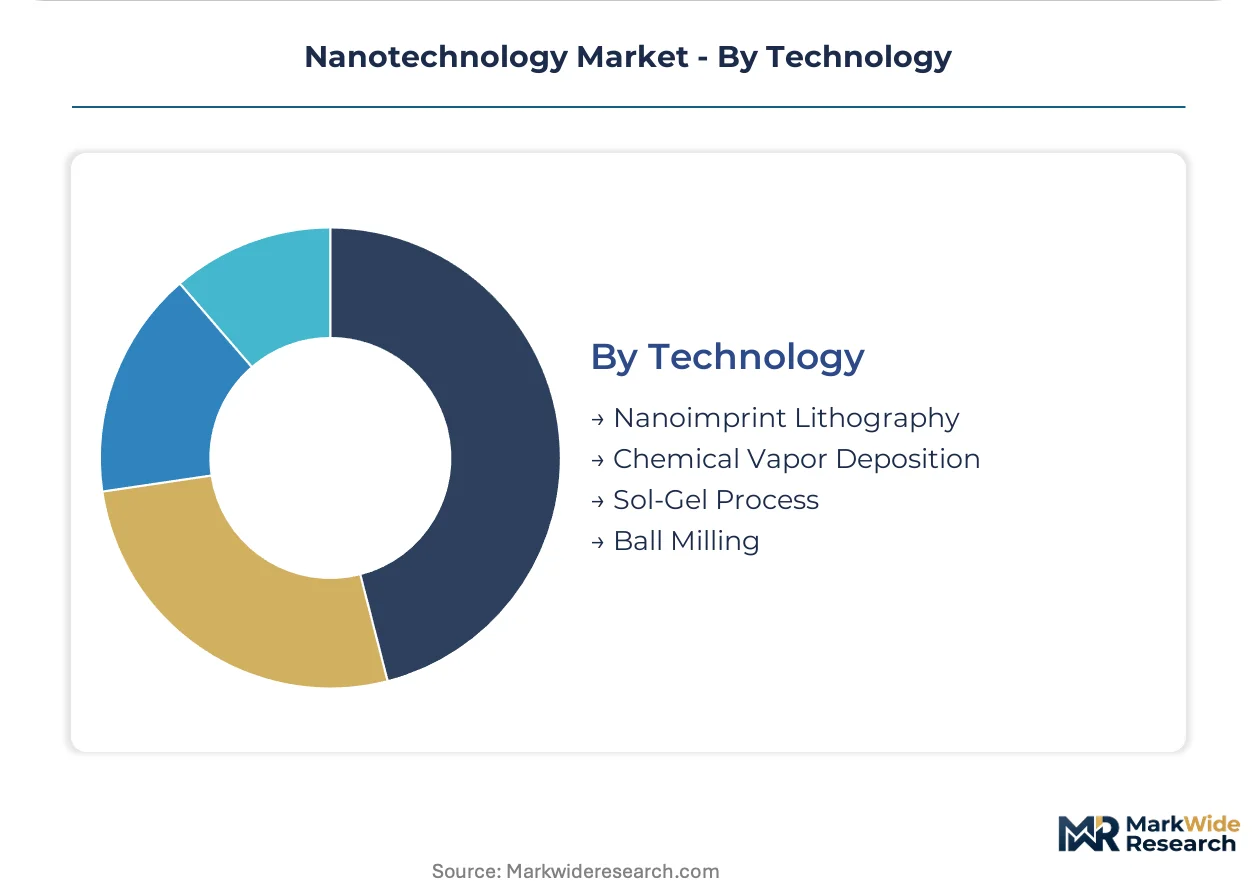
Technology:
Capital intensity and technical talent availability separate scalable production methods from laboratory-scale techniques.
- Nanoimprint Lithography:Mechanical patterning of sub-100nm features competes with EUV for cost-sensitive photonic devices. South Korean display manufacturers adopt NIL for quantum-dot patterning to reduce shot count.
- Chemical Vapor Deposition:Gas-phase precursor decomposition achieves conformal film coverage on complex topographies. German and US precursor suppliers face capacity constraints as Taiwan and South Korean fabs expand sub-3nm production.
- Sol-Gel Process:Wet-chemical hydrolysis and condensation produces oxide nanoparticles and thin films. Spain and Italy host specialist producers of silica and titania sols for coating applications.
- Ball Milling:Mechanical attrition reduces particle size without chemical transformation. Lower-purity applications in construction materials and pigments rely on this cost-minimized approach.
Chemical vapor deposition dominates semiconductor-facing revenue; nanoimprint lithography expands most quickly in display manufacturing.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Atomic-scale fabrication talent clusters in East Asian semiconductor corridors and German chemical engineering centers anchor nanotechnology production capacity worldwide.
United States
Defense aviation and quantum computing applications pull ultra-high-energy cell and quantum-dot demand. EPA regulates nanoscale pesticides under FIFRA with distinct data requirements from conventional chemicals. Boston and Silicon Valley host venture-backed startups commercializing silicon nanocomposite anodes and neuromorphic chips.
Germany
Precursor chemical synthesis and atomic layer deposition equipment manufacturing concentrate supplier leverage. ECHA registration fees and mammalian toxicity studies enforce REACH compliance thresholds that filter sub-scale producers. The Rhine-Ruhr and Bavarian chemical corridors house organometallic precursor specialists serving Asian fabs.
China
Battery gigafactory corridors in the Yangtze River Delta scale silicon nanowire anode production for domestic electric vehicle demand. MIIT and SAMR enforce GB standards on nanomaterial classification and occupational exposure limits. CATL and BYD lock long-term offtake agreements directly with Jiangsu-based anode specialists.
South Korea
Sub-3nm transistor gate oxide production pulls atomic layer deposition precursor volumes from German suppliers. MFDS maintains evolving guidance frameworks for nanotechnology-enabled medical products determining clinical trial timelines. Samsung and SK Hynix fabs in Gyeonggi Province compete on patterning density for memory and logic chips.
Japan
Electrospinning lines for nanofiber air filtration and wound dressings absorb production from METI-supported manufacturing sites. PMDA submission requirements extend development timelines for nanotechnology-enabled therapeutics. Osaka and Nagoya industrial clusters specialize in titania sols and photocatalytic coating applications.
Nanotechnology Market Key Industry Players
The competitive structure tilts toward technology-locked specialists with captive precursor supply or proprietary synthesis pathways. Consolidation pressure intensifies as automotive cell producers mandate silicon content thresholds and semiconductor fabs concentrate ALD equipment procurement. Two archetypes dominate: venture-backed battery material specialists with automotive offtake contracts, and legacy chemical producers with REACH-registered nanomaterial portfolios. Competitive moves center on backward integration into precursor chemical production and five-to-seven year supply contract lock-ins with battery OEMs.
Among US-based venture-scaled developers, Sila Nanotechnologies and Amprius occupy positions within the battery material archetype, while Nanosys sits within the quantum-dot display formulation tier. These entities exemplify how specialized synthesis expertise converts into long-term supply agreements with consolidated automotive and electronics buyers.
| Leading Market Players |
|---|
| Forge Nano |
| Nanoramic Laboratories |
| Sila Nanotechnologies |
| Moleaer |
| INBRAIN Neuroelectronics |
| Group14 Technologies |
| Amprius |
| Nano Dimension |
| Nanosys |
| Others |
Cost & Logistics Intelligence
Automotive OEM silicon content mandates for battery anodes are forcing electrode material suppliers to abandon graphite synthesis lines and absorb capital retooling costs, compressing margins across the anode supply base while concentrating pricing power with REACH-registered nanomaterial producers.
Pricing Analysis
Long-term offtake contracts versus spot-market purchasing splits the pricing landscape. Contract-based five-to-seven year supply agreements dominate automotive cell procurement, while commodity spot purchasing persists in consumer goods antimicrobial coatings. Price differentiation rests on ECHA registration status and silicon purity grades. Cost compression in unregistered Asian nanoparticle supplies is intensifying because European formulators are abandoning non-compliant sources. Battery OEMs show lowest price sensitivity; cosmetics manufacturers exhibit highest.
Supply Chain Analysis
Regional distribution centers in Germany's Rhine-Ruhr corridor and South Korea's Gyeonggi Province anchor hub-and-spoke precursor chemical flows. Taiwan, South Korea, and Germany concentrate ALD equipment and organometallic precursor production. German and US suppliers feed Asian fabs with trimethylaluminum and tetrakis precursors. Single-source vulnerability in organometallic ALD precursors creates structural risk. Distribution runs through direct fab-to-supplier pipelines for semiconductors, bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as a late-cycle quality story. Automotive OEMs are mandating silicon nanowire anode specifications that filter out sub-scale wet-chemical producers.
For Market Incumbents: Hedge against graphite anode asset stranding by accelerating backward integration into organometallic precursor synthesis in Germany or captive silicon nanowire production in China's Yangtze River Delta. Lock five-year supply contracts with CATL and BYD before qualification windows close. Reinforce REACH registration portfolios to capture EU cosmetics and textile formulators abandoning Asian suppliers. For New Entrants and Emerging Players: Enter via India's PLI scheme for advanced cell chemistry manufacturing in Gujarat and Tamil Nadu, where silicon nanocomposite anode capacity is underdeveloped. Target defense aviation lithium-metal cell applications where Amprius-style ultra-high-energy architectures face limited competition. Pursue dual EU AI Act and ISO/TS 80004 certification for nanosensor diagnostic platforms. For Investors and Strategic Acquirers: Asymmetric upside sits with venture-scaled battery material specialists holding automotive offtake contracts and captive precursor supply. Five-to-ten year viability hinges on silicon anode cost convergence with synthetic graphite. Watch for ECHA registration threshold enforcement as inflection signal for EU market access consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Synthesis | German organometallic suppliers capture margin from Taiwan and South Korean fab expansion. |
| REACH Registration Completion | ECHA compliance unlocks EU antimicrobial coating and sunscreen formulator contracts. |
| Long-term Supply Agreement Lock-in | Silicon nanowire producers secure five-to-seven year automotive cell procurement commitments. |
| Dual Certification Pathway | EU AI Act and ISO/TS 80004 convergence creates first-mover advantage for nanosensor diagnostics. |
| India PLI Scheme Entry | Production-linked incentives attract advanced anode manufacturing into Gujarat and Tamil Nadu corridors. |
Research Approach
Bottom-up energy storage and electronics demand modeling reconciled against top-down ALD equipment and precursor chemical supply tracking forms the analytical core. Primary interviews with semiconductor fab procurement officers, battery cell material directors, ECHA regulatory affairs leads, and automotive OEM cell qualification engineers combined with secondary validation. Sources include SEC filings from equipment manufacturers, ECHA registration databases, MIIT GB standard disclosures, and customs trade data for organometallic precursor flows. Triangulation against patent filing trends and foundry capex announcements anchored volume assumptions.
Input-output matrices mapped silicon nanowire anode production capacity against automotive cell demand across the projection horizon. Segmentation dimensions modeled include product type, application focus, end-user vertical, and synthesis technology. CAGRs derived from installed base growth rates for sub-3nm transistor production and electric vehicle cell manufacturing capacity. Forecast inputs incorporated ECHA registration timeline enforcement and India PLI scheme uptake trajectories.
Inputs from ECHA registration databases and MIIT standard disclosures were available through the study window; gaps in classified defense aviation program specifications introduce uncertainty bands around lithium-metal cell demand. Forecasts reflect documented assumptions regarding silicon-graphite cost convergence timing. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Metal Nitride Nanoparticles Market