
 United States Gold Nanoparticles Market | 2026-2036
United States Gold Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
United States Gold Nanoparticles Market Intelligence
FDA guidance on nanotechnology-enabled products is shifting the cost-of-entry calculus for commercializing gold nanoparticle therapies, requiring extensive toxicology and biodistribution data before investigational new drug approval. Fortis Life Sciences leverages its vertically integrated manufacturing platform to sustain consistent supply for diagnostics customers. Thermo Fisher Scientific anchors the market through its broad electron microscopy and analytical instrument portfolio that supports nanoparticle characterization workflows.
Gold nanoparticles are colloidal suspensions of metallic gold particles ranging from 1 to 100 nanometers in diameter, typically synthesized via citrate reduction or seed-mediated growth methods, valued for their surface plasmon resonance, biocompatibility, and facile surface functionalization with antibodies, nucleic acids, or small molecules. Colloidal gold dominates current pharmaceutical and diagnostics applications due to established manufacturing scale and regulatory familiarity, while gold nanorods represent the fastest-growing product type driven by near-infrared photothermal therapy development. Electron microscopy technology captures the largest share of analytical instrumentation demand as the definitive method for size and morphology verification.
FDA, EPA, and OSHA collectively govern gold nanoparticle commercialization through overlapping jurisdiction covering drug approval, environmental release, and worker exposure limits in manufacturing facilities. The National Nanotechnology Initiative coordinates federal research funding that indirectly shapes which applications receive sufficient toxicology data for regulatory advancement. Stakeholders must monitor evolving FDA guidance documents on characterization standards as these will determine which product formats achieve market access without protracted preclinical development timelines.
Market Dynamics
FDA's evolving nanotechnology characterization guidance is compressing preclinical timelines for gold nanoparticle drug candidates while simultaneously raising toxicology data requirements. Pharmaceutical sponsors must now front-load biodistribution studies before IND submission, fundamentally restructuring R&D resource allocation across the development pipeline.
Growth Catalysts
- Targeted oncology delivery:Gold nanoparticle-antibody conjugates enable precise tumor accumulation with reduced systemic toxicity, accelerating pipeline investment from biopharma sponsors in Massachusetts and California research corridors.
- OSHA exposure frameworks:Finalized workplace safety guidelines for engineered nanomaterials provide manufacturing clarity, enabling scaled production investments without regulatory ambiguity on worker protection protocols.
- Seed-mediated synthesis advances:Improved control over particle aspect ratios and surface plasmon tuning is expanding addressable applications in photothermal therapy and multiplexed diagnostics platforms.
Market Restraints
- Gold price volatility:Precious metal input costs fluctuate with commodity markets, compressing margin predictability for high-volume diagnostic reagent manufacturers.
- Massachusetts supply concentration:Specialized synthesis expertise and GMP manufacturing capacity cluster in limited geographic zones, creating single-source vulnerability for time-sensitive clinical programs.
- EPA environmental release protocols:Discharge monitoring requirements for aqueous synthesis effluent add compliance overhead without established precedent for sub-100 nanometer particle fate-and-transport assessment.
Strategic Opportunities
- Texas and North Carolina expansion:Emerging life sciences infrastructure in these states offers lower operational costs and available specialized workforce pools outside saturated Northeast corridors.
- Companion diagnostic pairing:FDA's simultaneous review pathways for drug-device combinations create regulatory efficiency for sponsors developing gold nanoparticle imaging agents alongside therapeutic payloads.
- AI-guided surface functionalization:Machine learning algorithms predicting protein corona formation and macrophage clearance rates are compressing formulation optimization cycles from months to weeks.
Industry Challenges
- Electron microscopy technician scarcity:Definitive particle characterization requires specialized operators for transmission and scanning electron microscopy, with training pipelines failing to match demand growth in quality control functions.
- Multi-agency compliance synchronization:FDA drug approval timelines, EPA environmental permits, and OSHA facility certifications operate on independent clocks, creating project management complexity for integrated manufacturing sites.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Gold Nanoparticles Market |
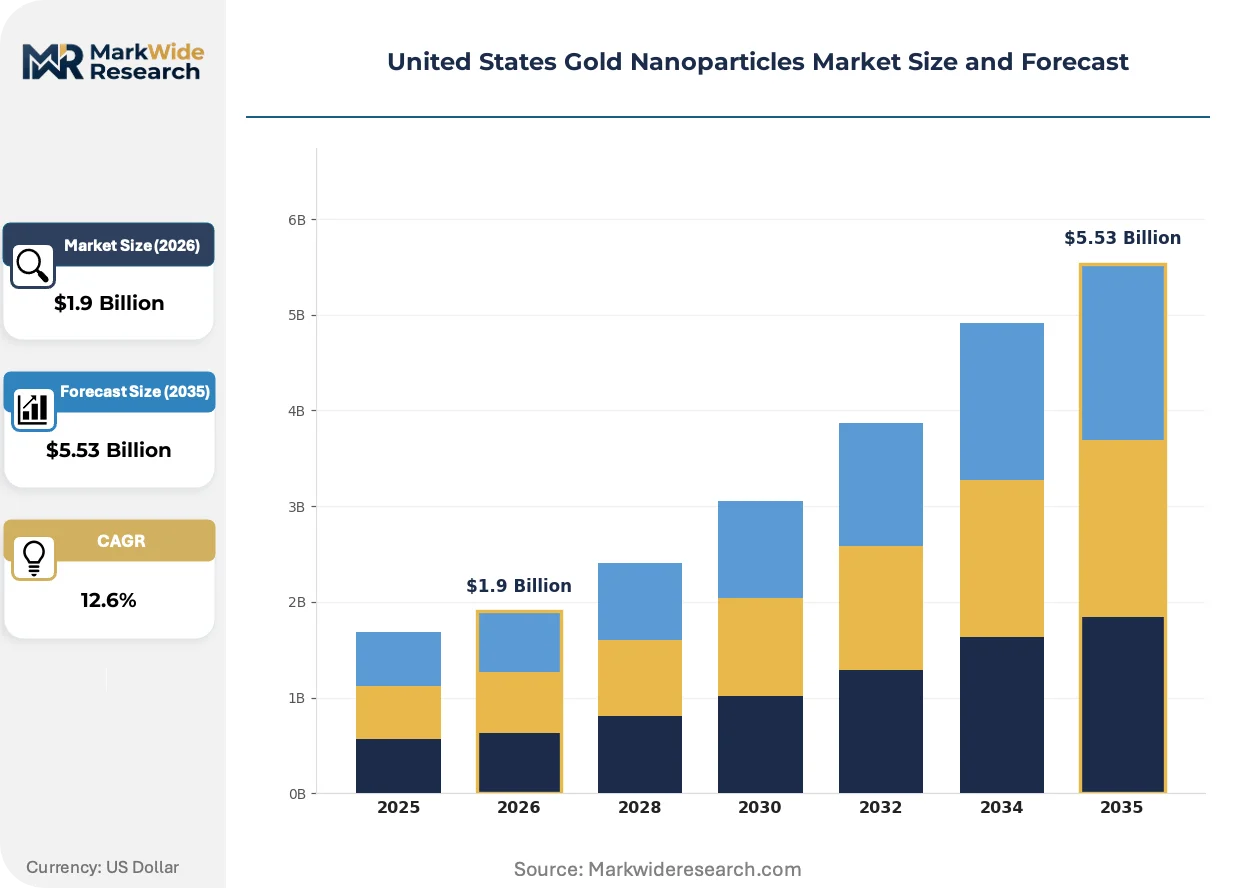
| Market Size in 2026 | $1.9 Billion |
| Market Size in 2035 | $5.53 Billion |
| CAGR (2026 – 2036) | 12.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colloidal Gold, Gold Nanostars, Gold Nanorods, Gold Nanospheres Application: Biomedical, Electronics, Catalysis, Imaging End User: Pharmaceuticals, Research Institutions, Diagnostics, Electronics Manufacturers Technology: UV-Vis Spectroscopy, Electron Microscopy, Flow Cytometry, X-ray Diffraction |
| Companies Covered | Fortis Life Sciences, LLC., nanoComposix, Thermo Fisher Scientific Inc., Meliorum Technologies, Inc., BBI Solutions, Danaher Corporation, Cytodiagnostics Inc., Nanopartz, Inc., Agilent Technologies, Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Gold Nanoparticles Market Strategic Shifts & Innovations
Photothermal therapy platforms and AI-augmented synthesis control are converging to redefine therapeutic index calculations for solid tumor treatment. These developments compress traditional boundaries between diagnostic imaging and interventional oncology.
Gold nanorods with tunable near-infrared absorption peaks are rewriting the clinical feasibility of deep-tissue hyperthermia. Academic medical centers in California and Massachusetts are adopting these constructs for glioblastoma and prostate cancer pilot programs. The technology is compressing the gap between diagnostic localization and therapeutic ablation into single-session procedures.
FDA's 2023 nanotechnology guidance update mandates standardized physiochemical characterization datasets for all IND submissions involving engineered nanomaterials. Sponsors must now submit transmission electron microscopy size distributions, surface charge measurements, and batch-to-batch variability analyses as core modules. Early-stage biotech firms without in-house analytical infrastructure are outsourcing to specialized contract research organizations in the Boston-Cambridge cluster.
Academic technology transfer offices are demanding equity stakes rather than traditional licensing fees for gold nanoparticle synthesis patents originating from federally funded research. This shift alters capital structure calculations for venture-backed startups in the San Francisco Bay Area and Research Triangle Park. The National Nanotechnology Initiative's funding priorities indirectly determine which institutional IP portfolios achieve commercial traction through these revised deal terms.
United States Gold Nanoparticles Market Segmentation
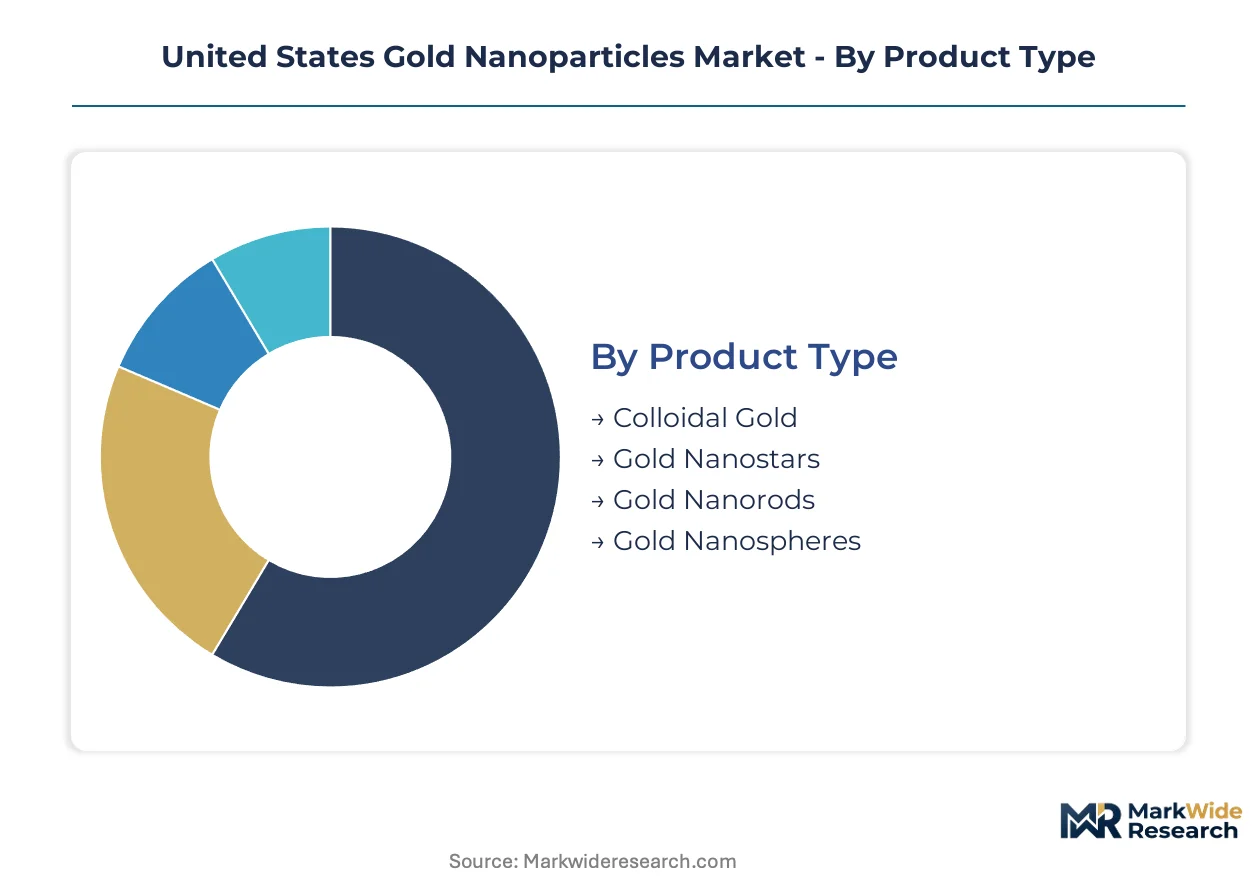
Segmentation reveals how gold nanoparticle demand fractures across distinct technical specifications and regulatory pathways. Buyers select product formats based on surface plasmon resonance requirements, FDA submission history, and compatibility with existing analytical infrastructure.
Product Type:
Buyers prioritize optical tunability and established toxicology datasets when selecting among morphological variants.
- Colloidal Gold:Spherical particles synthesized through citrate reduction dominate current pharmaceutical procurement due to decades of regulatory familiarity and scalable manufacturing. Massachusetts and California diagnostics manufacturers anchor demand for established lateral flow assay reagents, though margin compression from gold price volatility constrains high-volume contract negotiations.
- Gold Nanorods:Aspect-ratio-tunable constructs with longitudinal surface plasmon peaks in the near-infrared window are expanding most quickly. California academic medical centers and photothermal therapy developers in the Research Triangle Park drive procurement for deep-tissue hyperthermia applications where tissue penetration depth determines clinical viability.
- Gold Nanostars:Multi-branched morphologies with enhanced electromagnetic field confinement serve specialized surface-enhanced Raman scattering substrates. Research institutions in Boston-Cambridge cluster represent primary demand concentration.
- Gold Nanospheres:Uniform spherical constructs synthesized through seed-mediated growth provide baseline optical standards for analytical instrument calibration. Electronics manufacturers in Texas integrate these for plasmonic sensor development.
Volume sits with colloidal gold; growth tilts toward gold nanorods.
Application:
End-use selection hinges on reimbursement coding and FDA predicate device availability.
- Biomedical:Targeted drug delivery and therapeutic conjugation command premium pricing. Pharmaceutical sponsors in Massachusetts corridor front-load biodistribution studies to satisfy FDA nanotechnology guidance requirements.
- Imaging:Contrast agents for computed tomography and photoacoustic modalities benefit from companion diagnostic pairing pathways. California radiology practices pilot multimodal constructs combining localization and ablation functions.
- Electronics:Plasmonic waveguides and printable conductive inks leverage gold's oxidation resistance. Texas semiconductor fabrication facilities integrate nanoparticle deposition for next-generation interconnects.
- Catalysis:Surface-area-optimized particles accelerate selective oxidation reactions. Specialty chemical manufacturers in Gulf Coast petrochemical corridor represent concentrated demand.
Revenue concentrates in biomedical; imaging climbs the fastest.
End User:
Procurement scale and qualification requirements separate institutional buyer categories.
- Pharmaceuticals:Sponsors developing oncology therapeutics require GMP-certified synthesis and comprehensive stability data. IND-enabling toxicology investment creates high barriers to supplier switching.
- Diagnostics:Lateral flow and molecular assay manufacturers prioritize batch-to-batch consistency over optical sophistication. Supply agreements with Massachusetts-based CMOs lock in multi-year procurement schedules.
- Research Institutions:Academic laboratories value small-batch flexibility and rapid surface functionalization turnaround. Technology transfer offices increasingly demand equity participation in commercialization outcomes.
- Electronics Manufacturers:Precision deposition equipment compatibility and particle dispersion stability in organic solvents determine supplier selection. North Carolina emerging fabrication facilities expand addressable market.
Procurement volume favors pharmaceuticals; research institutions gain share fastest.
Technology:
Analytical method selection follows regulatory submission requirements and in-house capability investment.
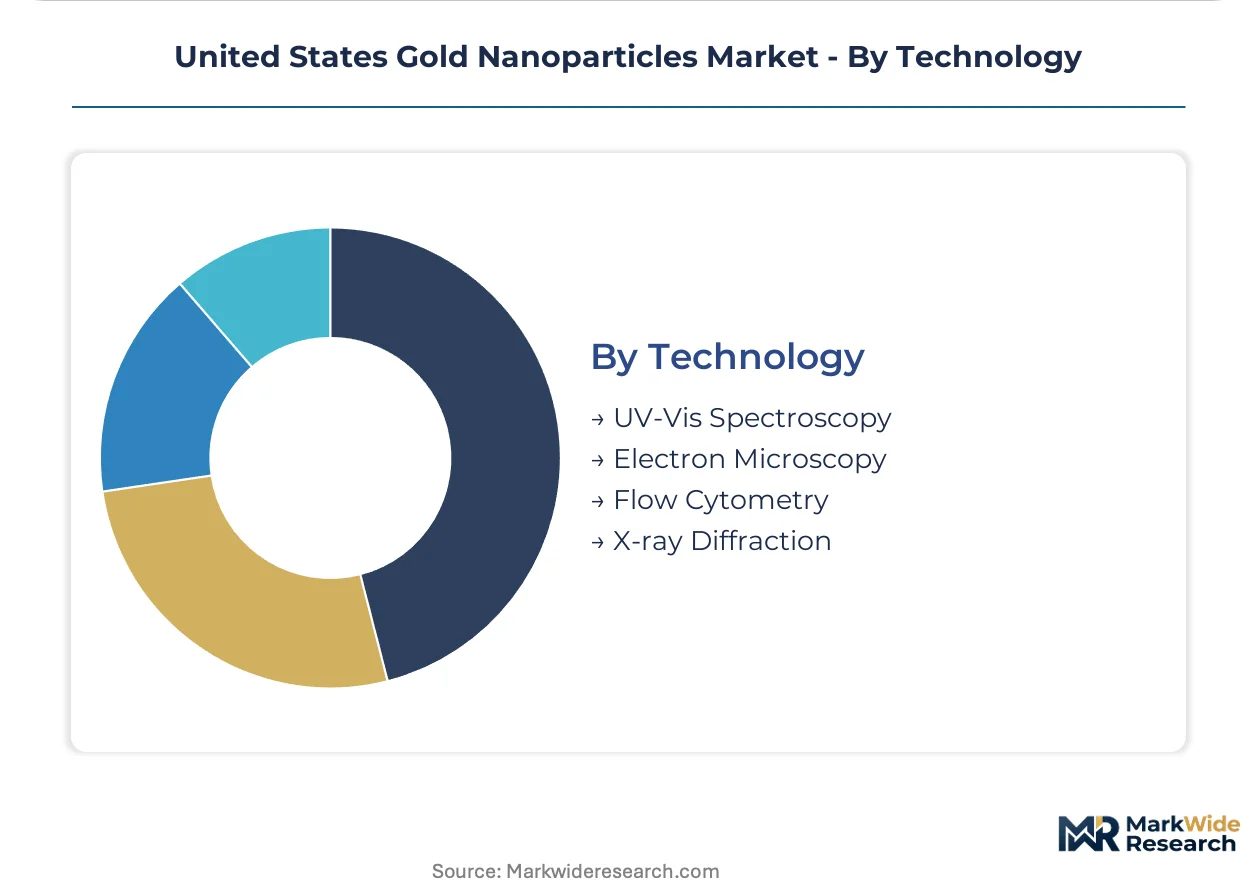
- Electron Microscopy:Transmission and scanning variants provide definitive size and morphology verification mandated by FDA nanotechnology guidance. Technician scarcity in quality control functions constrains analytical throughput expansion.
- UV-Vis Spectroscopy:Surface plasmon resonance peak detection offers rapid batch release for high-volume manufacturing. Diagnostics producers in California corridor standardize on this for routine quality control.
- Flow Cytometry:Single-particle resolution enables polydispersity quantification for complex therapeutic formulations. Emerging adoption in cell therapy co-manufacturing workflows.
- X-ray Diffraction:Crystallographic confirmation of gold face-centered cubic structure supports intellectual property documentation. Research institutions deploy for publication-grade characterization.
Instrument demand centers on electron microscopy; flow cytometry expands most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Qualified Opportunity Zones in Massachusetts and California concentrate synthesis capacity and venture funding for gold nanoparticle ventures. State-level tax incentives amplify federal programs, drawing GMP manufacturing investment into designated census tracts.
Massachusetts
Targeted drug delivery pipelines from Boston-Cambridge biotech sponsors drive procurement of GMP-certified colloidal gold. FDA's nanotechnology guidance mandates front-loaded biodistribution studies, forcing sponsors to co-locate analytical capabilities near manufacturing sites. Worcester County emerging fabrication facilities expand available cleanroom capacity beyond saturated Kendall Square corridors.
California
Photothermal therapy development for glioblastoma and prostate cancer accelerates gold nanorod demand from Stanford and UCSF medical centers. National Nanotechnology Initiative funding through Lawrence Berkeley National Laboratory shapes which synthesis patents achieve commercial licensing. San Diego diagnostics cluster anchors lateral flow assay production for point-of-care applications.
Texas
Semiconductor fabrication facilities in Austin integrate gold nanosphere deposition for plasmonic interconnect development. Lower operational costs relative to Northeast corridors attract electronics manufacturers seeking oxidation-resistant conductive inks. Houston petrochemical corridor provides feedstock proximity for catalysis-grade nanoparticle applications.
North Carolina
Research Triangle Park photothermal therapy developers source specialized nanorods for deep-tissue hyperthermia pilot programs. State biotechnology center grants reduce capital barriers for GMP manufacturing scale-up. Durham-Chapel Hill academic technology transfer offices increasingly demand equity participation in commercialization outcomes.
New York Metro
Electron microscopy service bureaus in Long Island and Westchester County support FDA-mandated characterization for IND submissions. Wall Street venture capital flows into Manhattan-based nanomaterial startups with companion diagnostic pairing strategies. Brooklyn emerging synthesis facilities target batch-to-batch consistency for diagnostics contract manufacturing.
United States Gold Nanoparticles Market Key Industry Players
Massachusetts producers anchor one tier; California specialists hold differentiated positions in photothermal applications. Market structure tilts toward consolidated supply for GMP-certified pharmaceutical-grade material, with fragmented competition in research-scale batches. Three archetypes dominate: vertically integrated life sciences conglomerates, dedicated nanomaterial synthesis houses, and analytical instrumentation providers with captive nanoparticle lines. Capacity expansion and strategic partnerships constitute the dominant competitive moves, as sponsors seek locked-in supply agreements for clinical programs.
Within the vertically integrated tier, Fortis Life Sciences and Danaher Corporation exemplify archetypes combining synthesis with downstream analytical capabilities. Thermo Fisher Scientific occupies a position bridging instrumentation and reagent supply. nanoComposix and Nanopartz, Inc. represent dedicated synthesis specialists serving research and clinical markets respectively. Meliorum Technologies, Inc. and Cytodiagnostics Inc. sit within the mid-scale GMP segment addressing diagnostics manufacturers. Agilent Technologies, Inc. anchors the analytical validation layer that all suppliers must interface with for FDA submission support.
| Leading Market Players |
|---|
| Fortis Life Sciences, LLC. |
| nanoComposix |
| Thermo Fisher Scientific Inc. |
| Meliorum Technologies, Inc. |
| BBI Solutions |
| Danaher Corporation |
| Cytodiagnostics Inc. |
| Nanopartz, Inc. |
| Agilent Technologies, Inc. |
| Others |
Cost & Logistics Intelligence
London Bullion Market Association gold price benchmarks cascade through synthesis workflows into three-tier pricing structures across premium, standard, and economy levels. GMP-certified pharmaceutical-grade material commands substantial premiums over research-scale batches, with spot-market volatility compressing margin predictability for high-volume diagnostic reagent manufacturers locked into annual supply agreements.
Pricing Analysis
Expedited lead-time premiums distinguish pricing tiers, with clinical-timeline sponsors paying 40-60% markups for sub-48-hour batch turnaround versus standard 2-week queue positions. Pricing stratifies across premium, standard, and economy tiers based on FDA master file reference availability and batch-to-batch variability coefficients. Cost compression in economy-tier research material is intensifying because academic technology transfer offices are demanding equity participation rather than traditional licensing fees. Diagnostics manufacturers with locked multi-year CMO contracts exhibit lowest price sensitivity; early-stage biotech sponsors without in-house analytical infrastructure face highest procurement cost volatility.
Supply Chain Analysis
Single-source vulnerability sits with Massachusetts-based GMP synthesis facilities, where Kendall Square corridor concentration creates bottleneck risk for IND-enabling toxicology programs. Domestic production draws from Chilean and Australian gold feedstock, with synthesis reagents and specialized electron microscopy calibration standards sourced from Japan and Germany. Tariff exposure on imported analytical instrumentation amplifies cost structure uncertainty for quality-control-dependent manufacturers. Distribution runs through life sciences-focused third-party logistics providers with cold-chain capabilities, terminating at pharmaceutical sponsor sites, diagnostics CMOs, and academic medical center loading docks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market is a vertical-integration race. Players are pursuing backward integration into GMP-certified synthesis capacity to secure locked-in supply agreements for clinical programs and escape margin compression from precious metal spot volatility.
For Market Incumbents: Acquire specialized electron microscopy service bureaus to capture FDA-mandated characterization workflows and defend against analytical instrumentation providers expanding into captive nanoparticle lines. Fortify Massachusetts manufacturing footprints with redundant cleanroom capacity in Worcester County to mitigate single-source vulnerability. Investment in AI-guided surface functionalization platforms compresses formulation optimization cycles, raising rival cost-of-entry for biosimilar conjugate development. For New Entrants and Emerging Players: Capture emerging photothermal therapy demand from Research Triangle Park academic medical centers, where gold nanorod procurement for glioblastoma pilot programs remains undersupplied relative to California corridor concentration. Target Texas semiconductor fabrication facilities seeking oxidation-resistant conductive inks, leveraging lower operational costs against Northeast incumbent pricing. Lead with rapid surface functionalization turnaround and small-batch flexibility rather than GMP scale, securing technology transfer partnerships with Durham-Chapel Hill offices demanding equity participation. For Investors and Strategic Acquirers: Distressed-cycle entries favor mid-scale GMP synthesis specialists in North Carolina, where state biotechnology center grants reduce capital barriers for manufacturing scale-up and valuation multiples remain compressed relative to Massachusetts comparables. Long-term viability hinges on locked-in supply agreements with Phase II-stage pharmaceutical sponsors, where IND-enabling toxicology investment creates high switching costs. Watch FDA nanotechnology guidance document revisions as the signal for which product formats achieve market access without protracted preclinical timelines, determining which synthesis patent portfolios command premium licensing terms.| Strategic Initiative | Industry Significance |
|---|---|
| GMP Manufacturing Scale-Up | Massachusetts corridor expansion satisfies FDA front-loaded biodistribution study requirements for IND submissions. |
| AI-Guided Surface Functionalization | Machine learning platforms compress protein corona prediction cycles from months to weeks for therapeutic conjugates. |
| Companion Diagnostic Pairing | Simultaneous FDA review pathways create regulatory efficiency for imaging agent and therapeutic payload development. |
| Electron Microscopy Service Bureau Acquisition | Captures FDA-mandated characterization workflows and addresses technician scarcity in quality control functions. |
| Texas and North Carolina Geographic Expansion | Lower operational costs and available specialized workforce pools reduce reliance on saturated Northeast corridors. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, with primary interviews conducted across drug development executives, regulatory affairs leads at pharmaceutical sponsors, GMP manufacturing site directors, and hospital procurement managers specializing in radiology contrast agents. FDA nanotechnology guidance documents, EPA environmental release protocols, OSHA engineered nanomaterial workplace safety guidelines, National Nanotechnology Initiative funding disclosures, and SEC 10-K filings from publicly traded life sciences conglomerates supplied quantitative benchmarks. Bottom-up synthesis capacity assessments and top-down pharmaceutical procurement spend estimates were triangulated against electron microscopy instrument installation records.
Data-stream reconciliation across product type, application, end user, and technology segmentation dimensions produced volume and value outputs across the projection horizon. CAGRs were derived from weighted regression analysis of historical synthesis capacity expansion, pharmaceutical pipeline advancement rates, and regulatory submission velocity. Forecast inputs incorporated gold price volatility scenarios, FDA guidance implementation timelines, and photothermal therapy clinical trial enrollment trajectories.
The model holds under stable precious metal commodity conditions and consistent FDA nanotechnology characterization standards; deviation in gold price spike events or accelerated EPA environmental discharge restrictions would shift manufacturing cost structures and regional facility investment patterns. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Nanoparticle Analysis Market