
 Asia-Pacific Nanocellulose Materials Market | 2026-2036
Asia-Pacific Nanocellulose Materials Market Size, Share, and Industry Trends Forecast 2026-2036
Asia-Pacific Nanocellulose Materials Market Analytics
Modular coating systems that separate barrier layers from structural substrates is realigning procurement patterns across Asia-Pacific packaging supply chains. Nippon Paper Industries Co., Ltd. leverages its integrated pulp-to-nanocellulose pilot infrastructure to anchor premium barrier film supply to Japanese food exporters. Daicel Corporation specializes in cellulose derivative chemistry that extends formulation compatibility for nanocrystalline grades in coating applications. DKS Co. Ltd. competes on consistent batch quality for suspension-based delivery systems sold to regional coating houses.
Asia-Pacific nanocellulose materials comprise cellulose fibers refined to nanometer-scale dimensions, typically 5-20 nanometers in width and several micrometers in length, produced through mechanical fibrillation, acid hydrolysis, or bacterial synthesis processes that yield high aspect-ratio structures with tensile strength exceeding 1 GPa. These materials primarily serve as renewable reinforcing agents, barrier coatings, and rheology modifiers that displace synthetic polymers in packaging and composite formulations. Nanofibrillated cellulose dominates current volume flows due to mature mechanical production pathways and established papermaking integration, while bacterial cellulose commands premium positioning in healthcare wound dressing and electronic substrate applications where ultrafine network purity justifies higher unit economics. The papermaking application segment retains structural importance as a demand floor, though packaging coatings represent the fastest-growing margin pool as brand owners reformulate around fiber-based barrier performance.
Japan's METI enforces technical standards for nanomaterial safety assessment that shape product registration requirements for domestic commercialization, while China's SAMR and GB standards framework governs food-contact material approvals that gate nanocellulose adoption in packaging serving the Chinese market. Australia's TGA and South Korea's MFDS maintain parallel cosmetic and medical device pathways that influence bacterial cellulose market access for healthcare end uses. Stakeholders must monitor divergence between Japanese JIS certification requirements and emerging ASEAN harmonization proposals to anticipate compliance cost structures for cross-border formulation deployment.
Market Dynamics
Japan's METI circular economy roadmaps and China's GB standards for biodegradable materials are mandating petroleum-derived film substitution, forcing packaging converters to reconfigure coating architectures around nanocellulose barrier layers.
Growth Catalysts
- Japan's METI technical standards:Nanomaterial safety assessment protocols accelerate domestic product registration timelines for food-contact applications.
- Flexible food packaging reformulation:Brand owners in Japan's Kanto industrial corridor are specifying nanocellulose barrier coatings to meet export compliance requirements.
- Tsukuba research park clustering:Pulp-to-nanocellulose pilot infrastructure concentration reduces R&D-to-commercialization lead times for regional coating houses.
Market Restraints
- Mechanical fibrillation energy intensity:High-pressure homogenization consumes substantial electricity, compressing margins for nanofibrillated cellulose producers.
- Acid hydrolysis feedstock purity:Bleached kraft pulp quality variability creates batch inconsistency that constrains nanocrystalline grade yields.
- China SAMR food-contact approval timelines:Extended safety dossier review periods delay nanocellulose packaging launches serving the Chinese market.
Strategic Opportunities
- Australia TGA wound dressing pathway:Bacterial cellulose ultrafine network purity positions premium healthcare applications with higher unit economics.
- South Korea MFDS cosmetic substrate demand:Electronic and biomedical device manufacturers are sourcing bacterial cellulose for specialized film applications.
- ASEAN harmonization proposals:Emerging cross-border formulation standards would reduce compliance cost structures for multi-country coating deployment.
Industry Challenges
- JIS certification divergence:Misalignment between Japanese standards and emerging ASEAN frameworks forces duplicate testing protocols for regional suppliers.
- Pilot line scale-up capex:Mechanical fibrillation equipment and cleanroom infrastructure require substantial capital commitment before commercial volume validation.
- Suspension stability formulation expertise:Coating houses face talent scarcity in nanocellulose rheology modification for consistent barrier performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Asia-Pacific Nanocellulose Materials Market |
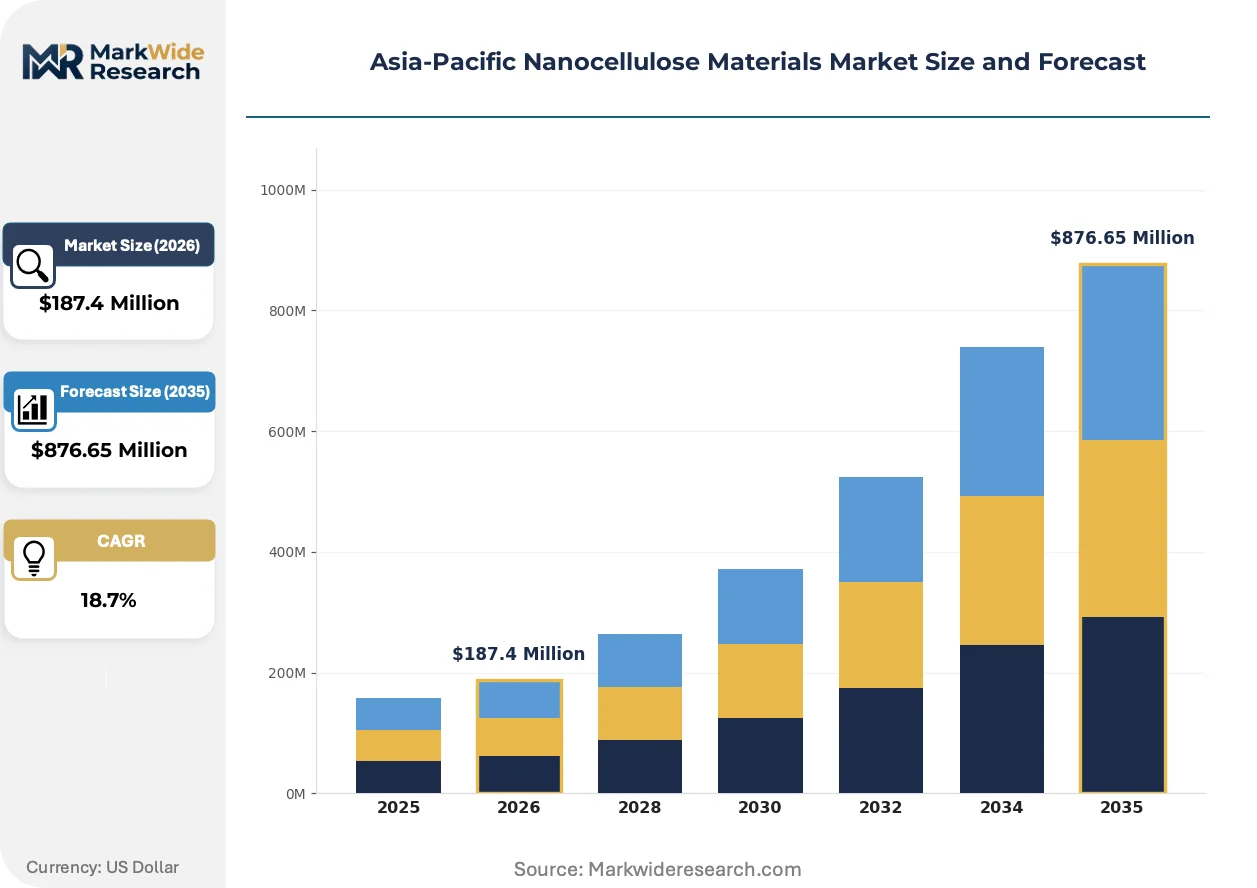
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $876.65 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nanofibrillated Cellulose, Nanocrystalline Cellulose, Bacterial Cellulose, Microfibrillated Cellulose Application: Packaging, Coatings, Composites, Papermaking End User: Food & Beverage, Healthcare, Automotive, Electronics Form: Powder, Suspension, Gel, Fibers |
| Companies Covered | DKS Co. Ltd., Seiko PMC Corporation, Nippon Paper Industries Co., Ltd., Daicel Corporation, GranBio, SAPPI, KAO Corporation, Norske Skog ASA, Oji Holdings Corporation, Others |
| Regions Covered | Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Asia-Pacific Nanocellulose Materials Market Evolving Landscape
Modular coating architectures are separating functional barrier layers from structural substrates, enabling substitution of multi-material laminates with fiber-based mono-material systems.
Enzymatic pretreatment combined with mechanical fibrillation is consolidating production economics for nanofibrillated cellulose. Japanese packaging converters are adopting these hybrid pathways to reduce energy intensity while maintaining aspect ratios above 100:1. This consolidation is compressing capital requirements for mid-scale producers entering the barrier coating supply base.
China's GB standards for biodegradable materials are tightening food-contact safety thresholds for petroleum-derived barriers. Manufacturers serving the Chinese market must reformulate around fiber-based alternatives or exit certified packaging segments. Japanese exporters to China are accelerating nanocellulose coating validation to maintain market access under SAMR enforcement timelines.
Brand owners are consolidating supplier relationships around coating houses with integrated nanocellulose suspension capabilities. Direct technical collaboration between pulp producers and converters is replacing arm's-length material procurement. This pattern concentrates most visibly in Japan's Kanto corridor, where pilot line proximity enables rapid formulation iteration cycles.
Asia-Pacific Nanocellulose Materials Market Segmentation
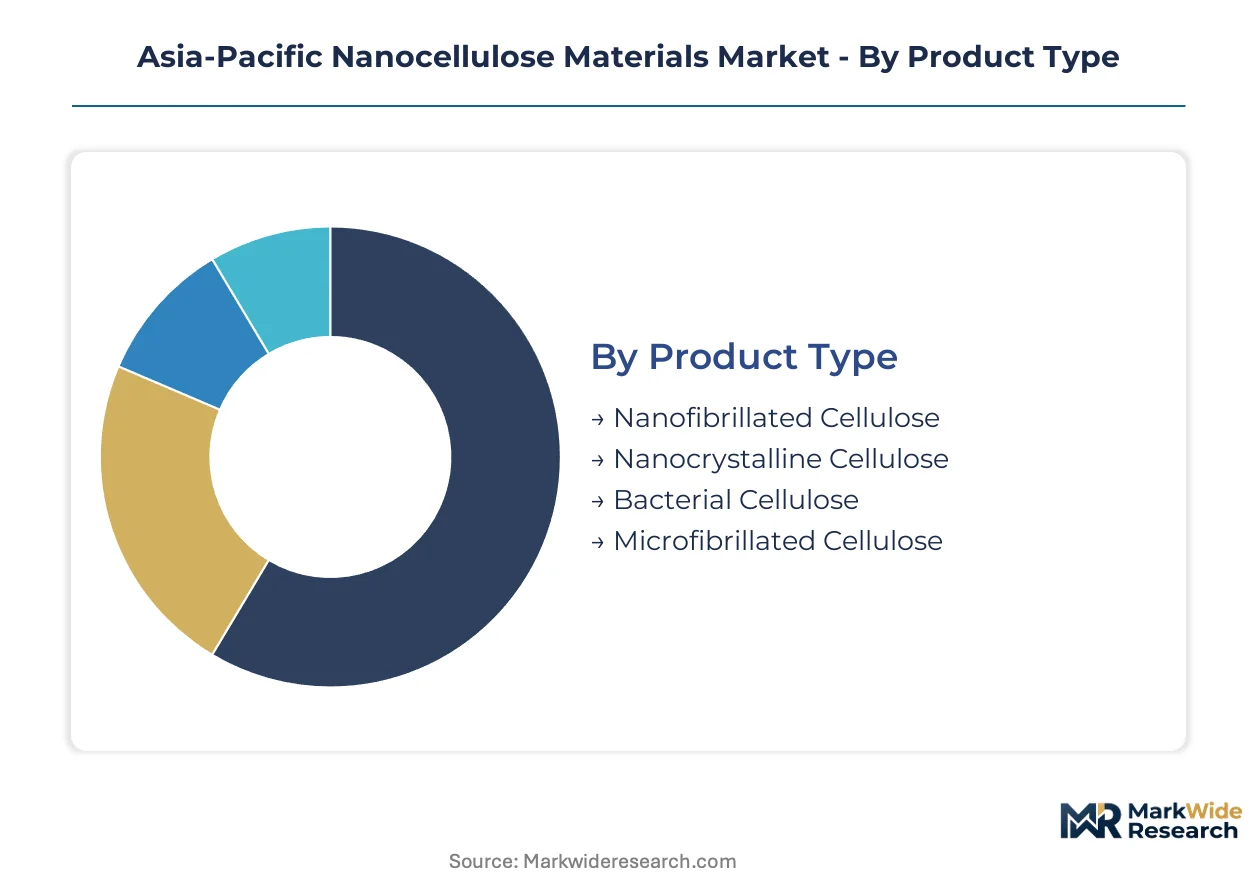
Segmentation in the Asia-Pacific nanocellulose materials market reveals how production pathways, application requirements, and regulatory constraints fragment procurement patterns across Japanese, Chinese, and Australian demand centers. Understanding these divisions exposes where formulation customization commands premium positioning versus where standardized grades achieve volume scale.
Product Type:
The customization-standardization spectrum runs from mechanically refined bulk grades to bacterially synthesized ultra-pure networks, with energy intensity and batch consistency determining which producers capture barrier coating versus healthcare applications.
- Nanofibrillated Cellulose:Mechanical fibrillation of bleached kraft pulp yields high aspect-ratio fibers (5-20nm width, micrometer-scale length) with tensile strength exceeding 1 GPa. Japanese packaging converters in the Kanto corridor specify this grade for food-contact barrier coatings under METI technical standards, though high-pressure homogenization electricity consumption compresses producer margins.
- Bacterial Cellulose:Acetobacter xylinum fermentation produces ultrafine network purity with zero residual lignin or hemicellulose. Australian TGA wound dressing pathways and South Korean MFDS cosmetic substrate approvals concentrate demand in Tsukuba research parks and Seoul satellite facilities where cleanroom infrastructure justifies premium unit economics.
- Nanocrystalline Cellulose:Acid hydrolysis of bleached pulp isolates crystalline domains for rheology modification in coating applications.
- Microfibrillated Cellulose:Lower intensity mechanical refining targets papermaking integration as a direct pulp additive.
Leading the category by volume: Nanofibrillated Cellulose. Growing fastest: Bacterial Cellulose.
Application:
Cost tier stratification separates commodity papermaking additives from performance-driven barrier formulations where petroleum-derived film substitution mandates reshape procurement budgets.
- Packaging:Flexible food packaging reformulation drives the steepest expansion trajectory as China's GB standards for biodegradable materials and Japan's METI circular economy roadmaps force petroleum-derived film substitution. Brand owners specify nanocellulose barrier layers to maintain SAMR food-contact approvals for exports into the Chinese market.
- Papermaking:Wet-end addition of microfibrillated grades retains structural importance as a demand floor across Indonesian and Australian integrated pulp mills, though margin compression limits producer interest.
- Coatings:Modular barrier layer architectures enable mono-material fiber systems to displace multi-material laminates in Japanese export packaging.
- Composites:Automotive and electronics manufacturers trial nanocrystalline grades for lightweight reinforcing applications with inconsistent volume commitment.
Packaging captures the highest value per kilogram. Papermaking absorbs the largest absolute tonnage.
End User:
Customer type fragmentation splits between regulated food-contact applications requiring JIS certification and medical device pathways governed by TGA and MFDS frameworks.
- Food & Beverage:Japanese exporters to China dominate specification activity, accelerating nanocellulose coating validation to meet SAMR enforcement timelines under tightening GB standards for biodegradable materials.
- Healthcare:Bacterial cellulose ultrafine networks command premium positioning in wound dressing and electronic substrate applications where purity justifies higher unit economics under Australian TGA and South Korean MFDS pathways.
- Automotive:Composite reinforcement trials proceed sporadically without consolidated demand commitment.
- Electronics:Specialized film applications source bacterial cellulose for biomedical device substrates in Seoul and Tsukuba research corridors.
Food & Beverage generates the broadest producer participation. Healthcare sustains the highest margins per ton.
Form:
Supply concentration clusters around suspension-based delivery systems where coating houses require integrated rheology modification expertise.
- Suspension:Aqueous nanocellulose dispersions dominate barrier coating applications, with DKS Co. Ltd. and regional Japanese suppliers competing on batch consistency for delivery to Kanto corridor converters.
- Powder:Spray-dried grades target composite and papermaking integration where transportation cost reduction outweighs redispersion energy requirements.
- Gel:Bacterial cellulose pellicles serve healthcare wound dressing applications requiring hydrated network integrity.
- Fibers:Dry-laid mats occupy niche filtration and specialty paper segments with limited Asia-Pacific volume.
Suspension forms anchor coating house procurement. Powder formats are gaining share in composite trials.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production clusters in Japan's Kanto corridor and China's Yangtze River Delta while consumption spreads across export-oriented packaging hubs. Regulatory divergence between METI safety protocols and SAMR approval timelines fragments procurement patterns. Pilot line proximity to research infrastructure determines competitive positioning.
Japan
Food-contact barrier coatings drive specification activity as exporters reformulate for Chinese market access. METI technical standards for nanomaterial safety assessment compress domestic product registration timelines. Tsukuba research parks concentrate pulp-to-nanocellulose pilot infrastructure serving Kanto corridor converters.
China
GB standards for biodegradable materials tighten food-contact safety thresholds for petroleum-derived barriers. SAMR extended safety dossier review periods delay packaging launches despite reformulation urgency. Yangtze River Delta coating houses accelerate nanocellulose validation to maintain certified segment participation.
South Korea
Cosmetic substrate and biomedical device applications concentrate demand for bacterial cellulose ultrafine networks. MFDS medical device pathways govern market access for healthcare wound dressing formulations. Seoul satellite facilities leverage cleanroom infrastructure to justify premium unit economics in specialized film sourcing.
Australia
Wound dressing applications anchor bacterial cellulose demand under TGA therapeutic goods frameworks. Domestic pulp integration remains limited, forcing reliance on imported suspension systems. Research partnerships with Japanese pilot line operators bridge supply gaps for healthcare end users.
Indonesia
Integrated pulp mills absorb microfibrillated grades as wet-end additives in papermaking integration. ASEAN harmonization proposals remain nascent, preserving fragmented national compliance requirements. Java-based facilities experiment with enzymatic pretreatment hybrids to reduce mechanical fibrillation energy intensity.
Asia-Pacific Nanocellulose Materials Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across coating formulation and raw material supply tiers. Market structure tilts toward consolidation around integrated pulp producers with captive nanocellulose streams. Three archetypes dominate: vertically integrated paper conglomerates, cellulose derivative chemists, and suspension-based delivery specialists. Capacity expansion and strategic partnerships represent the dominant competitive moves as firms secure pilot line scale-up capital and coating house relationships.
Among Japan-based operators, Nippon Paper Industries Co., Ltd. and Daicel Corporation exemplify divergent strategic positions within the integrated tier. DKS Co. Ltd. occupies a specialist position in suspension-based delivery systems. These three entities anchor distinct competitive vectors: captive pulp-to-nanocellulose infrastructure, cellulose derivative formulation chemistry, and batch-consistent aqueous dispersion supply.
| Leading Market Players |
|---|
| DKS Co. Ltd. |
| Seiko PMC Corporation |
| Nippon Paper Industries Co., Ltd. |
| Daicel Corporation |
| GranBio |
| SAPPI |
| KAO Corporation |
| Norske Skog ASA |
| Oji Holdings Corporation |
| Others |
Value Network & Pricing Analysis
Formulation chemists clustering in Japan's Kanto corridor and China's Yangtze River Delta create labor-cost differentials that widen spreads between premium bacterial cellulose grades and commodity nanofibrillated alternatives. These regional talent concentrations let Tsukuba-based producers command 40-60% pricing premiums over mid-scale Indonesian operators while coating houses absorb suspension stability expertise as a bundled service cost.
Pricing Analysis
Margin tightening in standard nanofibrillated grades reflects mechanical fibrillation electricity costs that compress producer returns below bacterial cellulose premiums. Three-tier pricing structure across premium, standard, and economy levels separates METI-certified food-contact formulations from industrial papermaking additives and uncertified commodity suspensions. Price differentiation hinges on JIS certification status and batch rheology consistency guarantees. Japanese food exporters show lowest price sensitivity for SAMR-compliant barrier coatings, while Indonesian integrated mills drive hardest volume negotiations for wet-end papermaking integration.
Supply Chain Analysis
Freight cost differentials between aqueous suspension and spray-dried powder formats reshape procurement radii for Australian healthcare end users sourcing from Japanese pilot lines. Supply concentrates in Japan, China, and South Korea, with Tsukuba research parks and Seoul satellite facilities anchoring bacterial cellulose premium production while Yangtze River Delta coating houses absorb nanofibrillated volume. Raw material flows draw from bleached kraft pulp streams, enzymatic pretreatment additives, and cleanroom infrastructure components. Single-source vulnerability around high-pressure homogenization equipment creates bottleneck risk. Distribution runs through integrated pulp producers with captive nanocellulose streams and regional coating house networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Asia-Pacific nanocellulose materials occupy a technology-transition phase where enzymatic-mechanical hybrid production is displacing energy-intensive pure mechanical fibrillation. This substitution is compressing capital barriers for mid-scale entrants while reshaping competitive moats around formulation expertise rather than equipment scale.
For Market Incumbents: Extend pilot line capacity in Tsukuba and Yangtze River Delta corridors to anchor coating house relationships before hybrid pathway commoditization erodes equipment-based differentiation. Deepen backward integration into enzymatic pretreatment chemistry to capture margin compression from electricity cost volatility. METI certification investment remains critical as SAMR approval timelines lengthen for cross-border suppliers.
For New Entrants and Emerging Players: Coating houses with integrated suspension capabilities represent the most penetrable channel partner type for bacterial cellulose premium positioning in Australian TGA and South Korean MFDS pathways. Target healthcare wound dressing and electronic substrate applications where ultrafine network purity justifies unit economics above commodity barrier coatings. Lead with formulation collaboration services rather than raw material supply to bypass incumbent pulp-to-nanocellulose infrastructure advantages.
For Investors and Strategic Acquirers: The window for entry favors cellulose derivative chemists with existing pharmaceutical or food-contact regulatory dossiers that accelerate nanocellulose certification timelines. Long-term viability hinges on positioning for ASEAN harmonization convergence that collapses duplicate JIS-GB testing costs. Watch for SAMR approval acceleration signals as the inflection indicator for Chinese market access premium realization.
| Strategic Initiative | Industry Significance |
|---|---|
| Enzymatic Pretreatment Scale-Up | Reduces mechanical fibrillation energy intensity for Japanese packaging converters. |
| Backward Integration into Pulp Supply | Nippon Paper Industries anchors captive feedstock for barrier coating premium positioning. |
| JIS-GB Dual Certification Investment | Accelerates SAMR approval timelines for Japanese exporters serving Chinese food-contact markets. |
| Coating House Partnership Networks | DKS Co. Ltd. leverages batch consistency reputation to lock Kanto corridor converter relationships. |
| Cleanroom Infrastructure Expansion | Seoul satellite facilities justify bacterial cellulose premium unit economics under MFDS pathways. |
Research Methodology
Trade statistics from Japan's Ministry of Finance, Chinese customs declarations, and Australian therapeutic goods registration databases formed the secondary backbone for volume and trade flow calibration. Primary interviews with nanocellulose plant managers, coating house technical directors, Japanese food exporter procurement leads, and Australian wound dressing formulators validated production cost structures and specification trends. Bottom-up and top-down triangulation reconciled pilot line capacity announcements with end-use demand segmentation across packaging, papermaking, and healthcare applications.
Bottom-up modeling aggregated segment-level consumption patterns by product type, application, and end-user category across the projection horizon. The analytical framework incorporated nanofibrillated versus bacterial cellulose grade tier splits, JIS-certified versus uncertified formulation channels, and regional regulatory cluster divergence between METI, SAMR, TGA, and MFDS pathways. CAGRs derived from elasticity-adjusted substitution rates for petroleum-derived barrier films and enzymatic pathway adoption curves in mechanical fibrillation operations.
Several conditions sit outside the modeled scope, including unannounced ASEAN harmonization treaty ratification, breakthrough acid hydrolysis yield improvements, and raw bleached kraft pulp price shocks beyond historical volatility bands. Forecasts reflect assumptions about SAMR enforcement consistency and METI technical standard stability that stakeholders should weight against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market