
 Global Nano Calcium Carbonate Market | 2026-2036
Global Nano Calcium Carbonate Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nano Calcium Carbonate Market Intelligence
New production capacity from Chinese producers is rebalancing the supply landscape historically dominated by European and American firms. Imerys leverages its extensive mineral portfolio to serve high-value applications globally. Omya Group competes on the basis of its large-scale manufacturing and logistics network. Meanwhile, specialists like Changzhou Calcium Carbonate Co., Ltd. focus on specific grades for the regional electronics and polymer industries.
Nano calcium carbonate consists of particles with a diameter typically below 100 nanometers, offering unique rheological and mechanical properties. It is primarily manufactured as precipitated calcium carbonate (PCC) to achieve precise particle size and morphology control. The precipitated product type therefore commands the market for high-performance uses. Applications in plastics and adhesives & sealants represent the largest volume segments, where the material acts as a reinforcing filler and viscosity modifier.
Market access and product formulation are governed by a complex web of chemical regulations. In Europe, materials must comply with REACH and ECHA guidelines for nanomaterials. The US FDA sets standards for its use in food-contact polymers, while China's GB standards dictate quality for industrial applications. Future success depends on vendors' ability to navigate these divergent regional compliance requirements while developing functionalized grades.
Market Dynamics
The central structural force is the geographic shift in production gravity towards China, which is reordering global supply chains. This concentration creates new pricing dynamics and logistical considerations for buyers in Europe and North America accustomed to regional supply networks.
Growth Catalysts
- Automotive Lightweighting:Stricter fuel economy mandates under frameworks like the EU Green Deal compel automakers to use more plastics, where nano calcium carbonate acts as a reinforcing agent to reduce component weight without compromising strength.
- Construction Sector Expansion:Growth in residential and commercial construction, particularly in South and Southeast Asia, drives demand for high-performance adhesives, sealants, and coatings that utilize the material for rheology control and improved durability.
- Advanced Polymer Demand:China's vast electronics and polymer manufacturing industries create a significant, localized demand pull for specialized nano-grades that enhance the properties of plastics used in consumer goods and industrial components.
Market Restraints
- Production Cost Structure:The precipitated calcium carbonate (PCC) manufacturing process is energy-intensive, resulting in a higher cost basis compared to conventional ground calcium carbonate (GCC), which limits its application in price-sensitive segments.
- Regulatory Fragmentation:Divergent nanomaterial regulations, such as Europe's REACH framework versus the US FDA's standards for food-contact materials, create significant compliance hurdles and increase the cost of global market access for producers.
- Dispersion and Agglomeration:The inherent tendency of nanoparticles to agglomerate poses technical challenges for end-users, often requiring specialized dispersion equipment and surface-treated grades that add complexity and cost to formulation.
Strategic Opportunities
- Biomedical Applications:The development of nano calcium carbonate for use in drug delivery systems and biocompatible bone graft composites offers a high-value opportunity, leveraging the material's unique properties for advanced medical technologies.
- Functionalized Grades:Creating surface-modified or functionalized nano-grades for specific applications, such as improving the barrier properties of packaging films or the fire retardancy of plastics, opens new performance-driven markets.
- Underpenetrated Geographies:Market expansion in Latin America and the Middle East, where industrialization and infrastructure investment are accelerating, presents an opportunity to supply emerging manufacturing sectors with advanced material additives.
Industry Challenges
- Harmonization of Standards:A lack of globally accepted standards for characterizing nanoparticles, including size distribution and surface chemistry, creates ambiguity in product specifications and makes direct comparison between suppliers difficult for purchasers.
- Capital Investment Hurdles:The high capital expenditure required to construct and operate a PCC plant with the necessary controls for producing consistent, high-purity nano-scale particles acts as a significant barrier to entry.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nano Calcium Carbonate Market |
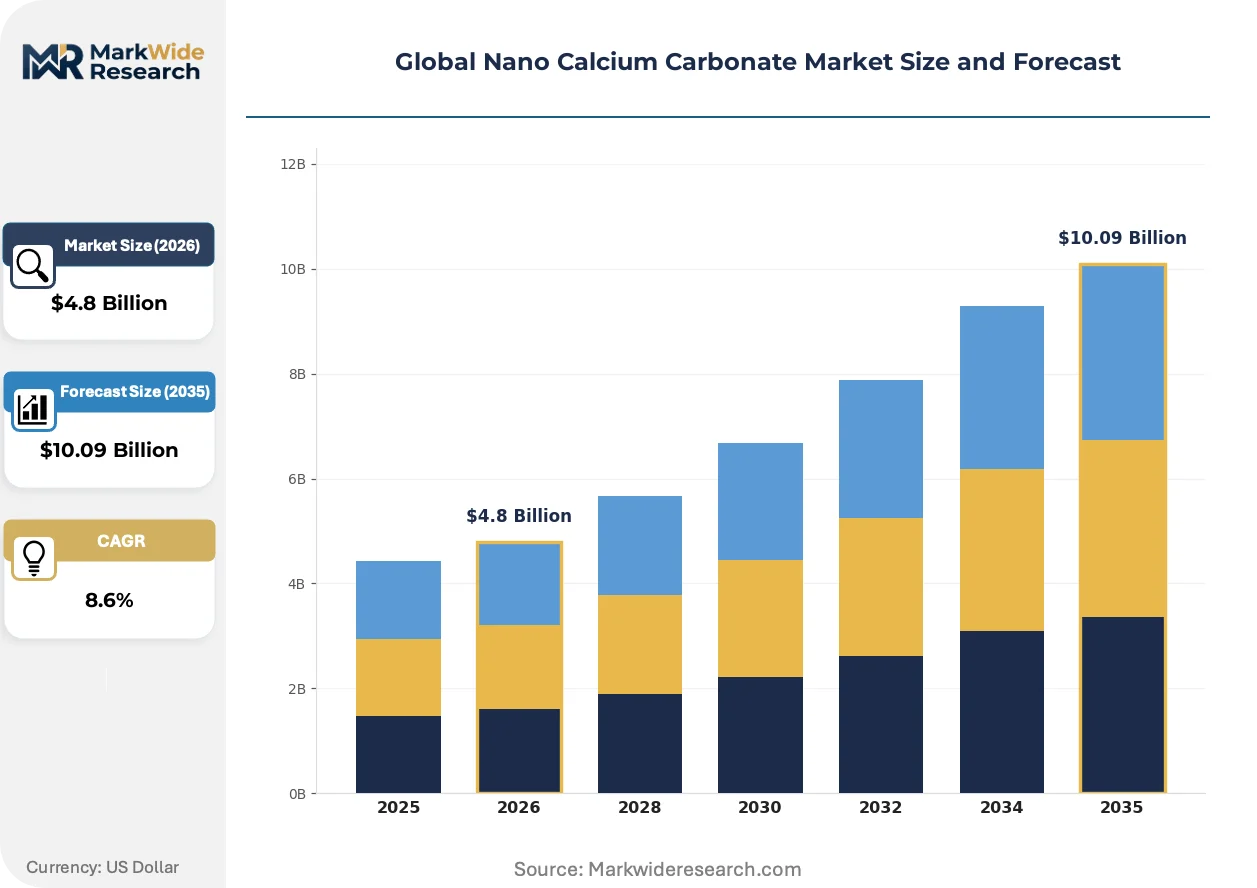
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $10.09 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Precipitated, Ground, Coated, Uncoated, Functionalized Application: Plastics, Paints & Coatings, Adhesives & Sealants, Paper & Packaging, Personal Care End Use Industry: Packaging Manufacturers, Construction Material Producers, Cosmetics Producers, Electronics Manufacturers, Agricultural Suppliers Form: Powder, Granules, Slurry, Pellets, Liquid Dispersion |
| Companies Covered | Minerals Technologies Inc., Evonik Industries AG, Changzhou Calcium Carbonate Co., Ltd., Shiraishi Group, J.M. Huber Corporation, Imerys, Maruo Calcium Co., Ltd., Fujian Sanmu Nano Calcium Carbonate Co., Ltd., Omya Group, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nano Calcium Carbonate Market Strategic Shifts & Innovations
Material science innovation is focused on enhancing particle functionality to meet specific end-use performance requirements. This drive for tailored properties is occurring within an increasingly stringent global regulatory environment for nanomaterials, pushing producers toward greater transparency and documentation.
Surface modification is a critical technology that applies specialized coatings, such as fatty acids, to nano calcium carbonate particles to improve their compatibility and dispersion within polymer matrices. The automotive plastics and advanced packaging industries are primary adopters of these functionalized grades. This development is modularizing the supply chain, enabling compounders to select specific surface chemistries to achieve target properties without deep in-house expertise in nanoparticle synthesis.
The European Chemicals Agency (ECHA) enforces stringent registration and data requirements for nanomaterials under the REACH regulation. This policy compels manufacturers to provide extensive characterization data and toxicological assessments, elevating the barrier to entry into the European market. The adhesives and sealants segment is most impacted, with formulators increasingly sourcing from suppliers who can provide comprehensive, REACH-compliant documentation for their nano-grade additives.
End-users in high-performance verticals are shifting from purchasing based on simple material specifications to performance-based procurement. This change disrupts the traditional commodity sales model, creating an advantage for suppliers capable of offering application development support and co-formulating solutions. The trend is most prominent in the North American aerospace and electronics sectors, where buyers specify final component characteristics like thermal stability or dielectric properties.
Global Nano Calcium Carbonate Market Segmentation
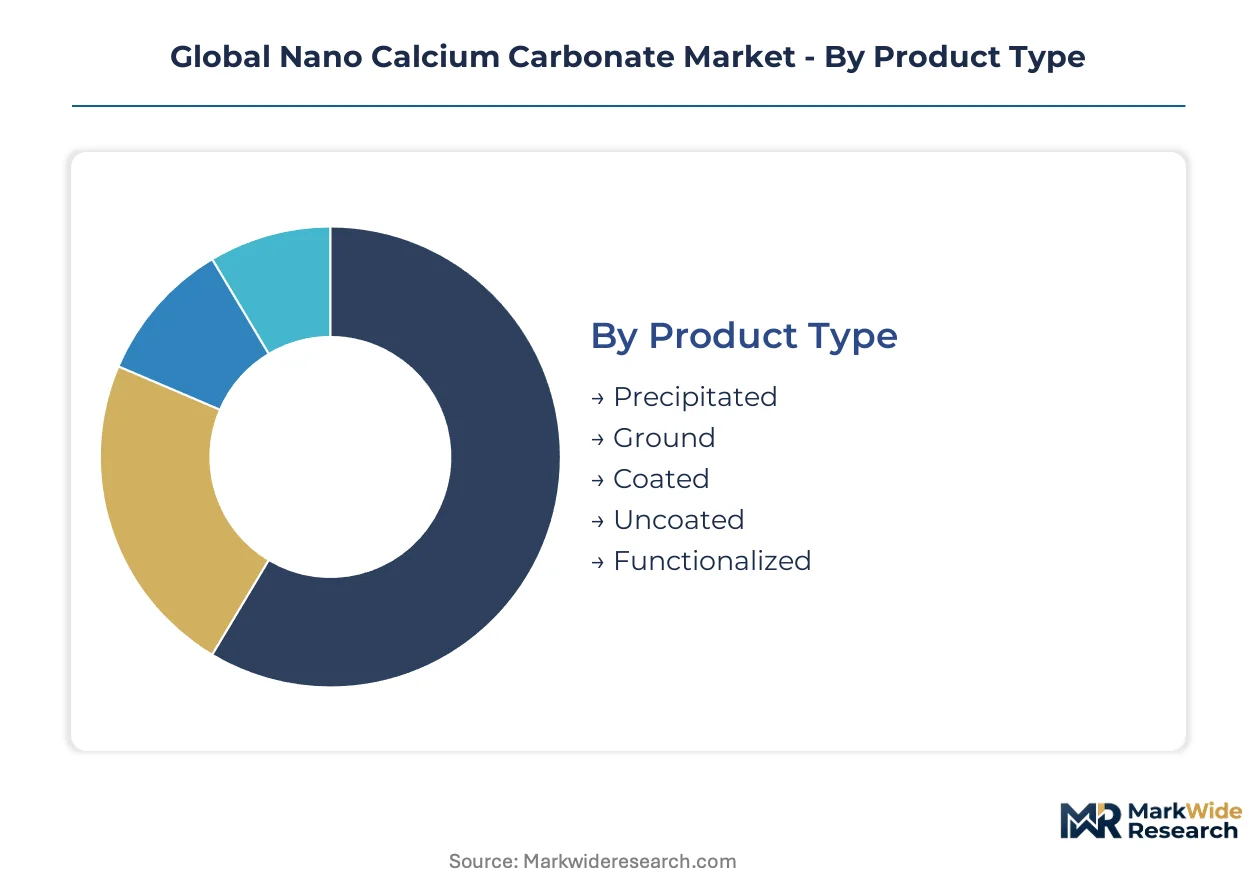
The global nano calcium carbonate market segments reflect diverse product characteristics and specialized end-use requirements. Understanding these distinctions is critical for vendors to tailor product offerings and navigate complex regulatory landscapes across different application areas.
Product Type:
Certain product types face stringent certification burdens, with functionalized and precipitated grades requiring extensive documentation under frameworks like Europe's REACH and the US FDA's food-contact material standards.
- Precipitated:This product type is manufactured to achieve precise particle size and morphology control, making it suitable for high-performance applications. It commands the market for high-performance uses where specific rheological and mechanical properties are essential.
- Functionalized:These grades incorporate specialized surface coatings, such as fatty acids, to enhance compatibility and dispersion within polymer matrices. Automotive plastics and advanced packaging industries are primary adopters of these tailored materials.
- Ground:Ground calcium carbonate (GCC) is produced by mechanical grinding, resulting in larger, more irregular particles compared to precipitated forms. It offers a cost-effective filler solution for less demanding applications.
- Coated:Coated nano calcium carbonate features a surface treatment to improve dispersion and reduce agglomeration in various matrices. This modification enhances material integration and performance in composite formulations.
- Uncoated:Uncoated nano calcium carbonate represents the basic form, offering fundamental reinforcing and viscosity modifying properties. It finds use in applications where advanced surface compatibility is not the primary requirement.
Leading the category by volume: Precipitated. Growing fastest: Functionalized.
Application:
Application segments differentiate by how nano calcium carbonate's unique properties, such as reinforcing capabilities or rheology control, are leveraged within specific material systems.
- Plastics:Nano calcium carbonate acts as a reinforcing filler in plastics, reducing component weight for automotive parts without compromising strength. Stricter fuel economy mandates under frameworks like the EU Green Deal compel automakers to integrate these materials.
- Adhesives & Sealants:The material provides rheology control and improved durability in high-performance adhesives and sealants. Growth in residential and commercial construction, particularly in South and Southeast Asia, drives demand for these formulations.
- Paints & Coatings:In paints and coatings, nano calcium carbonate functions as an extender and rheology modifier, enhancing film properties and reducing material costs. It contributes to improved scrub resistance and opacity in architectural and industrial finishes.
- Paper & Packaging:Nano calcium carbonate improves paper brightness, opacity, and printability while reducing pulp consumption. Advanced packaging films utilize functionalized grades for enhanced barrier properties.
- Personal Care:The material serves as a mild abrasive, opacifier, and rheology modifier in personal care products like toothpaste and cosmetics. It helps achieve desired textures and product stability.
These applications collectively influence the material's performance profile, with plastics and adhesives demanding the most tailored solutions.
End Use Industry:
End-use industries dictate the scale and technical specifications for nano calcium carbonate, with each sector presenting distinct demand characteristics and supply chain requirements.
- Electronics Manufacturers:China's vast electronics manufacturing sector creates a significant, localized demand pull for specialized nano-grades. These materials enhance the properties of plastics used in consumer goods and industrial components.
- Construction Material Producers:This industry requires nano calcium carbonate for high-performance adhesives, sealants, and coatings used in residential and commercial construction. Improved durability and rheology control are key benefits for these applications.
- Packaging Manufacturers:Nano calcium carbonate improves the mechanical strength and barrier properties of packaging films and containers. The shift towards lightweight and sustainable packaging drives demand in this sector.
- Cosmetics Producers:Cosmetics producers utilize nano calcium carbonate as a filler, opacifier, and texture enhancer in various formulations. Product stability and sensory attributes are key considerations for this industry.
- Agricultural Suppliers:In agriculture, nano calcium carbonate can be used as a soil amendment or as a carrier for active ingredients. It contributes to soil health and nutrient delivery in specific crop applications.
The electronics and construction sectors represent the largest regional consumption hubs for advanced nano calcium carbonate grades.
Form:
The form in which nano calcium carbonate is supplied directly impacts handling, dispersion, and integration into end-user formulations, influencing logistical considerations and processing complexity.
- Powder:The powder form is a common and versatile delivery method, requiring specialized dispersion equipment for optimal integration into matrices. It offers flexibility for diverse formulation needs across industries.
- Liquid Dispersion:This form addresses the inherent tendency of nanoparticles to agglomerate, providing easier integration for end-users. Liquid dispersions simplify processing steps and ensure consistent performance in applications.
- Granules:Granular forms offer improved handling characteristics and reduced dust generation compared to fine powders. They are often preferred in processes requiring automated feeding and reduced airborne particle exposure.
- Slurry:Slurry forms provide a pre-dispersed solution, often used in high-volume applications like paper manufacturing. This form minimizes on-site dispersion challenges for large-scale industrial users.
- Pellets:Pelleted nano calcium carbonate is particularly useful for direct compounding into polymer melts, reducing dust and improving material flow. This form streamlines manufacturing for plastics producers.
Ease of handling and integration drives preferences across these forms, with liquid dispersions gaining significant traction for high-performance applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's extensive mineral resources and manufacturing capabilities anchor the global nano calcium carbonate market, driving both production and consumption. This geographic concentration influences supply chain dynamics worldwide. Regional demand variations reflect diverse industrial applications and regulatory frameworks.
China
China's vast electronics and polymer manufacturing sectors create significant localized demand for specialized nano-grades. The country's GB standards dictate quality for industrial applications, ensuring product consistency. Manufacturing hubs like the Yangtze River Delta actively develop advanced material additives for domestic and export markets.
Germany
German automotive manufacturers increasingly demand nano calcium carbonate for lightweighting components, driven by EU Green Deal mandates. Materials must comply with stringent ECHA and REACH guidelines for nanomaterials within the European Union. Industrial clusters in Bavaria focus on advanced polymer compounding for electric vehicles.
United States
United States aerospace and electronics sectors require high-performance nano calcium carbonate for specialized component characteristics. The US FDA sets strict standards for its use in food-contact polymers, influencing product formulation. Research and development centers in California drive innovation for functionalized grades.
India
India's rapidly expanding construction sector fuels demand for high-performance adhesives, sealants, and coatings. The Bureau of Indian Standards (BIS) guides quality for industrial materials within the country. Industrial zones in Maharashtra exhibit robust growth in polymer processing and packaging applications.
Global Nano Calcium Carbonate Market Key Industry Players
Established producers occupy the standard tier; emerging entrants pursue high-value functionalized grades and specialized applications. The market structure exhibits a blend of large, diversified mineral companies and specialized nano-material producers. Key strategic archetypes include integrated raw material suppliers, application-focused formulators, and regional specialists. Companies engage in capacity expansion and strategic partnerships to strengthen their market presence.
At the scale-driven end, Omya Group exemplifies global manufacturing and logistics capabilities, leveraging its extensive network to serve diverse industrial sectors efficiently. This archetype focuses on broad market access and consistent supply across various regions. Imerys, with its extensive mineral portfolio, represents a large-scale integrated supplier focusing on high-value applications and specialized formulations across global markets. This strategy allows for tailored solutions in demanding performance segments. Meanwhile, Changzhou Calcium Carbonate Co., Ltd., a Chinese specialist, occupies a position focused on specific grades for the regional electronics and polymer industries, particularly within the rapidly expanding Asian market. Such regional specialists often excel in meeting localized demand for advanced materials.
| Leading Market Players |
|---|
| Minerals Technologies Inc. |
| Evonik Industries AG |
| Changzhou Calcium Carbonate Co., Ltd. |
| Shiraishi Group |
| J.M. Huber Corporation |
| Imerys |
| Maruo Calcium Co., Ltd. |
| Fujian Sanmu Nano Calcium Carbonate Co., Ltd. |
| Omya Group |
| Others |
Cost & Logistics Intelligence
Vertical integration into raw material sourcing anchors supply position, influencing pricing power for nano calcium carbonate producers. This integration helps manage volatile input costs while stabilizing pricing for downstream polymer and electronics manufacturers.
Pricing Analysis
Service-level agreements and application development support are often bundled with specialized nano calcium carbonate grades, differentiating offerings beyond mere material cost. The dominant pricing structure involves contract-based long-term offtake for high-volume applications and transactional pricing for niche functionalized grades. Price differentiation stems from precise particle morphology control, regulatory compliance certifications like REACH, and regional logistical costs. Pricing softness emerges from increased production capacity in China, particularly for standard grades, while buyers in construction exhibit higher price sensitivity than aerospace and electronics manufacturers.
Supply Chain Analysis
Single-source vulnerability sits with specialized precipitated calcium carbonate (PCC) producers, particularly those with advanced functionalization capabilities. Geographic supply concentrates significantly in China and Germany, influencing global availability. The supply chain relies on consistent access to high-purity limestone and stable energy for PCC manufacturing. Regulatory fragmentation, like divergent REACH and FDA standards, poses a structural risk for global market access, with distribution running through direct sales for major OEMs and specialized chemical distributors for smaller formulators.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global nano calcium carbonate market is navigating a technology-transition phase, where advanced functionalized grades are displacing conventional ground calcium carbonate in high-performance applications. This shift prioritizes material science innovation and application-specific performance over basic filler properties.
For Market Incumbents: Hedge against margin erosion from emerging Chinese competitors by investing heavily in R&D for next-generation functionalized grades. Incumbents should also pursue targeted capacity expansion in regulated markets like Europe and North America, coupled with robust certification investment (e.g., REACH compliance). Offering comprehensive application development support helps differentiate from price-focused entrants. This strategy mitigates the threat from commoditization of standard nano grades.
For New Entrants and Emerging Players: Capture white-space opportunities by focusing on high-value, specialized applications such as biomedical composites or advanced packaging films. New entrants can penetrate under-served geographies like Latin America and the Middle East, leveraging accelerating industrialization. A strong go-to-market angle involves offering performance-based solutions and co-formulation partnerships to address specific end-user challenges. This approach avoids direct competition with established players in commoditized segments.
For Investors and Strategic Acquirers: Exit pathways concentrate in mid-cap specialists possessing strong intellectual property in functionalized grades or regional leaders with robust logistics networks. The long-term viability of the nano calcium carbonate market remains favorable over the next 5-10 years, driven by sustained demand from automotive lightweighting and advanced polymer industries. Acquisition targets should demonstrate proven compliance with stringent regional regulations like REACH or FDA. A critical signal to watch is any progress towards harmonization of global nanomaterial characterization standards.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion in China | This move addresses growing localized demand from electronics manufacturers and strengthens global supply chain influence. |
| Functionalized Grade R&D | Developing surface-modified particles enhances performance in automotive plastics and advanced packaging applications. |
| REACH and FDA Certification | Achieving compliance enables market access to stringent European and US food-contact polymer segments. |
| Strategic Co-development Partnerships | Collaborating with major polymer compounders accelerates adoption of tailored nano calcium carbonate solutions. |
| Market Entry in Latin America | This expands reach into emerging industrial sectors with increasing demand for material additives. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs for this analysis, complemented by primary interviews. We engaged polymer R&D directors, procurement leads at automotive OEMs, chemical plant managers, and regulatory affairs specialists. Secondary validation involved ECHA reports, FDA guidance documents, and national chemical industry association publications. A rigorous bottom-up and top-down triangulation approach ensured data consistency and accuracy.
Data-stream reconciliation integrated historical trends with projected market dynamics across the analysis window. The analytical framework modeled segmentation by product type, application, end-use industry, form, and regional regulatory compliance. CAGRs derived from supply-side capacity additions and demand-side consumption patterns. Key forecast inputs included global automotive production forecasts and construction spending trends in South and Southeast Asia.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to evolving regulatory shifts and raw material price volatility. Forecasts reflect assumptions regarding technological advancements and geopolitical trade policies. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanochemicals Market
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Magnesium Oxide Nanoparticle Market