
 Advanced Nanomaterials Market | 2026-2036
Advanced Nanomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Advanced Nanomaterials Market Outlook
South Korean materials producers is pivoting toward high-purity carbon nanotube capacity to serve domestic semiconductor packaging demand. Arkema leverages its fluoropolymer expertise to anchor European supply chains for specialty nanocoatings. Sumitomo Metal Mining sustains integrated refining operations that control rare-earth nanocrystal feedstock quality from mine to powder. OCSiAl competes through single-wall carbon nanotube synthesis scale that differentiates it from multi-wall commodity suppliers.
Advanced nanomaterials are engineered structures with at least one dimension between 1 and 100 nanometers, typically produced via chemical vapor deposition, sol-gel processing, or mechanical milling to achieve surface-area-to-volume ratios exceeding 100 square meters per gram for catalytic and conductive applications. Carbon nanotubes dominate current revenue pools due to established conductivity enhancement in aerospace wiring and energy storage electrodes, while nanocrystals represent the fastest-expanding category as quantum-dot display manufacturers tighten color-gamut specifications. Nanocomposites command premium pricing in automotive crash structures where clay-polymer layering delivers impact resistance without weight penalties.
EPA oversees pre-manufacture notification under TSCA Section 5 for novel nanoscale substances, while REACH mandates registration dossiers with nanospecific characterization data across EU member states, and South Korea's MFDS enforces biocompatibility protocols for nanomaterials entering medical device supply chains. These frameworks elevate compliance costs for new entrants but protect incumbent producers with established toxicology portfolios. Stakeholders must monitor evolving classification criteria that could reassign multi-functional nanomaterials across regulatory jurisdictions.
Market Dynamics
Semiconductor packaging architectures are driving nanomaterial specification divergence, as South Korean foundries and Japanese integrators impose distinct purity thresholds that fragment supplier qualification pathways and compress batch-to-batch tolerance windows.
Growth Catalysts
- Carbon nanotube conductivity specifications:Aerospace wiring harness manufacturers and energy storage electrode producers are tightening electrical performance requirements that favor single-wall structures over multi-wall alternatives.
- REACH nanospecific characterization mandates:Registration dossiers across EU member states are elevating analytical rigor that protects incumbent producers with established toxicology portfolios.
- South Korean semiconductor packaging demand:Domestic materials producers are pivoting toward high-purity carbon nanotube capacity to serve foundry procurement concentrated in East Asian manufacturing clusters.
Market Restraints
- Rare-earth nanocrystal feedstock concentration:Integrated refining operations controlling mine-to-powder quality are concentrated among limited suppliers, creating single-source vulnerability for quantum-dot display manufacturers.
- EPA TSCA Section 5 notification costs:Pre-manufacture review timelines for novel nanoscale substances extend commercialization pathways for new entrants lacking established regulatory relationships.
- Clay-polymer nanocomposite processing complexity:Layering precision requirements for automotive crash structures demand capital-intensive extrusion equipment that limits supplier participation.
Strategic Opportunities
- Quantum-dot display color-gamut tightening:Nanocrystal specification evolution represents the fastest-expanding category as manufacturers differentiate through visual performance metrics.
- Japanese electronics integrator qualification pathways:Underpenetrated supplier relationships with precision coating specialists offer entry points for fluoropolymer-anchored European producers.
- Biocompatibility protocol convergence:South Korea's MFDS medical device frameworks are creating harmonization pressure that simplifies multi-jurisdictional registration for prepared suppliers.
Industry Challenges
- Surface-area-to-volume ratio certification:Analytical method standardization across chemical vapor deposition and sol-gel processing routes remains incomplete, delaying batch release timelines.
- Multi-functional nanomaterial classification ambiguity:Evolving jurisdictional criteria threaten to reassign products across regulatory frameworks, forcing redundant compliance investment.
- Mechanical milling scale-up reproducibility:Achieving consistent 100+ square meter per gram surface areas at production volumes requires process engineering expertise concentrated among limited technical workforces.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Advanced Nanomaterials Market |
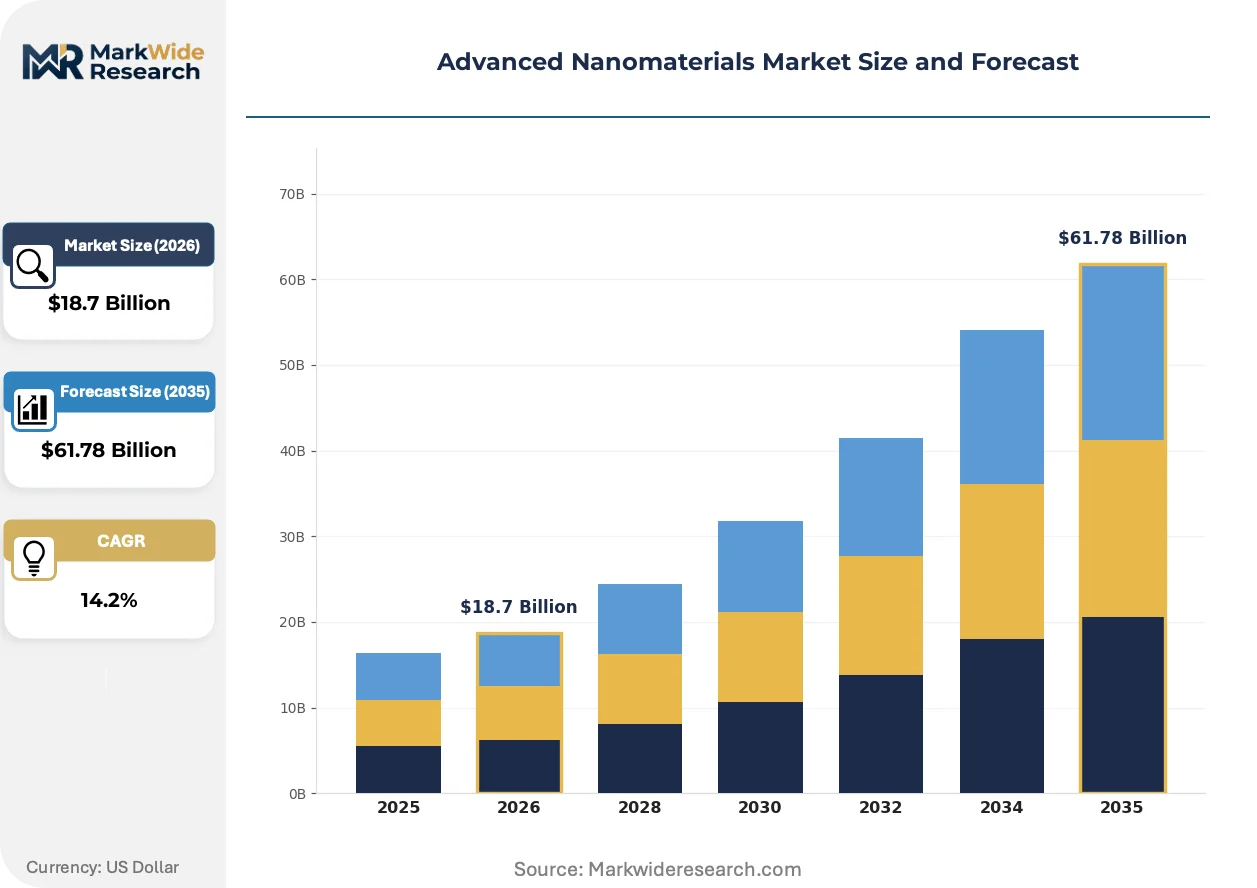
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Nanotubes, Nanocrystals, Nanocomposites, Nanoclays Application: Aerospace, Electronics, Energy Storage, Coatings End User: Automotive Manufacturers, Electronics Firms, Energy Sector, Healthcare Providers Delivery Mode: Direct Supply, Bulk Orders, Online Portals, Retail Distribution |
| Companies Covered | Arkema, Sumitomo Metal Mining, Merck KGaA, OCSiAl, Nanosys, Evonik Industries, Cabot Corporation, Advanced Nano Products, DuPont de Nemours, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Advanced Nanomaterials Market Strategic Shifts
Sol-gel synthesis protocols are fragmenting established supply relationships as buyers develop in-house nanomaterial production capabilities that bypass traditional merchant supplier channels.
Single-wall carbon nanotube purification is decentralizing conductive additive procurement for lithium-ion battery electrodes. Korean cell manufacturers are internalizing plasma-enhanced chemical vapor deposition systems that previously relied on OCSiAl and comparable merchant suppliers. This captive production trend compresses spot market volumes while elevating technical service requirements for remaining external suppliers.
REACH nanospecific annex revisions are redefiling characterization obligations for imported nanomaterial batches. ECHA guidance updates mandate expanded particle-size distribution data and surface chemistry documentation that extends registration preparation timelines. European nanocoating applicators are consolidating supplier bases to reduce qualification burden, favoring Arkema and comparable incumbents with established dossier libraries.
Japanese automotive tier-one suppliers are unbundling nanocomposite compound formulation from raw nanoclay procurement. Direct relationships with domestic clay producers are displacing merchant masterbatch intermediaries that previously controlled formulation intellectual property. This channel disintermediation concentrates in Osaka-Nagoya manufacturing corridors where crash-structure specification authority resides with vehicle assemblers rather than subsystem suppliers.
Advanced Nanomaterials Market Segmentation
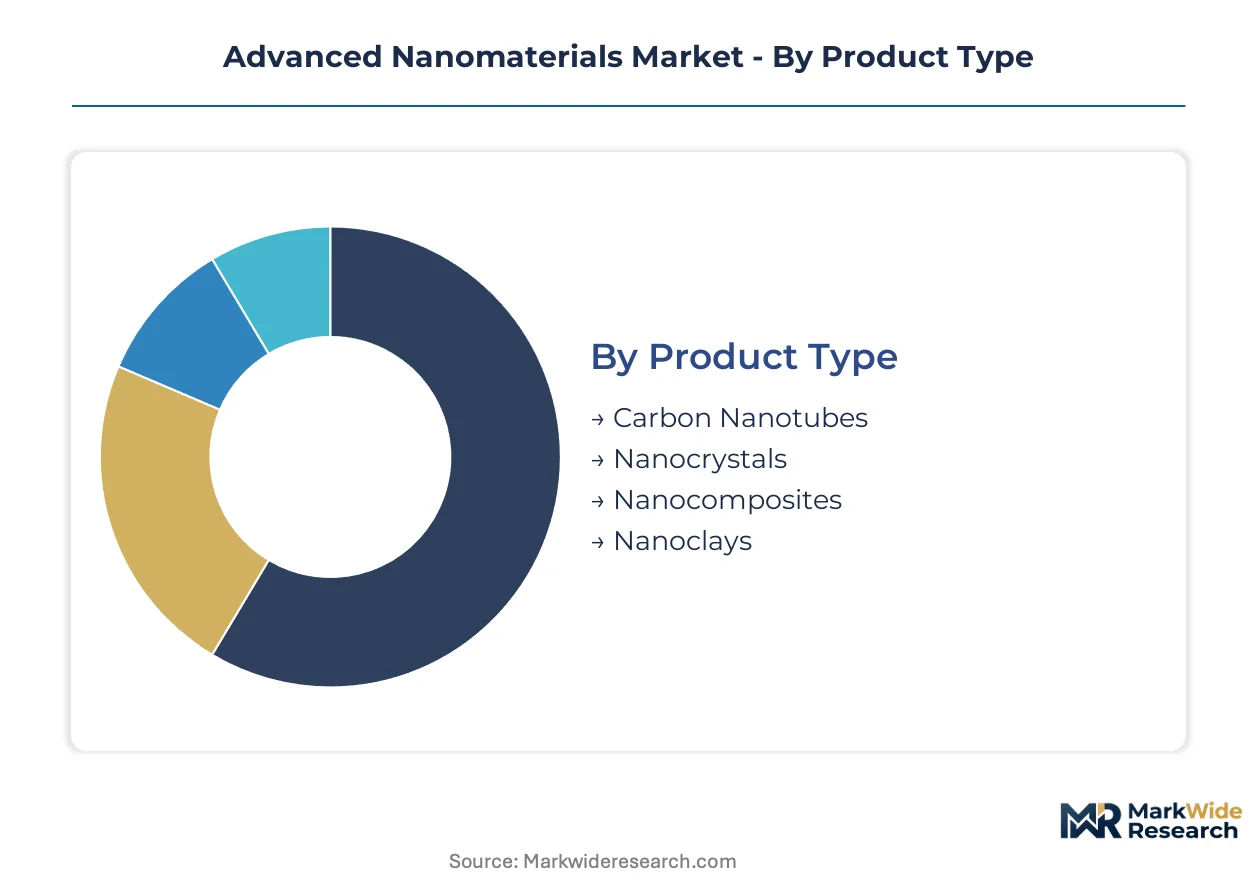
Segmentation in advanced nanomaterials reveals how specification divergence across semiconductor packaging, aerospace wiring, and quantum-dot displays fragments procurement pathways. Suppliers must navigate distinct purity thresholds, conductivity requirements, and regulatory dossier demands that vary sharply by product category and end-use.
Product Type:
Customization intensity spans from commodity multi-wall carbon nanotubes to highly specified single-wall structures and quantum-dot nanocrystals with tight size distributions.
- Carbon Nanotubes:Single-wall structures deliver superior conductivity for lithium-ion battery electrodes and aerospace wiring harnesses. South Korean foundries are tightening procurement specifications that favor high-purity grades over multi-wall alternatives for semiconductor packaging applications.
- Nanocrystals:Quantum-dot formulations with precise 1-10 nanometer dimensions enable display manufacturers to achieve expanded color gamuts. Japanese electronics integrators are driving the steepest specification evolution in this category as visual performance metrics become primary competitive differentiators.
- Nanocomposites:Clay-polymer layering systems deliver impact resistance without weight penalties for automotive crash structures.
- Nanoclays:Platelet structures with high aspect ratios enhance barrier properties in packaging and coating applications.
Leading the category by volume: Carbon Nanotubes. Expanding most quickly: Nanocrystals.
Application:
Cost tier stratification separates premium-qualified aerospace and semiconductor applications from volume-driven energy storage and industrial coatings.
- Aerospace:Wiring harness manufacturers demand single-wall carbon nanotube conductivity enhancement meeting FAA certification pathways. OEMs concentrate procurement among suppliers with established toxicology portfolios that satisfy EPA TSCA Section 5 notification requirements.
- Electronics:Quantum-dot display manufacturing tightens color-gamut specifications fastest among all application areas. South Korean and Japanese integrators impose distinct purity thresholds that fragment supplier qualification pathways.
- Energy Storage:Lithium-ion battery electrode producers are internalizing plasma-enhanced chemical vapor deposition systems, compressing spot market volumes for merchant suppliers.
- Coatings:Fluoropolymer-anchored nanocoatings serve European REACH compliance requirements with established registration dossiers.
Highest margin concentration: Aerospace and Electronics. Volume scaling fastest: Energy Storage.
End User:
Customer type determines regulatory burden intensity, from automotive OEMs navigating NHTSA crash standards to healthcare providers facing biocompatibility protocols.
- Automotive Manufacturers:Tier-one suppliers in Osaka-Nagoya corridors are unbundling nanocomposite formulation from raw nanoclay procurement, disintermediating merchant masterbatch intermediaries. Direct relationships with domestic clay producers now control crash-structure intellectual property.
- Electronics Firms:Display and semiconductor integrators drive the most demanding specification evolution. East Asian manufacturing clusters concentrate procurement authority with foundries and precision coating specialists.
- Energy Sector:Battery cell manufacturers are pivoting toward captive nanotube production capabilities.
- Healthcare Providers:South Korea's MFDS enforces biocompatibility protocols for nanomaterials entering medical device supply chains, creating harmonization pressure across jurisdictions.
Specification authority most concentrated: Electronics Firms. Regulatory compliance burden heaviest: Healthcare Providers.
Delivery Mode:
Supply chain configuration separates direct technical partnerships for qualified grades from transactional channels for standardized materials.
- Direct Supply:Technical service-intensive relationships dominate for single-wall carbon nanotubes and quantum-dot nanocrystals requiring batch-specific certification. Arkema and comparable incumbents leverage established dossier libraries to secure preferred supplier status.
- Bulk Orders:Volume contracting serves energy storage electrode producers with multi-wall carbon nanotube requirements, though captive production trends compress merchant market opportunities.
- Online Portals:Standardized nanoclays and commodity nanocomposites move through digital procurement channels with reduced qualification overhead.
- Retail Distribution:Limited to research-grade materials and small-batch specialty formulations for academic and pilot-scale buyers.
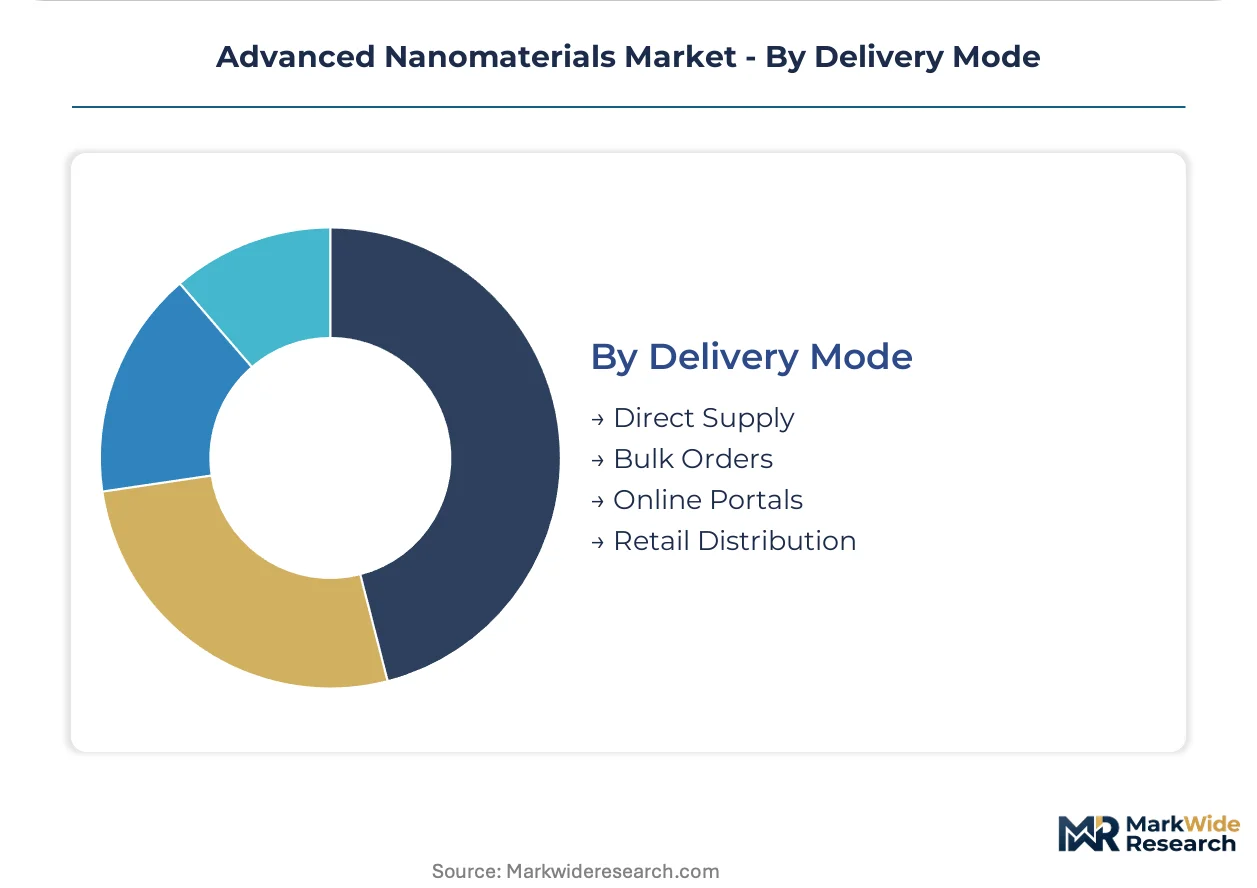
Revenue concentration highest: Direct Supply. Channel growth fastest: Bulk Orders shifting to captive supply.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Rare-earth nanocrystal feedstock quality hinges on integrated refining operations concentrated in select mining jurisdictions. Carbon nanotube synthesis scale and semiconductor packaging demand anchor production decisions across East Asian manufacturing clusters.
United States
Aerospace wiring harness manufacturers and energy storage electrode producers drive single-wall carbon nanotube procurement. EPA TSCA Section 5 pre-manufacture notification requirements extend commercialization timelines for novel nanoscale substances. Boston-area materials startups cluster near MIT and Harvard research corridors, leveraging proximity to federal laboratory partnerships for toxicology portfolio development.
Germany
Automotive crash-structure specifications for clay-polymer nanocomposites concentrate procurement authority with Stuttgart and Munich-based OEMs. ECHA REACH nanospecific annex revisions mandate expanded particle-size distribution documentation for imported batches. Frankfurt-Rhine-Main chemical corridors host formulation specialists serving European nanocoating applicators consolidating supplier bases.
South Korea
Domestic foundries are tightening high-purity carbon nanotube specifications for advanced semiconductor packaging architectures. MFDS biocompatibility protocols govern nanomaterials entering medical device supply chains, creating harmonization pressure across jurisdictions. Seoul Capital Area materials producers are pivoting toward captive plasma-enhanced chemical vapor deposition capacity to serve Samsung and SK Hynix procurement.
Japan
Electronics integrators in Osaka and Nagoya manufacturing corridors impose distinct quantum-dot nanocrystal purity thresholds that fragment supplier qualification pathways. METI industrial standards guide nanomaterial characterization for display manufacturing exports. Precision coating specialists in the Chubu region control color-gamut specification evolution for next-generation visual performance metrics.
China
Mechanical milling scale-up for surface-area-to-volume ratio certification concentrates technical expertise in Yangtze River Delta chemical processing hubs. MIIT and SAMR oversight of GB standards for nanoscale substances elevates analytical rigor for domestic batch release. Shenzhen and Dongguan electronics assemblers internalize sol-gel synthesis protocols that bypass traditional merchant nanomaterial channels.
Advanced Nanomaterials Market Competitive Environment
Global majors compete with regional champions across regulatory dossier depth and synthesis scale. Market structure tilts toward incumbents with established toxicology portfolios that satisfy REACH and EPA notification requirements. Three archetypes dominate: integrated mining-to-powder refiners controlling rare-earth nanocrystal feedstock, fluoropolymer-anchored coating specialists with European registration libraries, and single-wall carbon nanotube purifiers differentiating from multi-wall commodity suppliers. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with Korean cell manufacturers internalizing production systems and European applicators consolidating supplier bases.
Among diversified chemical conglomerates, Arkema and Evonik Industries exemplify incumbents leveraging established dossier libraries to secure preferred supplier status under REACH nanospecific mandates. OCSiAl occupies a position representing single-wall synthesis scale differentiation from multi-wall alternatives. Sumitomo Metal Mining anchors the integrated refining archetype controlling mine-to-powder quality for quantum-dot display feedstock. These three sit within distinct competitive vectors—regulatory compliance depth, structural purity at scale, and upstream feedstock integration—that define qualification pathways for fragmented end-use specifications.
| Leading Market Players |
|---|
| Arkema |
| Sumitomo Metal Mining |
| Merck KGaA |
| OCSiAl |
| Nanosys |
| Evonik Industries |
| Cabot Corporation |
| Advanced Nano Products |
| DuPont de Nemours |
| Others |
Value Chain & Pricing Dynamics
Rare-earth nanocrystal feedstock costs cascade through quantum-dot display supply chains, with integrated mine-to-powder refiners capturing margin premiums while merchant suppliers face commodity pricing pressure in multi-wall carbon nanotube categories.
Pricing Analysis
Technical service bundling separates premium direct-supply relationships from unbundled bulk contracting. Three-tier pricing structure across semiconductor-grade, industrial-grade, and research-grade nanomaterials reflects certification depth and batch-specific characterization. Cost compression in multi-wall carbon nanotubes is intensifying because Korean battery cell manufacturers are internalizing plasma-enhanced chemical vapor deposition capacity. Electronics integrators show least price sensitivity for quantum-dot nanocrystals with tight size distributions, while academic buyers drive spot-market volatility for research-grade materials.
Supply Chain Analysis
Single-wall carbon nanotube feedstock rests on South Korean and Japanese specialty chemical producers with plasma-enhanced synthesis expertise. Rare-earth oxide concentrates, fluoropolymer precursors, and high-purity metal-organic frameworks anchor upstream dependencies. Single-source vulnerability concentrates in Sumitomo Metal Mining's integrated refining operations for quantum-dot feedstock. Distribution runs through technical service-intensive direct partnerships for qualified grades, with digital procurement channels serving standardized nanoclays.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH nanospecific characterization mandates have erected a compliance moat that favors incumbents with established toxicology portfolios and extends commercialization timelines for unprepared entrants.
For Market Incumbents: Lock in preferred supplier status with European nanocoating applicators by expanding dossier libraries ahead of ECHA guidance updates. Deepen backward integration into rare-earth oxide refining to secure quantum-dot feedstock quality control against Sumitomo Metal Mining's mine-to-powder dominance. Capacity addition in South Korea's Seoul Capital Area serves Samsung and SK Hynix procurement concentration.
For New Entrants and Emerging Players: Online technical portals offer lower-qualification entry points for standardized nanoclays serving packaging and coating applications. Japanese precision coating specialists in the Chubu region represent underpenetrated relationships for fluoropolymer-anchored nanocoating producers. Direct sampling programs with Osaka-Nagoya automotive tier-one suppliers bypass disintermediated masterbatch channels.
For Investors and Strategic Acquirers: South Korean foundries tightening high-purity carbon nanotube specifications is the leading indicator that captive production trends will compress merchant market volumes. Long-term viability favors integrated refining archetypes controlling mine-to-powder quality and incumbents with REACH-compliant dossier libraries. Watch for ECHA annex revisions triggering supplier consolidation among European nanocoating applicators.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | South Korean materials producers scaling plasma-enhanced chemical vapor deposition serve domestic semiconductor packaging demand concentration. |
| Backward Integration | Korean battery cell manufacturers internalizing single-wall carbon nanotube synthesis reduce merchant supplier spot market volumes. |
| Long-term Supply Agreement | European nanocoating applicators consolidating supplier bases favor Arkema and comparable incumbents with established REACH dossiers. |
| Joint Venture | Japanese automotive tier-one suppliers unbundling nanocomposite formulation from raw nanoclay procurement displace merchant masterbatch intermediaries. |
| Regulatory Compliance Investment | ECHA nanospecific annex revisions mandate expanded particle-size distribution documentation that extends registration preparation timelines. |
Study Parameters
Multi-period observation of carbon nanotube conductivity specifications, quantum-dot color-gamut evolution, and REACH compliance timelines anchored the trend analysis, supplemented by interviews with nanomaterials plant managers, procurement leads at South Korean foundries, technical R&D directors at Japanese electronics integrators, and regulatory affairs specialists. Secondary validation drew from ECHA registration dossiers, EPA TSCA Section 5 filings, MFDS biocompatibility protocols, customs and trade data, and SEC 10-K disclosures from diversified chemical conglomerates. Bottom-up segment sizing triangulated against top-down market value estimates.
Segment-weighting across product type, application, end user, and delivery mode informed the analytical framework. Modeled dimensions included carbon nanotube structural purity, nanocrystal size distribution precision, and regional regulatory cluster alignment. CAGRs derived from production capacity announcements, foundry capital expenditure patterns, and display manufacturer procurement timelines. Industry-specific inputs encompassed plasma-enhanced chemical vapor deposition system installations and sol-gel synthesis protocol adoption rates.
The model holds under stable regulatory classification criteria; deviation in multi-functional nanomaterial jurisdiction reassignment or single-wall carbon nanotube purity threshold tightening would shift supplier qualification pathways. Forecasts reflect assumptions regarding continued East Asian manufacturing cluster concentration and REACH annex implementation timelines. EPA TSCA Section 5 notification backlog and rare-earth feedstock quality variance warrant ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Advanced Materials
Curable Materials Market
Advanced Materials
Solar Encapsulation Materials Market
Advanced Materials
Thermal Spray Market
Advanced Materials
Europe Graphene Market
Advanced Materials
Lithium Hydride Market
Advanced Materials
Long-Range Ordered Porous Carbon (LOPC) Market
Advanced Materials
Chemistry 4.0 Market
Advanced Materials
Boron Nitride Market
Advanced Materials
High Nickel Cathode Materials Market
Advanced Materials
Europe Blanket Aerogel Market
Advanced Materials
Carbon Prepreg Market
Advanced Materials
High-Purity Amorphous Boron Market
Advanced Materials
Nomex Honeycomb Market
Advanced Materials
Natural Single Crystal Diamond Market
Advanced Materials
Glass Reinforced Vinyl Ester (GRV) Market
Advanced Materials
Flexible Bio-Foams Market