
 Refinery Fuel Additives Market | 2026-2036
Refinery Fuel Additives Market Size, Share, and Industry Trends Forecast 2026-2036
Refinery Fuel Additives Market Analytics
Advanced molecular blending platforms is rewriting how refinery fuel additives achieve precision performance at scale. BASF SE leverages its integrated catalyst-additive technology portfolio to sustain leadership in octane booster formulations across European gasoline markets. Afton Chemical Corporation anchors its competitive position through specialized detergent packages that dominate North American premium fuel channels. Innospec Inc. differentiates by controlling niche cetane improver supply for high-sulfur diesel upgrade programs in emerging markets.
Refinery fuel additives are specialty chemicals—typically organometallic compounds, polyetheramines, or ester-based formulations dosed at 10–500 ppm—that modify combustion properties, prevent engine deposits, and protect fuel system infrastructure in refined petroleum products. Their primary industrial purpose is to bridge the gap between crude-derived base fuels and increasingly stringent end-use performance specifications mandated by engine OEMs and environmental regulators. Corrosion inhibitors and octane boosters command the deepest margin pools, as refiners prioritize asset protection and high-octane gasoline production over commodity detergent dosing. Diesel application growth outpaces gasoline as marine and heavy-duty engine standards tighten, while aviation fuel additives remain the most specification-intensive segment due to single-batch certification requirements and freeze-point sensitivity.
The EPA enforces Tier 3 sulfur limits that force refiners to reformulate gasoline with higher-performance detergent and corrosion inhibitor packages, directly expanding additive volume demand. REACH and the EU F-Gas Regulation impose disclosure and phase-down obligations on fluorinated additive chemistries, redirecting R&D spending toward bio-based and organometallic alternatives. India's BIS and CEA are implementing parallel fuel quality roadmaps that will require imported additive technology for domestic refinery upgrades. Stakeholders must monitor how regulatory divergence between EPA, ECHA, and Asian standards bodies fragments formulation requirements and complicates global product registration strategies.
Market Dynamics
Divergent fuel quality mandates across EPA, ECHA, and Asian regulators are fragmenting formulation requirements and forcing additive suppliers to maintain parallel product portfolios for regional compliance.
Growth Catalysts
- Aviation Thermal Stability Mandates:Airlines operating under FAA and EASA specifications are demanding higher-performance antioxidants and metal deactivators for jet fuel thermal stability, expanding specification-intensive additive categories.
- India's PLI Petroleum Quality Scheme:Domestic refinery modernization programs are accelerating specialty chemical imports and technology transfer partnerships for cetane improver and corrosion inhibitor packages.
- Marine Fuel Sulfur Transition:IMO 2020 low-sulfur marine fuel specifications are driving organometallic combustion improver demand for very low sulfur fuel oil stability and engine protection.
Market Restraints
- Organometallic Feedstock Concentration:Manganese and cerium supply for octane boosters concentrates in South African and Chinese mining operations, creating price volatility and supply security exposure.
- REACH Registration Burden:ECHA's substance evaluation and authorization procedures for polyetheramine detergents impose multi-year compliance timelines and documentation costs that freeze SME market entry.
- Biofuel Oxygenate Substitution:Ethanol and renewable diesel blending mandates in California LCFS and EU RED III are displacing conventional cetane improver and detergent volume in finished fuel pools.
Strategic Opportunities
- Indonesia Refinery Upgrade Wave:Pertamina's Cilacap and Balikpapan modernization projects represent uncontracted demand for imported fuel additive technology and technical service partnerships.
- Digital Dosing System Integration:Convergence of inline blending analytics with automated additive injection is enabling real-time performance optimization and premium service tier creation.
- Saudi Arabia Fuel Quality Roadmap:SABIC and domestic refiners are implementing Euro 5-equivalent specifications that require imported detergent and corrosion inhibitor formulations.
Industry Challenges
- Single-Batch Aviation Certification:Jet fuel additive qualification requires full engine test stand validation and freeze-point verification that extends product launch timelines to 18-24 months.
- Cross-Regulatory Formulation Conflict:EPA Tier 3 sulfur limits and EU F-Gas fluorinated compound restrictions impose incompatible chemistry requirements that complicate global product standardization.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Refinery Fuel Additives Market |
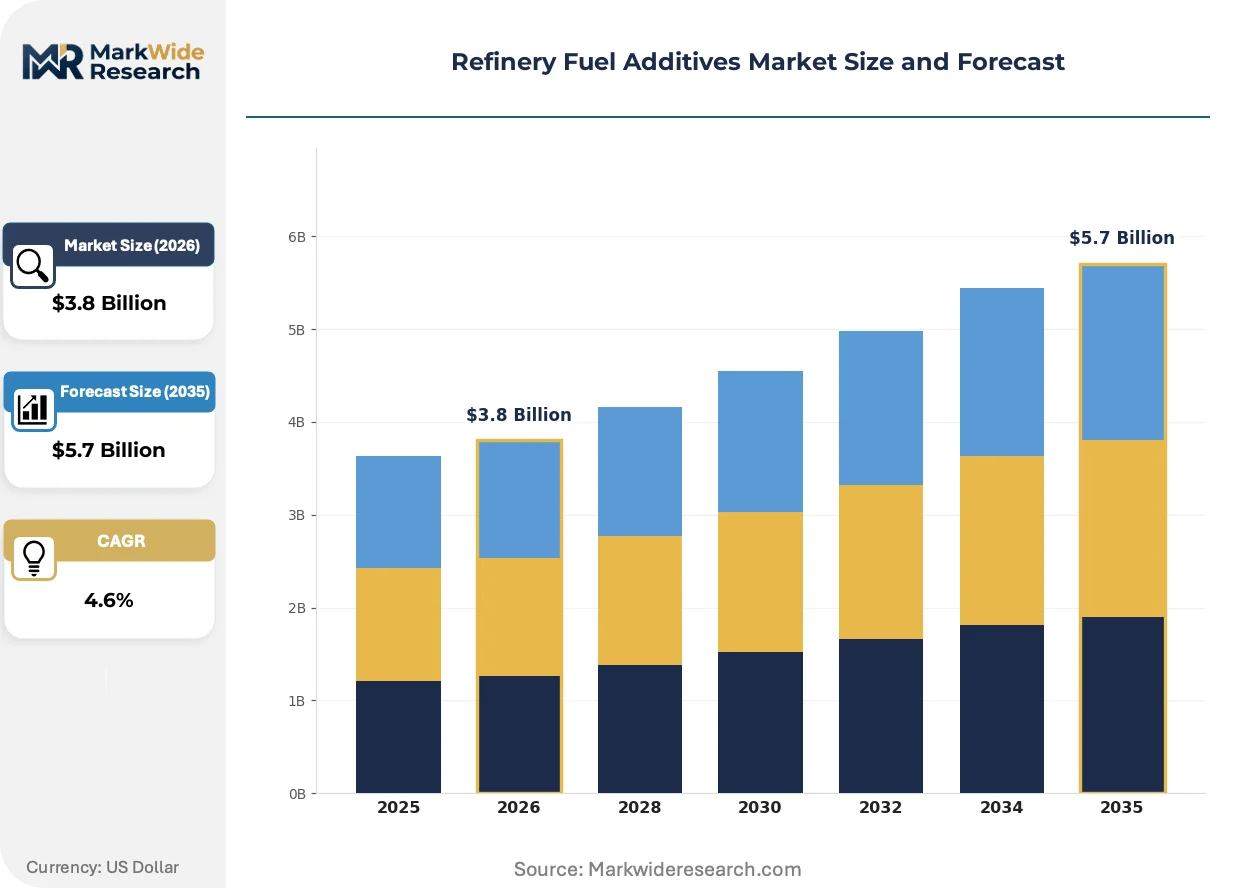
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $5.7 Billion |
| CAGR (2026 – 2036) | 4.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Detergents, Corrosion Inhibitors, Octane Boosters, Cetane Improvers Application: Gasoline, Diesel, Aviation Fuel, Heating Oil End User: Refineries, Fuel Distributors, Oil Companies, Commercial Fleet Operators Technology: Laboratory Formulations, Blending Techniques, Quality Control Methods, Testing Procedures |
| Companies Covered | BASF SE, Lubrizol Corporation, Afton Chemical Corporation, Innospec Inc., Infineum International Limited, Clariant, Chevron Oronite Company LLC, Dorf Ketal Chemicals, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Refinery Fuel Additives Market Evolving Landscape
Bio-based molecular architectures and precision dosing infrastructure are converging to redefine how refinery fuel additives deliver performance accountability and environmental compliance.
Synthetic ester and terpene-derived detergent chemistries are rendering obsolete petroleum-based polyisobutylene amine formulations in European premium gasoline channels. Shell, BP, and independent fuel retailers operating under REACH disclosure obligations are accelerating qualification timelines for plant-derived alternatives. This chemistry transition is compressing R&D amortization periods and forcing reformulation of legacy additive packages.
EPA's Tier 3 gasoline sulfur standards and testing protocols are mandating higher treat rates for corrosion inhibitors and deposit control additives in finished fuels. Refiners in PADDs 1-3 are reformulating summer-grade gasoline with enhanced detergent packages to meet intake valve deposit limits. The detergent segment is responding with concentrated polyetheramine blends that reduce logistics costs while maintaining performance thresholds.
Aviation fuel buyers at major hub airports are consolidating procurement around full-service additive management contracts that bundle chemical supply with injection system maintenance and quality assurance. This service unbundling is displacing traditional chemical-only supply agreements at Dallas-Fort Worth, Frankfurt, and Singapore Changi. MRO providers and into-plane operators are capturing margin previously held by standalone additive suppliers.
Refinery Fuel Additives Market Segmentation
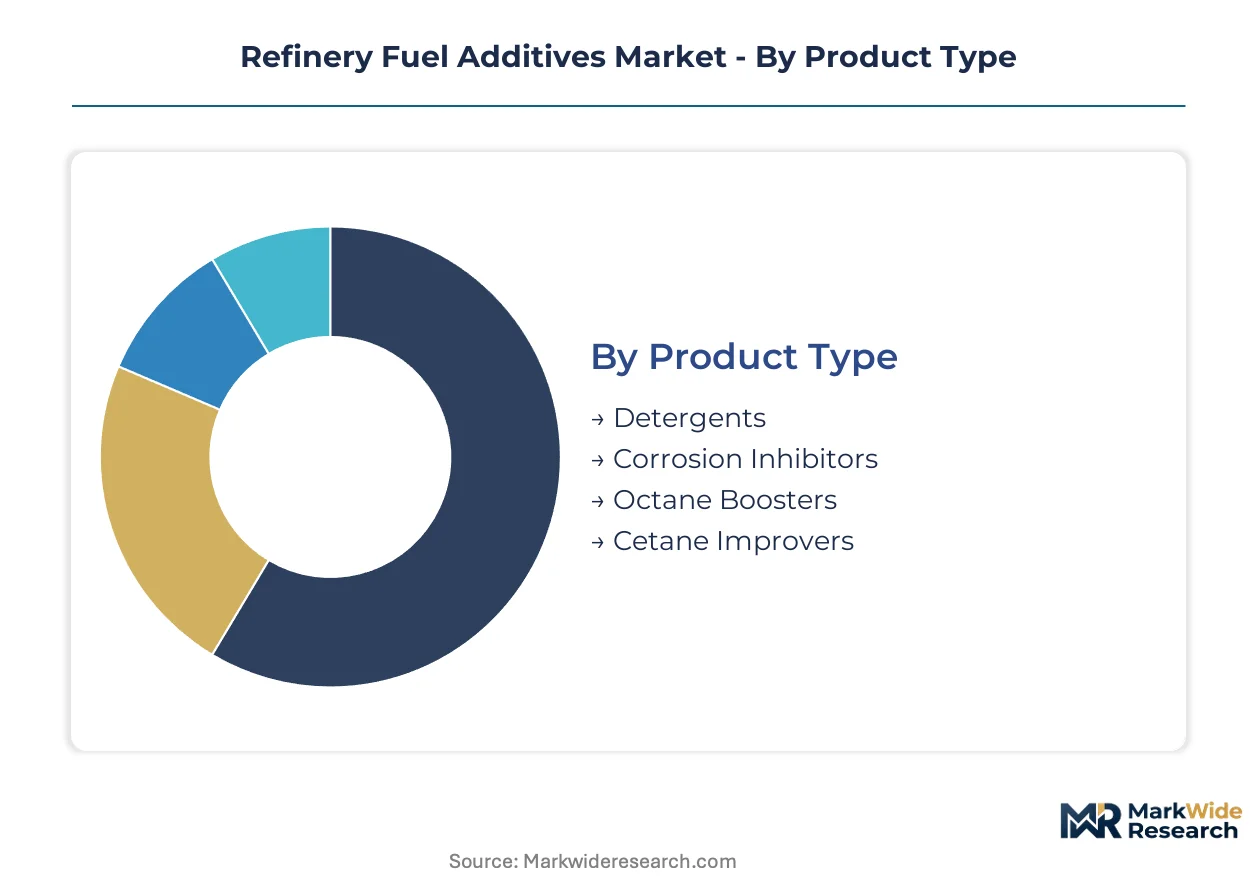
Refinery fuel additives serve distinct performance requirements across fuel types and end-use specifications. Segmentation reveals how formulation chemistry, application severity, and procurement authority fragment demand into specialized supply relationships.
Product Type:
Cost tier stratification separates commodity detergents from premium corrosion inhibitors and organometallic boosters commanding formulation premiums.
- Corrosion Inhibitors:Amine-based and carboxylate formulations protect refinery infrastructure and vehicle fuel systems from acidic condensation. Refiners in PADDs 1-3 prioritize these under EPA Tier 3 intake valve deposit limits, driving treat rate escalation in finished gasoline.
- Octane Boosters:Methylcyclopentadienyl manganese tricarbonyl (MMT) and ferrocene derivatives elevate gasoline antiknock performance. South African and Chinese mining concentration for manganese feedstock creates supply security exposure for North American refiners seeking high-octane production flexibility.
- Detergents:Polyetheramine and polyisobutylene amine chemistries prevent injector and valve deposits. REACH disclosure obligations in Europe accelerate substitution toward synthetic ester alternatives.
- Cetane Improvers:Alkyl nitrate and peroxide formulations enhance diesel ignition quality. India's PLI petroleum quality scheme accelerates import demand for high-concentration 2-ethylhexyl nitrate packages.
Corrosion inhibitors hold installed capacity. Octane boosters is rotating up the share rankings.
Application:
Application severity determines specification stringency and certification burden, from commodity heating oil to aviation thermal stability mandates.
- Aviation Fuel:Antioxidants and metal deactivators must pass single-batch freeze-point verification and full engine test stand validation. FAA and EASA specifications extend product launch timelines to 18-24 months, creating qualification barriers.
- Diesel:Marine IMO 2020 low-sulfur specifications and heavy-duty engine standards drive organometallic combustion improver demand for very low sulfur fuel oil stability. Organometallic cetane improvers face displacement pressure from renewable diesel blending in California LCFS.
- Gasoline:Summer-grade reformulation under EPA Tier 3 requires enhanced detergent packages to meet deposit control thresholds. Concentrated polyetheramine blends reduce logistics costs while maintaining performance.
- Heating Oil:Basic corrosion inhibition and cold flow improvement dominate specification requirements. Seasonal demand concentration in Northeast US residential markets creates inventory management complexity.
Aviation fuel holds installed capacity. Diesel is rotating up the share rankings.
End User:
Customer type determines procurement scale, technical service requirements, and contract structure from captive refinery supply to third-party distributor relationships.
- Refineries:Integrated producers maintain captive additive blending operations with direct supplier technical partnerships. India's domestic modernization programs accelerate technology transfer agreements for specialty chemical packages.
- Oil Companies:Branded fuel marketers specify proprietary additive packages for retail differentiation. Shell and BP accelerate plant-derived detergent qualification timelines under European disclosure obligations.
- Fuel Distributors:Independent terminals source generic additive packages for unbranded gasoline and diesel supply. Price-sensitive procurement favors concentrated formulations reducing per-gallon logistics burden.
- Commercial Fleet Operators:Large trucking and marine operators negotiate direct additive supply for bulk fuel treatment. Into-plane operators at Dallas-Fort Worth and Singapore Changi capture margin through bundled service contracts.
Refineries hold installed capacity. Oil companies is rotating up the share rankings.
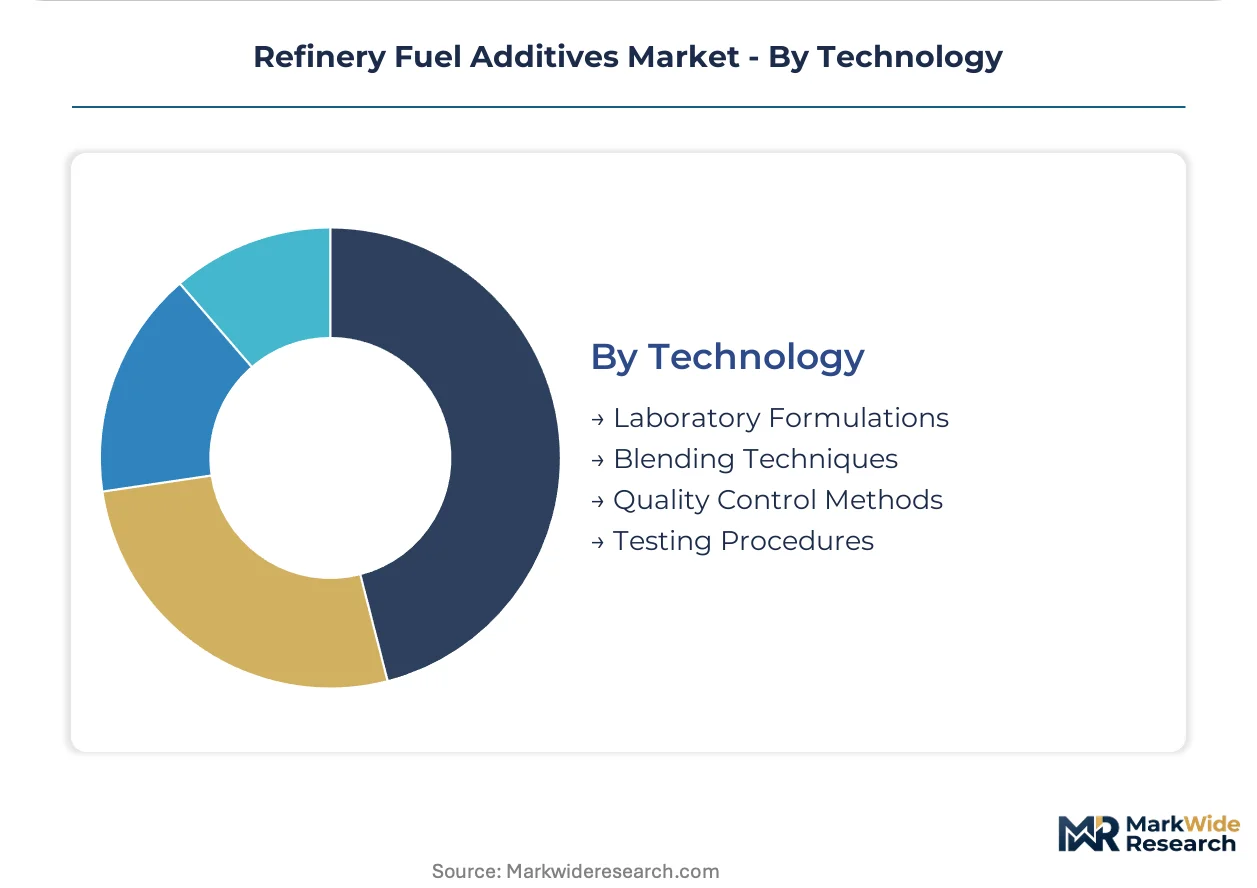
Technology:
Maturity gradients separate established laboratory formulation from emerging precision dosing infrastructure and real-time quality assurance.
- Blending Techniques:Inline blending analytics convergence with automated injection enables real-time performance optimization. Digital dosing system integration creates premium service tier opportunities for additive suppliers.
- Quality Control Methods:Spectroscopic and chromatographic verification ensures additive treat rate accuracy and batch consistency. Pertamina's Cilacap and Balikpapan modernization projects represent uncontracted demand for integrated quality assurance technology.
- Laboratory Formulations:Molecular design platforms optimize organometallic and ester chemistries for specific fuel matrices. R&D amortization periods compress as bio-based architectures displace petroleum-derived alternatives.
- Testing Procedures:Engine test stand validation and freeze-point verification protocols govern aviation fuel additive certification. SABIC and Saudi domestic refiners implementing Euro 5-equivalent specifications require imported testing protocols and technical service partnerships.
Laboratory formulations hold installed capacity. Blending techniques is rotating up the share rankings.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Integrated refiners and branded fuel marketers concentrate procurement authority in jurisdictions with the most stringent fuel quality roadmaps. India's PLI petroleum scheme, the EPA's Tier 3 enforcement, and Saudi Arabia's Euro 5 transition are reshaping where additive suppliers must establish technical service presence.
United States
Refiners in PADDs 1-3 are reformulating summer-grade gasoline with enhanced detergent packages to meet EPA Tier 3 intake valve deposit limits. The EPA's testing protocols mandate higher treat rates for corrosion inhibitors and deposit control additives. Houston-Galveston and the Delaware Valley host the densest concentration of captive additive blending operations serving integrated producers.
India
Domestic refinery modernization programs are accelerating specialty chemical imports and technology transfer partnerships for cetane improver and corrosion inhibitor packages. The BIS and CEA are implementing parallel fuel quality roadmaps that require imported additive technology for domestic upgrades. The Jamnagar refining complex and Mumbai-Pune industrial corridor represent the primary demand concentration for high-concentration 2-ethylhexyl nitrate packages.
Germany
Shell, BP, and independent fuel retailers operating under REACH disclosure obligations are accelerating qualification timelines for plant-derived detergent alternatives. The EU F-Gas Regulation imposes phase-down obligations on fluorinated additive chemistries, redirecting R&D spending toward bio-based and organometallic alternatives. The Rhine-Ruhr industrial region and the Port of Rotterdam hinterland anchor European additive formulation and distribution infrastructure.
Saudi Arabia
SABIC and domestic refiners are implementing Euro 5-equivalent specifications that require imported detergent and corrosion inhibitor formulations. The national fuel quality roadmap is driving technical service partnerships with international additive suppliers. The Jubail industrial city and Yanbu refining complex on the Red Sea coast represent uncontracted demand for integrated quality assurance technology and testing protocols.
Indonesia
Pertamina's Cilacap and Balikpapan modernization projects represent uncontracted demand for imported fuel additive technology and technical service partnerships. The country's national petroleum regulator is aligning domestic specifications with IMO 2020 marine fuel standards. Java's northern coastal refining belt and the Balikpapan industrial zone in East Kalimantan concentrate procurement activity for organometallic combustion improvers.
Refinery Fuel Additives Market Competitive Landscape
Channel-controlling players compete with product-specialist players across formulation tiers defined by specification intensity and certification burden. The vendor base organizes around three archetypes: integrated chemical conglomerates with catalyst-additive technology portfolios, mid-scale specialty chemical houses with regional formulation expertise, and niche technology licensors focused on single-molecule categories. Dominant competitive moves include strategic partnerships for refinery modernization programs and geographic expansion through technical service licensing.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify the conglomerate archetype with broad technology portfolios spanning organometallic and ester-based chemistries. Among specialty chemical houses, Afton Chemical Corporation and Innospec Inc. occupy positions defined by concentrated expertise in detergent packages and cetane improvers respectively. The competitive terrain rewards formulation precision and regulatory navigation capability over manufacturing scale alone.
| Leading Market Players |
|---|
| BASF SE |
| Lubrizol Corporation |
| Afton Chemical Corporation |
| Innospec Inc. |
| Infineum International Limited |
| Clariant |
| Chevron Oronite Company LLC |
| Dorf Ketal Chemicals |
| Evonik Industries AG |
| Others |
Value Network & Pricing Analysis
Manganese and cerium mining concentration in South African and Chinese operations anchors where margin pools accumulate downstream. Refiners seeking high-octane gasoline production flexibility face feedstock price volatility that compresses formulation premiums for octane boosters while elevating corrosion inhibitor and detergent contract values.
Pricing Analysis
Cost-plus contracts with manganese and rare earth indexation dominate octane booster procurement. Three-tier pricing structure across premium, standard, and economy levels separates aviation-certified antioxidants from commodity diesel detergents and unbranded heating oil packages. Cost compression in standard-tier polyetheramine blends is intensifying because REACH disclosure obligations accelerate synthetic ester substitution. Independent fuel distributors exhibit highest price sensitivity; integrated refiners with captive blending operations show lowest.
Supply Chain Analysis
Tariff exposure between China and North American refiners dominates supply chain risk assessment for organometallic feedstocks. Manufacturing concentrates in Germany, the United States, and India for formulated additive packages; South Africa and China anchor raw manganese and cerium extraction. Formulation draws from polyetheramine intermediates, organometallic precursors, and synthetic ester bases. Single-source vulnerability persists for aviation-certified metal deactivators. Distribution runs through refinery captive blending facilities, third-party terminal operators, and into-plane service providers at major hub airports.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Incumbents must navigate renewable diesel and ethanol oxygenate substitution that displaces conventional cetane improver and detergent volumes under California LCFS and EU RED III mandates.
For Market Incumbents: Entrench through backward integration into manganese and cerium feedstock sourcing to secure octane booster supply chains against South African and Chinese mining volatility. Deepen technical service partnerships with India's PLI petroleum quality scheme beneficiaries to lock in long-term cetane improver and corrosion inhibitor offtake. Certification investment for bio-based synthetic ester detergents defends against REACH-driven displacement of petroleum-derived polyisobutylene amine formulations. For New Entrants and Emerging Players: Indonesia's Pertamina Cilacap and Balikpapan refinery modernization projects represent the most penetrable entry point for imported additive technology and quality assurance system partnerships. Saudi Arabia's Euro 5-equivalent fuel quality roadmap offers secondary white-space for detergent and corrosion inhibitor formulation licensing. A go-to-market angle anchored in digital dosing system integration with inline blending analytics enables premium service tier creation without incumbent scale requirements. For Investors and Strategic Acquirers: Secondary-cycle assets sit with mid-scale specialty chemical houses holding regional formulation expertise but lacking integrated catalyst-additive technology portfolios. Long-term viability over a multi-year horizon hinges on regulatory navigation capability across divergent EPA, ECHA, and Asian fuel quality mandates. The signal to watch is aviation fuel additive procurement consolidation around full-service bundled contracts at Dallas-Fort Worth, Frankfurt, and Singapore Changi hub airports.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Organometallic Feedstocks | Secures manganese and cerium supply chains against South African and Chinese mining concentration risks. |
| Digital Dosing System Integration | Enables real-time performance optimization and premium service tier creation for refinery customers. |
| Bio-Based Synthetic Ester Qualification | Defends detergent market position under REACH disclosure obligations and EU F-Gas phase-down mandates. |
| Technical Service Partnership Expansion | Captures India's PLI petroleum quality scheme demand for cetane improver and corrosion inhibitor packages. |
| Aviation Additive Certification Investment | Overcomes FAA and EASA single-batch validation barriers that extend product launch timelines to 18-24 months. |
Research Methodology
Demand-side practitioners and supply-side operators were both consulted through structured primary interviews with refinery process engineers, additive procurement managers at integrated oil companies, terminal operations directors, aviation fuel quality specialists, and specialty chemical R&D directors. Secondary validation drew from EPA Tier 3 enforcement documentation, ECHA REACH registration databases, BIS and CEA fuel quality roadmap publications, and customs trade data for organometallic feedstock flows. Bottom-up segment sizing triangulated against top-down market boundary analysis.
Calibration against historical treat rate escalations and regulatory implementation timelines anchored the analytical framework across the analysis window. Segmentation dimensions modeled include product type tier, application severity, end-user procurement authority, and technology maturity gradient. CAGRs were derived from elasticity-adjusted demand projections. Industry-specific forecast inputs incorporated refinery modernization project pipelines and aviation certification backlog durations.
Macroeconomic conditions sit as an overlay; deviation in crude oil price volatility, mining sector labor disruptions, or currency fluctuations in South Africa and China would shift the trajectory. Forecasts reflect documented assumptions about regulatory implementation schedules and technology substitution rates. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Additives
Global Pour Point Depressant Market
Additives
Global Formulation Additives Market
Additives
Plasticizers Market
Additives
Chelating Agents Market
Additives
Hydroxyethyl Cellulose Market
Additives
Citric Acid Market
Additives
Inorganic Rheology Modifiers Market
Additives
Ballast Tank Corrosion Inhibitors Market
Additives
Disodium Guanylate Market
Additives
Nucleotide Premix Market
Additives
China Sodium Reduction Ingredient Market
Additives
Europe Feed Additives Market
Additives
Global Inorganic Corrosion Inhibitors Market
Additives
Paint Additives Market
Additives
Global Cement and Concrete Additives Market
Additives
Sodium Stearyl Fumarate Market