
 Global Nanoclay Reinforcement Market | 2026-2036
Global Nanoclay Reinforcement Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nanoclay Reinforcement Market Intelligence
Compliance with ISO standards for nanomaterial characterization, such as ISO/TS 19807, is redrawing competitive positioning. BYK Additives (ALTANA) leverages its expertise in organomodified clays to serve high-performance polymer applications. Elementis PLC sustains its market presence through a broad portfolio of rheology modifiers and specialty additives. Meanwhile, 3M differentiates with its advanced material science R&D, integrating nanoclays into proprietary composite systems for various industrial uses.
Nanoclay reinforcement involves dispersing layered mineral silicates, such as montmorillonite, into a polymer matrix at a nanometer scale. The primary function is to enhance material properties, including mechanical strength, flame retardancy, and gas barrier performance in composites. Organomodified nanoclay products dominate the market due to their superior compatibility with non-polar polymer systems. Within applications, packaging materials and automotive components are expanding rapidly, driven by the need for lightweight, high-barrier solutions.
Regulatory oversight from bodies like the US Environmental Protection Agency (EPA) under the TSCA and the European Chemicals Agency (ECHA) under REACH is stringent. These frameworks require extensive data on nanoparticle safety and environmental impact, governing market access and product labeling. China's Ministry of Ecology and Environment (MEE) also imposes strict controls. Suppliers must therefore invest in robust toxicological data and lifecycle assessments to meet evolving compliance demands from both regulators and downstream customers.
Market Dynamics
The central dynamic is the push-pull between the automotive and packaging industries demanding advanced material properties and the increasingly stringent regulatory frameworks, such as the EU's REACH, governing nanomaterial safety and lifecycle assessment. This shapes investment in R&D and compliance.
Growth Catalysts
- Automotive Lightweighting Mandates:Regulations like the European Union's CO2 emission performance standards for new passenger cars compel automakers to adopt lightweight composites, directly increasing the use of nanoclays for structural and under-hood components.
- Advanced Packaging Demand:The food and beverage sector's requirement for extended shelf life and reduced material usage drives adoption in multi-layer films, where nanoclays provide superior gas barrier properties compared to conventional materials.
- Chinese Industrial Concentration:China's large-scale polymer and electronics manufacturing base, supported by government industrial policies, creates a concentrated demand hub for nanoclay reinforcement to enhance product performance and durability.
Market Restraints
- Dispersion and Agglomeration Issues:Achieving uniform dispersion of nanoparticles within a polymer matrix remains a significant technical challenge, potentially leading to inconsistent material properties and limiting performance gains in finished products.
- High Compliance Costs:The extensive toxicological and lifecycle data required by regulatory bodies like the US EPA under TSCA and ECHA under REACH imposes substantial financial and time-to-market burdens on manufacturers.
- Substitution by Other Nanomaterials:Alternative reinforcements such as carbon nanotubes and graphene, while often more expensive, present a long-term substitution threat in high-performance applications where their specific properties offer a distinct advantage.
Strategic Opportunities
- Bio-Polymer Composites:The integration of nanoclays with bio-based polymers like polylactic acid (PLA) offers a path to creating high-performance, sustainable materials for packaging and consumer goods, aligning with circular economy goals.
- Expansion in Medical Devices:Opportunities exist in biomedical applications, such as using nanoclays to reinforce biocompatible polymers for medical implants or to develop advanced drug delivery systems with controlled release properties.
- Targeting Indian Automotive Sector:India's growing automotive manufacturing sector presents an underpenetrated market for nanoclay composites, particularly as the country implements stricter fuel efficiency and safety standards.
Industry Challenges
- Lack of Characterization Standards:The absence of universally adopted standards for characterizing nanoclay properties and their dispersion in composites, despite progress with ISO/TS 19807, creates inconsistencies and complicates material specification for end-users.
- Raw Material Quality Control:Ensuring a consistent supply of high-purity mineral silicates, the primary raw material, is a persistent operational challenge, as variations in natural deposits can affect final product performance.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nanoclay Reinforcement Market |
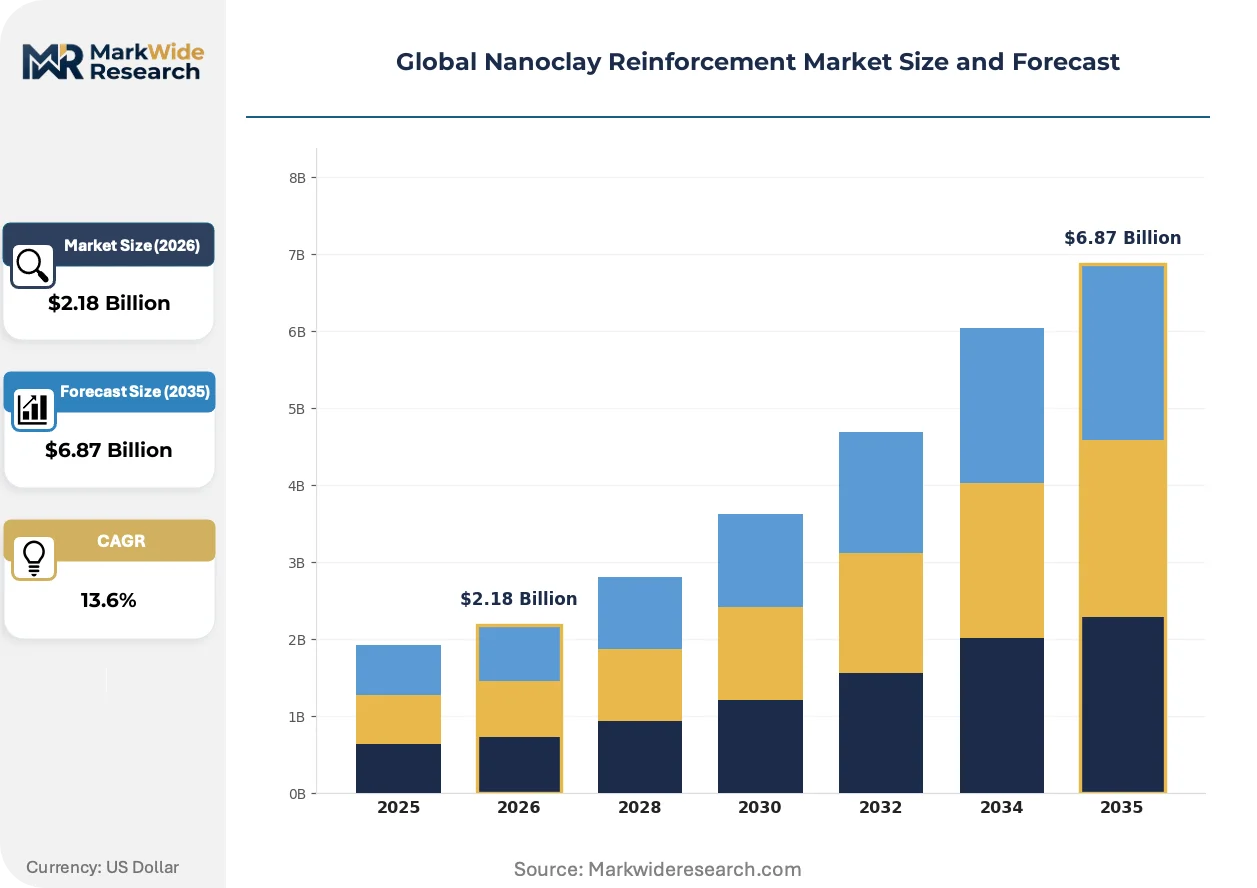
| Market Size in 2026 | $2.18 Billion |
| Market Size in 2035 | $6.87 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Organomodified Nanoclay, Unmodified Nanoclay, Exfoliated Nanoclay, Intercalated Nanoclay Application: Packaging Materials, Coatings, Automotive Components, Electronics, Construction Composites End User Industry: Polymer Manufacturing, Aerospace Manufacturing, Consumer Goods Producers, Electrical Equipment Fabricators Form: Powder, Masterbatch, Pellets, Films |
| Companies Covered | AMCOL Corporation, BYK Additives (ALTANA), Nanophase Technologies Corporation, 3M, Laviosa Chimic Mineraria SpA, Elementis PLC, RTP Company, Inframat Corporation, Sika AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nanoclay Reinforcement Market Strategic Shifts & Innovations
The market's evolution is defined by a shift from simple mechanical reinforcement to multifunctional material systems. This transition is driven by demands for integrated properties like flame retardancy and gas barrier performance, alongside a growing emphasis on sustainable, bio-compatible formulations.
Organomodified nanoclays, which are surface-treated to improve compatibility with polymer matrices, are becoming standard. The automotive and packaging sectors are rapidly adopting these advanced materials for higher-performance composites. This trend is decomposing the traditional separation between a passive filler and an active polymer matrix, creating truly integrated composite systems where the nanoclay is a functional component.
China's stringent controls on new chemical substances, enforced by the Ministry of Ecology and Environment (MEE), are setting a distinct regional standard. These rules mandate specific registration and risk assessment data for nanomaterials, often diverging from EU or US requirements. Consequently, suppliers targeting China's vast polymer market must navigate a separate, resource-intensive compliance pathway, impacting global product launch strategies.
A notable shift in buying behavior involves end-users moving away from purchasing raw nanoclay powders toward procuring pre-dispersed masterbatches. This change simplifies processing for plastics converters but concentrates market power with specialized compounders who guarantee dispersion quality. The trend is most prominent within the European automotive supply chain, where process reliability and material consistency are critical for Tier 1 suppliers.
Global Nanoclay Reinforcement Market Segmentation
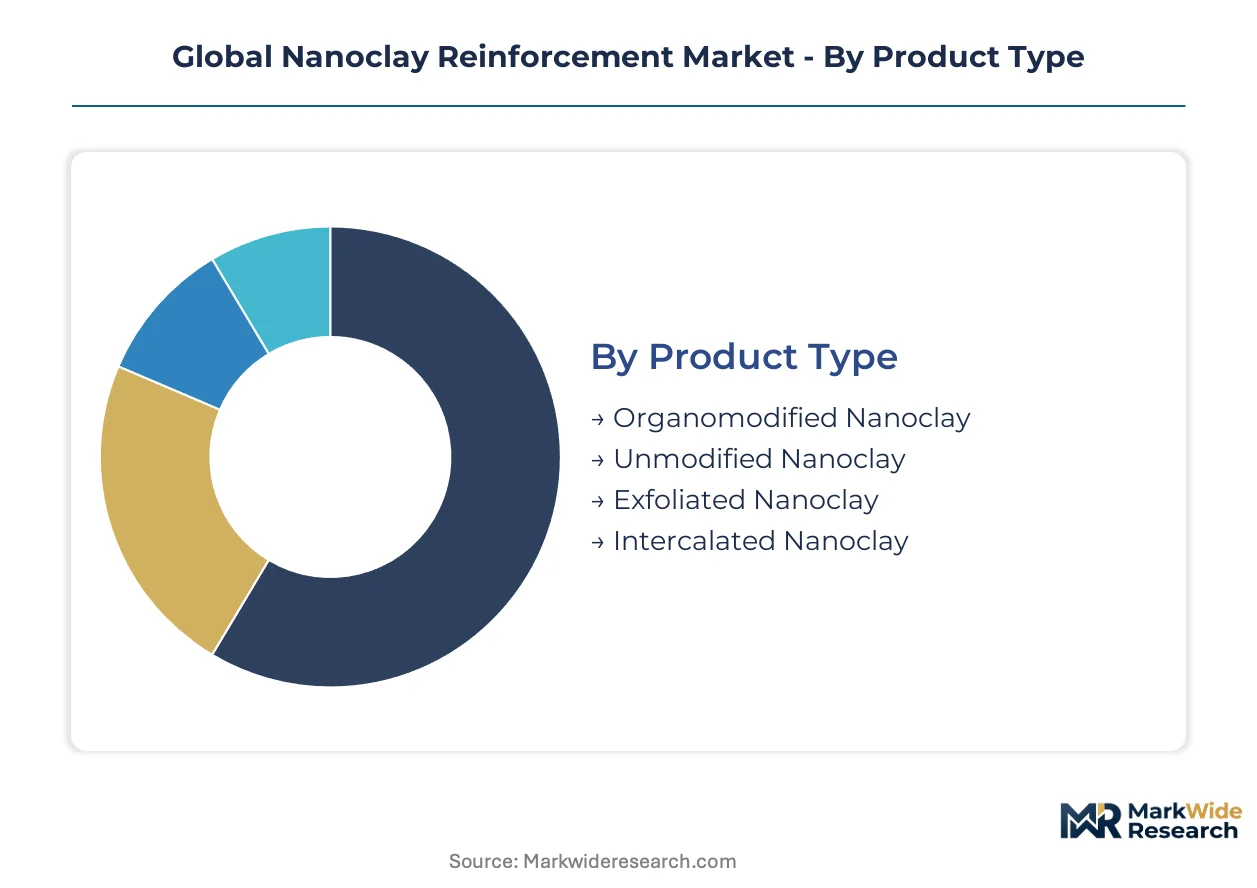
Understanding the varied applications and material forms of nanoclay reinforcement is critical for strategic market participation. Segmentation reveals distinct demand drivers and regulatory influences across different product types and end-use sectors, guiding product development and market entry strategies.
Product Type:
Regulatory bodies like ECHA and the US EPA influence product type differentiation, driving demand for well-characterized, compliant nanoclay variants.
- Organomodified Nanoclay:These clays feature surface treatments that improve compatibility with organic polymer matrices, enabling uniform dispersion and superior performance. Demand concentrates in automotive components for lightweighting and enhanced mechanical properties.
- Unmodified Nanoclay:These are raw mineral silicates without chemical surface modification, primarily used in less demanding applications or as precursors for further treatment.
- Exfoliated Nanoclay:Exfoliated nanoclays involve complete separation of individual silicate layers, maximizing surface area for polymer interaction and property enhancement. The packaging sector utilizes these for superior gas barrier performance in multi-layer films.
- Intercalated Nanoclay:Intercalated nanoclays have polymer chains inserted between silicate layers, forming a hybrid structure with improved mechanical and thermal properties.
Organomodified Nanoclay handles the majority of throughput; Exfoliated Nanoclay is the fastest mover on share.
Application:
Application segments exhibit distinct performance requirements and volume consumption patterns, reflecting diverse material engineering challenges.
- Packaging Materials:Nanoclays in packaging enhance barrier properties against gases and moisture, extending shelf life for food and beverages. The need for reduced material usage and sustainable solutions drives adoption in flexible films and rigid containers.
- Coatings:Nanoclays improve scratch resistance, fire retardancy, and barrier properties in various coating formulations for industrial and consumer products.
- Automotive Components:Using nanoclays in automotive parts contributes to vehicle lightweighting, improving fuel efficiency and reducing CO2 emissions. Structural and under-hood components are key areas where strength-to-weight ratio is critical.
- Electronics:Nanoclay reinforcement enhances thermal stability and mechanical strength in electronic enclosures and circuit board substrates.
- Construction Composites:These materials benefit from nanoclay integration through improved fire resistance, durability, and reduced permeability in building materials.
Packaging Materials represent the largest volume segment; Automotive Components exhibit the steepest expansion trajectory.
End User Industry:
Customer type segmentation highlights varying procurement scales and technical specifications, influencing supplier-customer relationships.
- Polymer Manufacturing:Polymer manufacturers integrate nanoclays directly into resin formulations to create advanced composite pellets and compounds. This sector demands high consistency and technical support for processing.
- Aerospace Manufacturing:Aerospace applications leverage nanoclays for high-performance, lightweight composites that meet stringent safety and performance standards.
- Consumer Goods Producers:Producers of consumer products utilize nanoclay-reinforced plastics for enhanced durability, aesthetics, and functional properties. This industry often seeks cost-effective and scalable solutions.
- Electrical Equipment Fabricators:These fabricators use nanoclay composites for electrical insulation, flame retardancy, and improved mechanical integrity in devices.
Polymer Manufacturing accounts for the bulk of nanoclay consumption; Consumer Goods Producers are rapidly increasing their adoption.
Form:
Material form determines ease of processing and dispersion quality for downstream manufacturers, impacting overall composite performance.
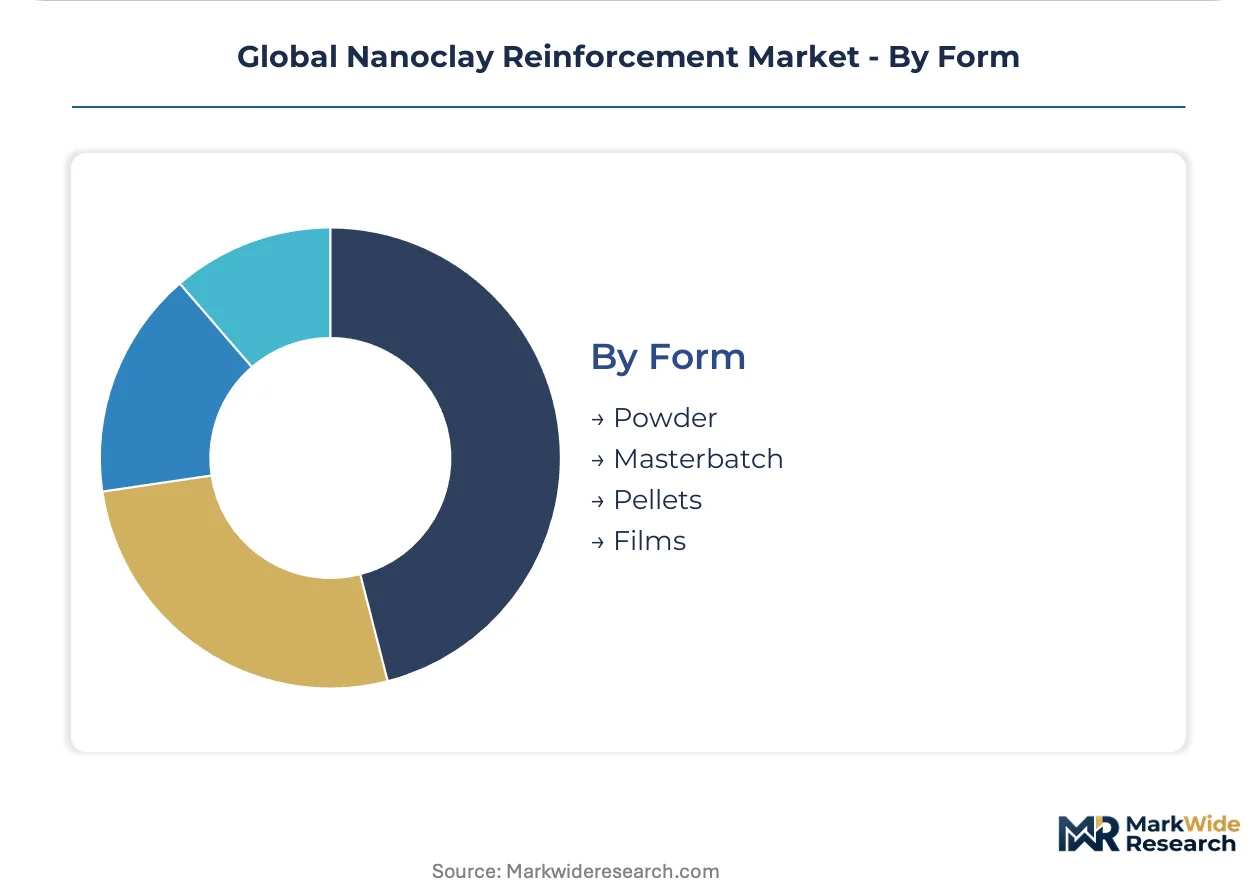
- Powder:Nanoclay powders are raw, dry forms requiring specialized dispersion equipment and expertise for integration into polymer matrices. These offer cost advantages for large-scale compounders with in-house capabilities.
- Masterbatch:Masterbatches are concentrated dispersions of nanoclay in a polymer carrier, simplifying processing and ensuring uniform distribution in final products. European automotive supply chains favor masterbatches for process reliability.
- Pellets:Nanoclay-infused pellets provide a convenient, ready-to-process form for injection molding and extrusion applications.
- Films:Nanoclay films are pre-formed sheets or layers containing nanoclays, often used in multi-layer packaging for barrier enhancement.
Masterbatch sales are expanding most quickly due to ease of use; Powder remains a foundational form for large-volume processors.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
China's manufacturing centers drive significant nanoclay demand, particularly in polymer and electronics industries. This concentration influences global supply chains and product development strategies. Regulatory frameworks across major economies shape market access and material specifications.
China
China's large polymer and electronics manufacturing base creates substantial demand for nanoclay reinforcement. The Ministry of Ecology and Environment (MEE) imposes strict controls on new chemical substances. The Yangtze River Delta region, with its polymer compounding facilities, requires advanced material solutions.
Germany
Germany's automotive sector demands nanoclays for lightweighting and high-performance polymer applications. The European Union's REACH framework and CO2 emission standards influence material choices. Bavaria's automotive cluster integrates nanoclays for enhanced vehicle performance and fuel efficiency.
United States
The United States market sees strong demand from advanced packaging, industrial composites, and automotive sectors. The US Environmental Protection Agency (EPA) regulates nanoparticle safety under TSCA. The Gulf Coast's chemical manufacturing hub focuses on polymer and composite material innovation.
India
India's growing automotive manufacturing sector and consumer goods production drive increasing nanoclay adoption. The Bureau of Indian Standards (BIS) promotes material quality and safety in diverse applications. Chennai's automotive corridor is a key area where vehicle producers seek lightweighting solutions.
Japan
Japan's electronics and precision automotive components industries are significant nanoclay consumers. The Ministry of Economy, Trade and Industry (METI) supports advanced materials development. Tokyo's industrial belt sees electronics manufacturers integrating nanoclays for thermal stability and mechanical strength.
Global Nanoclay Reinforcement Market Key Industry Players
Player mix skews toward established chemical and specialty materials manufacturers. The market exhibits a tiered structure, with large diversified industrial conglomerates alongside niche advanced material science firms. Key strategic archetypes include organoclay specialists, rheology modifier providers, and proprietary composite system developers. Companies primarily focus on R&D investment to meet evolving performance demands and navigate complex regulatory landscapes.
Within the specialty chemical archetype, BYK Additives (ALTANA) represents expertise in organomodified clays for high-performance polymer applications. Elementis PLC occupies a position among broad portfolio providers, sustaining market presence through rheology modifiers and specialty additives. Meanwhile, 3M anchors the advanced material science segment, integrating nanoclays into proprietary composite systems for various industrial uses. These firms continuously refine product formulations to enhance compatibility and performance across diverse end-user sectors.
| Leading Market Players |
|---|
| AMCOL Corporation |
| BYK Additives (ALTANA) |
| Nanophase Technologies Corporation |
| 3M |
| Laviosa Chimic Mineraria SpA |
| Elementis PLC |
| RTP Company |
| Inframat Corporation |
| Sika AG |
Cost & Logistics Intelligence
European Union's REACH framework directly gates nanoclay product qualification and significantly influences price differentiation by mandating extensive safety data. This regulatory burden shapes both market access and the cost structure of compliant materials.
Pricing Analysis
Cost-plus contract patterns, often indexed to raw material silicate prices, dominate the nanoclay market for large-volume procurement. Price differentiation stems from the degree of organomodification, compliance with ISO/TS 19807 characterization standards, and the form of delivery (powder versus masterbatch). Pricing pressure intensifies from automotive and packaging industries seeking cost-effective lightweighting solutions. Polymer manufacturers purchasing raw powder are highly price-sensitive, while European automotive Tier 1 suppliers prioritize consistent masterbatch quality over lowest cost.
Supply Chain Analysis
Just-in-time inventory strategies are common among downstream polymer manufacturers, but specialized compounders maintain strategic stockpiles of key raw materials. Global supply concentrates in China, the United States, and Germany, reflecting manufacturing hubs and regulatory landscapes. The supply chain relies heavily on consistent access to high-purity mineral silicates and specialized organic modifiers. Raw material quality control from natural deposits presents a persistent operational risk, while distribution primarily runs through specialized compounders supplying pre-dispersed masterbatches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanoclay market is experiencing a notable buyer-power shift, driven by end-users increasingly procuring pre-dispersed masterbatches. This concentrates buying power with specialized compounders who guarantee dispersion quality.
For Market Incumbents: Compound R&D investment in next-generation organomodified nanoclays to counter substitution threats from graphene and carbon nanotubes. Secure long-term supply agreements for high-purity mineral silicates, mitigating raw material quality control risks. Invest in robust toxicological data and lifecycle assessments to meet evolving compliance demands from REACH and TSCA. This proactive approach defends against emerging material alternatives and regulatory pressures.
For New Entrants and Emerging Players: Bio-based material certifications offer a fast-track entry point into sustainable packaging and consumer goods segments. Target underpenetrated markets like India's automotive sector, leveraging demand for lightweighting solutions. Focus on developing specialized masterbatches for bio-polymer composites, offering ease of processing for plastics converters. A go-to-market strategy emphasizing sustainable material solutions and simplified processing can gain traction.
For Investors and Strategic Acquirers: Secondary-cycle assets sit with specialty chemical archetype firms possessing strong organomodified nanoclay expertise. The market shows long-term viability, driven by sustained demand for advanced material properties in automotive and packaging. Seek out vertically integrated compounders with established regulatory compliance frameworks and strong R&D pipelines. A key signal to watch is the adoption rate of nanoclay masterbatches in novel bio-polymer applications.
| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Expansion | Meets growing demand from China's polymer and electronics industries. |
| Backward Integration | Secures consistent supply of high-purity mineral silicates. |
| Green Manufacturing Transition | Aligns with circular economy goals through bio-polymer composites. |
| Joint Venture | Accelerates development of multifunctional nanoclay systems. |
| Product Launch | Introduces advanced masterbatches for European automotive supply chains. |
Research Approach
Demand-side practitioners and supply-side operators were both consulted through extensive primary interviews, complemented by rigorous secondary validation. Stakeholders included polymer R&D directors, automotive procurement specialists, packaging engineers, and regulatory affairs leads from major markets. Secondary sources encompassed ECHA and EPA regulatory filings, ISO standards publications, and industry association reports. This approach facilitated bottom-up market sizing and top-down validation of segment projections.
The analytical framework projects market trajectories across the analysis window, integrating historical trends with future outlooks. Segmentation dimensions modeled include product type, application, end-user industry, form, and key regional markets. Compound annual growth rates were derived from a comprehensive assessment of demand drivers and market restraints. Key industry-specific inputs included automotive lightweighting mandates and advanced packaging barrier property requirements.
Underlying assumptions cover current regulatory frameworks and technological development rates, with deviation risk concentrated in unforeseen shifts in nanomaterial safety regulations. Forecasts reflect these documented assumptions, but market dynamics can evolve rapidly. Revision becomes warranted when significant changes in raw material supply consistency or regulatory stringency cross critical thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Nanofilms Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanotechnology Market