
 Metal Nitride Nanoparticles Market | 2026-2036
Metal Nitride Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Metal Nitride Nanoparticles Market Foresight
Atomic-scale precision in nitride synthesis is rewriting how high-performance ceramics and semiconductor substrates are engineered. Merck KGaA leverages its pharmaceutical-grade chemical heritage to sustain ultrahigh-purity gallium nitride precursor supply chains. American Elements anchors North American production with in-house reduction and nitridation capabilities spanning aluminium and titanium nitride grades. Evonik Industries AG differentiates through surface-functionalized nanoparticle architectures tailored for catalytic and electronic applications.
Metal nitride nanoparticles are crystalline or amorphous particles typically 1–100 nm in diameter, composed of metallic elements bonded with nitrogen through high-temperature ammonolysis or plasma-assisted synthesis, valued for exceptional thermal conductivity, wide bandgap semiconducting behavior, and chemical stability under extreme conditions. Gallium nitride dominates volume flows into power electronics and RF amplification, while titanium nitride captures premium pricing in medical device coatings and diffusion barriers. The optoelectronics application segment is expanding fastest as solid-state lighting and laser diode manufacturers seek higher luminous efficacy and thermal management.
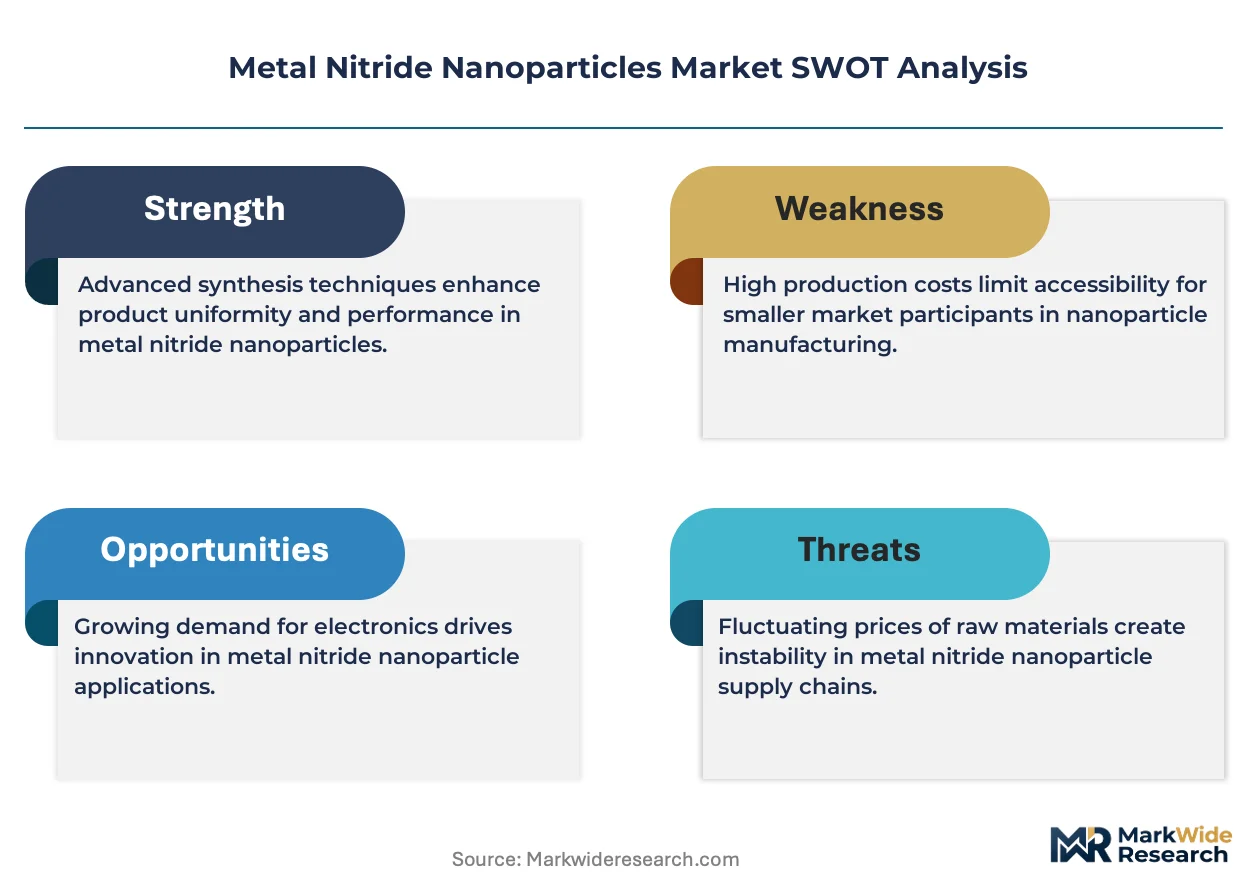
EPA oversight of nanomaterial environmental release and OSHA permissible exposure limits for refractory ceramic fibers are tightening workplace and discharge standards for U.S.-based producers. REACH registration requirements in Europe and China's GB standards for nanomaterial classification are creating divergent compliance pathways that fragment market access rules. Stakeholders must monitor how regulatory thresholds for particle size reporting and toxicity testing evolve, as these definitions determine which synthesis methods remain economically viable across jurisdictions.
Market Dynamics
Semiconductor manufacturers are consolidating gallium nitride sourcing around domestic wafer foundries, compressing supply chains and forcing precursor producers to co-locate near fabrication clusters.
Growth Catalysts
- EU Green Deal implementation:RoHS directive amendments are mandating higher-purity electronic components, accelerating gallium nitride substitution for silicon in power conversion systems.
- China's wafer foundry expansion:Domestic semiconductor fabrication capacity is concentrating nitride nanoparticle demand within the country's eastern coastal manufacturing corridors.
- Plasma-assisted synthesis maturation:This production method is enabling atomic-scale precision in titanium nitride coatings for medical device diffusion barriers.
Market Restraints
- Ammonia feedstock volatility:Natural gas price fluctuations directly impact ammonolysis production economics for aluminium nitride synthesis.
- Single-source precursor dependence:High-purity gallium metal supply concentrates among Chinese and German specialty chemical producers.
- REACH registration complexity:ECHA toxicity testing requirements for sub-100 nm particles are extending commercialization timelines for European entrants.
Strategic Opportunities
- India's PLI scheme for semiconductors:Government production-linked incentives are attracting nitride nanoparticle producers to establish local precursor facilities.
- Solid-state lighting convergence:Laser diode manufacturers are integrating gallium nitride substrates with silicon carbide heat spreaders for next-generation automotive headlamps.
- Direct-to-foundry distribution:Bypassing traditional chemical distributors is enabling producers to capture margin from semiconductor manufacturers seeking just-in-time delivery.
Industry Challenges
- Cleanroom technician scarcity:Nanoparticle synthesis facilities face recruitment gaps for operators qualified in inert atmosphere handling protocols.
- ISO 17025 certification timelines:Third-party laboratory accreditation for particle size distribution validation is extending quality assurance cycles by 8-14 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal Nitride Nanoparticles Market |
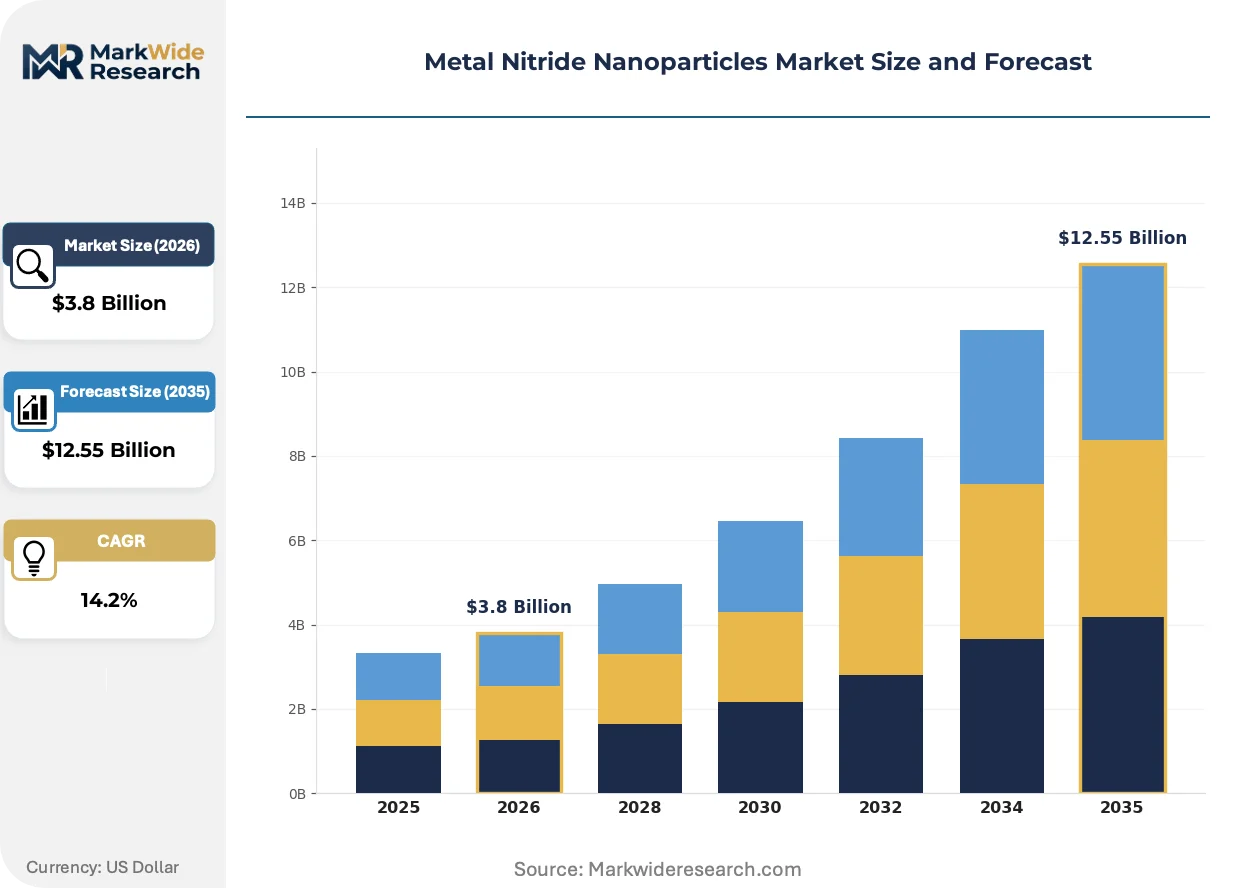
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $12.55 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Gallium Nitride, Aluminium Nitride, Indium Nitride, Titanium Nitride Application: Electronics, Optoelectronics, Photovoltaics, Catalysis End User: Aerospace, Automotive, Healthcare, Energy Technology: Synthesis Methods, Characterization Techniques, Fabrication Processes, Material Modifications |
| Companies Covered | SkySpring Nanomaterials, Inc., Merck KGaA, American Elements, ALB Materials, Inc., Spectrum Chemical Mfg., CeramTec North America, Evonik Industries AG, Toyo Aluminium K.K., AdTech Ceramics, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal Nitride Nanoparticles Market Shifts & Advancements
Atomic-scale engineering is compressing development cycles across nitride synthesis methods, with automation and regulatory alignment emerging as the dominant competitive differentiators.
Machine learning-driven process control is digitizing plasma-assisted synthesis parameters for gallium nitride production. Semiconductor substrate manufacturers in Taiwan and South Korea are adopting these systems to reduce batch-to-batch variance. This capability is digitizing quality assurance workflows that previously required manual electron microscopy verification.
REACH registration requirements are tightening disclosure thresholds for nanomaterial importers into the European Union. ECHA is mandating expanded toxicity datasets for particles below 50 nm diameter. Specialty chemical distributors serving German automotive electronics manufacturers are responding by pre-certifying entire product portfolios ahead of 2025 enforcement deadlines.
Long-term offtake agreements are displacing spot-market purchasing among power electronics manufacturers. Tier-one automotive suppliers in Japan are locking five-year gallium nitride precursor contracts directly with synthesis facilities. This pattern is most visible in the Kansai industrial corridor, where vertical integration between substrate producers and device fabricators is eliminating intermediary chemical traders.
Metal Nitride Nanoparticles Market Segmentation
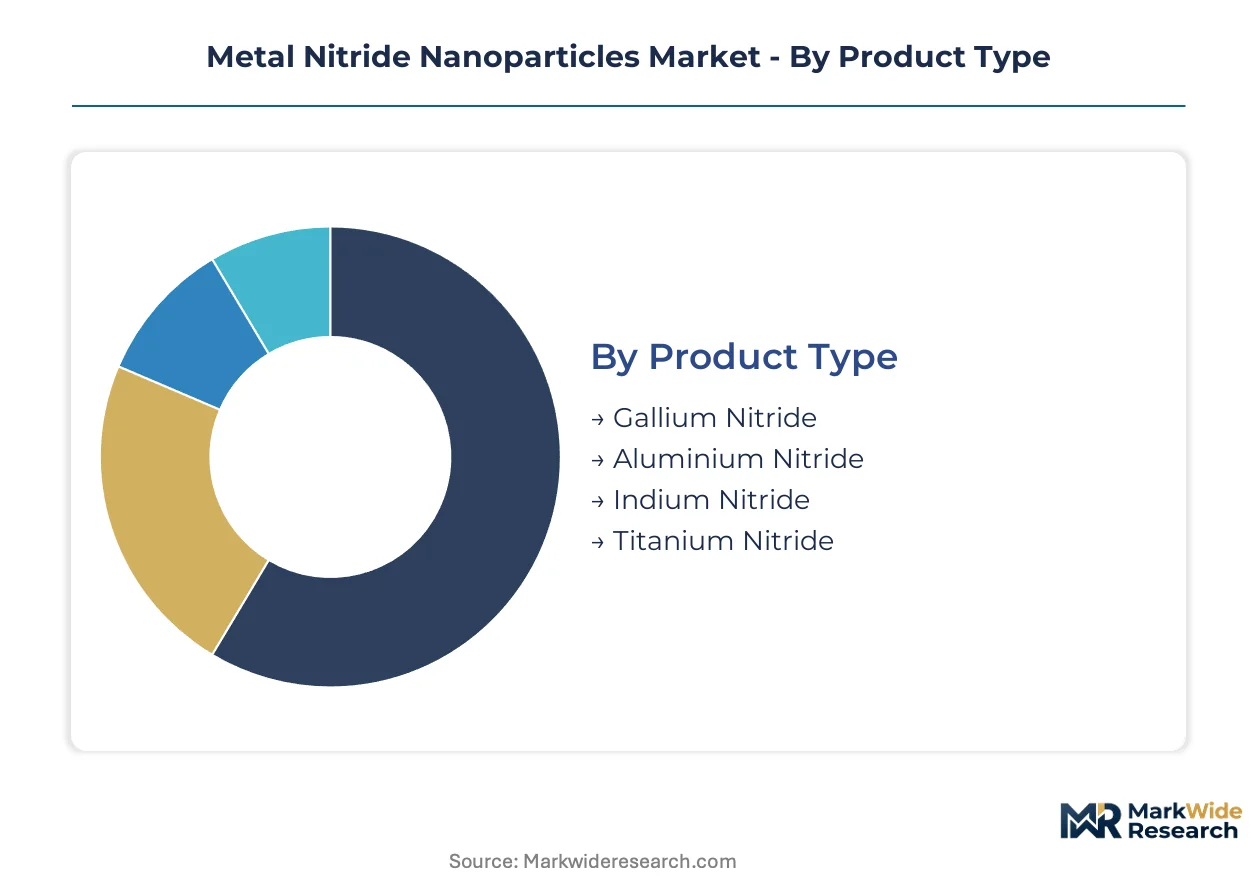
Metal nitride nanoparticles serve divergent performance requirements across power electronics, thermal management, and catalytic systems. Precise segmentation reveals how synthesis methods, purity grades, and surface functionalization determine addressable end-use markets and margin structures.
Product Type:
Each nitride compound occupies distinct positions on the thermal conductivity–bandgap spectrum, creating specialized supply chains tied to specific device architectures.
- Gallium Nitride:Wide bandgap semiconductor enabling high-frequency power conversion and RF amplification. Wafer foundries in Taiwan and South Korea are locking in multi-year precursor contracts to secure supply for electric vehicle inverters and 5G base stations.
- Titanium Nitride:Ceramic-metallic composite valued for extreme hardness and biocompatibility in implantable medical devices. German surgical instrument manufacturers are specifying sub-50 nm particle distributions to achieve uniform diffusion barrier performance.
- Aluminium Nitride:Thermal interface material with exceptional heat spreading capability for high-brightness LED packages.
- Indium Nitride:Narrow bandgap semiconductor under development for terahertz sensing and infrared optoelectronics.
The dominant share belongs to Gallium Nitride, while Titanium Nitride is closing the gap fastest.
Application:
End-use requirements cascade backward into particle size specifications, surface chemistry, and dispersion stability demands.
- Electronics:Power management substrates and gate drivers for wide bandgap semiconductor devices. Japanese automotive suppliers are integrating gallium nitride power modules into onboard chargers, tightening tolerance requirements for precursor purity.
- Optoelectronics:Solid-state lighting and laser diode substrates where luminous efficacy depends on crystalline defect density. Chinese LED packaging houses are scaling micro-LED production, pulling ultrahigh-purity nitride demand toward eastern coastal manufacturing corridors.
- Photovoltaics:Antireflection coatings and passivation layers for concentrated solar power receivers.
- Catalysis:Support structures for ammonia synthesis and hydrogenation reactions in chemical processing.
Electronics commands the largest revenue pool, though Optoelectronics is climbing the fastest as micro-LED commercialization accelerates.
End User:
Industry-specific certification regimes fragment procurement standards, with aerospace and healthcare imposing the most stringent traceability requirements.
- Aerospace:Thermal protection systems and radar components operating under extreme thermal cycling. US defense contractors are qualifying domestic nitride nanoparticle sources to satisfy DFARS supply chain security mandates.
- Automotive:Traction inverters and onboard charging systems for battery electric vehicles. South Korean battery manufacturers are specifying gallium nitride power stages to reduce switching losses and extend driving range.
- Healthcare:Orthopedic implants and surgical instruments requiring biocompatible ceramic coatings.
- Energy:Grid-scale power conversion and renewable integration infrastructure.
Automotive generates the highest volume uptake, with Aerospace exhibiting the steepest expansion trajectory as defense electronics modernization programs scale.
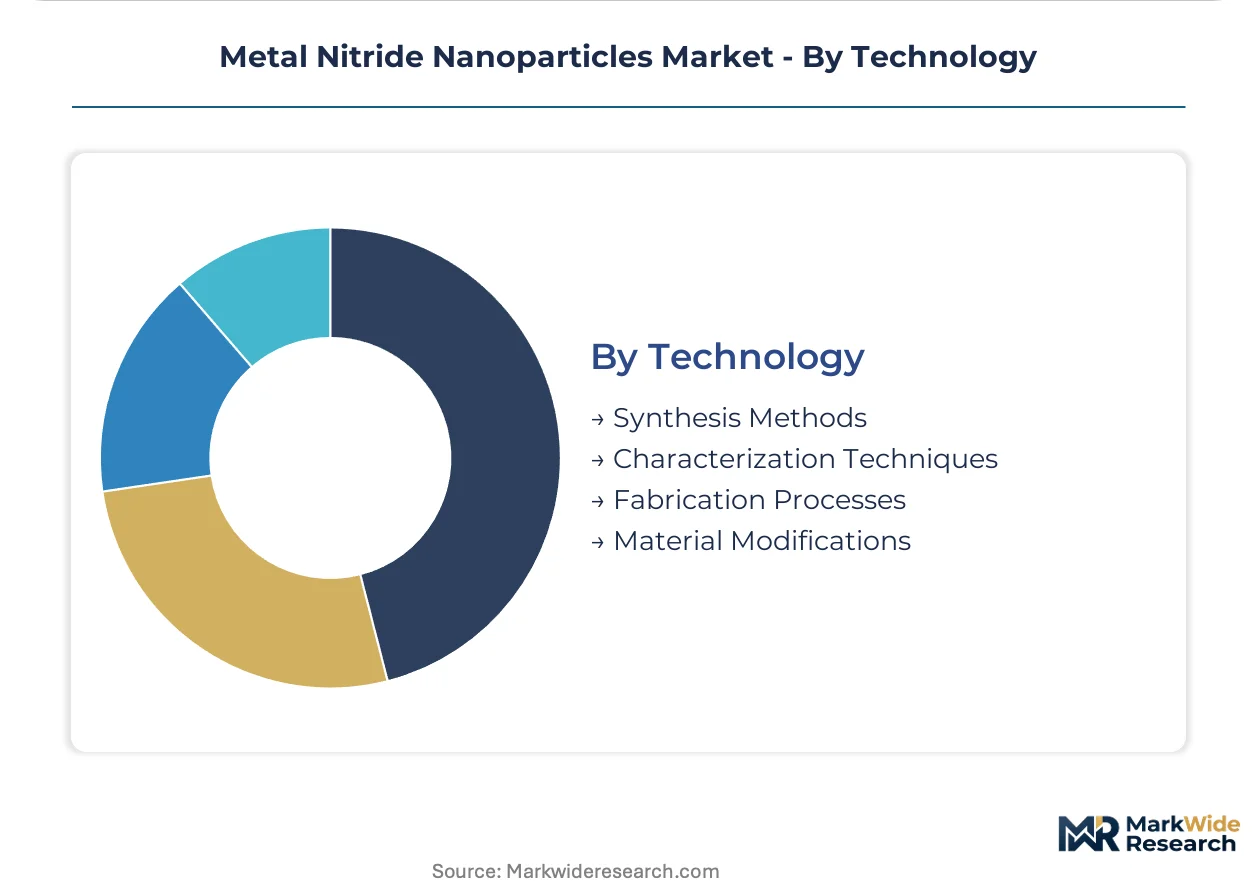
Technology:
Process maturity determines capital intensity, batch consistency, and regulatory compliance burden across production pathways.
- Synthesis Methods:Ammonolysis, plasma-assisted nitridation, and chemical vapor condensation each yield distinct particle morphologies. German specialty chemical producers are automating plasma reactor controls to reduce batch-to-batch variance for automotive electronics customers.
- Characterization Techniques:Electron microscopy, dynamic light scattering, and X-ray diffraction for particle size distribution validation. ISO 17025 accreditation timelines are extending quality assurance cycles by 8-14 months for new market entrants.
- Fabrication Processes:Thin-film deposition and bulk ceramic sintering adapted to nanoparticle feedstocks.
- Material Modifications:Surface functionalization and core-shell architectures for enhanced dispersion stability.
Synthesis Methods anchors commercial production scale, while Characterization Techniques is gaining share fastest as regulatory disclosure requirements tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Wafer foundries and power electronics manufacturers concentrate nitride nanoparticle procurement in four countries where semiconductor fabrication clusters and defense electronics programs overlap.
China
Domestic wafer foundries in Shanghai and Hefei are locking multi-year gallium nitride precursor contracts with local synthesis facilities. MIIT's semiconductor self-sufficiency directives accelerate import substitution for high-purity nitrides. The Yangtze River Delta manufacturing corridor now hosts vertically integrated nitride nanoparticle-to-substrate operations serving electric vehicle inverter producers.
United States
Defense contractors in Arizona and Texas are qualifying domestic nitride sources to satisfy DFARS supply chain security mandates for radar and thermal protection systems. EPA oversight of nanomaterial environmental release tightens discharge standards for New Mexico-based production facilities. The Southwest semiconductor cluster near Phoenix is pulling precursor producers to co-locate near advanced packaging fabs.
Germany
Automotive electronics suppliers in Bavaria are specifying sub-50 nm titanium nitride distributions for power module diffusion barriers. ECHA's REACH registration requirements for sub-100 nm particles extend commercialization timelines for new market entrants. The Munich-Stuttgart industrial corridor anchors European demand for plasma-assisted synthesis capabilities.
Japan
Tier-one automotive suppliers in the Kansai region are locking five-year gallium nitride precursor contracts directly with synthesis facilities. METI's critical materials security programs prioritize domestic nitride inventory buffers for power electronics supply chains. Osaka-based substrate producers are eliminating intermediary chemical traders through backward integration into precursor sourcing.
South Korea
Battery manufacturers in Gyeonggi Province are specifying gallium nitride power stages to reduce switching losses in traction inverters. MFDS nanomaterial classification standards align with corporate ESG disclosure requirements for semiconductor supply chains. The Seoul Capital Area's foundry cluster is compressing supply chains by forcing precursor producers to locate within two-hour logistics windows.
Metal Nitride Nanoparticles Market Competitive Landscape
Channel-controlling players compete with product-specialist players across three tiers. Consolidation concentrates among German and American chemical conglomerates with in-house nitridation capabilities, while Japanese and Korean ceramic specialists occupy premium niches. Strategic archetypes include pharmaceutical-grade purity suppliers, plasma-assisted synthesis automation leaders, and surface-functionalization architects. Dominant competitive moves span backward integration into precursor metal sourcing and direct-to-foundry distribution bypassing traditional chemical traders.
Within the purity-tier vector, Merck KGaA exemplifies pharmaceutical-grade chemical heritage applied to ultrahigh-purity gallium nitride supply chains. American Elements anchors North American production with in-house reduction capabilities spanning multiple nitride grades. Evonik Industries AG occupies a position among surface-functionalization architects tailoring nanoparticle architectures for electronic and catalytic applications.
| Leading Market Players |
|---|
| SkySpring Nanomaterials, Inc. |
| Merck KGaA |
| American Elements |
| ALB Materials, Inc. |
| Spectrum Chemical Mfg. |
| CeramTec North America |
| Evonik Industries AG |
| Toyo Aluminium K.K. |
| AdTech Ceramics |
| Others |
Supply & Pricing Matrix
Overcapacity in Chinese ammonolysis reactors is compressing spot pricing for aluminium nitride precursors while forcing European producers toward long-term offtake structures indexed to natural gas benchmarks. This utilization divergence rewards producers with captive ammonia supply and punishes merchant-market participants exposed to feedstock volatility.
Pricing Analysis
Cost-plus contracts indexed to ammonia futures dominate procurement for high-volume electronics customers, with premium tiers separating pharmaceutical-grade gallium nitride from industrial-grade titanium nitride based on ISO 17025 certification status. Price differentiation hinges on particle size distribution validation and REACH pre-registration status, with automotive electronics buyers exhibiting lowest price sensitivity due to qualification lock-in effects. Cost compression in standard-grade aluminium nitride is intensifying because Chinese wafer foundries are consolidating supplier panels.
Supply Chain Analysis
Tariff exposure between Germany and China dominates supply chain risk calculations for European automotive electronics suppliers dependent on high-purity gallium metal feedstock. Production concentrates in China, Germany, and Japan, with precursor synthesis drawing from Chinese rare earth refining, German specialty chemical processing, and Japanese ceramic powder expertise. Single-source vulnerability in high-purity gallium metal concentrates among Chinese and German producers. Distribution runs through direct-to-foundry channels bypassing traditional chemical distributors.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a defensive-moat story where regulatory entrenchment through REACH registration and ISO 17025 certification creates switching costs that protect qualified supplier relationships.
For Market Incumbents: Harden supply security through backward integration into gallium metal refining or ammonolysis capacity addition in the Yangtze River Delta. Incumbents must deepen certification moats against emerging Chinese producers by accelerating ECHA toxicity dataset completion ahead of enforcement deadlines. Channel control through direct-to-foundry distribution locks out trader intermediaries. For New Entrants and Emerging Players: India's semiconductor PLI scheme offers the most penetrable geographic entry point for nitride precursor facilities serving domestic wafer foundry demand. New entrants should target medical device coatings as the least saturated application segment, exploiting sub-50 nm titanium nitrile specification gaps left by incumbent capacity constraints. A go-to-market angle anchored to ISO 13485 medical device quality certification accelerates hospital system qualification. For Investors and Strategic Acquirers: Long-term, this sits as a specialty-chemical consolidation play because regulatory compliance burdens and capital intensity favor scaled producers with existing certification infrastructure. Acquisition targets include mid-cap plasma-assisted synthesis specialists with automated reactor controls and established automotive electronics customer relationships. The signal to watch is DFARS supply chain security mandate expansion requiring domestic nitride sourcing for defense applications.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Metal Sourcing | Captive gallium supply from Chinese or German refiners insulates against feedstock volatility and single-source risk. |
| Plasma Reactor Automation Investment | German automotive electronics customers demand batch-to-batch variance below 3% for diffusion barrier applications. |
| REACH Pre-Certification Program | ECHA disclosure thresholds for sub-50 nm particles require expanded toxicity datasets ahead of enforcement deadlines. |
| Direct-to-Foundry Distribution Buildout | Semiconductor manufacturers in Taiwan and South Korea seek just-in-time delivery bypassing chemical traders. |
| Medical Device Quality Certification | ISO 13485 alignment opens orthopedic implant and surgical instrument coating opportunities with premium pricing. |
Research Methodology
A spread of perspectives from nitride synthesis plant managers, wafer foundry procurement leads, automotive electronics Tier 1 suppliers, and ECHA regulatory affairs specialists converged on the working assumptions. Primary fieldwork combined with secondary validation from SEC filings of specialty chemical producers, MIIT semiconductor industry directives, and customs trade data for gallium metal imports. Bottom-up capacity modeling and top-down demand projection from power electronics and optoelectronics application segments were triangulated.
Demand-supply balance dynamics across the analysis window anchored the forecast framework, with segmentation across nitride compound type, synthesis method maturity, and end-use industry certification requirements. CAGRs derived from capacity utilization trends, import substitution rates in Chinese wafer fabrication, and automotive electrification content-per-vehicle trajectories. Industry-specific inputs included plasma reactor automation adoption curves and REACH registration completion timelines.
Practitioners should monitor ammonia feedstock price volatility, DFARS supply chain security mandate scope expansion, and ECHA nanomaterial disclosure threshold revisions for early signals. Forecasts reflect assumptions about semiconductor fabrication capacity expansion, electric vehicle inverter adoption rates, and regulatory enforcement intensity that remain subject to operating conditions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Graphene Nanocomposites Market