
 Nano Zinc Oxide Market | 2026-2036
Nano Zinc Oxide Market Size, Share, and Industry Trends Forecast 2026-2036
Nano Zinc Oxide Market Analysis
Particle surface functionalization is tilting manufacturing priorities toward coated variants with enhanced dispersion stability. BASF SE leverages its polymer science heritage to anchor premium cosmetic-grade supply chains. Sakai Chemical Industry Co. Ltd. sustains cost leadership through integrated zinc refining operations in East Asia. EverZinc competes on volume scale across European rubber and coatings accounts.
Nano zinc oxide denotes zinc oxide engineered at sub-100 nanometer dimensions, typically synthesized via sol-gel, precipitation, or vapor-phase methods to achieve high surface area, UV absorption, and catalytic activity; its primary commercial purpose spans UV protection, antimicrobial functionality, and electronic conductivity enhancement. The coated product type dominates margin pools in cosmetic and pharmaceutical channels where dispersion stability commands premium pricing, while uncoated grades lead volume in rubber vulcanization and industrial coatings. Electronics applications represent the fastest-growing segment as miniaturized devices demand precise semiconducting and piezoelectric properties from nanoscale metal oxides.
REACH registration requirements and the EU Cosmetics Regulation govern nano-material hazard communication and safety dossiers in Europe, while FDA guidance on nanotechnology in cosmetics shapes formulation standards and import compliance in the United States. China's GB standards for nano-material characterization and the National Medical Products Administration oversight of sunscreen additives create a multi-jurisdictional compliance matrix that favors suppliers with certified testing infrastructure. Stakeholders must monitor evolving nano-specific labeling mandates and pre-market notification thresholds as regulatory divergence between major economies intensifies qualification burdens.
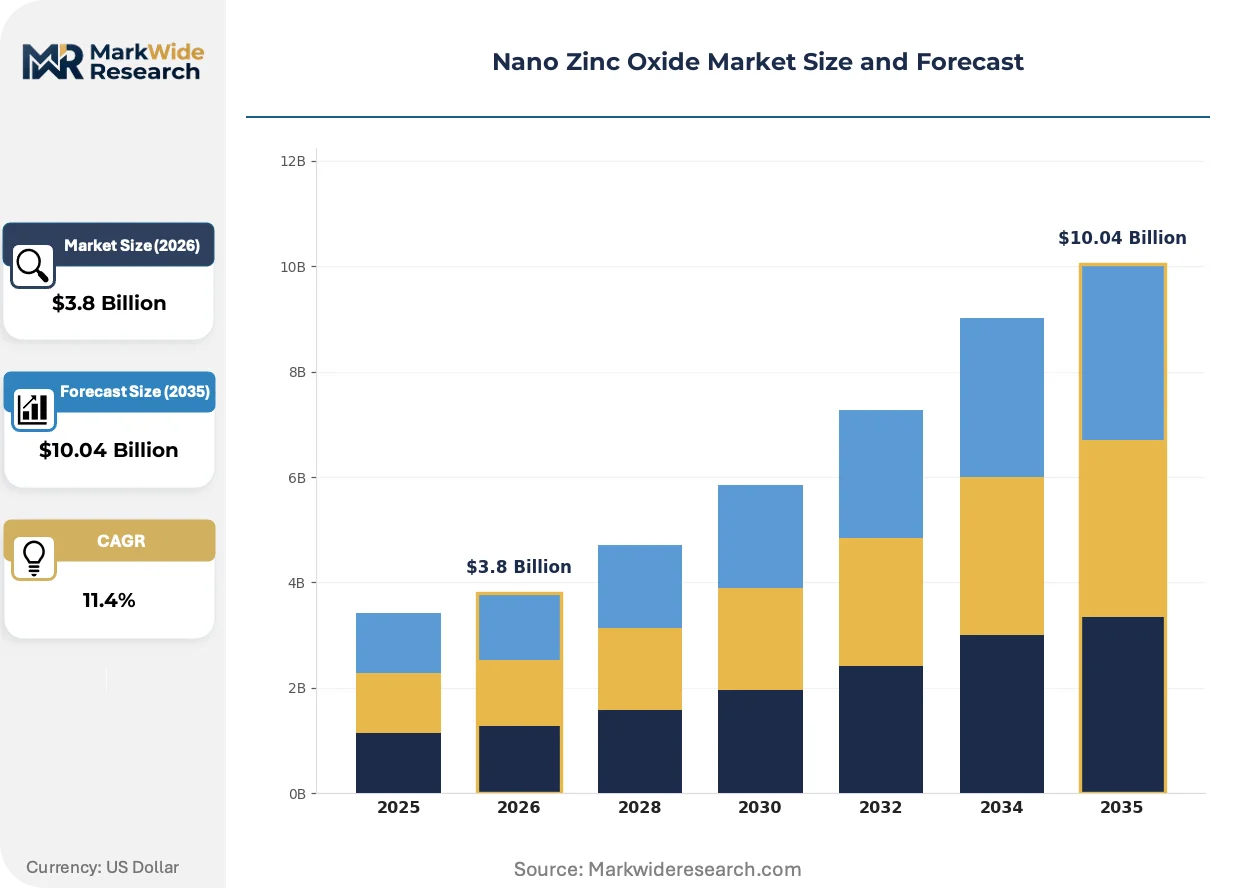
Market Dynamics
Surface functionalization chemistry is redrawing competitive boundaries as coated nano zinc oxide variants capture premium positioning in cosmetic and pharmaceutical channels while uncoated grades commoditize in industrial applications.
Growth Catalysts
- REACH nano-registration mandates:European ECHA dossier requirements for nano-material hazard communication are accelerating supplier consolidation toward certified testing infrastructure, favoring incumbents with pre-existing registration assets.
- Electronics miniaturization:Semiconductor and piezoelectric applications in advanced packaging are absorbing higher-purity nano zinc oxide volumes as device geometries shrink below 10 nanometer nodes.
- China rubber processing clusters:Concentrated tire manufacturing in Shandong and Jiangsu provinces is driving bulk procurement of uncoated grades for vulcanization acceleration.
Market Restraints
- Metallic zinc price volatility:Feedstock cost swings from Nyrstar and Glencore smelter operations compress margin predictability for precipitation-route producers.
- East Asian supply concentration:Integrated zinc refining and nano-oxide synthesis capacity clusters in Japan and China create geographic dependency risk for European and North American formulators.
- Titanium dioxide substitution:Cosmetic brands are reformulating toward alternative mineral UV filters where dispersion stability requirements permit, pressuring nano zinc oxide volume in premium sunscreen.
Strategic Opportunities
- India pharmaceutical excipient qualification:CDSCO accelerated approval pathways for nano-material drug delivery systems are opening formulation partnerships with domestic generic manufacturers.
- Antimicrobial textile finishing:Post-pandemic hospital linen and activewear specifications are incorporating nano zinc oxide for durable biocidal functionality against methicillin-resistant pathogens.
- US Inflation Reduction Act clean manufacturing credits:Domestic production incentives for low-carbon nano-material synthesis are attracting greenfield investment in electrochemical reduction routes.
Industry Challenges
- Colloidal stability formulation expertise:Cosmetic houses lack in-house dispersion science capability, forcing reliance on toll manufacturers for coated particle integration.
- ISO/TS 80004 nano-characterization certification:Extended third-party validation timelines for particle size distribution and surface area metrics delay new supplier qualification by 12-18 months.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nano Zinc Oxide Market |
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $10.04 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Coated, Uncoated, Nano Powders, Sols Application: Cosmetics, Electronics, Rubber, Coatings End User: Beauty Industry, Automotive Sector, Electronics Manufacturers, Paint Producers Distribution Channel: Online Retail, Distributors, Direct Sales, Wholesalers |
| Companies Covered | Grillo-Werke AG, Sakai Chemical Industry Co. Ltd., BASF SE, Pan-Continental Chemical Co. Ltd., Showa Denko Materials Co. Ltd., EverZinc, Nanophase Technologies Corporation, Inframat Advanced Materials LLC, Umicore, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nano Zinc Oxide Market Emerging Trajectories
Computational materials science and automated synthesis control are compressing development cycles for tailored nano zinc oxide morphologies, shifting competitive advantage from scale economies to precision engineering.
Silane and polymer surface coating technology is virtualizing the traditional distinction between cosmetic-grade and industrial-grade supply tiers. Sol-gel derived particles with covalently bound dispersant layers are penetrating sunscreen and dermal care formulations at price points previously associated with uncoated rubber additives. Korean and Japanese cosmetic houses are adopting these hybrids at contract volumes that exceed prior coated-grade forecasts.
EU F-Gas Regulation phase-down schedules are indirectly tightening purity requirements for nano zinc oxide used in semiconductor etching processes. Gas-phase synthesis routes employing fluorinated precursors face substitution pressure, pushing equipment manufacturers toward aqueous precipitation alternatives with equivalent particle size control. German and Dutch specialty chemical sites are retooling reactor configurations to meet this specification migration.
Direct procurement from synthesis specialists is displacing merchant distributor relationships in North American electronics and coatings verticals. Large compounders in Texas and California are establishing annual volume commitments with Japanese and Chinese producers, bypassing regional chemical distributors that previously managed inventory and technical service. This channel compression concentrates price negotiation leverage with buyers possessing certified incoming inspection protocols.
Nano Zinc Oxide Market Segmentation
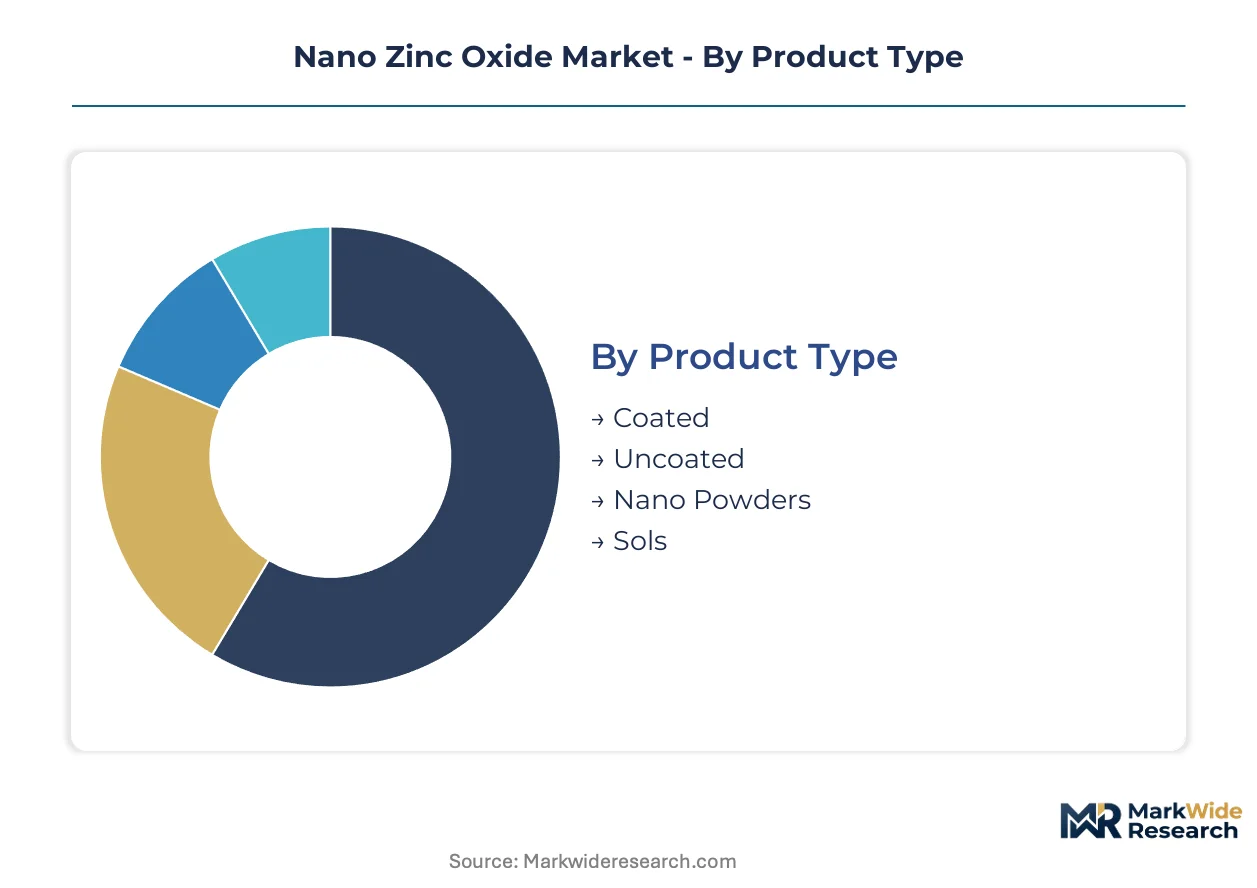
Segmentation in nano zinc oxide markets separates premium cosmetic-grade supply chains from commodity industrial flows. Technical service intensity, certification requirements, and formulation support needs vary dramatically across product tiers and end-use verticals.
Product Type:
After-sales service intensity peaks with coated variants requiring dispersion troubleshooting and stability guarantees, while uncoated grades demand minimal technical support.
- Coated:Silane, polymer, or surfactant surface layers covalently bound to particle surfaces enhance colloidal stability in polar and non-polar matrices. Cosmetic formulators in France and South Korea specify coated grades for sunscreen emulsions where aggregation would compromise SPF efficacy and aesthetic transparency. REACH nano-registration dossiers and ISO/TS 80004 certification requirements concentrate supply among incumbents with pre-existing testing infrastructure.
- Uncoated:Bare zinc oxide nanoparticles synthesized via precipitation or vapor-phase routes offer lower unit costs but inferior dispersion stability. Tire manufacturers in Shandong province absorb bulk volumes for rubber vulcanization acceleration where particle agglomeration poses minimal performance penalties. Metallic zinc feedstock volatility from Nyrstar and Glencore smelter operations compresses margin predictability for precipitation-route producers.
- Nano Powders:Dry particulate forms with controlled agglomerate size distribution suit powder coating and masterbatch compounding operations.
- Sols:Colloidal aqueous or organic dispersions with pre-stabilized particle populations reduce formulation complexity for cosmetic houses lacking in-house dispersion science capability.
Coated holds the largest share; momentum sits with sols as toll manufacturing partnerships proliferate.
Application:
Margin structures diverge sharply between pharmaceutical-grade cosmetic applications and industrial rubber and coatings volumes.
- Cosmetics:Sunscreen and dermal care formulations demand sub-50 nanometer particles with narrow size distribution for UV absorption without visible whitening. FDA guidance on nanotechnology in cosmetics and EU Cosmetics Regulation nano-labeling mandates shape formulation standards and import compliance. Titanium dioxide substitution pressure from reformulating brands constrains volume growth in premium segments.
- Electronics:Semiconductor packaging, piezoelectric devices, and transparent conductive films require high-purity grades with precise morphological control. Device geometries shrinking below 10 nanometer nodes are absorbing higher-purity volumes as miniaturization advances. EU F-Gas Regulation phase-down schedules are indirectly tightening purity requirements for etching process materials.
- Rubber:Vulcanization acceleration in tire manufacturing concentrates demand in China's Shandong and Jiangsu processing clusters.
- Coatings:Antimicrobial and UV-protective industrial finishes utilize uncoated grades where dispersion stability requirements are less stringent.
Cosmetics commands premium pricing; electronics is climbing the fastest on semiconductor packaging demand.
End User:
Procurement sophistication separates specification-driven electronics manufacturers from price-sensitive automotive compounders.
- Beauty Industry:Cosmetic houses and contract manufacturers source certified cosmetic-grade material with full safety dossiers and regulatory compliance documentation. Korean and Japanese formulators are adopting hybrid sol-gel particles at contract volumes exceeding prior coated-grade forecasts.
- Electronics Manufacturers:Advanced packaging specialists in Texas and California establish direct annual volume commitments with Japanese and Chinese synthesis specialists, bypassing regional distributors.
- Automotive Sector:Tire producers and coatings applicators prioritize cost efficiency and supply security over technical service intensity.
- Paint Producers:Industrial coatings formulators balance antimicrobial functionality claims against raw material cost pressures.
Beauty Industry generates highest per-kilogram margins; Electronics Manufacturers are expanding procurement fastest through direct channels.
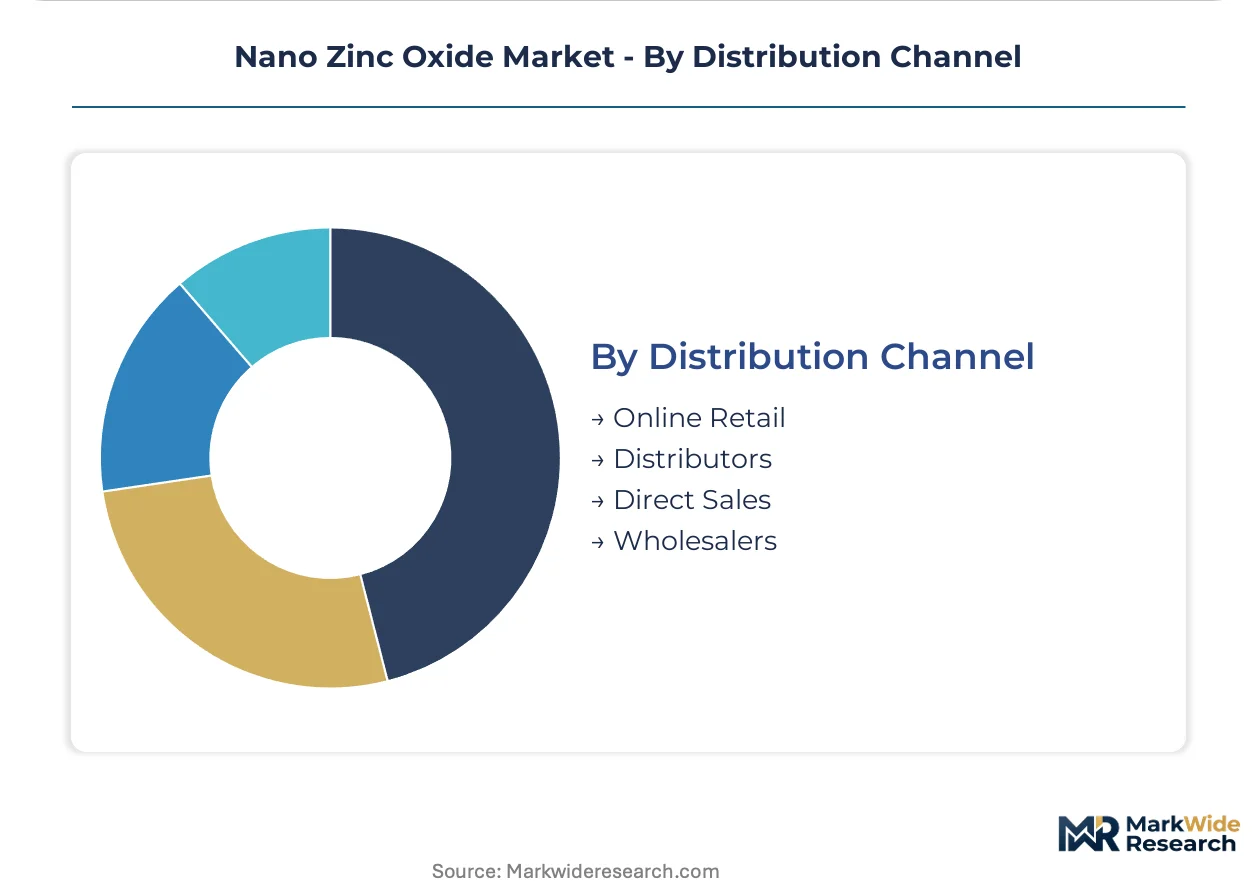
Distribution Channel:
Channel compression is redrawing intermediary economics as qualified buyers consolidate supplier relationships.
- Direct Sales:Large compounders with certified incoming inspection protocols negotiate annual volume commitments directly with synthesis specialists in Japan and China. This channel captures price negotiation leverage and technical service customization unavailable through intermediaries.
- Distributors:Regional chemical distributors manage inventory, credit terms, and basic technical service for mid-tier formulators lacking procurement scale. Channel compression in North American electronics and coatings verticals is eroding this intermediary role.
- Online Retail:Small-volume cosmetic and research-grade procurement through specialized chemical marketplaces serves formulation laboratories and independent chemists.
- Wholesalers:Bulk uncoated grade flows to rubber processing clusters through traditional commodity chemical channels with minimal value-added services.
Distributors retain largest volume share; Direct Sales is gaining share fastest as buyer qualification capabilities mature.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Chinese synthesis specialists export bulk uncoated grades to rubber processors in Germany and cosmetic formulators in France, while Japanese producers supply high-purity electronics-grade material to semiconductor packaging facilities in Texas and California.
China
Shandong and Jiangsu tire manufacturing clusters absorb significant uncoated nano zinc oxide volumes for vulcanization acceleration. The National Medical Products Administration oversees sunscreen additive safety dossiers under evolving GB standards for nano-material characterization. Integrated zinc refining and nano-oxide synthesis capacity in East China creates concentrated supply infrastructure serving both domestic rubber processors and export cosmetic channels.
United States
Semiconductor packaging specialists in Texas and California establish direct procurement relationships with Asian synthesis specialists for high-purity electronics grades. FDA guidance on nanotechnology in cosmetics shapes formulation standards and import compliance requirements for sunscreen manufacturers. The Inflation Reduction Act's clean manufacturing credits attract greenfield investment in electrochemical reduction routes for domestic nano-material production.
Germany
REACH nano-registration mandates through ECHA accelerate supplier consolidation toward certified testing infrastructure for cosmetic and pharmaceutical applications. The EU F-Gas Regulation phase-down indirectly tightens purity requirements for semiconductor etching process materials. Specialty chemical sites in North Rhine-Westphalia and Bavaria retool reactor configurations toward aqueous precipitation alternatives as fluorinated precursor routes face substitution pressure.
Japan
Korean and Japanese cosmetic houses adopt hybrid sol-gel particles at contract volumes exceeding prior coated-grade forecasts. METI oversight aligns with international OECD nano-safety guidelines for cross-border trade facilitation. Integrated zinc refining operations in East Asia sustain cost leadership through captive feedstock supply serving regional electronics and beauty industry demand.
India
CDSCO accelerated approval pathways for nano-material drug delivery systems open formulation partnerships with domestic generic pharmaceutical manufacturers. BIS standards for nano-material characterization create qualification frameworks for import substitution initiatives. Western and Southern industrial corridors develop toll manufacturing partnerships for coated particle integration serving cosmetic houses lacking in-house dispersion science capability.
Nano Zinc Oxide Market Vendor Landscape
On the supply side, the industry is consolidating around three strategic tiers: integrated zinc refiners with captive nano-oxide synthesis, specialty chemical houses with polymer science heritage, and precision synthesis specialists serving electronics-grade specifications. Market structure favors incumbents with pre-existing REACH registration assets and ISO/TS 80004 certification infrastructure. Dominant competitive moves include direct procurement relationship establishment with qualified buyers and surface functionalization chemistry investments to capture cosmetic-grade premium positioning.
Among German-anchored chemical conglomerates, BASF SE and Grillo-Werke AG exemplify the integrated specialty chemical archetype with polymer science heritage enabling premium cosmetic-grade supply chains. Japanese producers including Sakai Chemical Industry Co. Ltd. and Showa Denko Materials Co. Ltd. represent the precision synthesis specialist tier with integrated zinc refining operations sustaining cost leadership in East Asian markets. EverZinc occupies a position within the European volume-scale segment serving rubber and coatings accounts through established distributor relationships.
| Leading Market Players |
|---|
| Grillo-Werke AG |
| Sakai Chemical Industry Co. Ltd. |
| BASF SE |
| Pan-Continental Chemical Co. Ltd. |
| Showa Denko Materials Co. Ltd. |
| EverZinc |
| Nanophase Technologies Corporation |
| Inframat Advanced Materials LLC |
| Umicore |
| Others |
Supply Flow & Price Mechanics
Overcapacity in Chinese precipitation-route synthesis is compressing margin buffers for uncoated grades while tightening supply of certified cosmetic-grade material. This utilization divergence rewards incumbents with REACH dossiers and ISO/TS 80004 infrastructure while forcing commodity producers toward toll-manufacturing partnerships.
Pricing Analysis
Sol-gel derived cosmetic-grade particles command substantial premiums over legacy precipitation-route material, while next-generation aqueous-phase electronics grades are resetting purity benchmarks. Three-tier pricing structure across premium cosmetic, standard industrial, and economy rubber grades reflects certification burden and dispersion stability guarantees. Price differentiation hinges on REACH nano-registration status and ISO/TS 80004 particle characterization certification. Cost compression in uncoated rubber grades is intensifying because metallic zinc feedstock volatility from Nyrstar and Glencore smelter operations transmits directly to contract pricing. Tire manufacturers in Shandong province exhibit highest price sensitivity; semiconductor packaging specialists in Texas and California show lowest sensitivity due to specification-locked supply agreements.
Supply Chain Analysis
Toll-manufacturing concentration in Korean and Japanese cosmetic formulation houses absorbs growing volumes of pre-dispersed sols for sunscreen emulsions. Geographic supply concentrates in China, Japan, and Germany, with Chinese integrated zinc refiners feeding rubber processors and Japanese precision synthesis specialists serving electronics accounts. Raw material dependencies rest on metallic zinc cathode supply from Nyrstar and Glencore operations, silane coupling agents from German specialty chemical producers, and fluorinated precursors facing EU F-Gas Regulation phase-down pressure. Single-source vulnerability runs through East Asian high-purity electronics-grade capacity clusters. Distribution runs through direct annual volume commitments with qualified compounders displacing regional chemical distributors in North American electronics verticals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Dispersion-science technical service is expanding faster than base material sales as cosmetic houses outsource colloidal stability formulation to toll manufacturers. This service-attach dynamic elevates suppliers with in-house dispersion capability above commodity synthesis specialists.
For Market Incumbents: Insulate premium positioning by deepening backward integration into silane and polymer surface coating chemistry, and by expanding certified testing infrastructure to accelerate new customer qualification timelines. Titanium dioxide substitution pressure in premium sunscreen segments threatens volume retention; counter by locking Korean and Japanese cosmetic houses into multi-year sol supply agreements with embedded technical service tiers. For New Entrants and Emerging Players: Build out CDSCO-aligned nano-material drug delivery qualification capabilities to capture Indian pharmaceutical excipient partnerships, and establish toll-manufacturing relationships with domestic generic producers lacking in-house dispersion science. The most penetrable white-space sits in antimicrobial textile finishing for post-pandemic hospital linen specifications. Lead with durability-testing data against methicillin-resistant pathogens to differentiate from commodity biocide suppliers. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among precision synthesis specialists with embedded formulation partnerships and annual volume commitments from qualified electronics buyers. Long-term viability over the next decade favors suppliers with dual-use capability across cosmetic-grade and electronics-grade certification tiers. Acquisition target archetype: mid-cap synthesis specialists with pre-existing REACH registration assets and underutilized aqueous precipitation reactor capacity. Monitor EU F-Gas Regulation implementation timelines as inflection signal for gas-phase route substitution demand.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Surface Coating Chemistry | Captures margin pools from silane and polymer dispersant layers that cosmetic formulators currently source separately. |
| CDSCO Nano-Material Qualification Investment | Opens formulation partnerships with Indian generic pharmaceutical manufacturers accelerating drug delivery system approvals. |
| Aqueous Precipitation Reactor Retooling | Positions German and Dutch specialty chemical sites to meet EU F-Gas Regulation-driven purity specification migration. |
| Direct Procurement Relationship Establishment | Concentrates price negotiation leverage with Texas and California semiconductor packaging specialists bypassing distributors. |
| Antimicrobial Textile Finishing Partnership | Secures durable biocidal functionality specifications from post-pandemic hospital linen and activewear producers. |
Methodological Framework
The analysis maps coated and uncoated product tiers, cosmetic and electronics application verticals, and direct versus distributor channel flows, each validated through synthesis plant managers, cosmetic formulation scientists, semiconductor packaging procurement leads, and tire manufacturer technical directors. Primary interview data triangulates against customs and trade flow databases, ECHA REACH registration filings, SEC 10-K disclosures from listed chemical conglomerates, and CDSCO approval pathway documentation. Bottom-up volume estimates from named production facilities reconcile with top-down demand aggregation from end-use sector consumption patterns.
Forecast assumptions hold fixed current regulatory frameworks including REACH nano-registration mandates, FDA nanotechnology guidance, and EU F-Gas Regulation phase-down schedules, while varying metallic zinc feedstock cost trajectories and electronics miniaturization penetration rates across the projection horizon. Segmentation dimensions modeled include product type tier, end-use industry vertical, distribution channel structure, and regional production hub classification. CAGRs derive from installed capacity expansion timelines, substitution elasticity estimates between nano zinc oxide and titanium dioxide UV filters, and semiconductor packaging content-per-device coefficients. Industry-specific forecast inputs incorporate Shandong and Jiangsu tire manufacturing cluster procurement data and Korean cosmetic house sol adoption rates.
Sensitivities concentrate around EU nano-labeling mandate enforcement intensity, CDSCO approval pathway duration variability, and Nyrstar smelter operational disruption scenarios. Quarterly review of ECHA registration dossier submission volumes, CDSCO nano-material drug delivery approval decisions, and Texas semiconductor packaging facility capacity utilization is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Nanoceramic Market