
 Nanoceramic Market | 2026-2036
Nanoceramic Market Size, Share, and Industry Trends Forecast 2026-2036
Nanoceramic Market Intelligence
German specialty chemical producers is rebalancing European nanoceramic powder capacity after Asian supply disruptions tightened alumina precursor availability. BASF SE leverages its Ludwigshafen integrated site to sustain high-purity zirconia output for dental and electronics clients. 3M Company anchors North American demand through its St. Paul R&D campus, where fluoropolymer-ceramic hybrid films dominate industrial abrasion markets. AkzoNobel N.V. competes in marine and automotive coatings by controlling maritime channel access across Rotterdam and Singapore storage nodes.
Nanoceramics are engineered ceramic materials with grain sizes below 100 nanometers, typically produced via sol-gel synthesis, chemical vapor deposition, or spark plasma sintering to achieve superplasticity, enhanced fracture toughness, and thermal shock resistance beyond conventional micron-scale ceramics. Their primary purpose spans thermal barrier coatings in turbine engines, biocompatible implants in orthopedics, dielectric substrates in 5G infrastructure, and solid-state electrolytes in next-generation batteries. Powders command the largest volume share as feedstock for downstream coatings and composites, while Films generate the highest margin pools due to precision deposition requirements in semiconductor packaging and aerospace sensor windows. The Energy application segment shows the steepest growth trajectory as silicon nitride and hafnia compositions displace graphite in molten-metal battery containment systems.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants shapes U.S. coating formulation requirements, forcing solvent-based nanoceramic dispersion processes toward waterborne alternatives. REACH registration in Europe and evolving MDR clinical evidence rules for permanent implants create dual compliance burdens for biomedical-grade zirconia suppliers seeking transatlantic market access. Stakeholders must monitor how China's GB standards for advanced ceramics and its dual carbon goals redirect domestic hafnia and alumina capacity away from export markets.
Market Dynamics
Aerospace OEMs are compressing thermal barrier coating development cycles as next-generation turbine architectures demand nanoceramic films capable of withstanding 1,300°C operating temperatures without grain-boundary creep failure.
Growth Catalysts
- REACH substance registration:European chemical compliance is filtering out low-purity alumina precursors, concentrating demand among certified nanoceramic powder suppliers with verified toxicology dossiers.
- Solid-state battery containment:Silicon nitride and hafnia compositions are displacing graphite in molten-metal battery systems as energy storage OEMs seek non-flammable electrolyte barriers.
- German automotive cluster:Fraunhofer institute partnerships with power electronics manufacturers are accelerating ceramic film qualification for inverter modules in electric drivetrains.
Market Restraints
- Alumina precursor concentration:Asian supply disruptions have tightened high-purity feedstock availability, forcing European formulators to absorb 15-20% input cost volatility or reformulate.
- Spark plasma sintering capex:The capital intensity of densification equipment limits mid-scale producers from achieving the sub-100nm grain structures required for superplasticity certification.
- MDR clinical evidence rules:European medical device regulations are extending zirconia implant approval timelines by 18-24 months compared to legacy ceramic standards.
Strategic Opportunities
- 5G dielectric substrates:Low-loss hafnia-alumina laminates are penetrating semiconductor packaging as substrate manufacturers seek higher thermal conductivity than organic alternatives.
- Waterborne dispersion transition:EPA National Emission Standards enforcement is creating first-mover advantage for coating houses with solvent-free nanoceramic slurry capabilities.
- India BIS standardization:Emerging technical committee activity around advanced ceramics is opening early-entrant positioning for powder suppliers willing to establish local blending operations.
Industry Challenges
- Interdisciplinary talent scarcity:The convergence of ceramic science, nanoscale characterization, and thin-film deposition requires hybrid skill sets that traditional materials engineering programs rarely produce.
- ISO 13320 particle sizing disputes:Laser diffraction protocol variations between laboratories are creating batch acceptance conflicts between powder suppliers and coating applicators.
- Legacy coating line retrofit costs:Industrial finishers face 30-40% equipment replacement expenses to handle aqueous nanoceramic suspensions without agglomeration defects.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanoceramic Market |
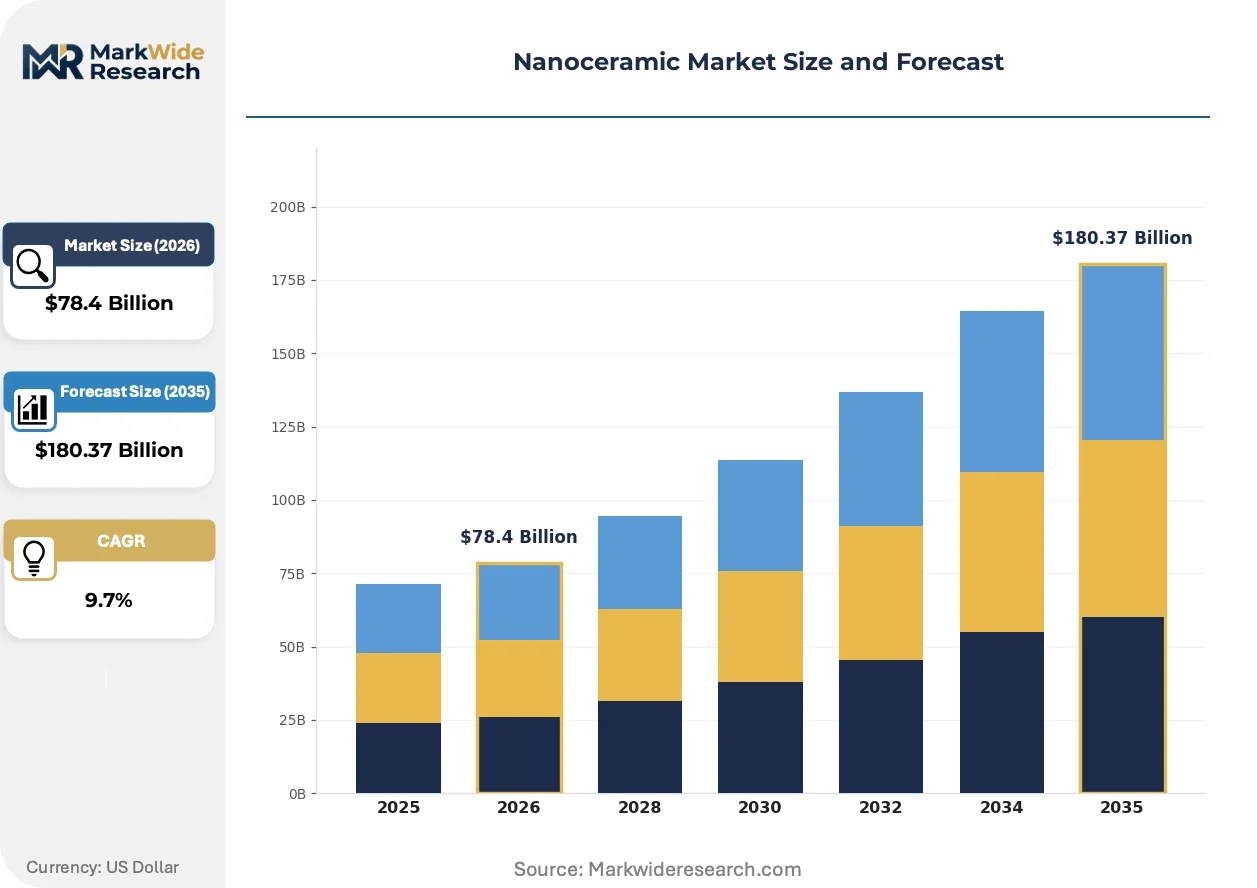
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $180.37 Billion |
| CAGR (2026 – 2036) | 9.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Powders, Coatings, Composites, Films Application: Biomedical, Electronics, Automotive, Energy Material: Alumina, Zirconia, Silicon Nitride, Hafnia End User: Manufacturers, R&D Institutions, Healthcare, Aerospace |
| Companies Covered | BASF SE, The Sherwin-Williams Company, 3M Company, Axalta Coating Systems, Kehui, Eastman Chemical Company, AkzoNobel N.V., Nanogate SE, PPG Industries, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanoceramic Market Strategic Shifts & Innovations
Processing architecture and regulatory chemistry are reshaping competitive positioning in nanoceramics, with densification methods and emissions compliance emerging as primary differentiators between specialty chemical houses.
Spark plasma sintering is overtaking conventional hot pressing for oxide and non-oxide ceramic fabrication. Turbine blade coating contractors in the US and Germany are adopting SPS platforms to achieve full densification below 1,000°C, preserving nanoscale grain structures that conventional sintering destroys through excessive thermal exposure. This temperature reduction is compressing cycle times from 12 hours to under 90 minutes while eliminating the secondary machining steps previously required for dimensional tolerance.
EPA enforcement of National Emission Standards for Hazardous Air Pollutants is forcing solvent-based nanoceramic dispersion processes toward waterborne alternatives. Industrial coating applicators in Michigan and Ohio are reformulating zirconia-alumina slurries to meet methylene chloride and perchloroethylene limits, with compliance deadlines concentrating capital expenditure into 2025-2026. The affected segment—abrasion-resistant films for oil and gas equipment—is responding by qualifying aqueous binders that match the hardness values of legacy solvent systems.
Specification-driven procurement is compressing supplier qualification cycles in aerospace and medical verticals. Buyers are unbundling material certification from coating application, demanding ISO 13320 particle size distributions and traceable precursor chain-of-custody documentation before contract award. This pattern is most visible in Germany, where Fraunhofer-certified testing protocols are becoming de facto gatekeepers for automotive power electronics and dental implant supply chains.
Nanoceramic Market Segmentation
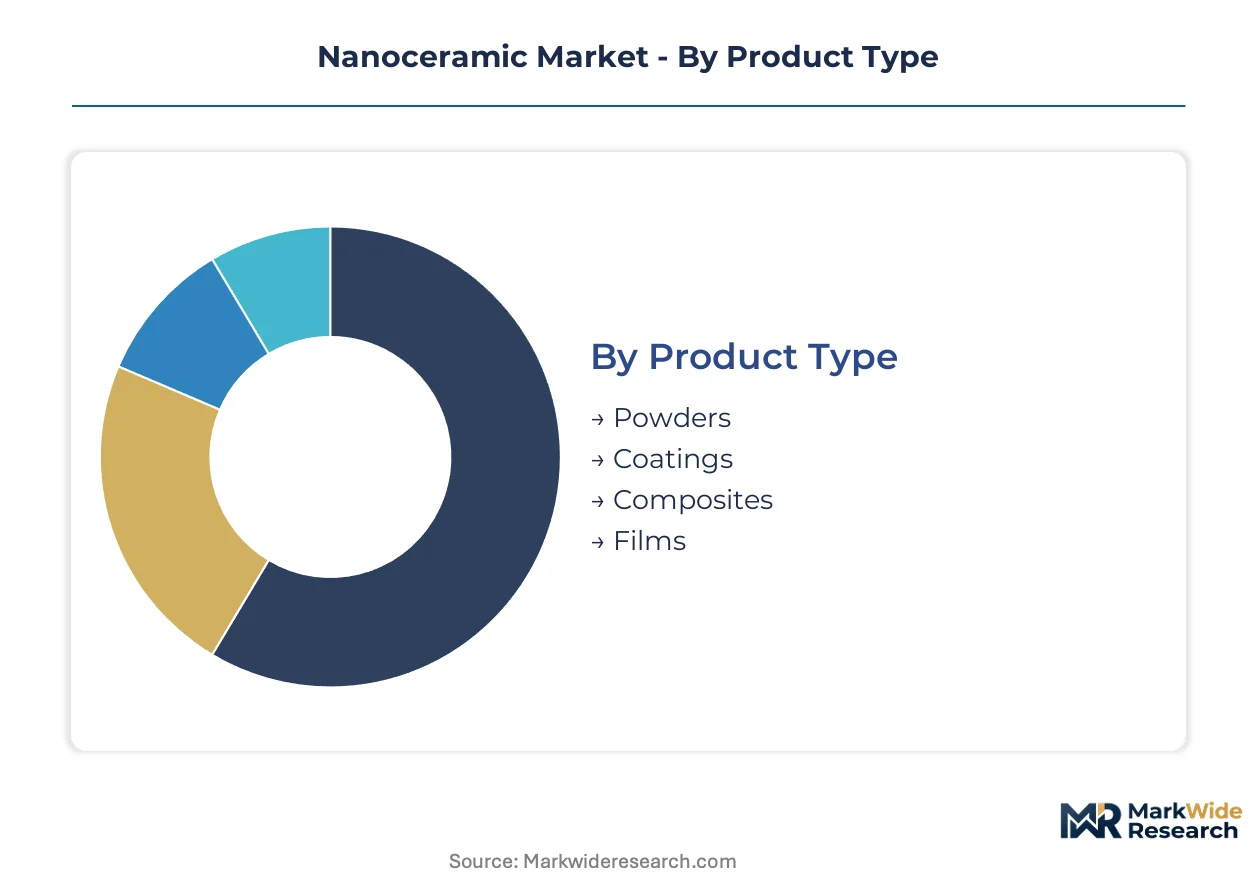
Segmentation in nanoceramics reveals how certification burdens and technical specifications concentrate purchasing power among qualified suppliers. Buyers unbundle material certification from application services, forcing upstream producers to maintain parallel compliance dossiers across medical, aerospace, and electronics verticals.
Product Type:
Powders require REACH registration and ISO 13320 particle sizing verification before European coating houses will qualify suppliers. Films demand additional semiconductor-grade cleanliness protocols and traceable chain-of-custody documentation for aerospace sensor window applications.
- Powders:Granular feedstock with sub-100nm grain structures produced via sol-gel or spray pyrolysis, serving as the foundational input for thermal spray and slurry-based coating processes. German automotive OEMs and Fraunhofer institutes concentrate procurement of high-purity alumina and zirconia powders for power electronics ceramic films, with REACH toxicology dossiers now mandatory for contract eligibility.
- Films:Precision-deposited layers ranging from nanometers to micrometers in thickness, manufactured through chemical vapor deposition or physical vapor deposition for dielectric and barrier applications. Aerospace manufacturers in the United States and Germany dominate demand for thermal barrier coatings capable of withstanding 1,300°C turbine operating temperatures, with EPA emissions compliance forcing rapid qualification of waterborne deposition processes.
- Coatings:Applied surface layers for abrasion and corrosion protection across industrial equipment, typically formulated as solvent-based or waterborne suspensions of nanoceramic particles.
- Composites:Hybrid materials integrating nanoceramic reinforcements within polymer or metal matrices for enhanced mechanical properties.
Leading the category by volume: Powders. Growing fastest: Films.
Application:
Medical devices face the steepest regulatory burden through European MDR clinical evidence requirements, while energy storage applications navigate evolving safety standards for molten-metal battery containment systems.
- Energy:Silicon nitride and hafnia compositions displace graphite in next-generation battery architectures, with solid-state electrolyte barriers commanding premium qualification cycles. OEMs in Germany and the United States concentrate procurement for non-flammable containment systems as thermal runaway risks reshape material specifications.
- Biomedical:Zirconia and alumina compositions for dental implants and orthopedic bearings, requiring biocompatibility certification and extended wear testing. European MDR rules have extended approval timelines by 18-24 months compared to legacy ceramic standards, concentrating demand among suppliers with established clinical dossiers.
- Electronics:Dielectric substrates and packaging materials for 5G infrastructure and semiconductor devices.
- Automotive:Ceramic films for power electronics in electric drivetrains, with inverter module applications driving qualification partnerships between OEMs and research institutes.
Energy applications climb the fastest as battery OEMs redesign containment architectures. Biomedical retains the highest margin pool despite regulatory friction.
Material:
Raw material selection determines which precursor supply chains and sintering protocols a producer must master, with alumina and zirconia offering the most established certification pathways.
- Alumina:The most widely produced oxide ceramic, valued for hardness, chemical inertness, and cost-effective high-volume manufacturing. Asian supply disruptions have tightened high-purity precursor availability, forcing European formulators to absorb input cost volatility or reformulate around alternative feedstocks.
- Zirconia:Transformation-toughened ceramic with exceptional fracture toughness and biocompatibility, dominating dental and orthopedic implant applications. BASF SE sustains high-purity output from its Ludwigshafen integrated site, serving European medical device manufacturers with verified REACH dossiers.
- Silicon Nitride:Non-oxide ceramic with superior thermal shock resistance and strength at elevated temperatures, penetrating molten-metal battery containment.
- Hafnia:High-k dielectric material with exceptional thermal stability and radiation resistance, qualifying for aerospace sensor windows and next-generation gate dielectrics.
Alumina dominates by production tonnage. Hafnia posts the steepest expansion trajectory as semiconductor packaging demands escalate.
End User:
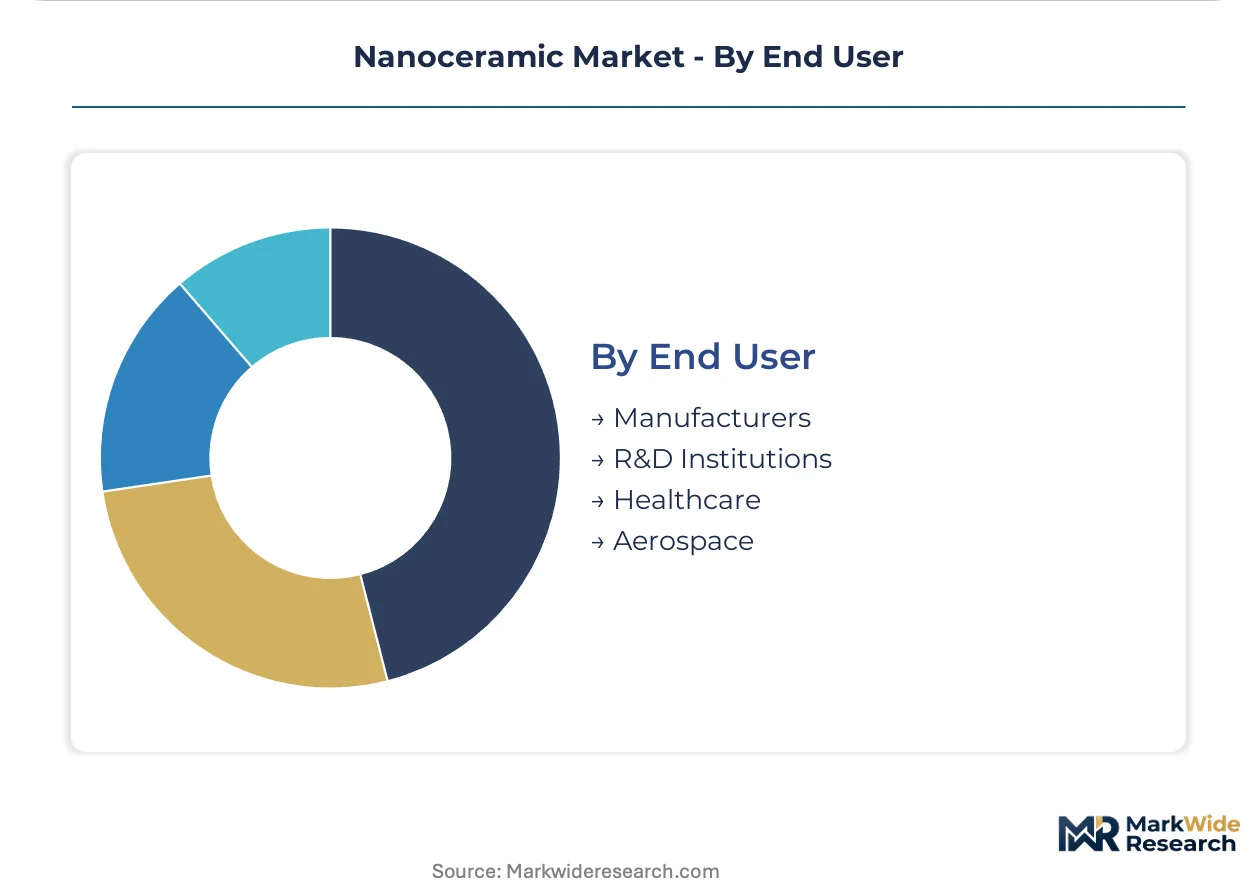
Procurement sophistication varies sharply across customer types, with R&D institutions driving specification development that later hardens into industrial qualification requirements.
- Manufacturers:Industrial coating applicators and component fabricators purchasing nanoceramic feedstock for integration into finished goods. Michigan and Ohio-based finishers face 30-40% equipment replacement costs to handle aqueous nanoceramic suspensions without agglomeration defects as EPA enforcement tightens.
- Aerospace:OEMs and tier suppliers specifying thermal barrier coatings and sensor window materials for turbine engines and airframes. Next-generation turbine architectures compress development cycles, demanding nanoceramic films with grain-boundary creep resistance at 1,300°C operating temperatures.
- R&D Institutions:Universities and national laboratories advancing processing methods and material compositions.
- Healthcare:Medical device manufacturers and dental laboratories procuring implant-grade ceramics.
Manufacturers account for the largest procurement volume. Aerospace commands the most stringent qualification protocols and highest price realization.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
High-purity alumina precursor deposits in Australia and processing clusters in Germany anchor nanoceramic feedstock availability. Turbine blade coating contractors in the United States and Germany compress development cycles as aerospace OEMs demand films withstanding extreme thermal loads. Regulatory chemistry and emissions enforcement are reshaping where production capacity concentrates.
United States
Aerospace OEMs in Connecticut and Ohio drive thermal barrier coating procurement for next-generation turbine architectures. EPA enforcement of National Emission Standards for Hazardous Air Pollutants forces Michigan and Ohio industrial finishers toward waterborne nanoceramic slurry reformulation. The St. Paul R&D campus anchors North American fluoropolymer-ceramic hybrid film development for abrasion-resistant industrial applications.
Germany
Automotive OEMs and Fraunhofer institutes co-develop ceramic films for power electronics in electric drivetrains. REACH substance registration filters out low-purity alumina precursors, concentrating demand among certified nanoceramic powder suppliers. The Ludwigshafen integrated site sustains high-purity zirconia output for dental and electronics clients across European medical device supply chains.
China
Domestic hafnia and alumina capacity is redirecting toward internal consumption as dual carbon goals reshape production priorities. GB standards for advanced ceramics create technical barriers for foreign powder suppliers seeking market access. Yangtze River Delta processing clusters are expanding spark plasma sintering platforms for oxide ceramic fabrication serving semiconductor packaging demand.
Japan
Dielectric substrate manufacturers in the Kansai region qualify low-loss hafnia-alumina laminates for 5G infrastructure deployment. METI industrial technology roadmaps prioritize nanoceramic solid-state electrolyte development for next-generation battery architectures. Osaka-based ceramic houses are advancing silicon nitride compositions for molten-metal battery containment systems in energy storage applications.
India
BIS technical committee activity around advanced ceramics is opening early-entrant positioning for powder suppliers establishing local blending operations. Automotive component manufacturers in Maharashtra and Tamil Nadu are qualifying ceramic films for power electronics as electric vehicle production scales. The PLI scheme for advanced chemistry cell manufacturing is creating downstream demand for non-flammable electrolyte barrier materials.
Nanoceramic Market Key Industry Players
Global majors compete with regional champions across certification depth and precursor supply security. The vendor base stratifies into integrated chemical conglomerates with captive feedstock, specialized ceramic coating houses with application expertise, and emerging Asian producers with cost-optimized powder output. Strategic moves concentrate on backward integration into alumina and zirconia precursors, plus technology licensing partnerships that accelerate waterborne dispersion qualification.
Among diversified chemical conglomerates, BASF SE and 3M Company exemplify the integrated archetype with multi-vertical nanoceramic portfolios spanning medical, electronics, and industrial end uses. Specialty coating specialists including The Sherwin-Williams Company and PPG Industries occupy positions emphasizing application-layer value capture and channel control. Axalta Coating Systems and AkzoNobel N.V. represent the automotive-marine focused tier where maritime storage node access and OEM qualification cycles create defensive positioning. Nanogate SE sits within the European mid-scale specialist segment where Fraunfofer-certified testing protocols serve as de facto market gatekeepers.
| Leading Market Players |
|---|
| BASF SE |
| The Sherwin-Williams Company |
| 3M Company |
| Axalta Coating Systems |
| Kehui |
| Eastman Chemical Company |
| AkzoNobel N.V. |
| Nanogate SE |
| PPG Industries |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between REACH-registered powders and uncertified commodity feedstock bifurcates the nanoceramic market into parallel pricing ecosystems, with German automotive OEMs and Fraunhofer institutes commanding premium qualification premiums while industrial finishers absorb volatile alumina precursor costs. This tiered separation manifests in supply chain configurations where high-purity zirconia channels through Ludwigshafen-integrated production nodes, while lower-grade alumina powders navigate Rotterdam and Singapore storage arbitrage.
Pricing Analysis
Warranty-bundled technical service packages separate aerospace thermal barrier coating contracts from transactional powder sales to industrial applicators, with turbine OEMs purchasing fully-qualified film systems while Michigan finishers buy unbundled feedstock. Three-tier pricing structure across premium, standard, and economy levels tracks ISO 13320 certification depth and REACH dossier completeness. Cost compression in standard-grade alumina powders intensifies because Asian supply disruptions force European formulators to reformulate or absorb input volatility. Healthcare procurement committees exhibit lowest price sensitivity due to MDR-mandated clinical evidence requirements, while automotive power electronics buyers negotiate aggressively on volume scales.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Singapore, and Houston orchestrate hub-and-spoke patterns for nanoceramic powders, with Ludwigshafen and St. Paul anchoring direct-to-OEM channels for certified films. Supply concentrates in Germany, China, and the United States, with Yangtze River Delta processing clusters expanding spark plasma sintering capacity for semiconductor packaging feedstock. Raw material flows draw from Australian high-purity alumina deposits, Chinese hafnia refining operations, and Japanese silicon nitride precursor synthesis. Single-source vulnerability concentrates in Asian alumina precursor supply following recent disruptions. Distribution runs through maritime bulk terminals for powders and air-freight cold chain for semiconductor-grade films.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanoceramic sector is consolidating around captive precursor supply, with backward integration into high-purity alumina and zirconia refining emerging as the decisive margin-control lever separating integrated conglomerates from coating-dependent specialists.
For Market Incumbents: Acquire spark plasma sintering equipment platforms and Australian alumina precursor offtake rights to secure sub-100nm grain structure certification. BASF SE's Ludwigshafen model demonstrates how integrated refining insulates against Asian supply volatility. Defensive patent clustering around waterborne dispersion binders protects against EPA enforcement-driven formulation shifts. Channel control through Fraunhofer-certified testing protocols creates switching costs for German automotive procurement. For New Entrants and Emerging Players: Enter via India BIS technical committee participation and Maharashtra blending operations to capture early-standardization positioning before domestic capacity scales. Target energy storage containment applications where silicon nitride qualification cycles remain open and molten-metal battery OEMs seek non-flammable electrolyte barriers. Pursue technology licensing partnerships with Osaka-based ceramic houses to accelerate hafnia-alumina laminate certification for 5G substrate markets. For Investors and Strategic Acquirers: Exit pathways concentrate in trade sales to diversified chemical conglomerates seeking nanoceramic vertical integration, with IPO windows requiring sustained profitability through regulatory compliance cycles. Long-term viability favors producers with captive precursor supply and multi-vertical certification dossiers spanning medical, aerospace, and electronics. Monitor EPA National Emission Standards enforcement intensity in Michigan and Ohio as inflection indicator for waterborne dispersion technology valuations.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Alumina Precursors | Australian deposit offtake agreements insulate BASF SE and 3M Company from Asian supply volatility. |
| Waterborne Dispersion Qualification | EPA enforcement in Michigan and Ohio compresses reformulation timelines for coating applicators. |
| Fraunhofer Certification Partnership | German automotive OEM procurement gates demand verified testing protocols for power electronics films. |
| Spark Plasma Sintering Scale-Up | Temperature-reduced densification preserves nanoscale grain structures for turbine blade contractors. |
| India BIS Standardization Engagement | Maharashtra and Tamil Nadu blending operations capture early-entrant positioning in emerging technical committees. |
Research Approach
Trade association data, regulatory filings, and customs records anchored secondary inputs, supplemented by primary interviews with ceramic plant managers, automotive OEM procurement leads, coating applicator technical directors, and Fraunhofer institute R&D coordinators. ECHA REACH registration databases, EPA National Emission Standards enforcement records, SEC 10-K disclosures from diversified chemical conglomerates, and Japanese METI industrial technology roadmaps provided validation layers. Bottom-up powder volume estimates and top-down film value assessments underwent cross-triangulation against customs trade flows.
Granularity extended to material-grade tier, end-use vertical, certification protocol, and regional production hub across the analysis window. CAGRs derived from segment-level volume trajectories and price realization curves, with silicon nitride energy containment and hafnia semiconductor packaging treated as breakout scenarios. Modeled inputs incorporated spark plasma sintering adoption rates, waterborne dispersion transition timelines, and MDR clinical evidence rule implementation pacing.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained Asian alumina supply disruption or accelerated EPA enforcement concentration. Forecasts reflect documented assumptions regarding REACH registration completion rates and Fraunhofer certification pipeline throughput. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanotechnology Market
Nanomaterials
Americas Gold Nanoparticles Market
Nanomaterials
Global Nanofilms Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Global Nanoclay Reinforcement Market
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Mesoporous Carbons Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Global Graphene Based Supercapacitors Market
Nanomaterials
Nanotools Market
Nanomaterials
Silver Nanoparticles Market