
 Global Nano Silver Market | 2026-2036
Global Nano Silver Market Size, Share, and Industry Trends Forecast 2026-2036
Global Nano Silver Market Foresight
Copper-based antimicrobial formulations in HVAC and plumbing systems is realigning cost-performance benchmarks across hygiene-sensitive industries. NovaCentrix specializes in printed electronics integration, leveraging its photonic curing expertise to anchor North American supply chains for flexible circuit applications. DOWA Electronics Materials dominates high-purity powder production in Asia, while American Elements extends its catalog of custom nanoparticle specifications to compete in pharmaceutical-grade segments.
Nano silver comprises metallic silver particles with at least one dimension between 1 and 100 nanometers, typically synthesized through chemical reduction of silver salts to achieve surface plasmon resonance and sustained ion release. Colloidal nano silver leads pharmaceutical and personal care formulations due to established dissolution kinetics, while nano silver powder concentrates margin pools in electronics where conductivity thresholds demand tight particle-size distribution. Green synthesis methods are gaining fastest in water purification applications as electrochemical routes face energy-cost scrutiny.
FDA antimicrobial device regulations and EPA pesticide product registrations shape commercialization pathways in the United States, while REACH substance evaluation and EU MDR biocompatibility standards govern access across European medical and consumer markets. ISO 10993 cytotoxicity testing protocols further constrain formulation choices for wound-care and implantable applications. Stakeholders must weigh regulatory compliance timelines against synthesis method selection before committing capital to capacity expansion.
Market Dynamics
Antimicrobial coating mandates in implantable medical devices are compressing synthesis certification timelines while amplifying demand for pharmaceutical-grade nano silver with documented ion-release kinetics.
Growth Catalysts
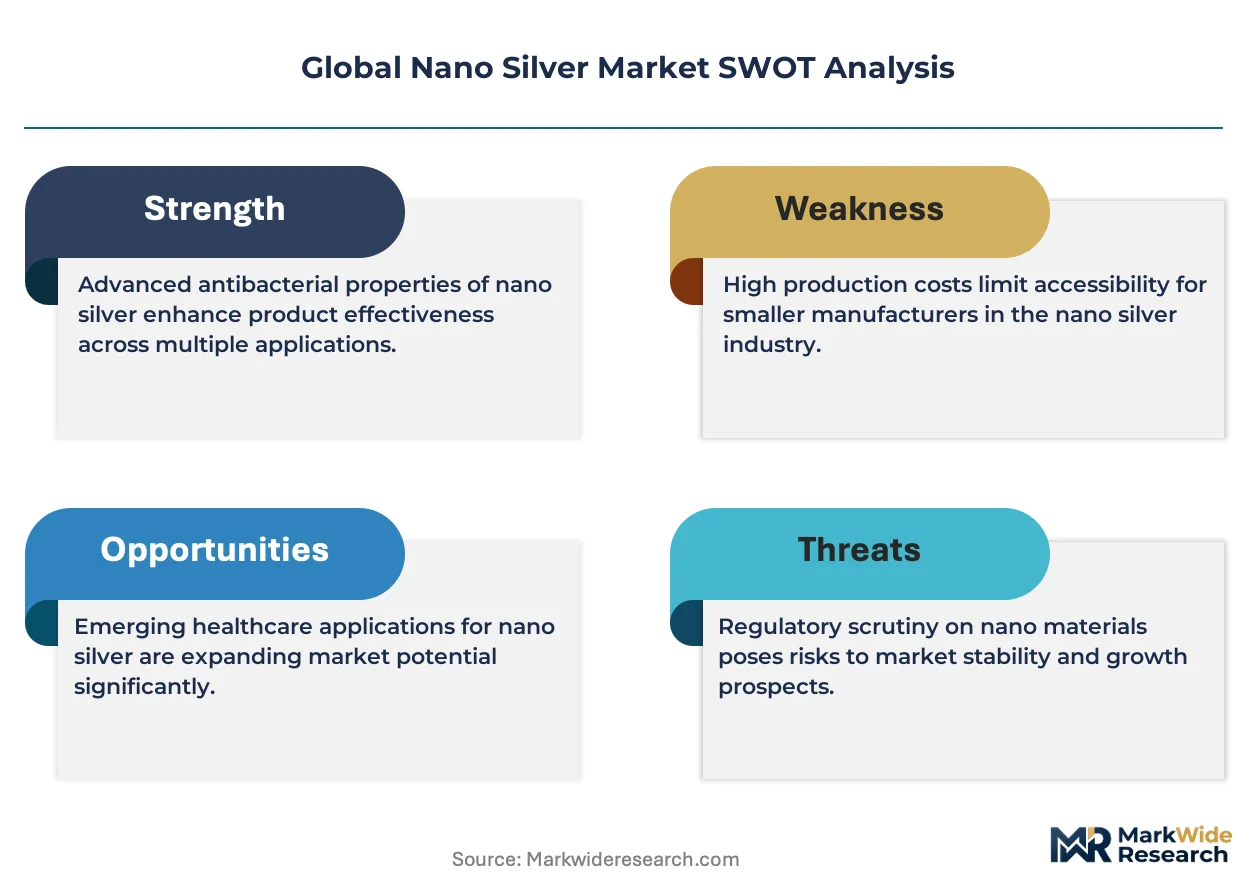
- EU MDR biocompatibility protocols:Tightened cytotoxicity testing requirements for wound-care applications are filtering out commodity suppliers and concentrating procurement among ISO 10993-certified producers.
- Photonic curing integration:Printed electronics manufacturers in North America are embedding nano silver inks into flexible circuit substrates, expanding addressable surface area per device.
- Water purification infrastructure:Electrochemical synthesis capacity in Singapore and South Korea is attracting municipal procurement contracts for antimicrobial filtration membranes.
Market Restraints
- Silver nitrate price volatility:Precursor chemical costs fluctuate with London Metal Exchange spot pricing, compressing margins for chemical reduction producers without long-term supply agreements.
- High-purity powder concentration:Asian supply chains dominate electronics-grade material, creating geographic single-source risk for North American flexible circuit fabricators.
- Copper substitution in HVAC:Lower-cost antimicrobial formulations are displacing nano silver in non-medical building systems where conductivity thresholds are less stringent.
Strategic Opportunities
- Green synthesis scale-up:Plant-extract reduction methods in South Korea qualify for national green technology tax credits while reducing energy intensity versus electrochemical routes.
- Implantable device coatings:Long-acting antimicrobial surface treatments for orthopedic hardware represent underpenetrated demand within FDA-regulated Class III device pathways.
- Direct-to-fabricator distribution:Nano silver ink producers are bypassing regional distributors to supply printed electronics OEMs through technical service partnerships.
Industry Challenges
- ISO 10993-5 cytotoxicity certification timelines:Medical device coating suppliers face 18-24 month validation cycles before EMA or PMDA submission.
- Particle-size distribution control:Tightening electronics conductivity specifications require capital-intensive classification equipment that mid-scale chemical reduction facilities lack.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Nano Silver Market |
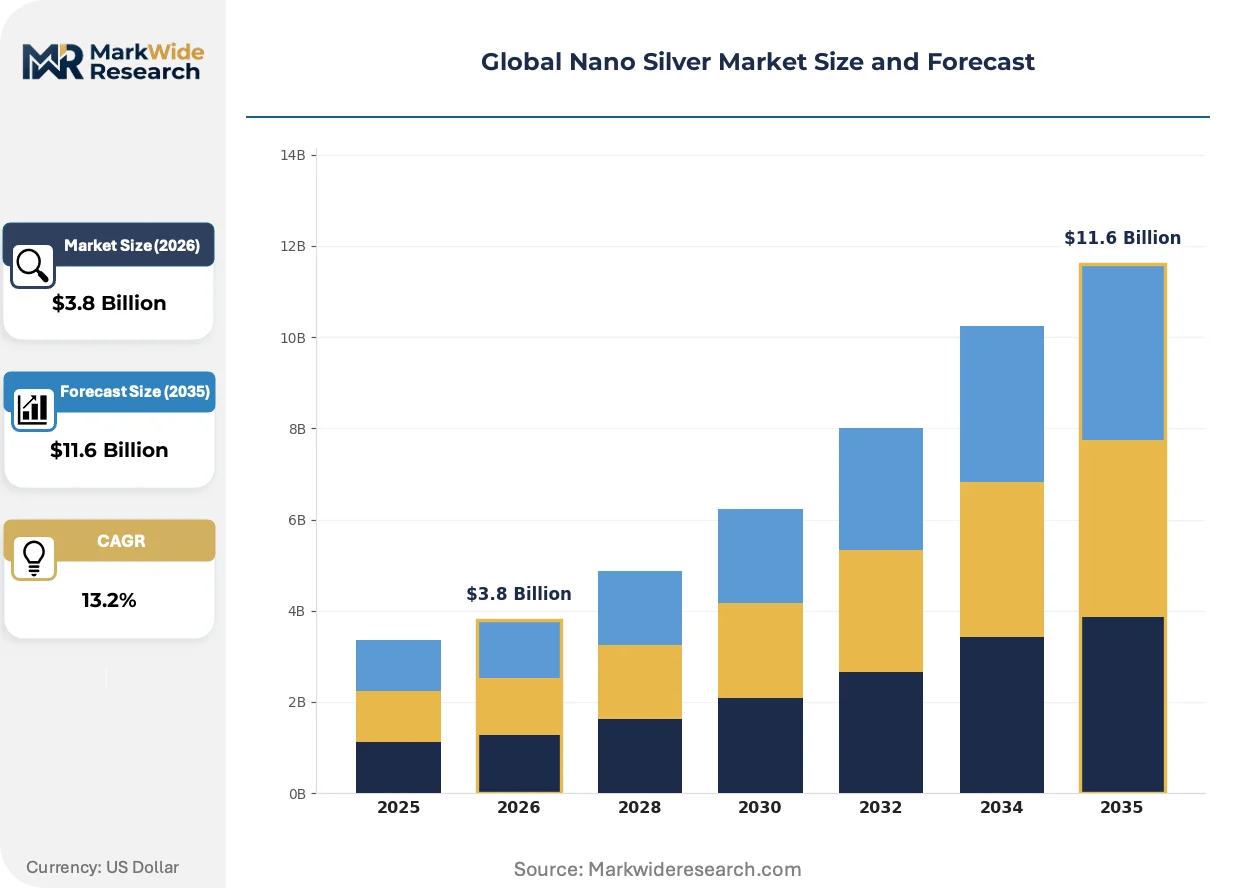
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $11.6 Billion |
| CAGR (2026 – 2036) | 13.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Colloidal Nano Silver, Nano Silver Powder, Nano Silver Suspension, Nano Silver Gel, Nano Silver Fibers Application: Antimicrobial Coatings, Water Treatment, Electronics, Textiles, Personal Care End User Industry: Pharmaceutical, Consumer Electronics, Textile Manufacturing, Water Purification, Cosmetics Production Technology: Chemical Reduction, Physical Vapor Deposition, Laser Ablation, Green Synthesis, Electrochemical |
| Companies Covered | Advanced Nano Products, Ames Goldsmith, NovaCentrix, Nano Silver Manufacturing Sdn Bhd, SILVIX, Applied Nanotech Holdings, NanoMas Technologies, American Elements, DOWA Electronics Materials, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Nano Silver Market Shifts & Advancements
Biogenic synthesis pathways are disrupting established chemical reduction economics while regulatory convergence around ion-release measurement standards is forcing reformulation investments across pharmaceutical and electronics segments.
Biosynthesis using plant polyphenol extracts is rewriting cost structures for water treatment applications. Municipal procurement agencies in Singapore are piloting membrane systems utilizing green-synthesized nano silver with comparable log-reduction efficacy to electrochemical material. The shift is compressing acceptable price premiums for sustainability-certified product categories.
REACH substance evaluation under ECHA's 2023-2025 work program is tightening environmental release documentation requirements for nano silver in consumer textiles. German medical textile manufacturers are accelerating substitution toward encapsulated ion-release formulations that limit downstream environmental mobility. The regulatory pressure is fragmenting supplier qualification pools between pharmaceutical-grade and industrial-grade producers.
Hospital procurement consortiums are consolidating antimicrobial coating specifications around standardized ion-release rate certificates rather than proprietary supplier claims. Group purchasing organizations in the United States are unbundling technical validation from material supply, forcing nano silver producers to submit to third-party testing protocols. The specification consolidation is compressing switching costs between qualified suppliers.
Global Nano Silver Market Segmentation
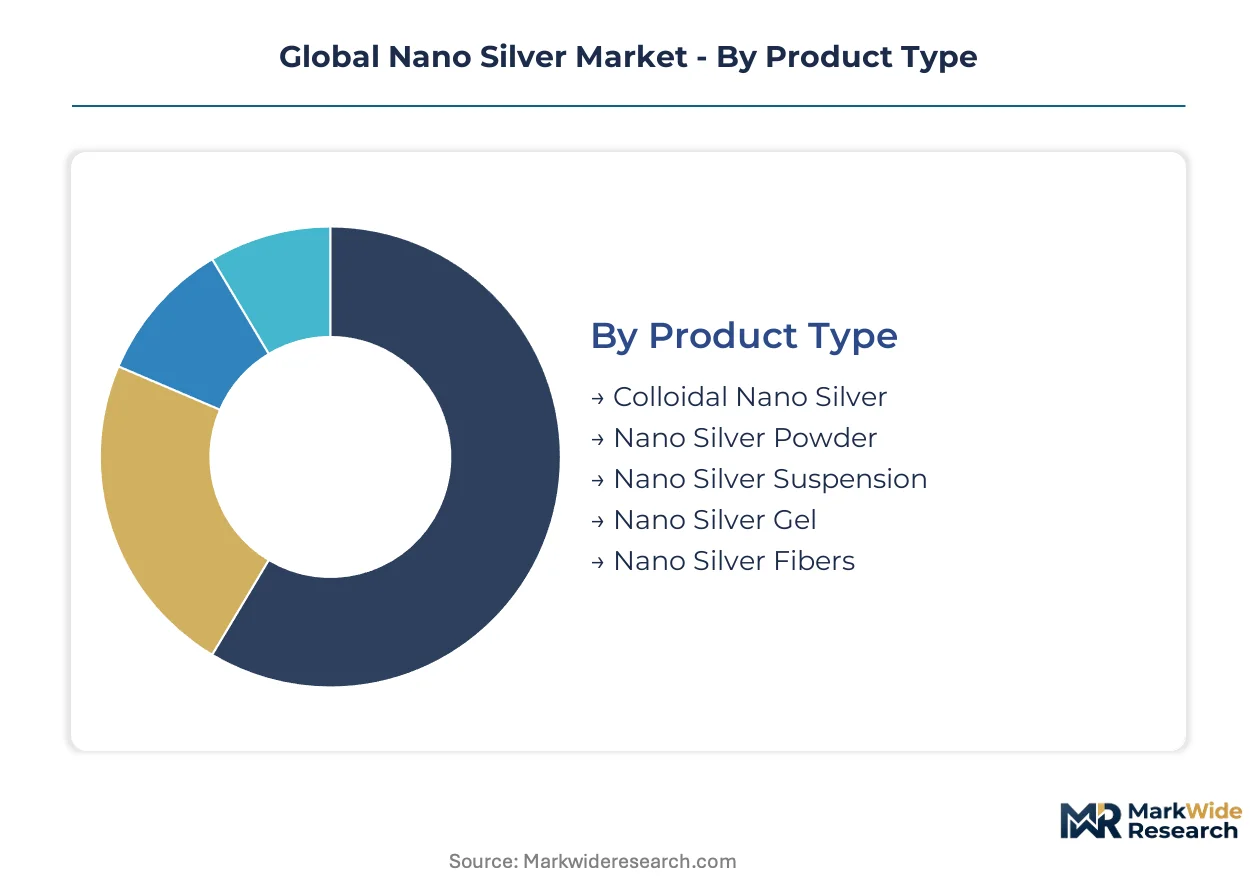
Segmentation in the nano silver market reveals how formulation chemistry and synthesis technology determine regulatory pathways and margin structures. Buyers select product types based on ion-release kinetics requirements, while application segments diverge sharply between medical-grade certification demands and industrial conductivity specifications.
Product Type:
Procurement decisions pivot on dissolution behavior and surface area-to-volume ratios that dictate antimicrobial efficacy windows.
- Colloidal Nano Silver:Metallic silver particles suspended in liquid medium with particle sizes typically ranging 1-100 nanometers enable controlled ion release. Pharmaceutical formulators in Germany and Japan prioritize colloidal systems for wound-care applications under tightened EMA and PMDA biocompatibility protocols. The established dissolution kinetics reduce regulatory validation timelines compared to novel formulations.
- Nano Silver Powder:Dried particulate with tight particle-size distribution serves electronics manufacturers requiring conductivity thresholds in flexible circuit substrates. Powder specifications concentrate margin pools where photonic curing integration demands precise surface plasmon resonance properties.
- Nano Silver Suspension:Higher solid-loading dispersions suit industrial coating applications requiring spray-deposition compatibility.
- Nano Silver Gel:Viscous formulations target topical medical applications where prolonged skin contact requires thickened rheology.
- Nano Silver Fibers:Embedded textile applications leverage fiber morphology for sustained antimicrobial surface activity in medical fabrics.
Colloidal nano silver leads on scale; green synthesis-compatible suspensions are climbing the fastest as municipal water treatment procurement expands in Singapore and South Korea.
Application:
End-use specifications fragment the addressable market between FDA-regulated medical pathways and industrial performance benchmarks.
- Antimicrobial Coatings:Surface treatments for implantable medical devices and HVAC systems dominate value capture. Orthopedic hardware manufacturers in the United States face compressed synthesis certification timelines under FDA antimicrobial device regulations while amplifying demand for pharmaceutical-grade material with documented ion-release kinetics.
- Water Treatment:Municipal filtration membrane applications in Singapore are piloting green-synthesized nano silver with comparable log-reduction efficacy to electrochemical material. The segment is gaining share fastest as electrochemical routes face energy-cost scrutiny and plant-extract reduction methods qualify for national green technology tax credits.
- Electronics:Printed circuit and flexible substrate applications concentrate procurement among ISO-certified producers with particle-size distribution control capabilities.
- Textiles:REACH substance evaluation under ECHA's work program is tightening environmental release documentation requirements, accelerating substitution toward encapsulated ion-release formulations.
- Personal Care:Cosmetic formulations face EPA pesticide product registration pathways in the United States and EU MDR biocompatibility standards across European consumer markets.
Antimicrobial coatings command premium pricing; water treatment is expanding most quickly as infrastructure procurement pivots toward sustainability-certified categories.
End User Industry:
Customer type determines certification burden and technical service intensity required from suppliers.
- Pharmaceutical:Wound-care and implantable device manufacturers require ISO 10993 cytotoxicity testing protocols with 18-24 month validation cycles before EMA or PMDA submission.
- Consumer Electronics:Flexible circuit fabricators in North America face geographic single-source risk for high-purity powder concentrated in Asian supply chains.
- Textile Manufacturing:German medical textile producers are fragmenting supplier qualification pools between pharmaceutical-grade and industrial-grade producers under regulatory pressure.
- Water Purification:Municipal procurement agencies are consolidating specifications around standardized ion-release rate certificates rather than proprietary supplier claims.
- Cosmetics Production:Formulators navigate REACH substance evaluation and EPA registration pathways with divergent environmental release documentation requirements.
Pharmaceutical buyers concentrate procurement among certified producers; water purification is gaining share fastest as green synthesis scale-up reduces acceptable price premiums.
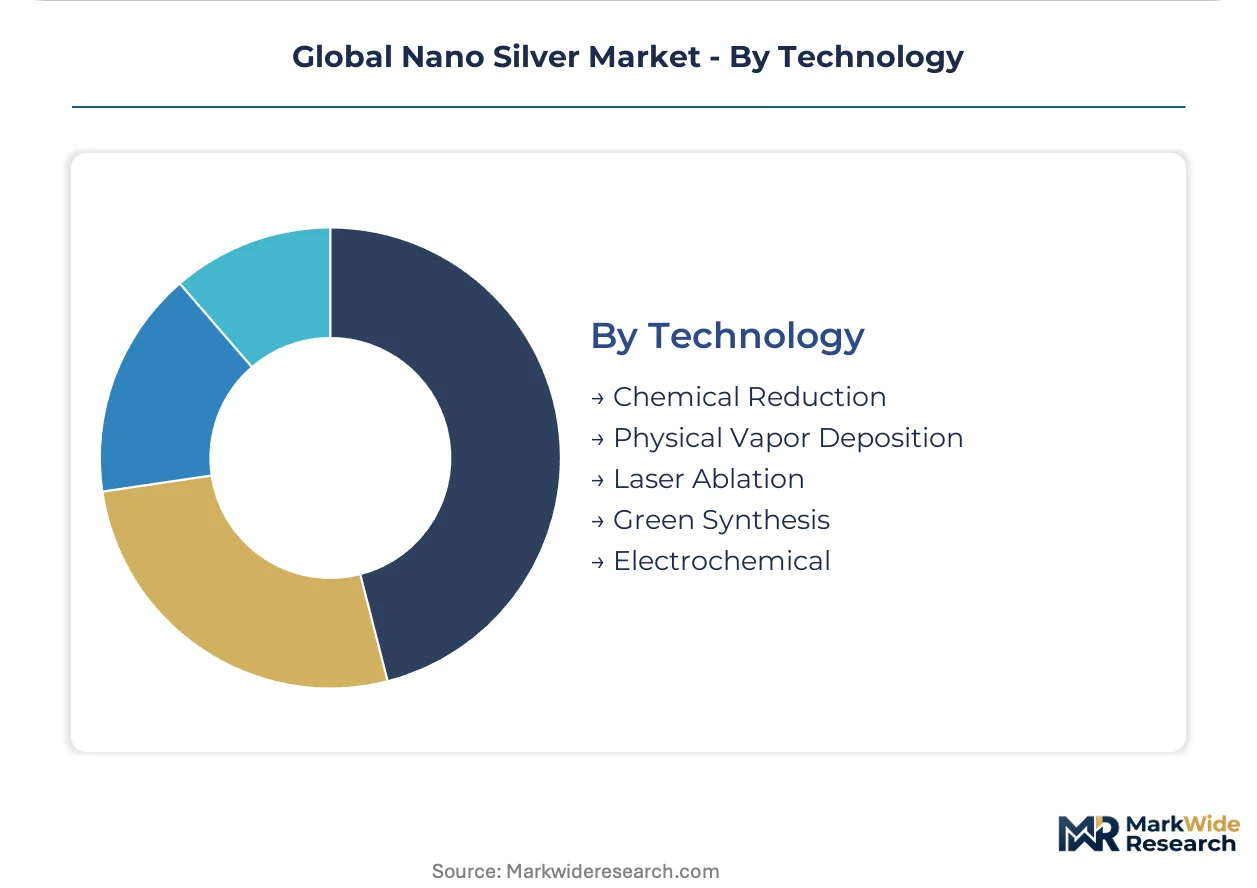
Technology:
Synthesis method selection commits capital to capacity expansion with irreversible regulatory compliance timelines.
- Chemical Reduction:Dominant volume output using silver salt precursors faces margin compression from London Metal Exchange spot price volatility without long-term supply agreements.
- Physical Vapor Deposition:Thin-film coating applications for electronics require capital-intensive equipment that mid-scale facilities lack.
- Laser Ablation:Pulsed laser systems produce high-purity nanoparticles with narrow size distribution for specialized pharmaceutical applications.
- Green Synthesis:Plant polyphenol extract methods are disrupting established chemical reduction economics in water treatment applications while reducing energy intensity versus electrochemical routes.
- Electrochemical:Singapore and South Korean capacity attracts municipal procurement contracts despite facing energy-cost scrutiny relative to biogenic alternatives.
Chemical reduction leads on scale; green synthesis is expanding most quickly as biogenic pathways rewrite cost structures for sustainability-certified procurement categories.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German medical device clusters in Bavaria and Baden-Württemberg anchor pharmaceutical-grade nano silver procurement under tightened EU MDR protocols. The report examines how regulatory convergence and synthesis technology investments reshape competitive positioning across five strategic markets.
United States
FDA antimicrobial device regulations and EPA pesticide registrations compress commercialization timelines for wound-care formulators. Hospital procurement consortiums in the Boston-Cambridge corridor consolidate specifications around third-party ion-release certificates. NovaCentrix anchors North American supply chains for flexible circuit applications from its Texas base.
Germany
EMA biocompatibility protocols filter commodity suppliers from ISO 10993-certified producers serving orthopedic hardware manufacturers. REACH substance evaluation under ECHA's 2023-2025 work program tightens environmental release documentation for medical textiles. Stuttgart's precision engineering cluster demands tight particle-size distribution for electronics-grade powder specifications.
Japan
PMDA protocols for implantable devices amplify demand for documented ion-release kinetics from pharmaceutical-grade producers. METI green technology incentives accelerate pilot programs for biogenic synthesis in municipal water treatment applications. Osaka-Kobe manufacturing corridors concentrate procurement for antimicrobial coating mandates in Class III device pathways.
South Korea
National green technology tax credits reduce energy intensity for plant-extract reduction methods versus electrochemical routes. MFDS cytotoxicity testing alignment with ISO 10993-5 shortens validation cycles for export-oriented formulators. Seoul-Incheon industrial complexes attract venture funding for green synthesis scale-up in filtration membrane contracts.
Singapore
Municipal procurement agencies pilot membrane systems utilizing green-synthesized nano silver with comparable log-reduction efficacy to electrochemical material. The national water agency's sustainability-certified procurement categories compress acceptable price premiums for biogenic alternatives. Jurong Island chemical processing infrastructure supports electrochemical capacity expansion despite energy-cost scrutiny.
Global Nano Silver Market Competitive Landscape
Capacity expansion dominates the current landscape as chemical reduction facilities face margin compression from silver nitrate price volatility. The vendor base stratifies across three tiers: pharmaceutical-grade certified producers, electronics-grade powder specialists, and emerging green synthesis ventures. Two strategic archetypes define competitive positioning: ISO 10993-certified medical suppliers and photonic curing-integrated ink formulators. Geographic expansion and technology licensing represent the dominant competitive moves as Asian supply chain concentration creates single-source risk for North American fabricators.
Among Asia-Pacific material suppliers, DOWA Electronics Materials and Nano Silver Manufacturing Sdn Bhd exemplify the high-purity powder concentration that dominates electronics-grade procurement. American Elements occupies a position within the custom nanoparticle specification tier competing for pharmaceutical-grade segments. These three entities represent how regional supply chain configuration shapes competitive access to FDA-regulated and EMA-governed pathways.
| Leading Market Players |
|---|
| Advanced Nano Products |
| Ames Goldsmith |
| NovaCentrix |
| Nano Silver Manufacturing Sdn Bhd |
| SILVIX |
| Applied Nanotech Holdings |
| NanoMas Technologies |
| American Elements |
| DOWA Electronics Materials |
| Others |
Supply & Pricing Matrix
Pharmaceutical-grade certification against industrial-grade commodity supply creates a bifurcated cost architecture where ISO 10993-validated producers in Germany and Japan command sustained premiums while chemical reduction facilities in Asia absorb silver nitrate volatility. This tier divergence concentrates margin capture among EMA-certified medical suppliers while fragmenting procurement pools for electronics-grade powder.
Pricing Analysis
Silver nitrate precursor costs pass through directly to chemical reduction producers without long-term London Metal Exchange hedging, compressing margins for mid-scale facilities. Three-tier pricing structure across pharmaceutical-grade, electronics-grade, and industrial-grade levels reflects certification burden and particle-size precision requirements. Pricing pressure stems from copper substitution in HVAC applications where conductivity thresholds permit lower-cost antimicrobial alternatives. Municipal water purification buyers in Singapore exhibit highest price sensitivity as green synthesis alternatives compress acceptable premiums for sustainability-certified categories.
Supply Chain Analysis
Single-source vulnerability sits with high-purity nano silver powder concentrated in Japan, South Korea, and Taiwan for electronics-grade specifications. Production draws from silver salt precursors, photonic curing equipment, and precision classification systems. Geographic concentration creates tariff exposure for North American flexible circuit fabricators dependent on Asian material flows. Distribution runs through technical service partnerships that bypass regional distributors for printed electronics OEMs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
EU MDR biocompatibility protocol tightening functions as a regulatory compounder, amplifying demand for pharmaceutical-grade nano silver with documented ion-release kinetics while filtering commodity suppliers from certified procurement pools.
For Market Incumbents: Deepen ISO 10993-5 cytotoxicity certification investments to defend against emerging green synthesis ventures capturing municipal water treatment contracts. Expand captive electrochemical capacity in Singapore or South Korea to offset single-source risk from Asian powder concentration. Secure long-term silver nitrate offtake agreements to stabilize input cost pass-through volatility.
For New Entrants and Emerging Players: Direct-to-fabricator digital channels offer lower customer acquisition cost than distributor-dependent routes for nano silver ink formulations. Target orthopedic implantable device coatings as the most penetrable segment given compressed supplier pools under FDA Class III pathways. Lead with technical service partnerships that bundle ion-release certification with material supply.
For Investors and Strategic Acquirers: Consolidation pressure builds where mid-scale chemical reduction facilities lack capital for particle-size distribution equipment demanded by tightening electronics specifications. Five-to-ten year viability favors vertically integrated producers with backward control into precursor supply and forward integration into pharmaceutical-grade certification. Watch for MFDS-PMDA regulatory alignment signals as inflection indicators for export-oriented formulator acquisition timing.
| Strategic Initiative | Industry Significance |
|---|---|
| Green Synthesis Scale-Up | Plant-extract reduction methods in South Korea qualify for national green technology tax credits while reducing energy intensity. |
| ISO 10993 Certification Investment | Eighteen-to-twenty-four month validation cycles for cytotoxicity testing filter commodity suppliers from EMA-governed procurement pools. |
| Backward Integration into Silver Nitrate | Long-term precursor supply agreements insulate chemical reduction producers from London Metal Exchange spot price volatility. |
| Direct-to-Fabricator Distribution | Technical service partnerships bypass regional distributors to supply printed electronics OEMs with embedded nano silver inks. |
| Implantable Device Coating Development | Long-acting antimicrobial surface treatments for orthopedic hardware represent underpenetrated demand within FDA-regulated pathways. |
Research Methodology
Coverage spans Germany, Japan, South Korea, Singapore, and the United States, with primary inputs from each market's regulatory and manufacturing clusters. Synthesis technology directors, medical device procurement managers at GPO consortiums, municipal water agency contract officers, and flexible circuit fabricator supply chain leads provided qualitative ground-truth. Secondary validation drew from EMA submission databases, FDA 510(k) filings, EPA pesticide product registrations, REACH substance evaluation dossiers, and trade customs records for silver salt precursor flows. Bottom-up capacity assessments triangulated against top-down demand segmentation.
Rate-of-change decomposition across the analysis window separates volume growth from price-mix effects in pharmaceutical versus electronics-grade segments. The modeling framework incorporates synthesis technology type, application end-use, regulatory certification tier, and geographic production hub as core segmentation dimensions. CAGRs derive from fitted growth curves calibrated to historical procurement patterns and announced capacity expansion timelines. Ion-release kinetics standardization and green synthesis cost curve shifts serve as key forecast sensitivity inputs.
Silver nitrate price volatility, regulatory timeline slippage for ISO 10993 validations, and copper substitution acceleration in non-medical building systems are the dominant revision risks that could compress or extend projected market trajectories. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
1,8-Dinitroanthraquinone Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Nanotools Market
Nanomaterials
Nanoceramic Market