
 Tungsten Disulphide Nanoparticles Market | 2026-2036
Tungsten Disulphide Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Tungsten Disulphide Nanoparticles Market Analytics
The EU Green Deal is pivoting nanomaterial procurement toward lower-carbon synthesis pathways across European coating plants. H.C. Starck Tungsten Powders leverages captive tungsten ore processing to secure feedstock continuity for high-purity WS2 output. American Elements sustains broad catalog breadth across powder and dispersion grades, serving R&D buyers in North America and Asia. Nanografi Nano Technology specializes in sub-100nm particle engineering for electronics applications, competing on specification tightness rather than volume scale.
Tungsten disulphide nanoparticles consist of layered transition-metal dichalcogenide crystals, typically synthesized at 2-100 nanometres with an interlayer spacing near 0.62 nanometres, functioning primarily as solid lubricants and conductive additives where extreme pressure or thermal stability is required. Powder forms dominate current shipment volumes owing to straightforward handling and compatibility with conventional compounding equipment, while dispersion grades capture expanding interest from battery producers seeking uniform slurry integration. Chemical vapor deposition yields the highest crystallinity for semiconductor applications, yet hydrothermal synthesis offers cost scalability that chemical processing plants favor for catalyst manufacturing.
EPA oversight in the United States governs nanomaterial reporting under the Toxic Substances Control Act, compelling importers to document particle size distributions and surface reactivity profiles before commercial distribution. REACH registration in the European Union mandates full toxicity dossiers for WS2 volumes exceeding one tonne annually, effectively filtering smaller trading houses from direct market access. China's SAMR enforces GB standards for nanomaterial labeling and workplace exposure limits that WS2 manufacturers must satisfy for domestic sales authorization. Stakeholders should monitor evolving battery safety certifications in South Korea and Japan, as MFDS and METI guidelines for solid-state cell components will likely incorporate nanoparticle-specific testing protocols that reshape supplier qualification timelines.
Market Dynamics
East Asian battery manufacturers are consolidating procurement contracts for solid-state electrolyte interfaces, compressing supplier qualification timelines and favoring producers with captive tungsten feedstock.
Growth Catalysts
- Solid-state battery interfaces:South Korean and Japanese cell manufacturers are expanding WS2 nanoparticle offtake for sulfide-based electrolyte layers, creating dedicated supply agreements with specialty chemical producers.
- REACH nanomaterial registration:The European Union's tightening purity thresholds for consumer-facing applications are filtering out commodity traders and rewarding dossier-compliant manufacturers with pricing premiums.
- Jiangsu-Zhejiang cluster expansion:China's domestic semiconductor foundries are localizing WS2 procurement through provincial specialty chemical parks, reducing import dependency for high-purity grades.
Market Restraints
- Tungsten ore concentration:Over sixty percent of mined tungsten concentrate originates from Chinese state-affiliated mining consortia, exposing non-integrated processors to export quota volatility.
- Hydrothermal synthesis yield limits:Batch-to-batch crystallinity variation in wet-chemical routes constrains semiconductor-grade output, forcing buyers toward higher-cost chemical vapor deposition sources.
- Molybdenum disulphide substitution:MoS2 nanoparticles compete directly in lubricant and catalyst applications where thermal tolerance requirements fall below four hundred degrees Celsius.
Strategic Opportunities
- Indian specialty chemical parks:Gujarat and Maharashtra state industrial corridors offer tariff advantages for WS2 dispersion manufacturing serving domestic automotive lubricant blenders.
- EU Green Deal synthesis mandates:Lower-carbon hydrothermal and mechanochemical processing routes qualify for green procurement preferences across European coating plants.
- Direct-to-foundry digital channels:Specialty nanoparticle distributors are bypassing regional chemical traders to serve Taiwan and South Korean semiconductor fabs through qualified supplier portals.
Industry Challenges
- MFDS and METI certification timelines:South Korean and Japanese battery safety protocols for solid-state cell components lack harmonized nanoparticle-specific testing standards, forcing redundant qualification cycles.
- Surface functionalization expertise:Dispersion stability engineering for lithium-sulfur electrolyte slurries requires scarce colloid chemistry talent concentrated in academic spinouts.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Tungsten Disulphide Nanoparticles Market |
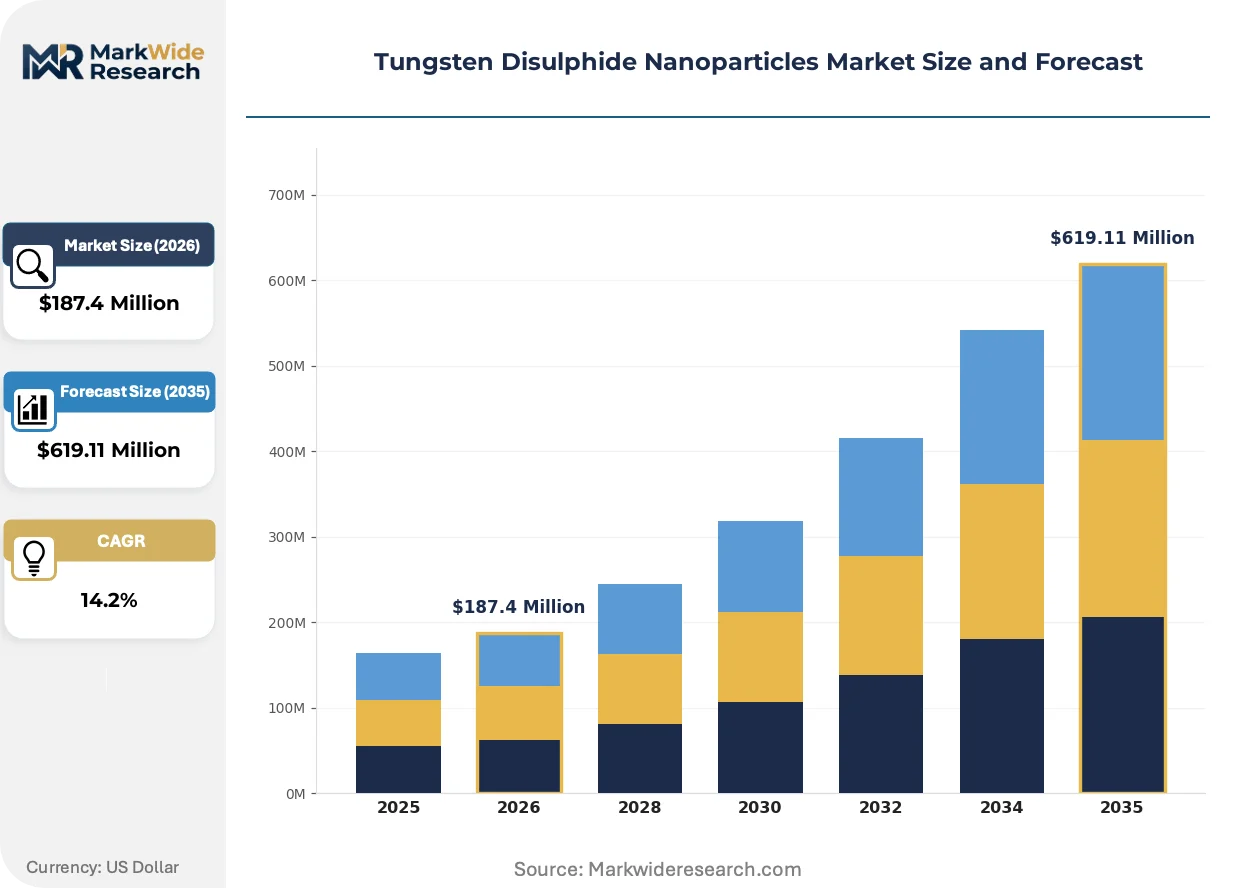
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Form: Powder, Suspension, Dispersion, Coated Particles Technology: Chemical Vapor Deposition, Ball Milling, Hydrothermal Synthesis, Solvothermal Method Application: Lubricants, Electronics, Battery Materials, Catalysts, Photovoltaics End User: Semiconductor Manufacturers, Battery Producers, Coating Plants, Chemical Processing Plants |
| Companies Covered | H.C. Starck Tungsten Powders, American Elements, Nanografi Nano Technology, SkySpring Nanomaterials, Inc., US Research Nanomaterials, Inc., Nanostructured & Amorphous Materials, Inc., Nanoshel LLC, Luoyang Tongrun Nano Technology Co., Ltd., EPRUI Nanoparticles & Microspheres Co. Ltd, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Tungsten Disulphide Nanoparticles Market Evolving Landscape
Synthesis methodology and regulatory compliance frameworks are diverging across geographies, creating technology-forcing conditions that favor integrated producers over trading intermediaries.
Mechanochemical ball-milling is modularizing WS2 nanoparticle production for mid-volume catalyst applications. Specialty chemical plants in China's Shandong province are retrofitting existing milling infrastructure to produce sub-50nm particle distributions at throughputs competitive with hydrothermal batch processing. This route is compressing capital barriers for regional entrants while crystallinity limitations keep semiconductor applications tethered to chemical vapor deposition.
REACH registration dossiers now mandate full toxicity profiles for WS2 volumes exceeding one tonne annually. The European Chemicals Agency's 2024 guidance on nanomaterial hazard classification is forcing reformulation of consumer-facing lubricant sprays and cosmetic additives. German and French coating manufacturers are responding by segregating industrial-grade and consumer-grade production lines to isolate compliance costs.
Semiconductor foundries are consolidating qualified supplier lists to single-source arrangements for critical solid lubricant precursors. Taiwan and South Korean fabs are extending vendor audit cycles from twelve to twenty-four months, favoring established producers with multi-year regulatory track records. This concentration is visible most acutely in EUV lithography component supply chains where particle purity specifications exceed 99.995 percent.
Tungsten Disulphide Nanoparticles Market Segmentation
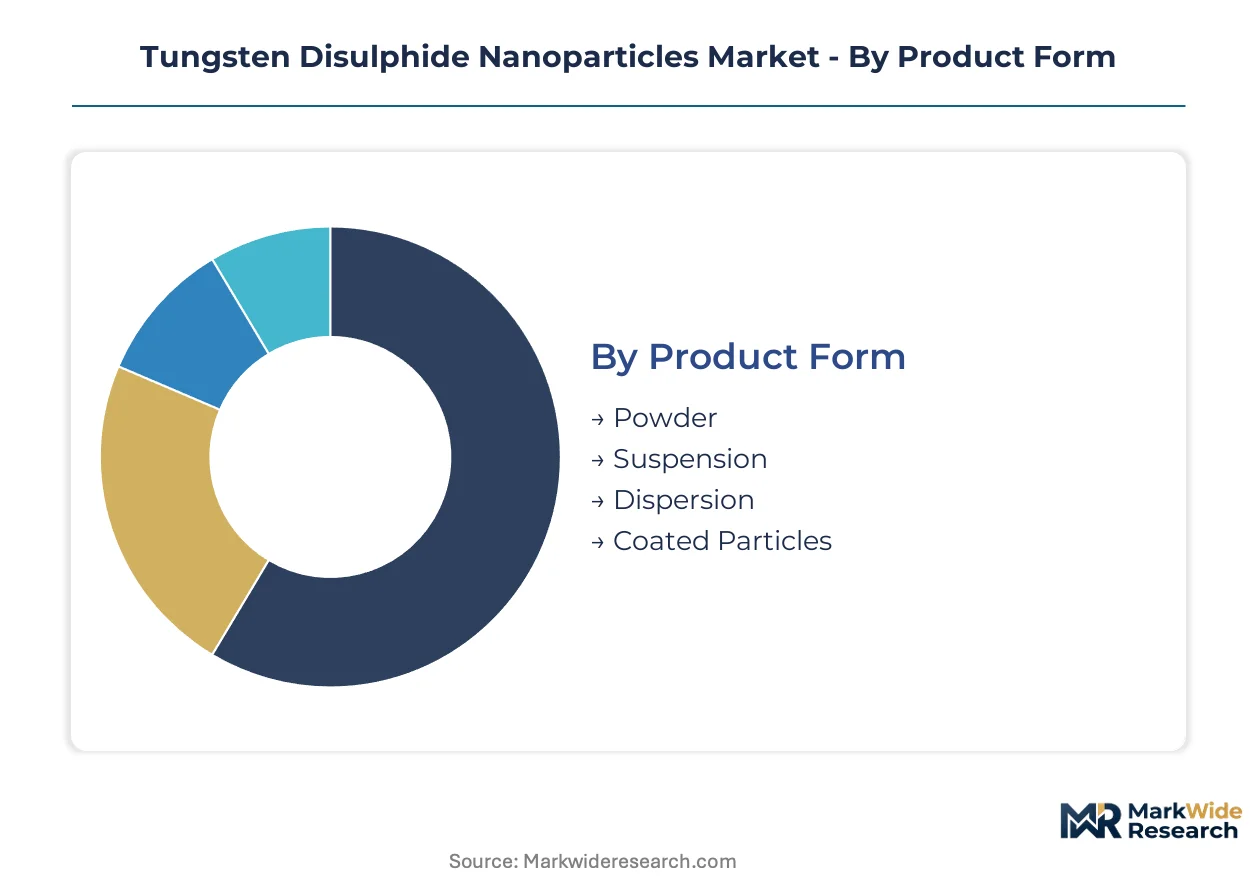
WS2 nanoparticle buyers diverge sharply by handling requirements and integration complexity. Semiconductor fabs demand crystalline precision; battery producers prioritize dispersion stability for slurry processing.
Product Form:
Buyers separate by equipment compatibility and downstream processing steps.
- Powder:Dry crystalline WS2 with particle sizes typically spanning 50-500 nanometres enables direct incorporation into solid lubricant greases and polymer masterbatches. Semiconductor foundries in Taiwan and South Korea specify powder grades for physical vapor deposition precursor materials, though handling protocols require nitrogen-purged environments to prevent surface oxidation.
- Dispersion:Pre-stabilized colloidal suspensions in organic or aqueous carriers eliminate agglomeration risks during battery electrolyte formulation. Jiangsu province coating plants are expanding procurement of dispersion grades for lithium-sulfur cell manufacturing, where uniform particle distribution determines cycling stability.
- Suspension:Intermediate liquid concentrates serve chemical processing plants seeking controlled dosing into continuous reactor streams.
- Coated Particles:Surface-functionalized WS2 with silica or polymer shells targets photovoltaics applications requiring enhanced environmental resistance.
Volume sits with powder; growth tilts toward dispersion.
Technology:
Cost structure and crystallinity requirements split procurement between high-purity and scale-oriented routes.
- Chemical Vapor Deposition:Gas-phase reaction of tungsten hexachloride and hydrogen sulfide at 800-1000°C yields hexagonal crystallites with interlayer spacing precision critical for EUV lithography components. South Korean semiconductor suppliers pay premiums for CVD material after twenty-four-month vendor qualification cycles.
- Hydrothermal Synthesis:Aqueous ammonium tungstate decomposition at 200-300°C under autogenous pressure offers throughput economics that Shandong province chemical parks favor for catalyst manufacturing, though batch-to-batch lattice defect variation constrains electronics-grade adoption.
- Ball Milling:Mechanochemical exfoliation of bulk WS2 in surfactant-stabilized media produces sub-50nm distributions without solvent-intensive processing.
- Solvothermal Method:Organic solvent-mediated crystal growth enables morphology control for niche photonics applications.
Ball milling captures mid-volume share; CVD commands margin premiums.
Application:
Thermal tolerance thresholds and electrical conductivity specifications determine grade selection.
- Lubricants:WS2's lamellar structure enables shear-induced interlayer slip under loads exceeding 300,000 psi, serving aerospace and automotive grease formulators where molybdenum disulphide fails above 400°C.
- Battery Materials:Solid-state electrolyte interfaces in sulfide-based cells exploit WS2's ionic conductivity and mechanical compliance to suppress dendrite formation. Japanese cell manufacturers are qualifying Korean and Chinese suppliers for 2025-2026 platform launches.
- Electronics:Thin-film transistors and flexible sensors exploit the material's semiconducting 2D properties.
- Catalysts:Edge-site-rich nanoparticles drive hydrogen evolution reaction efficiency in alkaline electrolyzers.
- Photovoltaics:Transparent conductive layers in perovskite tandem architectures test WS2's optical properties.
Lubricants anchor current revenue; battery materials are climbing the fastest.
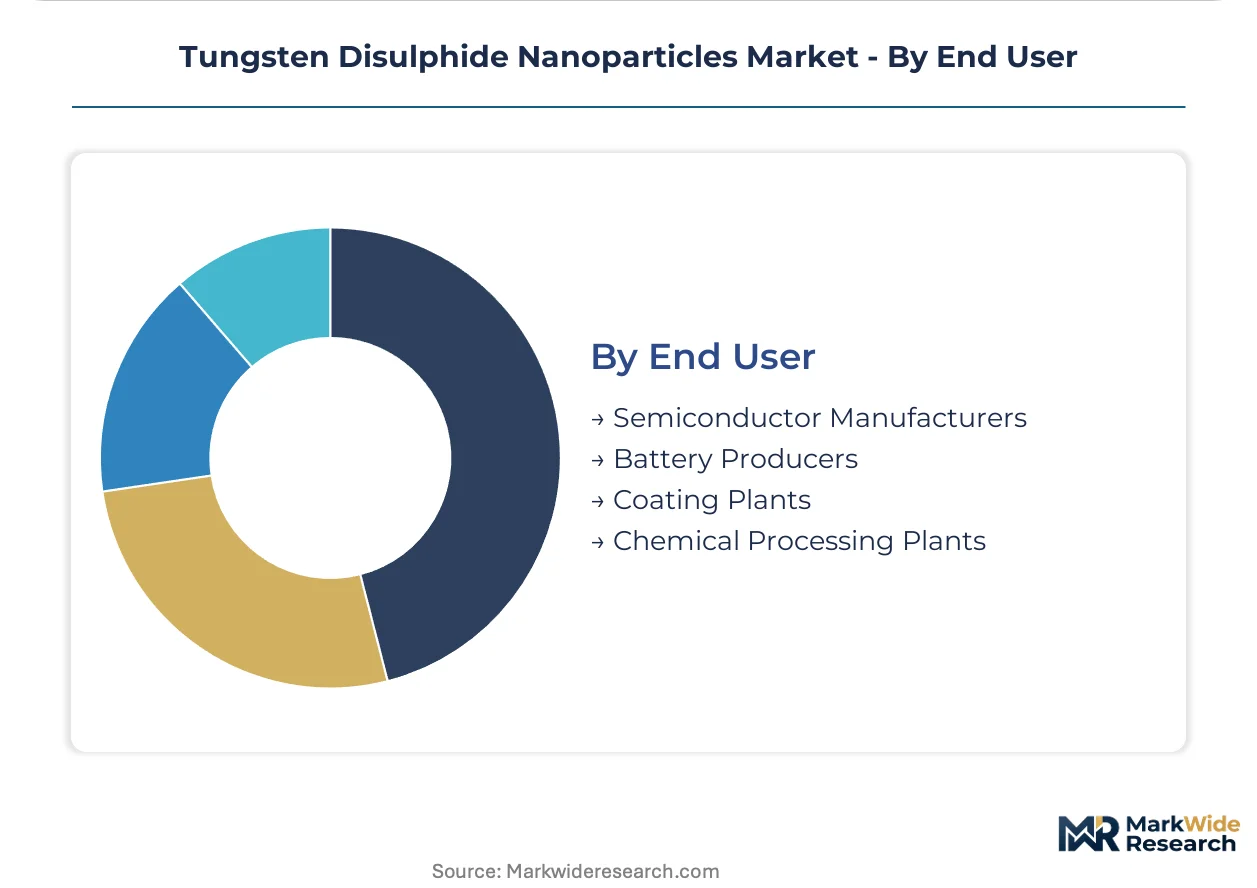
End User:
Qualification rigor and contract duration separate institutional procurement patterns.
- Semiconductor Manufacturers:Taiwan and South Korean fabs enforce 99.995% purity specifications with particle count protocols exceeding pharmaceutical cleanroom standards. Single-source agreements predominate after multi-year audit cycles.
- Battery Producers:South Korean and Japanese cell makers are compressing supplier onboarding from eighteen to twelve months for solid-state programs, favoring integrated tungsten processors with captive ore supply.
- Coating Plants:European automotive and industrial finishers specify WS2 for extreme-pressure lubricant films.
- Chemical Processing Plants:Petrochemical refiners and specialty chemical producers deploy WS2 catalysts for hydrodesulfurization upgrades.
Semiconductor manufacturers lock in supply; battery producers are expanding supplier rosters.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Jiangsu and Zhejiang provinces anchor regional procurement concentration, with specialty chemical clusters serving domestic semiconductor foundries and battery manufacturers across East Asia's manufacturing corridor.
China
Solid-state battery manufacturers in Jiangsu province are expanding WS2 nanoparticle procurement for sulfide-based electrolyte interfaces. SAMR enforces GB standards for nanomaterial labeling and workplace exposure limits that domestic producers must satisfy for sales authorization. Shandong province chemical parks are retrofitting mechanochemical ball-milling infrastructure to produce sub-50nm particle distributions.
South Korea
Cell manufacturers are compressing supplier qualification timelines from eighteen to twelve months for solid-state platform launches. MFDS battery safety protocols for solid-state cell components are evolving toward nanoparticle-specific testing standards that reshape supplier onboarding. Seoul Capital Area fabs are consolidating qualified supplier lists to single-source arrangements for EUV lithography component precursors.
Japan
Japanese cell makers are qualifying Korean and Chinese WS2 suppliers for 2025-2026 solid-state battery platform launches. METI guidelines for solid-state cell components will likely incorporate nanoparticle-specific testing protocols. Nagoya-area semiconductor suppliers pay premiums for chemical vapor deposition material after extended vendor qualification cycles.
United States
Battery R&D buyers in North America sustain demand for broad catalog breadth across powder and dispersion grades. EPA oversight governs nanomaterial reporting under the Toxic Substances Control Act, compelling importers to document particle size distributions before commercial distribution. Greater Boston and Pacific Northwest research corridors concentrate specialty nanoparticle procurement for advanced materials development.
Germany
German coating manufacturers are segregating industrial-grade and consumer-grade production lines to isolate REACH compliance costs. ECHA's 2024 guidance on nanomaterial hazard classification forces reformulation of consumer-facing lubricant sprays. Bavaria and North Rhine-Westphalia industrial clusters serve automotive and aerospace grease formulators requiring extreme-pressure thermal tolerance.
Tungsten Disulphide Nanoparticles Market Competitive Landscape
The competitive structure tilts toward integrated tungsten processors with captive ore supply and specialty chemical producers with regulatory dossier capabilities. Market concentration favors producers with backward integration into feedstock and forward integration into high-purity synthesis routes. Two strategic archetypes dominate: state-affiliated mining consortia leveraging ore concentration advantages, and specialty nanoparticle engineering firms competing on specification tightness. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with foundry-direct digital channels displacing regional chemical traders.
Among integrated material processors, H.C. Starck Tungsten Powders represents the captive feedstock archetype, while American Elements exemplifies broad-catalog positioning across research and industrial grades. Nanografi Nano Technology occupies a position within the specification-driven tier, competing on particle engineering precision rather than volume scale.
| Leading Market Players |
|---|
| H.C. Starck Tungsten Powders |
| American Elements |
| Nanografi Nano Technology |
| SkySpring Nanomaterials, Inc. |
| US Research Nanomaterials, Inc. |
| Nanostructured & Amorphous Materials, Inc. |
| Nanoshel LLC |
| Luoyang Tongrun Nano Technology Co., Ltd. |
| EPRUI Nanoparticles & Microspheres Co. Ltd |
| Others |
Value Network & Pricing Analysis
Colloid chemistry expertise concentrated in Jiangsu and Zhejiang province academic spinouts commands wage premiums that widen spreads between semiconductor-grade dispersion pricing and commodity powder tiers. Labor-cost differentials between coastal synthesis hubs and inland mechanochemical operations translate into pricing stratification across premium, standard, and economy levels.
Pricing Analysis
Yield-guaranteed pricing for battery electrolyte slurry integration anchors value-based contracts for dispersion grades, with chemical vapor deposition material commanding premiums after extended vendor qualification cycles. Price differentiation separates REACH-registered dossier-compliant manufacturers from unregistered traders, while volume scale and certification tier further stratify quotes. Cost compression in hydrothermal-synthesis powder grades is intensifying because Shandong province ball-milling retrofits expand sub-50nm capacity. Battery producers exhibit highest price sensitivity due to compressed supplier onboarding timelines, whereas semiconductor fabs prioritize purity guarantees over unit economics.
Supply Chain Analysis
China's GB standards for nanomaterial labeling and domestic-content preferences in Jiangsu specialty chemical parks are reshaping sourcing toward captive tungsten processors with in-house ore supply. Feedstock draws from Chinese state-affiliated mining consortia, South Korean semiconductor precursor specialists, and German coating chemical distributors. Raw material dependencies center on tungsten ore concentrate, ammonium tungstate precursor chemicals, and hydrogen sulfide reagent gas. Single-source vulnerability runs through Chinese ore concentration exceeding sixty percent of mined supply. Distribution runs through qualified supplier portals bypassing regional chemical traders for foundry-direct fulfillment.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market reads as supply-constrained, with chemical vapor deposition crystallinity bottlenecks propping pricing premiums for semiconductor-grade output.
For Market Incumbents: Extend qualification-track record advantages by deepening captive ore integration and accelerating REACH dossier updates ahead of ECHA's nanomaterial hazard classification enforcement. Molybdenum disulphide substitution in sub-400°C lubricant applications threatens volume-tier margins; defend through thermal-tolerance specification tightening and long-term offtake anchoring with South Korean battery platforms. For New Entrants and Emerging Players: The premium-economy tier price-point gap in Indian automotive lubricant blending opens white-space entry through Gujarat and Maharashtra state industrial corridor tariff positioning. Mechanochemical ball-milling retrofit economics enable mid-volume catalyst-grade competition without CVD capital intensity. Target direct-to-foundry digital channel bypass of entrenched regional traders for Taiwan and South Korean semiconductor fab procurement. For Investors and Strategic Acquirers: The window for entry favors specialty nanoparticle engineering firms with surface functionalization IP and regulatory dossier capabilities rather than commodity powder traders. Long-term viability hinges on backward integration into tungsten ore processing and forward qualification into solid-state battery supply chains. Watch for MFDS and METI harmonization on nanoparticle-specific testing standards as inflection signal for supplier consolidation acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Tungsten Ore Processing | H.C. Starck's captive feedstock model insulates margins from Chinese export quota volatility. |
| REACH Dossier Compliance Investment | ECHA registration mandates filter commodity traders and reward compliant manufacturers with pricing premiums. |
| Mechanochemical Ball-Milling Retrofit | Shandong province chemical parks compress capital barriers for sub-50nm catalyst-grade output. |
| Direct-to-Foundry Digital Channel | Specialty distributors bypass regional traders to serve Taiwan and South Korean semiconductor fabs. |
| Surface Functionalization R&D Partnership | Academic spinout alliances secure scarce colloid chemistry talent for lithium-sulfur dispersion stability. |
Research Methodology
Document review covered customs and trade flow databases, ECHA registration filings, and SAMR GB standard documentation, complemented by interviews with specialty chemical plant managers, battery procurement leads at South Korean cell manufacturers, semiconductor foundry materials engineers, and tungsten ore trading specialists. Secondary validation drew from SEC 10-K filings of listed material processors, industry association technical reports, and patent landscape analysis. Bottom-up volume modeling and top-down value triangulation cross-referenced shipment data against end-use application scaling assumptions.
Historical capacity utilization patterns were cross-referenced against expert panel input on qualification timeline compression and synthesis route economics. Segmentation dimensions modeled include product form, synthesis technology, application thermal tolerance threshold, end-user qualification rigor, and regional regulatory cluster. CAGRs were derived from slope analysis of application-specific adoption curves and supply-side capacity expansion schedules, with semiconductor foundry single-source consolidation and battery platform launch calendars serving as industry-specific forecast inputs.
Inputs from South Korean and Japanese regulatory agencies were available through the study window; gaps in real-time supplier qualification pipeline data introduce uncertainty bands around market share shift timing. Forecasts reflect assumptions on solid-state battery platform commercialization cadence and REACH enforcement consistency. Within these boundaries, the analytical envelope holds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Nanosilica Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Global Nanocrystalline Cellulose Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Nano Fillers Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Nanoceramic Market