
 United States Floor Coatings Market | 2026-2036
United States Floor Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United States Floor Coatings Market Analytics
Equipment leasing and project financing for industrial flooring contractors is narrowing the capital barrier for mid-tier applicators to bid on large commercial installations. BASF leverages its integrated resin supply chain to control raw material costs across epoxy and polyurethane systems. The Sherwin-Williams Company sustains dominant retail and direct-to-contractor channel coverage through its national store network. PPG Industries Inc. specializes in high-performance polyaspartic formulations that command premium positioning in fast-cure applications.
United States floor coatings comprise resin-based protective layers applied to concrete, wood, or metal substrates, typically formulated with epoxy, polyurethane, or polyaspartic polymers at film builds ranging from four to one hundred twenty mils to resist abrasion, chemical attack, and moisture intrusion. Their primary purpose spans industrial manufacturing floors, commercial retail spaces, and institutional healthcare environments where substrate longevity and safety compliance are critical. Epoxy products occupy the largest volume share due to proven performance in heavy-traffic manufacturing settings, while polyaspartic segments represent the fastest expansion trajectory driven by rapid return-to-service demands in commercial and retail end uses. Water-based formulations are gaining share against solvent-based alternatives as VOC regulations tighten and healthcare and education end users prioritize indoor air quality during application.
The EPA enforces VOC content limits under the National Volatile Organic Compound Emission Standards for Architectural Coatings, directly constraining solvent-based product formulations and redirecting R&D investment toward compliant water-based and high-solids systems. OSHA maintains slip-resistance and workplace safety standards that mandate specific surface texture profiles in industrial and manufacturing applications, creating specification pull-through for textured epoxy and broadcast systems. State-level regulations in California through the South Coast Air Quality Management District impose additional formulation constraints that exceed federal minimums, forcing suppliers to maintain dual product portfolios. Stakeholders must monitor evolving state-level air quality rules and federal infrastructure spending allocations to anticipate demand surges in public-sector manufacturing, education, and healthcare flooring projects.
Market Dynamics
EPA VOC emission standards under the Clean Air Act are compressing solvent-based formulation lifecycles and forcing capital reallocation toward water-based resin systems across industrial coating operations.
Growth Catalysts
- Commercial warehouse expansion:Distribution hub operators in Texas, California, and Ohio are accelerating protective flooring installations to withstand forklift traffic and chemical exposure in high-velocity logistics environments.
- EPA regulatory pressure:The National Volatile Organic Compound Emission Standards for Architectural Coatings are redirecting manufacturer R&D budgets toward compliant low-solvent and water-based polymer systems.
- Polyaspartic technology maturation:Rapid return-to-service capabilities are opening specification pathways in retail and healthcare sectors where downtime minimization commands premium pricing.
Market Restraints
- Epoxy resin supply concentration:Raw material sourcing for bisphenol-A and epichlorohydrin derivatives concentrates among Asian petrochemical producers, exposing formulators to freight cost volatility and currency fluctuation risk.
- Application skill scarcity:Proper film build achievement and moisture vapor transmission control require certified installer expertise that remains concentrated in legacy industrial corridors, constraining geographic expansion.
- Substrate preparation intensity:Concrete surface profiling, crack repair, and moisture mitigation add labor hours that compress contractor margins on fixed-bid commercial projects.
Strategic Opportunities
- Healthcare facility retrofit wave:Hospital and long-term care operators in Florida and Arizona are prioritizing seamless, antimicrobial flooring systems that support infection control protocols and indoor air quality mandates.
- Infrastructure spending allocation:Federal transportation and education facility appropriations are creating specification pipelines for high-durability coatings in airport terminals, bus depots, and K-12 renovation projects.
- Water-based polyurethane convergence:Advances in aliphatic isocyanate dispersion technology are enabling UV-stable, low-odor systems that penetrate premium residential and commercial segments previously dominated by solventborne alternatives.
Industry Challenges
- Certification timeline compression:South Coast Air Quality Management District formulation approvals and LEED v4.1 compliance documentation are extending product launch cycles by eight to fourteen months for California-targeted portfolios.
- Moisture-related failure liability:Calcium chloride testing protocol disputes and vapor emission warranty claims are elevating contractor insurance costs and forcing substrate guarantee renegotiations.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Floor Coatings Market |
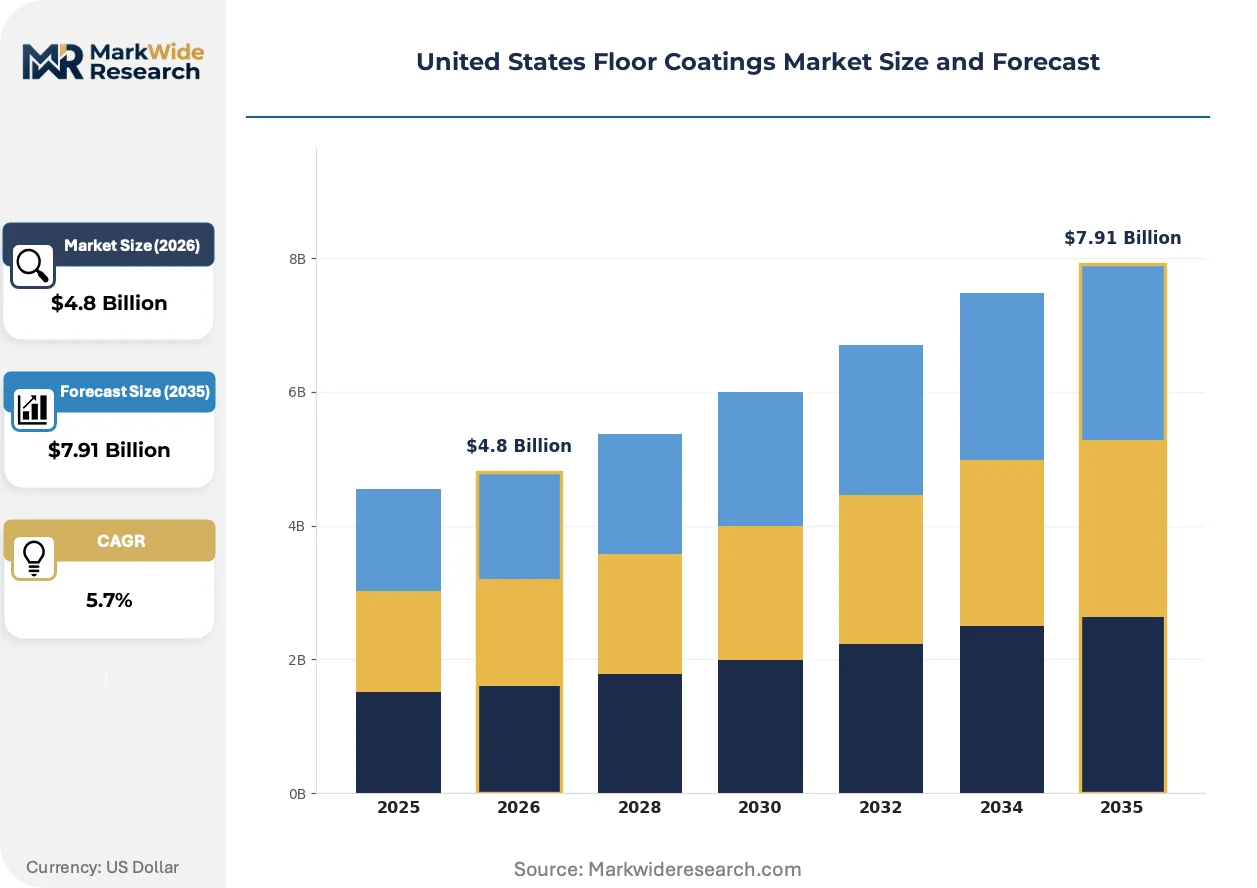
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $7.91 Billion |
| CAGR (2026 – 2036) | 5.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Polyaspartic Application: Industrial, Commercial, Residential, Agricultural Form: Liquid, Powder, Solvent-Based, Water-Based End User: Manufacturing, Healthcare, Education, Retail |
| Companies Covered | BASF, Axalta Coating Systems, The Sherwin-Williams Company, Stonhard, Akzo Nobel N.V., PPG Industries Inc., RPM International Inc., 3M, Sika AG, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Floor Coatings Market Evolving Landscape
Formulation chemistry and application economics are diverging as regulatory constraints and end-use performance requirements reshape competitive priorities across resin system categories.
High-solids polyurethane technology is migrating from automotive assembly plant maintenance departments into food and beverage processing environments where thermal shock resistance and cleanability standards are intensifying. Breweries and dairy processors in Wisconsin and Colorado are specifying these systems for pasteurization zone floors exposed to rapid temperature cycling. The shift is compressing specification windows for traditional epoxy novolacs in wet-process manufacturing.
OSHA workplace safety enforcement is elevating slip-resistance testing requirements for industrial epoxy and broadcast quartz systems in manufacturing settings. The agency's updated guidance on walkway surface profiles is forcing reformulation of smooth, high-gloss finishes toward textured aggregates that meet coefficient-of-friction thresholds. Chemical processing and metal fabrication facilities in the Gulf Coast petrochemical corridor are experiencing the most acute specification disruption.
Project bundling is consolidating flooring decisions with broader facility maintenance contracts as property management firms and institutional owners seek single-source accountability for capital improvement spend. National retail chains and hospital systems are migrating from transactional material procurement toward multi-site master service agreements with certified applicator networks. The pattern is most pronounced in Sun Belt metropolitan markets where construction cost inflation has compressed discretionary maintenance budgets.
United States Floor Coatings Market Segmentation
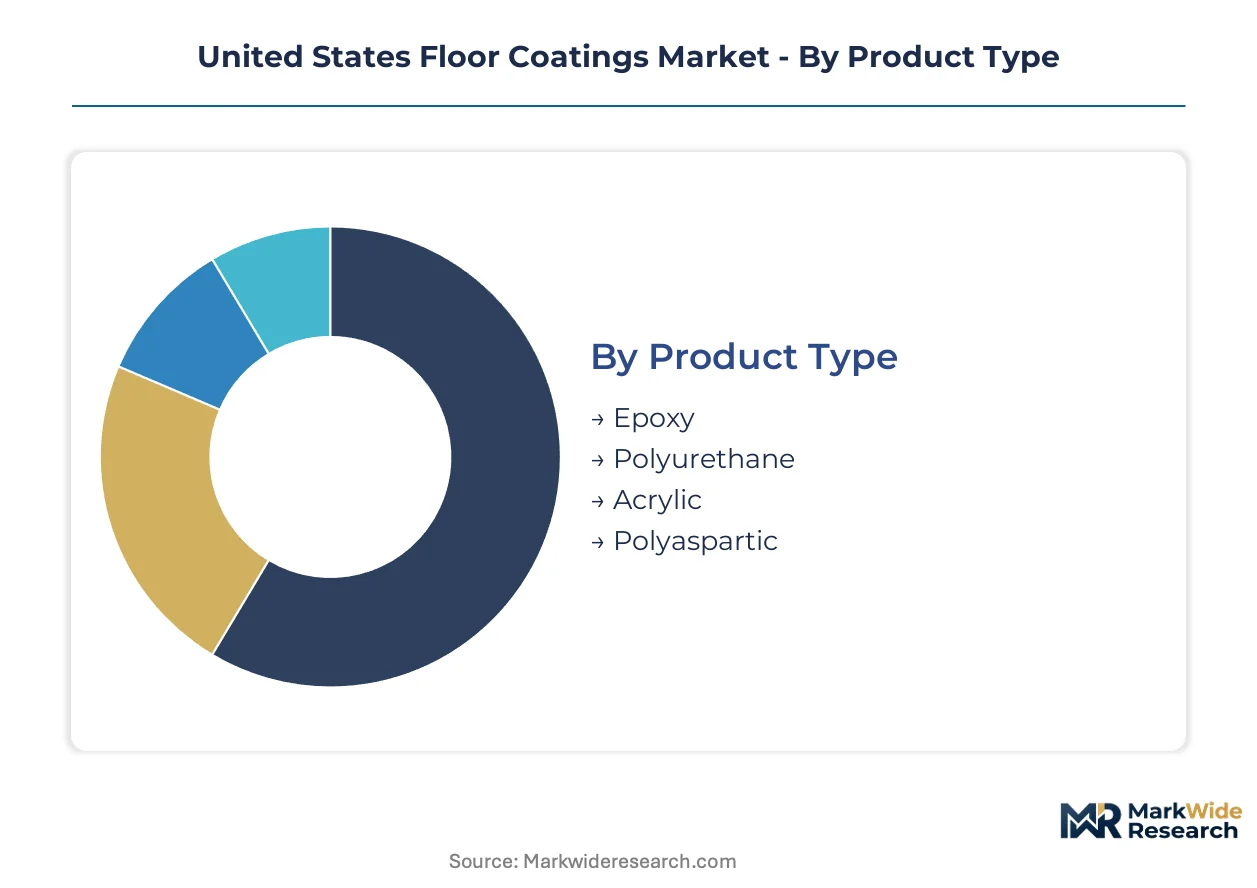
Floor coatings command distinct specification pathways across resin chemistry, installation environment, and regulatory exposure. Segmentation discipline separates volume-driven industrial maintenance from premium commercial retrofits where cure speed and air quality compliance determine bid outcomes.
Product Type:
After-sales service intensity concentrates in epoxy and polyurethane systems where applicator certification, warranty claims, and failure remediation create recurring revenue attachment for manufacturers.
- Epoxy:Formulated from bisphenol-A and epichlorohydrin precursors, these thermosetting systems achieve film builds of 10-120 mils for heavy manufacturing floors. Demand clusters in Ohio and Texas automotive stamping plants where chemical resistance and forklift traffic abrasion dominate specification criteria. After-sales service includes moisture vapor emission testing and delamination repair protocols that extend contractor engagement cycles.
- Polyurethane:Aliphatic and aromatic isocyanate-cured elastomers deliver UV stability and thermal shock resistance for food processing environments. Wisconsin dairy processors and Colorado craft breweries specify these systems for pasteurization zones exposed to rapid temperature cycling. Service intensity manifests in recoat scheduling and slip-resistance re-certification.
- Acrylic:Water-dispersed methacrylate polymers serve decorative commercial and light industrial applications in retail and institutional settings.
- Polyaspartic:Rapid-cure aliphatic polyurea technology enables return-to-service within hours for healthcare and retail environments where downtime costs exceed material premiums.
Epoxy holds the largest share; momentum sits with polyaspartic.
Application:
Cost tier stratification separates specification authority between capital-project engineering teams and facilities maintenance managers with discretionary spend constraints.
- Industrial:Heavy-traffic manufacturing floors in Gulf Coast petrochemical corridors and Midwest metal fabrication plants require chemical-resistant epoxy novolacs and broadcast quartz systems. OSHA slip-resistance mandates drive textured aggregate specifications that elevate installed cost per square foot.
- Commercial:Retail chains and hospitality operators in Sun Belt metropolitan markets prioritize rapid-cure polyaspartics and water-based polyurethanes for renovation scheduling flexibility. Master service agreements with national applicator networks consolidate procurement decisions.
- Residential:Garage floor and basement applications in suburban construction markets favor DIY-compatible epoxy kits and decorative flake systems.
- Agricultural:Dairy barns and food processing facilities specify antimicrobial seamless flooring with thermal cycling tolerance.
Industrial commands the revenue base; commercial is climbing the fastest.
Form:
Volume concentration in water-based formulations reflects EPA VOC enforcement trajectory and healthcare sector indoor air quality procurement mandates.
- Liquid:Self-leveling and trowel-applied resin systems dominate industrial and commercial installations where film build precision controls performance outcomes.
- Powder:Thermosetting epoxy powders serve specialty electrical and corrosion-resistant applications with zero VOC emission profiles.
- Solvent-Based:High-solids alkyds and urethanes retain foothold in exterior concrete sealing and rapid-field-repair scenarios where water sensitivity prohibits aqueous formulations.
- Water-Based:Low-odor acrylic and polyurethane dispersions penetrate K-12 education and healthcare retrofit specifications where occupancy during application drives selection criteria.
Liquid maintains installed volume leadership; water-based is gaining share fastest.
End User:
Customer type differentiation separates specification complexity between engineered capital projects and maintenance-driven refresh cycles.
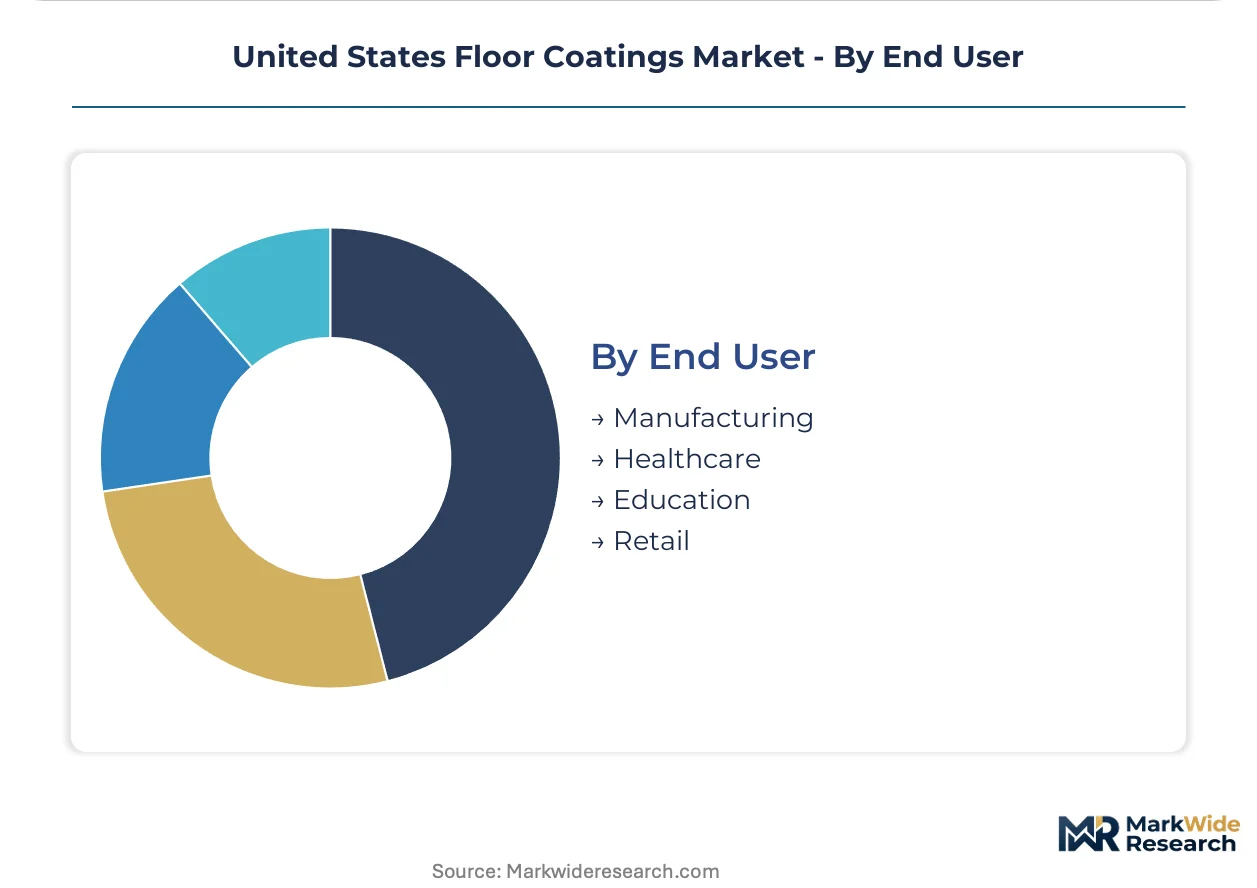
- Manufacturing:Automotive assembly plants in Michigan and battery gigafactories in Nevada specify conductive and chemical-resistant epoxy systems for ESD protection and electrolyte spill containment. Procurement runs through engineering teams with multi-year capital planning horizons.
- Healthcare:Hospital systems in Florida and Arizona prioritize seamless, antimicrobial polyurethane and polyaspartic systems that support infection control protocols and Joint Commission accreditation standards.
- Education:K-12 districts and university facilities managers balance durability requirements against summer renovation window constraints.
- Retail:National chains specify standardized flooring packages across distribution centers and storefront networks.
Manufacturing anchors the revenue base; healthcare shows the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Federal infrastructure appropriations and state-level air quality mandates are redistributing demand across manufacturing corridors and Sun Belt metropolitan markets. The EPA's VOC enforcement under the Clean Air Act compresses solvent-based formulation viability while accelerating specification shifts toward compliant systems in high-growth states.
Texas
Distribution hub operators in Dallas-Fort Worth and Houston are expanding protective flooring installations to withstand forklift traffic and chemical exposure in high-velocity logistics environments. The Texas Commission on Environmental Quality enforces VOC content limits that align with federal minimums while allowing flexibility for industrial maintenance applications. The Gulf Coast petrochemical corridor concentrates demand for chemical-resistant epoxy novolacs in processing facilities and refineries.
California
Healthcare facility operators in Los Angeles and San Francisco are prioritizing seamless, antimicrobial flooring systems that support infection control protocols and indoor air quality mandates. The South Coast Air Quality Management District imposes formulation constraints that exceed federal minimums, forcing suppliers to maintain dual product portfolios for California-targeted specifications. The Central Valley food processing belt is specifying high-solids polyurethane systems for thermal shock resistance in pasteurization zones.
Ohio
Automotive stamping plants in Toledo and Cleveland are specifying conductive epoxy systems for ESD protection in battery assembly and electronics manufacturing. The Ohio EPA administers VOC permitting under delegated Clean Air Act authority with particular scrutiny of large surface coating operations. The Midwest manufacturing corridor is experiencing shortened refurbishment cycles as capital equipment depreciation schedules compress.
Michigan
Battery gigafactories in Detroit and Grand Rapids are driving specification demand for electrolyte spill containment and chemical-resistant flooring in cleanroom environments. The Michigan Department of Environment, Great Lakes, and Energy coordinates with federal OSHA on workplace safety standards for slip-resistant surface profiles. The automotive assembly plant network is migrating toward rapid-cure polyaspartic systems to minimize production downtime during maintenance windows.
Florida
Hospital and long-term care operators in Miami and Tampa are retrofitting seamless flooring to meet Joint Commission accreditation standards and antimicrobial performance requirements. The Florida Department of Environmental Protection enforces VOC limits for architectural coatings with particular attention to healthcare and education sector applications. The Sun Belt retirement community expansion is creating specification pipelines for low-odor, water-based systems that accommodate occupancy during application.
United States Floor Coatings Market Competitive Landscape
Channel-controlling players compete with product-specialist players across distinct specification pathways in the United States floor coatings market. National store networks and direct-to-contractor relationships dominate volume distribution in commercial and residential segments, while integrated resin suppliers capture margin through captive raw material access. Three archetypes define competitive positioning: vertically integrated chemical conglomerates controlling precursor supply chains, specialty coating formulators with certified applicator networks, and diversified industrial materials companies with project bundling capabilities. M&A activity concentrates on regional applicator network consolidation and water-based formulation technology acquisitions.
Within the integrated chemical conglomerate tier, BASF and PPG Industries Inc. represent upstream-control archetypes that leverage resin manufacturing positions to manage input cost volatility across epoxy and polyurethane systems. Among specialty coating formulators with extensive retail presence, The Sherwin-Williams Company occupies a channel-dominant position through national store network coverage and direct contractor relationships. These three companies exemplify the strategic divergence between raw material integration and distribution control that shapes competitive dynamics in industrial and commercial specification channels.
| Leading Market Players |
|---|
| BASF |
| Axalta Coating Systems |
| The Sherwin-Williams Company |
| Stonhard |
| Akzo Nobel N.V. |
| PPG Industries Inc. |
| RPM International Inc. |
| 3M |
| Sika AG |
| Others |
Value Network & Pricing Analysis
Asian petrochemical concentration for bisphenol-A and epichlorohydrin precursors anchors cost volatility exposure for U.S. formulators, compressing margin pools at the applicator tier where fixed-bid commercial projects dominate procurement patterns. Epoxy resin input cost swings transmit directly to contractor bidding behavior, while water-based formulation premiums capture value in healthcare and education specifications.
Pricing Analysis
Certification level creates the primary spread between premium polyaspartic systems and commodity epoxy kits, with LEED v4.1 compliance and SCAQMD approval extending product launch timelines and supporting 15-25% price premiums in California-targeted portfolios. Three-tier pricing structure separates rapid-cure hospital-grade systems from standard industrial epoxies and economy residential DIY products. Pricing pressure stems from raw material freight cost volatility and currency fluctuation against Asian resin suppliers. Commercial warehouse operators exhibit highest price sensitivity due to large square-footage volumes, while healthcare facilities prioritize performance over unit cost.
Supply Chain Analysis
Bisphenol-A and epichlorohydrin feedstock production concentrates in China, South Korea, and Taiwan, with U.S. formulators drawing from this Asian supply base for epoxy resin precursors. Aliphatic isocyanate dispersions for polyurethane systems rest on German and Japanese specialty chemical production. Single-source vulnerability runs through the Taiwan Strait logistics corridor, where freight rate spikes and port congestion propagate into contractor material costs. Distribution runs through national store networks and direct-to-contractor relationships, with certified applicator networks handling specification-heavy commercial and industrial installations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Platform economics are reshaping procurement as master service agreements consolidate multi-site flooring decisions under single-source accountability, with interoperability between coating systems and facility management software becoming a specification gate.
For Market Incumbents: Insulate specification authority by deepening captive resin supply and accelerating water-based formulation portfolios ahead of EPA VOC enforcement tightening. BASF's integrated bisphenol-A position demonstrates how backward integration buffers raw material volatility. Channel control through certified applicator networks defends against price-transparent e-commerce encroachment in residential segments. For New Entrants and Emerging Players: Pursue geographic white space in the Mountain West and Pacific Northwest where certified installer scarcity constrains incumbent expansion. Water-based polyurethane convergence for K-12 education retrofits offers the most penetrable entry vector, with low-odor systems enabling occupancy-during-application procurement wins. Partner with regional equipment leasing platforms to narrow capital barriers for mid-tier applicator certification. For Investors and Strategic Acquirers: Secondary-cycle assets sit with PE-backed regional applicator networks that consolidated during post-pandemic facility maintenance backlogs. Long-term viability hinges on exposure to healthcare and logistics end-use diversification away from cyclical industrial manufacturing. Monitor South Coast Air Quality Management District rulemaking acceleration as an inflection signal for water-based formulation M&A premiums.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Resin Precursors | BASF's captive bisphenol-A supply shields margin from Asian petrochemical volatility. |
| Water-Based Formulation R&D Acceleration | EPA VOC enforcement under the Clean Air Act redirects R&D budgets toward compliant systems. |
| Certified Applicator Network Expansion | Sherwin-Williams' direct contractor relationships defend channel control against price transparency. |
| Master Service Agreement Penetration | National retail chains consolidate procurement under single-source accountability for capital spend. |
| Polyaspartic Technology Licensing | PPG's rapid-cure formulations command premium positioning in healthcare downtime-minimization specs. |
Research Methodology
Cross-validation between primary interviews with flooring contractors, plant maintenance directors, and healthcare facilities managers anchors the qualitative findings against secondary data from EPA regulatory filings, OSHA safety standard updates, and American Coatings Association industry reports. Bottom-up triangulation against top-down macroeconomic indicators ensures segmentation integrity across resin chemistry, installation environment, and end-use verticals.
Calibration against historical refurbishment cycle data and regional construction spending patterns shapes the analytical framework across the analysis window. Segmentation dimensions include resin type, application environment, formulation chemistry, and end-use vertical with regional regulatory exposure. CAGRs derive from installed base depreciation schedules, VOC compliance transition timelines, and logistics facility construction pipelines.
Macroeconomic conditions sit as an overlay; deviation in construction cost inflation and industrial capital expenditure cycles would shift the trajectory. Cross-checking against Dodge Construction Network regional spending data is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Fire Retardant Coatings Market
Coatings
Wood Preservative Coatings Market
Coatings
Perfluoroalkoxy (PFA) Coatings Market
Coatings
Coating Resins Market
Coatings
Industrial Coatings Market
Coatings
Polyvinylidene Chloride (PVDC) Coated Films Market
Coatings
Water-Based Alkyd Coatings Market
Coatings
Leisure Boat Marine Coatings Market
Coatings
High Performance Epoxy Coating Market
Coatings
Asia-Pacific Thermal Spray Market
Coatings
Cold Gas Spray Coating Market
Coatings
Germany Protective Coatings Market
Coatings
Plastic-Coated Wires Market
Coatings
Automotive Refinish Coatings Market
Coatings
Global Passive Fire Protection Coatings Market
Coatings
Dispersion Coating Market