
 Metal and Metal Oxide Nanoparticles Market | 2026-2036
Metal and Metal Oxide Nanoparticles Market Size, Share, and Industry Trends Forecast 2026-2036
Metal and Metal Oxide Nanoparticles Market Outlook
ISO/TS 19337:2015 qualification for nanoparticle characterization is collapsing the supplier base to laboratories with validated electron microscopy and dynamic light scattering protocols. American Elements leverages its Los Angeles manufacturing campus to sustain vertical integration across rare-earth and transition-metal nanoparticle grades. Nanophase Technologies Corporation anchors North American supply through patented plasma-processed oxide platforms with validated pharmaceutical master files.
Metal and metal oxide nanoparticles are engineered structures with at least one dimension between 1 and 100 nanometers, typically synthesized through sol-gel, flame spray pyrolysis, or plasma arc methods to achieve high surface-area-to-volume ratios for catalytic, optical, or antimicrobial functions. Silver nanoparticles dominate biomedical and electronics applications where surface plasmon resonance and electrical conductivity command premium positioning, while zinc oxide nanoparticles lead cosmetics and coating end users due to broadband UV absorption and GRAS status in topical formulations. Iron oxide nanoparticles specialize in magnetic separation and targeted drug delivery, with superparamagnetic behavior at sub-20 nanometer crystallite sizes creating concentrated margin pools in healthcare procurement.
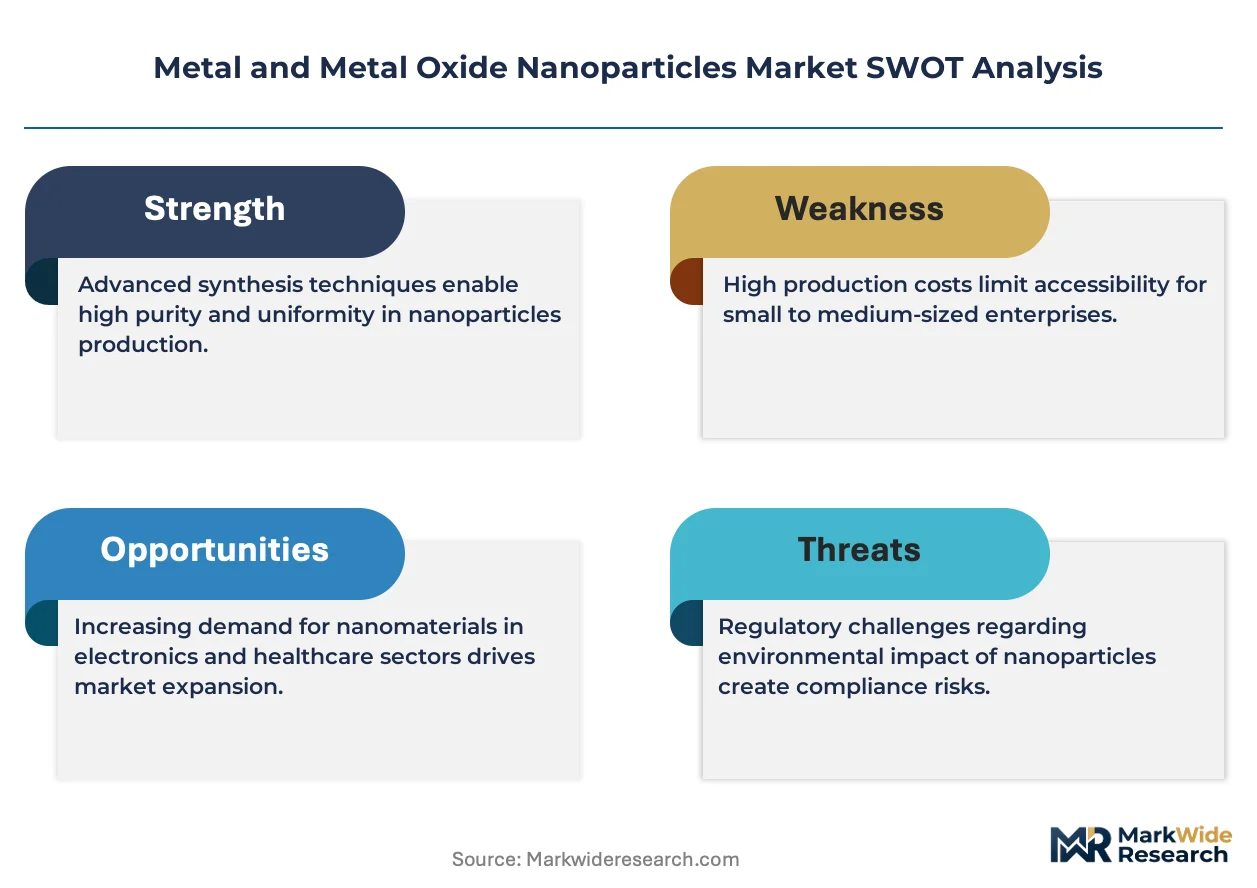
EPA and OSHA frameworks in the United States govern workplace exposure limits and environmental release reporting for engineered nanomaterials, while REACH registration requirements in Europe mandate full toxicological dossiers for nanoparticle substances above tonnage thresholds. The EU Green Deal and advancing MEE guidelines in China are tightening lifecycle assessment obligations, forcing reformulation of legacy oxide products. Stakeholders must monitor evolving nano-specific hazard classifications under OECD testing programs to anticipate product registration barriers and redirect R&D toward inherently safer-by-design architectures.
Market Dynamics
REACH registration dossiers and OSHA permissible exposure limits are forcing nanoparticle suppliers to consolidate around ISO/TS 19337:2015 validated characterization protocols, collapsing the qualified vendor base to laboratories with electron microscopy and dynamic light scattering capabilities.
Growth Catalysts
- UV-shielding coatings:Zinc oxide nanoparticles command premium positioning in cosmetics and automotive clearcoats due to broadband absorption and GRAS status in topical formulations.
- REACH compliance:European chemical registration mandates full toxicological dossiers above tonnage thresholds, accelerating displacement of unqualified suppliers.
- Iron oxide catalysts:Domestic Chinese production scales rapidly for petrochemical and environmental remediation applications.
Market Restraints
- Silver price volatility:Precious metal feedstock costs fluctuate with COMEX futures, compressing margins for conductive ink manufacturers.
- Supplier concentration:Plasma-processed oxide platforms concentrate among North American specialists with pharmaceutical master files.
- Substitution threat:Carbon nanotubes and graphene derivatives displace silver nanoparticles in select flexible electronics applications.
Strategic Opportunities
- Targeted drug delivery:Superparamagnetic iron oxide nanoparticles below 20 nanometers open concentrated margin pools in oncology and diagnostic imaging.
- EU Green Deal:Lifecycle assessment obligations force reformulation of legacy oxide products toward inherently safer-by-design architectures.
- India PLI scheme:Domestic manufacturing incentives attract specialty nanoparticle production for electronics and pharmaceutical export markets.
Industry Challenges
- Electron microscopy expertise:ISO/TS 19337:2015 validation requires scarce technicians trained in transmission electron microscopy sample preparation and statistical particle counting.
- Master file timelines:Pharmaceutical-grade oxide qualifications face 18-24 month FDA Type II drug master file review cycles.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Metal and Metal Oxide Nanoparticles Market |
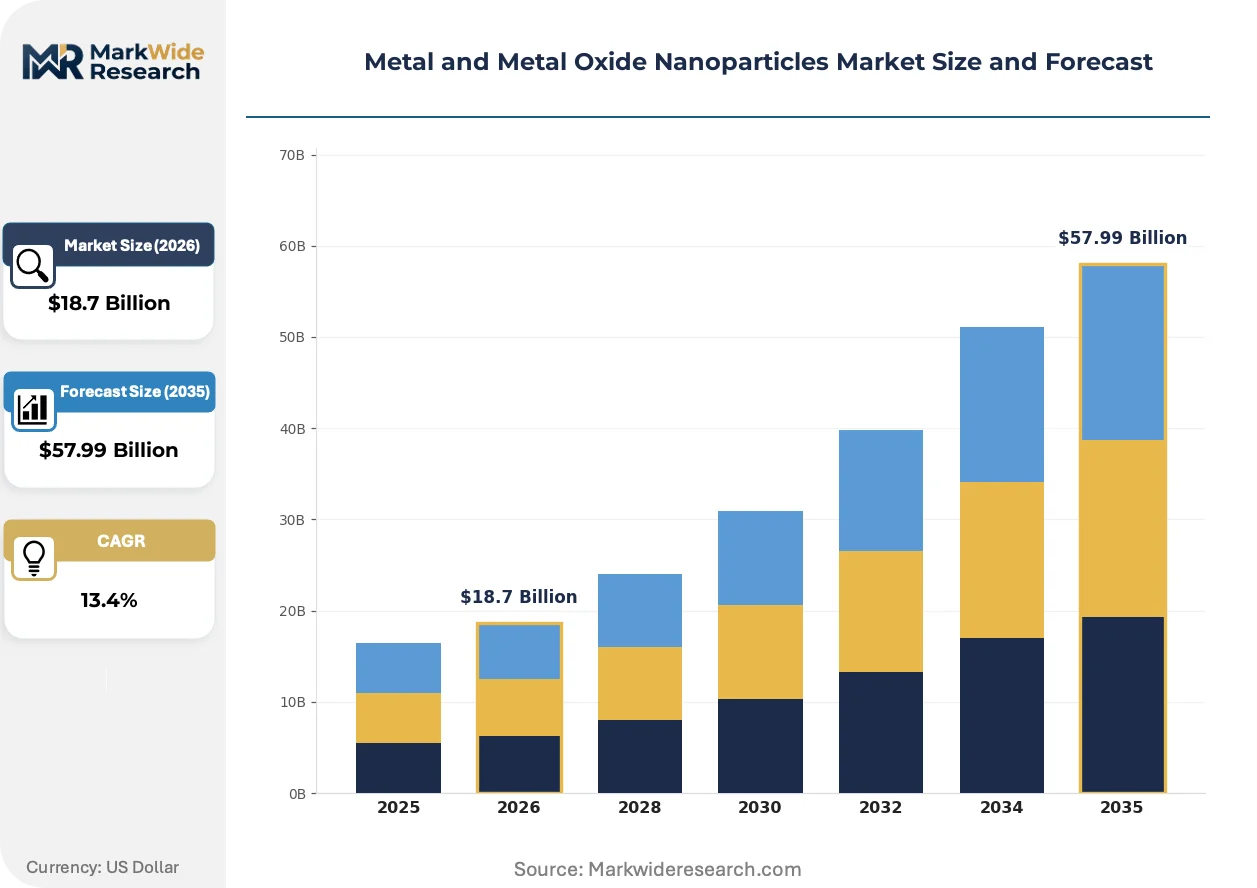
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $57.99 Billion |
| CAGR (2026 – 2036) | 13.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Silver Nanoparticles, Gold Nanoparticles, Iron Oxide Nanoparticles, Zinc Oxide Nanoparticles Application: Biomedical, Electronics, Catalysts, Cosmetics End User: Healthcare, Electronics Manufacturers, Coating Industry, Agriculture Form: Powder, Colloidal, Dispersion, Coated |
| Companies Covered | American Elements, Nanophase Technologies Corporation, Nanoshel LLC, Meliorum Technologies, U.S. Research & Nanomaterials Inc, NanoComposix Inc., Showa Denko K.K., Tekna Systèmes Plasma Inc., Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Metal and Metal Oxide Nanoparticles Market Strategic Shifts
Flame spray pyrolysis and sol-gel synthesis methods are converging with plasma arc platforms to reshape how metal oxide nanoparticles achieve surface-area-to-volume ratios for catalytic and optical functions.
Atomic layer deposition is miniaturizing metal oxide coatings onto complex three-dimensional substrates for semiconductor and energy storage applications. Battery manufacturers in South Korea and Japan adopt these conformal coatings at pilot scale. The technology is miniaturizing defect tolerance requirements, compressing acceptable particle size distributions from 50 nanometers to sub-10 nanometer control bands.
EU Green Deal lifecycle assessment obligations are tightening carbon footprint disclosure for engineered nanomaterial imports. Suppliers must now document cradle-to-gate emissions for zinc oxide and iron oxide grades entering European customs territories. Cosmetics and coating formulators in Germany and France accelerate supplier audits to preempt CSRD-aligned supply chain reporting requirements.
Certification-driven procurement now dominates pharmaceutical and medical device channels, displacing price-primary sourcing. Buyers prioritize suppliers with validated FDA Type II drug master files and EMA quality documentation over unqualified competitors. This preference shift concentrates contract awards among plasma-processed oxide specialists in North America and Western Europe.
Metal and Metal Oxide Nanoparticles Market Segmentation
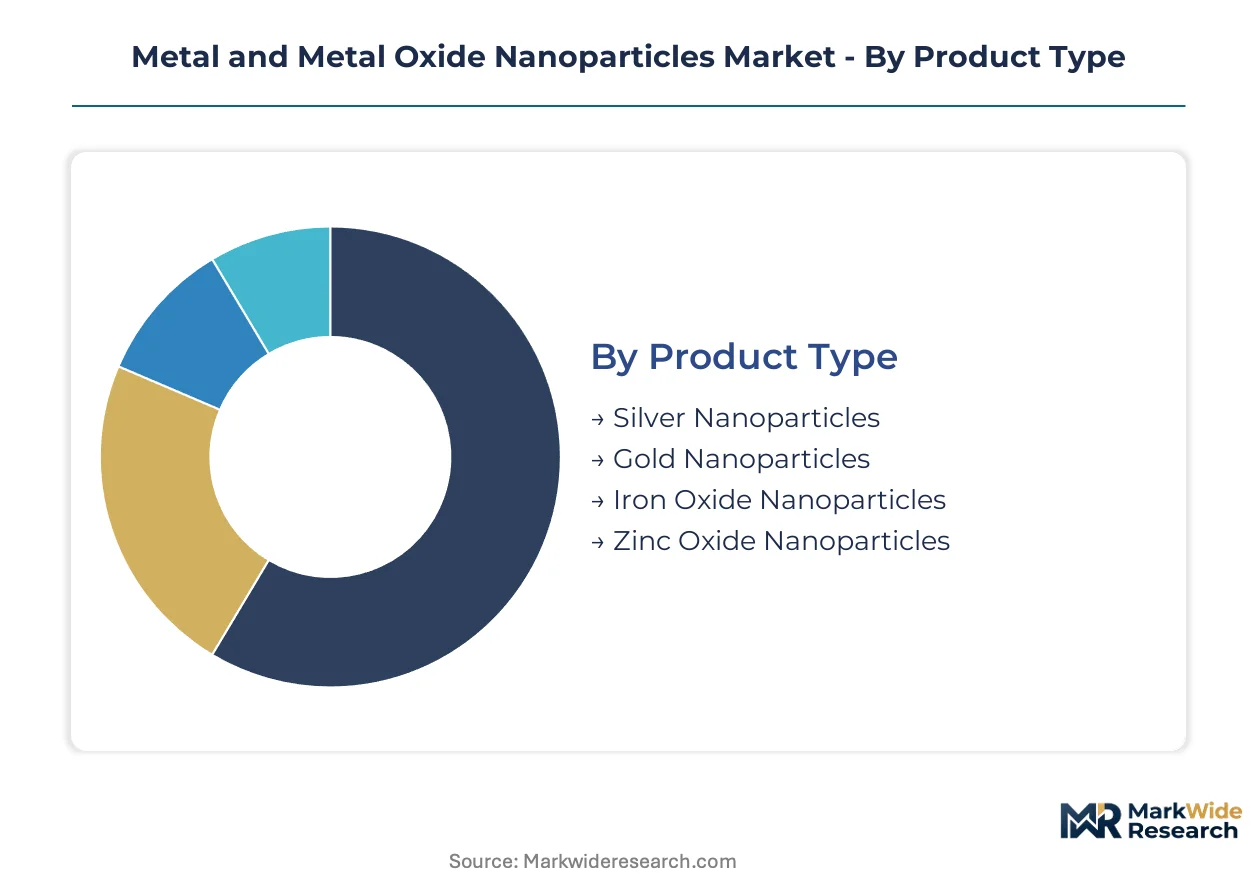
Segmentation in metal and metal oxide nanoparticles reveals distinct procurement patterns across product grades, with pharmaceutical and electronics channels demanding validated characterization while industrial buyers prioritize cost efficiency. Each dimension carries regulatory and technical implications that reshape supplier qualification requirements.
Product Type:
Domestic production dominates iron oxide and zinc oxide supply chains in China, while silver and gold nanoparticles flow through export-led specialists in North America and Western Europe with ISO/TS 19337:2015 validation.
- Silver Nanoparticles:Surface plasmon resonance properties enable conductive ink formulations and antimicrobial coatings. Electronics manufacturers in South Korea and Japan expand procurement for flexible circuit applications, though COMEX silver price volatility compresses margins.
- Zinc Oxide Nanoparticles:Broadband UV absorption and GRAS status position this grade in cosmetics and automotive clearcoats. German and French formulators accelerate supplier audits to meet EU Green Deal lifecycle disclosure obligations.
- Iron Oxide Nanoparticles:Superparamagnetic behavior below 20 nanometers drives healthcare demand in magnetic separation and drug delivery.
- Gold Nanoparticles:Biomedical imaging and diagnostic applications concentrate procurement among North American pharmaceutical specialists.
Silver nanoparticles hold the largest share; momentum sits with iron oxide for catalyst and healthcare applications.
Application:
Cost tier differentiation separates premium pharmaceutical-grade qualifications from commodity industrial catalyst procurement, with certification timelines driving 40-60% price spreads.
- Biomedical:Targeted drug delivery and diagnostic imaging demand sub-20 nanometer iron oxide with validated FDA Type II drug master files. Oncology applications in the United States concentrate margin pools among plasma-processed oxide specialists.
- Electronics:Conductive inks and printed circuit applications favor silver nanoparticles with narrow size distributions. South Korean battery manufacturers pilot atomic layer deposition for conformal oxide coatings at sub-10 nanometer tolerances.
- Catalysts:Petrochemical and environmental remediation applications scale rapidly in Chinese domestic production.
- Cosmetics:UV-shielding formulations in Germany and France prioritize zinc oxide with cradle-to-gate emissions documentation.
Biomedical commands premium pricing; electronics expands most quickly with flexible circuit adoption.
End User:
Customer type determines validation intensity, with healthcare and electronics manufacturers requiring electron microscopy protocols while agriculture and coating industries accept standard specifications.
- Healthcare:Pharmaceutical and medical device channels prioritize suppliers with FDA Type II drug master files and EMA quality documentation over unqualified competitors. Superparamagnetic iron oxide procurement concentrates in oncology and diagnostic imaging segments.
- Electronics Manufacturers:South Korean and Japanese battery producers drive demand for atomic layer deposition coatings with defect tolerance below 10 nanometers.
- Coating Industry:Automotive clearcoat formulators in Germany audit suppliers for CSRD-aligned supply chain reporting.
- Agriculture:Fertilizer and pesticide applications utilize zinc oxide and iron oxide at commodity price points with reduced characterization requirements.
Healthcare holds the largest share; coating industry gains share fastest with UV-shielding automotive demand.
Form:
Supply concentration favors powder and colloidal specialists with plasma arc capabilities, while dispersion and coated forms require downstream formulation partnerships.
- Powder:Dry nanoparticle grades serve catalyst and electronics applications requiring precise dosing. Chinese domestic producers scale iron oxide powder for petrochemical customers.
- Colloidal:Liquid suspensions enable biomedical and cosmetic formulations with controlled aggregation states. Silver colloids command premium positioning in antimicrobial coatings.
- Dispersion:Pre-stabilized nanoparticle systems reduce formulation complexity for coating industry customers.
- Coated:Surface-modified particles enhance compatibility in polymer matrices and biological media.
Powder holds the largest share; colloidal climbs the fastest with biomedical formulation demand.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Domestic manufacturing incentives and tightening environmental regulations are redrawing procurement maps across major nanoparticle-consuming economies. National industrial policies now determine supplier qualification timelines and market access conditions more decisively than raw material availability.
United States
Pharmaceutical-grade iron oxide procurement concentrates among plasma-processed oxide specialists serving oncology and diagnostic imaging segments. FDA Type II drug master file requirements drive 18-24 month qualification cycles that favor established domestic suppliers. Los Angeles-area manufacturing campuses anchor rare-earth and transition-metal nanoparticle production for electronics and biomedical channels.
China
Iron oxide nanoparticle production for petrochemical catalysts and environmental remediation applications scales rapidly under advancing MEE guidelines. Dual carbon goals force cradle-to-gate emissions documentation for zinc oxide grades entering industrial supply chains. Yangtze River Delta chemical clusters concentrate domestic manufacturing capacity for export-competitive oxide platforms.
Germany
Automotive clearcoat formulators accelerate supplier audits to preempt CSRD-aligned supply chain reporting requirements for UV-shielding zinc oxide nanoparticles. EU Green Deal lifecycle assessment obligations tighten carbon footprint disclosure for engineered nanomaterial imports. Frankfurt and Munich metropolitan areas concentrate cosmetics and coating R&D facilities demanding validated ISO/TS 19337:2015 characterization protocols.
South Korea
Battery manufacturers pilot atomic layer deposition for conformal oxide coatings at sub-10 nanometer defect tolerance thresholds. Electronics producers expand silver nanoparticle procurement for flexible circuit applications despite COMEX price volatility. Seoul Capital Area semiconductor clusters drive demand for precision-controlled metal oxide deposition systems.
India
Production-linked incentive schemes attract specialty nanoparticle manufacturing for electronics and pharmaceutical export markets. CDSCO pharmaceutical regulations align with international standards to accelerate domestic master file qualifications. Gujarat and Maharashtra industrial corridors concentrate emerging capacity for zinc oxide and iron oxide grades serving regional coating and catalyst demand.
Metal and Metal Oxide Nanoparticles Market Competitive Environment
Listed leaders compete with private specialists across plasma-processed oxide platforms and validated characterization capabilities. The qualified vendor base collapses toward laboratories with electron microscopy and dynamic light scattering protocols under REACH and OSHA compliance pressure. Three archetypes dominate: vertically integrated rare-earth processors, plasma-technology platform specialists, and ISO-validated analytical service providers. Competitive moves center on pharmaceutical master file accumulation and geographic expansion into PLI-subsidized manufacturing jurisdictions.
Among North American fabricators, American Elements and Nanophase Technologies Corporation exemplify the vertically integrated and plasma-technology archetypes respectively. Nanoshel LLC occupies a position within the specialty colloid and dispersion tier. These three anchors illustrate how supplier qualification requirements favor entities with validated electron microscopy capabilities and regulatory dossier depth over commodity producers.
| Leading Market Players |
|---|
| American Elements |
| Nanophase Technologies Corporation |
| Nanoshel LLC |
| Meliorum Technologies |
| U.S. Research & Nanomaterials Inc |
| NanoComposix Inc. |
| Showa Denko K.K. |
| Tekna Systèmes Plasma Inc. |
| Evonik Industries AG |
| Others |
Value Chain & Pricing Dynamics
Plasma-processed oxide capacity utilization above 80% in North American specialist facilities establishes price floors that commodity sol-gel producers cannot match, compressing the qualified supplier base while elevating certification-grade premiums across pharmaceutical and electronics procurement channels.
Pricing Analysis
Certification level (ISO/TS 19337:2015, FDA Type II drug master file, REACH dossier completeness) creates the primary spread between pharmaceutical-grade iron oxide at 40-60% premiums over industrial catalyst grades. Three-tier pricing structure across pharmaceutical-certified, electronics-validated, and commodity industrial grades reflects electron microscopy protocol investments and 18-24 month master file timelines. Cost compression in silver nanoparticle conductive inks intensifies because COMEX futures volatility transfers directly to formulated product margins. Agriculture and coating formulators exhibit highest price sensitivity, while oncology drug developers prioritize qualification depth over unit economics.
Supply Chain Analysis
Container availability constraints on Asia-Europe trade lanes elevate inbound logistics costs for zinc oxide and iron oxide grades entering German and French customs territories, forcing inventory pre-positioning strategies. Production gravity centers on China for iron oxide catalyst powders, the United States for plasma-processed pharmaceutical oxides, and South Korea for atomic layer deposition precursors. Raw material dependencies span silver bullion from COMEX-linked refiners, rare-earth feedstocks from Mountain Pass and Bayan Obo operations, and high-purity metal organics for ALD processes. Single-source vulnerability concentrates in plasma arc equipment manufacturers serving validated oxide specialists. Distribution runs through direct mill relationships for pharmaceutical tiers and chemical distributor networks for industrial grades.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Atomic layer deposition miniaturization below 10 nanometer tolerances and EU Green Deal lifecycle disclosure mandates constitute twin inflections reshaping competitive viability across the forecast horizon.
For Market Incumbents: Consolidate electron microscopy validation capabilities through captive laboratory investments or exclusive service partnerships to defend against ISO/TS 19337:2015 qualification collapses. Deepen backward integration into rare-earth and transition-metal feedstocks to buffer COMEX silver volatility and Chinese export policy shifts in oxide precursor markets. For New Entrants and Emerging Players: FDA Type II drug master file fast-track programs for sub-20 nanometer superparamagnetic iron oxide open concentrated margin pools in oncology applications underserved by plasma-processed incumbents. Target India's PLI-subsidized manufacturing corridors for zinc oxide export production serving European cosmetics formulators with CSRD-aligned emissions documentation. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among plasma-processed oxide specialists with pharmaceutical master file portfolios and long-term supply agreements with medical device OEMs. Five-to-ten year viability favors entities with validated ALD precursor capabilities and dual carbon compliance infrastructure. Watch South Korean battery manufacturer pilot-to-production conversion rates as the inflection signal for conformal coating demand scaling.| Strategic Initiative | Industry Significance |
|---|---|
| Pharmaceutical Master File Accumulation | FDA Type II dossiers lock in 18-24 month competitive moats against unqualified oxide suppliers. |
| Plasma Process Capacity Expansion | Los Angeles and Midwest manufacturing campuses anchor North American rare-earth nanoparticle supply security. |
| ISO/TS 19337:2015 Laboratory Validation | Electron microscopy protocols collapse supplier qualification to validated analytical service providers. |
| India PLI Manufacturing Entry | Domestic production incentives attract specialty nanoparticle capacity for electronics and pharmaceutical exports. |
| EU Green Deal Compliance Infrastructure | Cradle-to-gate emissions documentation becomes mandatory for zinc oxide entering German automotive clearcoat supply chains. |
Study Parameters
Two parallel data streams informed the analysis: structured primary interviews with plasma process engineers, pharmaceutical procurement managers, cosmetics formulators, and regulatory affairs specialists; and secondary validation against SEC 10-K filings, ECHA REACH registration databases, FDA drug master file repositories, and customs trade records. Bottom-up triangulation across nanoparticle grade volumes and top-down cross-checks against end-use industry consumption patterns ensured convergence.
Across the projection horizon, the analytical framework modeled product type, application channel, end-user validation intensity, and regional regulatory cluster segmentation. CAGRs derived from historical capacity expansion rates, master file approval velocity, and substitution elasticity estimates for carbon nanotube and graphene alternatives. Forecast inputs incorporated MEE guideline enforcement timelines in China and CSRD phased implementation across EU member states.
Underlying assumptions cover sustained REACH dossier completeness requirements and stable silver futures volatility regimes, with deviation risk concentrated in OSHA permissible exposure limit revisions and OECD nano-specific hazard classification advances. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
United States Gold Nanoparticles Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Magnesium Oxide Nanoparticle Market
Nanomaterials
Nanotools Market