
 Mesoporous Carbons Market | 2026-2036
Mesoporous Carbons Market Size, Share, and Industry Trends Forecast 2026-2036
Mesoporous Carbons Market Foresight
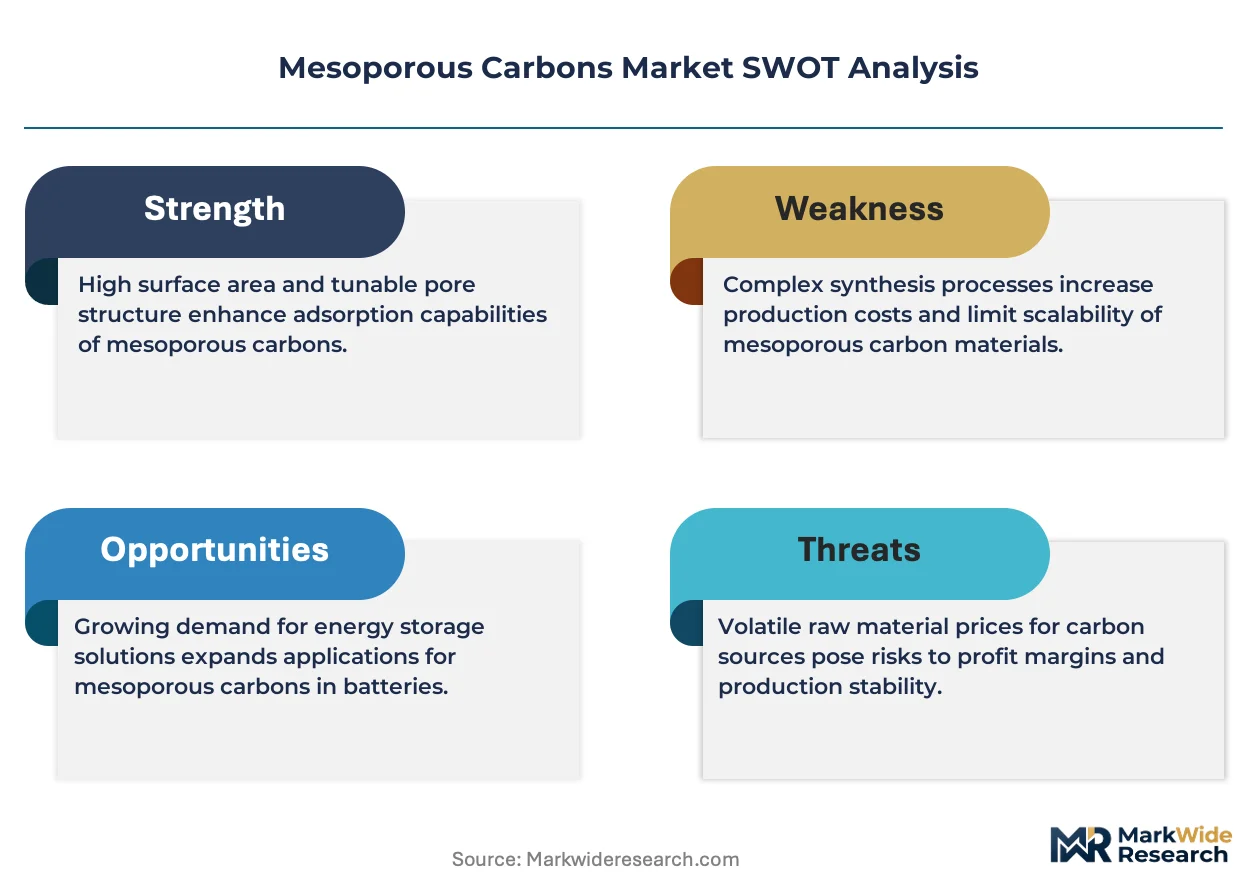
Buyer concentration in the pharmaceutical and electronics sectors is expanding as large-scale drug manufacturers and battery producers internalize mesoporous carbon procurement to secure supply chain stability. BASF SE leverages its integrated chemical platform to control precursor sourcing for specialized carbon structures. Kuraray Co. Ltd. dominates Asian supply channels through its synthetic polymer-derived carbon technologies. Calgon Carbon Corporation anchors North American demand with its activated carbon expertise extending into mesoporous grades for environmental applications.
Mesoporous carbons are porous carbon materials with ordered pore structures typically ranging from 2 to 50 nanometers, synthesized through template-assisted methods or hydrothermal carbonization to achieve high surface areas exceeding 500 square meters per gram for catalysis, adsorption, and controlled release applications. The template method produces the most precisely structured pores for drug delivery systems where uniform cavity dimensions govern active pharmaceutical ingredient loading efficiency. Energy storage applications favor carbon nanotubes and graphene variants where electrical conductivity and ion transport pathways determine electrode performance. Activated carbon retains the largest volume position in catalysis and adsorption due to mature manufacturing economics and established regeneration protocols.
EPA guidelines in the United States and REACH requirements in Europe enforce purity thresholds and environmental release controls that elevate compliance costs for producers serving pharmaceutical and chemical end users. Japan's METI promotes advanced carbon material development through national technology roadmaps that subsidize domestic manufacturers competing in energy storage supply chains. Stakeholders must monitor evolving regulatory divergence between jurisdictions to anticipate certification burdens that will reshape competitive access across major demand centers.
Market Dynamics
Template-assisted synthesis methods are compressing production timelines for pharmaceutical-grade mesoporous carbons while REACH compliance costs in Europe and EPA purity mandates in the United States simultaneously elevate qualification barriers for new entrants.
Growth Catalysts
- Controlled drug release systems:Pharmaceutical manufacturers are expanding procurement of ordered mesoporous structures for active pharmaceutical ingredient encapsulation, with cavity dimensions governing loading efficiency for oncology and cardiovascular therapeutics.
- EU Green Deal frameworks:Carbon neutrality mandates are accelerating demand for mesoporous carbons in catalytic carbon capture and hydrogen storage applications, tightening purity specifications for materials used in emission reduction systems.
- Energy storage procurement:Battery producers in China, Japan, and Germany are concentrating long-term supply agreements for high-grade mesoporous carbons serving supercapacitor electrodes and lithium-sulfur battery cathodes.
Market Restraints
- Precursor cost volatility:Synthetic polymer feedstock prices fluctuate with petrochemical markets, compressing margins for template-derived carbon producers serving price-sensitive environmental remediation segments.
- Supply concentration risk:Asian manufacturers dominate precursor chemical supply for hard-template methods, exposing European and North American carbon producers to shipping disruptions and tariff exposure.
- Technical limitation in scale-up:Batch-to-batch pore uniformity degrades beyond laboratory-scale reactors, constraining pharmaceutical customers seeking consistent cavity dimensions for regulatory filings.
Strategic Opportunities
- Underpenetrated environmental remediation:Industrial wastewater treatment facilities in India are adopting mesoporous carbon adsorbents for heavy metal removal, supported by national pollution control mandates and subsidy programs.
- Technology convergence:Hybrid graphene-mesoporous carbon composites are emerging for next-generation supercapacitors, combining electrical conductivity with ordered ion transport pathways.
- Regulatory tailwind:Japan's METI national technology roadmaps subsidize domestic advanced carbon material development, creating procurement preference for local manufacturers in energy storage supply chains.
Industry Challenges
- Specialized synthesis expertise gap:Template-assisted methods require PhD-level materials chemists for process optimization, with talent scarcity concentrated in Germany, Japan, and select US research clusters.
- Extended certification timelines:FDA and EMA qualification protocols for pharmaceutical-grade carbons demand 18-36 month stability studies, delaying revenue recognition for new production facilities.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Mesoporous Carbons Market |
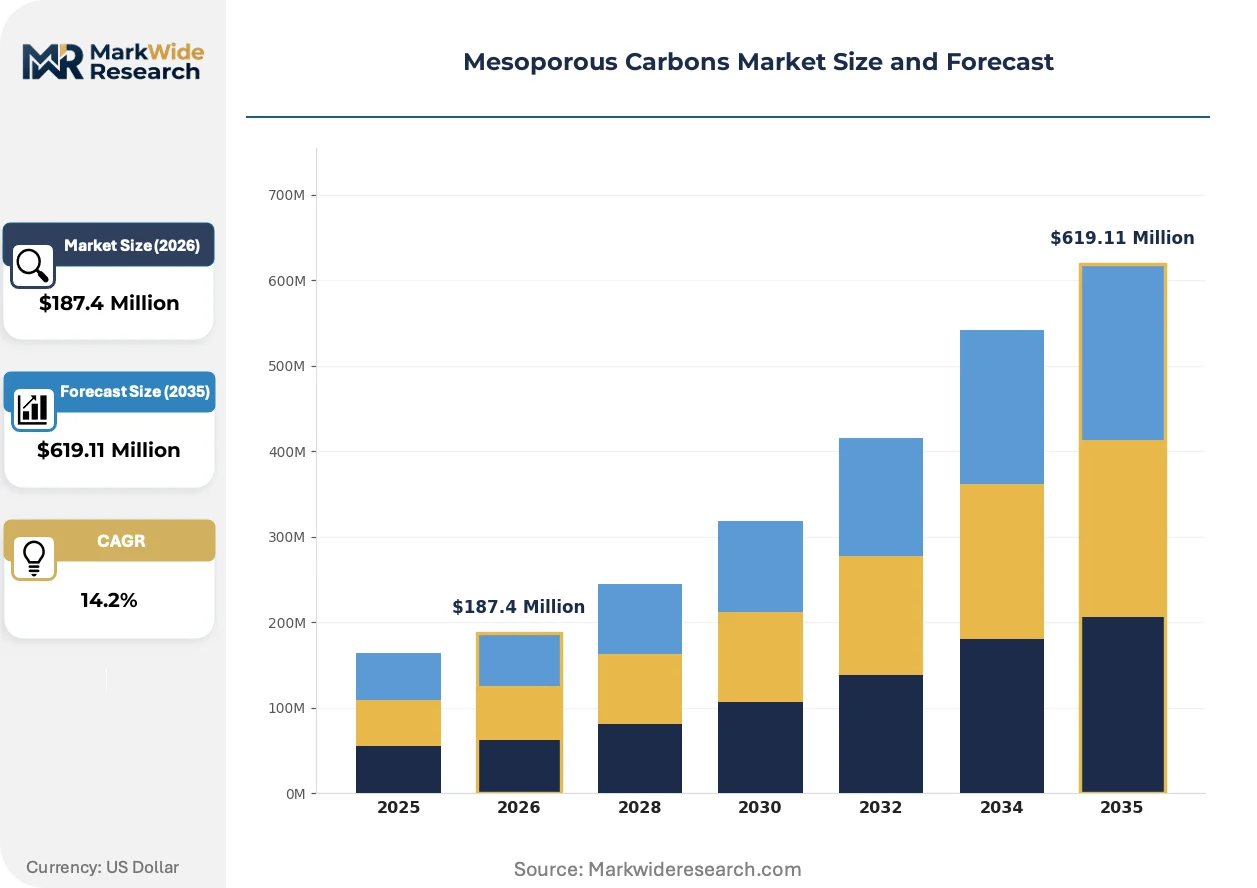
| Market Size in 2026 | $187.4 Million |
| Market Size in 2035 | $619.11 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Activated Carbon, Graphene, Carbon Nanotubes, Carbon Aerogels Application: Catalysis, Adsorption, Drug Delivery, Energy Storage End User: Chemical Industry, Pharmaceutical Companies, Research Laboratories, Electronics Technology: Sol-Gel Process, Chemical Vapor Deposition, Hydrothermal Carbonization, Template Method |
| Companies Covered | Calgon Carbon Corporation, Ingevity Corporation, BASF SE, Haycarb Plc, W.R. Grace & Co., Kuraray Co. Ltd., Jacobi Carbons AB, ACS Material, LLC, Cabot Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Mesoporous Carbons Market Shifts & Advancements
Continuous flow synthesis reactors are displacing batch methods in mesoporous carbon manufacturing, compressing production cycles while regulatory divergence between jurisdictions forces producers to maintain parallel qualification tracks for pharmaceutical and energy storage segments.
Hard-templating using ordered mesoporous silica is integrating into commercial-scale drug delivery manufacturing, enabling pharmaceutical companies to achieve sub-5% batch-to-batch variability in pore dimensions. Large-scale generic drug manufacturers in Germany and India are adopting this approach for controlled-release formulations. The technology is integrating quality-by-design principles into carbon procurement specifications, compressing supplier qualification timelines from 24 months to 14 months for qualified template-method producers.
REACH substance registration requirements are expanding purity disclosure obligations for carbon materials used in medical devices and catalytic applications, forcing producers to document heavy metal content below 10 parts per million. European chemical distributors are consolidating supplier bases to reduce compliance administration burdens. Battery-grade mesoporous carbon importers are responding by establishing EU-based toll manufacturing partnerships to avoid direct registration costs.
Direct contracting between pharmaceutical manufacturers and specialized carbon producers is displacing traditional chemical distributor channels for high-purity grades, with buyers seeking supply chain transparency for regulatory audit trails. This pattern concentrates procurement among five to seven qualified producers globally. The shift is most visible in Germany and Switzerland, where medical device manufacturers now require carbon suppliers to maintain ISO 13485 quality management certifications.
Mesoporous Carbons Market Segmentation
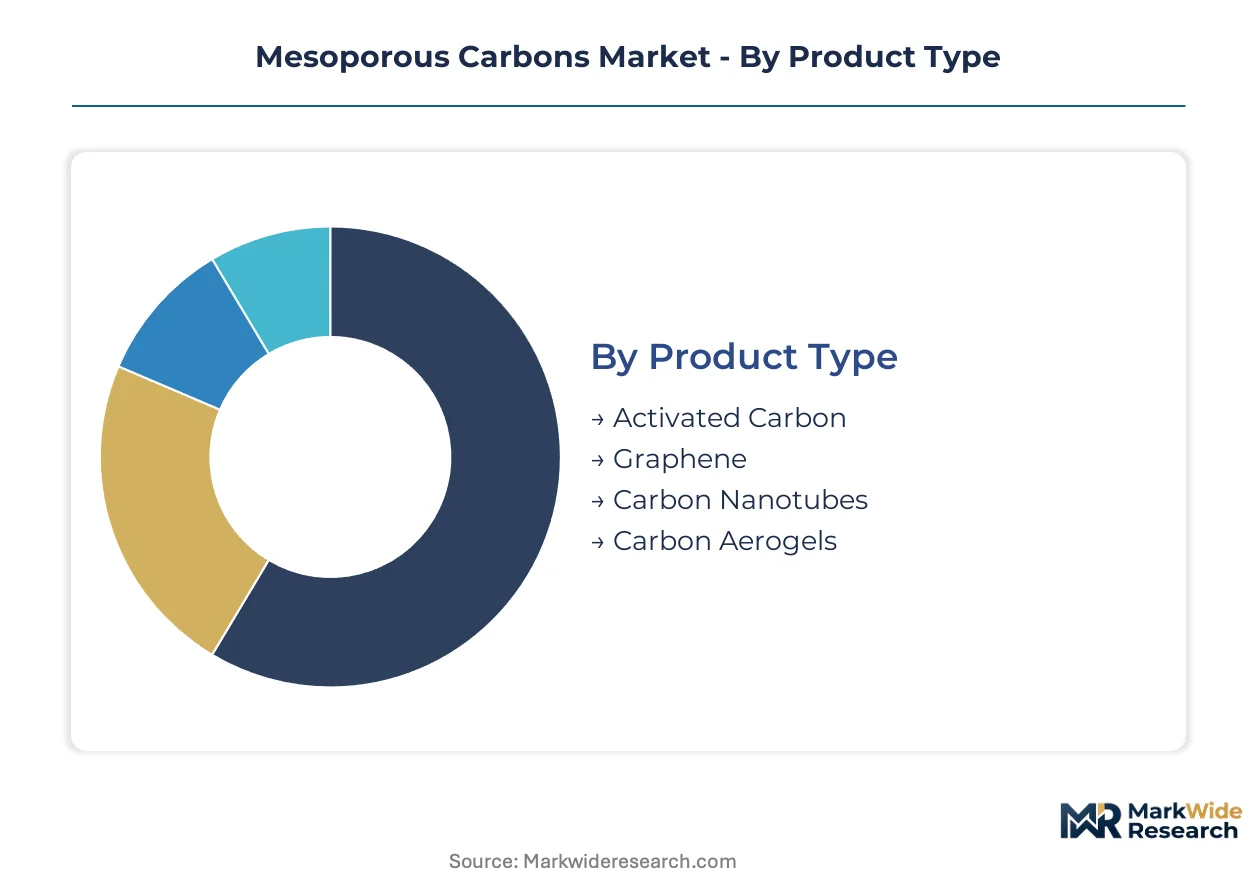
Mesoporous carbon producers face divergent capital requirements across synthesis routes and purity grades. Pharmaceutical and electronics end users demand tailored pore architectures that fragment manufacturing footprints into specialized production clusters.
Product Type:
Capital intensity peaks with graphene and carbon nanotube production, where chemical vapor deposition reactors and plasma synthesis equipment demand seven-figure facility investments.
- Activated Carbon:Mature thermal activation processes using steam or chemical agents yield surface areas exceeding 500 square meters per gram. Chemical industry procurement in Germany and India concentrates demand for catalytic supports and wastewater treatment media, though margin compression from commoditized supply limits expansion capital deployment.
- Graphene:Single-atom-thick carbon sheets produced via chemical exfoliation or CVD deliver exceptional electrical conductivity for supercapacitor electrodes. Battery manufacturers in Japan and China are consolidating long-term offtake agreements, driving capacity expansion despite high front-end equipment costs.
- Carbon Nanotubes:Cylindrical nanostructures with tunable diameters serve conductive additives and structural composites. Electronics sector demand concentrates in South Korea and Taiwan for EMI shielding applications.
- Carbon Aerogels:Ultra-low-density mesoporous networks synthesized through sol-gel polymerization and supercritical drying. Research laboratories in Switzerland and the United States represent primary procurement channels for thermal insulation prototypes.
Most installed capacity flows through Activated Carbon. Expansion is steepest in Graphene.
Application:
Application selection determines regulatory pathway complexity and customer concentration risk for carbon producers.
- Catalysis:Ordered pore structures host metal nanoparticles for selective chemical transformations. Petrochemical refineries in China and Germany deploy mesoporous carbon supports for hydrogenation reactions, with REACH and GB standards enforcing heavy metal leaching thresholds below 10 parts per million.
- Adsorption:High surface area enables contaminant capture from gas and liquid streams. Environmental remediation contracts in India are accelerating under national pollution control mandates targeting heavy metal removal from industrial effluent.
- Drug Delivery:Template-synthesized cavity dimensions govern active pharmaceutical ingredient loading kinetics. Oncology and cardiovascular therapeutic developers in Switzerland and the United States require sub-5% batch-to-batch pore variability for FDA and Swissmedic filings.
- Energy Storage:Ion transport optimization in ordered mesopores enhances supercapacitor and lithium-sulfur battery performance. German and Japanese battery producers are securing dedicated supply lines for high-purity grades.
Revenue concentration currently favors Catalysis. Regulatory tailwinds are accelerating most quickly in Drug Delivery.
End User:
End user selection dictates certification burden and contract structure, with pharmaceutical and electronics segments demanding supply chain transparency.
- Chemical Industry:Bulk procurement of activated and mesoporous carbons for process catalysis and solvent recovery. German chemical conglomerates are backward-integrating into specialized carbon production to secure precursor supply stability.
- Pharmaceutical Companies:Controlled-release formulation developers require ISO 13485-certified suppliers with documented heavy metal content below regulatory thresholds. Direct contracting is displacing distributor channels for high-purity grades.
- Research Laboratories:Small-volume procurement of experimental carbon morphologies for materials science investigation. Academic and government labs in Japan and the United States drive early-stage technology validation.
- Electronics:Supercapacitor and battery manufacturers demand electrical conductivity specifications above 1000 siemens per meter. Asian electronics supply chains concentrate procurement for consumer device applications.
Contract values are largest with Pharmaceutical Companies. Procurement velocity is climbing fastest in Electronics.
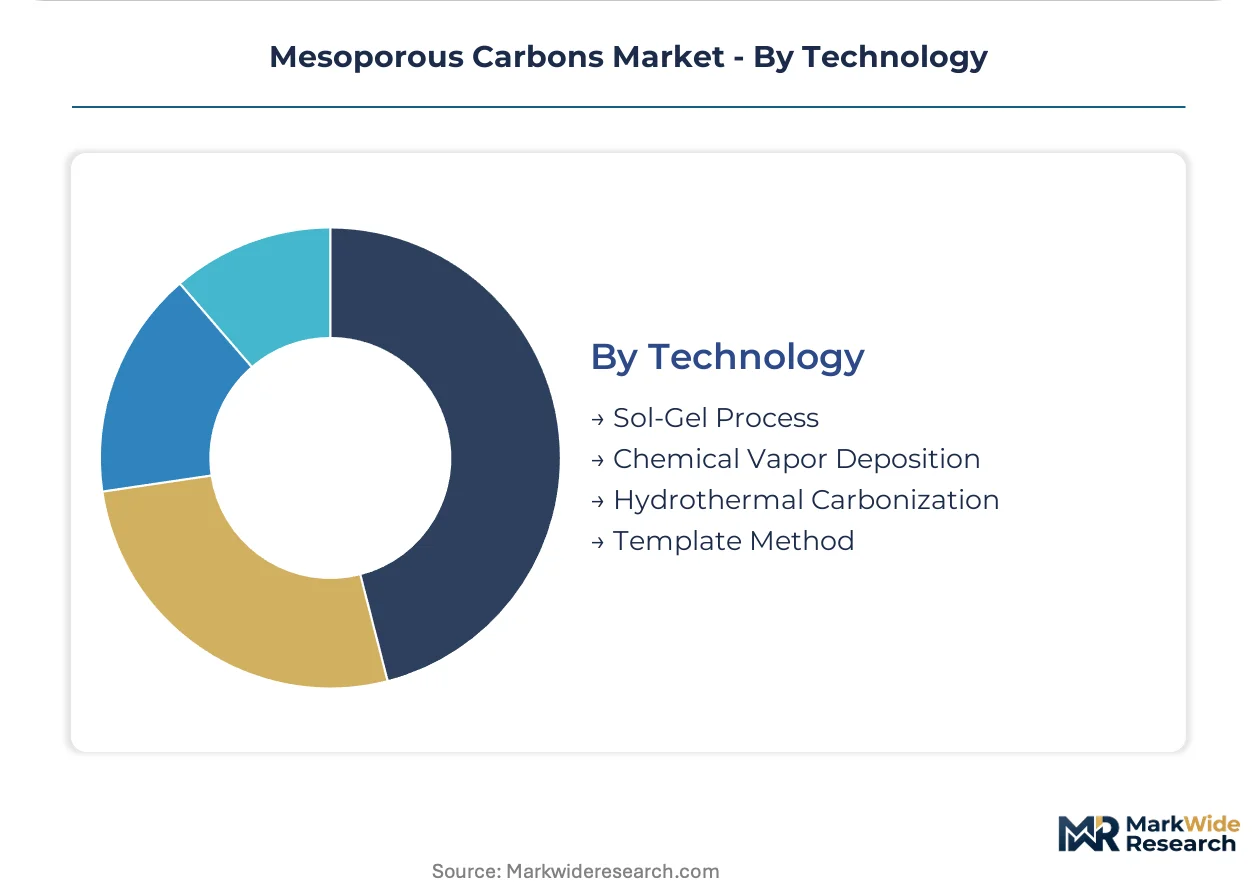
Technology:
Technology choice determines pore uniformity, scalability ceiling, and intellectual property position for carbon producers.
- Sol-Gel Process:Polymer gel formation and controlled pyrolysis yield interconnected mesoporous networks. Carbon aerogel producers in the United States leverage this route for thermal insulation applications requiring ultra-low density.
- Chemical Vapor Deposition:Gas-phase precursor decomposition deposits carbon onto catalytic substrates with precise thickness control. Graphene and nanotube manufacturers in South Korea and Japan deploy CVD for electronics-grade material output.
- Hydrothermal Carbonization:Biomass conversion in aqueous media at moderate temperatures produces functionalized carbon spheres. Environmental remediation suppliers favor this lower-capital route for cost-sensitive adsorbent production.
- Template Method:Hard-templating using ordered mesoporous silica or soft-templating with block copolymers achieves sub-5-nanometer pore uniformity. Pharmaceutical-grade producers in Germany and Switzerland dominate this high-precision segment despite batch-scale limitations.
Production volume concentrates in Hydrothermal Carbonization. Capability premiums accrue most steeply to Template Method specialists.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Germany concentrates pharmaceutical-grade production while Japan dominates energy storage supply chains, creating divergent regional specialization patterns across the mesoporous carbons market.
United States
EPA purity mandates and FDA qualification protocols drive demand from oncology drug developers in Greater Boston and the Research Triangle. The Environmental Protection Agency enforces heavy metal thresholds below 10 parts per million for catalytic applications. Houston petrochemical clusters deploy mesoporous carbon supports for hydrogenation reactions under tightened emissions controls.
Germany
Chemical conglomerates in North Rhine-Westphalia backward-integrate into specialized carbon production to secure precursor stability. REACH substance registration expands purity disclosure obligations for medical device applications. Basel-Land transects the Swiss-German border where ISO 13485-certified suppliers serve cardiovascular therapeutic developers requiring sub-5% pore variability.
Japan
METI national technology roadmaps subsidize domestic advanced carbon material development for supercapacitor electrodes. The Ministry of Economy, Trade and Industry channels funding toward lithium-sulfur battery cathode suppliers. Osaka-Kobe industrial corridors concentrate long-term offtake agreements between battery producers and high-grade carbon manufacturers.
China
GB standards and dual carbon goals accelerate mesoporous carbon procurement for catalytic carbon capture systems. The Ministry of Ecology and Environment tightens industrial effluent mandates supporting environmental remediation demand. Yangtze River Delta battery producers secure dedicated supply lines for graphene-mesoporous carbon composites.
India
National pollution control mandates and PLI scheme subsidies drive adoption of mesoporous carbon adsorbents for heavy metal removal. The Central Pollution Control Board enforces stricter industrial wastewater standards. Gujarat chemical clusters expand procurement for cost-sensitive environmental remediation segments under compressed margin conditions.
Mesoporous Carbons Market Competitive Landscape
German and Swiss producers anchor the pharmaceutical-grade tier; Japanese and South Korean specialists hold the energy storage vector. The vendor base splits between integrated chemical conglomerates with captive carbon capabilities and focused carbon material houses serving narrow specification bands. Three archetypes dominate: template-method precision specialists, activated carbon scale operators, and graphene-nanotube technology licensors. Competitive moves concentrate on backward integration into precursor supply and geographic toll manufacturing partnerships to circumvent REACH registration costs.
Within the precision-tier, BASF SE and Kuraray Co. Ltd. exemplify divergent strategic positions. BASF SE leverages its Ludwigshafen integrated chemical platform to control precursor sourcing for specialized carbon structures. Kuraray Co. Ltd. occupies a position as a synthetic polymer-derived carbon technology anchor across Asian supply channels. Calgon Carbon Corporation represents the activated carbon scale archetype, extending established environmental application expertise into mesoporous grades for North American remediation markets.
| Leading Market Players |
|---|
| Calgon Carbon Corporation |
| Ingevity Corporation |
| BASF SE |
| Haycarb Plc |
| W.R. Grace & Co. |
| Kuraray Co. Ltd. |
| Jacobi Carbons AB |
| ACS Material, LLC |
| Cabot Corporation |
| Others |
Supply & Pricing Matrix
Family-owned mid-cap specialists in Germany and Switzerland anchor pharmaceutical-grade supply, translating ISO 13485 certification premiums into pricing discipline that commodity activated carbon producers cannot match. Their captive precursor relationships insulate margins from petrochemical volatility while forcing Asian hydrothermal operators into cost-competitive environmental remediation tiers.
Pricing Analysis
Capacity additions in China are reshaping price floors for battery-grade graphene-mesoporous carbon composites, compressing margins for Japanese and South Korean CVD specialists. Three-tier pricing structure across pharmaceutical-certified, industrial-grade, and environmental-economy levels segments buyers by regulatory burden. Cost compression in the environmental tier intensifies because Indian wastewater treatment facilities prioritize heavy metal removal efficiency over pore uniformity. Pharmaceutical companies exhibit least price sensitivity due to FDA filing requirements, while municipal remediation contractors in India face acute budget constraints.
Supply Chain Analysis
REACH substance registration and FDA qualification protocols gate supply chain participation, elevating working capital requirements for new entrants. Production concentrates in China, Japan, and Germany, with Chinese manufacturers dominating hydrothermal carbonization feedstock supply. Hard-template silica precursors and synthetic polymer resins constitute critical input dependencies. Single-source vulnerability runs through ordered mesoporous silica suppliers serving German pharmaceutical template-method producers. Distribution runs through direct contracting for pharmaceutical grades and chemical distributors for industrial volumes.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a geographic-arbitrage play: REACH compliance costs in Europe exceed EPA registration burdens in the United States by a factor that justifies toll manufacturing partnerships for battery-grade importers seeking EU market access without direct substance registration.
For Market Incumbents: Lock in long-term offtake agreements with Yangtze River Delta battery producers before Chinese graphene-mesoporous carbon composite capacity saturates Asian pricing. Deepen upstream control over synthetic polymer precursor supply to offset petrochemical cost volatility threatening environmental remediation margins. Prioritize ISO 13485 certification maintenance for Swiss and German pharmaceutical customers facing shortened supplier qualification timelines. For New Entrants and Emerging Players: India's PLI scheme subsidies for pollution control equipment open a window for cost-optimized hydrothermal carbon producers to capture heavy metal remediation contracts in Gujarat chemical clusters. Environmental adsorption applications offer the most penetrable entry point given lower regulatory barriers and compressed incumbent margins. Pursue toll manufacturing partnerships with established REACH-registered distributors to circumvent direct European substance registration costs. For Investors and Strategic Acquirers: Valuations sit cheapest among hydrothermal carbonization operators serving price-sensitive environmental segments, while template-method precision specialists command scarcity premiums in pharmaceutical-grade supply. Five-to-ten-year viability favors producers with demonstrated batch-to-batch pore uniformity below five percent and established FDA master files. Watch for METI subsidy expansion announcements as inflection indicators for Japanese energy storage supply chain consolidation.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | BASF's Ludwigshafen platform demonstrates margin protection against synthetic polymer price volatility. |
| REACH Toll Manufacturing Partnership | Battery-grade importers avoid direct registration costs while maintaining EU market access. |
| ISO 13485 Quality Certification | Swiss cardiovascular therapeutic developers now mandate this for carbon supplier qualification. |
| Continuous Flow Synthesis Scale-Up | Hard-template producers compress batch-to-batch variability below five percent for FDA filings. |
| Hybrid Graphene-Mesoporous Composite Development | Osaka-Kobe battery producers secure dedicated supply lines for next-generation supercapacitor electrodes. |
Research Methodology
Bottom-up pharmaceutical and electronics demand modeling reconciled against top-down synthesis capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German chemical conglomerates, procurement leads at Japanese battery manufacturers, regulatory affairs directors at Swiss pharmaceutical developers, and technical R&D directors at carbon material specialists informed demand assumptions. Secondary validation drew from ECHA REACH registration databases, FDA drug master file submissions, METI technology roadmap disclosures, and customs trade data for activated and mesoporous carbon imports. Triangulation across these sources resolved discrepancies between disclosed capacity expansion plans and verified equipment procurement.
Input-output matrices mapped precursor chemical flows through hard-template, soft-template, hydrothermal, and CVD synthesis routes to end-use applications across catalysis, adsorption, drug delivery, and energy storage. Segmentation dimensions modeled include product type hierarchy, application-specific purity requirements, end-user certification tiers, and regional regulatory clusters. CAGRs were derived from elasticity-adjusted demand projections against supply-side capacity constraints. Forecast inputs incorporated METI subsidy allocation trajectories and EU Green Deal carbon neutrality mandate implementation timelines.
Forecast precision tightens around the base case; tail outcomes carry wider variance under sustained petrochemical feedstock price volatility or abrupt REACH substance registration requirement expansion. Projections reflect assumptions regarding template-method scale-up technical limitations and pharmaceutical customer qualification timeline compression. A model refresh is warranted upon material change in FDA or EMA carbon material qualification protocols.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Global Nano Calcium Carbonate Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Boron Nitride Nanotubes Market
Nanomaterials
Nanoceramic Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Polymer Nanocomposites Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Colloidal Selenium Nanoparticles Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Metal Nanoparticles Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Nanoscale Chemicals and Materials Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Platinum Nanoparticles Market