
 Nanocatalysts Market | 2026-2036
Nanocatalysts Market Size, Share, and Industry Trends Forecast 2026-2036
Nanocatalysts Market Analysis
Refinery end-user demand is restructuring as hydrogen economy investments displace conventional hydrocracking catalyst volumes. BASF SE leverages its Ludwigshafen integrated site to sustain captive production of metal oxide nanocatalysts for ammonia and methanol loops. Johnson Matthey Plc anchors its position through technology leadership in fuel cell membrane electrode assemblies. Umicore N.V. competes via closed-loop recycling of platinum-group metals for automotive catalytic converters.
Nanocatalysts are engineered materials with at least one dimension below 100 nanometers, typically comprising transition metals or metal oxides on porous supports such as alumina, silica, or carbon black, designed to maximize surface-area-to-volume ratios for enhanced reaction kinetics and selectivity in heterogeneous catalysis. Metal-based nanocatalysts dominate current volume owing to established petrochemical demand, while bimetallic variants represent the fastest-growing product class as alloy compositions enable superior oxygen reduction kinetics in fuel cells. Chemical manufacturing applications retain the largest installed base, though environmental remediation is emerging as a high-margin segment where supported nanocatalysts command premium pricing for groundwater and air purification contracts.
The U.S. EPA enforces emissions thresholds that mandate nanocatalyst integration in refinery flue-gas treatment, while the EU REACH framework governs nanomaterial registration and safe-use obligations for imported catalyst precursors. Japan's METI promotes hydrogen supply chain buildouts that directly subsidize nanocatalyst procurement for domestic electrolyzer OEMs. Stakeholders must monitor evolving carbon-border adjustment mechanisms that will reshape cost competitiveness between regional nanocatalyst suppliers and their downstream customers.
Market Dynamics
Platinum-group-metal supply concentration is forcing fuel cell manufacturers to accelerate bimetallic nanocatalyst development, restructuring procurement priorities away from single-metal dependency toward engineered alloy compositions that reduce raw material exposure.
Growth Catalysts
- U.S. Inflation Reduction Act:Clean hydrogen production tax credits are accelerating capital deployment into nanocatalyst R&D for electrolyzer and fuel cell applications.
- Automotive exhaust treatment:Germany's automotive conglomerates are integrating nanocatalysts into next-generation catalytic converter platforms to meet tightening emission thresholds.
- Metal oxide platforms:Captive production of alumina-supported metal oxide nanocatalysts for ammonia synthesis loops is expanding at integrated chemical sites.
Market Restraints
- Platinum price volatility:South African and Russian supply concentration exposes membrane electrode assembly manufacturers to input cost swings that compress margin structures.
- EU REACH registration:Nanomaterial safe-use obligations for imported catalyst precursors create compliance friction and extend qualification timelines.
- Carbon-based substitute threat:Nitrogen-doped carbon catalysts are advancing in low-temperature fuel cell testing, threatening PGM demand in select power ranges.
Strategic Opportunities
- Japan METI subsidies:Hydrogen supply chain buildouts directly fund nanocatalyst procurement for domestic electrolyzer OEMs, creating a protected demand pool.
- Environmental remediation contracts:Groundwater and air purification applications command premium pricing for supported nanocatalysts in high-margin service models.
- Closed-loop recycling convergence:Pyrometallurgical recovery of platinum-group metals from spent automotive catalysts is expanding into fuel cell electrode recycling streams.
Industry Challenges
- Membrane electrode assembly integration:Fuel cell stack manufacturers face technical complexity marrying nanocatalyst layer uniformity with proton-exchange membrane durability requirements.
- Scale-up talent scarcity:Industrial chemists with heterogeneous catalysis expertise and nanomaterial synthesis experience command premium compensation, constraining production expansion.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanocatalysts Market |
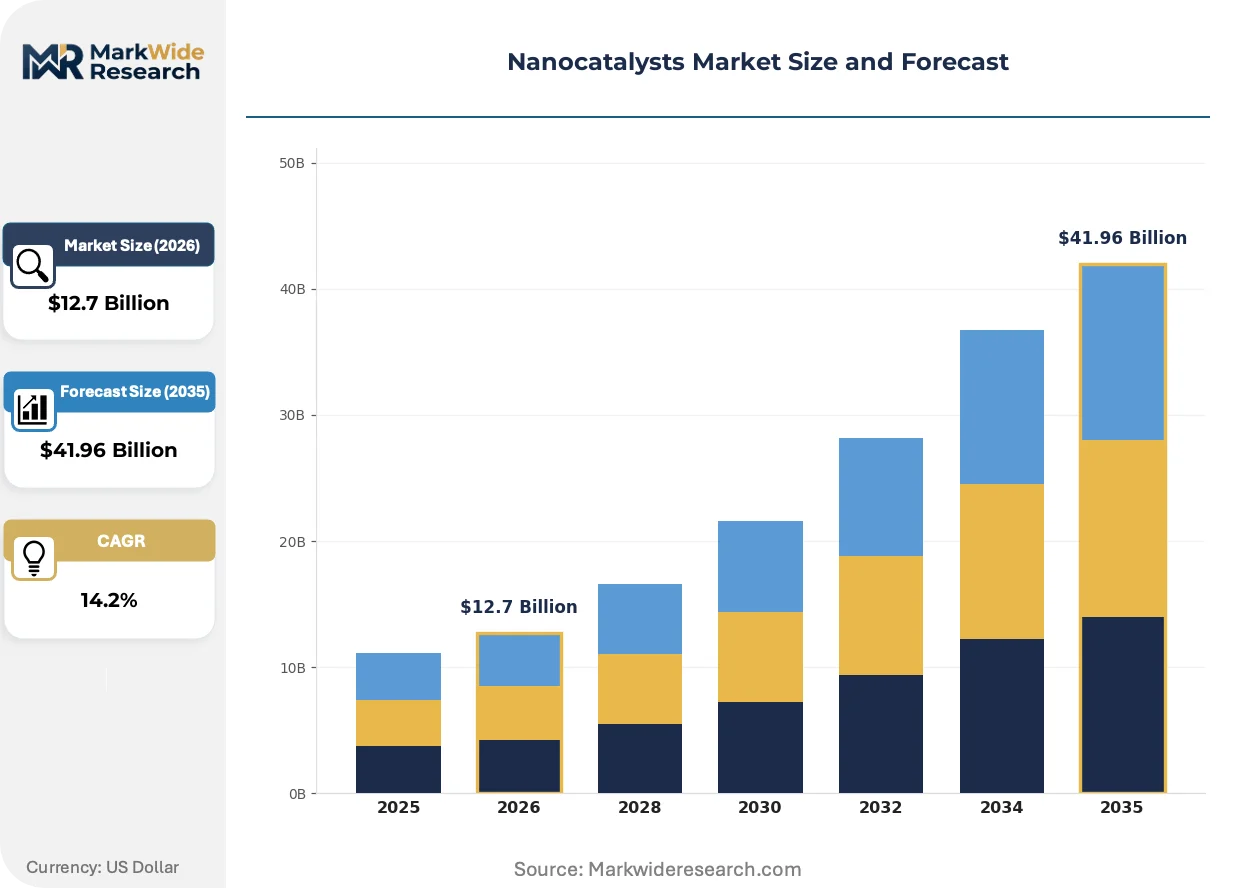
| Market Size in 2026 | $12.7 Billion |
| Market Size in 2035 | $41.96 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Metal-Based, Metal Oxides, Supported Nanocatalysts, Bimetallic Nanocatalysts Application: Petrochemical Synthesis, Environmental Remediation, Fuel Cells, Chemical Manufacturing End User: Refineries, Chemical Plants, Research Institutions, Wastewater Treatment Facilities Technology: Chemical Vapor Deposition, Sol-Gel Method, Co-precipitation, Hydrothermal Synthesis |
| Companies Covered | BASF SE, Dow, Inc., Evonik Industries AG, Johnson Matthey Plc, NanoScale Corporation, Nanophase Technologies Corporation, Umicore N.V., Clariant AG, QuantumSphere, Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanocatalysts Market Emerging Trajectories
Engineered nanocatalyst architectures are advancing beyond simple particle-size reduction toward surface-structure control and support-interaction optimization, enabling step-change performance in electrochemical and thermochemical applications.
Bimetallic alloy nanocatalysts are expanding into fuel cell cathode applications through precise control of platinum-nickel and platinum-cobalt core-shell structures. Automotive and stationary power OEMs are qualifying these materials for 2025-2027 platform launches. The technology is expanding into markets previously reserved for pure platinum catalysts by delivering superior oxygen reduction kinetics at lower metal loadings.
EU REACH nanomaterial registration requirements are tightening documentation burdens for catalyst precursors crossing into European customs territory. Importers must now submit full safety dossiers for nanoscale metal oxides and carbon-supported metals before commercial distribution. Fuel cell membrane suppliers with German manufacturing footprints are responding by regionalizing precursor synthesis to avoid cross-border compliance exposure.
Long-term offtake agreements are displacing spot-market catalyst procurement among electrolyzer OEMs building multi-gigawatt production pipelines. Buyers are locking in platinum-group-metal supply through five-to-seven-year contracts with fixed-volume escalators rather than accepting exchange-price exposure. This pattern is most visible in California and Texas, where hydrogen hub developers are securing catalyst supply chains ahead of IRA-funded project commissioning.
Nanocatalysts Market Segmentation
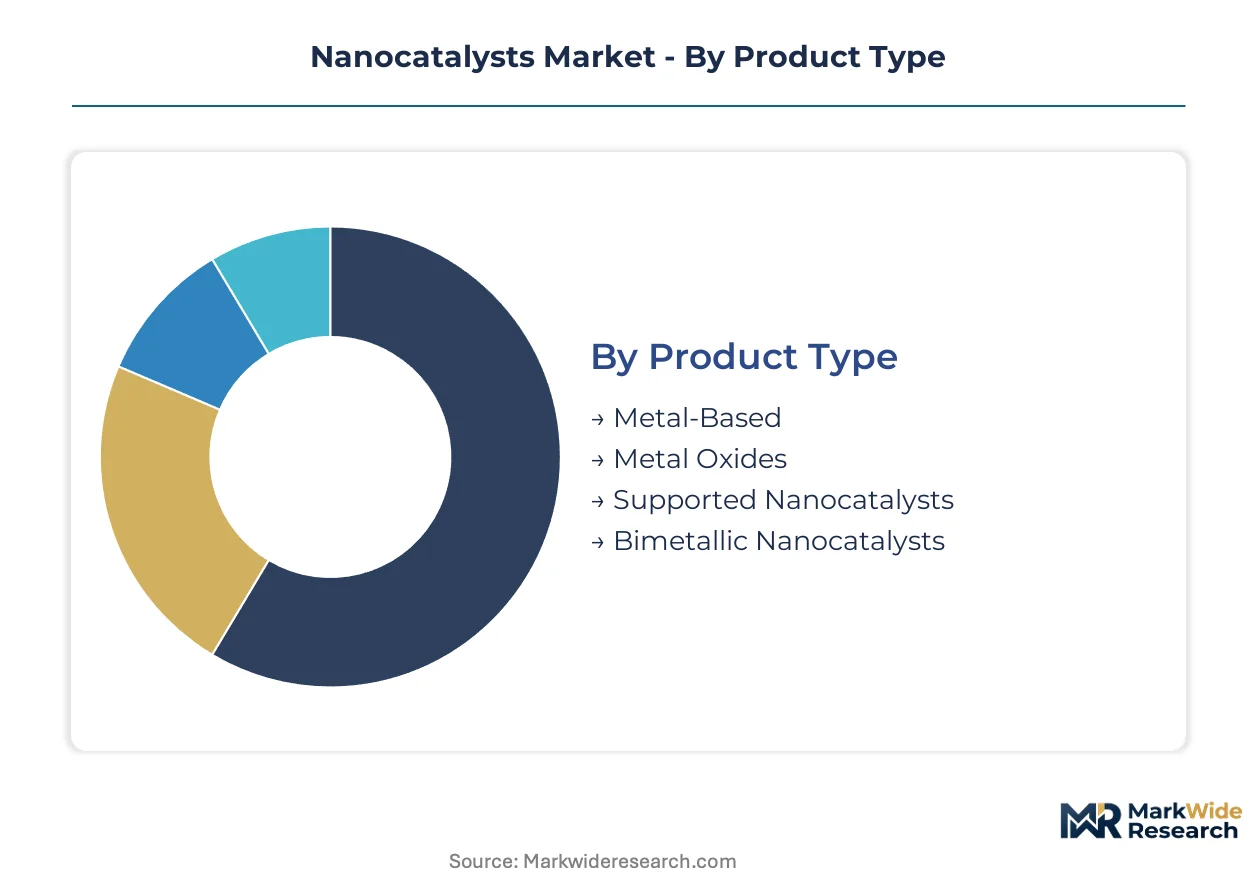
Segmentation in nanocatalysts reveals divergent margin structures and qualification barriers across product architectures and end-use environments. Buyers in fuel cells and environmental remediation prioritize performance guarantees over unit economics, while petrochemical procurement remains volume-driven and price-sensitive.
Product Type:
Buyers select product categories based on reaction specificity requirements and precious metal exposure tolerance.
- Metal-Based:Platinum, palladium, and nickel nanoparticles on carbon or alumina supports deliver established activity in hydrogenation and dehydrogenation reactions. Refinery hydrocracking units in Texas and Louisiana specify these materials for sulfur removal, though South African supply concentration forces buyers toward long-term offtake contracts to hedge price volatility.
- Bimetallic Nanocatalysts:Core-shell platinum-nickel and platinum-cobalt architectures achieve superior oxygen reduction kinetics with reduced platinum loadings. Fuel cell membrane electrode assembly manufacturers in California and Bavaria are qualifying these alloys for next-generation proton-exchange membrane stacks, driven by IRA clean hydrogen tax credits that reward metal efficiency.
- Metal Oxides:Ceria, titania, and iron oxide nanoparticles serve oxidation and photocatalytic applications. Wastewater treatment operators in Japan specify these for advanced oxidation process installations.
- Supported Nanocatalysts:Active metal phases dispersed on engineered carbon, silica, or zeolite supports maximize surface area for fixed-bed reactors. Ammonia synthesis loops at German integrated chemical sites favor alumina-supported cobalt and iron catalysts.
Volume sits with metal-based platforms; growth tilts toward bimetallic architectures.
Application:
Application selection correlates with regulatory stringency and carbon intensity disclosure requirements.
- Chemical Manufacturing:Nanocatalysts enable selective hydrogenation, oxidation, and polymerization in continuous flow reactors. Methanol and ammonia producers in the US Gulf Coast and Germany's Ruhr region operate captive catalyst regeneration facilities to minimize downtime.
- Environmental Remediation:Supported palladium and zero-valent iron nanoparticles degrade chlorinated solvents and heavy metals in groundwater plumes. Remediation contractors in California and New Jersey command premium pricing for guaranteed destruction removal efficiency contracts.
- Fuel Cells:Platinum-group-metal nanocatalysts coat membrane electrode assemblies for proton-exchange and anion-exchange systems. Electrolyzer OEMs in Texas and Norway are locking in catalyst supply through multi-year agreements ahead of gigawatt-scale project commissioning.
- Petrochemical Synthesis:Zeolite-supported metal nanocatalysts drive fluid catalytic cracking and hydrocracking conversions. Indian and Saudi refinery expansions are absorbing merchant catalyst volumes as integrated producers defer captive investment.
Chemical manufacturing retains the largest installed base; environmental remediation claims the steepest expansion trajectory.
End User:
End-user procurement sophistication varies with in-house catalysis expertise and scale economies.
- Refineries:Continuous reforming and hydroprocessing units consume bulk metal sulfide and zeolite catalysts under long-term supply agreements. US refiners face EPA emissions thresholds that mandate nanocatalyst integration in flue-gas treatment systems.
- Chemical Plants:Ammonia, methanol, and specialty chemical producers operate catalyst changeout cycles measured in years. BASF's Ludwigshafen complex sustains captive production to secure supply chain control.
- Wastewater Treatment Facilities:Municipal and industrial operators deploy nanocatalysts in advanced oxidation and catalytic wet peroxide oxidation units. Japanese utilities leverage METI subsidies for hydrogen peroxide activation systems.
- Research Institutions:National laboratories and university consortia prototype next-generation architectures through DOE and Horizon Europe funding. Lawrence Berkeley National Laboratory and Fraunhofer IKTS anchor US and German materials discovery pipelines.
Refineries dominate procurement tonnage; research institutions anchor technology pipelines.
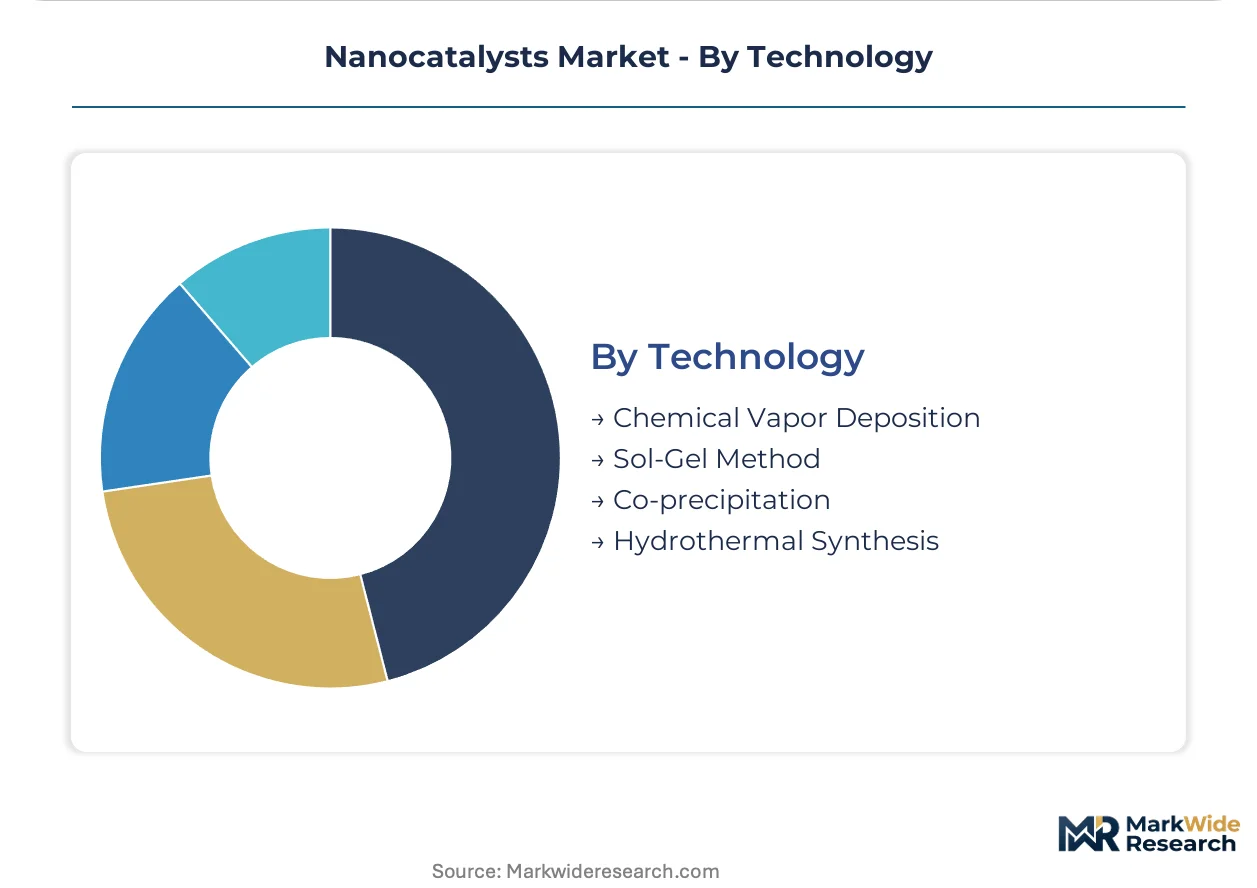
Technology:
Technology selection trades capital intensity against particle-size control and batch-to-batch reproducibility.
- Chemical Vapor Deposition:Precursor gases decompose on heated substrates to deposit ultrathin catalytic films. Fuel cell electrode manufacturers favor this route for membrane electrode assembly fabrication.
- Sol-Gel Method:Metal alkoxide hydrolysis and condensation yield high-purity oxide nanoparticles with tunable porosity. Environmental catalyst producers employ this for titania and silica support synthesis.
- Co-precipitation:Simultaneous precipitation of multiple metal salts creates intimate mixed-oxide or alloy phases at scale. BASF and Johnson Matthey operate continuous co-precipitation trains for automotive exhaust catalysts.
- Hydrothermal Synthesis:High-temperature aqueous crystallization produces well-defined metal oxide morphologies. Japanese suppliers leverage this for perovskite and spinel structures in solid oxide fuel cell electrodes.
Co-precipitation commands volume leadership; chemical vapor deposition is gaining share fastest in electrochemical applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production of platinum-group-metal nanocatalysts concentrates in South Africa and Russia, while consumption gravitates toward electrolyzer and fuel cell manufacturing clusters in Germany, the United States, and Japan. This geographic disconnect shapes procurement strategies and long-term offtake contracting patterns across the value chain.
United States
Texas and California electrolyzer OEMs are locking in multi-year catalyst supply agreements ahead of gigawatt-scale project commissioning. The Inflation Reduction Act's clean hydrogen production tax credits directly subsidize nanocatalyst procurement for proton-exchange membrane stacks. Houston hydrogen hub developers coordinate with membrane electrode assembly manufacturers to secure regional supply chain resilience.
Germany
Automotive and chemical conglomerates in Bavaria and North Rhine-Westphalia integrate nanocatalysts into exhaust-treatment and ammonia synthesis platforms. EU REACH nanomaterial registration requirements tighten documentation burdens for imported catalyst precursors. BASF's Ludwigshafen complex sustains captive production of metal oxide nanocatalysts to bypass cross-border compliance exposure.
Japan
Domestic electrolyzer manufacturers leverage METI hydrogen supply chain subsidies to fund nanocatalyst procurement. Tokyo-based fuel cell stack developers qualify bimetallic alloy architectures for 2025-2027 platform launches. Osaka industrial gas suppliers coordinate with national laboratories on perovskite electrode structures for solid oxide systems.
China
State-backed refinery expansions absorb merchant catalyst volumes as integrated producers defer captive investment. MIIT dual carbon goals accelerate membrane electrode assembly localization for domestic fuel cell vehicle programs. Yangtze River Delta chemical parks pilot alumina-supported cobalt catalysts for green ammonia demonstration projects.
South Korea
Seoul Capital Area hydrogen station operators specify platinum-group-metal nanocatalysts for high-pressure electrolyzer installations. MFDS guidelines govern nanomaterial safety dossiers for catalyst precursors entering commercial distribution. Busan-Ulsan petrochemical complexes evaluate bimetallic alternatives to reduce raw material exposure in reforming units.
Nanocatalysts Market Vendor Landscape
Top-tier vendors anchor technology leadership in membrane electrode assemblies and automotive catalytic converters, while mid-scale specialists occupy environmental remediation and research-grade niches. The vendor base stratifies across integrated chemical conglomerates with captive production capabilities, dedicated catalyst manufacturers with heterogeneous catalysis expertise, and nanomaterial specialists with precision synthesis platforms. Two dominant competitive moves define current positioning: backward integration into platinum-group-metal recycling streams and geographic regionalization of precursor synthesis to evade EU REACH cross-border compliance burdens.
Within the integrated chemical tier, BASF SE and Evonik Industries AG exemplify archetypes combining captive nanocatalyst production with downstream process technology integration. Johnson Matthey Plc occupies a distinct position as a dedicated catalyst and fuel cell component specialist with technology leadership credentials in membrane electrode assemblies. These three entities represent the competitive spectrum from diversified conglomerate to focused technology provider.
| Leading Market Players |
|---|
| BASF SE |
| Dow, Inc. |
| Evonik Industries AG |
| Johnson Matthey Plc |
| NanoScale Corporation |
| Nanophase Technologies Corporation |
| Umicore N.V. |
| Clariant AG |
| QuantumSphere, Inc. |
| Others |
Supply Flow & Price Mechanics
EU REACH nanomaterial registration mandates gate qualified supply access and premium-tier pricing power for membrane electrode assembly manufacturers seeking to serve German and French electrolyzer OEMs without cross-border compliance friction.
Pricing Analysis
Margin tightening in fuel cell-grade platinum-group-metal nanocatalysts reflects South African and Russian supply concentration forcing long-term offtake contracting at fixed-volume escalators. Three-tier pricing structure across performance-guaranteed premium, qualified-standard, and economy-grade volumes separates membrane electrode assembly manufacturers from refinery bulk buyers and research institutions. Cost-down pressure on bimetallic alloy variants accelerates as California hydrogen hub developers lock in five-to-seven-year supply agreements ahead of IRA-funded project commissioning. Petrochemical procurement teams show highest price sensitivity, while environmental remediation contractors accept premium positioning for guaranteed destruction removal efficiency contracts.
Supply Chain Analysis
Single-source vulnerability sits with South African platinum and Russian palladium concentrate output that feeds refined metal precursor production. Raw material dependencies center on platinum-group-metal sponge, carbon black supports, and alumina carriers that membrane electrode assembly fabricators source from Johnson Matthey and Umicore refining streams. Tariff exposure on nanomaterial precursors crossing into EU customs territory compounds logistics chokepoints at Rotterdam and Hamburg port complexes. Distribution runs through integrated chemical conglomerates with captive production, dedicated catalyst manufacturers with heterogeneous catalysis expertise, and nanomaterial specialists serving research-grade niches.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The nanocatalysts market sits in a technology-transition phase as bimetallic alloy architectures displace pure platinum catalysts in proton-exchange membrane fuel cell cathodes.
For Market Incumbents: Extend technology leadership in membrane electrode assemblies through backward integration into platinum-group-metal recycling streams, capturing spent automotive catalyst pyrometallurgical recovery for fuel cell electrode feedstocks. Deepen regional precursor synthesis footprints in Ludwigshafen and Bavaria to evade EU REACH cross-border documentation burdens that delay qualification timelines. For New Entrants and Emerging Players: Capture environmental remediation service contracts in California and New Jersey where premium pricing for guaranteed groundwater destruction removal efficiency creates accessible white-space. Target bimetallic nanocatalyst qualification programs at Tokyo-based fuel cell stack developers preparing 2025-2027 platform launches, leveraging METI subsidy documentation to accelerate OEM approval. For Investors and Strategic Acquirers: Long-term offtake agreement announcements from Texas and California hydrogen hub developers are the leading indicator that electrolyzer OEM procurement pipelines are firming ahead of gigawatt-scale commissioning. Position acquisition screening toward nanomaterial specialists with precision synthesis platforms and existing EPA or REACH registration dossiers, as regulatory qualification assets compound valuation premiums across the analysis window.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into PGM Recycling | Pyrometallurgical recovery from spent automotive catalysts secures feedstock for fuel cell electrode production. |
| Regional Precursor Synthesis Localization | German manufacturing footprints bypass EU REACH cross-border compliance exposure for membrane suppliers. |
| Bimetallic Alloy Architecture Development | Platinum-nickel and platinum-cobalt core-shell structures reduce metal loadings for IRA credit-eligible electrolyzers. |
| Long-term Supply Agreement Lock-in | Five-to-seven-year offtake contracts hedge South African and Russian supply concentration for OEMs. |
| Environmental Remediation Service Expansion | California and New Jersey groundwater contracts command premium pricing for supported palladium nanoparticles. |
Methodological Framework
Trade databases, SEC filings from catalyst manufacturers, and EU REACH registration dossiers formed the secondary backbone for volume and value estimation. Primary interviews with membrane electrode assembly procurement directors, electrolyzer OEM technology leads, refinery catalyst specialists, and environmental remediation contractors combined with customs records and hydrogen hub development announcements to triangulate bottom-up and top-down market sizing.
Bottom-up modeling aggregated segment-level volume across product type, application, end user, and technology dimensions, while top-down cross-checks validated aggregate figures against chemical industry capex disclosures and PGM demand forecasts. CAGRs derived from fitted growth curves incorporating IRA clean hydrogen tax credit deployment schedules, METI subsidy allocation patterns, and EU carbon border adjustment mechanism implementation phases across the projection horizon.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to platinum-group-metal price volatility, bimetallic alloy qualification timelines at automotive OEMs, and REACH nanomaterial registration enforcement intensity. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Graphene Aerogel Market
Nanomaterials
Metal and Metal Oxide Nanoparticles Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Lipid Nanoparticles Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nanocellulose Market
Nanomaterials
Carbon Nanotubes (Cnts) Market
Nanomaterials
Nano Composite Zirconia Market
Nanomaterials
Silver Nanoparticles Market
Nanomaterials
Nanotools Market