
 United Kingdom Protective Coatings Market | 2026-2036
United Kingdom Protective Coatings Market Size, Share, and Industry Trends Forecast 2026-2036
United Kingdom Protective Coatings Market Analytics
UK manufacturing capacity in protective coatings is narrowing as domestic producers face higher raw material costs and stricter environmental compliance. AkzoNobel NV leverages its marine coatings expertise to sustain leadership in North Sea offshore wind projects. PPG Industries Inc. anchors its position through automotive refinish networks serving Midlands vehicle plants. Jotun competes aggressively on industrial corrosion protection for petrochemical facilities along England's eastern seaboard.
United Kingdom Protective Coatings are formulated systems comprising epoxy, polyurethane, acrylic, or alkyd resin bases with pigments, solvents, and functional additives, applied at film thicknesses typically ranging from 50 to 500 microns depending on exposure severity. These systems protect steel and concrete substrates from corrosion, chemical attack, fire damage, and weathering across infrastructure and industrial assets. Epoxy formulations dominate heavy-duty corrosion protection applications where chemical resistance and substrate adhesion prove critical. Polyurethane topcoats command premium positioning in aesthetic finishes for architectural and automotive segments where color retention and gloss durability determine specification. The marine industry vertical generates outsized demand growth as port expansion and floating offshore wind installations multiply immersion-zone coating requirements.
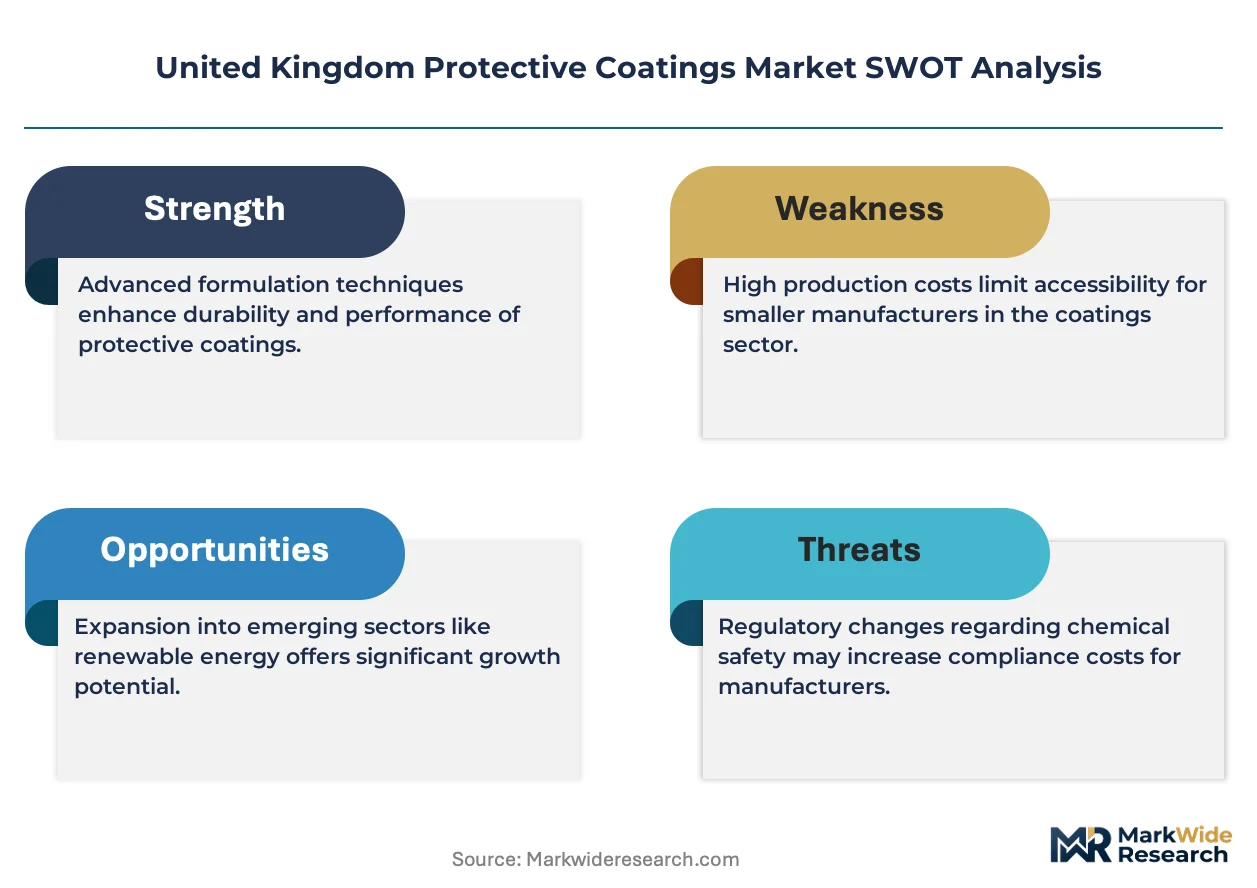
UK REACH, the Health and Safety Executive's Chemicals Regulation Division, and British Standards Institution certification frameworks collectively govern VOC limits, hazardous substance classifications, and performance testing protocols for protective coating formulations sold in Great Britain. Compliance costs favor larger formulators with dedicated regulatory affairs teams, pressuring mid-tier competitors to reformulate or exit certain product lines. Stakeholders must monitor divergence between UK REACH and EU REACH restriction schedules, as asynchronous chemical bans could fragment formulation strategies and supply qualifications across the Irish Sea trade corridor.
Market Dynamics
UK REACH chemical restrictions and floating offshore wind construction are forcing simultaneous reformulation of coating chemistry and expansion of immersion-zone application capacity across England's eastern seaboard.
Growth Catalysts
- UK REACH compliance deadlines:The Health and Safety Executive's Chemicals Regulation Division mandates low-VOC system transitions, accelerating waterborne epoxy and high-solids polyurethane adoption for industrial maintenance contracts.
- Floating offshore wind installations:Port expansion at Hull and Great Yarmouth multiplies demand for marine-grade corrosion protection systems rated for constant seawater immersion.
- East Anglia turbine manufacturing clusters:Concentrated blade and tower production facilities require specialized coating application shops with controlled environment capabilities.
Market Restraints
- Titanium dioxide supply volatility:Pigment cost fluctuations squeeze mid-tier formulators lacking long-term raw material hedging contracts with Chinese suppliers.
- Specialty resin import dependence:Epoxy hardener and isocyanate precursor supply concentrates among German and Dutch chemical producers, exposing UK blenders to Brexit-related customs friction.
- Solvent substitution technical limits:High-performance marine coatings retain solvent-borne formulations where waterborne alternatives fail to achieve required film build and cure speed specifications.
Strategic Opportunities
- Scotland's Celtic Sea lease rounds:Floating wind development west of Shetland opens new marine coating demand centers beyond England's established Humber cluster.
- Digital coating specification platforms:BIM-integrated material selection tools enable formulators to embed performance data directly into infrastructure project design phases.
- Carbon border adjustment mechanism alignment:UK producers with verified low-carbon resin sourcing gain preferential positioning for public sector infrastructure tenders.
Industry Challenges
- Certified applicator workforce gaps:SSPC and NACE-qualified spray technicians remain scarce in northern England and Scotland, constraining project execution timelines.
- UK REACH authorization dossier costs:Mid-sized formulators face six-figure regulatory submission expenses for novel biocide and corrosion inhibitor chemistries.
- Legacy asset coating compatibility:Maintenance programs on aging North Sea oil platforms require matching existing epoxy-amine systems no longer compliant with current VOC limits.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United Kingdom Protective Coatings Market |
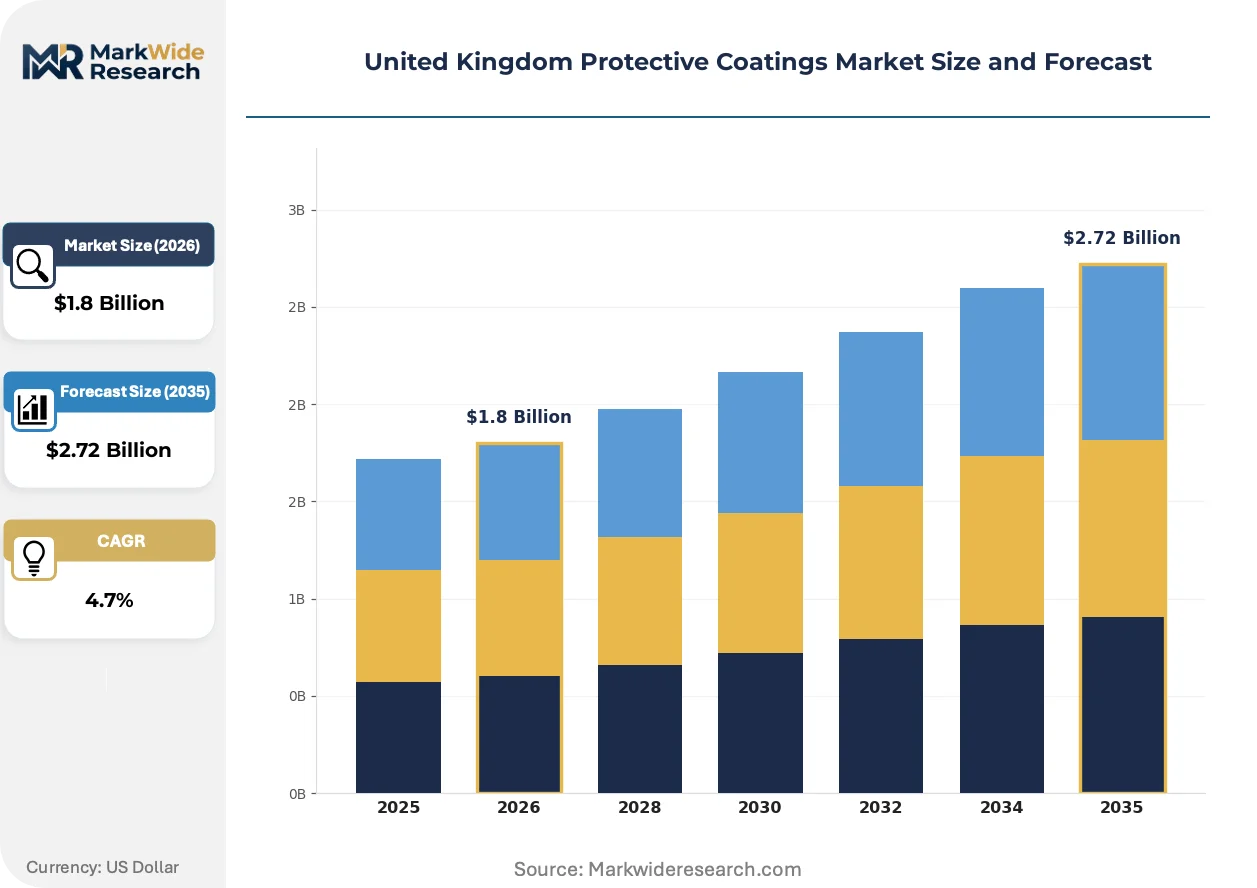
| Market Size in 2026 | $1.8 Billion |
| Market Size in 2035 | $2.72 Billion |
| CAGR (2026 – 2036) | 4.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Epoxy, Polyurethane, Acrylic, Alkyd Industry Vertical: Construction, Automotive, Marine, Aerospace Application: Corrosion Protection, Aesthetic Finishes, Fire Resistance, Chemical Resistance Delivery Mode: Spray, Brush, Roller, Dip |
| Companies Covered | AkzoNobel NV, PPG Industries Inc., RPM International Inc., Axalta Coatings Systems, Jotun, The Sherwin-Williams, HEMPEL A/S, Crown Paints, Patterson Protective Coatings Ltd., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United Kingdom Protective Coatings Market Evolving Landscape
Digital specification tools and predictive corrosion monitoring are compressing traditional coating procurement cycles while reformulation pressures accelerate bio-based resin development across marine and industrial segments.
Self-healing microcapsule technology is virtualizing protective coating value propositions by embedding crack-sealing agents within epoxy matrices. North Sea offshore wind operators are piloting these systems on monopile transition pieces to reduce inspection frequency requirements. The technology is virtualizing maintenance scheduling from calendar-based interventions toward condition-responsive service models.
UK REACH restriction proposals on chromium trioxide in corrosion inhibitors are forcing accelerated trivalent chrome and rare-earth alternative testing. The Health and Safety Executive's anticipated 2026 sunset date for hexavalent chromium in aerospace pretreatments is compressing qualification timelines for primer systems serving Midlands aircraft component suppliers. Industrial maintenance contractors are stockpiling legacy formulations while validating cerium-based conversion coating performance.
Asset owner procurement teams are consolidating coating specification authority from site-level maintenance managers toward centralized engineering functions with lifecycle cost modeling capabilities. This concentration is displacing spot-buy relationships with distributors in favor of multi-year framework agreements with formulators offering application training and warranty-backed performance guarantees. The shift is most visible across Network Rail and National Highways infrastructure programs where total cost of ownership calculations now dominate material selection criteria.
United Kingdom Protective Coatings Market Segmentation
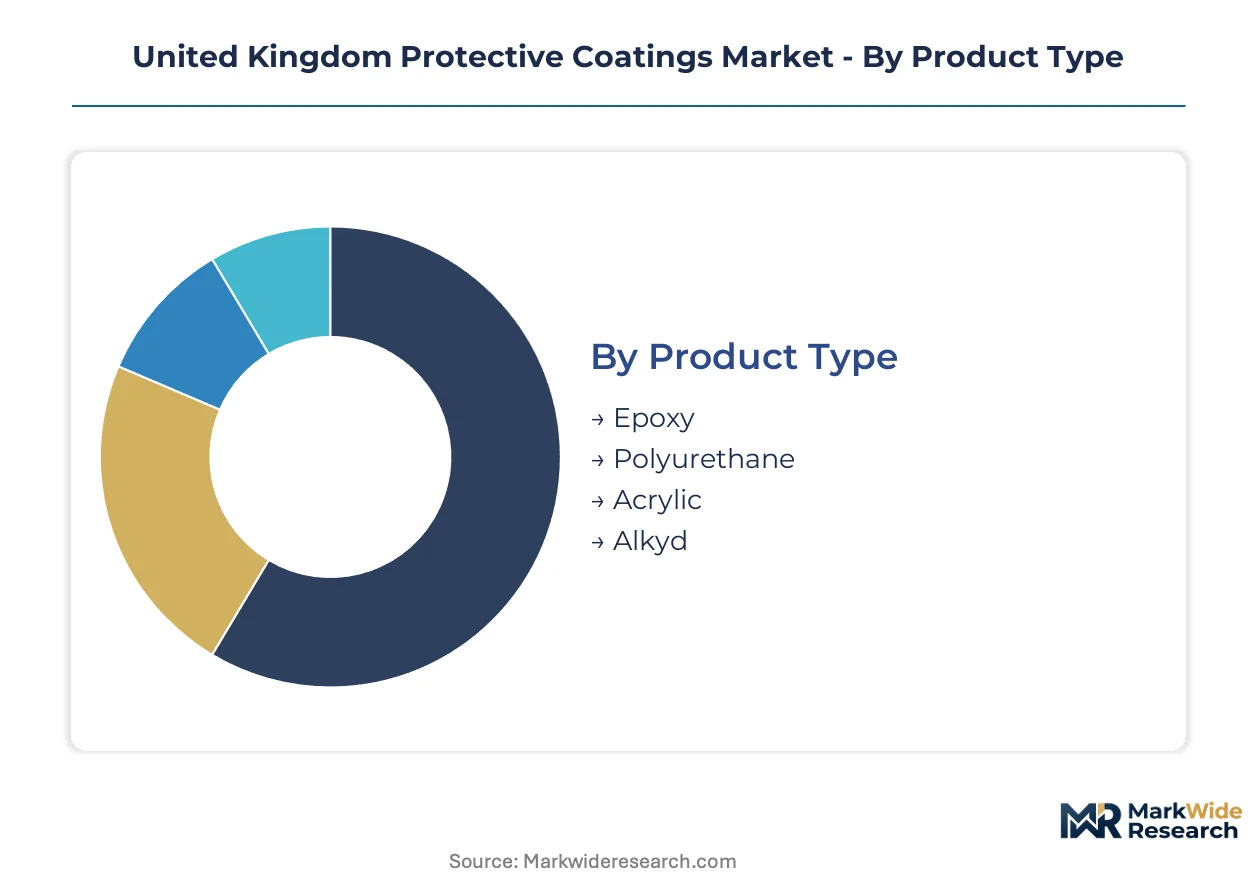
Protective coatings specification in the United Kingdom follows substrate exposure severity, regulatory compliance tiers, and application equipment availability across industrial maintenance and new construction workflows. Segmentation reveals where formulation chemistry, end-use performance requirements, and applicator skill levels intersect to determine procurement patterns.
Product Type:
Mature epoxy systems dominate heavy-duty corrosion contracts while polyurethane and acrylic formulations capture emerging demand for aesthetic durability and faster cure cycles.
- Epoxy:Two-component amine-cured systems deliver superior substrate adhesion and chemical resistance for immersion-zone marine applications and petrochemical tank linings. Demand concentrates in Humber port infrastructure and North Sea offshore wind monopile foundations where film builds exceeding 500 microns withstand constant seawater exposure. UK REACH low-VOC mandates are forcing waterborne epoxy adoption despite slower cure speeds.
- Polyurethane:Aliphatic topcoats provide UV stability and color retention for architectural steel and automotive refinish segments. East Anglia turbine manufacturing clusters specify polyurethane finishes for blade aesthetics where gloss durability determines warranty compliance. High-solids formulations are displacing conventional solvent-borne systems under HSE enforcement timelines.
- Acrylic:Waterborne acrylics serve light industrial and decorative metalwork with faster drying properties. Midlands architectural fabricators specify acrylic systems for secondary steel where corrosion exposure remains moderate.
- Alkyd:Traditional oil-modified polyesters persist in maintenance touch-up applications and heritage restoration. Yorkshire industrial contractors stock alkyd primers for compatibility with legacy coating systems on aging infrastructure.
Epoxy handles the majority of throughput; polyurethane is the fastest mover on share.
Industry Vertical:
Application complexity and asset criticality separate construction volume from marine value concentration across UK protective coatings demand.
- Construction:Steel frame buildings, bridges, and infrastructure assets require corrosion protection systems with 15-25 year design lives. Network Rail and National Highways procurement frameworks dominate specification authority, consolidating demand around certified applicator networks with warranty-backed performance guarantees.
- Marine:Port expansion at Hull and Great Yarmouth multiplies immersion-zone coating requirements for floating offshore wind installations. Constant seawater exposure demands specialized epoxy-amine systems with cathodic disbondment resistance.
- Automotive:Midlands vehicle plants and refinish networks anchor polyurethane demand for color-matched repair work. OEM clearcoat specifications drive premium formulation requirements.
- Aerospace:Aircraft component suppliers in the Midlands face UK REACH deadlines for hexavalent chromium replacement in pretreatment and primer systems. Cerium-based conversion coatings are accelerating qualification timelines.
Construction absorbs the largest application volume; marine verticals are expanding most quickly on project pipeline.
Application:
Performance specifications separate functional corrosion barriers from aesthetic and safety-critical coating functions in UK industrial procurement.
- Corrosion Protection:Barrier and inhibitive systems protect steel substrates across offshore wind, petrochemical, and infrastructure assets. Cathodic protection compatibility and salt spray resistance determine specification for North Sea environments.
- Aesthetic Finishes:Color stability and gloss retention dominate architectural and automotive segments where visual appearance affects asset valuation. Polyurethane topcoats command premium positioning.
- Fire Resistance:Intumescent coatings expand under heat exposure to protect structural steel in commercial buildings and transport infrastructure. Building Regulations approval drives certification requirements.
- Chemical Resistance:Tank linings and secondary containment systems require epoxy novolac and vinyl ester formulations for aggressive chemical exposure. Petrochemical facilities along England's eastern seaboard specify specialized systems.
Corrosion protection commands the deepest specification expertise; fire resistance is climbing fastest on regulatory enforcement.
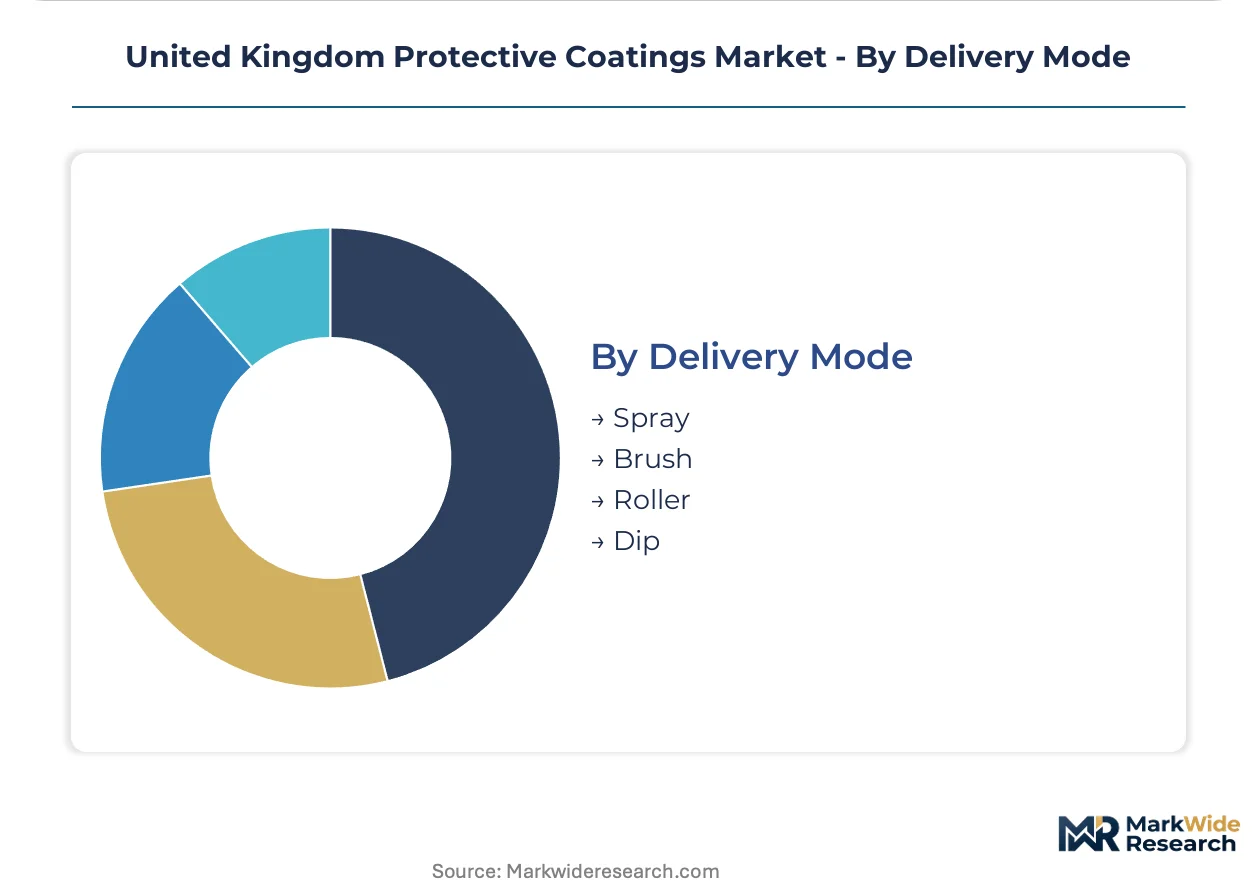
Delivery Mode:
Equipment capital intensity and applicator certification requirements segment spray application from manual methods across UK coating contractor bases.
- Spray:Airless and conventional spray equipment deliver high film builds efficiently across large surface areas. SSPC and NACE-qualified spray technicians remain scarce in northern England and Scotland, constraining project execution timelines for industrial maintenance contracts.
- Brush:Manual application persists in touch-up work, complex geometries, and confined spaces where spray overspray risks exceed tolerances. Heritage restoration and secondary steel maintenance specify brush application.
- Roller:Large flat surfaces in tank interiors and structural steel benefit from roller application speed where surface profile permits. Mid-tier contractors deploy roller methods for cost-sensitive maintenance programs.
- Dip:Batch coating of small components and fasteners achieves uniform coverage in controlled factory environments. Yorkshire and Midlands metal finishing shops maintain dip line capacity for hardware and fabrication accessories.
Spray application handles the majority of industrial throughput; dip coating is gaining share fastest on manufacturing reshoring.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
England's eastern seaboard consumes protective coatings differently from Scotland's emerging wind frontiers, with immersion-grade marine systems dominating Hull while high-altitude corrosion protection shapes Shetland specifications.
London and the Southeast
Commercial construction and transport infrastructure anchor demand for intumescent fire protection and architectural steel coatings. UK REACH compliance deadlines from the Health and Safety Executive accelerate waterborne system adoption across Thames-side fabrication yards. Crossrail and HS2 legacy projects concentrate specification authority with Network Rail procurement frameworks serving Greater London contractors.
Midlands
Automotive OEM plants and aerospace component suppliers drive polyurethane and pretreatment chemical demand. UK REACH's anticipated hexavalent chromium sunset compresses qualification timelines for cerium-based conversion coatings at Birmingham and Derby manufacturing clusters. Midlands vehicle plants specify color-matched refinish networks for warranty-compliant repair work.
North England
Humber port infrastructure and East Anglia turbine manufacturing generate concentrated marine-grade epoxy demand for offshore wind monopile foundations. Hull and Great Yarmouth expansion projects multiply immersion-zone coating requirements where film builds exceed 500 microns. SSPC-certified applicator scarcity constrains project execution timelines across Yorkshire industrial maintenance contracts.
Scotland
Floating offshore wind development west of Shetland opens new marine coating demand centers beyond England's established clusters. Celtic Sea lease rounds require cathodic disbondment-resistant systems rated for constant North Atlantic exposure. Aberdeen's decommissioning expertise transfers to floating wind jacket foundation coating programs.
Wales
Steel fabrication for construction and port maintenance sustains alkyd and epoxy demand around Cardiff and Newport. Heritage restoration projects specify brush-applied traditional systems for compatibility with aging infrastructure. Welsh industrial contractors stock legacy formulations while validating low-VOC alternatives under UK REACH transition timelines.
United Kingdom Protective Coatings Market Competitive Landscape
Capability concentration sits with specialized marine formulators; scale advantage sits with diversified industrial coatings portfolios. The vendor base separates into three tiers: multinational integrated suppliers with UK REACH compliance infrastructure, regional specialists anchoring port-based application networks, and mid-tier blenders facing raw material cost pressure. Dominant competitive moves include formulation reformulation for VOC compliance and strategic positioning around floating offshore wind qualification programs.
Among Netherlands-based integrated suppliers, AkzoNobel NV exemplifies the marine-specialized archetype with North Sea offshore wind positioning. PPG Industries Inc. represents the diversified industrial portfolio model serving Midlands automotive networks. Jotun occupies a position within the immersion-zone corrosion protection tier competing on petrochemical facility specifications along England's eastern seaboard.
| Leading Market Players |
|---|
| AkzoNobel NV |
| PPG Industries Inc. |
| RPM International Inc. |
| Axalta Coatings Systems |
| Jotun |
| The Sherwin-Williams |
| HEMPEL A/S |
| Crown Paints |
| Patterson Protective Coatings Ltd. |
| Others |
Value Network & Pricing Analysis
Hull's marine coating application capacity concentration grants qualified contractors substantial pricing leverage over floating offshore wind developers facing compressed installation windows. UK REACH compliance costs and titanium dioxide supply volatility are forcing mid-tier formulators to absorb margin compression or exit certain product lines entirely.
Pricing Analysis
Long-term framework agreements dominate procurement across Network Rail and National Highways infrastructure programs, displacing spot-buy relationships with distributors. Three-tier pricing structure across premium, standard, and economy levels separates warranty-backed marine systems from basic industrial maintenance formulations. Pricing pressure stems from raw material cost volatility and certified applicator scarcity constraining project execution timelines. Volume-sensitive maintenance contractors exhibit highest price sensitivity; offshore wind developers with lifecycle cost modeling capabilities show lowest.
Supply Chain Analysis
Epoxy hardener and isocyanate precursor feedstocks draw from German and Dutch chemical producers, exposing UK blenders to Brexit-related customs friction. Titanium dioxide pigments source from Chinese suppliers; specialty corrosion inhibitors concentrate among European formulators. Single-source vulnerability runs through German epoxy hardener supply for North Sea marine applications. Distribution runs through port-based coating contractors with SSPC certification and direct formulator relationships.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The UK protective coatings market functions as a service-attach opportunity where application training, warranty-backed performance guarantees, and predictive maintenance contracts expand faster than commodity formulation sales. Recurring revenue from certified applicator networks and digital specification platform subscriptions outpaces hardware growth.
For Market Incumbents: Pre-empt mid-tier competitor exits by acquiring distressed formulation assets and converting them to UK REACH-compliant waterborne production capacity. Anchor position through backward integration into specialty resin blending to reduce German supply dependency. Prioritize SSPC-certified applicator training program expansion to capture floating offshore wind installation demand. For New Entrants and Emerging Players: Establish a beachhead in Scotland's Celtic Sea floating wind corridor where incumbent applicator networks remain underdeveloped. Target digital coating specification platform partnerships with infrastructure engineering consultancies lacking BIM-integrated material selection tools. Deploy cerium-based conversion coating qualification services for Midlands aerospace suppliers facing hexavalent chromium sunset deadlines. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors vertically integrated coating contractors with captive applicator certification programs and port-based logistics infrastructure. Long-term viability hinges on UK REACH compliance infrastructure and floating offshore wind qualification track records. Monitor divergence between UK REACH and EU REACH restriction schedules as inflection indicator for supply chain reconfiguration opportunities.| Strategic Initiative | Industry Significance |
|---|---|
| UK REACH Compliance Infrastructure Investment | Health and Safety Executive enforcement timelines favor formulators with dedicated regulatory affairs teams and reformulation capabilities. |
| Floating Offshore Wind Qualification Programs | Cathodic disbondment-resistant system certifications unlock Hull and Great Yarmouth port expansion contract access. |
| SSPC-Certified Applicator Network Expansion | Scarce spray technician capacity in northern England and Scotland constrains project execution timelines for qualified contractors. |
| Digital Specification Platform Development | BIM-integrated material selection tools embed formulator performance data directly into Network Rail infrastructure design phases. |
| Bio-Based Resin R&D Partnerships | UK REACH low-VOC mandates accelerate waterborne epoxy and high-solids polyurethane adoption requiring novel feedstock pathways. |
Research Methodology
Two parallel data streams informed the analysis: primary interviews with coating formulator technical directors, port infrastructure procurement managers, SSPC-certified applicator contractors, and Health and Safety Executive regulatory affairs specialists; and secondary validation against UK trade statistics, British Standards Institution certification databases, offshore wind project development registries, and SEC filings of multinational coating suppliers. Bottom-up volume estimates from individual application segments were triangulated against top-down market sizing from raw material consumption patterns.
Forecast inputs across the projection horizon incorporated resin chemistry segmentation, industry vertical exposure severity tiers, and regional installation capacity constraints. CAGRs were derived from regression analysis of historical formulation demand against offshore wind capacity deployment schedules and UK REACH transition timelines. Modeling explicitly captured applicator certification bottlenecks and titanium dioxide supply elasticity assumptions.
Stress conditions across raw material cost volatility, regulatory restriction acceleration, and certified technician availability were modeled; outcomes outside those bands fall beyond the analytical envelope. Forecasts reflect documented assumptions about floating offshore wind project sanctioning rates and UK REACH enforcement intensity. Cross-checking against Health and Safety Executive chemical registration databases and Crown Estate lease round announcements is advised before commitment-grade decisions.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Coatings
Silicate Coatings Market
Coatings
Camouflage Coatings Market
Coatings
Functional Coil Coating Market
Coatings
Conductive Polymer Coatings Market
Coatings
Global Fire-Resistant Coating Market
Coatings
Self-Healing Coatings Market
Coatings
United Arab Emirates Floor Coatings Market
Coatings
In-Mold Coatings Market
Coatings
Coatings Raw Materials Market
Coatings
Asia-Pacific Coil Coatings Market
Coatings
Japan Protective Coatings Market
Coatings
Global Antiviral Coatings Market
Coatings
Marine Deck Coatings Market
Coatings
Nigeria Protective Coatings Market
Coatings
Coating Equipment Market
Coatings
Global Surface Protection Films Market