
 Boron Nitride Nanotubes Market | 2026-2036
Boron Nitride Nanotubes Market Size, Share, and Industry Trends Forecast 2026-2036
Boron Nitride Nanotubes Market Outlook
The EU Green Deal is rebalancing material selection criteria across European aerospace and electronics supply chains, compelling formulators to validate non-toxic thermal conductors. BN Nano leverages its patent position in high-purity synthesis to sustain premium pricing for defense-qualified grades. Tekna anchors European supply through plasma-torch production scale-up, while BNNano competes on cost-engineered multi-walled variants for industrial coating applications.
Boron nitride nanotubes are hollow cylindrical structures composed of alternating boron and nitrogen atoms, exhibiting thermal conductivity up to 400 W/m·K and band gaps near 5.5 eV, serving primarily as electrically insulating heat dissipators and structural reinforcements in extreme environments. The aerospace application segment leads in value contribution due to qualification cycles and performance premiums attached to radiation-shielding and ablative coating grades. Multi-walled product types dominate volume throughput, though functionalized variants are capturing margin pools as epoxy and ceramic matrix composite formulators seek covalent grafting compatibility.
EPA toxicity review protocols in the United States and REACH substance authorization under ECHA are tightening the evidentiary burden for nanomaterial commercialization, advantaging producers with pre-registered safety dossiers. Japan's METI coordinates domestic standardization through JIS committees, accelerating qualification pathways for semiconductor thermal interface materials. Stakeholders must monitor evolving polymer matrix qualification standards and alignment between national nanomaterial registries to secure uninterrupted market access across jurisdictions.
Market Dynamics
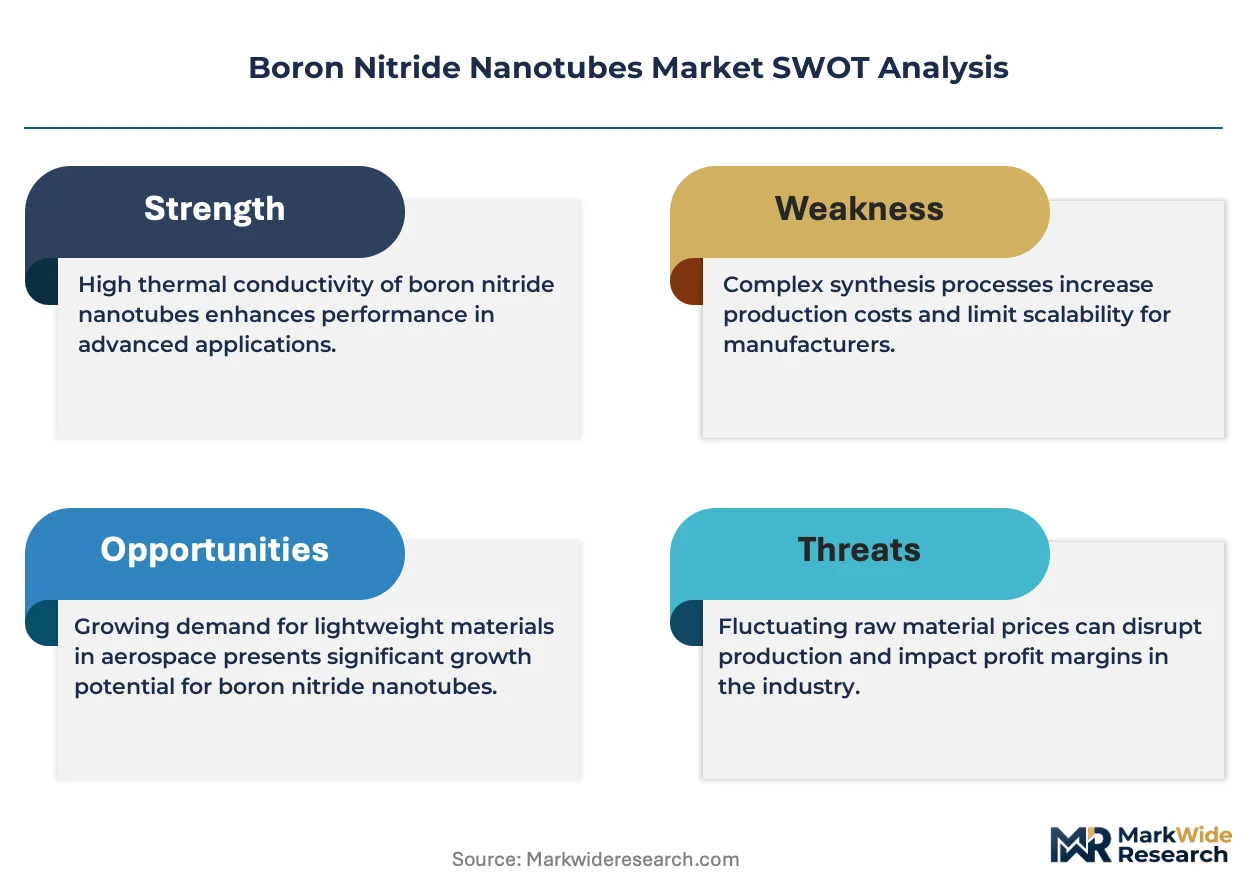
The Boron Nitride Nanotubes Market pivots on a fundamental supply-demand asymmetry: aerospace and semiconductor thermal management requirements are outstripping qualified production capacity, creating qualification bottlenecks that favor incumbent synthesizers with defense-grade certification histories.
Growth Catalysts
- Hypersonic vehicle thermal protection systems:US and Japanese aerospace primes are accelerating material qualification for leading-edge and nose-cone applications, pulling multi-walled BNNT volumes into long-term supply agreements.
- EU Green Deal substance substitution mandates:REACH authorization pressures are forcing coating formulators to replace carbon nanotubes in electrically conductive thermal interface materials, redirecting specification work toward boron nitride alternatives.
- Plasma-torch synthesis scale-up:European producers are expanding reactor throughput for industrial-grade powders, lowering unit costs for polymer matrix composite integration.
Market Restraints
- High-purity boron precursor cost volatility:Isotopically enriched boron feedstock prices fluctuate with nuclear industry demand cycles, compressing margins for semiconductor-grade nanotube production.
- Single-source defense qualification dependencies:US aerospace supply chains concentrate on two qualified synthesizers, creating concentration risk for hypersonic program timelines.
- Functionalization chemistry limitations:Covalent sidewall modification protocols remain proprietary, restricting epoxy and ceramic matrix grafting compatibility for second-tier composite formulators.
Strategic Opportunities
- India semiconductor packaging thermal materials:PLI scheme incentives for domestic chip fabrication are opening specification windows for imported BNNT thermal interface materials in Bengaluru and Hyderabad packaging facilities.
- Quantum computing cryogenic thermal management:Superconducting qubit architectures require electrically insulating heat sinks at millikelvin temperatures, a performance envelope where boron nitride nanotubes outperform metallic alternatives.
- Japan METI-funded radiation shielding consortia:Government-backed standardization through JIS committees is accelerating qualification pathways for lunar and deep-space habitat applications.
Industry Challenges
- Plasma physics and materials science PhD scarcity:Reactor optimization and quality control functions require specialized expertise that outpaces academic pipeline output in Europe and North America.
- Dual-use export control classification complexity:US ITAR and EU dual-use regulations create licensing friction for aerospace-grade material shipments, extending order-to-delivery cycles.
- Polymer matrix qualification protocol fragmentation:Absent harmonized ASTM or ISO test standards, composite formulators must repeat expensive qualification work for each OEM customer.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Boron Nitride Nanotubes Market |
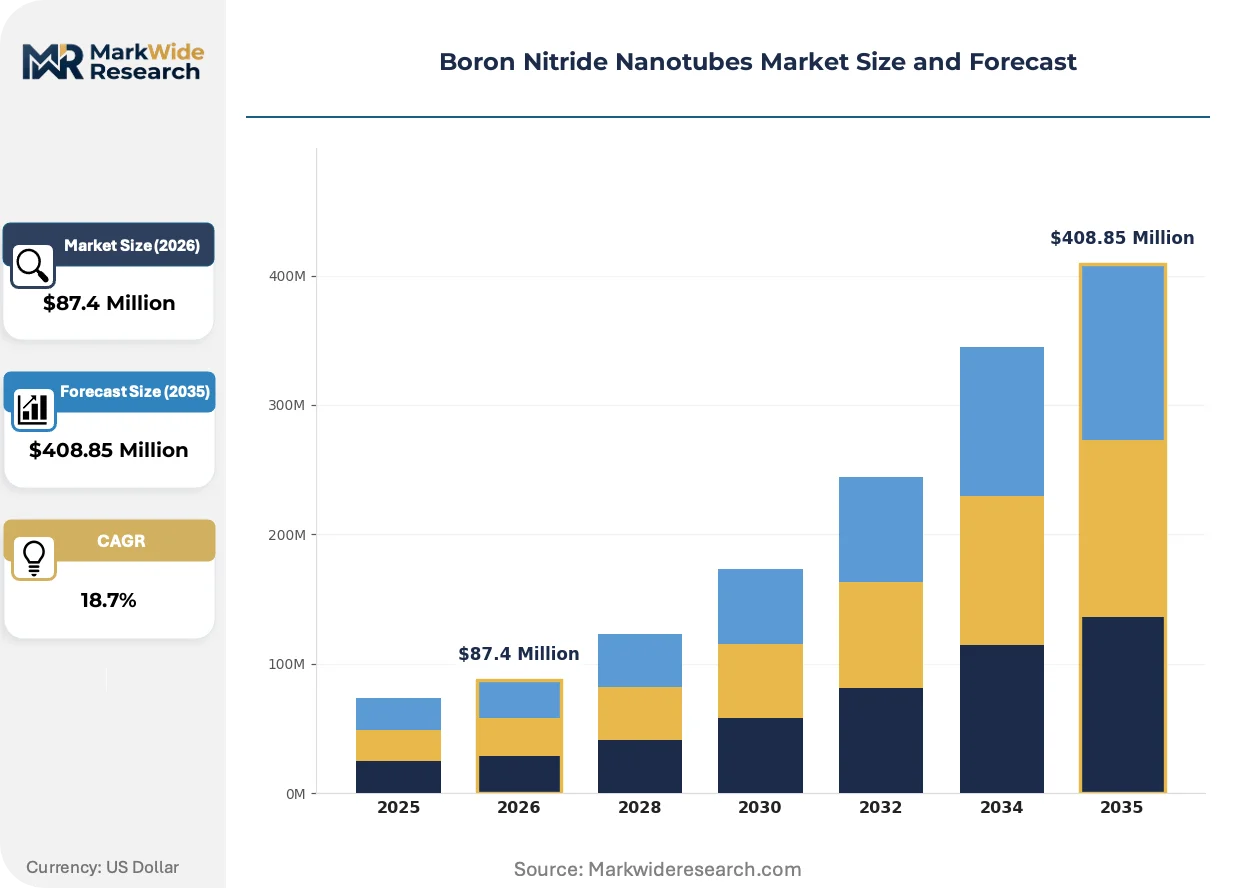
| Market Size in 2026 | $87.4 Million |
| Market Size in 2035 | $408.85 Million |
| CAGR (2026 – 2036) | 18.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single-Walled, Multi-Walled, Functionalized, Composite Application: Electronics, Aerospace, Coatings, Nanocomposites End User: Consumer Electronics, Automotive, Defense, Healthcare Distribution Channel: Direct Sales, Online Retail, Distributors, Resellers |
| Companies Covered | BN Nano, NanoIntegris Technologies, Tekna, US Research Nanomaterials, Alfa Chemistry, BNNano, Nan Integris, Epic Advanced Materials, BNNT, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Boron Nitride Nanotubes Market Strategic Shifts
Plasma-based synthesis methods are consolidating technical leadership in this market, compressing the viable process window for competing chemical vapor deposition routes while enabling new application categories through purity and scale improvements.
High-temperature plasma-torch synthesis is consolidating as the dominant production architecture for industrial-grade boron nitride nanotubes. Aerospace thermal protection system suppliers in the United States and Japan are specifying plasma-derived powders exclusively for ablative coating matrices. This technology is consolidating supplier tiers by rendering small-batch chemical vapor deposition operations economically unviable for volume contracts.
REACH substance authorization requirements under ECHA are tightening evidentiary standards for nanomaterial commercialization in European coating and electronics supply chains. Formulators must now submit extended safety dossiers for boron nitride variants previously grandfathered under carbon nanotube registrations. Industrial coating segments in Germany and France are responding by consolidating procurement onto pre-registered supply sources with existing authorization track records.
Long-term offtake agreements are displacing spot-market purchasing in semiconductor thermal interface material supply chains. Japanese packaging houses in Kyoto and Osaka prefectures are locking multi-year supply contracts directly with synthesizers, bypassing traditional distributor intermediaries. This pattern is most visible in METI-coordinated consortia where radiation shielding and thermal management specifications are bundled into single-source qualification programs.
Boron Nitride Nanotubes Market Segmentation
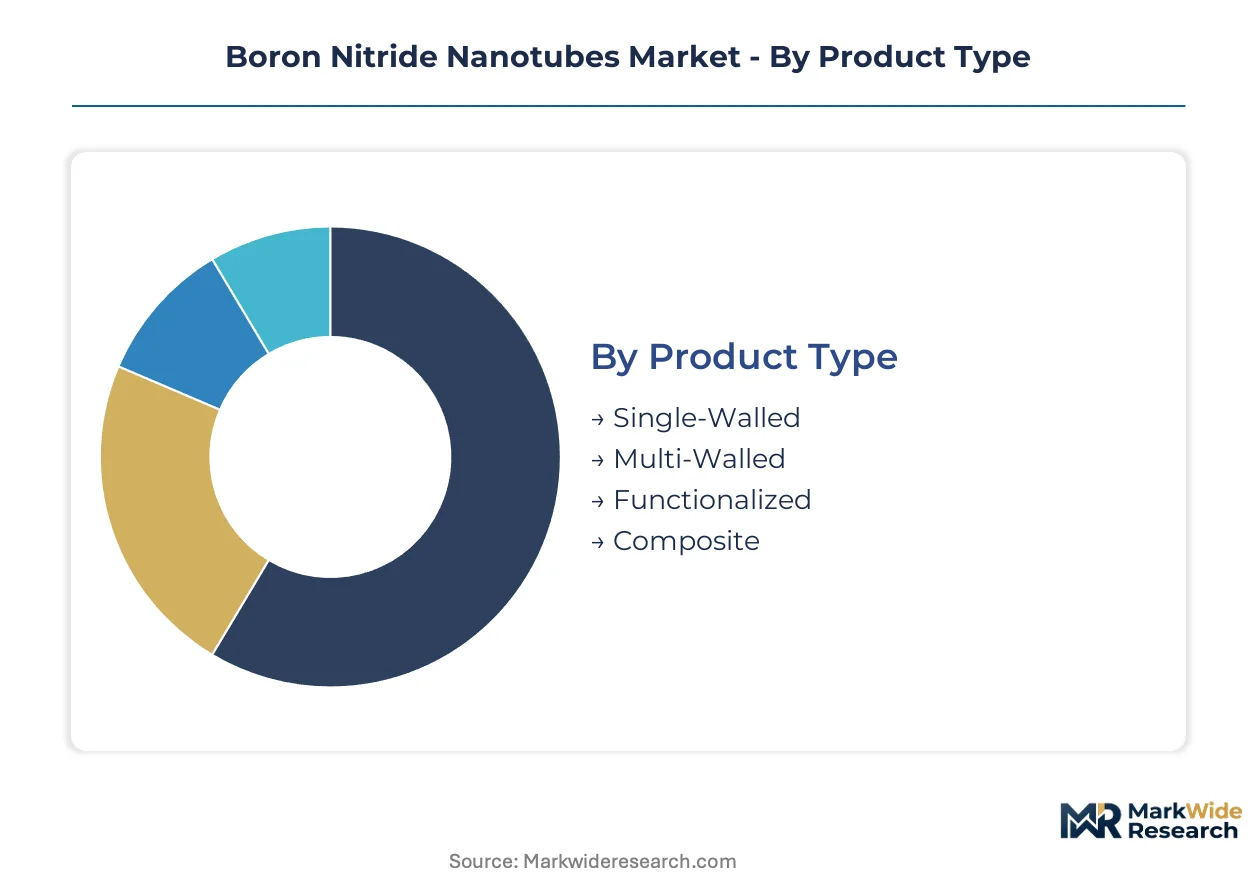
Segmentation in boron nitride nanotubes reveals how synthesis complexity and qualification barriers create distinct commercial tiers. Buyers sort by thermal performance requirements, regulatory exposure, and integration chemistry rather than commodity pricing.
Product Type:
Cost tiers separate qualified aerospace grades from industrial coating powders, with purity premiums widening as defense certification layers accumulate.
- Multi-Walled:Concentric cylindrical shells of alternating boron and nitrogen atoms deliver thermal conductivity exceeding 300 W/m·K with mechanical resilience. Aerospace manufacturers in the United States and Japan specify these exclusively for ablative thermal protection systems, pulling volumes through multi-year defense contracts with embedded price escalation clauses.
- Functionalized:Covalent sidewall modifications enable dispersion in epoxy and ceramic matrix composites through grafting chemistry. European coating formulators under REACH authorization pressure are redirecting procurement toward pre-registered functionalized grades that bypass extended safety dossier requirements.
- Single-Walled:Atomically thin walls exhibit band gaps near 5.5 eV with exceptional specific surface area for semiconductor thermal interfaces.
- Composite:Pre-dispersed polymer masterbatches reduce handling complexity for industrial composite formulators lacking in-house nanomaterial processing capability.
Multi-Walled leads volumes today; Functionalized is gaining share fastest.
Application:
Application selection tracks environmental extremity, with radiation exposure and re-entry heating defining the performance envelope.
- Aerospace:Leading-edge and nose-cone thermal protection systems for hypersonic vehicles demand qualified multi-walled powders with defense-grade certification histories. Japanese METI-funded consortia are bundling radiation shielding and thermal management specifications into single-source qualification programs for lunar habitat applications.
- Electronics:Semiconductor packaging thermal interface materials require electrically insulating heat dissipation with dielectric strength above breakdown thresholds for advanced node chips. Kyoto and Osaka packaging houses are locking multi-year supply contracts directly with synthesizers, bypassing traditional distributor intermediaries.
- Coatings:EU Green Deal substance substitution mandates are forcing replacement of carbon nanotubes in electrically conductive thermal interface materials.
- Nanocomposites:Ceramic and polymer matrix reinforcement applications concentrate in industrial tooling and wear-resistant components.
Aerospace dominates value contribution; Electronics is climbing the fastest as semiconductor node advancement accelerates thermal density challenges.
End User:
End user procurement patterns diverge sharply between specification-driven defense primes and price-sensitive industrial formulators.
- Defense:Hypersonic vehicle programs in the United States and Japan concentrate procurement onto two qualified synthesizers, creating single-source dependencies that extend order-to-delivery cycles through ITAR licensing friction. Long-term offtake agreements with embedded minimum volume guarantees lock supply security for critical thermal protection system timelines.
- Consumer Electronics:Smartphone and laptop manufacturers specify boron nitride nanotubes for thermal interface pads and heat spreaders, with Japanese packaging houses driving qualification through METI-coordinated standardization committees.
- Automotive:Battery thermal management and power electronics cooling applications are emerging as specification targets for industrial-grade functionalized powders.
- Healthcare:Biocompatible coating applications for implantable devices remain pre-commercial, constrained by FDA toxicity review protocol timelines.
Defense anchors premium pricing; Consumer Electronics is expanding most quickly as device thermal density intensifies.
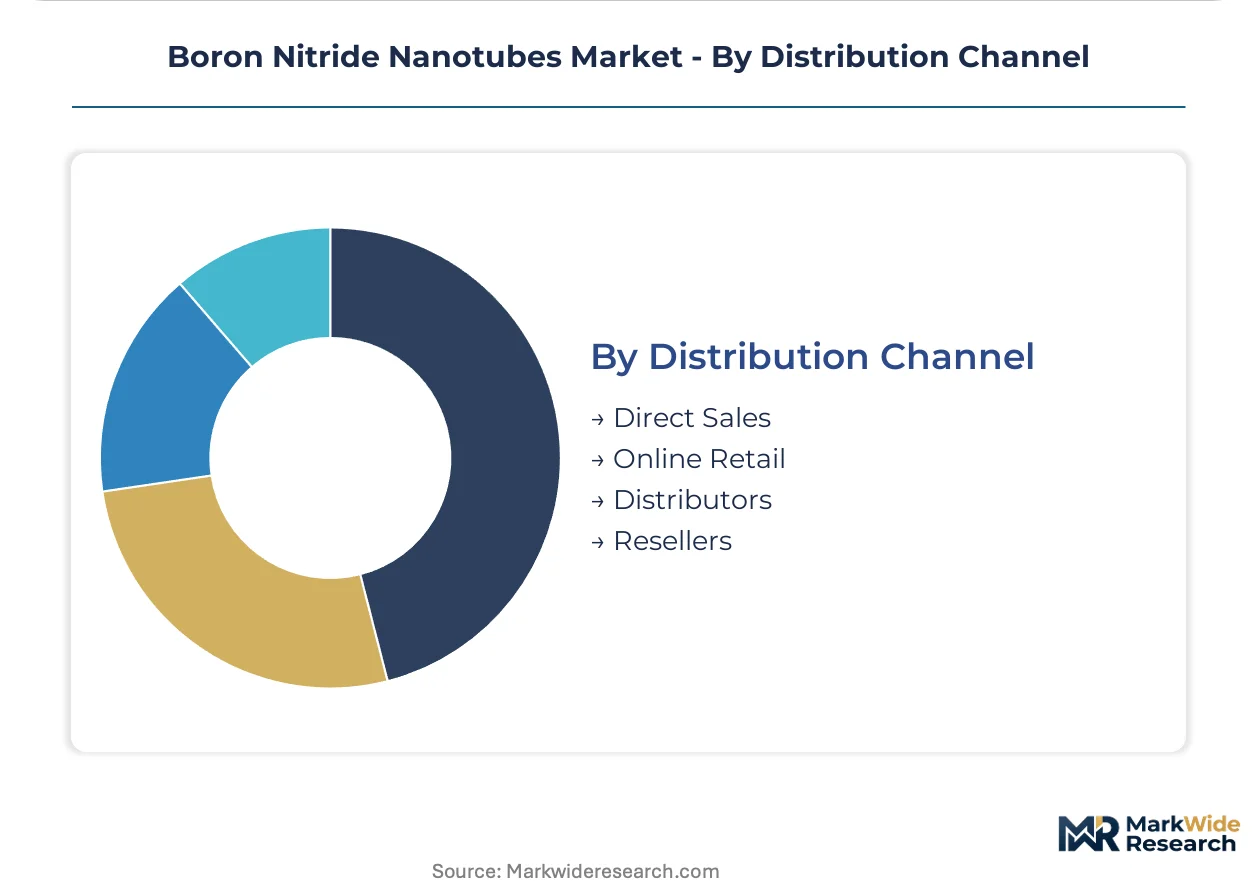
Distribution Channel:
Channel selection reflects customer scale and qualification burden, with large-volume buyers internalizing supply chain risk.
- Direct Sales:Aerospace primes and semiconductor packaging houses negotiate multi-year supply agreements directly with plasma-torch synthesis operators, securing volume commitments and technical support for matrix qualification protocols. This channel captures the highest-margin defense and electronics grades.
- Distributors:Industrial coating formulators and smaller composite manufacturers rely on authorized distributors for batch-scale procurement and regulatory documentation, particularly in Europe where REACH authorization requirements demand pre-registered supply sources.
- Online Retail:Research quantities and sample batches for academic and early-stage development flow through specialized nanomaterial portals.
- Resellers:Secondary market participants aggregate spot availability for unqualified industrial grades with limited traceability.
Direct Sales dominates value capture; Distributors is gaining share fastest as REACH compliance burdens concentrate procurement onto authorized intermediaries.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Plasma physics and materials science PhD concentrations in Japan, the United States, and Germany anchor the qualified production base for aerospace-grade nanotubes. Defense procurement offices and semiconductor packaging clusters in these markets pull volumes through multi-year supply agreements.
United States
Hypersonic vehicle thermal protection programs at Lockheed Martin and Raytheon drive multi-walled BNNT procurement through ITAR-governed channels. EPA toxicity review protocols under TSCA Section 5 tighten pre-manufacture notification requirements for nanomaterial commercialization. California's aerospace corridor from Palmdale to San Diego concentrates ablative coating qualification work with defense-certified synthesizers.
Japan
METI-funded consortia bundle radiation shielding and thermal interface specifications for lunar habitat and advanced node semiconductor packaging. JIS standardization committees accelerate qualification pathways through coordinated industry-government working groups. Kyoto and Osaka prefectures host packaging houses locking multi-year direct supply contracts with plasma-torch operators.
Germany
EU Green Deal substance substitution mandates force coating formulators toward REACH-authorized boron nitride alternatives to carbon nanotubes. ECHA extended safety dossier requirements concentrate procurement onto pre-registered supply sources. The Rhine-Ruhr industrial cluster sees industrial coating manufacturers consolidating vendor qualification onto authorized distributors.
South Korea
Semiconductor foundries at Samsung and SK Hynix specify electrically insulating thermal interface materials for 3nm node advancement. MFDS nanomaterial safety guidelines align with OECD test guidelines for commercialization readiness. The Gyeonggi-do packaging corridor drives specification work for imported BNNT masterbatches.
India
PLI scheme incentives for domestic chip fabrication open specification windows for thermal interface material imports at Bengaluru and Hyderabad packaging facilities. BIS nanomaterial standards development lags commercial demand, creating temporary reliance on qualified foreign supply. The Delhi-Mumbai Industrial Corridor hosts early composite formulator trials for industrial coating applications.
Boron Nitride Nanotubes Market Competitive Environment
Capital-heavy plasma-torch producers compete with asset-light specialty distributors and research-grade suppliers in a tiered market structure. The vendor base separates into defense-qualified synthesizers with ITAR certifications, industrial-grade powder suppliers scaling reactor throughput, and research-quantity providers serving academic development. Three archetypes dominate: integrated plasma operators, functionalization chemistry specialists, and authorized distribution intermediaries. Capacity expansion and strategic partnerships constitute the dominant competitive moves as qualified production scarcity extends order-to-delivery cycles.
Among North American synthesizers, BN Nano and BNNano occupy positions within the defense-qualified tier, while Tekna anchors European supply through plasma-torch scale-up. These three exemplify the geographic clustering of qualified production capacity around government-funded standardization programs and aerospace procurement offices.
| Leading Market Players |
|---|
| BN Nano |
| NanoIntegris Technologies |
| Tekna |
| US Research Nanomaterials |
| Alfa Chemistry |
| BNNano |
| Nan Integris |
| Epic Advanced Materials |
| BNNT |
| Others |
Value Chain & Pricing Dynamics
Defense-qualified plasma-torch operators backed by venture and sovereign capital pools anchor supply discipline, translating scarcity premiums into sustained margin capture across aerospace and semiconductor tiers. This ownership pattern concentrates pricing power with synthesizers holding ITAR certifications and METI-registered production lines, while cost-engineered industrial grades compete on volume throughput from European scale-up facilities.
Pricing Analysis
Long-term offtake agreements versus spot procurement splits the market into contract-anchored and transaction-exposed tiers. Three-tier pricing structure across defense-qualified, industrial-grade, and research-quantity levels separates ITAR-certified aerospace powders from REACH-registered coating grades and unqualified academic batches. Cost compression in industrial coating segments is intensifying because plasma-torch scale-up in Europe expands qualified supply. Defense primes exhibit lowest price sensitivity due to program-critical qualification dependencies; industrial formulators face highest sensitivity as carbon nanotube substitution mandates compress substitution economics.
Supply Chain Analysis
Isotopically enriched boron feedstock supply rests on nuclear industry demand cycles in the United States, Kazakhstan, and Turkey, tethering semiconductor-grade nanotube margins to uranium enrichment byproduct markets. Hexagonal boron nitride precursor, plasma reactor consumables, and functionalization chemistry reagents constitute critical input dependencies. Single-source vulnerability concentrates in ITAR-governed defense qualification channels, where two US synthesizers control qualified hypersonic program supply. Distribution runs through direct sales for aerospace and electronics volumes, with authorized distributors handling REACH-compliant European coating procurement.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Plasma-torch synthesis scale-up represents the dominant cost-down trajectory, enabling margin expansion as reactor throughput absorbs fixed capital across larger output bases while defense premiums sustain pricing power in qualified tiers.
For Market Incumbents: Hedge against functionalization chemistry commoditization by locking proprietary sidewall modification IP through targeted R&D allocation in covalent grafting protocols. Secure backward integration into isotopically enriched boron feedstock through offtake agreements with nuclear industry suppliers, insulating semiconductor-grade margins from raw material volatility. Channel control through direct sales relationships with Japanese packaging houses and US aerospace primes sustains pricing power against distributor-mediated competition. For New Entrants and Emerging Players: Authorized distributors with REACH pre-registration track records offer the most penetrable entry channel for European industrial coating formulators seeking compliant supply alternatives to carbon nanotubes. Target India's PLI-backed semiconductor packaging facilities in Bengaluru and Hyderabad, where BIS standardization lags create temporary windows for qualified foreign supply. A technical partnership with established plasma-torch operators for toll synthesis under private-label arrangements accelerates market access without capital-intensive reactor buildout. For Investors and Strategic Acquirers: Valuations sit cheapest among asset-light functionalization chemistry specialists with proprietary grafting protocols but limited synthesis capacity. The five-to-ten year viability window favors integrated plasma operators with defense certification histories and METI-registered Japanese production lines. Watch JIS standardization committee outputs for lunar habitat radiation shielding specifications as the inflection signal for qualification pathway acceleration and demand pull-through timing.| Strategic Initiative | Industry Significance |
|---|---|
| Plasma Reactor Scale-Up | Expands qualified production capacity for European REACH-compliant industrial coating grades. |
| Backward Integration into Boron Feedstock | Secures isotopically enriched supply against nuclear industry demand cycle volatility. |
| Proprietary Functionalization Chemistry | Locks differentiated grafting compatibility for epoxy and ceramic matrix composite formulators. |
| Direct Sales Channel Expansion | Bypasses distributor intermediaries to capture margin in Japanese semiconductor packaging clusters. |
| JIS Standardization Committee Engagement | Accelerates qualification pathways for METI-funded lunar habitat radiation shielding applications. |
Study Parameters
Coverage spans North America, Europe, and Asia-Pacific, with primary inputs from each region combining structured interviews with plasma-torch synthesis operators, defense procurement officers, semiconductor packaging engineers, and REACH-authorized coating formulators with secondary validation. Trade data from USITC and Eurostat, ECHA substance authorization filings, METI consortium disclosures, and JIS standardization committee records anchored supply-side assessment. Bottom-up capacity modeling and top-down demand segmentation triangulated volume and value estimates.
Rate-of-change decomposition separated volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include product type tier, application extremity envelope, end-user procurement pattern, and regional regulatory cluster. CAGRs derived from fitted growth curves applied to qualified capacity expansion timelines and program-based demand pull-through from hypersonic vehicle and semiconductor packaging roadmaps. Forecast inputs incorporated plasma reactor throughput assumptions, boron feedstock cost trajectories, and defense qualification queue lengths.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to ITAR licensing friction, REACH authorization timeline slippage, and plasma physics PhD pipeline constraints. Forecasts reflect documented assumptions on capacity ramp schedules, program milestone dates, and regulatory harmonization progress. A small set of named triggers—including JIS standardization outputs, ECHA extended dossier rulings, and hypersonic vehicle program funding adjustments—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Titanium Dioxide Nanomaterials Market
Nanomaterials
Single-Walled Carbon Nanotube (SWCNT) Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Nanoparticle Analysis Market
Nanomaterials
Global Nanoclay Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Polymeric Nanoparticles Market
Nanomaterials
Nanoparticle Titanium Dioxide (Tio2) Market
Nanomaterials
Platinum Nanoparticles Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nanomaterials Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market
Nanomaterials
Nanotubes Market