
 Nanomaterials Market | 2026-2036
Nanomaterials Market Size, Share, and Industry Trends Forecast 2026-2036
Nanomaterials Market Intelligence
Chinese state-backed material science institutes is decoupling from Western precursor supply for carbon nanotube production. BASF SE anchors European specialty nanoparticle output through integrated R&D centers in Ludwigshafen. Evonik Industries AG differentiates via aerosol-based silica manufacturing for tire and coating applications. Cabot Corporation dominates conductive additive supply for lithium-ion battery cathodes across Asia-Pacific manufacturing zones.
Nanomaterials are engineered structures with at least one dimension between 1 and 100 nanometers, typically synthesized through chemical vapor deposition or sol-gel processing to achieve surface-area-to-volume ratios exceeding conventional bulk materials by orders of magnitude. Their primary commercial purpose centers on manipulating optical, electrical, mechanical, or thermal properties at atomic and molecular scales for performance-critical applications. Carbon nanotubes lead product type revenue due to established conductivity demand from energy storage and electronics manufacturing, while quantum dots represent the fastest-expanding category as display manufacturers replace organic phosphors with cadmium-free alternatives. Bottom-up synthesis commands the technology segment's margin pool because atomic-layer precision reduces defect rates in semiconductor and pharmaceutical applications compared to mechanical top-down fabrication.
EPA oversees pre-manufacture notification requirements under TSCA Section 5 for nano-scale substances entering US commerce, while REACH mandates registration and hazard data for nanomaterials produced or imported above one ton annually in Europe. China's SAMR enforces GB standards for nano-product labeling and workplace exposure limits, creating divergent compliance architectures that fragment market access protocols. ISO technical committees are harmonizing measurement and characterization methodologies, though jurisdictional gaps in toxicity assessment frameworks persist. Stakeholders must monitor evolving registration thresholds and testing cost burdens as regulatory science outpaces standardized risk evaluation protocols.
Market Dynamics
Semiconductor miniaturization below 3nm nodes is forcing manufacturers to adopt atomic-precision nanomaterials for interconnect and gate structures, tightening specifications across the entire supply chain.
Growth Catalysts
- TSCA Section 5 notification:EPA's streamlined pre-manufacture review for nano-scale substances is accelerating US commercialization timelines for carbon nanotube producers.
- Lithium-ion cathode conductivity:Battery manufacturers in China and South Korea are embedding carbon nanotube networks to reduce internal resistance and enable fast-charging architectures.
- Sol-gel processing:Advances in wet-chemical synthesis are lowering capital barriers for quantum dot production, expanding supplier entry across specialized chemical firms.
Market Restraints
- Precursor supply concentration:High-purity acetylene and metal-organic feedstocks cluster in Gulf Coast petrochemical corridors, exposing producers to hurricane-disruption risk.
- REACH registration thresholds:ECHA's one-ton annual volume trigger forces SMEs to absorb disproportionate toxicity testing costs, consolidating market access among larger registrants.
- Mechanical top-down limits:Ball-milling and lithography approaches cannot achieve the defect densities required for sub-5nm semiconductor features, constraining legacy equipment utilization.
Strategic Opportunities
- India PLI scheme:Production-linked incentives for advanced chemistry cell manufacturing are attracting nanomaterial suppliers to Gujarat and Tamil Nadu battery clusters.
- Cadmium-free quantum dots:Display OEMs are qualifying indium phosphide alternatives to satisfy EU RoHS restrictions, opening formulation partnerships with specialty phosphor houses.
- ISO/TS 80004 harmonization:Emerging consensus on nanomaterial terminology and measurement is reducing cross-border certification friction for multi-jurisdictional suppliers.
Industry Challenges
- Atomic-layer deposition expertise:The scarcity of technicians trained in ALD reactor operation and precursor handling is extending commissioning timelines for new fabrication facilities.
- Cross-jurisdictional dossier alignment:Divergent data requirements between EPA's TSCA and ECHA's REACH are forcing manufacturers to maintain parallel toxicology studies, inflating compliance overhead.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanomaterials Market |
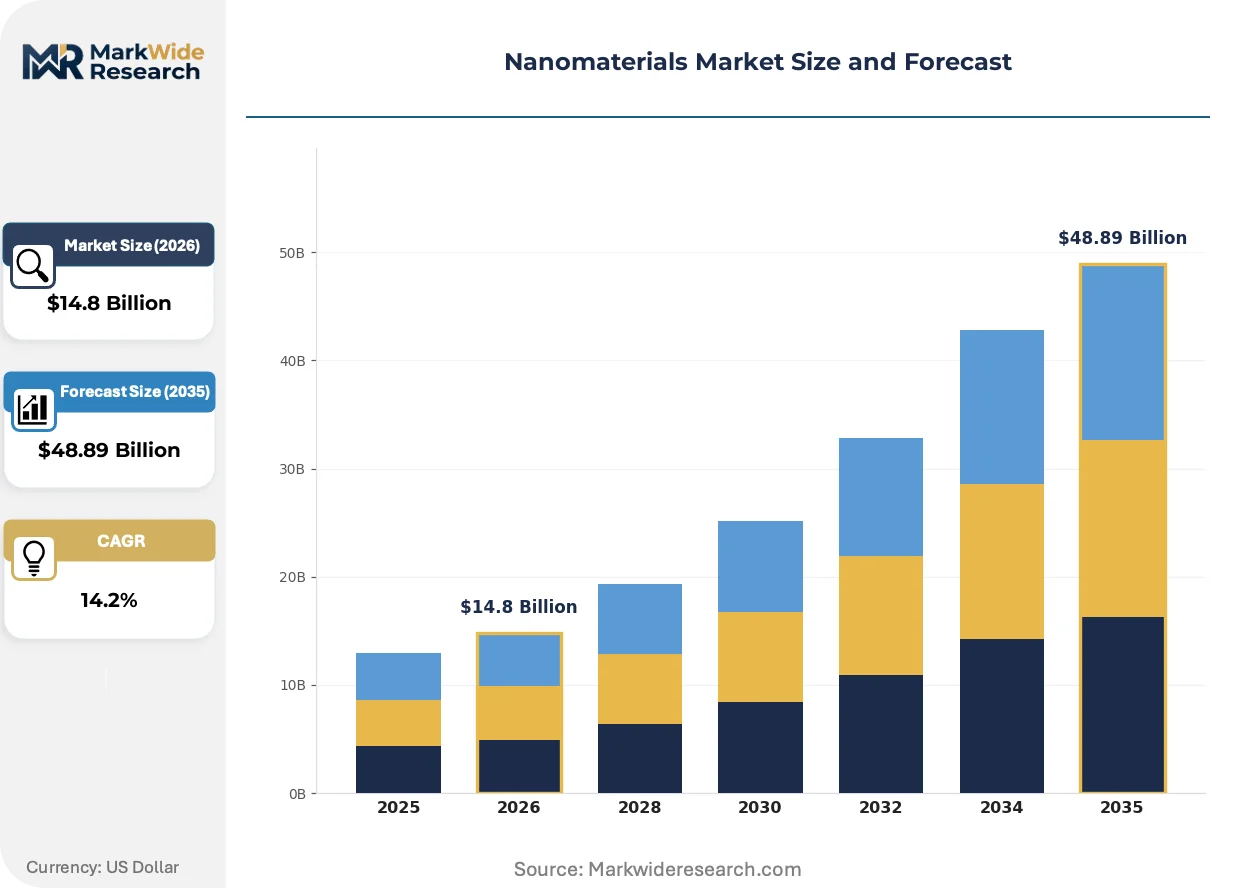
| Market Size in 2026 | $14.8 Billion |
| Market Size in 2035 | $48.89 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Carbon Nanotubes, Quantum Dots, Fullerenes, Nanowires, Nanoparticles Technology: Bottom-Up Synthesis, Top-Down Fabrication, Chemical Vapor Deposition, Sol-Gel Processing, Electrospinning Application: Electronics, Energy Storage, Cosmetics, Food Packaging, Environmental Remediation End User Industry: Electronics Manufacturing, Pharmaceuticals, Aerospace, Agriculture, Construction |
| Companies Covered | American Elements, Nanophase Technologies Corporation, Arkema Group, Cabot Corporation, BASF SE, OCSiAl, SkySpring Nanomaterials, Inc., Advanced Nano Products Corporation, Evonik Industries AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanomaterials Market Strategic Shifts & Innovations
Atomic-precision manufacturing techniques are compressing defect tolerances while regulatory fragmentation forces parallel compliance investments across major commercial zones.
Aerosol-based silica synthesis is expanding into tire and coating applications as manufacturers seek to replace precipitated silica with higher surface-area alternatives. Automotive OEMs in Germany and Japan are qualifying these materials for rolling resistance reduction in premium tire lines. The shift is expanding into battery separator coatings, where controlled porosity enhances ion transport without mechanical degradation.
REACH is tightening hazard data requirements for nanomaterials produced or imported above registration thresholds, forcing registrants to submit expanded physico-chemical and ecotoxicological dossiers. Specialty chemical firms are consolidating registration responsibilities through Only Representative structures to manage cost exposure. Battery and electronics sectors face the steepest compliance burden due to high-volume carbon nanotube and metal oxide utilization.
Direct procurement from material science institutes is displacing traditional distributor channels for carbon nanotube supply in China. State-backed research centers in Beijing and Suzhou are establishing captive production lines, bypassing Western precursor suppliers entirely. This pattern concentrates most visible in energy storage verticals, where domestic battery manufacturers prioritize supply security over incumbent supplier relationships.
Nanomaterials Market Segmentation
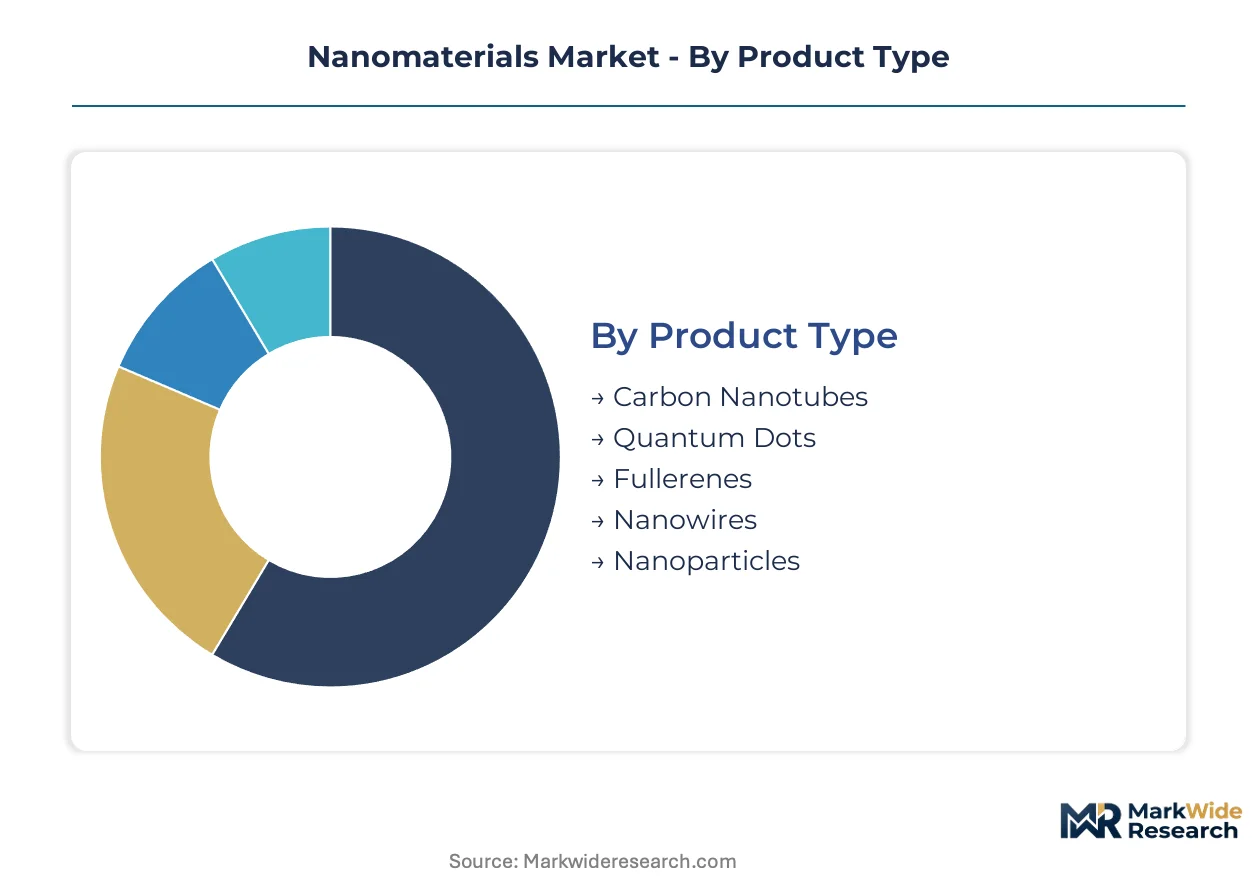
Segmentation in nanomaterials reveals how regulatory thresholds and application-specific certification requirements fragment commercial pathways. Each dimension carries distinct compliance architectures that determine viable supplier participation.
Product Type:
Certification burden varies sharply across product categories, with carbon nanotubes and quantum dots facing the most stringent REACH and EPA pre-manufacture notification requirements due to volume thresholds and novel substance classifications.
- Carbon Nanotubes:Hollow cylindrical carbon structures with exceptional tensile strength and electrical conductivity. Battery manufacturers in China and South Korea embed these networks into lithium-ion cathodes to enable fast-charging architectures. TSCA Section 5 notification requirements in the US and REACH registration above one ton annually impose the heaviest compliance overhead on producers.
- Quantum Dots:Semiconductor nanocrystals exhibiting size-tunable optical properties through quantum confinement effects. Display OEMs in Japan and South Korea are qualifying cadmium-free indium phosphide variants to satisfy EU RoHS restrictions. ECHA's expanded physico-chemical dossier demands for nanomaterials disproportionately burden this segment given its emerging volume trajectory.
- Fullerenes:Spherical carbon allotropes with cage-like structures used in targeted drug delivery and antioxidant applications. Pharmaceutical developers in Switzerland and Japan pursue clinical approvals under national health authority frameworks.
- Nanowires:One-dimensional structures with high aspect ratios serving as interconnects in sub-3nm semiconductor nodes. Taiwan and South Korean foundries drive specification tightening for atomic-precision gate structures.
- Nanoparticles:Zero-dimensional materials including metal oxides and ceramics deployed across coatings, catalysts, and sunscreens. SAMR's GB standards for nano-product labeling in China create distinct packaging and documentation requirements separate from Western protocols.
Carbon nanotubes sit at the top of the volume ranking, with quantum dots climbing the fastest.
Technology:
Cost tier stratification separates capital-intensive atomic-precision methods from accessible wet-chemical routes, determining which supplier categories can enter each production segment.
- Bottom-Up Synthesis:Atomic-layer construction from molecular precursors enabling defect densities below 10^10 per square centimeter. Semiconductor foundries in Taiwan and Intel's Arizona facilities command premium pricing for this precision tier. The scarcity of ALD reactor technicians extends commissioning timelines and concentrates margin capture among established equipment operators.
- Chemical Vapor Deposition:Gas-phase precursor decomposition producing high-purity carbon nanotubes and graphene films. Energy storage suppliers in China's Suzhou cluster leverage CVD for battery-grade conductive additive production. Precursor supply concentration along the US Gulf Coast exposes producers to hurricane-disruption risk.
- Sol-Gel Processing:Wet-chemical hydrolysis and condensation forming metal oxide nanoparticles and quantum dots. Specialty chemical firms in Germany and India exploit lower capital barriers to expand quantum dot supply for display phosphor replacement.
- Top-Down Fabrication:Mechanical ball-milling and lithographic reduction of bulk materials. Legacy equipment cannot achieve defect densities required for sub-5nm semiconductor features, constraining utilization to coarse filtration and structural reinforcement applications.
- Electrospinning:Electric-field-driven fiber formation producing nanofiber membranes for filtration and tissue scaffolding. Medical device manufacturers in Massachusetts and Bavaria qualify these structures under FDA and MDR biocompatibility pathways.
Bottom-up synthesis commands the highest margin tier, with sol-gel processing expanding most quickly among new entrants.
Application:
Customer type fragmentation separates performance-critical specifications in electronics from cost-sensitive deployment in packaging and remediation.
- Electronics:Interconnects, gate dielectrics, and quantum dot displays requiring atomic-scale precision. Taiwan Semiconductor Manufacturing and Samsung Foundry enforce specifications below 3nm nodes. REACH and TSCA notification requirements apply differentially based on import volume and substance novelty.
- Energy Storage:Carbon nanotube conductive networks and silicon nanowire anodes for lithium-ion and solid-state batteries. CATL in Ningbo and LG Energy Solution in South Korea drive cathode additive specifications. India's PLI scheme for advanced chemistry cells is attracting nanomaterial suppliers to Gujarat clusters.
- Cosmetics:Titanium dioxide and zinc oxide nanoparticles for UV protection in sunscreens. ANSM in France and FDA in the US maintain divergent safety assessment protocols for dermal exposure.
- Food Packaging:Silver and clay nanoparticles for antimicrobial barrier properties. EFSA evaluations and FDA food contact notifications create parallel approval tracks for European and North American market access.
- Environmental Remediation:Iron nanoparticles for groundwater dechlorination and photocatalytic titanium dioxide for air purification. US EPA's Office of Research and Development and China's MEE administer distinct field deployment permitting.
Electronics dominates the value concentration, with energy storage gaining share fastest.
End User Industry:
Geography of demand determines which regulatory frameworks suppliers must navigate, with electronics manufacturing and pharmaceuticals facing the most multi-jurisdictional compliance exposure.
- Electronics Manufacturing:Semiconductor fabrication, display assembly, and printed circuit board production. Taiwan, South Korea, and China's Yangtze River Delta concentrate the highest specification demand. ISO/TS 80004 harmonization efforts are reducing cross-border certification friction for multi-jurisdictional suppliers.
- Pharmaceuticals:Targeted drug delivery, imaging agents, and therapeutic formulations. FDA's nanotechnology guidance and EMA's reflection papers on nanomedicines create divergent clinical trial and manufacturing standards.
- Aerospace:Lightweight structural composites and thermal management coatings. Boeing in Washington and Airbus in Toulouse qualify materials under FAA and EASA airworthiness pathways.
- Agriculture:Nanopesticides, nutrient delivery systems, and soil sensors. EPA's Federal Insecticide, Fungicide, and Rodenticide Act and PMRA in Canada impose distinct registration requirements for nano-scale agrochemicals.
- Construction:Self-cleaning concrete, insulating aerogels, and reinforced composites. BIS in India and JIS in Japan maintain separate standards for nano-enabled building material performance claims.
Electronics manufacturing leads end-use value capture, with pharmaceuticals showing the steepest expansion trajectory.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regulatory arbitrage is redirecting nanomaterial production toward jurisdictions where compliance cost differentials outweigh logistics penalties. Manufacturers are relocating carbon nanotube and quantum dot synthesis to regions with streamlined chemical notification pathways and state-backed facility subsidies.
United States
EPA's TSCA Section 5 pre-manufacture notification streamlines commercialization for carbon nanotube producers targeting battery and electronics verticals. The Gulf Coast petrochemical corridor concentrates high-purity acetylene precursor supply, though hurricane exposure creates periodic disruption risk for CVD-dependent operations. Texas and Louisiana host the dominant domestic production clusters for conductive additive manufacturing.
China
State-backed material science institutes in Beijing and Suzhou are establishing captive carbon nanotube production lines, displacing Western precursor suppliers entirely. SAMR enforces GB standards for nano-product labeling and workplace exposure limits, creating distinct compliance architectures from Western protocols. The Yangtze River Delta battery manufacturing belt drives concentrated demand for domestic conductive additive supply.
Germany
REACH registration thresholds above one ton annually force specialty chemical firms to consolidate responsibilities through Only Representative structures. BASF SE anchors European nanoparticle output through integrated R&D centers in Ludwigshafen. The country's automotive OEMs are qualifying aerosol-based silica for premium tire rolling resistance reduction.
South Korea
Samsung Foundry and LG Energy Solution enforce atomic-precision specifications for sub-3nm semiconductor interconnects and fast-charging battery cathodes. MFDS maintains distinct nanomedicine evaluation pathways separate from FDA or EMA frameworks. The Seoul Capital Area concentrates display manufacturing demand for cadmium-free quantum dot phosphor alternatives.
India
The PLI scheme for advanced chemistry cell manufacturing is attracting nanomaterial suppliers to Gujarat and Tamil Nadu battery clusters. BIS maintains separate standards for nano-enabled building material performance claims in construction applications. Domestic pharmaceutical developers pursue targeted drug delivery approvals under CDSCO frameworks for fullerene-based therapeutic formulations.
Nanomaterials Market Key Industry Players
Chinese state-backed producers anchor one tier; European specialty chemical specialists hold differentiated positions in regulated premium segments. The vendor base stratifies across integrated conglomerates with captive R&D infrastructure, independent technology licensors, and regional distributors facing consolidation pressure. Two archetypes dominate: atomic-precision foundry operators commanding semiconductor-grade premiums, and commodity-scale CVD producers competing on cathode additive volumes. Competitive moves center on backward integration into precursor supply and geographic expansion via joint ventures in battery manufacturing clusters.
Within the integrated chemical conglomerate tier, BASF SE and Evonik Industries AG exemplify European registrants leveraging REACH consolidation to manage compliance overhead. Cabot Corporation occupies a position among Asia-Pacific conductive additive suppliers serving lithium-ion battery cathode manufacturers. These three entities represent distinct strategic postures: Ludwigshafen-anchored R&D integration, aerosol-based silica specialization, and Asia-Pacific manufacturing zone dominance.
| Leading Market Players |
|---|
| American Elements |
| Nanophase Technologies Corporation |
| Arkema Group |
| Cabot Corporation |
| BASF SE |
| OCSiAl |
| SkySpring Nanomaterials, Inc. |
| Advanced Nano Products Corporation |
| Evonik Industries AG |
| Others |
Cost & Logistics Intelligence
High-purity acetylene spot indices on the US Gulf Coast cascade through carbon nanotube production economics, compressing margins for CVD-dependent suppliers while amplifying pricing power for integrated precursor producers in Ludwigshafen and Beijing.
Pricing Analysis
Distributor margins for specialty nanoparticles absorb 15-25 point spreads between CVD reactor output and battery cathode qualification, though direct procurement from Chinese state-backed institutes is collapsing this layer entirely. Three-tier pricing structure across semiconductor-grade, battery-grade, and industrial-grade certification levels separates atomic-precision foundries from commodity-scale suppliers. Cost compression in battery-grade carbon nanotubes is intensifying because CATL and LG Energy Solution are consolidating qualified supplier lists to three per cathode formulation. Electronics manufacturers exhibit the lowest price sensitivity due to defect-density specifications below 10^10 per square centimeter, while construction and environmental remediation buyers negotiate aggressively on volume.
Supply Chain Analysis
ISO/TS 80004 certification and REACH registration dossiers gate market access for European and North American suppliers, creating compliance moats that Chinese state-backed producers bypass through domestic GB standard qualification. Manufacturing concentrates in China, Germany, and the United States, with precursor supply anchored in Gulf Coast petrochemical corridors and acetylene feedstock from Ludwigshafen crackers. Production draws from high-purity metal-organic precursors, specialty gases, and ALD reactor equipment where single-source vulnerability persists for atomic-layer deposition chambers. Tariff exposure on Chinese carbon nanotube imports into the US and EU threatens to reroute supply through South Korean tolling arrangements. Distribution runs through qualified material science institutes in Beijing and Suzhou displacing traditional chemical distributor networks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
REACH registration cost differentials between European specialty chemical firms and Chinese state-backed producers create geographic-arbitrage opportunities for battery-grade nanomaterial supply, with India PLI subsidies offering an emerging intermediate cost structure.
For Market Incumbents: Hedge precursor supply concentration by securing dual-source acetylene contracts from Ludwigshafen crackers and Gulf Coast corridors, while consolidating REACH registration responsibilities through Only Representative structures to defray ECHA toxicity testing burdens. Capacity addition in Gujarat battery clusters under India's PLI scheme captures demand migrating from China-plus-one procurement strategies. For New Entrants and Emerging Players: Sol-gel quantum dot production for cadmium-free display phosphors offers the most penetrable wedge, as South Korean and Japanese OEMs actively qualify indium phosphide alternatives to satisfy EU RoHS restrictions. Target India's advanced chemistry cell manufacturing zones through joint ventures with Tamil Nadu cathode producers, leveraging lower capital barriers in wet-chemical synthesis versus CVD infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with aerosol-based silica specialists serving premium tire OEMs in Germany and Japan, where rolling resistance specifications command persistent margin premiums over precipitated silica alternatives. Atomic-layer deposition equipment operators with captive technician training programs represent the optimal acquisition archetype given commissioning timeline scarcity. Watch for ECHA expansion of nanomaterial registration thresholds as the inflection indicator for compliance-cost consolidation among European registrants.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Precursor Supply | Captures acetylene and metal-organic margin layers from Gulf Coast petrochemical corridors. |
| REACH Only Representative Consolidation | Spreads ECHA toxicity testing costs across multiple registrants via Ludwigshafen-anchored structures. |
| India PLI Joint Venture Formation | Positions suppliers for Gujarat and Tamil Nadu battery cluster demand under subsidized chemistry cell manufacturing. |
| ISO/TS 80004 Certification Investment | Reduces cross-border friction for multi-jurisdictional suppliers serving Taiwan and South Korean foundries. |
| Cadmium-Free Quantum Dot Formulation Partnership | Opens display phosphor replacement opportunities with Samsung and LG under EU RoHS compliance pathways. |
Research Approach
Direct dialogue with CVD reactor operators, battery cathode procurement leads at CATL and LG Energy Solution, specialty chemical distribution channel partners, and ECHA regulatory affairs consultants grounded the qualitative framework, validated against SEC 10-K filings from BASF and Evonik, customs trade data for carbon nanotube imports, ACC and Cefic chemical industry reports, and ISO technical committee documentation. Bottom-up production capacity modeling triangulated with top-down demand aggregation from semiconductor foundry capex disclosures and battery manufacturing expansion announcements.
Segment-level value outputs across the projection horizon reflect disaggregated modeling of product type, synthesis technology, application vertical, and end-use industry dimensions, with CAGRs derived from production volume trajectories and pricing tier movements in semiconductor-grade versus battery-grade material. Forecast inputs incorporated REACH registration threshold evolution, EPA TSCA Section 5 notification timelines, and India PLI scheme disbursement pacing for advanced chemistry cell manufacturing.
The model holds under stable regulatory registration thresholds and continued semiconductor node shrinkage; deviation in ECHA volume trigger adjustments or atomic-precision equipment commissioning delays would shift supply-side capacity assumptions. A model refresh is warranted upon material change in EU nanomaterial hazard data requirements or China SAMR enforcement intensity for nano-product labeling standards.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Nanocomposites Market
Nanomaterials
Nanotechnology Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Nano Copper Oxide Market
Nanomaterials
Global Gold Nanorods Market
Nanomaterials
Nanochemicals Market
Nanomaterials
Nanoparticle Contract Manufacturing Market
Nanomaterials
Asia-Pacific Nanocellulose Materials Market
Nanomaterials
Tungsten Disulphide Nanoparticles Market
Nanomaterials
Nanopesticides Market
Nanomaterials
Graphene Nanocomposites Market
Nanomaterials
Inorganic Nano Porous Adsorbents Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Nanoscale Chemicals Market
Nanomaterials
Copper Nano Powder Market