
 Nanotools Market | 2026-2036
Nanotools Market Size, Share, and Industry Trends Forecast 2026-2036
Nanotools Market Analytics
ISO 14644 cleanroom certification is redrawing competitive boundaries for nanotools suppliers serving semiconductor fabs. Bruker Corporation leverages its installed base of atomic force microscopy systems to sustain aftermarket revenue streams across Asian fabrication corridors. Thermo Fisher Scientific anchors its position through integrated workflows combining electron microscopy with sample preparation automation. Oxford Instruments competes in cryogenic nanomanipulation, a niche where technical differentiation commands premium positioning.
Nanotools encompass precision instruments engineered to manipulate, characterize, or fabricate structures at the nanometer scale, typically operating with positional accuracy below 10 nanometers using piezoelectric actuators or focused charged particle beams. Their primary purpose spans material characterization, device prototyping, and quality control in industries where dimensional tolerances approach atomic dimensions. Scanning electron microscopy platforms generate the largest revenue pool among technology categories due to their ubiquity in failure analysis and process development workflows. Atomic force microscopy systems represent the fastest-expanding segment as pharmaceutical companies adopt them for molecular interaction studies at single-cell resolution. Nano-manipulator product lines command superior margins in biomedical research settings where optical transparency and force feedback precision justify specialized configurations.
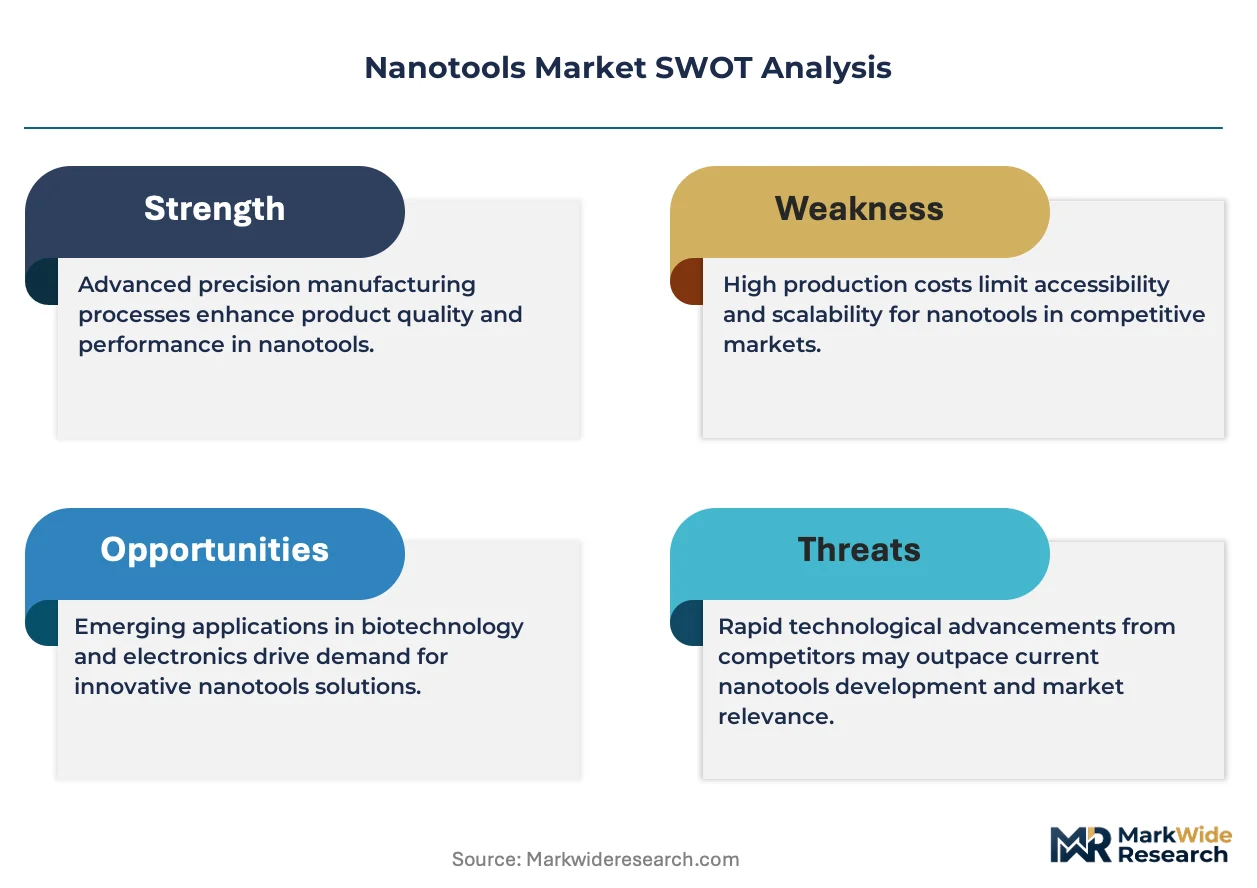
The EPA regulates nanomaterial reporting under TSCA Section 8(a) in the United States, while REACH governs substance registration and restriction across European markets; both frameworks elevate compliance costs but simultaneously filter out uncertified competitors. FDA qualification pathways for nanotools used in medical device manufacturing create additional gating mechanisms that favor established suppliers with documented quality management systems. Stakeholders must monitor evolving export control classifications for dual-use nanofabrication equipment, as geopolitical alignment increasingly determines equipment availability in strategic technology sectors.
Market Dynamics
Sub-3nm semiconductor node development is compressing replacement cycles for nanomanipulation platforms as Taiwan and South Korean fabs demand atomic-scale positional accuracy for gate-all-around transistor architectures.
Growth Catalysts
- REACH substance registration:European nanomaterial qualification protocols are filtering out uncertified competitors and consolidating procurement among qualified suppliers serving medical device manufacturers.
- Gate-all-around transistor prototyping:Semiconductor foundries in Taiwan and South Korea are accelerating focused ion beam system deployment for three-dimensional device characterization.
- Single-cell molecular interaction studies:Pharmaceutical research laboratories are expanding atomic force microscopy adoption for biophysical characterization of therapeutic candidates.
Market Restraints
- Piezoelectric actuator supply concentration:Japanese and German component specialists control precision motion control subassemblies, creating input bottlenecks for system integrators.
- EPA TSCA Section 8(a) reporting burden:Nanomaterial importers face elevated compliance documentation costs that disproportionately burden mid-tier research instrument distributors.
- Optical microscopy substitution:Super-resolution fluorescence techniques are capturing share in live-cell imaging applications where optical transparency outweighs nanometer-scale precision requirements.
Strategic Opportunities
- India's PLI scheme for semiconductor manufacturing:Domestic fabrication incentives are creating greenfield demand for cleanroom-certified nanomanipulation infrastructure in Bengaluru and Gujarat clusters.
- Cryogenic nanomanipulation convergence:Integration of dilution refrigeration with scanning probe systems is opening quantum device prototyping workflows previously inaccessible to commercial platforms.
- ISO 14644 certification services:Third-party cleanroom validation is emerging as a high-margin adjacent revenue stream for established instrumentation suppliers.
Industry Challenges
- Atomic-scale metrology talent scarcity:Fabs and research institutions compete for finite pools of technicians trained in focused charged particle beam operation and vibration isolation protocols.
- Dual-use export control reclassification:Geopolitical alignment requirements are complicating equipment availability assessments for nanofabrication systems with patterning capabilities below 10 nanometers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Nanotools Market |
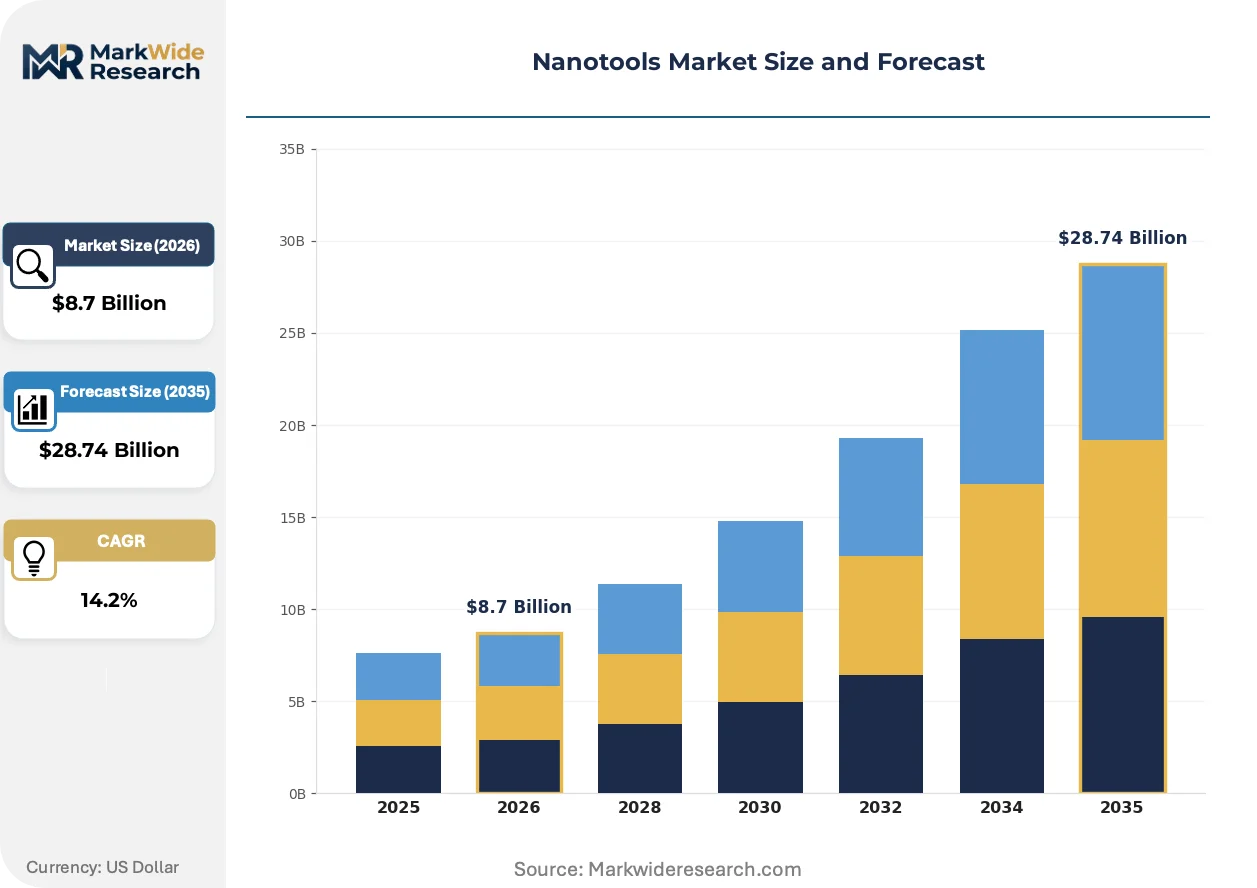
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Nano-Skalpel, Nano-Pincer, Nano-Drill, Nano-Manipulator Application: Biomedical Research, Material Science, Semiconductor Manufacturing, Surface Engineering Technology: Atomic Force Microscopy, Scanning Electron Microscopy, Focused Ion Beam, Dip Pen Nanolithography End User: Research Institutes, Pharmaceutical Companies, Electronics Manufacturers, Academic Laboratories |
| Companies Covered | Bruker Corporation, Thermo Fisher Scientific, Oxford Instruments, Carl Zeiss AG, Heidelberg Instruments, Raith GmbH, Nanonics Imaging Ltd., Park Systems Corp., TESCAN ORSAY HOLDING a.s., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Nanotools Market Evolving Landscape
Workflow automation and environmental control integration are redefining competitive differentiation as buyers prioritize throughput stability over standalone resolution specifications in high-volume process development environments.
Correlative microscopy platforms combining electron beam and scanning probe modalities are miniaturizing vacuum transfer chambers and sample preparation modules. Semiconductor failure analysis laboratories in Taiwan and South Korea are adopting these integrated systems to compress turnaround times for defect localization. This convergence is miniaturizing the footprint and staffing requirements for multi-technique characterization facilities.
REACH restriction candidate list expansion is compelling nanomaterial suppliers to reformulate probe coatings and substrate materials. Industrial consequences include accelerated qualification timelines for replacement chemistries in biomedical research consumables. European pharmaceutical and medical device manufacturers are responding by consolidating supplier relationships with entities possessing documented substitution roadmaps.
Service contract unbundling is fragmenting traditional bundled maintenance agreements into modular offerings covering hardware, software, and application support separately. Asian fabrication clusters are driving this shift as foundries internalize routine calibration protocols while outsourcing specialized repair functions. This pattern is most pronounced in Taiwan where leading-edge fabs operate captive metrology teams alongside vendor-provided escalation support.
Nanotools Market Segmentation
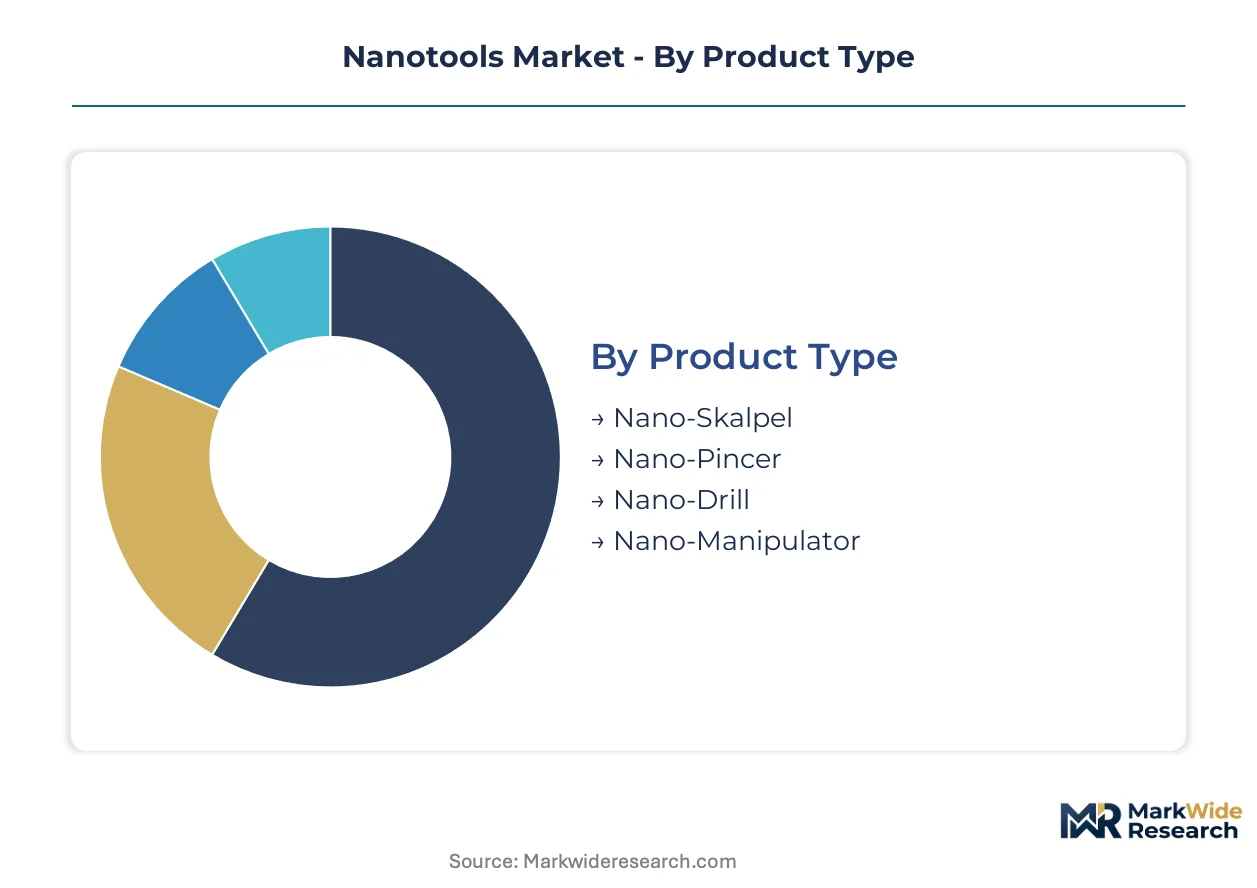
Nanotools procurement patterns diverge sharply across technical specifications, with regulatory frameworks in Europe and East Asia filtering supplier eligibility by product category. Segment-specific qualification requirements from ECHA and Taiwan's Industrial Development Bureau compress vendor pools for high-precision instrumentation.
Product Type:
REACH substance registration and ISO 14644 cleanroom certification create divergent compliance burdens across product categories, favoring suppliers with documented substitution roadmaps for probe materials.
- Nano-Manipulator:Piezoelectric actuator arrays deliver sub-nanometer positional accuracy for gate-all-around transistor prototyping in Hsinchu and Suwon fabrication corridors. South Korean foundries compress replacement cycles as sub-3nm node development demands atomic-scale precision for three-dimensional device characterization. Established volume favors nano-manipulator; emerging adoption favors nano-skalpel.
- Scanning Electron Microscopy:Electron beam columns with aberration correction enable failure analysis workflows at Taiwan Semiconductor Manufacturing Company and Samsung Electronics process development labs. Revenue concentration reflects ubiquity in defect localization and cross-sectional imaging for advanced packaging architectures. This segment commands the largest installed base among precision nanotools.
- Nano-Skalpel:Focused ion beam sources enable site-specific material removal for transmission electron microscopy sample preparation in biomedical research settings.
- Nano-Pincer:Optical tweezer-integrated force feedback systems support single-cell manipulation in pharmaceutical screening workflows.
- Nano-Drill:Ultrasonic piezoelectric drivers create high-aspect-ratio features in brittle substrates for MEMS fabrication.
Cost tier differentiation separates capital-intensive nano-manipulator deployments from consumables-driven nano-skalpel adoption in distributed research networks.
Application:
Application selection correlates with customer scale, where semiconductor manufacturers internalize metrology teams while biomedical researchers rely on shared facility access.
- Semiconductor Manufacturing:Gate-all-around transistor development in Taiwan and South Korea drives focused ion beam system procurement for three-dimensional characterization workflows. Atomic-scale positional requirements compress equipment replacement cycles as foundries migrate from finFET to nanosheet architectures. This application absorbs the highest capital expenditure per installation.
- Biomedical Research:Single-cell molecular interaction studies at pharmaceutical laboratories in Basel and Cambridge expand atomic force microscopy adoption for biophysical characterization of therapeutic candidates. FDA qualification pathways for nanotools used in medical device manufacturing favor established suppliers with documented quality management systems. Biomedical research represents the steepest expansion trajectory among application segments.
- Material Science:Correlative microscopy platforms combine electron beam and scanning probe modalities for multi-scale structure-property mapping.
- Surface Engineering:Dip pen nanolithography enables functionalization of implantable device coatings with nanometer-scale feature control.
Volume concentrates in semiconductor manufacturing; margin expansion favors biomedical research where specialized configurations justify premium positioning.
Technology:
Technology selection reflects resolution-throughput tradeoffs, with semiconductor fabs prioritizing automation stability over standalone specifications.
- Scanning Electron Microscopy:Schottky field emission sources deliver sub-nanometer resolution for failure analysis laboratories in Hsinchu and Yongin. Environmental control integration and workflow automation redefine competitive differentiation as buyers prioritize throughput stability in high-volume process development. This technology generates the largest revenue pool among nanotools categories.
- Atomic Force Microscopy:Cantilever arrays with photodiode detection enable single-molecule force spectroscopy for pharmaceutical target validation. Basel-based Roche and Cambridge-based AstraZeneca expand biophysical characterization capabilities for therapeutic candidate screening. Atomic force microscopy is gaining share fastest in life science applications.
- Focused Ion Beam:Gallium liquid metal ion sources enable site-specific milling for transmission electron microscopy sample preparation.
- Dip Pen Nanolithography:Ink-coated atomic force microscopy tips deposit molecular patterns for biosensor functionalization.
Maturity favors scanning electron microscopy; technology convergence favors integrated correlative platforms combining multiple modalities.
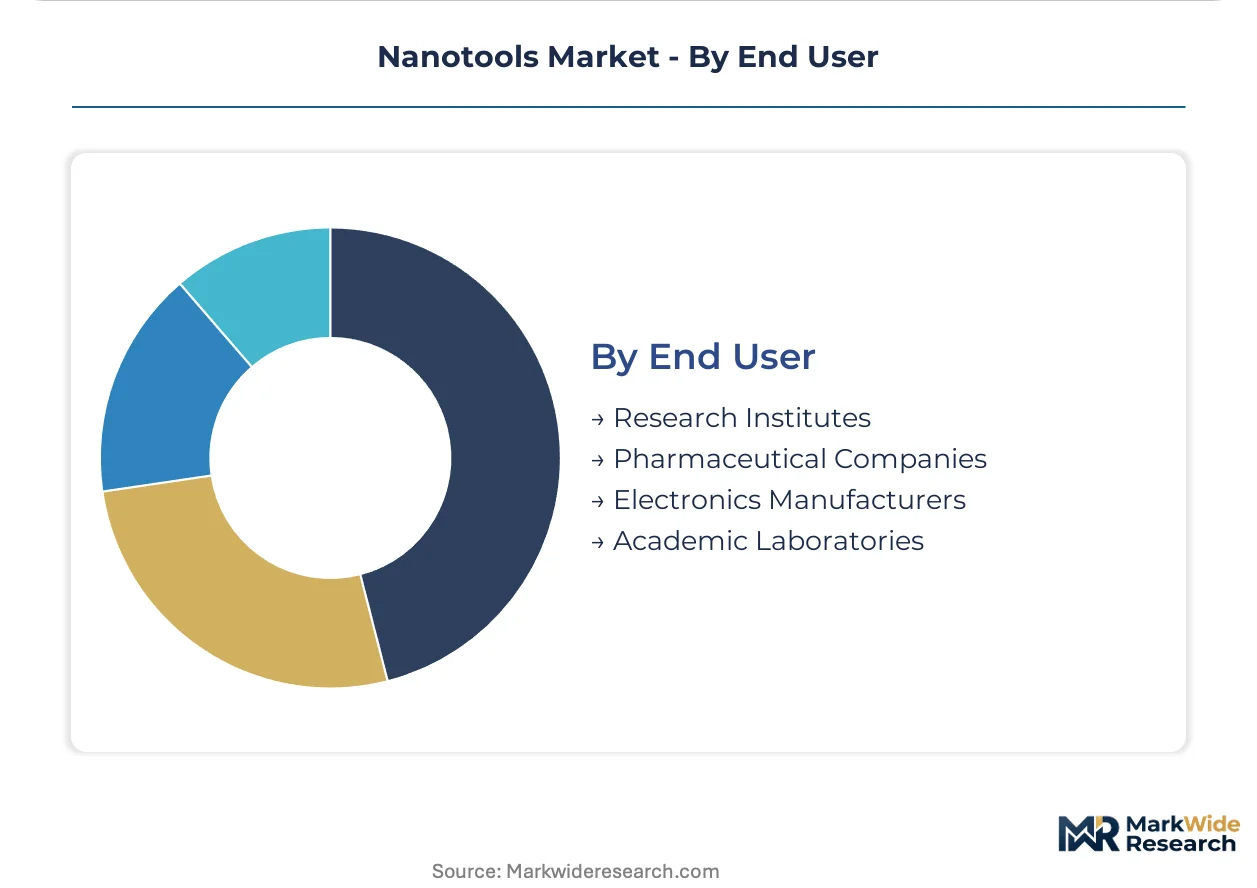
End User:
End user type determines procurement centralization, with electronics manufacturers operating captive metrology teams and academic laboratories accessing shared core facilities.
- Electronics Manufacturers:Taiwan Semiconductor Manufacturing Company and Samsung Electronics operate internal failure analysis laboratories with dedicated focused ion beam and scanning electron microscopy infrastructure. Service contract unbundling fragments traditional bundled maintenance agreements as foundries internalize routine calibration protocols. This end user category deploys the highest equipment density per facility.
- Pharmaceutical Companies:Roche in Basel and Novartis in Cambridge consolidate atomic force microscopy procurement for biophysical characterization of antibody-drug conjugates. REACH restriction candidate list expansion compels reformulation of probe coatings and substrate materials, accelerating qualification timelines for replacement chemistries. Pharmaceutical procurement is climbing the fastest among end user segments.
- Research Institutes:Max Planck Society and CEA operate multi-technique characterization facilities with shared access models.
- Academic Laboratories:University core facilities in Oxford and Zurich provide subsidized access to scanning probe systems for principal investigator research programs.
Procurement scale favors electronics manufacturers; pricing flexibility favors academic laboratories with institutional purchasing consortia.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Kaohsiung-Taichung semiconductor corridor underwrites Taiwan's dominance in advanced nanomanipulation procurement, while South Korea's KTX high-speed rail network connects Suwon and Yongin fabrication clusters to Seoul's research infrastructure.
Taiwan
Hsinchu Science Park fabs drive focused ion beam system deployment for sub-3nm gate-all-around transistor development. The Industrial Development Bureau enforces ISO 14644 cleanroom certification for nanotools suppliers serving domestic foundries. Kaohsiung-based packaging houses are expanding correlative microscopy infrastructure for advanced interconnect characterization.
South Korea
Samsung Electronics and SK Hynix compress equipment replacement cycles as nanosheet architectures demand atomic-scale positional accuracy. The Ministry of Trade, Industry and Energy coordinates national nanofabrication roadmaps through the K-Nano initiative. Yongin semiconductor complexes anchor procurement for aberration-corrected electron microscopy platforms.
United States
Pharmaceutical laboratories in Cambridge and Basel expand atomic force microscopy adoption for biophysical characterization workflows. The EPA enforces TSCA Section 8(a) nanomaterial reporting requirements that elevate compliance documentation burdens for research instrument distributors. Greater Boston's biotech corridor concentrates demand for single-cell manipulation platforms.
Germany
Max Planck Society institutes and Fraunhofer centers operate multi-technique characterization facilities with shared access models. ECHA REACH substance registration protocols filter uncertified competitors from European nanomaterial supply chains. Munich and Stuttgart industrial clusters sustain demand for precision motion control subassemblies.
India
The PLI scheme for semiconductor manufacturing creates greenfield demand for cleanroom-certified nanomanipulation infrastructure. BIS certification requirements shape procurement protocols for imported precision instrumentation. Bengaluru and Gujarat fabrication clusters are emerging as focal points for focused ion beam system deployment.
Nanotools Market Competitive Landscape
Listed leaders compete with private specialists across capital intensity tiers, with publicly traded instrumentation conglomerates commanding installed base advantages while private specialists capture niche premium positioning. The vendor landscape stratifies into three tiers: diversified conglomerates with aftermarket service networks, mid-scale specialists with regional fabrication corridor presence, and boutique providers serving biomedical research niches. Dominant competitive moves include portfolio diversification into adjacent workflow automation and strategic partnerships with foundry operators for co-development of process-specific configurations.
Within the diversified instrumentation tier, Bruker Corporation and Thermo Fisher Scientific exemplify archetypes leveraging installed base scale to sustain aftermarket revenue streams. Oxford Instruments occupies a position among specialized providers where cryogenic nanomanipulation capabilities command premium positioning in quantum device prototyping workflows. These three entities collectively represent the competitive spectrum spanning conglomerate breadth to technical specialization depth.
| Leading Market Players |
|---|
| Bruker Corporation |
| Thermo Fisher Scientific |
| Oxford Instruments |
| Carl Zeiss AG |
| Heidelberg Instruments |
| Raith GmbH |
| Nanonics Imaging Ltd. |
| Park Systems Corp. |
| TESCAN ORSAY HOLDING a.s. |
| Others |
Value Network & Pricing Analysis
Long-term service contracts with bundled calibration protocols lock in supply access for semiconductor foundries while fixing visibility into aftermarket revenue streams across Asian fabrication corridors. Taiwan's Industrial Development Bureau and South Korea's K-Nano initiative reinforce this structure by mandating ISO 14644 certification as a procurement gate, embedding compliance costs into multi-year agreements.
Pricing Analysis
Three-tier pricing structure across premium, standard, and economy levels separates aberration-corrected electron microscopy platforms from entry-level scanning probe systems and refurbished legacy units. Certification grade and volume scale drive differentiation, with cleanroom-qualified configurations commanding substantial premiums over laboratory-grade alternatives. Cost compression in the standard tier is intensifying because Japanese and German piezoelectric actuator suppliers exercise pricing power over precision motion subassemblies. Academic laboratories with institutional purchasing consortia exhibit the highest price sensitivity, while Taiwan Semiconductor Manufacturing Company and Samsung Electronics prioritize throughput stability over unit economics.
Supply Chain Analysis
Container availability constraints on the Rotterdam-Singapore trade lane elevate inbound logistics costs for European nanotools suppliers serving Asian fabrication clusters. Precision motion control subassemblies concentrate in Japan and Germany, electron beam columns draw from specialized German and Dutch manufacturers, and gallium liquid metal ion sources rest on South Korean and American suppliers. Single-source vulnerability pervades the piezoelectric actuator segment, where Murata and Physik Instrumente control critical production capacity. Distribution runs through direct sales forces for electronics manufacturers alongside regional distributors serving pharmaceutical and academic end users.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The acute shortage of technicians trained in focused charged particle beam operation and vibration isolation protocols constrains fab expansion timelines and inflates compensation costs for qualified personnel. This capability gap favors incumbents with captive training programs and documented workforce development pipelines.
For Market Incumbents: Compound aftermarket revenue through unbundled service contracts that separate hardware maintenance from software support and application consulting. Defend position by deepening backward integration into precision motion control subassemblies to reduce exposure to Japanese and German component bottlenecks. Invest in ISO 14644 certification services as a high-margin adjacent stream, leveraging existing customer relationships in Taiwan and South Korea. For New Entrants and Emerging Players: Anchor in India's PLI scheme for semiconductor manufacturing, where greenfield fabrication clusters in Bengaluru and Gujarat lack established supplier relationships. Cryogenic nanomanipulation for quantum device prototyping represents the most penetrable niche, with technical differentiation commanding premium positioning absent from saturated electron microscopy segments. Pursue co-development partnerships with domestic foundry operators to embed process-specific configurations before incumbent lock-in solidifies. For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among diversified instrumentation conglomerates with installed base scale across Asian fabrication corridors, where service contract unbundling fragments traditional bundled agreements into modular offerings. Long-term viability hinges on exposure to sub-3nm semiconductor node development and gate-all-around transistor architectures, which compress replacement cycles and sustain capital expenditure intensity. Target acquisition profiles should emphasize entities with documented substitution roadmaps for REACH-compliant probe materials. The signal to watch is export control reclassification for dual-use nanofabrication equipment, which would abruptly reshape equipment availability assessments and geographic demand distribution.| Strategic Initiative | Industry Significance |
|---|---|
| Workflow Automation Integration | Taiwan Semiconductor Manufacturing Company prioritizes throughput stability over standalone resolution specifications in process development. |
| REACH-Compliant Material Substitution | ECHA restriction candidate list expansion compels reformulation of probe coatings and substrate materials for European medical device manufacturers. |
| Cryogenic Platform Convergence | Integration of dilution refrigeration with scanning probe systems opens quantum device prototyping workflows previously inaccessible to commercial platforms. |
| Service Contract Unbundling | Asian fabrication clusters fragment traditional bundled maintenance agreements into modular offerings covering hardware, software, and application support separately. |
| Cleanroom Certification Services | Third-party ISO 14644 validation emerges as high-margin adjacent revenue stream leveraging existing instrumentation supplier relationships. |
Research Methodology
Two parallel data streams informed the analysis: structured primary interviews with semiconductor failure analysis directors, pharmaceutical biophysical characterization leads, nanofabrication facility managers, and precision instrumentation procurement officers; alongside secondary validation drawing from EPA TSCA Section 8(a) filings, ECHA REACH registration databases, SEC 10-K equipment supplier disclosures, and Taiwan Industrial Development Bureau certification records. Bottom-up triangulation across equipment shipment data and top-down reconciliation against foundry capital expenditure announcements anchored volume estimates.
Across the analysis window, the forecasting framework modeled technology categories, application segments, end-user types, and regional regulatory clusters to generate segment-specific growth trajectories. CAGRs were derived from replacement cycle compression rates tied to sub-3nm node development and pharmaceutical atomic force microscopy adoption curves. Industry-specific inputs included piezoelectric actuator supply constraints and evolving export control classifications for dual-use nanofabrication equipment.
Decision-makers should treat outputs as directional under assumptions of continued East Asian semiconductor fabrication concentration and stable REACH substance registration protocols; material deviation would warrant model refresh. Specific risks include abrupt dual-use export control reclassification, breakthrough super-resolution optical microscopy displacement, or supply chain disruption in Japanese precision motion control subassemblies. Outcomes outside this envelope would require model recalibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Nanomaterials
Europe Gold Nanoparticle Market
Nanomaterials
Nano Zinc Oxide Market
Nanomaterials
Copper Nano Powder Market
Nanomaterials
Aluminium Oxide Nanoparticles Market
Nanomaterials
Global Nanoemulsion Market
Nanomaterials
Nanocomposites Market
Nanomaterials
Nanocellulose Materials Market
Nanomaterials
Global Nano Metal Oxide Market
Nanomaterials
Nanocatalysts Market
Nanomaterials
Global Nanosilica Market
Nanomaterials
Metal Nitride Nanoparticles Market
Nanomaterials
Nanomaterials for Printing Market
Nanomaterials
Global Nano Silver Market
Nanomaterials
Global Gold Nanoparticles Market
Nanomaterials
Molybdenum Trioxide Nanopowder Market
Nanomaterials
Global Cerium Oxide Nanoparticles Market