
 Global Bioliquid Heat and Power Generation Market | 2026-2036
Global Bioliquid Heat and Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Global Bioliquid Heat and Power Generation Market Intelligence
Adoption of second-generation feedstocks, such as non-food biomass and waste materials, is redrawing the competitive landscape for bioliquid production. This shift favors technology-focused producers over traditional crop-based suppliers. Neste leverages its advanced refining capabilities to produce renewable fuels from waste and residues. Ensyn Fuels specializes in converting non-food solid biomass into its proprietary bio-oil through rapid thermal processing.
Bioliquid heat and power generation involves the combustion of liquid fuels derived from biomass to produce thermal and electrical energy. These systems often utilize technologies like Organic Rankine Cycle or gas engines to provide decentralized energy for various applications. Among fuel types, bio-oil derived from pyrolysis is gaining traction for its transportability and storage advantages. Industrial plants represent a primary end-user segment, employing combined heat and power configurations to improve overall energy efficiency.
Regulatory frameworks are critical in shaping market access and incentives. The European Union's Renewable Energy Directive (RED) sets sustainability criteria, directly influencing feedstock sourcing and processing. In the United States, the EPA's Renewable Fuel Standard program creates obligations for transportation fuel refiners, which supports bioliquid demand. Navigating the evolving sustainability certification requirements and feedstock eligibility rules will be a central challenge for all market participants.
Market Dynamics
The market's central dynamic is the accelerating shift from first-generation feedstocks to second-generation sources like waste oils and non-food biomass. This transition, driven by sustainability mandates and technology advancements in thermal processing, is fundamentally altering supply chain economics and competitive hierarchies.
Growth Catalysts
- Decarbonization Policies:National and regional climate targets, such as those within the EU Green Deal, create direct incentives and mandates for replacing fossil fuels in heat and power generation, positioning bioliquids as a key compliance pathway.
- District Heating Modernization:Demand from district heating operators, especially in Northern Europe, is a significant catalyst as utilities seek flexible, low-carbon fuel sources to modernize aging infrastructure and meet local emissions standards.
- Pyrolysis Bio-oil Advancement:Technical maturation of rapid thermal processing allows for the conversion of diverse solid biomass into energy-dense, transportable bio-oil, overcoming logistical barriers associated with raw biomass.
Market Restraints
- Feedstock Cost Volatility:The price and availability of second-generation feedstocks, including used cooking oil and forestry residues, are subject to significant fluctuations, creating cost uncertainty for bioliquid producers and power generators.
- Regulatory Complexity:Navigating the intricate and evolving sustainability criteria of frameworks like the EU's Renewable Energy Directive (RED) creates compliance burdens and risks for market access, particularly for non-EU producers.
- Substitution from Electrification:In some applications, particularly smaller-scale heating, direct electrification using heat pumps powered by an increasingly green grid presents a viable long-term substitute, limiting bioliquid expansion.
Strategic Opportunities
- Geographic Expansion:Untapped potential exists in biomass-rich regions of Southeast Asia and Latin America, where developing supportive policies for decentralized energy could open significant new markets for heat and power projects.
- Negative-Emissions Power:Pairing bioliquid combustion with carbon capture and storage (CCS) technologies offers a pathway to create bioenergy with carbon capture and storage (BECCS) facilities, providing valuable negative-emissions power.
- Marine and Off-Grid Applications:The transportability of bio-oils creates opportunities to displace diesel in off-grid power generation for remote communities or mining operations, as well as in the maritime sector as a bunker fuel alternative.
Industry Challenges
- Supply Chain Development:Establishing robust, large-scale collection and aggregation networks for diverse, geographically dispersed waste and residue feedstocks presents a significant logistical and operational hurdle for producers.
- Certification and Verification:The process of certifying feedstocks and production pathways against multiple international and national sustainability standards is time-consuming and costly, acting as a barrier to entry.
- Legacy Asset Integration:Retrofitting existing industrial boilers and power plants, originally designed for fossil fuels, to run efficiently and reliably on bioliquids can involve significant capital expenditure and technical compatibility challenges.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Bioliquid Heat and Power Generation Market |
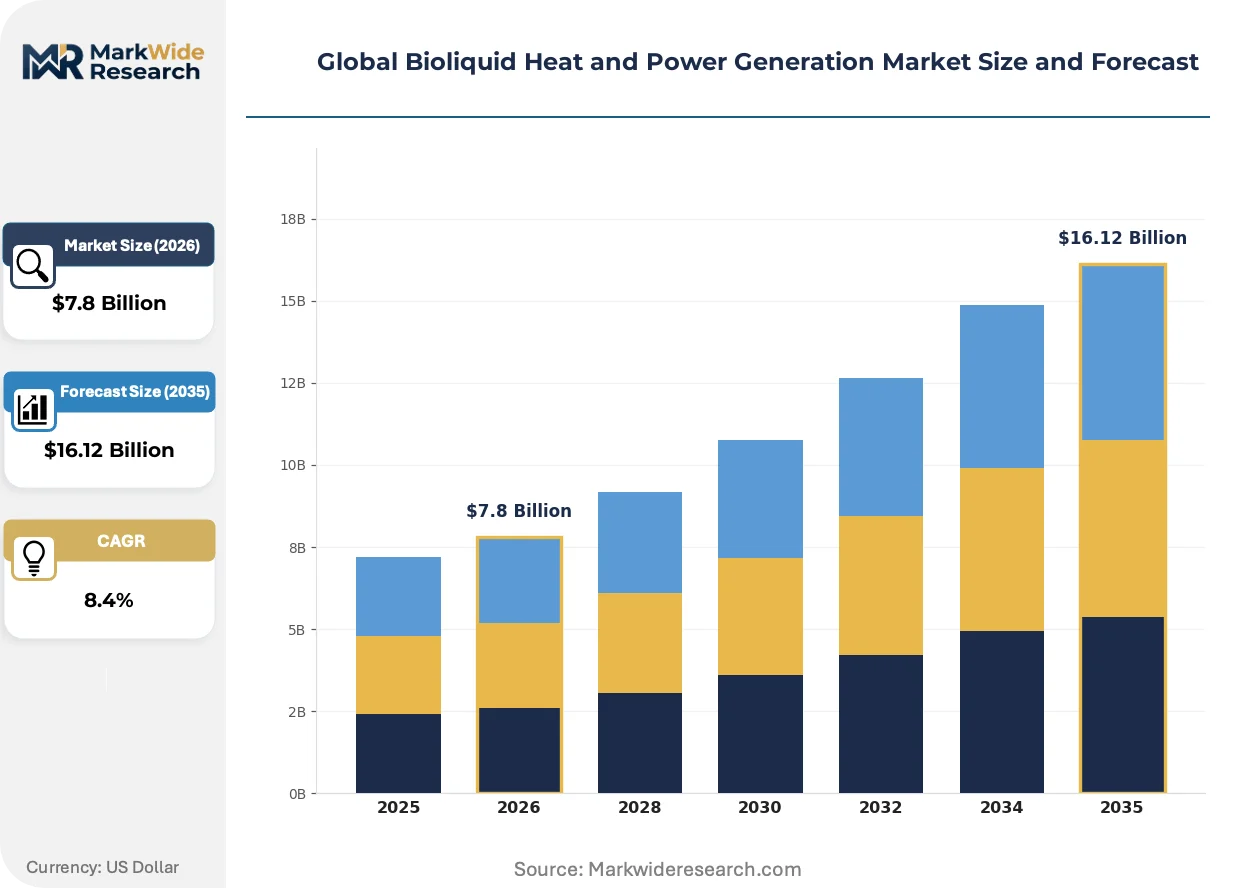
| Market Size in 2026 | $7.8 Billion |
| Market Size in 2035 | $16.12 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: Bioethanol, Biodiesel, Biogas, Biomethanol, Bio-oil Generation Technology: Steam Turbine, Gas Engine, Stirling Engine, Organic Rankine Cycle, Microturbine End User: Power Producers, Industrial Plants, Commercial Facilities, District Heating Operators, Agricultural Estates Distribution Channel: Direct Sales, Energy Traders, Equipment Suppliers, EPC Contractors, Technology Licensors |
| Companies Covered | Ensyn Fuels, Neste, Archer Daniels Midland Company, Albioma SA, REG, Argent Energy, Kraton, MBP Group, BTG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Bioliquid Heat and Power Generation Market Strategic Shifts & Innovations
The market is defined by a technological push towards higher-value fuels from waste and a regulatory pull demanding rigorous proof of sustainability. This dual pressure is professionalizing the industry, favoring producers with advanced processing capabilities and transparent supply chains.
Bio-oil produced via fast pyrolysis is a key product innovation, converting solid biomass into a transportable, liquid energy carrier. Industrial end-users and decentralized power operators are adopting this fuel for its ease of handling and storage. Its logistical advantages and stable combustion properties mean pyrolysis oil is supplanting direct combustion of wood chips and agricultural residues in new combined heat and power installations.
The European Union's Renewable Energy Directive (RED) sets stringent sustainability and greenhouse gas emission-saving criteria for bioliquids. This regulation forces a rigorous lifecycle analysis of fuels, directly influencing global feedstock sourcing. Producers aiming for the lucrative European market must now prioritize certified waste and residue-based supply chains, moving away from food or feed crop-based inputs.
A notable shift in customer behavior involves the bundling of fuel supply with energy services. Large industrial consumers are increasingly seeking comprehensive, long-term contracts that include guaranteed fuel delivery, on-site storage management, and equipment performance monitoring. This disrupts the traditional spot market for fuel and is most visible in the district heating sector in Germany and Nordic countries.
Global Bioliquid Heat and Power Generation Market Segmentation
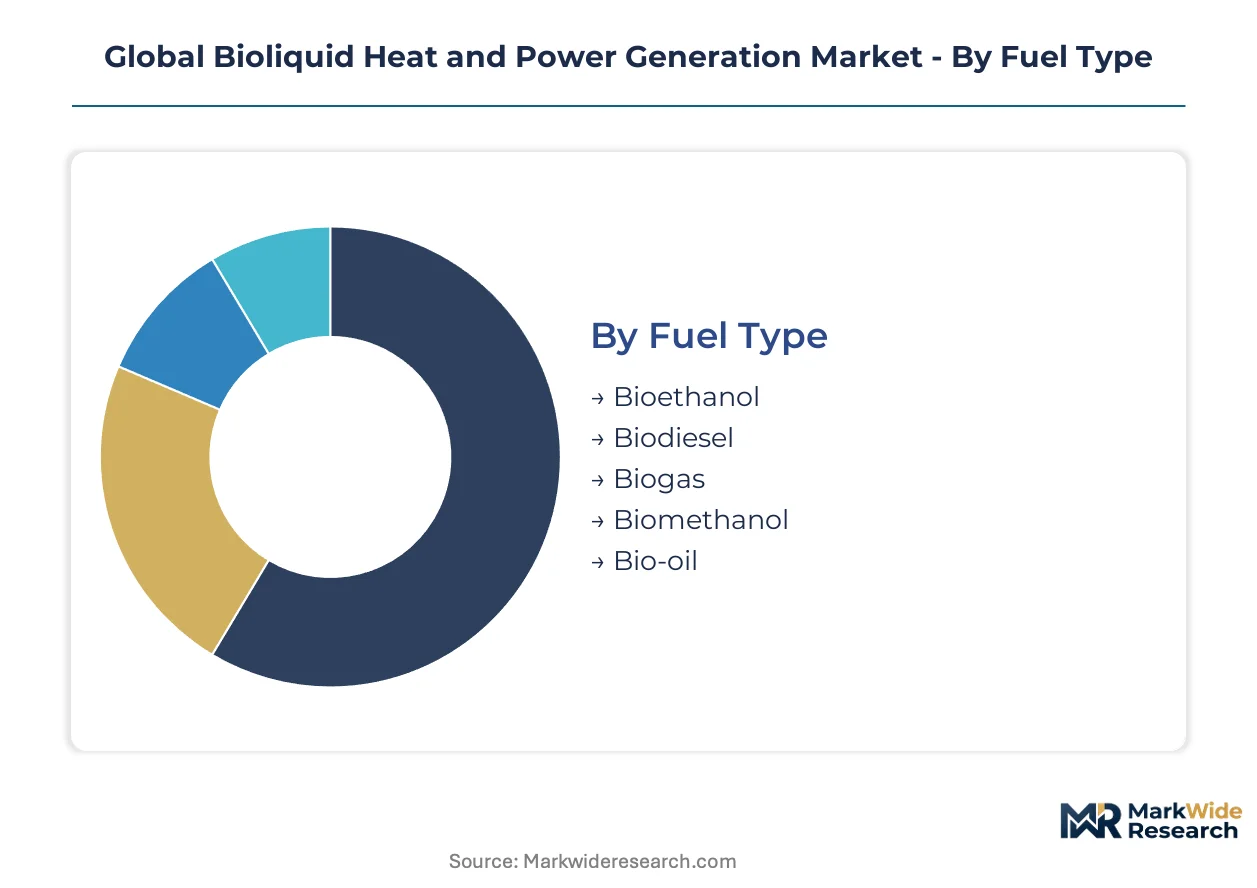
The Global Bioliquid Heat and Power Generation Market is complex, with distinct segments influencing technology adoption, feedstock sourcing, and regulatory compliance. Understanding these granular divisions helps identify areas of concentrated demand and emerging competitive dynamics. Segmentation reveals how different fuel types, generation technologies, and end-user requirements shape investment decisions.
Fuel Type:
The market for bioliquid fuels faces substitution pressure from alternative renewable energy sources and grid electrification. Sustainability mandates increasingly favor specific bioliquid types with lower lifecycle emissions.
- Bio-oil:Produced via rapid thermal processing of solid biomass, this liquid energy carrier offers transportability and storage advantages over raw biomass. Demand concentrates among industrial end-users and decentralized power operators in regions like Northern Europe, driven by its ease of handling and stable combustion properties.
- Biodiesel:Comprising fatty acid methyl esters (FAME) from vegetable oils or animal fats, biodiesel is primarily used in transportation but also for heat and power. Demand is significant in countries with strong blending mandates, such as Germany and the United States, where it helps meet renewable energy obligations.
- Bioethanol:This alcohol fuel is derived from the fermentation of sugars found in biomass, primarily used as a gasoline additive.
- Biogas:A methane-rich gas produced from anaerobic digestion of organic matter, often used in gas engines for combined heat and power.
- Biomethanol:A synthetic alcohol produced through gasification of biomass, offering a clean-burning fuel alternative.
Biodiesel retains volume leadership; Bio-oil holds the steepest expansion curve.
Generation Technology:
The choice of generation technology directly impacts efficiency, scale, and operational flexibility for bioliquid heat and power systems. Technology selection often optimizes for specific fuel characteristics and end-user thermal or electrical load requirements.
- Organic Rankine Cycle:ORC systems efficiently convert low-temperature heat sources into electrical power using an organic working fluid with a lower boiling point than water. Demand is growing in industrial waste heat recovery and small-scale power generation applications, particularly where lower-grade bioliquids are used.
- Gas Engine:Reciprocating internal combustion engines are widely deployed for combined heat and power (CHP) applications, offering high electrical efficiency and fuel flexibility with various bioliquid types. These engines are prevalent in industrial plants and district heating facilities seeking reliable decentralized energy.
- Steam Turbine:Traditional power generation technology using high-pressure steam from bioliquid combustion to drive a turbine, suitable for larger-scale installations.
- Stirling Engine:An external combustion engine known for its quiet operation and ability to run on diverse heat sources, though less common for large-scale bioliquid power.
- Microturbine:Compact, high-speed turbines suitable for small-scale decentralized power generation, offering low emissions and flexible fuel options for commercial facilities.
Gas engines offer proven versatility across various bioliquids, while Organic Rankine Cycle technology maximizes efficiency for lower-grade heat recovery.
End User:
Different end-user segments exhibit unique demand patterns and regulatory drivers for bioliquid heat and power generation. Industrial applications and district heating represent significant demand concentrations.
- Industrial Plants:These facilities utilize bioliquids for on-site combined heat and power (CHP) to reduce energy costs and meet decarbonization targets for process heat and electricity. Energy-intensive sectors across Germany and other European nations are significant adopters.
- District Heating Operators:Utilities in urban areas, particularly across Northern Europe, integrate bioliquids to modernize aging infrastructure and provide centralized heat with lower carbon footprints. The EU Green Deal provides direct incentives for this transition.
- Power Producers:Utility-scale generators integrate bioliquids into their energy mix to meet renewable portfolio standards and reduce reliance on fossil fuels for grid power.
- Commercial Facilities:Businesses and institutions use bioliquid systems for building heating, cooling, and backup power, seeking energy independence and sustainability credentials.
- Agricultural Estates:Farms and rural enterprises employ bioliquid systems for on-farm energy needs, often utilizing agricultural residues as feedstock.
Industrial plants maintain a robust demand base, while district heating operators are expanding bioliquid integration rapidly.
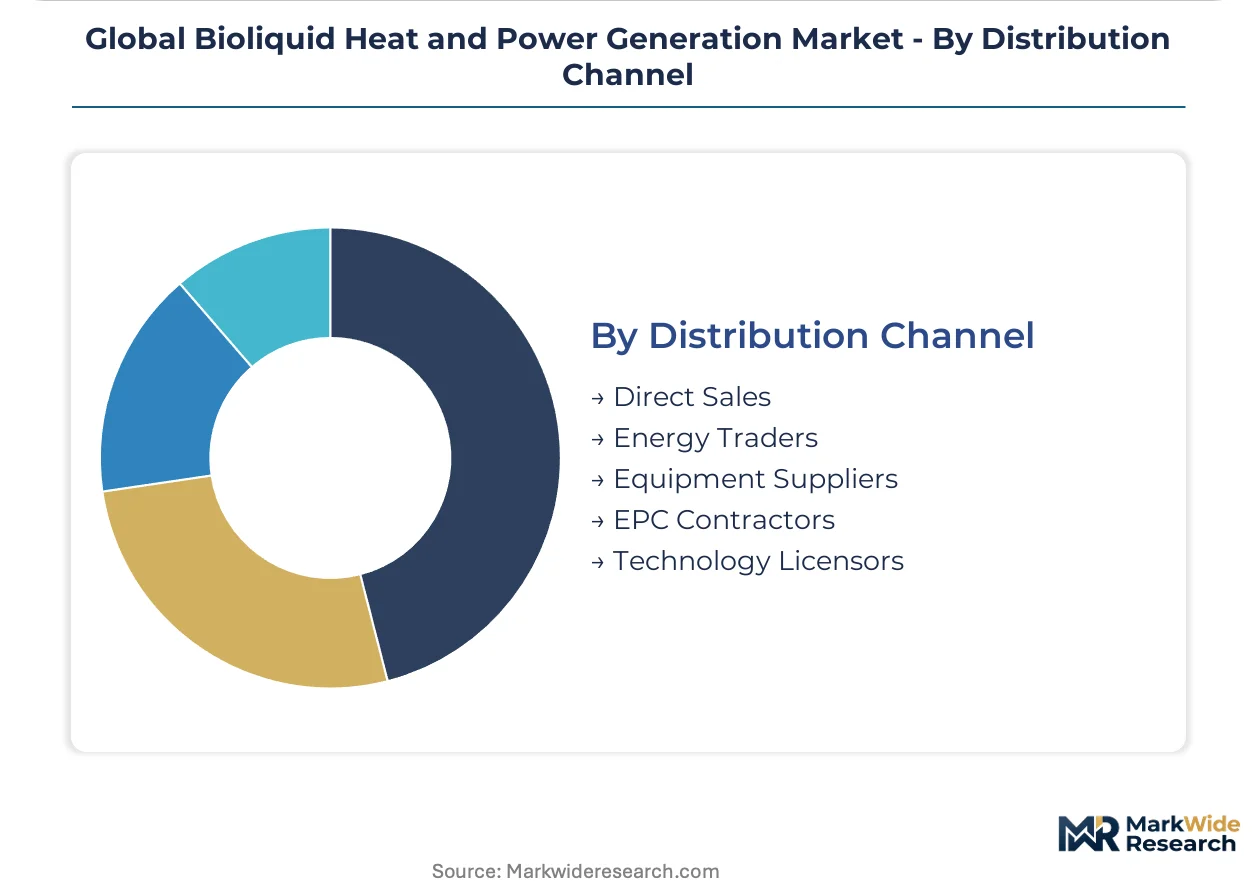
Distribution Channel:
The distribution channels for bioliquids and associated generation equipment vary based on project scale, complexity, and customer sophistication. Direct relationships and integrated project delivery are becoming more prominent.
- Direct Sales:Bioliquid producers establish direct relationships with large industrial consumers and district heating operators for customized, long-term fuel supply contracts. This channel facilitates guaranteed fuel delivery and on-site storage management for substantial off-takers.
- EPC Contractors:Engineering, Procurement, and Construction (EPC) firms deliver turnkey bioliquid heat and power plants, managing project design, equipment sourcing, and construction for industrial clients. These contractors are crucial for complex, large-scale infrastructure developments.
- Energy Traders:These entities facilitate the buying and selling of bioliquid commodities, providing market liquidity and price optimization services for producers and large consumers.
- Equipment Suppliers:Manufacturers of bioliquid combustion systems, gas engines, or ORC units sell directly or through distributors to various end-users and project developers.
- Technology Licensors:Companies offering proprietary bioliquid production processes or generation technologies license their intellectual property to other market participants.
Direct sales optimize long-term supply relationships, and EPC contractors streamline complex project implementation.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The global bioliquid heat and power generation market exhibits varied export-import balances, with some regions relying on domestic biomass resources while others import specialized bioliquids. This dynamic influences local pricing structures and supply chain resilience. Policy frameworks often prioritize local sourcing or sustainable international trade to meet energy demands.
Germany
Germany drives demand through its ambitious decarbonization policies for heat and power infrastructure. The EU Green Deal and national targets incentivize district heating operators to adopt bioliquids. Industrial plants in North Rhine-Westphalia and district heating networks in Hamburg extensively integrate these fuels.
United States
United States demand stems from renewable energy obligations for transportation fuels, extending to heat and power applications. The EPA's Renewable Fuel Standard program supports bioliquid demand across various sectors. Refineries along the Gulf Coast and industrial facilities in California are key adopters of advanced biofuels.
Sweden
Sweden's district heating operators are significant catalysts, seeking flexible, low-carbon fuel sources for modernization. National climate targets, aligned with the EU Green Deal, accelerate the transition from fossil fuels. Stockholm's extensive district heating network and industrial facilities in biomass-rich northern regions utilize bioliquids.
Brazil
Brazil offers substantial potential due to its abundant biomass resources and focus on decentralized energy solutions. National bioenergy programs promote the use of agricultural residues for heat and power generation. The São Paulo state, a hub for sugarcane production, converts byproducts into various bioliquids for local consumption.
Indonesia
Indonesia presents opportunities for bioliquid heat and power, particularly from its vast palm oil industry residues. National renewable energy targets encourage the conversion of these waste streams into valuable fuels. Industrial facilities in Sumatra and Kalimantan are exploring advanced pyrolysis for localized energy solutions.
Global Bioliquid Heat and Power Generation Market Key Industry Players
Listed leaders compete with private specialists across the bioliquid value chain, creating a tiered market structure. Large integrated energy companies often focus on scale and feedstock diversification, aiming for global supply chain control. Specialized firms develop niche processing technologies, particularly for second-generation feedstocks, addressing specific regional needs. Competitive moves frequently involve strategic partnerships for feedstock security and significant capacity expansion in advanced biofuel production facilities.
Specialists in advanced processing, such as Ensyn Fuels, exemplify technology-driven approaches by converting non-food solid biomass into proprietary bio-oil through rapid thermal processing. Neste, a Finland-based company, anchors the segment for renewable fuels derived from waste and residues, leveraging its advanced refining capabilities for global distribution. Archer Daniels Midland Company (ADM), a US-based agricultural giant, represents the integration of feedstock supply with biofuel production, capitalizing on its extensive agricultural processing infrastructure to meet diverse energy demands. These players collectively shape the market's evolution towards more sustainable and efficient bioliquid solutions.
| Leading Market Players |
|---|
| Ensyn Fuels |
| Neste |
| Archer Daniels Midland Company |
| Albioma SA |
| REG |
| Argent Energy |
| Kraton |
| MBP Group |
| BTG |
Cost & Logistics Intelligence
Bioliquid production facilities, especially advanced refining for second-generation feedstocks, require significant capital investment. This scale economy drives consolidation among producers and establishes a baseline for pricing across the market.
Pricing Analysis
Industrial OEM buyers anchor long-term, contract-based pricing structures for bioliquids. Price differentiation stems from feedstock sustainability certification under frameworks like the EU's Renewable Energy Directive, volume scale, and geographic delivery costs. Pricing softness stems from competition with increasingly green grid electricity and substitution from direct electrification in some applications. District heating operators and industrial plants with long-term contracts exhibit lower price sensitivity, while smaller commercial facilities on spot markets are more sensitive.
Supply Chain Analysis
Strategic stockpiling of bio-oil and other bioliquids is common to mitigate feedstock price volatility and ensure supply continuity for industrial users. Supply concentrates in biomass-rich regions like Brazil, Indonesia (from palm oil residues), and Northern Europe (from forestry residues), alongside advanced refining hubs in the US Gulf Coast. The supply chain relies heavily on diverse raw materials, including used cooking oil, forestry residues, and agricultural byproducts. Feedstock cost volatility and complex regulatory compliance, such as RED sustainability criteria, represent significant structural risks. Distribution primarily occurs through direct sales for large contracts and energy traders facilitating spot market transactions.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The global bioliquid heat and power generation market is in an early-cycle expansion phase. Decarbonization policies, such as the EU Green Deal, provide a strong tailwind for increased adoption in industrial and district heating applications.
For Market Incumbents: Consolidate feedstock sourcing networks to achieve economies of scale and enhance supply chain resilience against price fluctuations. Invest in advanced processing technologies for waste-based inputs to meet evolving sustainability mandates and reduce reliance on first-generation feedstocks. Substitution from grid electrification poses a long-term threat to smaller-scale applications. Vertical integration into waste collection infrastructure strengthens feedstock security and cost control.
For New Entrants and Emerging Players: Service-layer gaps exist in providing comprehensive energy solutions beyond fuel supply, including on-site storage management and equipment optimization. Niche opportunities include off-grid power for remote communities and maritime bunker fuel alternatives. Biomass-rich regions in Southeast Asia and Latin America, with developing policy support for decentralized energy, represent penetrable geographic markets. Offer bundled energy services, encompassing fuel delivery, storage, and equipment maintenance, as a compelling go-to-market angle.
For Investors and Strategic Acquirers: Recurring-revenue conversion is highest among bioliquid producers with long-term offtake agreements with industrial and district heating operators. The long-term viability of bioliquids is anchored in policy support for decarbonization over the next decade. Companies specializing in second-generation feedstock conversion or bioenergy with carbon capture and storage (BECCS) projects represent attractive acquisition targets. The rapid deployment of carbon capture and storage infrastructure will signal accelerated BECCS project viability.
| Strategic Initiative | Industry Significance |
|---|---|
| Expand Second-Generation Feedstock Processing | Secures access to sustainable inputs, mitigating regulatory risks and feedstock cost volatility for producers. |
| Develop Bioenergy with Carbon Capture and Storage (BECCS) | Positions facilities to deliver negative-emissions power, aligning with stringent climate targets and creating new revenue streams. |
| Form Long-Term Offtake Agreements | Provides revenue stability and guaranteed supply for bioliquid producers and district heating operators. |
| Invest in Waste Collection Infrastructure | Enhances supply chain control and reduces logistics costs for waste-to-bioliquid conversion facilities. |
| Pursue Global Sustainability Certifications | Ensures market access, particularly in the EU, by demonstrating compliance with stringent Renewable Energy Directive criteria. |
Research Approach
Initial hypotheses were tested against primary input from bioliquid producers, district heating operators, industrial plant managers, EPC contractors, and technology licensors, and refined through iterative feedback. This approach combined in-depth primary interviews with rigorous secondary validation. Secondary data sources included EU Renewable Energy Directive (RED) reports, EPA Renewable Fuel Standard program documents, IEA bioenergy reports, and national energy agency statistics. Both bottom-up and top-down triangulation methods were employed to ensure data accuracy.
Variance-decomposition modeling was applied to assess the impact of key market drivers and restraints across the projection horizon. The analytical framework incorporated segmentation dimensions such as fuel type, generation technology, end user, distribution channel, and regional policy frameworks. Compound annual growth rates were derived from historical trends, market drivers, and expert projections, accounting for market dynamics. Key industry-specific forecast inputs included feedstock availability and the evolution of carbon pricing mechanisms.
Forecasts assume regulatory continuity in regimes like the EU Green Deal and the EPA's Renewable Fuel Standard program; material policy shifts would require re-modeling. The projections reflect assumptions regarding technological advancements and market adoption rates. Revision becomes warranted when significant fluctuations in feedstock prices or rapid advancements in alternative renewable energy technologies cross predefined thresholds.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Biofuels Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
United States Biodiesel Market
Biofuels
Europe Biofuel Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Europe Biodiesel Market
Biofuels
Bioethanol Market
Biofuels
Second Generation Biofuels Market
Biofuels
Biodiesel Market
Biofuels
Latin America Biodiesel Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Brazil Biofuel Market