
 Bioethanol Market | 2026-2036
Bioethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Bioethanol Market Insights
Fleet operators and fuel distributors is unwinding legacy petroleum-centric procurement patterns as low-carbon fuel obligations tighten. POET LLC leverages its integrated corn ethanol platform across the Midwest to sustain supply security for obligated parties. Valero Energy Corporation anchors its renewable fuels division with refinery-adjacent biorefineries that compete on logistics density. Raízen specializes in Brazilian sugarcane ethanol, dominating cost curves through year-round crush operations and bagasse cogeneration.
Bioethanol denotes ethanol derived from biomass fermentation, typically containing 99.5 percent purity after dehydration, with energy content of approximately 21.2 megajoules per liter, serving primarily as an oxygenated fuel additive or petroleum blend component. Corn and sugarcane feedstocks occupy the bulk of installed capacity, though margin pools are shifting toward cellulosic pathways where biochemical conversion technologies unlock lignocellulosic biomass. Dry milling leads production technology deployment due to capital efficiency, while wet milling retains relevance where co-product extraction—distillers grains and corn oil—supports facility economics.
The EPA enforces Renewable Fuel Standard blending mandates that obligate petroleum refiners to incorporate specified bioethanol volumes, directly shaping demand floors and compliance credit markets. Brazil's ANP administers RenovaBio carbon intensity targets that redirect investment toward efficient mills and pipeline infrastructure. Stakeholders must monitor how evolving lifecycle assessment methodologies and land-use criteria recalibrate which feedstock-technology combinations qualify for premium credits under tightening sustainability protocols.
Market Dynamics
Decarbonization mandates across transport sectors are compressing blending economics while cellulosic conversion technologies mature. The tension between first-generation feedstock saturation and second-generation yield improvements defines capital allocation priorities.
Growth Catalysts
- RenovaBio carbon intensity targets:Brazil's ANP-administered program redirects investment toward efficient mills with cogeneration assets, tightening compliance premiums for low-carbon intensity ethanol.
- Cellulosic biochemical conversion:Enzymatic hydrolysis of agricultural residues unlocks lignocellulosic feedstocks previously excluded from fuel credit programs.
- Midwest corn belt concentration:Integrated biorefinery networks in Iowa and Illinois sustain supply security through captive grain procurement and distillers grains co-product streams.
Market Restraints
- Natural gas price volatility:Thermal energy requirements for distillation and dehydration expose margin structures to input cost swings at US Gulf Coast hubs.
- US corn supply concentration:Drought risk across the Corn Belt threatens feedstock security for dry-mill operations dependent on local grain origination.
- Lifecycle assessment methodology uncertainty:Indirect land-use change calculations under EPA Renewable Fuel Standard create compliance credit price instability.
Strategic Opportunities
- Indian ethanol blending program:The country's 20 percent blending target by 2025 redirects molasses and damaged grain into fuel ethanol, creating new demand floors.
- Aviation sector offtake:Sustainable aviation fuel pathways incorporating ethanol-to-jet conversion attract long-term purchase commitments from cargo carriers.
- Pipeline infrastructure expansion:Dedicated ethanol pipelines in Brazil's Southeast reduce trucking costs and enable year-round distribution to coastal terminals.
Industry Challenges
- Enzyme formulation expertise:Cellulosic operations require specialized biochemical engineering talent scarce outside established biotechnology clusters.
- Co-product market saturation:Distillers dried grains with solubles face pricing pressure from alternative protein feeds, compressing facility revenue diversification.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Bioethanol Market |
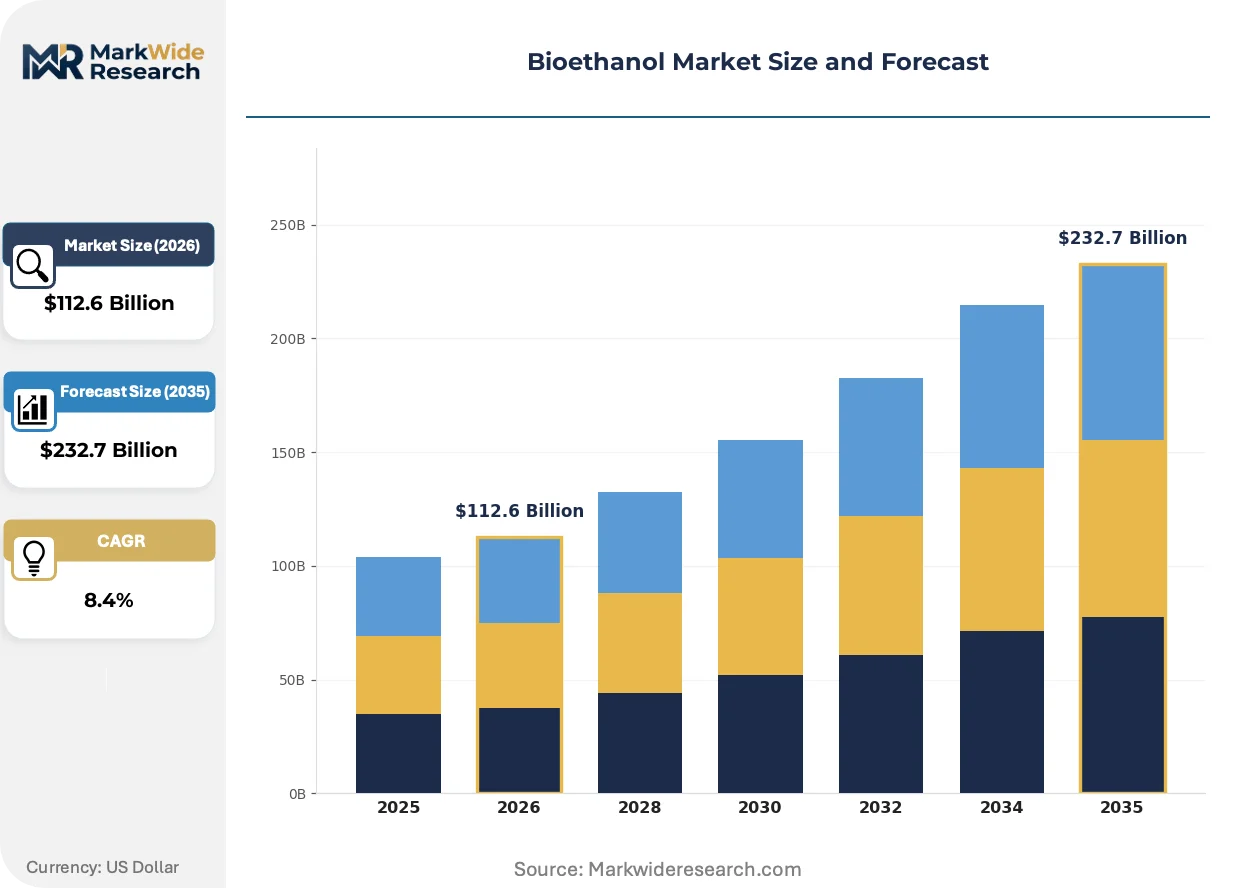
| Market Size in 2026 | $112.6 Billion |
| Market Size in 2035 | $232.7 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Corn, Sugarcane, Cellulose, Cassava, Wheat, Barley Production Technology: Dry Milling, Wet Milling, Cellulosic, Thermochemical, Biochemical Application: Fuel Additive, Solvent, Beverage Alcohol, Pharmaceutical, Personal Care End User: Fuel Distributors, Chemical Manufacturers, Beverage Producers, Cosmetic Companies |
| Companies Covered | POET LLC, Archer Daniels Midland Company, Valero Energy Corporation, Green Plains, Raízen, CropEnergies AG, Tereos, Alto Ingredients, The Andersons, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Bioethanol Market Trends and Innovations
Process intensification and carbon accounting precision are redefining competitive advantage. Facilities now compete on energy integration density and verified emission reductions rather than scale alone.
Cellulosic ethanol production is bifurcating between consolidated biorefinery platforms and distributed preprocessing depots. POET-DSM Liberty technology licensees deploy enzymatic hydrolysis at commercial scale, while smaller operators focus on feedstock densification. This technology split is compressing capital requirements for market entry while raising technical barriers for full integration.
EPA Renewable Fuel Standard lifecycle assessment updates are tightening feedstock eligibility criteria. The agency's revised greenhouse gas modeling excludes certain land-use change scenarios, forcing Brazilian mills toward certified sugarcane sourcing. US corn ethanol producers respond with precision agriculture partnerships to document carbon intensity reductions at field level.
Fleet operators now demand mass-balance certification for contracted ethanol volumes. Transport and logistics companies in California source specifically from facilities registered under the state's Low Carbon Fuel Standard, displacing generic commodity procurement. This preference shift concentrates offtake toward integrated producers with verified supply chain documentation.
Bioethanol Market Segmentation
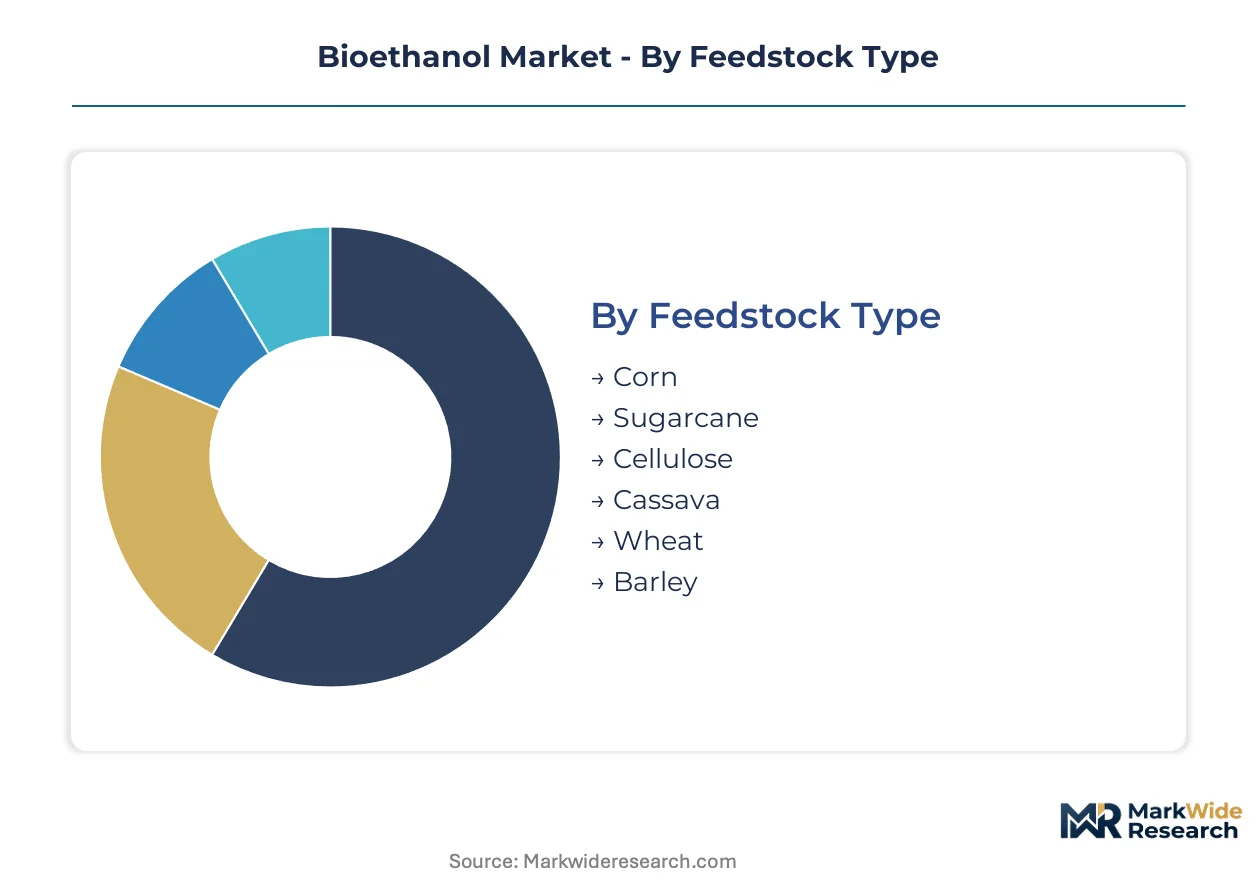
Feedstock selection determines carbon intensity scores under evolving sustainability protocols, while production technology choices lock in capital requirements and co-product revenue streams. Application mix shifts with transport electrification timelines and chemical sector offtake patterns.
Feedstock Type:
EPA Renewable Fuel Standard and Brazil's RenovaBio apply divergent carbon intensity benchmarks that privilege certain feedstocks over others in compliance credit markets.
- Corn:Starch-rich kernels processed through dry or wet milling yield fermentation substrates with established supply chains across the US Midwest. Iowa and Illinois biorefineries source through captive grain origination networks, though drought risk concentrates feedstock security exposure in the Corn Belt.
- Sugarcane:Sucrose from crushed stalks delivers superior energy balance ratios and year-round harvest windows in tropical climates. São Paulo mills integrate bagasse cogeneration to slash operational carbon intensity and capture RenovaBio premium credits.
- Cellulose:Agricultural residues and dedicated energy crops unlock lignocellulosic conversion pathways with lower indirect land-use change penalties.
- Cassava:Starch tubers serve ethanol production in Southeast Asian markets with limited grain infrastructure.
- Wheat:European biorefineries deploy surplus grain stocks during favorable harvest cycles.
- Barley:Malt-grade and feed-grade varieties enter ethanol streams where brewing sector demand softens.
Corn handles the majority of throughput; cellulosic feedstocks are expanding most quickly on share as enzymatic hydrolysis technologies mature.
Production Technology:
Capital efficiency separates incumbent platforms from emerging pathways, with dry milling dominating installed capacity due to lower upfront investment requirements.
- Dry Milling:Whole kernel grinding followed by simultaneous saccharification and fermentation yields ethanol plus distillers dried grains with solubles. US facilities concentrate in Iowa and Nebraska where grain origination costs compress manufacturing economics.
- Wet Milling:Starch separation from gluten and fiber fractions enables high-purity ethanol plus corn oil and gluten meal co-products. Illinois and Indiana plants target food-grade and pharmaceutical-grade specifications where purity premiums justify higher capital intensity.
- Cellulosic:Enzymatic pretreatment and fermentation of lignocellulosic biomass operates at commercial scale through POET-DSM Liberty configurations.
- Thermochemical:Gasification and catalytic synthesis routes convert heterogeneous feedstocks via syngas intermediates.
- Biochemical:Consolidated bioprocessing approaches integrate enzyme production, hydrolysis, and fermentation in single-reactor systems.
Dry milling commands the largest installed base; cellulosic platforms are gaining share fastest as biochemical conversion yields improve.
Application:
Transport fuel obligations anchor volume demand while industrial applications provide pricing diversification.
- Fuel Additive:Oxygenated blending components at 10 percent (E10) or higher concentrations reduce petroleum dependency and tailpipe emissions. US obligated parties under EPA Renewable Fuel Standard and Brazilian distributors under ANP blending mandates sustain procurement floors.
- Solvent:High-purity ethanol extracts flavors, fragrances, and pharmaceutical actives where residue specifications demand food-grade or USP-grade certification.
- Beverage Alcohol:Neutral spirits for distilled products require regulatory compliance with national excise frameworks.
- Pharmaceutical:USP-grade and EP-grade specifications apply to disinfectant and solvent applications in drug manufacturing.
- Personal Care:Cosmetic formulations utilize denatured ethanol as carrier solvents and antimicrobial agents.
Fuel additive absorbs the dominant share of production volume; pharmaceutical applications are climbing the fastest on margin contribution.
End User:
Procurement patterns diverge between compliance-driven fuel distributors and specification-sensitive industrial buyers.
- Fuel Distributors:Obligated parties under EPA Renewable Fuel Standard and Brazil's ANP blending mandates source ethanol to satisfy renewable volume obligations and generate compliance credits. Valero Energy Corporation and Raízen anchor procurement through long-term supply agreements with integrated biorefineries.
- Chemical Manufacturers:Solvent and intermediate applications in specialty chemical production demand consistent purity grades and supply security.
- Beverage Producers:Neutral spirit procurement follows excise tax regulations and organoleptic quality specifications.
- Cosmetic Companies:Personal care formulators specify denatured ethanol grades with residual impurity limits.
Fuel distributors handle the majority of offtake; chemical manufacturers are expanding procurement fastest as industrial ethanol demand diversifies beyond transport applications.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fuel distributors and fleet operators concentrate procurement in jurisdictions with enforceable blending mandates and established agricultural supply chains. Corn and sugarcane processing clusters anchor regional production economics.
United States
Midwest fuel distributors source ethanol from Iowa and Illinois biorefineries to meet EPA Renewable Fuel Standard obligations. The EPA enforces annual renewable volume obligations that create compliance credit markets. Corn Belt processing facilities leverage captive grain origination networks and distillers grains co-product streams.
Brazil
São Paulo mill operators supply coastal fuel distributors under ANP-administered RenovaBio carbon intensity targets. The program redirects investment toward efficient mills with bagasse cogeneration assets. Southeast pipeline infrastructure reduces trucking costs to coastal terminals.
India
State-run oil marketing companies procure ethanol from Uttar Pradesh and Maharashtra distilleries for 20 percent blending targets. The country's ethanol program redirects molasses and damaged grain into fuel ethanol. Western and Northern processing clusters expand capacity to meet procurement floors.
Germany
Chemical manufacturers source high-purity ethanol from Saxony-Anhalt and Lower Saxony biorefineries for solvent and pharmaceutical applications. EU Green Deal sustainability criteria tighten feedstock eligibility for imported volumes. Eastern processing facilities integrate with regional sugar beet and grain supply chains.
China
Provincial fuel blenders in Jilin and Henan absorb corn-based ethanol for E10 gasoline mandates. The country's national energy administration enforces blending quotas in targeted provinces. Northeast processing clusters benefit from surplus grain stocks and state-backed capacity expansion.
Bioethanol Market Competitive Landscape
Player mix skews toward integrated agribusiness conglomerates with captive feedstock access and refinery-adjacent biorefinery operators competing on logistics density. Structure concentrates around first-generation ethanol platforms with cellulosic specialists occupying emerging technology tiers. Dominant archetypes include grain-origination-integrated processors, sugarcane crush-and-distill operators, and petroleum refinery renewable fuels divisions. Competitive moves center on biorefinery capacity expansion and strategic partnerships for cellulosic technology licensing.
Within the integrated agribusiness tier, POET LLC and Archer Daniels Midland Company exemplify grain-origination-integrated processors with Midwest corn belt concentration. Valero Energy Corporation occupies a position among petroleum refinery renewable fuels divisions with refinery-adjacent biorefinery networks. These three entities represent the dominant competitive archetypes: captive agricultural supply chain control, petroleum industry downstream integration, and multi-feedstock processing flexibility.
| Leading Market Players |
|---|
| POET LLC |
| Archer Daniels Midland Company |
| Valero Energy Corporation |
| Green Plains |
| Raízen |
| CropEnergies AG |
| Tereos |
| Alto Ingredients |
| The Andersons |
| Others |
Pricing and Supply Chain Analysis
EPA Renewable Fuel Standard lifecycle assessment methodologies gate both feedstock qualification and compliance credit premiums, forcing producers to document carbon intensity reductions before accessing price-tiers reserved for low-carbon ethanol. This certification filter simultaneously constrains supply pool eligibility and stratifies pricing across verified and unverified production streams.
Pricing Analysis
First-generation corn and sugarcane ethanol trades at commodity benchmarks while cellulosic platforms command structural premiums reflecting enzymatic hydrolysis yields. Pricing stratifies across certified low-carbon, standard compliance-grade, and unverified economy tiers based on documented carbon intensity scores and mass-balance certification. Cost compression in standard-grade streams is intensifying because distillers dried grains face pricing pressure from alternative protein feeds. Chemical manufacturers demonstrate lowest price sensitivity due to purity specifications, while fuel distributors maximize volume procurement at compliance-floor pricing.
Supply Chain Analysis
Inventory cycles compress during harvest windows when corn belt biorefineries draw from captive grain origination networks and sugarcane mills run year-round crush operations. Feedstock supply concentrates in the United States, Brazil, and India where established agricultural infrastructure anchors production economics. Raw material dependencies center on corn starch, sugarcane sucrose, and agricultural residues for enzymatic conversion. Single-source vulnerability runs through Corn Belt drought exposure that threatens localized grain security. Distribution runs through dedicated pipeline infrastructure in Brazil's Southeast and barge-rail networks across the US Midwest.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Specialized biochemical engineering talent for cellulosic operations remains concentrated outside established biotechnology clusters, creating acquisition premiums for facilities with in-house enzymatic formulation expertise.
For Market Incumbents: Consolidate position through backward integration into captive grain origination networks and bagasse cogeneration assets that capture RenovaBio premium credits. Cellulosic technology licensing from POET-DSM Liberty configurations offers defensive moats against second-generation yield improvements threatening first-generation margin pools. Prioritize precision agriculture partnerships to document field-level carbon intensity reductions before EPA assessment updates tighten eligibility. For New Entrants and Emerging Players: Lead with distributed preprocessing depot models that compress capital requirements for lignocellulosic feedstock densification before committing to full biorefinery integration. India's 20 percent ethanol blending program offers the most penetrable demand floor, redirecting molasses and damaged grain into fuel ethanol with less incumbent concentration than US or Brazilian markets. Target long-term offtake agreements with state-run oil marketing companies seeking supply security for blending mandates. For Investors and Strategic Acquirers: EPA lifecycle assessment updates reshapes the acquisition landscape by devaluing facilities without verified supply chain documentation or precision agriculture partnerships. Five-to-ten year viability favors integrated producers with demonstrated carbon intensity tracking and refinery-adjacent logistics density. Watch for RenovaBio carbon intensity target recalibrations as the signal indicating which Brazilian mill configurations will sustain premium credit access.| Strategic Initiative | Industry Significance |
|---|---|
| Cellulosic Technology Licensing | POET-DSM Liberty configurations unlock lignocellulosic pathways previously excluded from fuel credit programs. |
| Backward Integration into Feedstock | Captive grain origination networks in Iowa and Illinois compress manufacturing economics through harvest-window procurement control. |
| Precision Agriculture Partnerships | Field-level carbon intensity documentation secures EPA compliance credit eligibility under tightening assessment methodologies. |
| Pipeline Infrastructure Expansion | Dedicated ethanol pipelines in Brazil's Southeast reduce trucking costs and enable year-round distribution to coastal terminals. |
| Bagasse Cogeneration Investment | São Paulo mills integrate cogeneration assets to slash operational carbon intensity and capture RenovaBio premium credits. |
Research Methodology
A standing panel of biorefinery operations directors, fuel procurement managers at obligated parties, grain origination specialists, and ANP compliance officers provided ongoing calibration across primary interview cycles. Secondary validation drew from EPA renewable volume obligation filings, ANP RenovaBio carbon intensity registry data, USDA crop production reports, and customs trade records for ethanol import-export flows. Bottom-up facility capacity assessments triangulated against top-down demand modeling from transport fleet decarbonization mandates.
Consistency checks validated volume and value outputs against external benchmarks including EIA ethanol production statistics and IEA biofuel demand projections across the analysis window. Segmentation modeling incorporated feedstock type, production technology platform, application grade, and regional regulatory framework dimensions. CAGRs were derived from regression analysis of historical production trends and policy-mandated blending trajectory requirements, with specific inputs for enzyme cost curves and natural gas price volatility at US Gulf Coast hubs.
Forecasts assume regulatory continuity in EPA Renewable Fuel Standard enforcement and ANP RenovaBio administration; material policy shifts around lifecycle assessment methodologies or land-use change calculations would require re-modeling. Outputs are directional rather than point-estimates.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Europe Advanced Biofuel Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Second Generation Biofuels Market
Biofuels
Biodiesel Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Europe Biofuel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Latin America Biodiesel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Brazil Biofuel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Europe Biodiesel Market
Biofuels
United States Biodiesel Market