
 South-East Asia Biodiesel Market | 2026-2036
South-East Asia Biodiesel Market Size, Share, and Industry Trends Forecast 2026-2036
South-East Asia Biodiesel Market Analytics
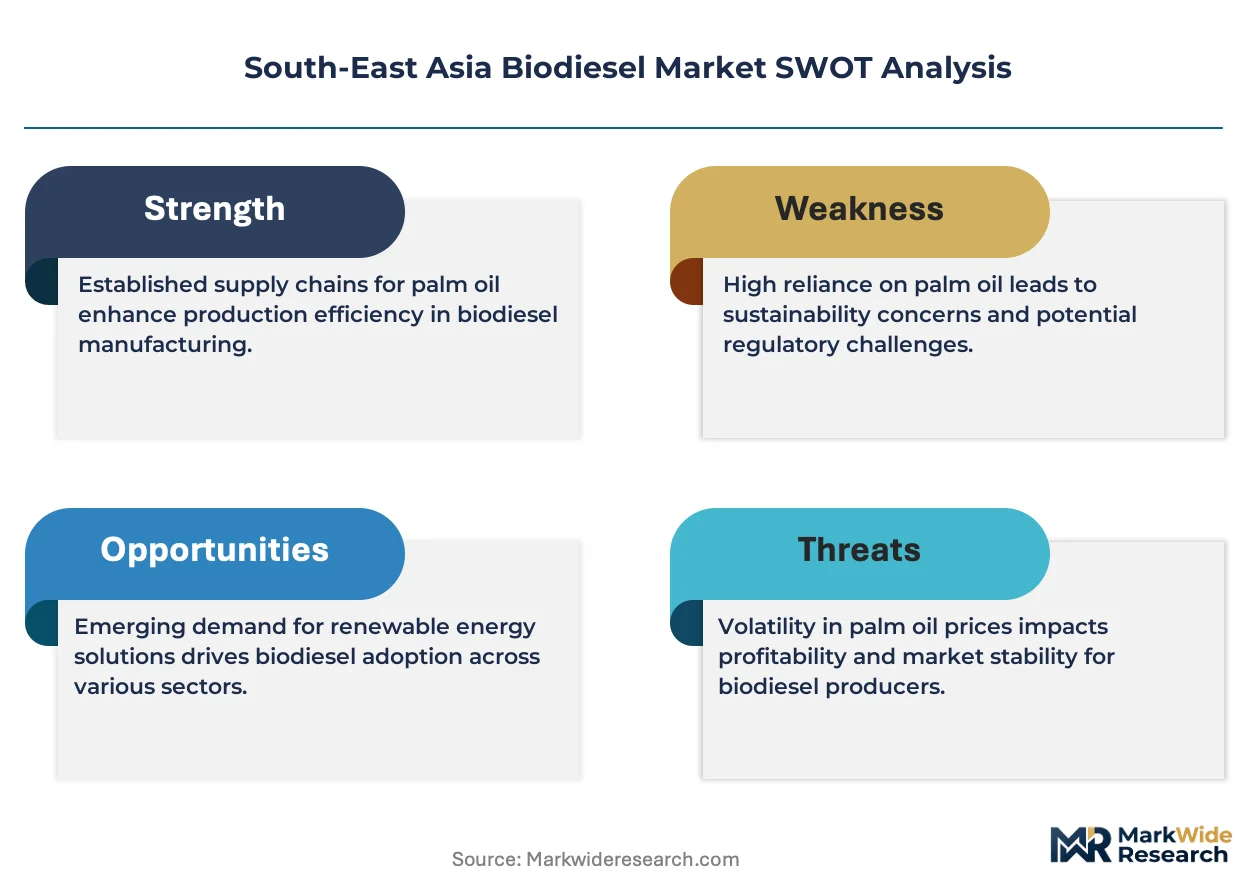
ISCC certification is unwinding competitive access across the South-East Asia biodiesel landscape, filtering out uncertified producers from European offtake contracts. EcoCeres leverages its integrated refinery complex in Singapore to sustain premium product grades for export markets. KLK Bioenergy Sdn Bhd anchors Malaysian supply through its oleochemical-to-biodiesel vertical chain. PT Musim Mas competes on crude palm oil sourcing depth, while BBGI Public Company Limited differentiates through domestic Thai distribution networks.
South-East Asia biodiesel comprises fatty acid methyl esters synthesized from vegetable oils or animal fats via transesterification, yielding a renewable diesel substitute with cetane values exceeding 51 and sulfur content below 10 ppm for compression ignition engines. Palm oil feedstock dominates regional output given established crushing infrastructure and mature estate logistics across Indonesia and Malaysia. Transesterification remains the prevailing production method, though hydrothermal routes gain traction for waste cooking oil valorization. The transportation end user industry commands the largest volume share, while waste cooking oil feedstock represents the fastest-expanding segment as circular economy mandates harden.
Indonesia's Ministry of Energy and Mineral Resources enforces B35 blending mandates that structurally lift domestic offtake obligations, while Malaysia's BIS-equivalent biodiesel standards govern product quality for fleet certification. Thailand's Department of Alternative Energy Development and Efficiency coordinates with the country's national petroleum regulator to calibrate biofuel subsidy tiers. Stakeholders must monitor feedstock price volatility against mandate enforcement consistency to calibrate capacity commitments.
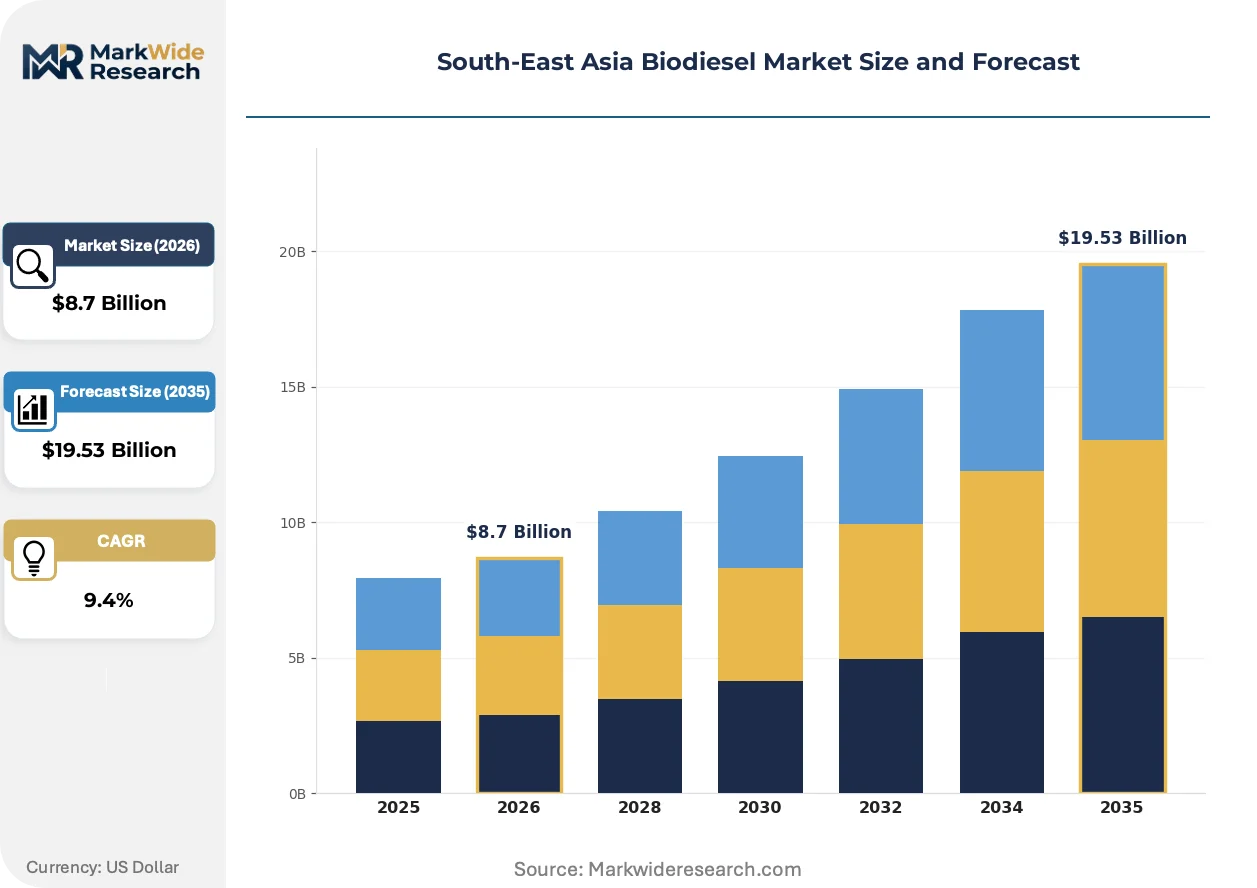
Market Dynamics
Indonesia's B35 blending mandate is compressing supply elasticity across South-East Asia, forcing producers to lock in palm oil feedstock contracts before crushing season peaks.
Growth Catalysts
- Indonesian B35 Mandate:The Ministry of Energy and Mineral Resources enforces rising biofuel blend floors, structurally lifting offtake obligations for domestic refiners and fleet operators.
- Waste Cooking Oil Valorization:Hydrothermal processing routes gain commercial traction as circular economy mandates harden across Thai and Malaysian jurisdictions.
- ISCC Certification:European offtake contracts increasingly require sustainability credentials, filtering uncertified producers from premium export channels.
Market Restraints
- Crude Palm Oil Volatility:Feedstock costs swing with El Niño cycles and Indonesian export levy adjustments, compressing refinery margins without warning.
- Singapore Refinery Concentration:Premium product grades cluster at integrated complexes, leaving standalone Malaysian and Thai processors exposed to quality arbitrage.
- FAME Cold-Flow Limitations:Fatty acid methyl esters gel below 15°C, restricting winter deployment in northern Vietnamese and highland Thai applications.
Strategic Opportunities
- Vietnamese Fleet Electrification Lag:Diesel dependence persists in heavy trucking and marine sectors, opening B10-B20 penetration before EV infrastructure matures.
- Philippine Biofuel Act Enforcement:The Department of Energy is calibrating biodiesel blend mandates, creating first-mover positioning for ISCC-certified exporters.
- HVO-Biodiesel Co-processing:Hydrotreated vegetable oil convergence with conventional transesterification allows refiners to toggle output grades based offtake premiums.
Industry Challenges
- ISCC Audit Backlogs:Certification timelines stretch 8-14 months as accredited bodies face inspection capacity constraints across Indonesian estate networks.
- Transesterification Catalyst Sourcing:Homogeneous alkaline catalyst supply concentrates in Chinese chemical producers, exposing ASEAN refiners to shipping disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | South-East Asia Biodiesel Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $19.53 Billion |
| CAGR (2026 – 2036) | 9.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Palm Oil, Soybean Oil, Waste Cooking Oil, Jatropha Oil Production Method: Transesterification, Fermentation, Hydrothermal, Supercritical End User Industry: Transportation, Agriculture, Energy Generation, Industrial Distribution Channel: Wholesale, Retail, Online Sales, Direct Supply |
| Companies Covered | EcoCeres, Vance Group Limited, Louis Dreyfus Company, Tristar Global, PT Anugerah Inti Gemanusa, KLK Bioenergy Sdn Bhd, BBGI Public Company Limited, PT Batara Elok Semesta Terpadu, PT Musim Mas, Others |
| Regions Covered | Southeast Asia: Indonesia, Thailand, Vietnam, Philippines, Malaysia, Singapore, Myanmar, Cambodia, Rest of Southeast Asia |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
South-East Asia Biodiesel Market Evolving Landscape
Technology trajectories across South-East Asia are splitting between legacy transesterification scale and emergent hydrothermal valorization, while regulatory stringency in European offtake markets filters producer access.
Hydrothermal liquefaction of waste cooking oil is fragmenting feedstock procurement patterns across Thai and Vietnamese refineries. Small-scale urban collectors now supply decentralized processing units that bypass traditional estate-crushing infrastructure. This distributed model is fragmenting the historical palm oil supply monopoly and enabling non-estate producers to capture circular economy subsidies.
Thailand's Department of Alternative Energy Development and Efficiency has tightened biofuel subsidy tiering, linking support levels to lifecycle carbon intensity scores. Refiners must now submit third-party verified greenhouse gas calculations to access premium tariff bands. Malaysian processors with captive oleochemical chains are adapting fastest, while standalone biodiesel operators face margin compression.
Fleet operators in Indonesia are consolidating procurement through state-owned Pertamina's contracted supply pools, displacing spot-market purchasing. Large transport cooperatives in Java and Sumatra now negotiate direct offtake agreements with certified refiners, compressing distributor intermediaries. This concentration is most visible in Jakarta's metropolitan bus and trucking networks, where fuel card systems track blend compliance in real time.
South-East Asia Biodiesel Market Segmentation
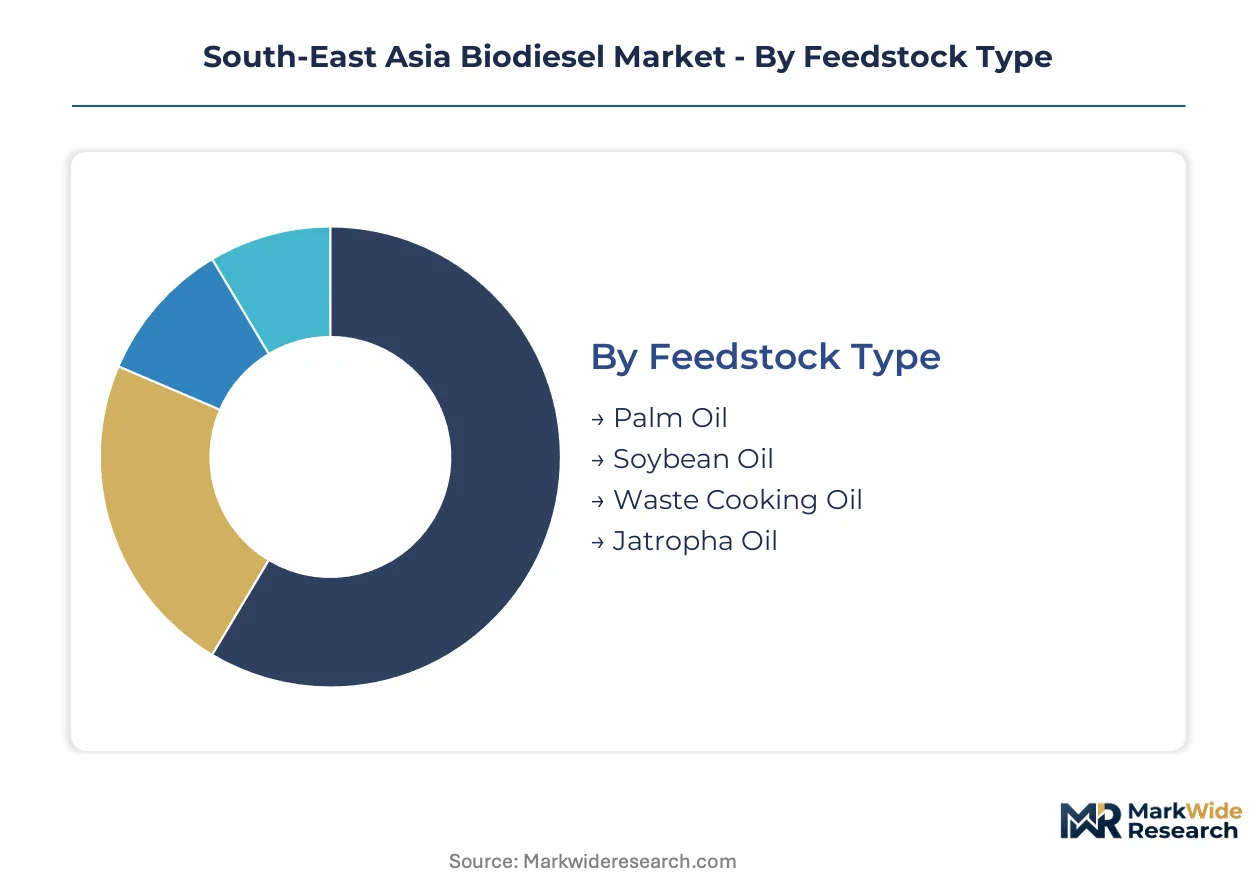
South-East Asia biodiesel demand fragments across feedstock origins, production chemistries, and end-use applications. Procurement channels vary sharply by volume scale and certification requirements, with fleet operators, industrial burners, and export traders each accessing distinct supply tiers.
Feedstock Type:
Channel-mix patterns diverge sharply by feedstock origin, with estate-linked palm oil flowing through wholesale pools while waste cooking oil reaches refiners via decentralized collection networks.
- Palm Oil:Crude and refined palm oil dominates regional input volumes, sourced from Indonesian and Malaysian crushing estates with integrated logistics to major refineries. Indonesian transportation fleets absorb the largest share under B35 mandate enforcement, though export levy volatility compresses contract pricing predictability.
- Waste Cooking Oil:Post-consumer grease and industrial frying residues supply hydrothermal processing routes with lower carbon intensity scores. Thai urban collection networks and Vietnamese hospitality sector aggregators are expanding fastest as circular economy subsidies harden.
- Soybean Oil:Argentine and Brazilian soybean oil imports supplement regional supply during palm oil price spikes, landing primarily at Singapore storage terminals for re-export blending.
- Jatropha Oil:Marginal cultivation across Philippine and Indonesian non-estate smallholdings supplies niche research quantities, constrained by oil yield variability and limited crushing infrastructure.
By volume, palm oil leads. By growth pace, waste cooking oil is climbing fastest.
Production Method:
Cost tier separation is pronounced, with legacy alkaline routes serving price-sensitive domestic mandates while supercritical and hydrothermal units capture premium export certifications.
- Transesterification:Alkaline-catalyzed esterification of triglycerides remains the baseline technology, producing fatty acid methyl esters with cetane values above 51. Indonesian state-owned refiners and Malaysian oleochemical-integrated processors dominate this tier, feeding B20-B35 domestic blending pools.
- Hydrothermal:Sub-critical water processing of high-moisture waste oils eliminates pre-drying costs and catalyst consumption. Thai small-scale refiners near Bangkok and Chiang Mai are deploying containerized units to bypass estate supply dependence.
- Fermentation:Microbial lipid conversion from lignocellulosic feedstocks remains pre-commercial, with pilot units at Singapore research clusters targeting aviation fuel precursors.
- Supercritical:Methanol reactions above critical temperature and pressure eliminate catalyst requirements entirely. Singapore integrated complexes deploy this route for ISCC-certified export grades commanding European offtake premiums.
Transesterification handles the greatest throughput. Supercritical methods are expanding most quickly in value terms.
End User Industry:
Application requirements split procurement patterns, with transportation mandates enforcing volume scale while industrial burners prioritize sulfur content and cold-flow specifications.
- Transportation:Road freight, metropolitan bus fleets, and marine bunkering absorb mandated blend volumes across Indonesian and Malaysian jurisdictions. Fleet operators consolidate purchasing through state oil company contracted pools, displacing spot-market intermediaries.
- Energy Generation:Power utilities and industrial cogeneration plants burn B100 or high-blend biodiesel in compression ignition generators. Philippine and Vietnamese off-grid installations represent emerging demand pockets as diesel price differentials widen.
- Agriculture:Estate machinery and irrigation pumps consume unblended biodiesel in remote Indonesian and Malaysian plantation zones, bypassing formal distribution infrastructure entirely.
- Industrial:Boiler fuel substitution in food processing and textile manufacturing concentrates in Thai and Vietnamese factory zones, with sulfur content below 10 ppm required for stack emission compliance.
Transportation commands the largest volume share. Energy generation is gaining share fastest as utility fuel-switching accelerates.
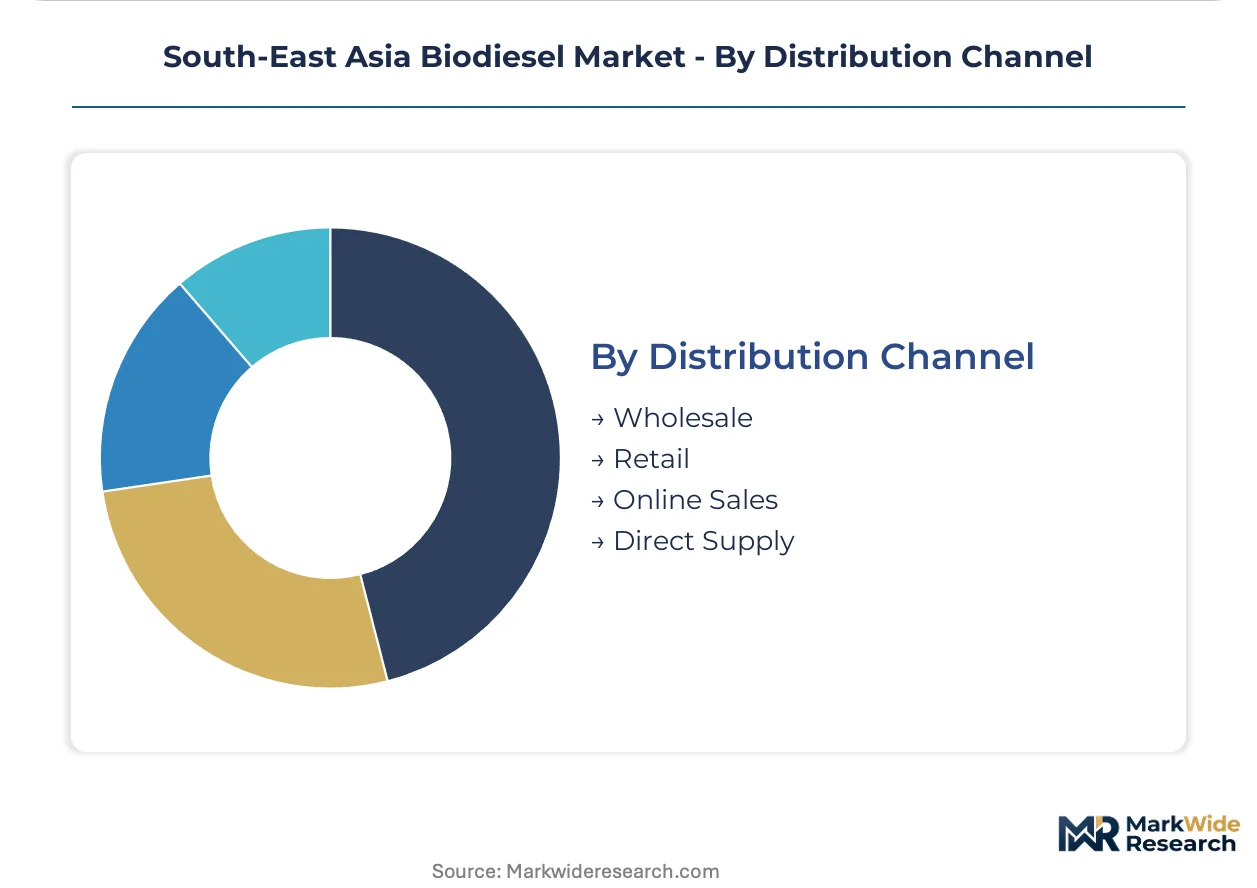
Distribution Channel:
Customer type determines channel access, with wholesale pools serving certified fleet operators while direct supply relationships lock in industrial offtake at fixed premiums.
- Wholesale:Bulk terminal sales through Singapore, Jakarta, and Port Klang storage hubs supply blenders and distributors. ISCC certification filters participation, with uncertified producers excluded from European-bound cargo pooling.
- Direct Supply:Refiner-to-fleet long-term contracts eliminate distributor margins, concentrated in Indonesian state-owned Pertamina supply pools and Malaysian transport cooperative agreements.
- Retail:Service station blending at B20-B35 ratios serves fragmented owner-operator trucking across Indonesian inter-island routes and Thai provincial highways.
- Online Sales:Digital platforms for small-volume B100 purchases by agricultural machinery owners and generator operators remain nascent, concentrated in Vietnamese and Philippine e-commerce experiments.
Wholesale channels move the greatest volume. Direct supply is expanding most quickly as fleet consolidation progresses.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Fleet operators and estate-linked refiners dominate procurement across South-East Asia, with national blending mandates concentrating demand in Indonesia, Malaysia, and Thailand while Vietnam and the Philippines emerge as incremental absorption zones.
Indonesia
Domestic transportation fleets and marine bunkering operations absorb the largest mandated volumes under B35 enforcement. The Ministry of Energy and Mineral Resources calibrates export levy structures to preserve domestic crushing margins. Java's integrated refinery corridor around Jakarta and Surabaya processes estate-sourced crude palm oil into fatty acid methyl esters for state-owned distribution pools.
Malaysia
Transport cooperatives and industrial cogeneration plants drive offtake under the B20 program expansion. The national biodiesel standards regulator enforces BIS-equivalent quality certification for fleet compliance. Port Klang's storage terminals and the Klang Valley oleochemical cluster anchor production scale, with integrated processors leveraging captive palm oil supply chains.
Thailand
Metropolitan bus operators and food processing manufacturers diversify feedstock procurement toward waste cooking oil valorization. The Department of Alternative Energy Development and Efficiency ties subsidy tiers to verified lifecycle carbon intensity scores. Bangkok and Chiang Mai host containerized hydrothermal processing units that bypass traditional estate infrastructure.
Vietnam
Heavy trucking fleets and off-grid power utilities sustain diesel dependence amid lagging electrification infrastructure. The national petroleum regulator coordinates biofuel blend specifications with provincial distribution licensing. Ho Chi Minh City's industrial zones and the Mekong Delta agricultural machinery corridor represent emerging B10-B20 penetration pockets.
Singapore
Export-oriented traders and ISCC-certified European offtake contracts concentrate premium product grades at integrated refinery complexes. The city-state's storage and blending terminals serve as regional arbitrage hubs. Jurong Island's supercritical processing capacity supplies sustainability-verified cargoes commanding premium tariff bands.
South-East Asia Biodiesel Market Competitive Landscape
Player mix skews toward estate-integrated refiners and oleochemical conglomerates with captive feedstock access, compressing margins for standalone processors dependent on spot palm oil markets. Strategic archetypes split between vertical estate-to-refinery operators, Singapore-based export certification specialists, and Thai waste-oil valorization pioneers. Capacity expansion and ISCC accreditation drives are the dominant competitive moves, with producers racing to secure European offtake contracts before audit backlogs lengthen.
Within the estate-integrated tier, KLK Bioenergy Sdn Bhd and PT Musim Mas exemplify producers leveraging Malaysian and Indonesian palm oil sourcing depth respectively. EcoCeres occupies a position among Singapore-based refiners commanding premium export grades through supercritical processing infrastructure. BBGI Public Company Limited represents Thai operators differentiating through domestic distribution network density and circular economy subsidy capture.
| Leading Market Players |
|---|
| EcoCeres |
| Vance Group Limited |
| Louis Dreyfus Company |
| Tristar Global |
| PT Anugerah Inti Gemanusa |
| KLK Bioenergy Sdn Bhd |
| BBGI Public Company Limited |
| PT Batara Elok Semesta Terpadu |
| PT Musim Mas |
| Others |
Value Network & Pricing Analysis
Long-term offtake contracts with Indonesian state-owned Pertamina lock in both palm oil feedstock access and price visibility for estate-integrated refiners, while spot-market processors absorb margin volatility from export levy swings. These contracted supply pools compress distributor intermediaries and concentrate procurement leverage among certified fleet operators.
Pricing Analysis
Cost-plus contracts indexed to Malaysian Palm Oil Board futures dominate Indonesian and Malaysian procurement, with ISCC-certified cargoes commanding premium spreads over uncertified grades. Price differentiation hinges on sustainability verification and volume scale, with small Thai hydrothermal operators facing compression from circular economy subsidy tiering. Pricing pressure intensifies as El Niño cycles spike feedstock costs, squeezing standalone refiners without captive estate supply. Fleet cooperatives exhibit lowest price sensitivity due to mandate compliance requirements, while industrial boiler operators demonstrate highest sensitivity to sulfur-content premiums.
Supply Chain Analysis
Indonesia and Malaysia anchor regional palm oil crushing, with Singapore refining complexes processing premium export grades. Feedstock draws from Indonesian estate networks, Malaysian oleochemical chains, and Thai waste cooking oil collectors. Single-source vulnerability concentrates in homogeneous alkaline catalyst supply from Chinese chemical producers. Distribution runs through Singapore storage terminals, Jakarta wholesale pools, and direct refiner-to-fleet contracts displacing spot intermediaries.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator consolidation through Pertamina contracted pools has shifted buyer power toward state-coordinated procurement, fragmenting spot-market access for uncertified producers.
For Market Incumbents: Shield margin position by deepening backward integration into Indonesian estate crushing infrastructure and accelerating ISCC certification timelines before audit backlogs lengthen. Prioritize captive palm oil supply chains over spot-market exposure to El Niño-driven volatility. For New Entrants and Emerging Players: Anchor in Vietnamese heavy trucking and off-grid power utilities where electrification lag sustains diesel dependence and B10-B20 penetration precedes EV infrastructure maturity. Deploy containerized hydrothermal units near Bangkok or Ho Chi Minh City to capture circular economy subsidies without estate supply dependence. For Investors and Strategic Acquirers: Capital is best deployed toward Singapore-based ISCC-certified refiners with supercritical processing capacity and European offtake relationships, positioned for sustained premium capture across the analysis window. Monitor Philippine Department of Energy mandate calibration as inflection signal for first-mover positioning.| Strategic Initiative | Industry Significance |
|---|---|
| ISCC Certification Acceleration | European offtake contracts increasingly require sustainability credentials, filtering uncertified Indonesian producers from premium export channels. |
| Backward Integration into Estates | Malaysian oleochemical-integrated processors leverage captive palm oil supply chains to compress feedstock cost volatility. |
| Hydrothermal Capacity Deployment | Thai containerized units near Bangkok bypass traditional estate infrastructure and capture circular economy subsidy tiers. |
| Direct Fleet Supply Contracts | Indonesian transport cooperatives consolidate procurement through Pertamina pools, eliminating distributor margins. |
| Waste Cooking Oil Collection Networks | Urban aggregators in Vietnamese hospitality sectors expand decentralized feedstock access for small-scale refiners. |
Research Methodology
Initial hypotheses were tested against primary input from refinery operations managers, fleet procurement directors at Indonesian transport cooperatives, Malaysian oleochemical supply chain leads, and Thai alternative energy regulators, then refined against customs trade data, Indonesian Ministry of Energy mandate filings, Malaysian Palm Oil Board production statistics, and ISCC certification registry records. Bottom-up capacity assessments triangulated with top-down demand modeling across the projection horizon.
Variance decomposition across feedstock type, production chemistry, end-use application, and distribution channel shaped analytical framework development throughout the modeling period. CAGRs were derived from segmented volume projections calibrated against mandate enforcement trajectories and estate expansion pipelines. Forecast inputs incorporated El Niño cycle probability distributions and European renewable energy directive compliance timelines.
Underlying assumptions cover Indonesian B35 mandate consistency, Malaysian B20 program expansion, and Thai subsidy tier stability, with deviation risk concentrated in palm oil export levy adjustments and ISCC audit capacity constraints. Recalibration cycles align with material shifts in national blending mandates and European offtake contract specifications.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Brazil Biofuel Market
Biofuels
Europe Biofuel Market
Biofuels
Latin America Biodiesel Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Biodiesel Market
Biofuels
United States Biodiesel Market
Biofuels
Bioethanol Market
Biofuels
Biofuel Ethanol Market
Biofuels
Second Generation Biofuels Market
Biofuels
Biofuels Market
Biofuels
Next Generation Biofuels Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Europe Biodiesel Market
Biofuels
Europe Advanced Biofuel Market