
 Next Generation Biofuels Market | 2026-2036
Next Generation Biofuels Market Size, Share, and Industry Trends Forecast 2026-2036
Next Generation Biofuels Market Intelligence
Brazilian ethanol producers is hardening their grip on cellulosic conversion capacity as harvest seasons lengthen. LanzaJet leverages alcohol-to-jet technology to anchor sustainable aviation fuel supply chains across multiple continents. Enerkem competes through municipal waste gasification platforms that convert refuse into synthetic fuels at commercial scale. Gevo specializes in isobutanol pathways that integrate with existing petroleum infrastructure, reducing retrofit costs for refiners.
Next generation biofuels comprise liquid or gaseous fuels derived from non-food feedstocks through advanced biochemical or thermochemical processes, typically achieving greenhouse-gas reductions exceeding conventional biofuels. These fuels primarily serve hard-to-decarbonize transport modes and industrial heat applications where electrification remains impractical. Cellulosic biomass feedstocks occupy the deepest margin pools due to abundant agricultural residues and limited competition with food markets. Hydroprocessing technology leads commercial deployment for renewable diesel and aviation fuel, while gasification platforms represent the fastest-growing production category as waste-to-fuel economics improve.
The US Environmental Protection Agency administers Renewable Fuel Standard volume obligations that mandate minimum advanced biofuel blending, while the EU Renewable Energy Directive sets progressively stricter greenhouse-gas intensity thresholds for transport fuels. Brazil's National Biofuels Policy regulates carbon intensity certification and social sustainability criteria for feedstock sourcing. Stakeholders must monitor blending mandate enforcement trajectories and carbon credit market liquidity to time capacity investments effectively.
Market Dynamics
Blending mandate enforcement trajectories across major economies are compressing investment timelines for cellulosic conversion capacity, forcing producers to secure feedstock contracts before technology deployment.
Growth Catalysts
- US Renewable Fuel Standard:EPA volume obligations mandate minimum advanced biofuel blending thresholds that create guaranteed offtake for cellulosic ethanol producers.
- Sustainable aviation fuel:Airlines and freight operators are scaling long-term purchase agreements that de-risk capital deployment for alcohol-to-jet technology platforms.
- Sugarcane bagasse concentration:Brazilian harvest season extensions are anchoring year-round cellulosic feedstock supply chains that reduce storage costs.
Market Restraints
- Lignocellulosic enzyme costs:Pre-treatment biocatalysts represent 25-30% of production costs and remain concentrated with specialized suppliers.
- Gasification equipment lead times:Commercial-scale syngas reactors face 18-24 month delivery cycles from a limited vendor base.
- EU greenhouse-gas intensity thresholds:RED certification requirements create compliance friction for waste-to-fuel pathways with complex feedstock provenance.
Strategic Opportunities
- Municipal solid waste streams:Urban refuse collection infrastructure in North American and European cities offers captive feedstock for thermochemical conversion platforms.
- Isobutanol blending:Drop-in compatibility with existing petroleum refining infrastructure eliminates retrofit barriers for conventional refiners.
- Brazil RenovaBio carbon credits:The National Biofuels Policy's decarbonization credit market generates additional revenue streams for certified low-carbon intensity fuels.
Industry Challenges
- Feedstock logistics coordination:Seasonal agricultural residue collection requires multi-year contracting with dispersed farming operations.
- ASTM D7566 certification timelines:Sustainable aviation fuel pathway approvals demand 12-18 months of engine testing and data submission.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Next Generation Biofuels Market |
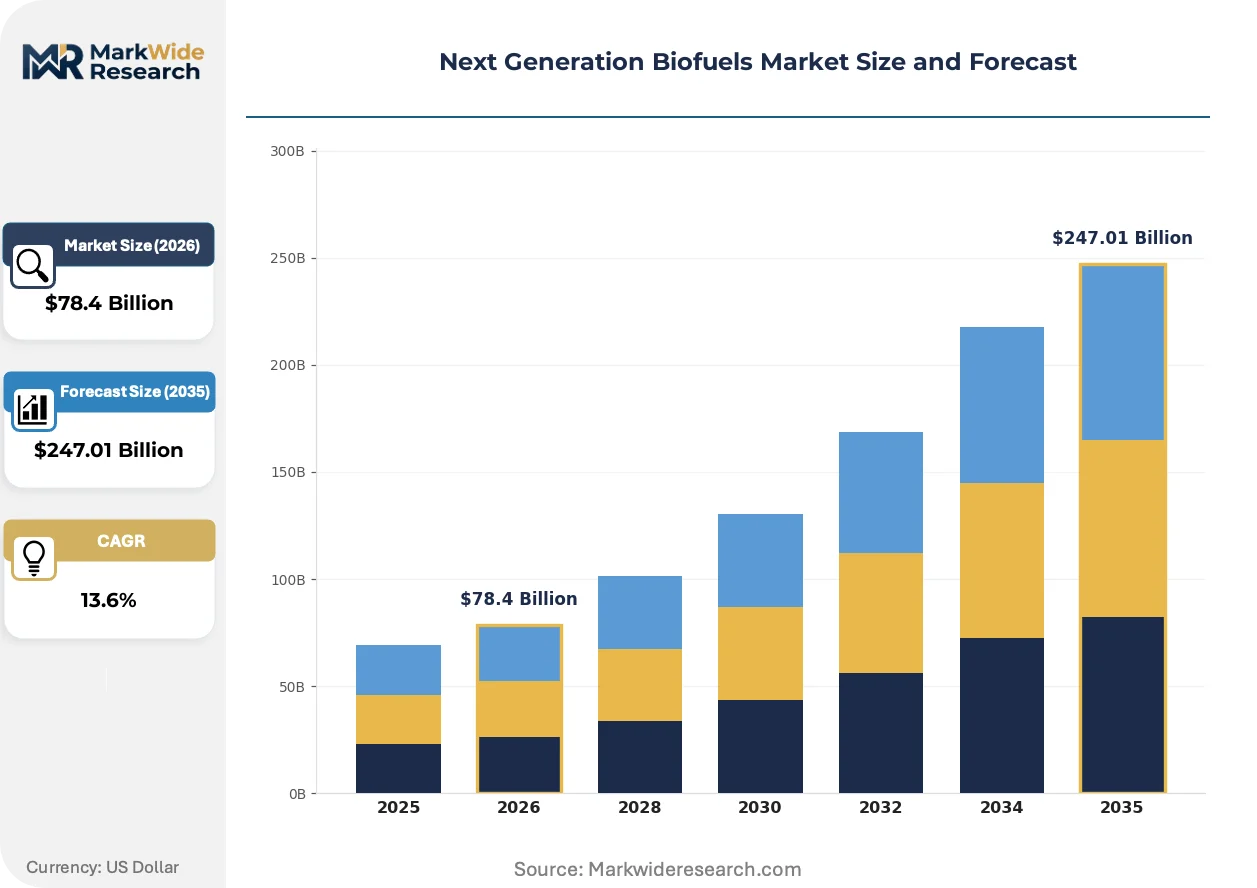
| Market Size in 2026 | $78.4 Billion |
| Market Size in 2035 | $247.01 Billion |
| CAGR (2026 – 2036) | 13.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Crops, Waste Oils, Algae, Cellulosic Biomass Production Technology: Fermentation, Gasification, Hydroprocessing, Pyrolysis End Use Application: Transportation, Power Generation, Heating, Industrial Distribution Channel: Direct Sales, E-commerce, Retail, Bulk Supply |
| Companies Covered | Aemetis, LanzaJet, LanzaTech, Woodland Biofuels, GranBio, Infinium, Enerkem, Avioxx, Gevo, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Next Generation Biofuels Market Strategic Shifts & Innovations
Process intensification and digital control systems are compressing unit economics for advanced biofuel pathways while regulatory compliance automation reduces certification burdens.
Continuous enzymatic hydrolysis systems are automating biomass pre-treatment operations that previously required batch-wise intervention. Cellulosic ethanol producers in the US Midwest and Brazilian Center-West are retrofitting first-generation facilities with continuous flow reactors. This automation is reducing labor intensity and enabling real-time quality adjustments that stabilize fermentation yields.
The EU Renewable Energy Directive's tightening greenhouse-gas intensity thresholds are forcing fuel suppliers to document full lifecycle emissions across supply chains. Refiners must now integrate feedstock traceability systems that track carbon intensity from cultivation to combustion. Hard-to-abate transport sectors including maritime and aviation are responding by locking in decade-long offtake agreements with certified low-carbon fuel producers.
Airlines are consolidating procurement through direct partnerships with technology licensors rather than trading intermediaries. This disintermediation concentrates volume commitments with platforms demonstrating commercial-scale production. European and North American carriers are leading this shift, with freight operators following as container shipping lines face parallel decarbonization pressures from the International Maritime Organization.
Next Generation Biofuels Market Segmentation
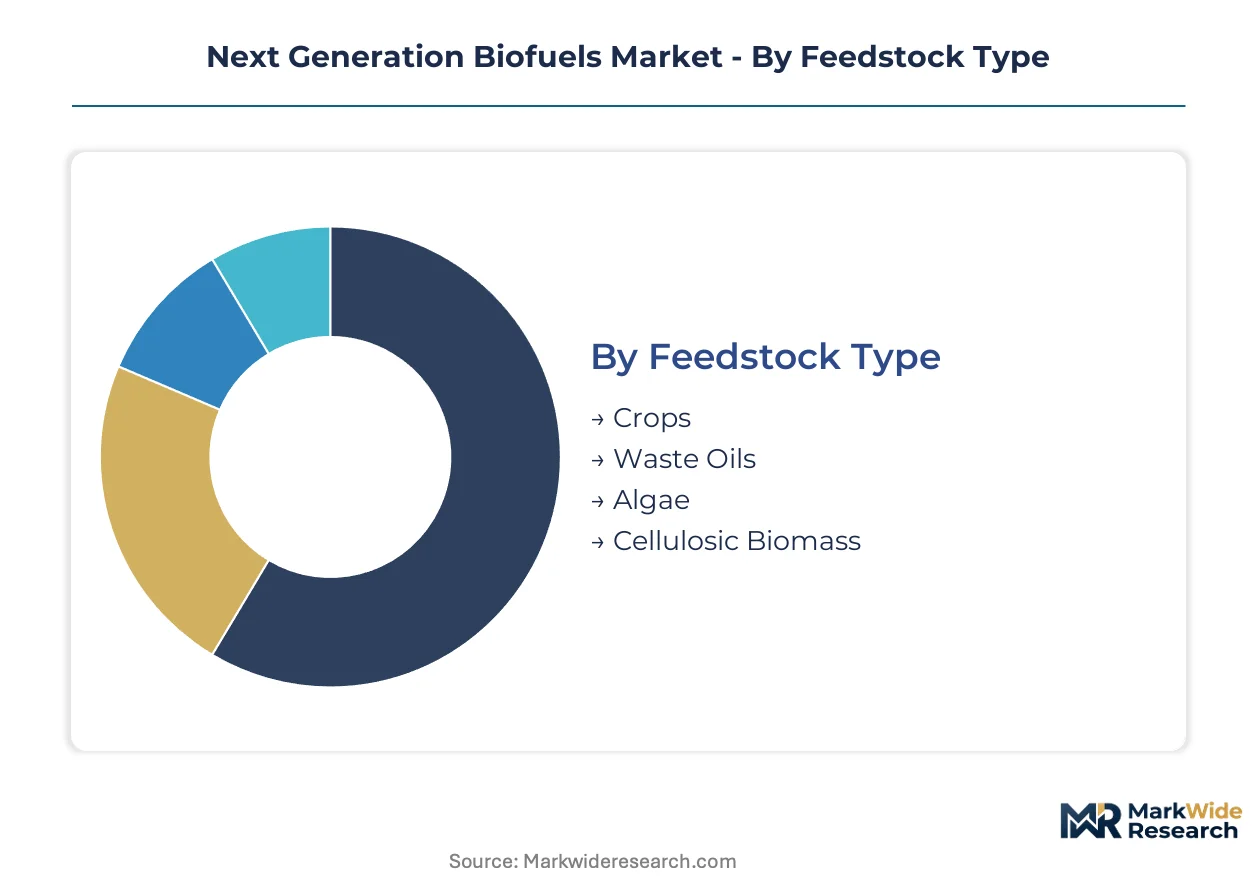
Feedstock chemistry and conversion pathway economics determine competitive positioning across next generation biofuels. Producers optimize segment mix against carbon intensity certification requirements and regional blending mandate structures.
Feedstock Type:
Standalone fuel production relies on dedicated energy crops and cultivated algae, while embedded systems leverage waste streams and agricultural residues integrated with existing operations.
- Cellulosic Biomass:Agricultural residues including corn stover, wheat straw, and sugarcane bagasse supply lignocellulosic material requiring enzymatic pre-treatment. Brazilian Center-West processors and US Midwest biorefineries concentrate demand here as harvest season extensions reduce storage infrastructure requirements.
- Waste Oils:Used cooking oil, animal fats, and tallow feed hydroprocessing units for renewable diesel and sustainable aviation fuel. European collectors and North American rendering facilities anchor supply chains as the EU Renewable Energy Directive tightens greenhouse-gas intensity thresholds for transport fuels.
- Crops:Dedicated energy crops including switchgrass and miscanthus provide consistent feedstock quality for thermochemical conversion.
- Algae:Photosynthetic microorganisms cultivated in open ponds or photobioreactors offer high lipid content per acre with minimal land competition.
Cellulosic biomass leads volumes today; waste oils are gaining share fastest.
Production Technology:
Cost tier stratification separates mature hydroprocessing platforms from emerging thermochemical pathways still scaling toward commercial parity.
- Hydroprocessing:Catalytic hydrogenation of triglycerides and fatty acids produces drop-in renewable diesel and aviation fuel meeting ASTM D7566 specifications. US Gulf Coast refiners and European integrated oil companies dominate deployment as retrofits of existing hydrotreating units minimize capital intensity.
- Gasification:High-temperature partial oxidation converts solid feedstocks into synthesis gas for Fischer-Tropsch synthesis or methanol-to-jet pathways. Municipal waste processors in North American and European cities concentrate demand here as landfill diversion regulations tighten feedstock availability.
- Fermentation:Microbial conversion of C5 and C6 sugars yields cellulosic ethanol requiring organism engineering for inhibitor tolerance.
- Pyrolysis:Thermal decomposition in oxygen-limited environments produces bio-oil requiring extensive upgrading for fuel applications.
Hydroprocessing leads volumes today; gasification is expanding most quickly.
End Use Application:
Application concentration varies by decarbonization urgency, with hard-to-abate transport modes commanding premium pricing against electrification constraints.
- Transportation:Aviation, maritime, and heavy-duty road freight absorb the majority of next generation biofuel offtake as battery-electric alternatives face weight and range limitations. Airlines under EU Emissions Trading System compliance pressure and freight operators facing International Maritime Organization targets concentrate procurement through direct technology partnerships.
- Industrial:High-temperature process heat in cement, steel, and chemicals production utilizes bio-based fuels where electrification remains technically challenging. European industrial clusters and North American manufacturing corridors anchor demand as carbon border adjustment mechanisms reshape fuel economics.
- Power Generation:Stationary combustion turbines and reciprocating engines integrate liquid biofuels for grid stability and remote generation.
- Heating:Residential and commercial building thermal applications compete directly with heat pump electrification and renewable natural gas.
Transportation leads volumes today; industrial is climbing the fastest.
Distribution Channel:
Customer type determines channel structure, with volume buyers accessing direct supply arrangements while fragmented demand relies on intermediated distribution.
- Bulk Supply:Pipeline injection, barge, and railcar deliveries serve refiners, blenders, and large fleet operators requiring continuous offtake. US Renewable Fuel Standard obligated parties and EU fuel suppliers concentrate procurement here as Renewable Identification Number and certificate tracking demands integrated logistics.
- Direct Sales:Long-term offtake agreements between technology licensors and end-users eliminate trading intermediaries. Airlines and container shipping lines anchor this channel as they consolidate procurement through direct partnerships rather than commodity traders.
- Retail:Branded fuel stations and consumer-facing networks distribute blended products to light-duty vehicle markets.
- E-commerce:Digital platforms facilitate spot transactions and certificate trading for compliance buyers.
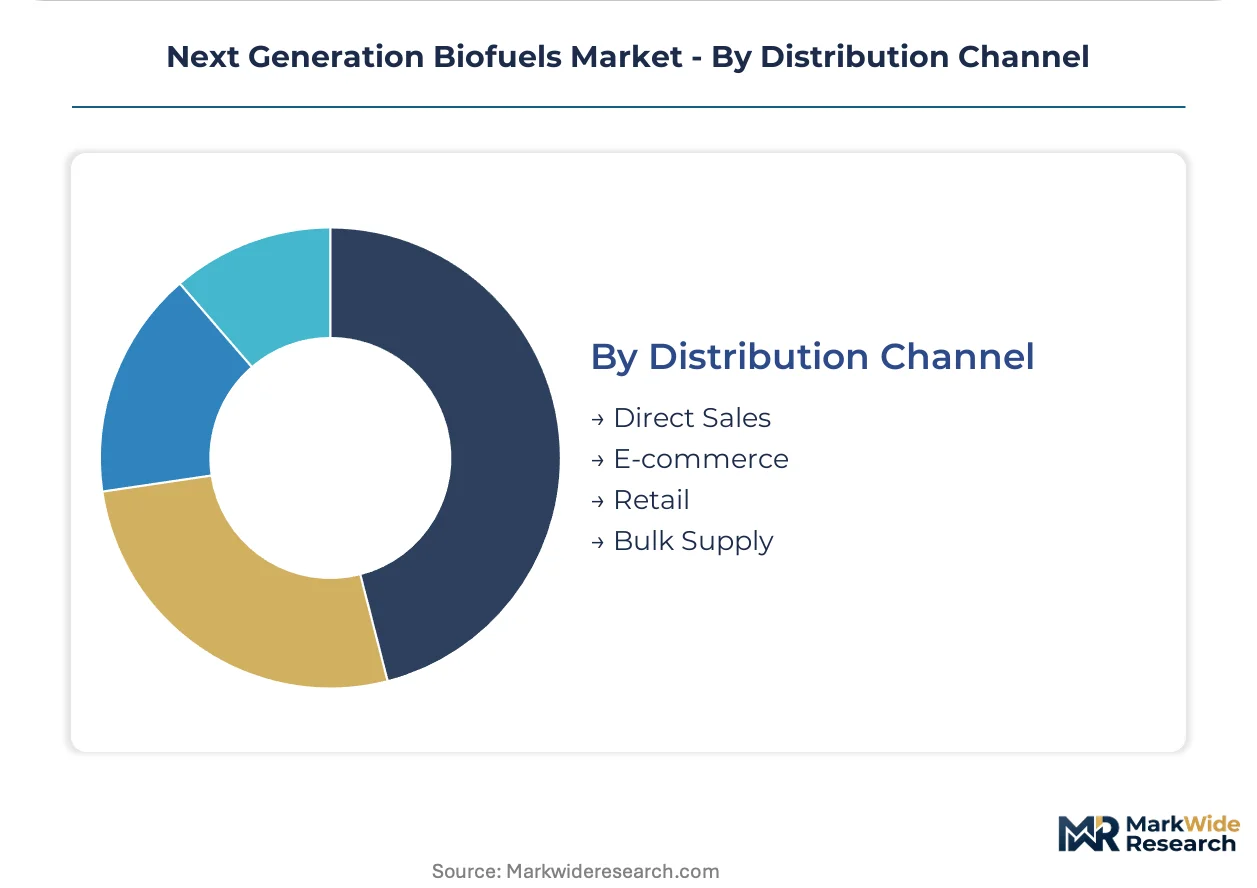
Bulk supply leads volumes today; direct sales are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazil commands cellulosic ethanol capacity through sugarcane bagasse integration, while the United States drives sustainable aviation fuel deployment via alcohol-to-jet technology licensing. Policy divergence between these markets shapes capital allocation timelines for advanced biofuel producers.
United States
Airlines under EPA Renewable Fuel Standard obligations are consolidating decade-long offtake agreements with alcohol-to-jet technology licensors. The EPA administers volume obligations that mandate minimum advanced biofuel blending thresholds. US Gulf Coast refiners anchor hydroprocessing capacity for renewable diesel and sustainable aviation fuel production.
Brazil
Ethanol producers in the Center-West region are retrofitting first-generation facilities with continuous flow reactors for cellulosic conversion. ANVISA, the national health regulator, oversees industrial chemical safety standards for biorefinery operations. São Paulo state processors leverage harvest season extensions to reduce feedstock storage infrastructure requirements.
Germany
Integrated oil companies dominate renewable diesel deployment as retrofits of existing hydrotreating units minimize capital intensity. The EU Renewable Energy Directive sets progressively stricter greenhouse-gas intensity thresholds for transport fuels. Industrial clusters in North Rhine-Westphalia concentrate hydroprocessing capacity for waste oils conversion.
Canada
Municipal waste processors in Ontario and Quebec are deploying gasification platforms as landfill diversion regulations tighten feedstock availability. Health Canada and PMRA administer environmental and agricultural chemical standards affecting biorefinery operations. Enerkem anchors commercial-scale syngas production from urban refuse collection infrastructure.
United Kingdom
Freight operators facing International Maritime Organization decarbonization targets are locking in long-term purchase agreements with certified low-carbon fuel producers. The UK Environment Agency enforces industrial emissions standards for thermochemical conversion facilities. London-based airlines are consolidating procurement through direct technology partnerships rather than commodity traders.
Next Generation Biofuels Market Key Industry Players
Brazilian producers anchor one tier through sugarcane bagasse integration; US specialists hold another via alcohol-to-jet technology platforms. The market structure stratifies between integrated energy companies with refinery retrofits and pure-play technology licensors with proprietary conversion pathways. Two archetypes dominate: hydroprocessing retrofits of existing petroleum infrastructure, and standalone thermochemical platforms for waste-to-fuel conversion. Capacity expansion and strategic partnerships represent the dominant competitive moves as producers secure feedstock contracts before technology deployment.
Within the technology licensor tier, LanzaJet and LanzaTech exemplify platforms leveraging alcohol-to-jet and gas fermentation pathways respectively. Enerkem occupies a position among municipal waste gasification specialists converting refuse into synthetic fuels. These three companies represent distinct strategic archetypes: sustainable aviation fuel supply chain anchoring, carbon capture and utilization integration, and urban waste stream valorization for circular fuel production.
| Leading Market Players |
|---|
| Aemetis |
| LanzaJet |
| LanzaTech |
| Woodland Biofuels |
| GranBio |
| Infinium |
| Enerkem |
| Avioxx |
| Gevo |
| Others |
Cost & Logistics Intelligence
Hydroprocessing retrofits of existing petroleum infrastructure are compressing capital requirements for renewable diesel producers while simultaneously concentrating margin capture among integrated refiners with captive hydrogen supply. This technology transition rewards players with existing hydrotreating assets in the US Gulf Coast and German industrial clusters, squeezing standalone cellulosic ethanol operators on feedstock procurement economics.
Pricing Analysis
Capacity additions in Brazil and the United States are reshaping price floors for cellulosic ethanol as harvest season extensions reduce storage cost premiums. Contract-based long-term offtake agreements dominate, with price differentiation hinging on carbon intensity certification tier under the EU Renewable Energy Directive and volume scale commitments from airlines. Cost compression in fermentation pathways is intensifying because lignocellulosic enzyme suppliers retain pricing power. Freight operators exhibit the highest price sensitivity due to thin shipping margins, while aviation carriers under EU Emissions Trading System compliance pressure accept certified low-carbon fuel premiums.
Supply Chain Analysis
Regional distribution centers in São Paulo state and the US Midwest anchor hub-and-spoke patterns for agricultural residue collection, with satellite storage facilities reducing transport radius requirements. Feedstock supply concentrates in Brazil, the United States, and Canada, with Brazilian sugarcane bagasse and North American corn stover feeding distinct conversion pathways. The supply chain draws from specialized enzyme suppliers, gasification equipment vendors with extended lead times, and municipal waste collection infrastructure. Single-source vulnerability around thermochemical reactor fabrication creates bottleneck risk. Distribution runs through bulk pipeline injection and barge networks serving obligated parties under the US Renewable Fuel Standard.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The next generation biofuels market functions as a regulatory compounder, with the EU Renewable Energy Directive's tightening greenhouse-gas intensity thresholds forcing fuel suppliers into certified low-carbon procurement that locks in demand visibility for compliant producers.
For Market Incumbents: To counter emerging alcohol-to-jet technology licensors capturing airline offtake through direct partnerships, integrated refiners should accelerate hydroprocessing retrofits of existing hydrotreating assets in the US Gulf Coast and German industrial clusters. Securing multi-year municipal solid waste contracts in North American and European cities before gasification platform deployment represents critical feedstock control. Certification investment under Brazil's RenovaBio carbon credit system generates incremental revenue streams that pure-play technology licensors cannot replicate. For New Entrants and Emerging Players: Begin with isobutanol pathway development targeting drop-in compatibility with existing petroleum refining infrastructure, eliminating retrofit barriers that slow customer adoption. Municipal waste gasification in Ontario and Quebec offers the most penetrable geography as landfill diversion regulations tighten feedstock availability and Enerkem's commercial-scale demonstration reduces technology risk perception. Direct sales channel entry through long-term offtake negotiations with container shipping lines facing International Maritime Organization decarbonization targets bypasses commodity trader intermediation. For Investors and Strategic Acquirers: Valuations sit cheapest among pure-play cellulosic ethanol operators in the Brazilian Center-West region, where harvest season extensions have improved unit economics but capital markets underappreciate the operational de-risking. The five-to-ten year viability window favors technology licensors with demonstrated commercial-scale production and ASTM D7566 pathway approvals over pre-revenue thermochemical platforms. Watch carbon credit market liquidity under Brazil's National Biofuels Policy as the inflection signal for capacity investment timing.| Strategic Initiative | Industry Significance |
|---|---|
| Capacity Buildout | Retrofitting first-generation Brazilian facilities with continuous flow reactors anchors year-round cellulosic supply. |
| Technology Licensing | Alcohol-to-jet platforms from LanzaJet concentrate airline procurement through direct partnerships rather than traders. |
| Long-term Supply Agreement | Decade-long offtake contracts with freight operators de-risk capital deployment for gasification platforms. |
| Backward Integration | Captive sugarcane bagasse supply chains in São Paulo state reduce storage infrastructure requirements. |
| Green Certification Program | EU Renewable Energy Directive compliance documentation enables premium pricing for certified low-carbon fuels. |
Research Approach
Coverage spans North America, Brazil, and Western Europe, with primary inputs from each region combined with secondary validation across regulatory filings and trade databases. The research draws from interviews with biorefinery operations managers, airline fuel procurement officers, EPA regulatory affairs specialists, and municipal waste collection coordinators. Secondary sources include EPA Renewable Fuel Standard volume obligation filings, EU Renewable Energy Directive implementation reports, ANVISA industrial chemical safety standards, and Brazil's National Biofuels Policy certification databases. Bottom-up capacity installation tracking and top-down fuel demand modeling were triangulated against carbon intensity certification flows.
Granularity-level modeling operated at the conversion pathway-technology tier, with separate projections for hydroprocessing, gasification, fermentation, and pyrolysis platforms across feedstock chemistry categories. Segmentation dimensions included feedstock type, production technology, end-use application, and distribution channel structure, with additional modeling for regional regulatory framework clusters. CAGRs were derived from installed capacity buildout schedules, blending mandate enforcement trajectories, and carbon credit market development assumptions. Key forecast inputs encompassed ASTM D7566 certification timeline distributions and harvest season extension trends in Brazilian sugarcane regions.
Several conditions sit outside the modeled scope, including breakthrough catalyst innovations that could displace enzymatic pre-treatment, geopolitical disruptions to agricultural residue trade flows, and step-change reductions in electrolytic hydrogen costs that would reshape hydroprocessing economics. Forecasts reflect documented assumptions around policy continuity for the US Renewable Fuel Standard and EU Renewable Energy Directive. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Europe Biofuel Market
Biofuels
Second Generation Biofuels Market
Biofuels
Brazil Biofuel Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Biodiesel Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Latin America Biodiesel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Biofuel Ethanol Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Biofuels Market
Biofuels
Bioethanol Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
United States Biodiesel Market
Biofuels
Global Advanced Biofuel Market