
 Home Solar Energy Storage Battery Market | 2026-2036
Home Solar Energy Storage Battery Market Size, Share, and Industry Trends Forecast 2026-2036
Home Solar Energy Storage Battery Market Insights
Lithium iron phosphate is repositioning home battery economics away from nickel-cobalt-manganese chemistries by slashing thermal runaway risk and raw material exposure. Tesla leverages its integrated Powerwall ecosystem and Supercharger-adjacent software to dominate the North American installer channel. BYD Company anchors its position through captive cell production and aggressive cost engineering across the Asia-Pacific residential segment. LG Energy Solution differentiates via cylindrical cell expertise inherited from automotive programs, sustaining premium positioning in European markets.
Home solar energy storage batteries are electrochemical systems designed to store photovoltaic-generated DC power for later discharge as AC electricity through bidirectional inverters, typically achieving round-trip efficiencies of 85-95% and cycle lifetimes exceeding 6,000 charges. These systems buffer intermittency from rooftop solar arrays, enabling households to shift self-generated power to evening peak-rate periods or maintain critical loads during grid outages. Lithium-ion products command the dominant share of installed capacity due to declining cell costs and established manufacturing scale, while flow batteries occupy a narrow niche in large-capacity off-grid applications where extended duration and fire safety outweigh footprint penalties. The 10 kWh capacity tier captures the bulk of residential demand as it aligns with average daily household consumption patterns and inverter compatibility standards.
FERC Order 2222 in the United States enables aggregated distributed energy resources to participate in wholesale markets, reshaping revenue stacking opportunities for storage-equipped homes. The EU Green Deal and national building performance standards across Germany, Italy, and Spain mandate renewable integration in renovations, directly stimulating storage attachment rates. Australia's state-level battery rebate programs and virtual power plant frameworks create regulated demand pools that manufacturers must navigate for market access. Stakeholders should monitor how evolving grid interconnection standards and dynamic tariff designs alter the value proposition of storage versus standalone solar across their target geographies.
Market Dynamics
Lithium iron phosphate chemistry is restructuring competitive economics by collapsing thermal runaway risk and decoupling manufacturers from volatile nickel-cobalt supply chains. This chemistry migration concentrates production investment in cell facilities serving residential storage, altering how battery pack assemblers source cathode materials.
Growth Catalysts
- FERC Order 2222:Aggregated distributed energy resources gain wholesale market participation rights in the United States. Residential battery owners stack revenue streams beyond self-consumption.
- German building performance standards:National renovation mandates under the EU Green Deal require renewable integration. Storage attachment rates climb as contractors bundle batteries with rooftop solar retrofits.
- Virtual power plant frameworks:Australian state-level programs create regulated demand pools. Manufacturers secure market access through utility partnership channels.
Market Restraints
- Lithium carbonate volatility:Raw material price swings compress pack assembler margins. Contract structures struggle to pass through input cost fluctuations to residential buyers.
- Cell production concentration:Cylindrical and prismatic cell supply clusters in East Asian manufacturing hubs. Geographic concentration risk elevates for European and North American pack integrators.
- Round-trip efficiency ceiling:Lithium-ion electrochemistry approaches theoretical limits near 95%. Further gains require system-level inverter optimization rather than cell improvements.
Strategic Opportunities
- Italian residential retrofits:Superbonus tax incentives expire but transition to structured renovation financing. Storage penetration lags Germany, creating white space for mid-tier capacity products.
- Solar-plus-storage microgrids:Off-grid applications in rural Australia and Texas ranchland converge photovoltaic generation with extended-duration lithium iron phosphate banks.
- Installer certification programs:NABCEP credentialing and state electrical licensing create channel control points. Manufacturers capture margin by training captive installer networks.
Industry Challenges
- Electrochemical engineering talent scarcity:Cell characterization and battery management system firmware development require specialized expertise. Universities produce insufficient graduates for residential storage demand.
- Interconnection queue delays:Utility approval timelines for behind-the-meter storage stretch 6-18 months in California and Hawaii. Customer acquisition costs inflate as installers absorb prolonged project cycles.
- Legacy inverter compatibility:Retrofit installations face AC coupling complexity with existing string inverters. Integration engineering consumes technical support resources.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Home Solar Energy Storage Battery Market |
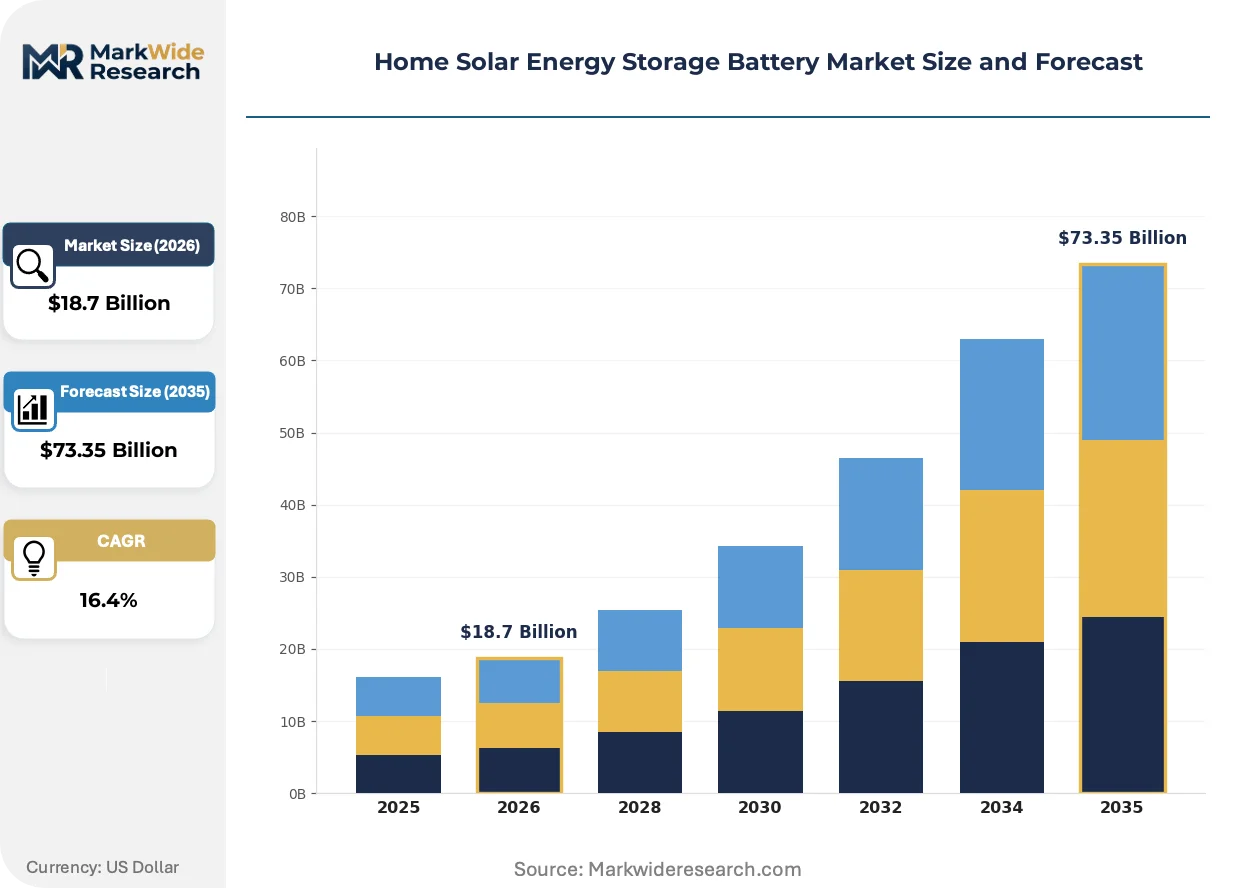
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $73.35 Billion |
| CAGR (2026 – 2036) | 16.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Lithium-ion, Lead-acid, Flow Batteries, Nickel-based Capacity: 5 kWh, 10 kWh, 15 kWh, 20 kWh Installation: Indoor, Outdoor, Wall-mounted, Ground-mounted End User: Residential, Small Business, Off-grid, Urban |
| Companies Covered | Tesla, BYD Company, Panasonic Holdings Corporation, LG Energy Solution, Sonnen GmbH, CATL, Samsung SDI, Pylontech, SMA Solar Technology, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Home Solar Energy Storage Battery Market Trends and Innovations
Solid-state cell architectures and silicon-anode formulations are approaching commercial viability for residential packs. These innovations promise energy density gains that compress footprint requirements for suburban installation sites.
Silicon-anode blending is electrifying next-generation lithium-ion cell design by replacing graphite with higher-capacity silicon composites. Residential buyers in space-constrained urban markets adopt these packs despite premium positioning. The technology is electrifying installer channel preferences toward slimmer wall-mounted form factors.
The EU F-Gas Regulation phases down hydrofluorocarbon use in thermal management systems. Battery manufacturers reformulate cooling loops with CO2 or propane refrigerants. European pack assemblers face compliance deadlines that accelerate redesign cycles for 2027 product lines.
Homeowners increasingly self-direct equipment procurement through online marketplaces rather than turnkey installer quotes. This channel shift fragments customer acquisition and elevates manufacturer brand recognition requirements. The pattern concentrates in California and Australia where solar literacy rates exceed other markets.
Home Solar Energy Storage Battery Market Segmentation
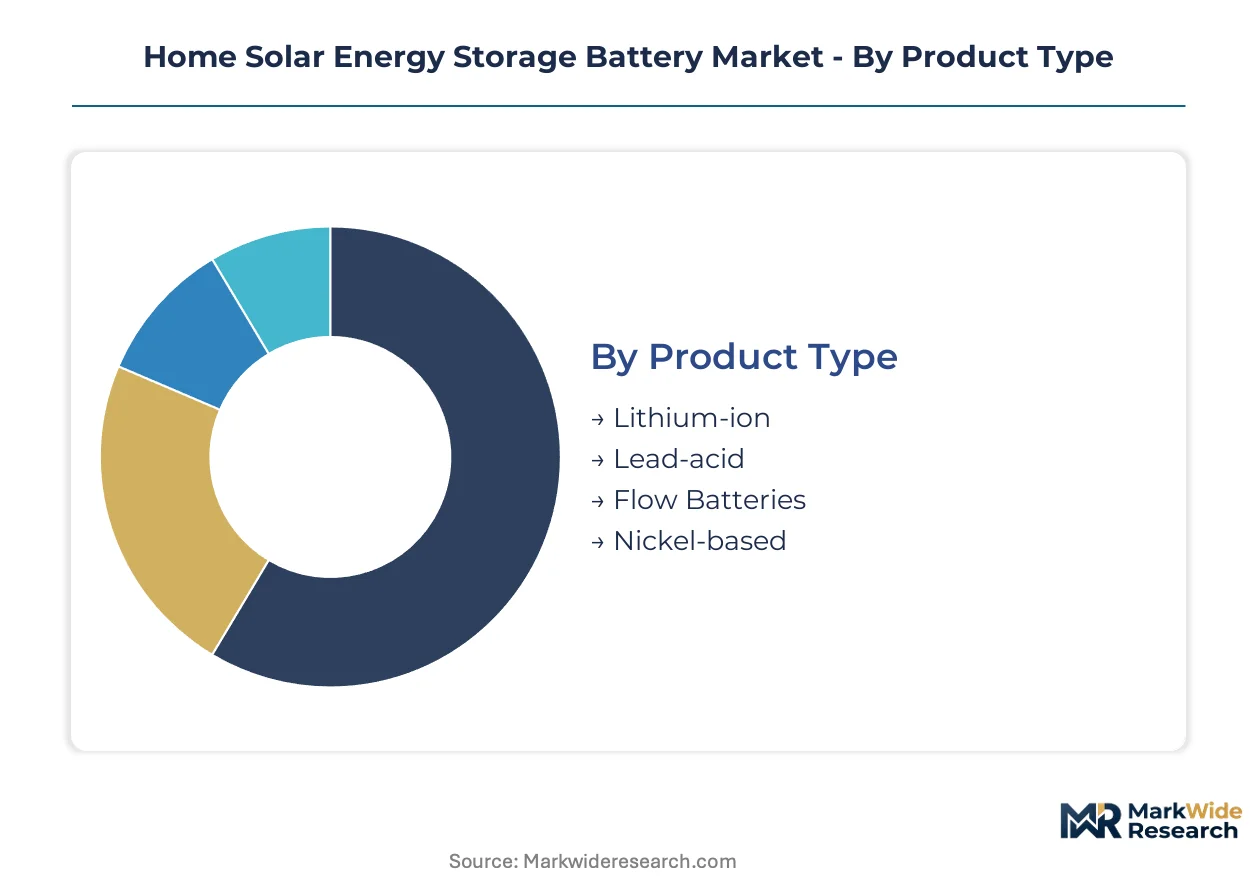
Home solar energy storage batteries fragment across electrochemical chemistries, capacity tiers, mounting configurations, and user archetypes. Each segmentation axis carries distinct margin profiles, installation complexity, and regulatory exposure that manufacturers must navigate for portfolio positioning.
Product Type:
Lithium iron phosphate chemistry is repositioning product economics by collapsing thermal runaway risk and decoupling manufacturers from volatile nickel-cobalt supply chains.
- Lithium-ion:Lithium iron phosphate cells dominate residential packs due to 6,000+ cycle lifetimes and superior thermal stability versus nickel-cobalt-manganese alternatives. Demand concentrates in Germany, Australia, and the United States where feed-in tariff reductions incentivize self-consumption optimization.
- Lead-acid:Flooded and absorbed glass mat variants persist in price-sensitive rural installations and backup-only applications where cycle frequency remains low. Sub-Saharan African off-grid clusters and Southeast Asian island communities sustain residual demand despite lithium-ion cost convergence.
- Flow Batteries:Vanadium redox systems occupy extended-duration niches above 8-hour discharge requirements, typically in large rural properties with seasonal storage needs.
- Nickel-based:Nickel-metal hydride retains marginal presence in legacy Japanese residential retrofits where existing inverter compatibility constrains chemistry migration.
Lithium-ion leads on scale; flow batteries lead on momentum in duration-extended applications.
Capacity:
Capacity selection directly determines inverter pairing, installation labor, and utility interconnection pathways across residential applications.
- 5 kWh:Compact modules serve apartment balconies and small rooftop arrays in Tokyo and Singapore where space constraints dominate. German mini-storage subsidies and Australian state rebate thresholds sustain demand despite limited whole-home backup duration.
- 10 kWh:The standard residential tier aligns with average daily household consumption patterns and single-phase inverter compatibility across North American and European markets. California's SGIP incentive structure and Italy's Superbonus tax credits target this capacity band specifically.
- 15 kWh:Larger homes with electric vehicle charging loads and pool equipment in Texas and Arizona adopt this tier for peak-shaving economics under time-of-use rate structures.
- 20 kWh:Estate properties and small commercial adjacencies in rural Australia and Colorado ranchland deploy these systems for multi-day off-grid autonomy.
Ten kWh configurations anchor volume deployment; fifteen kWh systems are climbing the fastest as electrification loads expand.
Installation:
Mounting topology shapes thermal management engineering, electrical code compliance, and installer certification requirements.
- Indoor:Garage and utility room placements dominate in cold climates where battery chemistry performance degrades below freezing. Canadian and Nordic markets mandate indoor siting for warranty compliance.
- Outdoor:NEMA 3R and IP65 enclosures enable backyard and side-yard placement in mild-climate regions. Australian and Californian suburban installations favor outdoor siting to preserve garage space.
- Wall-mounted:Slim form factors reduce footprint in dense urban environments. Tokyo condominium retrofits and London terrace house installations drive demand for sub-150mm depth profiles.
- Ground-mounted:Pad-mounted cabinets serve large-capacity systems and properties with limited structural wall capacity. Texas and Arizona desert installations favor ground mounting for passive cooling.
Wall-mounted systems lead on scale; outdoor configurations are gaining share fastest as suburban electrification accelerates.
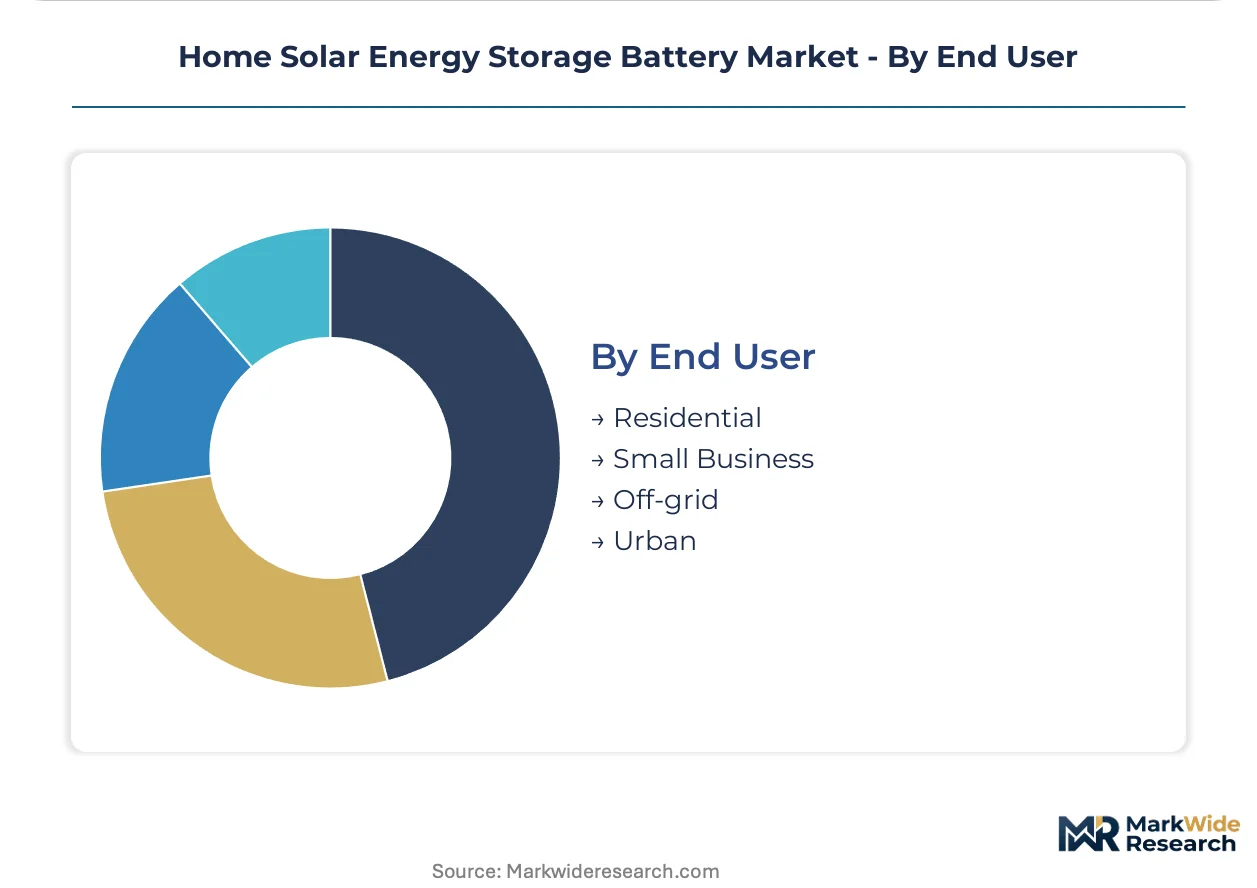
End User:
User archetype determines financing mechanisms, regulatory incentive eligibility, and grid services participation frameworks.
- Residential:Single-family homeowners with rooftop solar represent the core demand pool across all major markets. FERC Order 2222 aggregation rights and Australian virtual power plant frameworks create revenue stacking opportunities.
- Small Business:Retail storefronts and professional offices with behind-the-meter solar adopt storage for demand charge management. California and New York commercial rate structures incentivize this segment specifically.
- Off-grid:Rural properties beyond utility service territory rely on solar-plus-storage microgrids. Australian cattle stations and Texas ranchland converge photovoltaic generation with lithium iron phosphate banks for extended autonomy.
- Urban:Multi-unit dwelling residents face split-incentive barriers and limited roof rights. Berlin and Vancouver co-housing developments pioneer shared battery models through strata governance structures.
Residential households anchor volume; off-grid applications are expanding most quickly as grid extension costs escalate.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
German installer networks and Australian state rebate programs anchor residential storage deployment volumes. National regulators reshape interconnection economics through wholesale market participation rules and building renovation mandates.
United States
Time-of-use rate structures in California and Texas drive peak-shaving economics for suburban households. FERC Order 2222 enables aggregated distributed energy resources to access wholesale revenue streams. Installer certification programs through NABCEP concentrate channel control in the California-Arizona corridor.
Germany
Feed-in tariff reductions since 2021 have redirected rooftop solar economics toward self-consumption maximization. The EU Green Deal mandates renewable integration in building renovations under national performance standards. Bavarian and Baden-Württemberg installer clusters bundle storage retrofits with heat pump conversions.
Australia
State-level battery rebate programs in Victoria and South Australia create regulated demand pools with standardized product eligibility. Virtual power plant frameworks through AEMO enable residential aggregation for frequency control services. Queensland cattle stations deploy solar-plus-storage microgrids where grid extension costs exceed standalone system economics.
Italy
Superbonus tax incentives transition toward structured renovation financing as 110% rates expire. Storage attachment rates lag German benchmarks, creating white space for mid-tier capacity products. Lombardy and Veneto contractors pilot battery-solar-heat pump bundles under revised ecobonus schemes.
Japan
Tokyo condominium retrofits drive demand for sub-150mm depth wall-mounted form factors. METI residential storage subsidies target post-FIT households seeking energy independence. Kansai region installers specialize in AC-coupled retrofits compatible with legacy string inverter infrastructure.
Home Solar Energy Storage Battery Market Competitive Landscape
Global majors compete with regional champions across installer channel access and software integration depth. The vendor base stratifies into three tiers: integrated automotive spin-offs with captive cell supply, dedicated residential specialists with utility partnership frameworks, and contract manufacturers serving price-sensitive emerging markets. Strategic moves concentrate on installer certification program sponsorship and virtual power plant software licensing.
Among the integrated tier, Tesla and BYD Company exemplify divergent geographic positioning strategies. Tesla anchors North American channel control through Supercharger-adjacent software ecosystems. BYD Company occupies a position in Asia-Pacific residential segments through cost-engineered product architectures. LG Energy Solution sits within the premium European positioning tier, leveraging cylindrical cell expertise inherited from automotive programs.
| Leading Market Players |
|---|
| Tesla |
| BYD Company |
| Panasonic Holdings Corporation |
| LG Energy Solution |
| Sonnen GmbH |
| CATL |
| Samsung SDI |
| Pylontech |
| SMA Solar Technology |
| Others |
Pricing and Supply Chain Analysis
German rooftop solar retrofit mandates under the EU Green Deal are forcing battery pack assemblers to source lithium iron phosphate cells from qualified suppliers, compressing procurement timelines and elevating pricing power among certified cathode material producers.
Pricing Analysis
Input-cost pass-through from lithium carbonate volatility runs through residential battery pricing, with contract structures struggling to fully transmit raw material swings to end buyers. Three-tier pricing structure across premium, standard, and economy levels separates Tesla and LG Energy Solution's software-integrated offerings from BYD's cost-engineered packs and white-label contract manufacturers. Pricing pressure stems from lithium carbonate spot market gyrations, squeezing pack assembler margins most acutely in the economy tier. Small business and off-grid segments exhibit highest price sensitivity, while premium residential buyers absorbing whole-home backup premiums show least elasticity.
Supply Chain Analysis
Workforce availability constraints in Chinese and South Korean cylindrical cell facilities are tightening output allocation for residential storage packagers. Cathode active material production clusters in China, cathode precursor refining in Indonesia, and separator manufacturing in Japan form the upstream backbone. Supply chain risk centers on single-source vulnerability for high-purity lithium hydroxide feedstock. Distribution runs through NABCEP-certified installer networks in California and utility partnership channels in Australian state markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market offers margin expansion through lithium iron phosphate chemistry migration collapsing thermal runaway remediation costs and enabling premium positioning for safety-certified products.
For Market Incumbents: Anchor channel control through captive installer certification programs in California and Victoria, defending against emerging Chinese contract manufacturers penetrating price-sensitive segments via direct-to-consumer marketplaces. Deepen backward integration into cathode active material production to decouple from lithium carbonate spot exposure. For New Entrants and Emerging Players: Enter via Italian residential retrofits where Superbonus transition creates white space for mid-tier 10-15 kWh capacity products lacking established local incumbents. Target Lombardy and Veneto contractor networks with AC-coupled retrofit compatibility for legacy string inverter infrastructure. For Investors and Strategic Acquirers: Asymmetric upside sits with cylindrical cell specialists possessing automotive program heritage and residential storage software integration capabilities. Five-to-ten year viability hinges on virtual power plant aggregation platform ownership. Monitor FERC Order 2222 implementation pace across US ISO territories as inflection indicator for revenue-stacking monetization.| Strategic Initiative | Industry Significance |
|---|---|
| Cell Chemistry Migration | Lithium iron phosphate adoption collapses thermal runaway risk and raw material cost volatility for residential packs. |
| Installer Certification Sponsorship | NABCEP program capture locks channel access in California-Arizona corridor against emerging competitors. |
| Virtual Power Plant Software Licensing | AEMO aggregation frameworks in Australia create recurring revenue streams beyond hardware sales. |
| Backward Integration into Cathode Materials | In-house lithium iron phosphate production insulates margins from carbonate spot market swings. |
| AC-Coupled Retrofit Compatibility | Legacy string inverter integration opens Japanese and European replacement markets with minimal channel buildout. |
Research Methodology
Bottom-up residential household modeling reconciled against top-down cell production tracking forms the analytical core. Primary interviews with utility planning officers, NABCEP-certified installers, battery pack engineering directors, and virtual power plant software architects combined with secondary validation from EIA deployment data, IEA technology roadmaps, FERC Order 2222 dockets, and Australian state rebate program disclosures. Cross-referencing installer channel surveys against cathode material trade flows enables demand-supply reconciliation.
Input-output matrix framing connects lithium iron phosphate cell capacity expansion to rooftop solar attachment rate assumptions across the analysis window. Segmentation dimensions span electrochemical chemistry, capacity tier, mounting configuration, and end-user archetype. CAGRs derive from fitted adoption curves against historical German and Australian deployment trajectories. Forecast inputs incorporate feed-in tariff reduction schedules and time-of-use rate structure evolution.
Inputs from AEMO virtual power plant enrollment databases and California SGIP incentive disbursement records were available through the study window; gaps in real-time installer inventory positioning introduce uncertainty bands around near-term deployment velocity. Forecasts reflect assumptions on interconnection queue clearance timelines and lithium carbonate price normalization trajectories. Material deviation in FERC aggregation rule implementation or EU building performance standard enforcement pace warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy Storage
Lead Acid Battery for Energy Storage Market
Energy Storage
Hydrogen Storage System Market
Energy Storage
Battery Energy Storage System Fire Protection Market
Energy Storage
Energy Storage Sodium Ion Battery Market
Energy Storage
Vessel Energy Storage Systems Market
Energy Storage
Power Bank Market
Energy Storage
Flywheel Energy Storage (FES) Systems Market
Energy Storage
ASEAN Energy Storage Devices Market
Energy Storage
Hybrid Solar Wind Energy Storage Market
Energy Storage
Energy Storage Software Market
Energy Storage
Battery Storage Inverter Market
Energy Storage
Battery Cell Dry Room Dehumidification Systems Market
Energy Storage
Supercapacitor Market
Energy Storage
ASEAN Energy Storage Market
Energy Storage
Superconducting Magnetic Energy Storage Market
Energy Storage
Natural Gas Storage Market