
 Oil and Gas Security Services Market | 2026-2036
Oil and Gas Security Services Market Size, Share, and Industry Trends Forecast 2026-2036
Oil and Gas Security Services Market Insights
The EU Green Deal is rebalancing procurement priorities across European oil and gas infrastructure, compelling operators to integrate emissions monitoring with physical security architectures. Honeywell International Inc. leverages its building automation heritage to merge climate compliance with perimeter defense systems. Siemens AG anchors its position through industrial cybersecurity platforms tailored to downstream processing environments. Schneider Electric SE competes on integrated power-security management for remote extraction sites.
Oil and gas security services encompass the design, deployment, and operation of protective systems safeguarding hydrocarbon assets against physical intrusion, cyber intrusion, and operational disruption, typically incorporating intrusion detection sensors, network segmentation protocols, and emergency shutdown integration with response latencies under 500 milliseconds. The primary purpose is ensuring continuity of extraction, transport, and refining operations while preventing catastrophic releases, theft, or sabotage. Cybersecurity Solutions represents the fastest-expanding service type as ransomware attacks against SCADA environments multiply, while Physical Security retains the largest revenue pool due to sustained manned-guarding and perimeter hardening requirements across Middle Eastern and African production zones. Pipeline Operators among end users command disproportionate investment share given the linear vulnerability profile of cross-border transport infrastructure and regulatory mandates for continuous leak and intrusion monitoring.
The US Department of Homeland Security, through TSA pipeline security directives and EPA methane performance standards, shapes vendor qualification requirements and technology deployment timelines across American midstream networks. In Europe, the NIS2 Directive and EU AI Act are converging to mandate algorithmic transparency in automated threat detection systems deployed at critical energy facilities. Stakeholders must evaluate whether their technology portfolios satisfy both cyber resilience certifications and emerging sustainability-linked security procurement criteria without awaiting harmonized standards.
Market Dynamics
The convergence of cyber-physical threats against critical energy infrastructure is forcing asset operators to unify historically siloed security functions under single command architectures, with TSA pipeline directives and EU methane mandates accelerating procurement cycles for integrated detection systems.
Growth Catalysts
- Ransomware Proliferation:SCADA-targeting attacks against midstream networks are compelling pipeline operators to harden network segmentation and deploy zero-trust architectures across geographically dispersed control systems.
- EU Green Deal Methane Mandates:Emissions detection requirements for European energy infrastructure are creating procurement pull for combined optical gas imaging and perimeter surveillance platforms.
- Permian Basin Threat Intensification:Physical sabotage risks and organized theft rings across West Texas extraction zones are sustaining demand for armed response capabilities and aerial monitoring services.
Market Restraints
- Specialized Labor Scarcity:Shortages of cleared cybersecurity professionals with ICS/SCADA expertise are inflating personnel costs and extending deployment timelines for complex integration projects.
- Semiconductor Supply Concentration:Dependence on East Asian fabrication for advanced sensor chipsets creates vulnerability in intrusion detection hardware procurement channels.
- Legacy System Interoperability:Proprietary protocols in decades-old distributed control systems impose technical barriers to seamless security overlay deployment without operational disruption.
Strategic Opportunities
- Middle East Digitalization Wave:Saudi and UAE national oil companies are modernizing desert extraction facilities with AI-enabled surveillance, creating demand for extreme-climate hardened security hardware.
- Drone-based Methane Patrol:Unmanned aerial systems paired with tunable diode laser absorption spectroscopy are opening service revenue streams beyond traditional manned guarding contracts.
- NIS2 Directive Compliance Services:European critical infrastructure operators require external security operations center support to satisfy incident reporting and risk management obligations under the expanded directive.
Industry Challenges
- Converged Skill Requirements:Security operations centers now demand personnel fluent in both OT network protocols and physical access control systems, compressing available talent pools.
- Certification Timeline Compression:Vendor qualification processes under TSA security directives and EPA performance standards are extending sales cycles by six to twelve months for new market entrants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Oil and Gas Security Services Market |
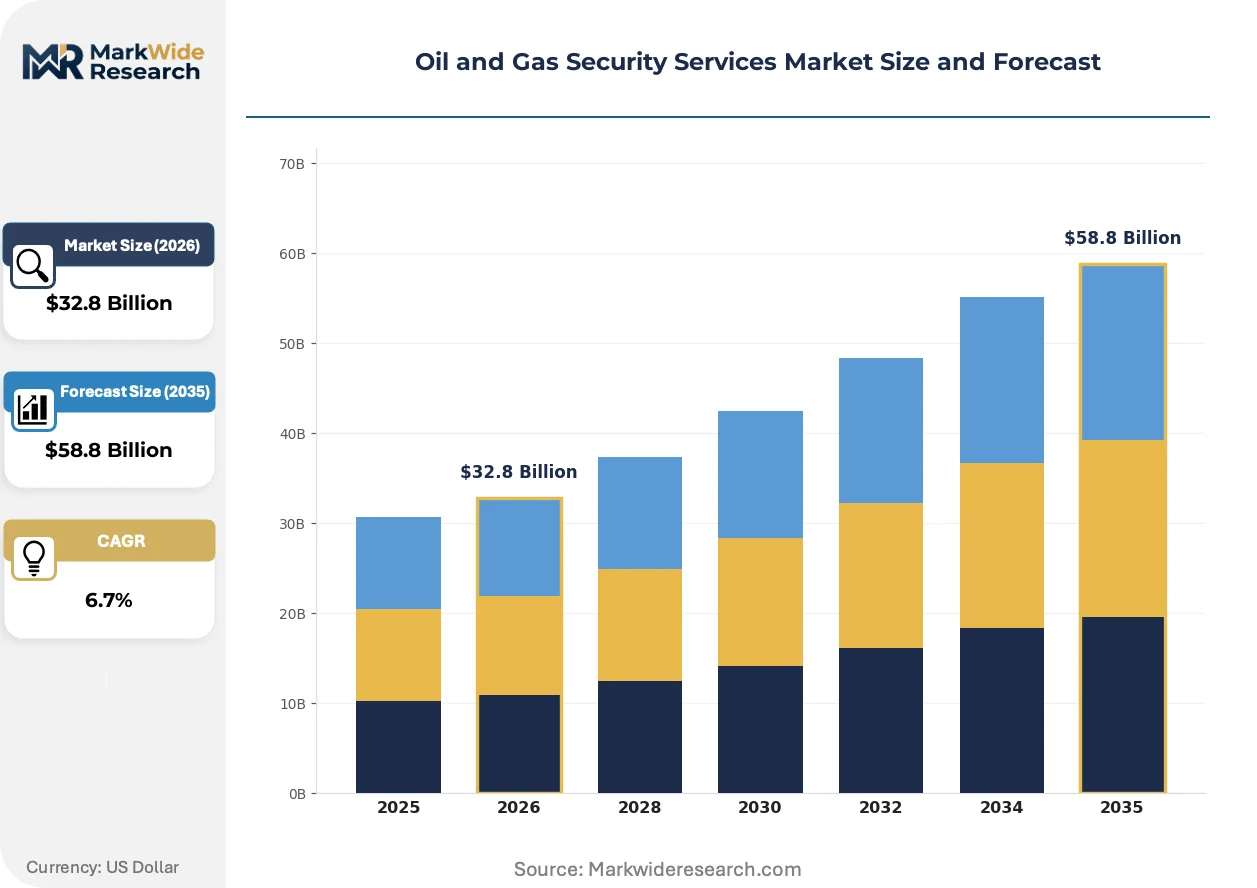
| Market Size in 2026 | $32.8 Billion |
| Market Size in 2035 | $58.8 Billion |
| CAGR (2026 – 2036) | 6.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Service Type: Threat Assessment, Physical Security, Cybersecurity Solutions, Risk Management End User: Exploration Companies, Production Firms, Pipeline Operators, Refiners Technology: Surveillance Systems, Access Control, Incident Response, Data Encryption Application: Site Security, Transport Security, Asset Protection, Emergency Response |
| Companies Covered | Honeywell International Inc., Siemens AG, ABB Ltd., Cisco Systems Inc., Schneider Electric SE, Waterfall Security Solutions Ltd., Parsons Corporation, BAE Systems plc, Airbus Defence and Space, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Oil and Gas Security Services Market Trends and Innovations
Security architectures for hydrocarbon assets are pivoting from reactive perimeter defense to predictive threat detection, with artificial intelligence and autonomous sensing platforms displacing human-intensive monitoring models across upstream and midstream environments.
Edge-deployed machine learning inference engines are expanding into pipeline leak and intrusion detection workflows, analyzing acoustic and thermal sensor arrays in real-time without cloud latency. Midstream operators in the Permian Basin and North Dakota Bakken formation are piloting these systems at compressor stations and block valve sites. The technology is expanding into satellite-linked remote monitoring contracts previously served by manned flyover patrols, compressing response windows from hours to minutes.
The EU AI Act algorithmic transparency requirements are reshaping procurement specifications for automated threat detection systems deployed at European refineries and LNG terminals. Vendors must now document training data provenance and decision logic for security software classified as high-risk AI systems. Downstream processing facilities in Rotterdam and Antwerp are demanding compliance pre-certification before contract award, filtering supplier pools.
Buyer preference for integrated service contracts bundling hardware, monitoring, and response is displacing discrete equipment sales in the North American midstream segment. Pipeline operators now specify outcome-based agreements with guaranteed detection rates and response time service levels rather than capital expenditure procurement. This pattern is most visible among master limited partnerships operating cross-border infrastructure between Texas and Oklahoma, where operational expenditure treatment carries tax advantages.
Oil and Gas Security Services Market Segmentation
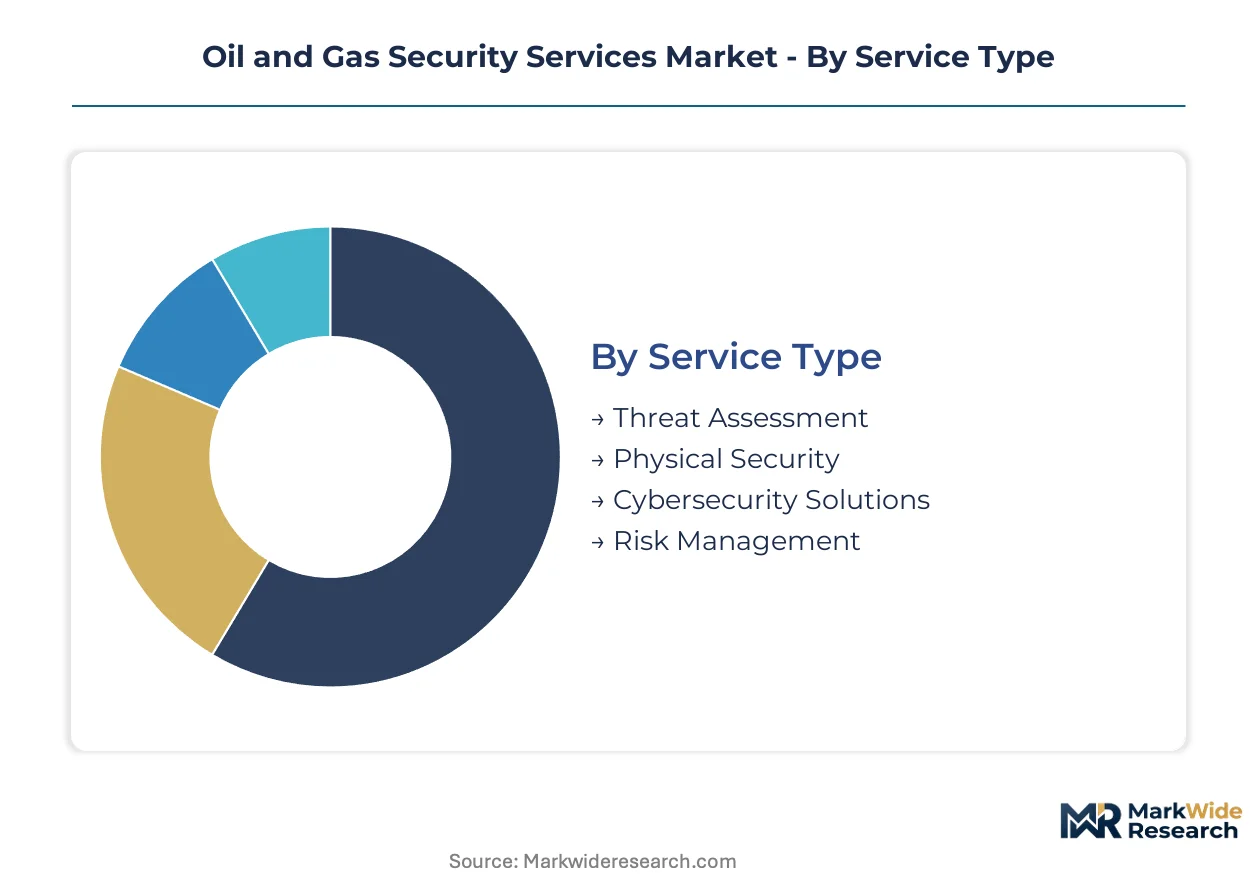
Oil and gas security services segment along four functional dimensions that reflect divergent procurement priorities across the hydrocarbon value chain. Certification requirements from TSA pipeline directives and EU NIS2 standards fragment vendor eligibility differently across each category. Understanding these segment boundaries clarifies where integrated service contracts concentrate versus discrete technology sales.
Service Type:
Cybersecurity Solutions and Physical Security carry distinct certification burdens under TSA security directives and EPA methane performance standards, while Threat Assessment and Risk Management face lighter vendor qualification timelines.
- Cybersecurity Solutions:Network segmentation protocols, zero-trust architectures, and SCADA-specific threat detection systems designed for operational technology environments. Demand concentrates among Permian Basin pipeline operators confronting ransomware proliferation against geographically dispersed control systems.
- Physical Security:Perimeter hardening, manned guarding, and armed response capabilities deployed at extraction sites and transport corridors. Middle Eastern and African production zones sustain the largest revenue pools due to sustained manned-guarding requirements and organized theft risks.
- Threat Assessment:Vulnerability analysis and attack surface mapping for upstream and midstream assets.
- Risk Management:Compliance documentation and incident response planning tied to regulatory reporting obligations.
Physical Security sits at the top of the volume ranking, with Cybersecurity Solutions climbing the fastest.
End User:
Procurement scale varies dramatically across the value chain, with midstream linear infrastructure commanding disproportionate investment relative to asset count.
- Pipeline Operators:Cross-border transport infrastructure requiring continuous leak monitoring, intrusion detection, and emergency shutdown integration with response latencies under 500 milliseconds. TSA pipeline security directives mandate specific technology deployment timelines across American midstream networks.
- Refiners:Downstream processing facilities in Rotterdam and Antwerp demanding EU AI Act compliance pre-certification for automated threat detection systems classified as high-risk AI.
- Exploration Companies:Upfront security planning for frontier drilling operations in remote geographies.
- Production Firms:Field-level asset protection at extraction sites facing physical sabotage and theft risks.
Pipeline Operators anchor procurement volume given regulatory mandates, while Refiners are expanding most quickly under European emissions-security convergence requirements.
Technology:
Technology selection tracks operational expenditure treatment preferences and tax advantages among master limited partnerships.
- Surveillance Systems:Optical gas imaging paired with perimeter monitoring platforms, plus AI-enabled aerial surveillance for desert extraction facilities. Saudi and UAE national oil companies are modernizing with extreme-climate hardened hardware.
- Access Control:Biometric and credential-based entry management for critical facility zones.
- Incident Response:Automated alert routing and emergency coordination protocols.
- Data Encryption:Protocol-level protection for SCADA communications and control system integrity.
Surveillance Systems holds the volume lead, with Data Encryption gaining share fastest as ransomware attacks multiply.
Application:
Application scope determines whether procurement favors capital expenditure equipment sales or outcome-based service contracts with guaranteed detection rates.
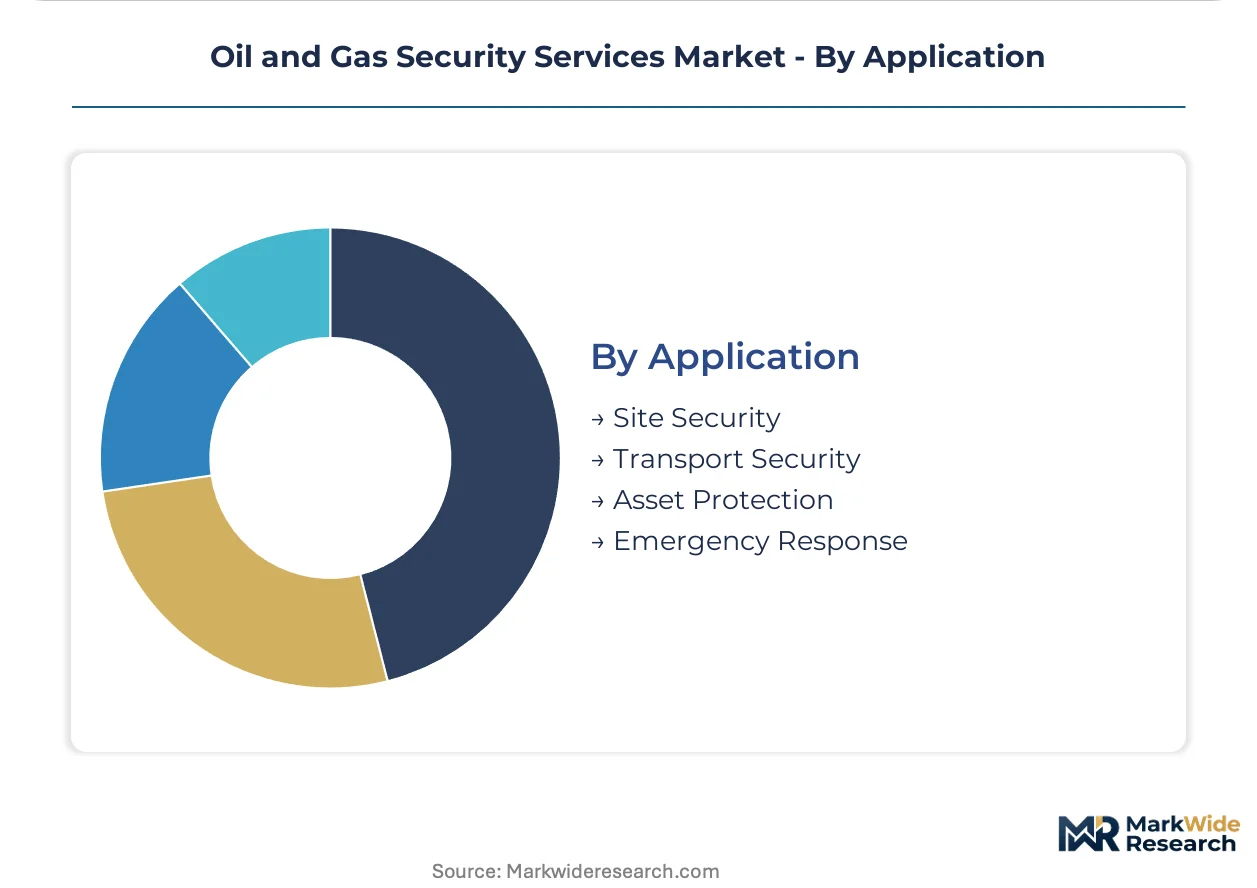
- Site Security:Integrated perimeter defense and emissions monitoring architectures for extraction and processing facilities. The EU Green Deal is accelerating combined optical gas imaging and surveillance procurement across European energy infrastructure.
- Transport Security:Linear infrastructure protection spanning compressor stations, block valve sites, and cross-border pipelines. North Dakota Bakken formation operators are piloting edge-deployed machine learning for real-time acoustic and thermal analysis.
- Asset Protection:Equipment and inventory safeguarding against organized theft rings.
- Emergency Response:Coordinated shutdown and containment protocols for catastrophic release prevention.
Site Security dominates current procurement value, with Transport Security showing the steepest expansion trajectory under drone-based methane patrol adoption.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The oil and gas security services industry traces its modern scaling to North American pipeline protection mandates following post-9/11 critical infrastructure designations. Regulatory fragmentation now shapes procurement patterns across extraction basins and transport corridors worldwide.
United States
The Permian Basin and Gulf Coast refining clusters drive sustained demand for cyber-physical protection systems. TSA pipeline security directives and EPA methane performance standards dictate vendor qualification timelines across midstream networks. West Texas operators deploy armed response capabilities and aerial monitoring to counter organized theft rings targeting extraction equipment.
Saudi Arabia
Aramco-led desert facility modernization programs are accelerating procurement of extreme-climate hardened surveillance hardware. The national oil company's digitalization wave creates demand for AI-enabled perimeter defense at remote extraction sites. Eastern Province processing complexes anchor regional security service contracting volumes.
Germany
Downstream refineries in the Rhine-Ruhr industrial belt face converging NIS2 Directive and EU AI Act compliance obligations. Algorithmic transparency requirements for automated threat detection systems filter supplier pools before contract award. Industrial cybersecurity platforms tailored to processing environments concentrate vendor activity around Ludwigshafen and Leverkusen chemical corridors.
United Arab Emirates
ADNOC and Emirates National Oil Company infrastructure expansion sustains demand for integrated physical-digital security architectures. MOHAP regulatory frameworks intersect with critical energy facility protection standards. Abu Dhabi and Dubai anchor procurement for combined optical gas imaging and perimeter surveillance platforms across LNG terminal and refinery assets.
Netherlands
Rotterdam and Antwerp refining complexes demand EU AI Act pre-certification for high-risk automated threat detection systems. The EU Green Deal methane mandate accelerates combined emissions monitoring and security procurement. Port-adjacent processing facilities specify outcome-based service contracts with guaranteed detection rates rather than capital expenditure equipment sales.
Oil and Gas Security Services Market Competitive Landscape
Premium-margin players sit above commodity-margin players across certification complexity and integration depth. The vendor base clusters around three strategic archetypes: industrial automation conglomerates with building control heritage, pure-play cybersecurity specialists with ICS/SCADA expertise, and defense contractors with government security clearances. Dominant competitive moves include strategic partnerships for combined hardware-monitoring-response bundling and vertical integration into sensor chipset supply to mitigate semiconductor procurement vulnerability.
Within the industrial automation tier, Honeywell International Inc., Siemens AG, and Schneider Electric SE exemplify players leveraging legacy building and power management platforms to merge climate compliance with perimeter defense. These corporations occupy positions where EU methane mandates and physical security requirements converge, anchoring integrated service contract negotiations across European and North American downstream facilities.
| Leading Market Players |
|---|
| Honeywell International Inc. |
| Siemens AG |
| ABB Ltd. |
| Cisco Systems Inc. |
| Schneider Electric SE |
| Waterfall Security Solutions Ltd. |
| Parsons Corporation |
| BAE Systems plc |
| Airbus Defence and Space |
| Others |
Pricing and Supply Chain Analysis
Semiconductor chipsets for intrusion detection sensors flow from East Asian fabrication through three pricing tiers downstream, with buyers in the Permian Basin and European downstream facilities absorbing tiered premiums based on TSA certification timelines and EU AI Act compliance pre-certification status.
Pricing Analysis
Outcome-based service contracts with guaranteed detection rates and response time service levels dominate North American midstream procurement, particularly among master limited partnerships seeking operational expenditure treatment. Price differentiation separates TSA-certified vendors with cleared personnel pools from uncertified competitors facing six-to-twelve-month qualification delays. Cost compression in the cybersecurity tier intensifies as ICS/SCADA talent scarcity inflates deployment timelines. Pipeline operators show lowest price sensitivity for emergency shutdown integration sub-500-millisecond latency, while exploration companies drive hardest bargain on frontier site security planning.
Supply Chain Analysis
Dual-sourcing requirements for critical sensor chipsets mandate multi-supplier qualification across Taiwan, South Korea, and Japan fabrication networks. Hardware procurement draws from Chinese component suppliers for perimeter enclosures, German industrial automation houses for control system integration, and Israeli firms for cybersecurity firmware. Single-source vulnerability concentrates in advanced optical gas imaging sensors where tunable diode laser absorption spectroscopy suppliers number under ten globally. Distribution runs through authorized system integrators holding TSA security directive certifications and EPA methane performance standard accreditations.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Geographic arbitrage between US Gulf Coast and European Rhine-Ruhr procurement clusters rewards vendors with dual TSA and EU AI Act certification capabilities, as regulatory timeline differentials create six-month pricing premiums for qualified suppliers.
For Market Incumbents: Acquire cleared cybersecurity personnel pools with ICS/SCADA expertise to offset talent scarcity inflating deployment costs. Consolidate sensor chipset supply through captive production partnerships with Taiwanese foundries, reducing exposure to East Asian supply concentration. Reinforce position against pure-play cybersecurity specialists by bundling physical-digital security architectures under single command contracts. For New Entrants and Emerging Players: Enter via NIS2 Directive compliance services for European critical infrastructure operators requiring external security operations center support. Target drone-based methane patrol contracts in North Dakota Bakken formation where satellite-linked remote monitoring displaces manned flyover patrols. Pursue white-label partnerships with industrial automation conglomerates lacking AI-enabled surveillance capabilities for extreme-climate desert extraction facilities. For Investors and Strategic Acquirers: Consolidation pressure builds where vendor qualification timelines under TSA security directives and EPA performance standards extend sales cycles beyond twelve months for unqualified entrants. Long-term viability favors vertically integrated platforms spanning hardware fabrication, monitoring services, and armed response capabilities. Watch for inflection where master limited partnerships accelerate outcome-based contract adoption over capital expenditure procurement.| Strategic Initiative | Industry Significance |
|---|---|
| Certification Pre-Investment | TSA pipeline directive and EU AI Act pre-certification compresses vendor qualification timelines for midstream contracts. |
| Personnel Pool Acquisition | Cleared cybersecurity professionals with ICS/SCADA expertise command premium valuations amid acute labor scarcity. |
| Chipset Supply Partnership | Foundry relationships with Taiwanese and South Korean suppliers mitigate intrusion detection hardware procurement vulnerability. |
| Drone Patrol Service Launch | Unmanned aerial systems paired with tunable diode laser absorption spectroscopy open revenue beyond manned guarding. |
| Integrated Outcome Contracts | Guaranteed detection rate agreements with operational expenditure treatment attract master limited partnership procurement. |
Research Methodology
Coverage spans North American midstream networks, European downstream refining corridors, and Middle Eastern desert extraction facilities, with primary inputs from each. The study combines interviews with pipeline security directors, critical infrastructure protection officers, industrial cybersecurity engineers, and procurement leads at national oil companies with secondary validation through TSA security directive filings, EPA methane performance standard records, EU NIS2 Directive implementation guidance, and SEC 10-K disclosures from master limited partnerships. Bottom-up segment sizing triangulates against top-down market reconstruction.
Granularity-level modeling disaggregates revenue across service type, end user, technology, and application dimensions, with additional segmentation by regulatory compliance tier and contract structure preference. Value projections across the analysis window derive from CAGR trajectories anchored to disclosed procurement volumes, announced facility modernization programs, and regulatory mandate implementation timelines. Forecast inputs incorporate Aramco-led digitalization wave expenditure, Permian Basin threat intensification patterns, and EU Green Deal methane detection procurement acceleration.
Inputs from TSA pipeline security directive compliance databases and EU AI Act pre-certification registries were available through the study window; gaps in proprietary national oil company security expenditure disclosures introduce uncertainty bands around Middle Eastern and African production zone estimates. Deviation in semiconductor supply chain resilience or ICS/SCADA labor market tightness would shift the outlook materially.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Oil & Gas
Oil & Gas Static and Rotating Equipment Market
Oil & Gas
Australia Oil and Gas Midstream Market
Oil & Gas
Middle-East Oilfield Services Market
Oil & Gas
Central Asia Oil and Gas Midstream Market
Oil & Gas
Mexico Oil and Gas Downstream Market
Oil & Gas
Wellhead Equipment Market
Oil & Gas
Subsea Manifolds Market
Oil & Gas
Oil and Gas Digital Rock Analysis Market
Oil & Gas
Blowout Preventers (BOP) Market
Oil & Gas
Brazil Wireline Logging Services Market
Oil & Gas
Frac Stack Market
Oil & Gas
Oil and Gas Pipeline and Transportation Automation Market
Oil & Gas
Oil and Gas Data Monetization Market
Oil & Gas
Europe Hydraulic Fracturing Fluids Market
Oil & Gas
North America Digital Oilfield Market
Oil & Gas
Rig and Oilfield Mats Market