
 Latin America Biodiesel Market | 2026-2036
Latin America Biodiesel Market Size, Share, and Industry Trends Forecast 2026-2036
Latin America Biodiesel Market Intelligence
The gap between premium-certified and commodity-grade biodiesel is broadening across Latin America. Petrobras leverages its downstream infrastructure to sustain distribution advantages in Brazilian metropolitan fuel markets. GranBio anchors cellulosic ethanol-biodiesel integration in the Northeast, while Cargill competes through captive soybean oil supply across Argentina's Rosario hub.
Biodiesel comprises fatty acid methyl esters produced via transesterification of vegetable oils or animal fats with methanol, yielding a drop-in diesel substitute with cetane ratings typically exceeding 51. Soybean oil feedstock dominates Latin American production economics due to established crushing infrastructure, though waste cooking oil segments are gaining traction as collection networks formalize in São Paulo and Mexico City. Transesterification technology leads installed capacity, while hydrothermal liquefaction represents an emerging pathway for lignocellulosic and algal feedstocks with higher energy density outputs. Transportation fuels command the largest application share, yet industrial heating segments in Chilean mining operations present concentrated margin pools.
Brazil's National Petroleum Agency and Argentina's Secretariat of Energy enforce blending mandates that directly structure demand floors and product quality specifications. ANP's RenovaBio program and Argentina's Biofuels Law create compliance pathways that shape investment timing and technology selection for producers. Stakeholders must monitor feedstock price convergence between soybean oil and petroleum diesel, as this spread determines refiner willingness to absorb biodiesel premiums at the blending terminal.
Market Dynamics
Blending mandates across Brazil and Argentina are compressing feedstock arbitrage windows, forcing producers to secure captive soybean oil supply or absorb margin erosion when vegetable oil prices diverge from fossil diesel benchmarks.
Growth Catalysts
- RenovaBio carbon intensity targets:Brazil's ANP program creates compliance credit markets that reward lower-carbon production pathways, directing capital toward efficiency upgrades and alternative feedstock processing.
- Mining sector diesel displacement:Chilean copper and lithium operations are substituting biodiesel for diesel in haul truck fleets and stationary generators, absorbing premium-priced certified fuel volumes.
- Cellulosic integration:Hydrothermal liquefaction pilot plants in Brazil's Northeast are converting sugarcane bagasse and forestry residues into higher-energy-density biofuels, diversifying beyond oilseed dependence.
Market Restraints
- Soybean oil price volatility:Feedstock costs constitute 70-85% of production economics, exposing crushers to Chicago Board of Trade futures swings that compress blending margins at Brazilian refineries.
- Southern Cone crushing concentration:Argentina's Rosario-Entre Ríos corridor and Brazil's Mato Grosso processing belt control regional oilseed supply, creating logistics bottlenecks and freight cost premiums for distant consumers.
- Argentina's biofuel tax framework:Export parity pricing mechanisms and variable export duties on soybean products create policy uncertainty that delays long-term processing investments.
Strategic Opportunities
- Mexico's unenforced blending law:The 2008 biofuels mandate remains unimplemented due to infrastructure gaps, creating first-mover advantage for distributors building storage and blending terminals in Guadalajara and Monterrey.
- Waste cooking oil formalization:São Paulo and Mexico City collection networks are consolidating restaurant grease supply chains, enabling ISCC-certified product streams that command carbon credit premiums under voluntary schemes.
- Marine fuel substitution:IMO 2020 sulfur regulations are pushing Brazilian port authorities to trial B30-B50 blends in tugboat and coastal shipping fleets, opening bunker fuel adjacent demand.
Industry Challenges
- ASTM D6751 and EN 14214 certification timelines:Laboratory testing backlogs at Brazil's INMETRO and Argentina's INTI facilities delay product release, tying up working capital in finished goods inventory.
- Transesterification catalyst supply security:Homogeneous alkaline catalyst procurement depends on imported sodium methoxide, exposing producers to currency risk and maritime shipping disruptions.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Latin America Biodiesel Market |
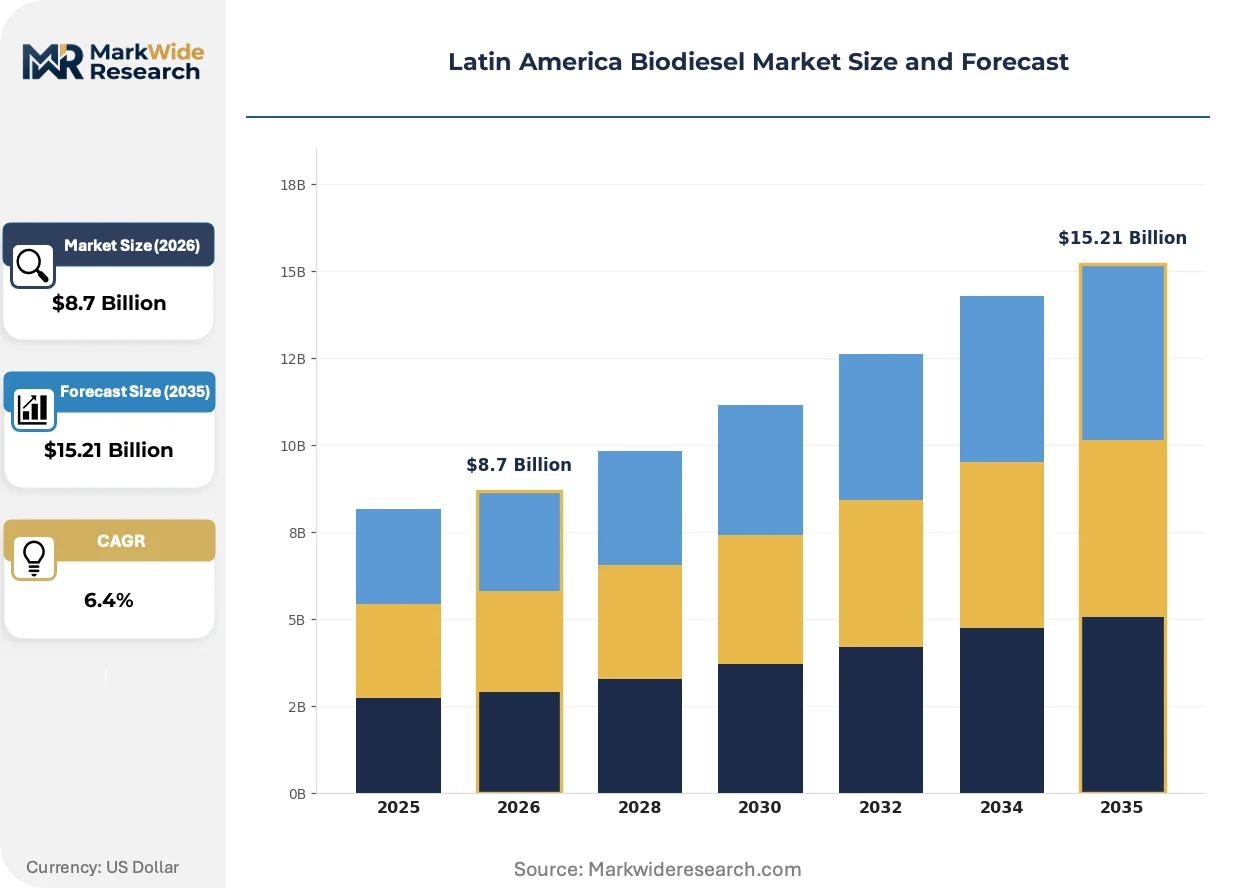
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $15.21 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Soybean Oil, Palm Oil, Corn Oil, Waste Cooking Oil Production Technology: Transesterification, Pyrolysis, Fermentation, Hydrothermal Liquefaction Application: Transportation Fuels, Industrial Heating, Power Generation, Blending Agents End User: Agriculture, Transportation, Power Plants, Retail Distribution |
| Companies Covered | Petrobras, GranBio, Cargill, Ecodiesel Colombia S.A., Cosan, Bunge Limited, Biosev, Agrosuper, ADM, Others |
| Regions Covered | Latin America: Brazil, Mexico, Argentina, Colombia, Chile, Peru, Rest of Latin America |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Latin America Biodiesel Market Strategic Shifts & Innovations
Technology convergence and regulatory stringency are fragmenting the historically commoditized biodiesel value chain, creating tiered product markets differentiated by carbon intensity certification and feedstock provenance.
Small-scale continuous transesterification reactors are decentralizing production economics across Brazil's interior. Rural cooperatives and independent crushers are deploying skid-mounted units with 5,000-20,000 ton annual capacity, bypassing centralized refinery blending infrastructure. This distributed model is compressing logistics costs for remote agricultural diesel consumers while fragmenting supply contracts previously dominated by Petrobras-affiliated distributors.
Argentina's Secretariat of Energy is tightening biodiesel carbon balance requirements through updated Biofuels Law implementing regulations. The revised framework mandates lifecycle emissions verification for compliance credit eligibility, disqualifying deforestation-linked soybean supply. Northern Argentine producers with Chaco clearance exposure are accelerating ISCC and RSB certification investments to maintain market access.
Fleet procurement departments are embedding sustainability clauses into multiyear diesel supply agreements, unbundling fuel purchasing from legacy integrated refinery contracts. Brazilian logistics operators and Argentine agribusiness conglomerates are negotiating direct offtake with certified biodiesel producers, disintermediating traditional fuel distributors in São Paulo and Buenos Aires metropolitan zones. This bilateral contracting concentrates volume with low-carbon verified suppliers while pressuring commodity-grade product discounts.
Latin America Biodiesel Market Segmentation
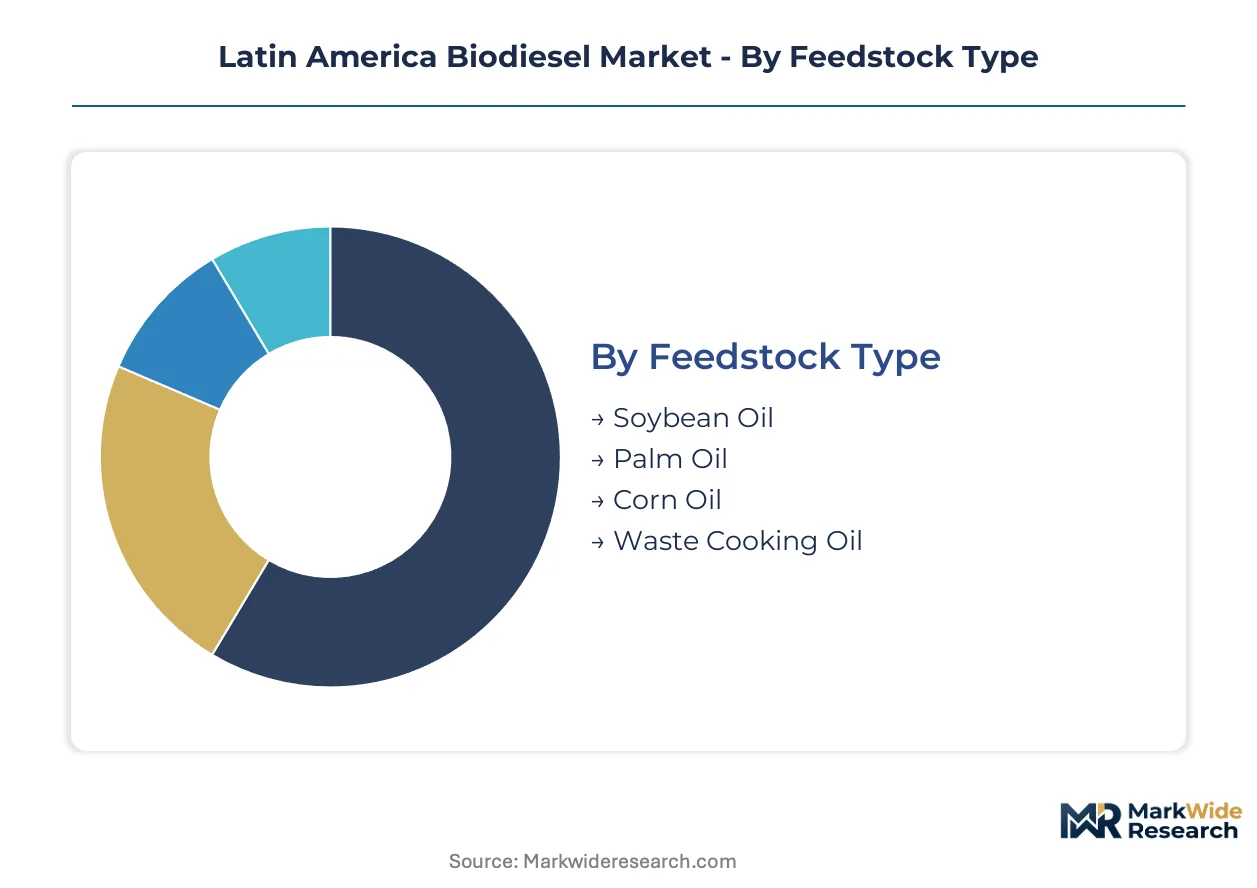
Feedstock economics and blending mandate specifications fragment Latin American biodiesel into distinct supply tiers. Producers align processing technology and certification pathways with end-use carbon intensity requirements and refinery offtake terms.
Feedstock Type:
Volume concentration in commodity oilseeds contrasts with emerging premium streams from waste oils.
- Soybean Oil:Dominates installed crushing capacity across Argentina's Rosario-Entre Ríos corridor and Brazil's Mato Grosso belt. ANP blending mandates anchor baseline demand, though CBOT futures volatility compresses margins when soybean oil diverges from fossil diesel benchmarks.
- Waste Cooking Oil:Collection networks in São Paulo and Mexico City are consolidating restaurant grease supply chains. ISCC certification unlocks carbon credit premiums under voluntary schemes, positioning this segment as the fastest-expanding feedstock category for low-carbon verified production.
- Palm Oil:Concentrated in Colombian and Ecuadorian coastal plantations with established refining infrastructure.
- Corn Oil:Captured as byproduct from Brazil's corn ethanol facilities in Mato Grosso do Sul.
Today's leader: Soybean Oil. Tomorrow's challenger: Waste Cooking Oil.
Production Technology:
Cost tier separation between mature transesterification and emerging thermochemical pathways shapes capital allocation.
- Transesterification:Alkaline-catalyzed reaction of vegetable oils with methanol yielding fatty acid methyl esters with cetane ratings exceeding 51. Brazil's interior cooperatives deploy skid-mounted continuous reactors, fragmenting supply contracts previously held by Petrobras-affiliated distributors.
- Hydrothermal Liquefaction:Converts sugarcane bagasse and forestry residues into higher-energy-density biofuels under supercritical water conditions. GranBio's Northeast pilot operations demonstrate cellulosic integration potential, diversifying beyond oilseed dependence.
- Pyrolysis:Thermal decomposition of lignocellulosic biomass in oxygen-limited environments.
- Fermentation:Microbial conversion of sugars to fatty acid esters, currently at laboratory scale in Brazilian research consortia.
Transesterification commands current capacity. Hydrothermal Liquefaction offers the steepest expansion trajectory for next-generation production.
Application:
Transportation mandates anchor volume while industrial segments absorb premium-certified product.
- Transportation Fuels:Diesel blending mandates enforced by Brazil's ANP and Argentina's Secretariat of Energy create compliance floors. Fleet procurement departments embed sustainability clauses into multiyear supply agreements, disintermediating traditional distributors in São Paulo and Buenos Aires metropolitan zones.
- Industrial Heating:Chilean copper and lithium operations substitute biodiesel for diesel in haul truck fleets and stationary generators. Mining procurement absorbs premium-priced certified fuel volumes, creating concentrated margin pools distinct from commodity transportation markets.
- Power Generation:Backup diesel generators in Brazilian agribusiness facilities trial B20-B30 blends.
- Blending Agents:Intermediate product streams sold to Petrobras and YPF refinery terminals for mandate compliance.
Transportation Fuels drives current volume. Industrial Heating captures expanding premium pricing.
End User:
Customer type determines contract structure and certification requirements.
- Transportation:Brazilian logistics operators and Argentine agribusiness conglomerates negotiate direct offtake with certified producers. Bilateral contracting concentrates volume with low-carbon verified suppliers while pressuring commodity-grade discounts.
- Agriculture:Remote diesel consumers in Brazil's interior source from distributed cooperative production, compressing logistics costs versus centralized refinery supply.
- Power Plants:Grid backup and distributed generation facilities in mining regions.
- Retail Distribution:Fuel stations in metropolitan corridors under Petrobras and YPF branding.
Transportation dominates contract innovation. Agriculture sustains distributed production economics.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Crushing corridor expertise clusters in Brazil's Mato Grosso and Argentina's Entre Ríos, anchoring regional production capacity. Technical talent concentrates around transesterification operations and ANP compliance systems. Logistics specialists manage soybean oil freight economics across the Southern Cone.
Brazil
ANP blending mandates and RenovaBio carbon intensity targets structure investment timing for producers. The national petroleum agency enforces compliance credit markets that reward lower-carbon production pathways. Mato Grosso processing belt and Northeast pilot operations concentrate capacity expansion.
Argentina
Rosario-Entre Ríos corridor controls regional oilseed supply through established crushing infrastructure. The Secretariat of Energy tightens carbon balance requirements through updated Biofuels Law implementing regulations. Northern producers with Chaco clearance exposure accelerate ISCC certification investments.
Mexico
Unenforced 2008 biofuel mandate creates first-mover advantage for infrastructure builders. The national energy regulator maintains policy framework without implementation due to storage and blending terminal gaps. Guadalajara and Monterrey metropolitan zones attract distributor investment.
Chile
Copper and lithium mining operations substitute biodiesel for diesel in haul truck fleets and stationary generators. The Ministry of Mining procurement absorbs premium-priced certified fuel volumes. Northern mining regions present concentrated margin pools distinct from transportation markets.
Colombia
Palm oil coastal plantations with established refining infrastructure anchor feedstock supply. Ecodiesel Colombia S.A. exemplifies national production capacity. Pacific and Caribbean port zones enable marine fuel substitution trials under IMO 2020 sulfur regulations.
Latin America Biodiesel Market Key Industry Players
Top-tier vendors anchor integrated oilseed-to-fuel operations, while mid-scale cooperatives deploy distributed skid-mounted reactors. State-affiliated energy groups leverage downstream infrastructure for distribution advantages. Independent crushers compete through captive soybean oil supply or waste cooking oil formalization. Dominant competitive moves include strategic partnerships for feedstock security and technology licensing for cellulosic integration pathways.
Among Brazil-based operators, Petrobras and GranBio occupy distinct archetype positions. Petrobras exemplifies state-affiliated downstream integration through metropolitan fuel market distribution. GranBio represents cellulosic technology pioneers with Northeast pilot operations converting sugarcane bagasse. Cargill anchors multinational agribusiness competition through Rosario hub oilseed supply control.
| Leading Market Players |
|---|
| Petrobras |
| GranBio |
| Cargill |
| Ecodiesel Colombia S.A. |
| Cosan |
| Bunge Limited |
| Biosev |
| Agrosuper |
| ADM |
| Others |
Cost & Logistics Intelligence
Certification-grade divergence between ISCC-verified premium streams and commodity-grade biodiesel fragments Latin American pricing architectures while concentrating supply chain control among crush-and-process operators in Brazil's Mato Grosso and Argentina's Rosario corridor. This bifurcation rewards producers who backward-integrate into captive soybean oil supply with margin stability, while unbundled offtake agreements force commodity sellers into spot-market volatility.
Pricing Analysis
Bundled long-term offtake contracts dominate premium-tier transactions, while unbundled spot sales characterize commodity-grade exchanges. Price differentiation rests on carbon intensity certification tier and feedstock provenance verification, with ISCC-RSB dual-certified product commanding substantial premia over baseline ANP-compliant volumes. Pricing pressure stems from Chicago Board of Trade soybean oil futures divergence from fossil diesel benchmarks, compressing blending margins at Brazilian refineries. Mining procurement departments in Chile exhibit lowest price sensitivity, absorbing certified fuel at substantial markups, while agricultural cooperatives in Brazil's interior remain most cost-conscious.
Supply Chain Analysis
Certification gating through ANP's RenovaBio program and Argentina's updated Biofuels Law implementing regulations concentrates supply chain leverage among pre-qualified producers with established carbon accounting systems. Geographic supply concentration centers on Brazil, Argentina, and Colombia, with crushing infrastructure anchoring feedstock flows. Raw material dependencies draw from soybean oil, methanol catalysts, and sodium methoxide imports. Single-source vulnerability runs through homogeneous alkaline catalyst procurement, which feeds from Asian chemical manufacturers. Distribution runs through Petrobras and YPF refinery terminals, with coastal marine bunkers emerging as an alternative channel.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Latin American biodiesel economics present margin-expansion potential as waste cooking oil formalization in São Paulo and Mexico City unlocks carbon credit premia, shifting producer mix toward lower-cost, higher-margin feedstock tiers.
For Market Incumbents: To counter distributed cooperative production fragmenting supply contracts, Petrobras-affiliated distributors should tighten channel control through exclusive storage and blending terminal access in metropolitan corridors. Cargill and Bunge must deepen backward integration into seed genetics and crushing capacity to lock in feedstock cost advantages against price volatility.
For New Entrants and Emerging Players: The premium-to-commodity price-point gap in certified mining fuel offtake offers the most penetrable white-space target, with Chilean copper and lithium operations absorbing volumes at margins unavailable in transportation mandates. Mexico's unenforced blending law presents geographic whitespace, where first-mover distributors building Guadalajara and Monterrey infrastructure capture pre-mandate positioning. A direct procurement bypass model—selling certified product straight to fleet sustainability officers—disintermediates legacy fuel distributors.
For Investors and Strategic Acquirers: Consolidation pressure builds where small-scale cooperative reactors lack working capital to fund ISCC certification investments required by Argentina's tightened carbon balance regulations. Long-term viability favors vertically integrated crush-and-process operators with captive oilseed supply and established carbon accounting infrastructure. The signal to watch is feedstock price convergence between waste cooking oil collection network scale and soybean oil futures, which would trigger accelerated capital rotation toward formalized grease supply chains.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Oilseed Crushing | Captive soybean oil supply insulates Petrobras and Cargill from CBOT futures volatility. |
| ISCC-RSB Dual Certification Investment | Unlocks RenovaBio compliance credit markets and Chilean mining procurement eligibility. |
| Waste Cooking Oil Collection Network Buildout | São Paulo and Mexico City formalization enables lowest-carbon production pathway scaling. |
| Direct Fleet Procurement Bypass | Bilateral contracting with Brazilian logistics operators disintermediates traditional distributors. |
| Marine Bunker Fuel Terminal Development | Brazilian port authority B30-B50 trials under IMO 2020 open adjacent demand pools. |
Research Approach
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with ANP compliance officers, Petrobras downstream strategists, Argentine crushing facility managers, Chilean mining procurement directors, and ISCC certification auditors with secondary validation. Secondary sources included ANP regulatory filings, Argentina Secretariat of Energy Biofu Law implementing regulations, Chicago Board of Trade futures data, and customs trade records for sodium methoxide imports. Bottom-up production capacity modeling triangulated against top-down blending mandate demand forecasts.
Segment-weighting approaches distributed value and volume across feedstock type, production technology maturity, application end-use, and end-user contract structure throughout the forecast period. CAGRs were derived from feedstock availability projections, mandate enforcement trajectories, and carbon credit market development curves. Industry-specific forecast inputs incorporated RenovaBio carbon intensity target stringency scenarios and waste cooking oil collection network formalization rates.
Caveats apply where ANP mandate enforcement delays, Argentina export duty regime shifts, or Chicago Board of Trade soybean oil volatility spikes could materially shift the outlook. A model refresh is warranted upon material change in RenovaBio compliance credit pricing or Petrobras downstream infrastructure investment announcements.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Biofuels Market
Biofuels
Europe Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Global Advanced Biofuel Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Bioethanol Market
Biofuels
Brazil Biofuel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Second Generation Biofuels Market
Biofuels
Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Europe Biodiesel Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
United States Biodiesel Market