
 Europe Biodiesel Market | 2026-2036
Europe Biodiesel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Biodiesel Market Intelligence
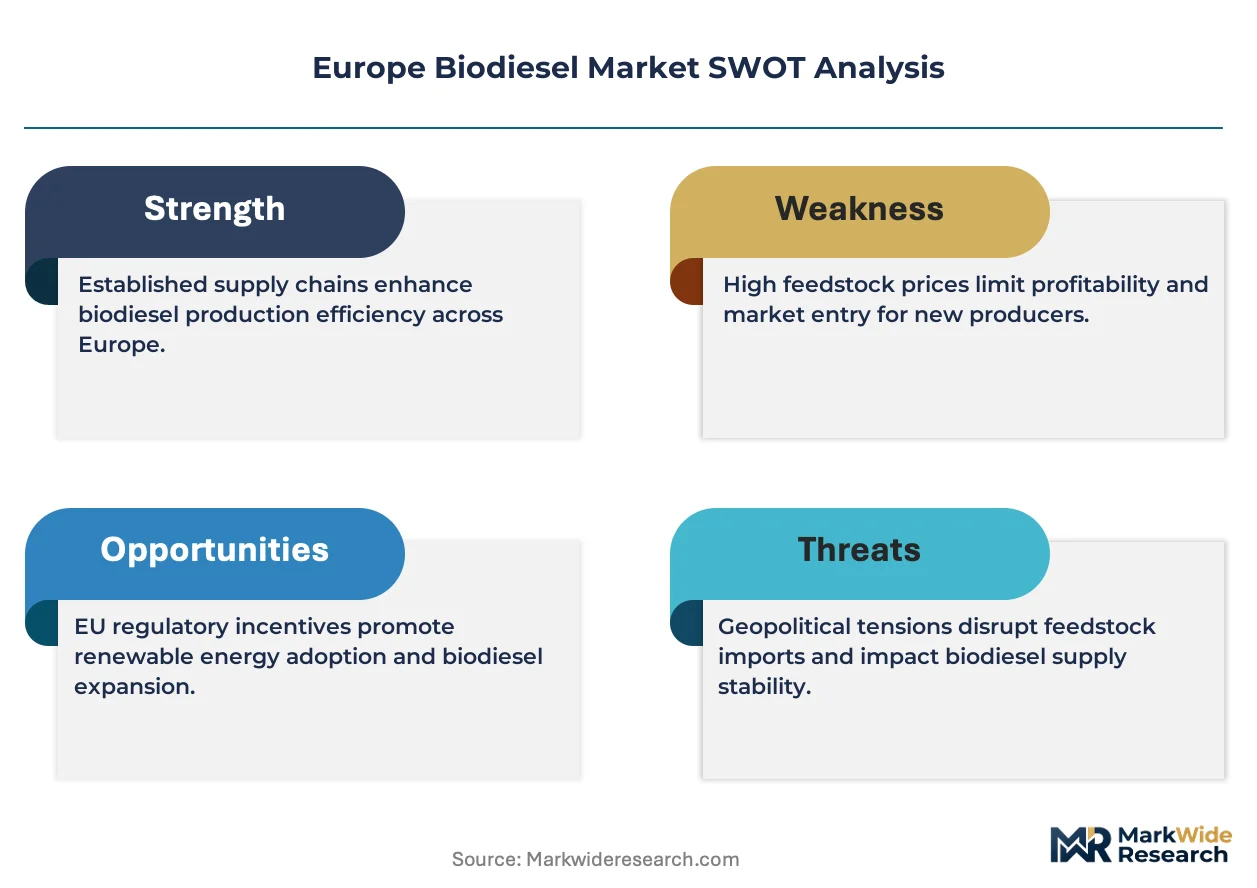
The gap between premium hydrotreated vegetable oil and commodity fatty acid methyl ester is expanding in European biodiesel. Neste Oyj leverages proprietary NEXBTL hydroprocessing to dominate the renewable diesel tier, while TotalEnergies SE anchors its position through integrated refining and biorefinery co-location in France. Verbio AG competes by specializing in agricultural waste-to-fuel pathways that reduce feedstock cost volatility.
Europe biodiesel comprises fatty acid methyl esters or hydrocarbon-like renewable diesel synthesized from vegetable oils, animal fats, or waste lipids through transesterification or hydroprocessing, typically meeting EN 14214 or ASTM D6751 specifications for compression-ignition engine compatibility. Its primary purpose is displacing fossil diesel in transportation and stationary combustion to reduce net greenhouse gas emissions. Vegetable oils sustain the largest production volume base, though used cooking oil commands premium pricing due to lower indirect land-use change risk under EU sustainability criteria. Hydroprocessing represents the fastest-growing technology segment as refiners retrofit existing assets to produce drop-in renewable diesel with superior cold-flow properties.
The EU Renewable Energy Directive, the F-Gas Regulation, and national implementing laws such as Germany's Bundes-Immissionsschutzgesetz collectively mandate blending quotas, sustainability certification, and greenhouse gas reduction thresholds that determine market access for biodiesel suppliers. EMA and national regulators in France and Germany enforce fuel quality standards that effectively segment compliant premium supply from uncertified commodity volumes. Stakeholders must monitor feedstock traceability requirements and cross-border certificate trading mechanics as the EU tightens deforestation-linked import restrictions.
Market Dynamics
Refiners across Europe face mounting pressure to retrofit hydroprocessing assets as renewable diesel margins pull ahead of conventional fatty acid methyl ester production, compressing the competitive window for transesterification-only operators.
Growth Catalysts
- RED III Mandate Escalation:The EU Renewable Energy Directive's tightening greenhouse gas reduction thresholds force fuel suppliers to blend higher volumes of certified sustainable fuel into road and maritime transport.
- Marine Fuel Diversification:Baltic and North Sea shipping corridors are absorbing increasing volumes of biodiesel for IMO 2030 compliance, creating new offtake for European producers.
- Rapeseed Cluster Proximity:German crushing capacity along the Rhine-Danube corridor secures feedstock cost advantages for domestic transesterification plants.
Market Restraints
- Used Cooking Oil Squeeze:Waste lipid collection infrastructure concentrates in Benelux and northern Germany, leaving southern European producers exposed to feedstock cost volatility.
- Hydrogen Supply Bottlenecks:Renewable diesel hydroprocessing requires substantial green hydrogen inputs that remain scarce and expensive across most of the continent.
- Indirect Land-Use Change Penalties:EU sustainability criteria penalize crop-based feedstocks, compressing margins for rapeseed-dependent producers relative to waste-stream competitors.
Strategic Opportunities
- Poland and Romania Feedstock Expansion:Underdeveloped agricultural waste collection networks in eastern Europe offer first-mover advantages for biorefinery siting near emerging supply bases.
- Aviation Fuel Pathway:Synthetic paraffinic kerosene certification opens long-term offtake contracts with airlines facing ReFuelEU Aviation mandates.
- Power-to-Liquid Convergence:Integration of electrolytic hydrogen with captured carbon dioxide enables e-fuel production that qualifies for double-counting under EU renewable targets.
Industry Challenges
- ISCC Certification Timeline:Multi-month audit cycles for International Sustainability and Carbon Certification delay market access for new entrants and facility expansions.
- Hydroprocessing Capex Burden:Refinery retrofit investments for renewable diesel exceed transesterification plant costs by substantial multiples, constraining balance sheet capacity.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Biodiesel Market |
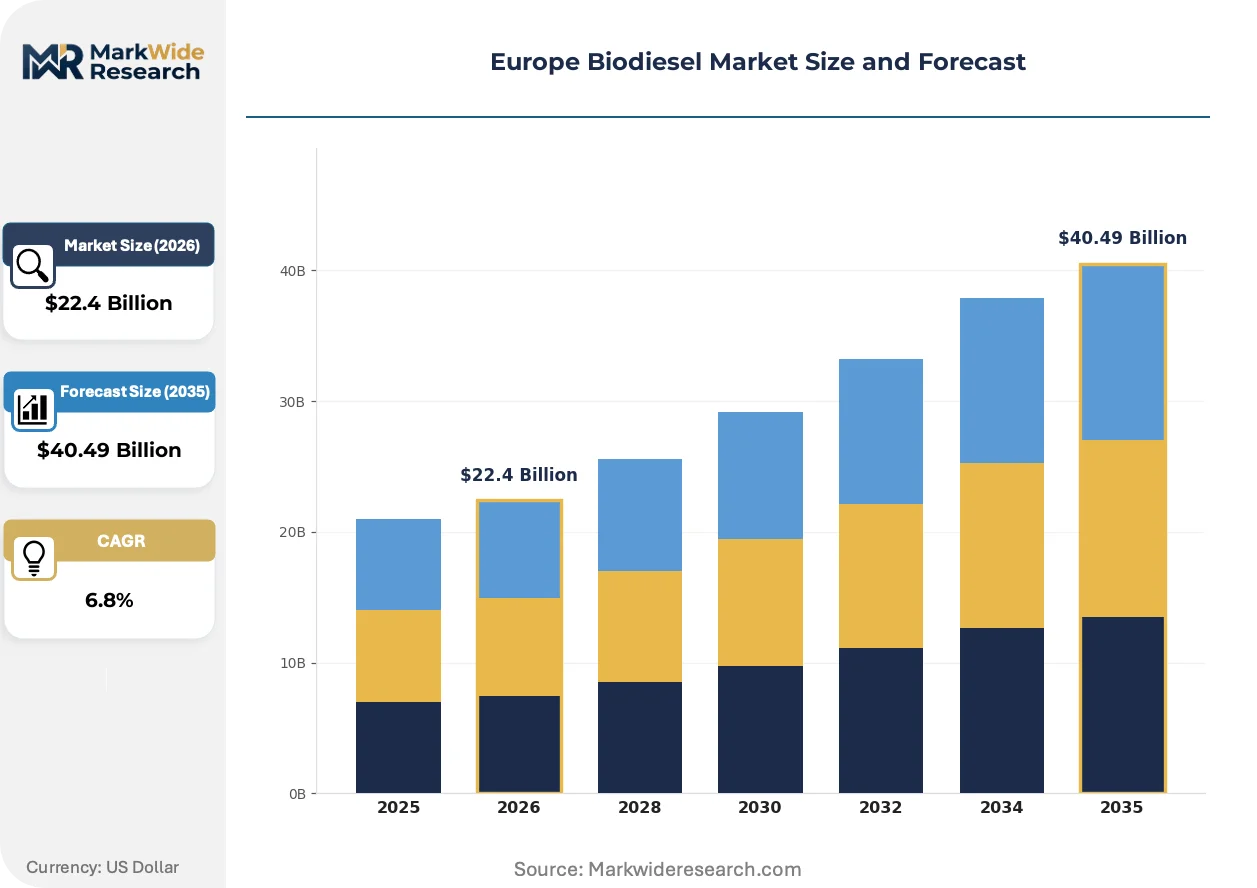
| Market Size in 2026 | $22.4 Billion |
| Market Size in 2035 | $40.49 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Vegetable Oils, Animal Fats, Used Cooking Oil, Palm Oil Production Technology: Transesterification, Hydroprocessing, Fermentation, Catalytic Conversion End Use Sector: Transportation, Power Generation, Heating, Industrial Distribution Channel: Wholesale, Retail, Direct Sales, Online |
| Companies Covered | Neste Oyj, TotalEnergies SE, Eni S.p.A., Greenergy International Ltd., Verbio AG, Münzer Bioindustrie, Repsol, Cepsa, Olleco, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Biodiesel Market Strategic Shifts & Innovations
European biodiesel production is bifurcating between commodity methyl ester and premium renewable diesel tiers, with technology choices locking in divergent margin structures for the next decade.
Containerized pretreatment units for heterogeneous waste feedstocks are modularizing deployment economics for smaller biorefineries. Agricultural cooperatives in France and Germany are piloting skid-mounted systems that decontaminate used cooking oil and animal fats on-site before transfer to central processing. This distributed configuration slashes transport costs for low-density waste streams while enabling regional producers to capture ISCC certification premiums previously reserved for integrated refiners.
REACH and F-Gas Regulation amendments are tightening traceability requirements for imported feedstocks, forcing suppliers to document chain-of-custody back to origin. The industrial consequence is accelerated due diligence spending and withdrawal of uncertified palm oil derivatives from European supply chains. Southeast Asian exporters are responding by redirecting volumes to non-EU markets while European producers accelerate domestic waste oil collection infrastructure.
Fleet procurement contracts are compressing tender cycles as logistics operators seek price hedges against fossil diesel volatility. Major German freight carriers now issue 12-18 month biodiesel supply agreements with fixed-volume, floating-price structures indexed to gas oil futures. This shift is most visible in the Rhine-Ruhr corridor, where road haulage consolidation has concentrated buying power among four national operators dictating blend specifications to refiners.
Europe Biodiesel Market Segmentation
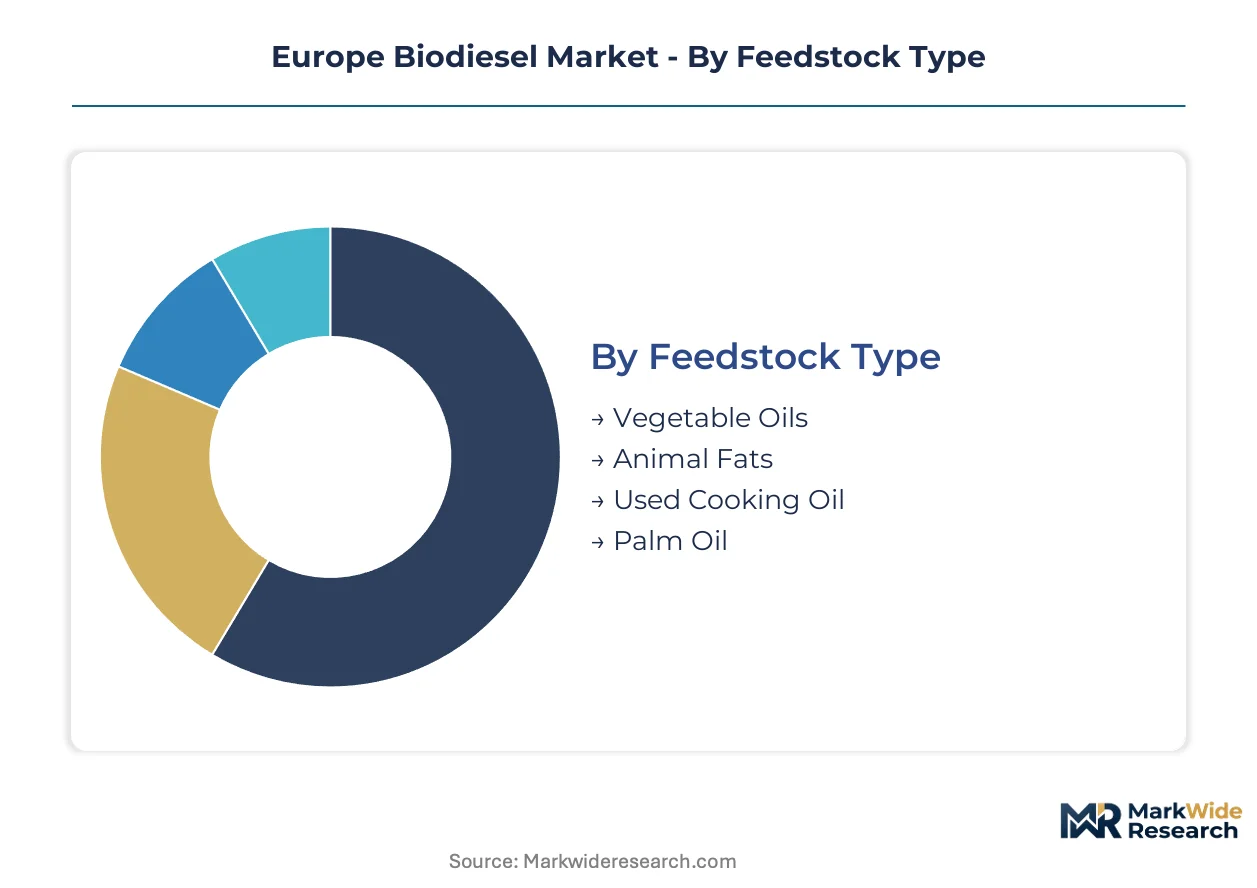
Feedstock traceability, technology capex intensity, and end-use carbon accounting rules create distinct margin pools across European biodiesel segments. Producers optimize positioning by matching production configuration to certificate premiums and offtake contract structures.
Feedstock Type:
Standardized commodity oils compete with certified waste streams for refinery intake slots, with sustainability premiums widening the effective price spread between tiers.
- Vegetable Oils:Rapeseed oil dominates German and French crush capacity, supplying transesterification plants along the Rhine corridor with predictable, volume-scalable input. Road freight operators in Bavaria and Baden-Württemberg absorb the largest share, driven by corporate fleet decarbonization mandates and RED III compliance deadlines.
- Used Cooking Oil:Waste lipid collection from Benelux and northern German hospitality sectors yields ISCC-certified feedstock with near-zero indirect land-use change risk. Maritime fuel bunkering at Rotterdam and Hamburg ports concentrates demand, as shipping operators prioritize GHG intensity scores for IMO 2030 trajectory compliance.
- Animal Fats:Category 1 and 2 tallow from German and French rendering facilities supplies niche renewable diesel production with restricted feedstock eligibility.
- Palm Oil:European import volumes have collapsed under EUDR deforestation screening and RED III sustainability penalties, leaving residual demand for pre-certified segregated supply chains.
Most installed capacity flows through Vegetable Oils. Expansion is steepest in Used Cooking Oil.
Production Technology:
Capital deployment separates incumbent transesterification assets from hydroprocessing retrofits, with margin capture diverging based on product specification and offtake channel access.
- Transesterification:Alkaline-catalyzed reaction of triglycerides with methanol produces fatty acid methyl ester meeting EN 14214 specifications for compression-ignition blending. German agricultural cooperatives and independent refiners in the Rhine-Ruhr cluster operate the majority of European nameplate capacity, supplying B7-B10 blend mandates for road transport.
- Hydroprocessing:Catalytic hydrogenation of lipids yields renewable diesel with superior cold-flow properties and seamless fossil infrastructure compatibility. Neste's Rotterdam and Singapore-adjacent capacity anchors European supply, while TotalEnergies' La Mède and Grandpuits biorefineries capture French domestic demand and export positions.
- Fermentation:Microbial lipid conversion from lignocellulosic sugars remains pre-commercial at European scale, with pilot facilities in Denmark and the Netherlands testing integrated biorefinery economics.
- Catalytic Conversion:Thermochemical upgrading of pyrolysis oils and syngas-to-liquids pathways occupy emerging technology tiers with unproven cost structures.
Transesterification holds the capacity base. Hydroprocessing climbs the fastest on margin pull-through.
End Use Sector:
Carbon accounting methodologies and blending infrastructure availability segment demand across stationary and mobile applications.
- Transportation:Road freight, passenger vehicle fleets, and maritime bunkering absorb certified biodiesel volumes under RED III and FuelEU Maritime compliance frameworks. German long-haul operators and Baltic Sea shipping corridors drive volume concentration.
- Power Generation:Combined heat and power plants in rural German and Austrian districts utilize biodiesel for grid-balancing and renewable heat quotas.
- Heating:Residential and commercial oil-fired boiler retrofits in northern Europe accept B100 or high-blend deliveries where district heating penetration lags.
- Industrial:Process heat and captive power applications in food processing and ceramics manufacturing source biodiesel for scope 1 emissions reduction.
Transportation commands volume leadership. Industrial offtake expands most quickly on corporate net-zero procurement.
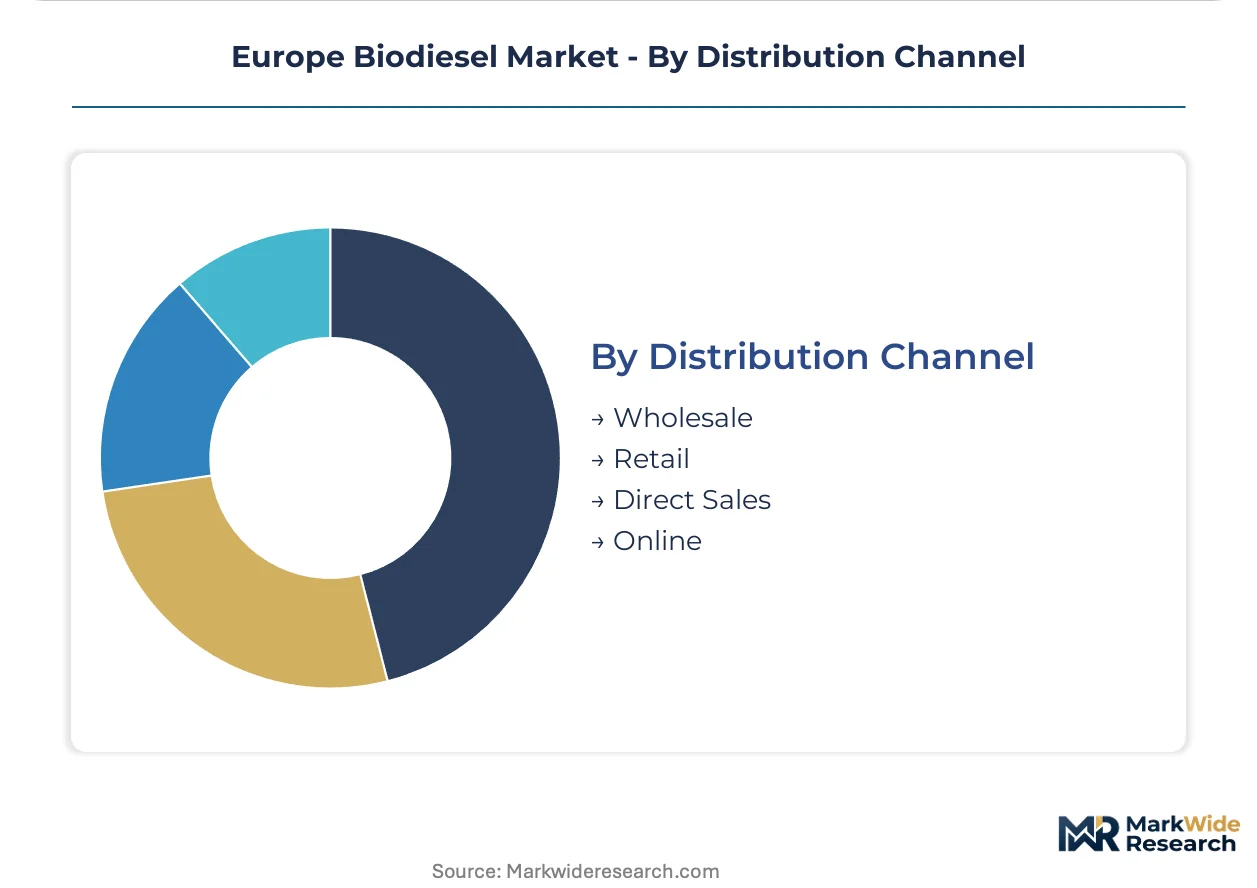
Distribution Channel:
Contract structure and price discovery mechanisms differentiate bulk wholesale from fragmented retail pathways.
- Wholesale:Term contracts between refiners and integrated oil companies or large fleet operators dominate volume flows, with pricing indexed to gas oil futures and certificate premiums.
- Retail:Branded pump stations and independent fuel retailers serve dispersed agricultural and light commercial demand across rural France and Germany.
- Direct Sales:Large industrial heat users and power generators negotiate bilateral supply agreements with dedicated logistics arrangements.
- Online:Digital procurement platforms for certificate trading and spot physical volumes are emerging in Benelux and Nordic markets.
Wholesale channels carry the throughput base. Direct sales gain share fastest on industrial decarbonization procurement.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized refining engineers and agricultural cooperative managers cluster along the Rhine corridor, anchoring Europe's biodiesel production workforce in Germany and the Netherlands.
Germany
Long-haul freight operators in Bavaria and Baden-Württemberg absorb rapeseed-based biodiesel volumes under corporate fleet decarbonization mandates. The Bundes-Immissionsschutzgesetz enforces blending quotas that pressure fuel suppliers toward certified sustainable volumes. Crushing facilities along the Rhine-Danube corridor supply transesterification plants with predictable feedstock, while inland barge distribution infrastructure reduces logistics costs for domestic producers.
France
TotalEnergies SE anchors renewable diesel supply from integrated biorefineries serving domestic road transport and export positions. The national implementation of RED III sustainability criteria shapes procurement patterns for agricultural cooperatives in the Grand Est region. La Mède and Grandpuits processing clusters capture economies of scale through co-location with conventional refining assets, enabling rapid product switching based on margin signals.
Netherlands
Rotterdam port bunkering operations concentrate maritime biodiesel demand as shipping operators prioritize GHG intensity scores for IMO 2030 compliance. REACH amendments tighten traceability requirements for imported feedstocks, forcing suppliers to document chain-of-custody documentation. Waste lipid collection infrastructure in the Randstad metropolitan area yields ISCC-certified feedstock with near-zero indirect land-use change risk.
Poland
Underdeveloped agricultural waste collection networks in eastern regions offer first-mover advantages for biorefinery siting near emerging supply bases. National transposition of EU renewable energy directives creates compliance obligations for domestic fuel distributors. Rural agricultural cooperatives pilot containerized pretreatment units that decontaminate heterogeneous feedstocks on-site before transfer to central processing facilities.
Spain
Repsol and Cepsa leverage conventional refining assets for renewable diesel retrofits targeting Iberian road freight and Mediterranean shipping corridors. National climate legislation mandates escalating renewable fuel quotas that pressure importers to secure certified supply chains. Processing clusters near Barcelona and Bilbao capture feedstock from domestic olive oil production and imported waste streams.
Europe Biodiesel Market Key Industry Players
Capital-heavy producers compete with asset-light traders across a bifurcated structure where hydroprocessing retrofits demand substantially larger balance sheet commitments than transesterification operations. Integrated oil companies anchor the premium renewable diesel tier through co-located biorefinery investments, while agricultural cooperatives and independent refiners populate the commodity methyl ester segment. Strategic archetypes include technology licensors, feedstock aggregators, and certificate traders. Dominant competitive moves center on hydroprocessing capacity expansion and ISCC certification acquisition to capture sustainability premiums.
Among Nordic-origin technology specialists, Neste Oyj exemplifies the premium-tier hydroprocessing archetype through proprietary NEXBTL deployment. TotalEnergies SE and Eni S.p.A. represent integrated oil company positioning with biorefinery co-location strategies. Verbio AG occupies a distinct specialization niche in agricultural waste-to-fuel pathways that reduce feedstock cost volatility relative to crop-dependent competitors.
| Leading Market Players |
|---|
| Neste Oyj |
| TotalEnergies SE |
| Eni S.p.A. |
| Greenergy International Ltd. |
| Verbio AG |
| Münzer Bioindustrie |
| Repsol |
| Cepsa |
| Olleco |
| Others |
Cost & Logistics Intelligence
Horizontal integration across crushing, refining, and distribution assets in the Rhine corridor anchors supply security and pricing leverage for German producers. Co-located biorefineries capture margin premiums through captive rapeseed oil supply and barge-logistics cost advantages that independent transesterification operators cannot replicate.
Pricing Analysis
Bundled long-term offtake contracts dominate wholesale transactions, while unbundled spot trading concentrates in certificate markets and waste-oil arbitrage. Three-tier pricing structure across ISCC-certified renewable diesel, standard EN 14214 methyl ester, and uncertified commodity volumes reflects sustainability grade and cold-flow performance differentiation. Cost compression in the methyl ester tier intensifies as hydroprocessing capacity expands and RED III thresholds tighten. Fleet operators with corporate decarbonization mandates exhibit lowest price sensitivity; independent agricultural cooperatives face highest margin pressure.
Supply Chain Analysis
Specialized refining engineers and agricultural cooperative managers cluster along the Rhine-Danube corridor, constraining workforce mobility for new facility development. Feedstock supply concentrates in Germany, France, and the Netherlands, with rapeseed crushing, waste lipid collection, and integrated biorefinery assets geographically interdependent. Production draws from vegetable oil crush, imported used cooking oil, and rendered animal fats, with hydrogen supply for hydroprocessing remaining a critical bottleneck. Single-source vulnerability to Benelux waste oil collection infrastructure exposes southern European producers to feedstock disruption. Distribution runs through inland barge networks and Rotterdam port bunkering terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The Europe biodiesel market functions as a regulatory compounder where RED III mandate escalation and FuelEU Maritime compliance deadlines mechanically expand addressable demand regardless of fossil fuel price cycles.
For Market Incumbents: Anticipate margin compression in commodity methyl ester production as Neste and TotalEnergies expand hydroprocessing capacity, and defend position by accelerating ISCC certification coverage and securing captive waste oil supply through backward integration into collection infrastructure. For New Entrants and Emerging Players: Launch via distributed pretreatment units in Poland and Romania where agricultural waste networks remain underdeveloped, targeting ISCC-certified feedstock aggregation for sale to integrated refiners lacking eastern European collection presence. For Investors and Strategic Acquirers: Roll-up economics work for regional waste oil collectors because fragmented hospitality-sector collection infrastructure lacks scale efficiencies and regulatory compliance capabilities that consolidated platforms can deploy. Five-to-ten year viability hinges on hydrogen supply cost curves and e-fuel technology maturation. Acquisition targets should demonstrate established ISCC audit relationships and long-term supply contracts with biorefinery operators. The signal to watch is green hydrogen electrolyzer capacity announcements at Rotterdam and Hamburg industrial clusters.| Strategic Initiative | Industry Significance |
|---|---|
| Hydroprocessing Capacity Expansion | Retrofitting conventional refineries captures renewable diesel margin premiums under RED III. |
| ISCC Certification Program | International Sustainability and Carbon Certification unlocks EU market access and sustainability premiums. |
| Waste Oil Collection Infrastructure | Backward integration into used cooking oil aggregation secures feedstock cost advantages against crop-based competitors. |
| Power-to-Liquid Pilot Development | Electrolytic hydrogen integration enables e-fuel production qualifying for double-counting under EU targets. |
| Maritime Bunkering Partnership | Rotterdam and Hamburg port supply agreements capture IMO 2030 compliance-driven demand from Baltic shipping. |
Research Approach
Bottom-up transportation sector modeling reconciled against top-down biorefinery capacity tracking forms the analytical core of this study. Primary interviews with plant managers at German and French transesterification facilities, procurement leads at integrated oil companies, EPC contractors specializing in hydroprocessing retrofits, and maritime fuel supply specialists at Rotterdam bunkering operations provided operational data. Secondary validation drew from EU RED III implementation documents, REACH feedstock traceability amendments, ISCC certification registry data, and customs records of vegetable oil and waste lipid trade flows. Top-down supply-side estimates from nameplate capacity announcements were triangulated against bottom-up demand projections from fleet operator procurement disclosures.
Input-output matrices mapping feedstock type, production technology, and end-use sector across the projection horizon generated volume and value estimates. Segmentation dimensions modeled include feedstock certification tier, hydroprocessing versus transesterification configuration, road freight versus maritime versus stationary combustion application, and wholesale versus direct sales channel structure. CAGRs were derived from least-squares fitting of annual capacity and demand trajectories. Industry-specific forecast inputs incorporated RED III greenhouse gas reduction threshold schedules and FuelEU Maritime carbon intensity benchmarks.
Forecast precision tightens around the base case; tail outcomes carry wider variance under hydrogen supply disruption or accelerated e-fuel technology cost reduction. Projections reflect assumptions regarding regulatory enforcement consistency, feedstock import restriction timelines, and biorefinery construction completion rates. Material deviation in green hydrogen electrolyzer deployment or EU deforestation regulation implementation scope warrants pause and re-evaluation.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
South-East Asia Biodiesel Market
Biofuels
Bioethanol Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Europe Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Second Generation Biofuels Market
Biofuels
United States Biodiesel Market
Biofuels
Biodiesel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Latin America Biodiesel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Brazil Biofuel Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Next Generation Biofuels Market