
 Solar Tracker for Power Generation Market | 2026-2036
Solar Tracker for Power Generation Market Size, Share, and Industry Trends Forecast 2026-2036
Solar Tracker for Power Generation Market Analytics
India is tilting toward tracker-heavy solar park development under its national renewable energy mission. NEXTracker Inc. leverages its vertically integrated steel supply and software controls to dominate utility-scale procurement in North America. Array Technologies Inc. sustains cost competitiveness through a decentralized manufacturing model that reduces logistics exposure. Arctech Solar Holding Co. Ltd. anchors Asia-Pacific demand with region-specific structural engineering for high-wind and coastal installations.
A solar tracker for power generation is a mechanical racking system that orients photovoltaic modules toward the sun throughout the day, typically achieving 20-35% additional energy yield over fixed-tilt configurations depending on latitude and weather patterns. The device employs electric motors, sensors, and control algorithms to adjust azimuth and elevation angles, serving primarily to maximize irradiance capture and improve project-level levelized cost of electricity. Single-axis trackers occupy the largest share of installed capacity due to favorable economics at utility scale, while bifacial trackers represent the fastest-expanding product category as dual-glass module deployment accelerates. Smart trackers with IoT-enabled predictive maintenance are capturing margin pools through software subscription revenues and reduced operational expenditure.
The US Inflation Reduction Act, administered through the Department of Treasury and IRS, shapes domestic demand through domestic content bonuses and standalone manufacturing credits. India's Ministry of New and Renewable Energy and Central Electricity Authority mandate domestic value-add requirements that influence tracker sourcing decisions for public tenders. The EU Green Deal and associated F-Gas Regulation indirectly affect tracker design through supply chain decarbonization requirements for steel and aluminum components. Stakeholders must monitor how evolving local content rules across multiple jurisdictions reshape competitive positioning between integrated manufacturers and pure-play tracker suppliers.
Market Dynamics
The solar tracker market is reorienting around domestic content mandates that bifurcate supply chains into regional manufacturing zones, forcing technology providers to establish localized production footprints or forfeit procurement eligibility in major tenders.
Growth Catalysts
- US IRA Domestic Content Bonuses:The Inflation Reduction Act's adder credits for domestically produced steel and assembled trackers are pulling manufacturing investment toward American fabrication facilities.
- India's Solar Park Scale-Up:State-level tenders under the national renewable energy mission increasingly specify tracker-compatible configurations, creating dedicated demand corridors for single-axis systems.
- Bifacial Module Proliferation:Dual-glass photovoltaic deployment is accelerating tracker adoption as project developers seek to maximize rear-side irradiance capture through elevated, tracking configurations.
Market Restraints
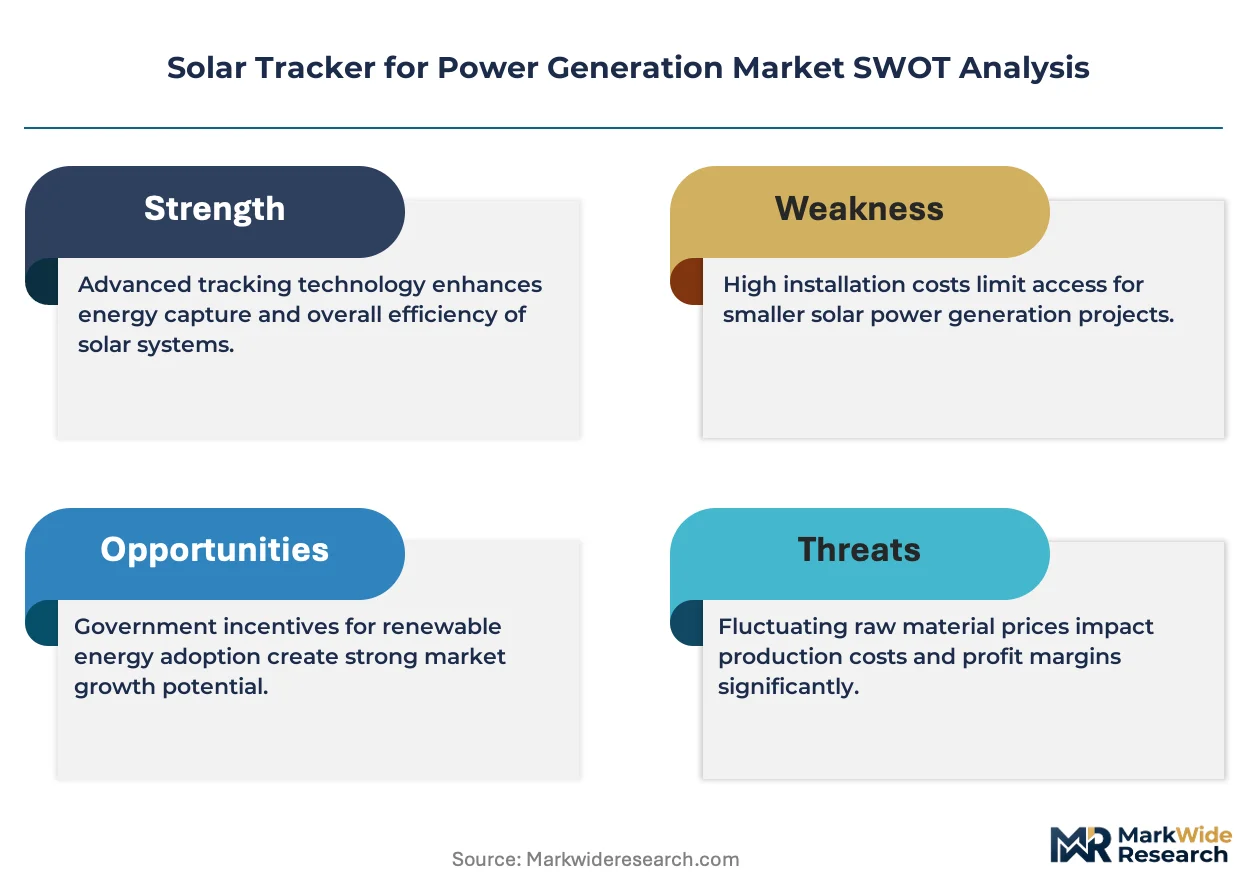
- Steel Price Volatility:Galvanized steel constitutes the primary structural input for tracker assemblies, exposing project economics to commodity swings and tariff-driven cost spikes.
- Wind Load Engineering Constraints:High-wind zones and coastal installations impose structural limitations that increase foundation costs and restrict tracker deployment in otherwise attractive solar resource regions.
- EU F-Gas Regulation Compliance:Supply chain decarbonization requirements for aluminum and steel components add certification overhead and extend procurement timelines for European project developers.
Strategic Opportunities
- IoT-Enabled Predictive Maintenance:Smart trackers with embedded sensors and cloud-based analytics platforms are opening recurring software revenue streams and reducing operational expenditure for asset owners.
- Agrivoltaics Integration:Tracker systems designed for elevated clearance and adjustable tilt angles are penetrating agricultural land-use configurations, unlocking dual-revenue models for farmers and energy developers.
- India PLI Scheme Tailwinds:Production-linked incentive schemes for solar module and component manufacturing are lowering landed costs for tracker assemblies in the fastest-expanding demand geography.
Industry Challenges
- Control Systems Integration Complexity:Tracker fleets must interface with plant-level SCADA and grid dispatch systems, requiring specialized software engineering talent that remains scarce in emerging solar markets.
- Foundation Civil Works Coordination:Geotechnical variability across project sites demands customized pile driving and anchoring approaches, compressing installation margins and extending project timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Solar Tracker for Power Generation Market |
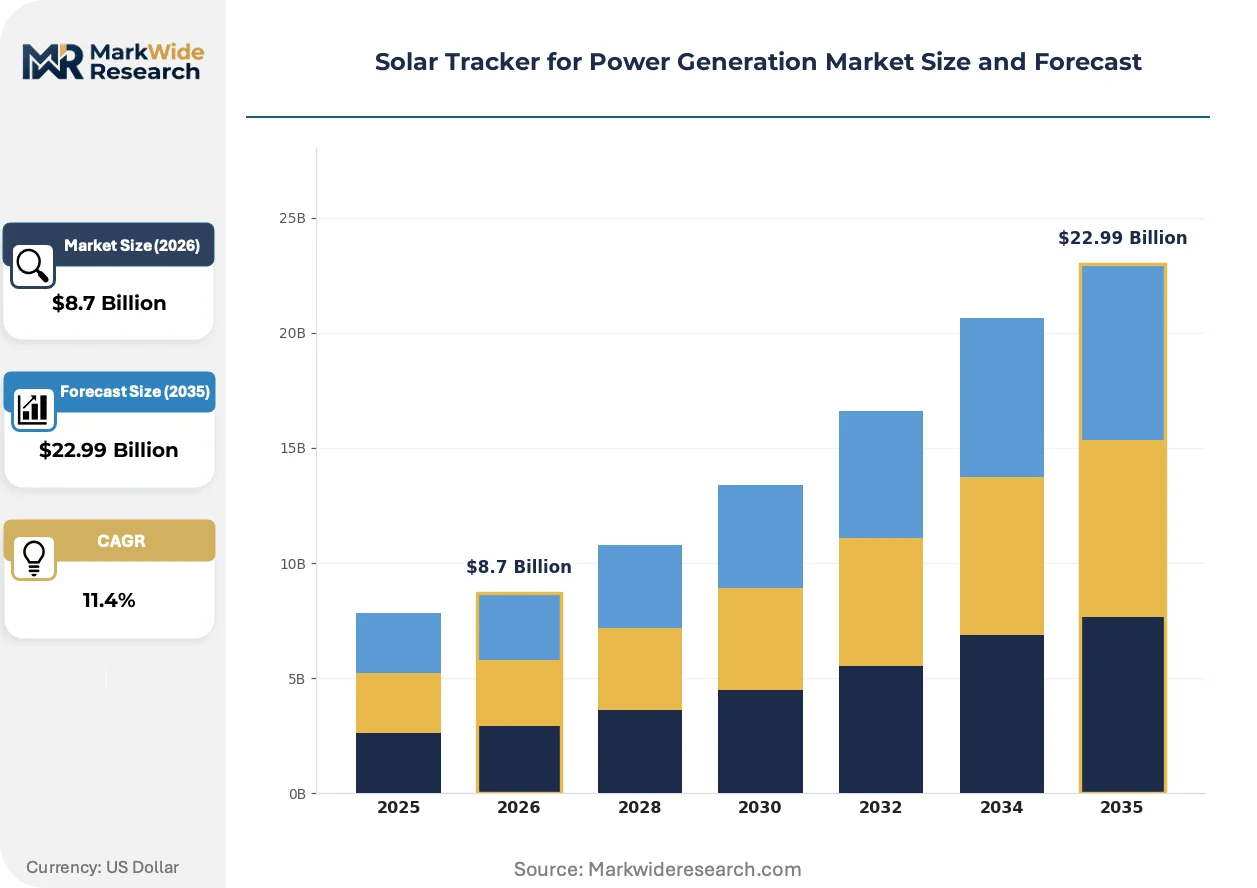
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $22.99 Billion |
| CAGR (2026 – 2036) | 11.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Single Axis, Dual Axis, Smart Trackers, Bifacial Trackers Application: Utility Scale, Commercial, Residential, Ground Mounted Technology: Active Tracking, Passive Tracking, Hybrid Systems, IoT Enabled End User: Utility Providers, Independent Power Producers, Residential Users, Business Enterprises |
| Companies Covered | NEXTracker Inc., Array Technologies Inc., Arctech Solar Holding Co. Ltd., Soltec Power Holdings SA, PV Hardware Solutions S.L.U., Trina Solar Co. Ltd., FTC Solar Inc., GameChange Solar, Valmont Industries Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Solar Tracker for Power Generation Market Evolving Landscape
Tracker technology is converging with digital infrastructure and module-level power electronics, transforming mechanical racking into intelligent energy systems that optimize yield through real-time environmental response.
Artificial intelligence-driven control algorithms are hybridizing with traditional astronomical tracking methods, enabling predictive positioning that anticipates cloud cover and diffuse light conditions. Utility-scale developers in the southwestern United States are deploying these systems to minimize clipping losses during variable weather. The fusion of machine learning with hardware control is compressing the performance gap between premium and standard tracker tiers.
The EU Green Deal's embedded carbon reporting requirements through the Carbon Border Adjustment Mechanism are forcing tracker manufacturers to document supply chain emissions for steel and aluminum inputs. European project developers now prioritize suppliers with verified low-carbon production processes. This regulatory pressure is accelerating investment in electric arc furnace steel and recycled aluminum sourcing across the continent's supplier base.
Asset owners are consolidating procurement decisions under engineering-procurement-construction firms with tracker design-build capabilities, displacing direct manufacturer relationships. This channel concentration shifts pricing power toward large EPCs with multi-gigawatt pipeline visibility. The pattern is most pronounced in India and Brazil, where integrated developers prefer single-contract accountability over component-level sourcing.
Solar Tracker for Power Generation Market Segmentation
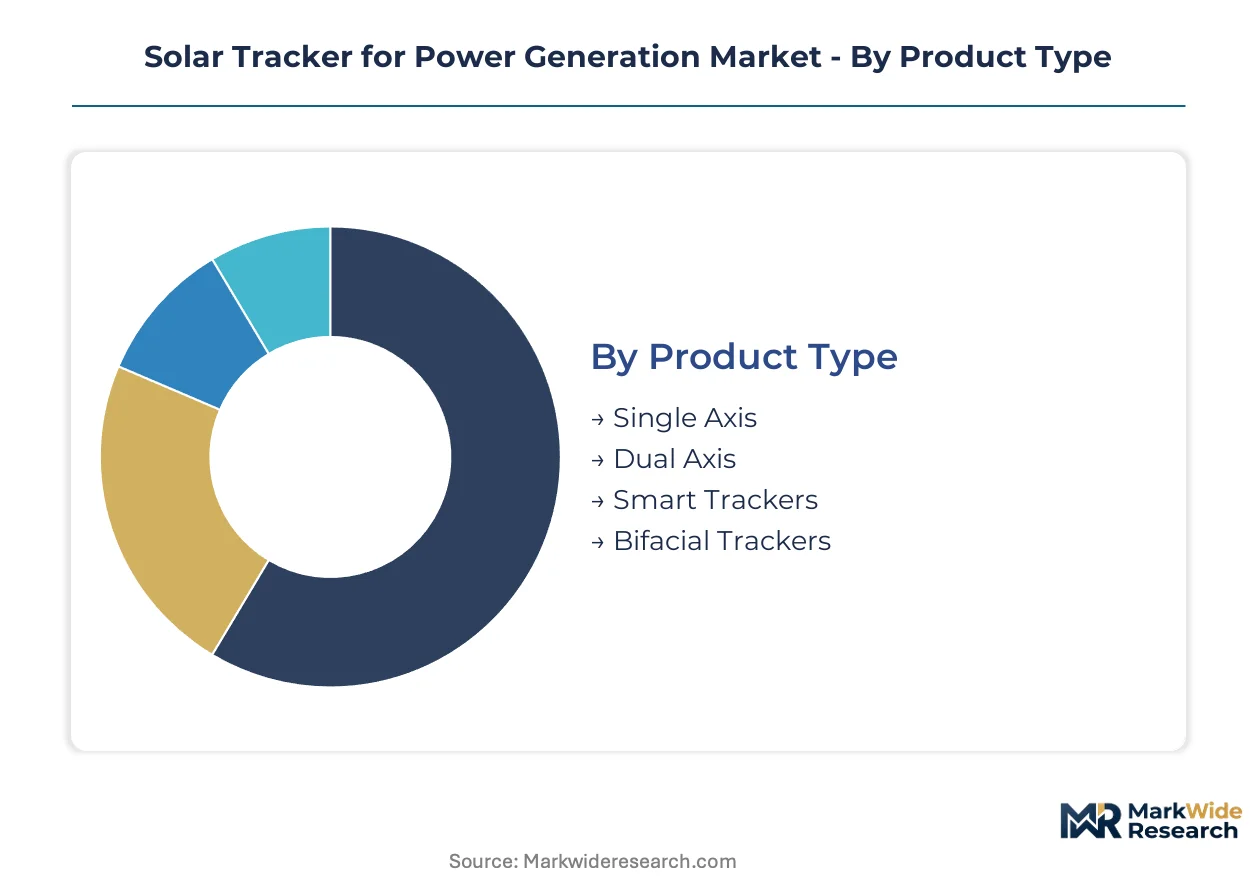
Tracker segmentation reveals divergent service intensity profiles across product architectures. Single-axis systems demand minimal field intervention, while smart tracker deployments generate recurring software maintenance contracts that reshape vendor economics over project lifecycles.
Product Type:
After-sales-service intensity varies sharply across mechanical complexity tiers, with sensor-laden configurations requiring predictive maintenance subscriptions.
- Single Axis:Horizontal or tilted rotation along one plane dominates utility-scale procurement due to favorable cost-yield ratios. Project developers in India specify these systems for state-level solar park tenders seeking elevated capacity factors without premium hardware expenditure.
- Dual Axis:Azimuth and elevation articulation maximizes irradiance capture at high latitudes but doubles mechanical complexity and foundation requirements. European installations facing EU F-Gas Regulation compliance pressures favor these systems for premium rooftop and constrained-site applications where yield optimization outweighs capital cost premiums.
- Smart Trackers:Embedded sensors and cloud-connected control platforms enable predictive positioning algorithms.
- Bifacial Trackers:Elevated, tracking configurations optimized for dual-glass module rear-side gain.
Single Axis holds the largest share; momentum sits with Bifacial Trackers.
Application:
Customer procurement scale determines integration complexity, with gigawatt-level developers demanding fleet-wide SCADA interoperability.
- Utility Scale:Single-axis tracking arrays exceeding 100 MW capacity anchor demand volume. US developers leverage IRA domestic content bonuses to source steel-intensive tracker assemblies from American fabrication facilities, compressing project-level LCOE through tax credit stacking.
- Commercial:Rooftop and carport installations between 100 kW and 5 MW deploy compact single-axis or fixed-tilt hybrids. Indian commercial enterprises under state net-metering regimes adopt these systems for captive consumption models that offset grid tariff volatility.
- Residential:Backyard-scale tracking remains niche due to structural footprint constraints.
- Ground Mounted:Agricultural land-use configurations favor elevated tracker clearance for agrivoltaic dual-revenue models.
Utility Scale commands procurement volume; Commercial applications are expanding most quickly.
Technology:
Control architecture sophistication separates capital expenditure tiers from operational expenditure profiles across tracker fleets.
- Active Tracking:Motor-driven positioning using GPS and astronomical algorithms delivers precision alignment. Southwestern US utility-scale developers deploy these systems to minimize clipping losses during variable weather patterns that challenge fixed-tilt economics.
- Passive Tracking:Thermal or hydraulic actuation without external power suits off-grid and remote installations. African and Southeast Asian micro-grid operators favor these configurations where electrical infrastructure reliability remains constrained.
- Hybrid Systems:Combined active-passive architectures balance precision with backup resilience.
- IoT Enabled:Sensor networks and edge computing enable real-time performance optimization.
Active Tracking retains dominant installed base; IoT Enabled systems show steepest expansion trajectory.
End User:
Balance-sheet capacity and regulatory access differentiate procurement behavior across ownership structures.
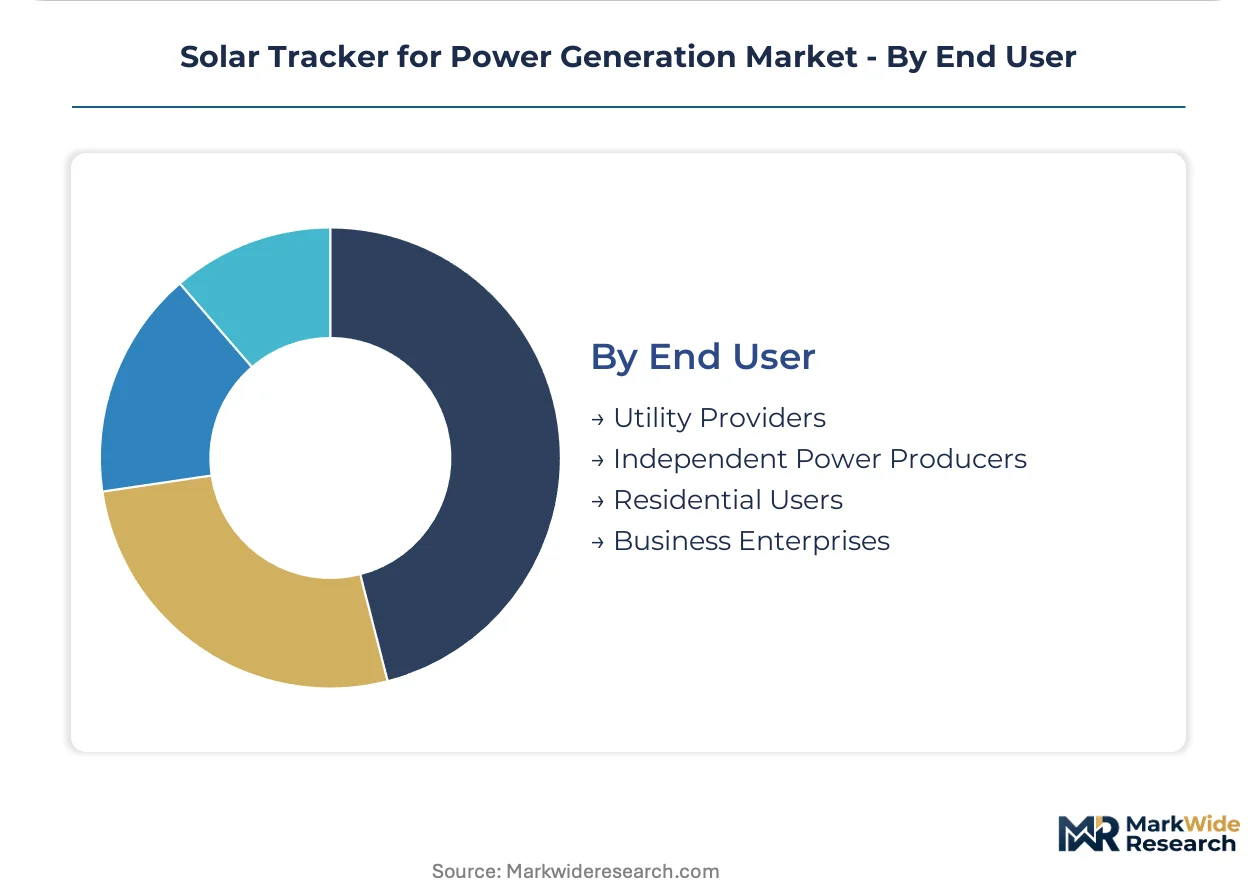
- Utility Providers:Vertically integrated electric utilities with investment-grade ratings deploy tracker fleets through engineering-procurement-construction partnerships. These stakeholders prioritize 25-year asset life and manufacturer balance-sheet backing for warranty enforcement.
- Independent Power Producers:Project finance-dependent developers monetize tax credits and power purchase agreements. US IPPs structure ownership around IRA domestic content bonus eligibility, sourcing tracker assemblies from qualified American fabrication facilities.
- Residential Users:Individual homeowners with distributed generation permits.
- Business Enterprises:Corporates executing renewable energy procurement for Scope 2 emissions targets.
Utility Providers anchor procurement volume; Independent Power Producers are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Steel fabrication clusters and module assembly plants are concentrating tracker supply chains in specific manufacturing corridors, while project development capital flows toward jurisdictions with production tax credit clarity and domestic content enforcement.
United States
Utility-scale developers in Texas and Arizona are deploying single-axis systems at record pace to capture IRA domestic content bonuses. The Department of Treasury and IRS administer tax credit eligibility rules that require qualified steel and assembled components from American fabrication facilities. NEXTracker Inc. anchors manufacturing in the Southwest industrial corridor.
India
State-level solar park tenders in Rajasthan and Gujarat increasingly specify tracker-compatible configurations under the national renewable energy mission. The Ministry of New and Renewable Energy mandates domestic value-add requirements through Central Electricity Authority guidelines. Arctech Solar Holding Co. Ltd. has established engineering presence for high-wind coastal installations.
Germany
Premium rooftop and constrained-site applications favor dual-axis configurations where yield optimization outweighs capital cost premiums. The EU Green Deal and F-Gas Regulation impose supply chain decarbonization requirements for steel and aluminum components. Array Technologies Inc. serves demand through European distribution partnerships.
Brazil
Agrivoltaic configurations with elevated tracker clearance are penetrating agricultural land-use models in Minas Gerais and São Paulo states. ANVISA and national development bank BNDES shape procurement through local content scoring in renewable energy auctions. Soltec Power Holdings SA anchors Ibero-American demand with region-specific structural engineering.
Australia
Remote mine sites and micro-grid operators favor passive tracking configurations where electrical infrastructure reliability remains constrained. The Clean Energy Regulator and Australian Energy Market Operator administer grid connection standards that influence control system specifications. FTC Solar Inc. has established presence for utility-scale procurement in Queensland and Western Australia.
Solar Tracker for Power Generation Market Competitive Landscape
Vertically integrated steel suppliers and pure-play tracker specialists split the market between cost-controlled volume production and software-differentiated premium positioning. The vendor base concentrates around three strategic archetypes: captive steel producers with in-house fabrication, control-system specialists licensing hardware platforms, and diversified solar manufacturers bundling trackers with module supply. Competitive moves center on regional manufacturing footprint expansion to satisfy domestic content mandates and predictive maintenance software subscription models.
Among North American integrated manufacturers, NEXTracker Inc. and Array Technologies Inc. occupy positions defined by steel supply control and decentralized production models respectively. Arctech Solar Holding Co. Ltd. represents the Asia-Pacific engineering-specialist archetype with region-specific structural adaptations. These three anchors exemplify how competitive positioning diverges between supply-chain-integrated and technology-differentiated strategies across major demand geographies.
| Leading Market Players |
|---|
| NEXTracker Inc. |
| Array Technologies Inc. |
| Arctech Solar Holding Co. Ltd. |
| Soltec Power Holdings SA |
| PV Hardware Solutions S.L.U. |
| Trina Solar Co. Ltd. |
| FTC Solar Inc. |
| GameChange Solar |
| Valmont Industries Inc. |
| Others |
Value Network & Pricing Analysis
Underutilization at Chinese steel mills is compressing input costs for tracker manufacturers while simultaneously eroding pricing power across standard-tier assemblies. This capacity slack forces suppliers into volume-driven bidding wars for utility-scale procurement contracts in India and the United States.
Pricing Analysis
The US Inflation Reduction Act dictates the pricing tier structure through domestic content bonus eligibility thresholds. Project developers capture tax credit differentials by sourcing qualified steel from American fabrication facilities, creating a three-tier pricing structure across premium, standard, and economy levels. Cost compression in economy-tier assemblies is intensifying because Indian and Southeast Asian producers are flooding spot markets with excess galvanised steel inventory. Independent power producers exhibit the highest price sensitivity due to project finance leverage constraints, while vertically integrated utilities demonstrate greater tolerance for premium hardware expenditure.
Supply Chain Analysis
Export controls on high-precision motor controllers and sensor arrays are fragmenting technology flows between North American and Asia-Pacific manufacturing zones. Tracker assembly draws from steel production concentrated in China, India, and the United States, with control systems sourcing anchored in Taiwan, South Korea, and Germany. Supply chain risk centres on single-source vulnerability for astronomical tracking algorithms and cloud-based fleet management platforms. Distribution runs through engineering-procurement-construction firms with multi-gigawatt pipeline visibility, displacing direct manufacturer relationships in India and Brazil.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Buyer power is concentrating among a shrinking cohort of mega-developers with multi-gigawatt procurement visibility, fragmenting pricing leverage across smaller independent power producers. This consolidation is reshaping contract structures toward master service agreements with embedded volume commitments.
For Market Incumbents: Insulate margin pools by securing captive steel supply through backward integration into galvanising facilities in Texas and Gujarat. Establish software subscription revenue streams through predictive maintenance platforms that lock in 20-year service contracts. The threat of pure-play control-system specialists licensing hardware platforms demands immediate investment in proprietary IoT-enabled fleet management architectures. For New Entrants and Emerging Players: Pursue agrivoltaic configurations in Brazil and Australia where elevated clearance requirements create specification gaps incumbent suppliers have overlooked. The most penetrable segment sits with passive tracking systems for remote mine sites and micro-grid operators in African and Southeast Asian markets lacking reliable electrical infrastructure. A go-to-market angle anchored in thermal-hydraulic actuation without external power addresses off-grid demand corridors established players have deprioritised. For Investors and Strategic Acquirers: Long-term, this sits as a domestic-content-arbitrage play because jurisdictional manufacturing mandates are permanently reshaping competitive moats around regional fabrication footprints. Acquisition targets should display qualified steel supply integration or software-differentiated control platforms with recurring revenue profiles. The signal to watch is enforcement granularity in Treasury Department domestic content rulings that determine eligibility thresholds for bonus tax credits.| Strategic Initiative | Industry Significance |
|---|---|
| Domestic Manufacturing Footprint Expansion | IRA compliance eligibility secures access to utility-scale procurement pipelines in Texas and Arizona. |
| Predictive Maintenance Software Launch | IoT-enabled fleet analytics generate recurring revenue streams across 25-year asset lifecycles. |
| Agrivoltaic Tracker Configuration Development | Elevated clearance designs unlock dual-revenue agricultural land-use models in Brazil and Australia. |
| Steel Supply Backward Integration | Captive galvanising capacity insulates margins from commodity volatility and tariff exposure. |
| High-Wind Structural Engineering Certification | Region-specific coastal installation approvals open tenders in Gujarat and Queensland markets. |
Research Methodology
Cross-validation between EIA project development databases and FERC interconnection filings anchors the qualitative findings on utility-scale deployment trajectories. Primary interviews with IPP project developers, EPC procurement leads, tracker manufacturer sales directors, and utility planning officers combined with secondary validation against IEA renewable energy reports, customs trade data, and SEC 10-K equipment supplier disclosures. Bottom-up installation forecasts triangulate against top-down capacity factor assumptions across single-axis, dual-axis, and smart tracker configurations.
Calibration against historical capacity additions and module shipment correlations shapes the analytical framework across the projection horizon. Segmentation dimensions modelled include product architecture complexity, project scale tier, control system technology, and regional regulatory framework cluster. CAGRs derive from slope-consistent growth trajectory fitting against steel price elasticity and domestic content bonus uptake assumptions. Forecast inputs incorporate bifacial module penetration rates and agrivoltaic land-use configuration adoption.
Sensitivities concentrate around Treasury Department guidance on domestic content thresholds and Indian PLI scheme enforcement granularity. Forecasts reflect documented assumptions on tax credit durability and state-level solar park tender specifications. Material shifts in IRA domestic content rulings or EU Carbon Border Adjustment Mechanism steel import protocols would require updated calibration.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Solar Power Systems
Solar Fuel Market
Solar Power Systems
Bifacial Solar Cells Market
Solar Power Systems
US Solar Market
Solar Power Systems
Slovakia Renewable Energy Market
Solar Power Systems
Global Crystalline Solar Cells Market
Solar Power Systems
3D Printed Solar Energy Trees Market
Solar Power Systems
High-Efficiency Solar Modules Market
Solar Power Systems
Off-Grid Solar Generator Market
Solar Power Systems
Portable Solar Charger Market
Solar Power Systems
Ecuador Solar Energy Market
Solar Power Systems
Solar Photovoltaic Glass Market
Solar Power Systems
Grid-Connected Solar Microinverter Market
Solar Power Systems
Germany Distributed Solar Power Generation Market
Solar Power Systems
Smart Solar Power Market
Solar Power Systems
Bacteria Powered Solar Cell Market
Solar Power Systems
Solar Rack Market