
 United States Biodiesel Market | 2026-2036
United States Biodiesel Market Size, Share, and Industry Trends Forecast 2026-2036
United States Biodiesel Market Intelligence
Iowa and Illinois are rewriting the production geography of American biodiesel. Renewable Energy Group leverages its multi-feedstock technology platform across Upper Midwest facilities. Archer Daniels Midland sustains crushing-scale advantages through integrated soybean oil supply chains. Cargill competes via farmer-producer networks that secure feedstock origination.
Biodiesel comprises fatty acid methyl esters synthesized from vegetable oils or animal fats through transesterification, yielding a drop-in diesel substitute with cetane ratings typically exceeding 48 and sulfur content below 15 ppm. The fuel serves transportation, heating, and industrial combustion applications requiring petroleum displacement with minimal engine modification. Soybean oil dominates feedstock supply, though used cooking oil channels are expanding fastest as collection infrastructure matures and lipid extraction technologies improve unit economics. Fleet operators represent the deepest end-user margin pool, while retail fuel providers occupy a structurally thinner position constrained by rack pricing and blender tax credit pass-through mechanics.
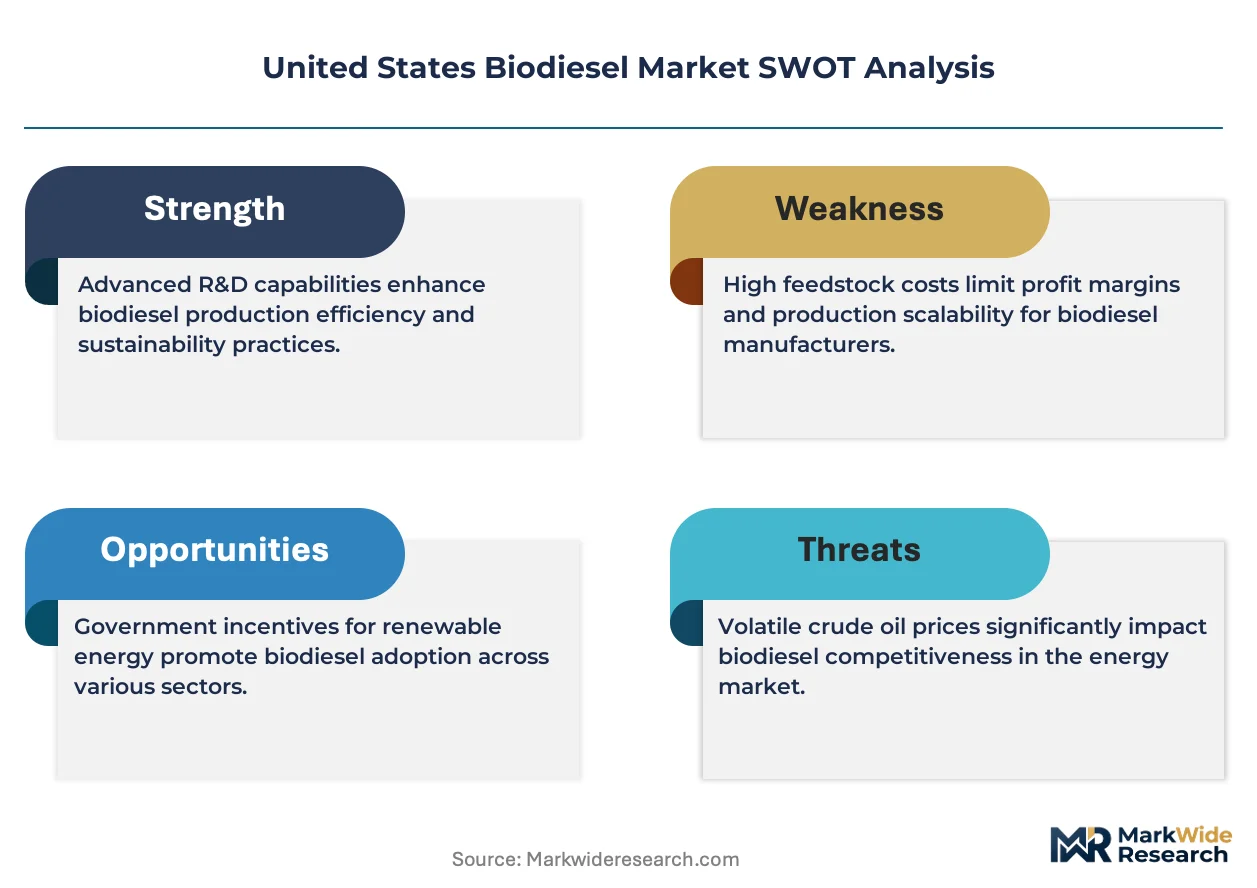
The EPA administers Renewable Fuel Standard volume obligations that mandate annual biofuel blending quotas, while the IRS governs the biodiesel mixture excise tax credit that shapes blender economics. State regulators in Iowa and Illinois supplement federal frameworks with production incentives and fuel quality standards. Stakeholders must monitor RIN price volatility and feedstock cost spreads to time capacity commitments and hedging strategies.
Market Dynamics
The EPA's Renewable Fuel Standard mandates are compressing compliance timelines for obligated parties, forcing accelerated capital deployment into multi-feedstock processing infrastructure across the Upper Midwest soybean belt.
Growth Catalysts
- Renewable Fuel Standard mandates:The EPA's escalating annual volume obligations create binding demand floors for obligated refiners and importers, locking in offtake commitments regardless of petroleum price cycles.
- Used cooking oil collection networks:Restaurant grease trap aggregation infrastructure in metropolitan Chicago and Des Moines is expanding feedstock diversification beyond soybean oil dependence.
- Fleet decarbonization targets:Municipal transit authorities in Illinois and Iowa are mandating B20 minimum blends in diesel procurement specifications, creating anchored demand pools.
Market Restraints
- Soybean oil price volatility:Crush margin fluctuations at Archer Daniels Midland and Cargill facilities transmit directly to biodiesel production economics, compressing blender margins during commodity spikes.
- Midwest supply corridor concentration:Iowa and Illinois processing clusters account for disproportionate national capacity, creating regional disruption risk from weather or logistics interruptions.
- FAME cold-flow limitations:Fatty acid methyl ester gelling above -15°C restricts winter blending ratios in northern tier states without pour-point depressant additives.
Strategic Opportunities
- California Low Carbon Fuel Standard:Out-of-state producers can capture LCFS credit premiums by routing supply through West Coast distribution terminals, arbitraging Midwest production costs against coastal clean fuel deficits.
- Railcar injection blending:Biodiesel rack injection at unit train terminals enables pipeline-integrated distribution without dedicated tankage infrastructure at every destination terminal.
- Renewable diesel co-processing:Hydrotreated renewable diesel production at existing petroleum refineries offers pathway to maximize RIN generation per feedstock gallon.
Industry Challenges
- RIN verification auditing:The EPA's quality assurance program imposes documentation burdens on small producers lacking enterprise compliance systems, raising administrative cost structures.
- Feedstock contamination protocols:Free fatty acid thresholds in used cooking oil require pretreatment capital expenditure that stranded first-generation facilities cannot economically retrofit.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Biodiesel Market |
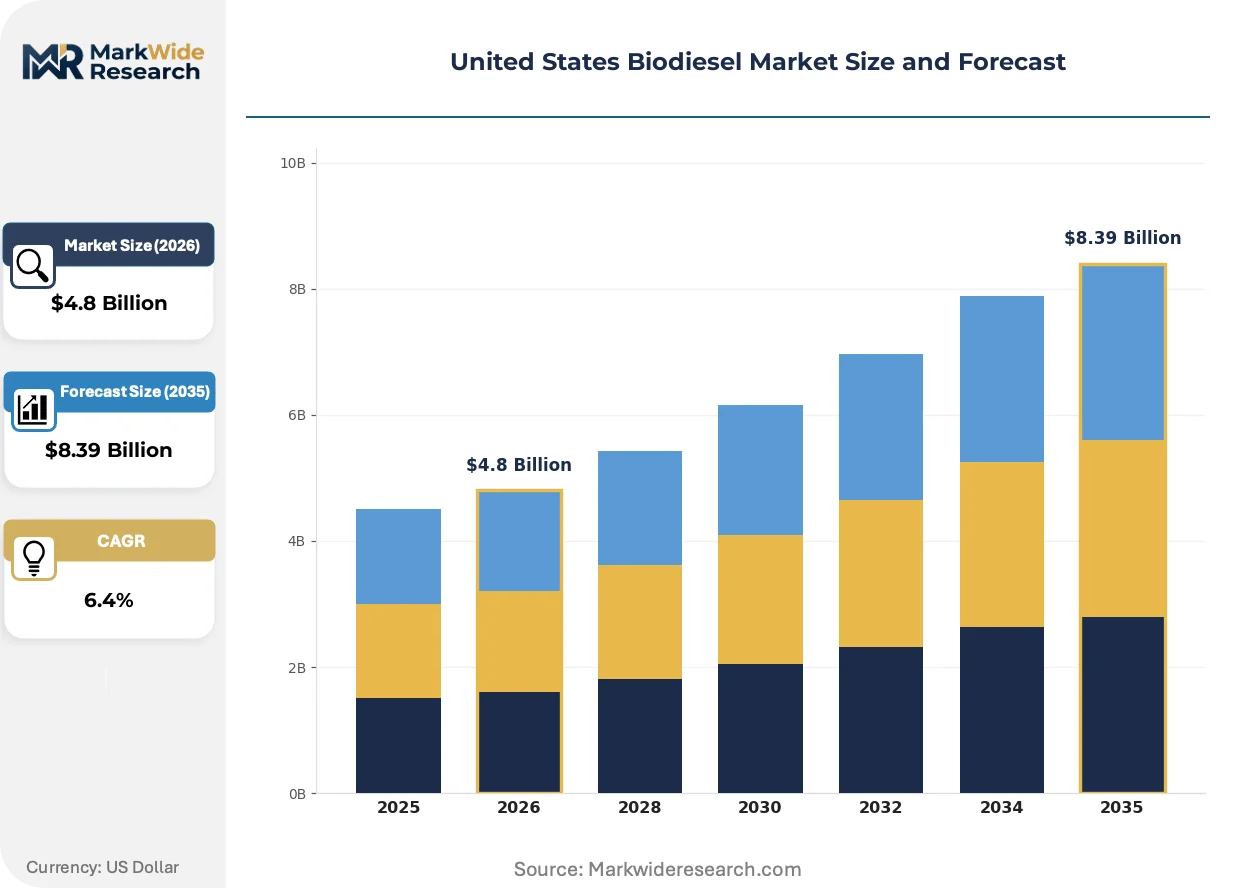
| Market Size in 2026 | $4.8 Billion |
| Market Size in 2035 | $8.39 Billion |
| CAGR (2026 – 2036) | 6.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Soybean Oil, Canola Oil, Used Cooking Oil, Animal Fat Application: Transportation Fuels, Industrial Usage, Heating, Electricity Generation Production Technology: Transesterification, Lipid Extraction, Pyrolysis, Fermentation End User: Agriculture, Fleet Operators, Retail Fuel Providers, Energy Companies |
| Companies Covered | Renewable Energy Group, Archer Daniels Midland Company, Cargill, Valero Energy Corporation, Ag Processing Inc, Neste Corporation, Marathon Petroleum Corporation, Flint Hills Resources, Bunge Limited, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Biodiesel Market Strategic Shifts & Innovations
Processing technology advances and regulatory credit mechanics are restructuring competitive economics in American biodiesel, collapsing historical barriers between feedstock categories and geographic markets.
Hydrotreatment is collapsing the historical separation between biodiesel and renewable diesel categories, enabling petroleum refiners to process lipids in existing hydroprocessing units without dedicated transesterification assets. Valero and Marathon Petroleum are retrofitting Gulf Coast and California facilities to run increasing renewable feedstock percentages, eroding the equipment-based moats of standalone FAME producers. This convergence is compressing RIN generation premiums toward parity across production pathways.
The Inflation Reduction Act's clean fuel production credit is restructuring blender economics by substituting technology-neutral incentives for the lapsed biodiesel mixture excise tax credit. The IRS guidance on 45Z credit qualification is forcing processors to document lifecycle carbon intensity through approved pathways, advantaging facilities with feedstock traceability systems. California and Oregon clean fuel programs are amplifying this effect by stacking state credit value on qualifying shipments.
Fleet operators are consolidating procurement around certified low-carbon-intensity fuel contracts that bundle RIN retirement, LCFS credit transfer, and Scope 3 emissions reporting into single-source agreements. This bypasses traditional rack-based spot purchasing through fuel jobbers, concentrating volume commitments with integrated producers capable of documentation transparency. The pattern is most pronounced in Illinois municipal and private fleet tenders, where sustainability officers now specify pathway-certified supply.
United States Biodiesel Market Segmentation
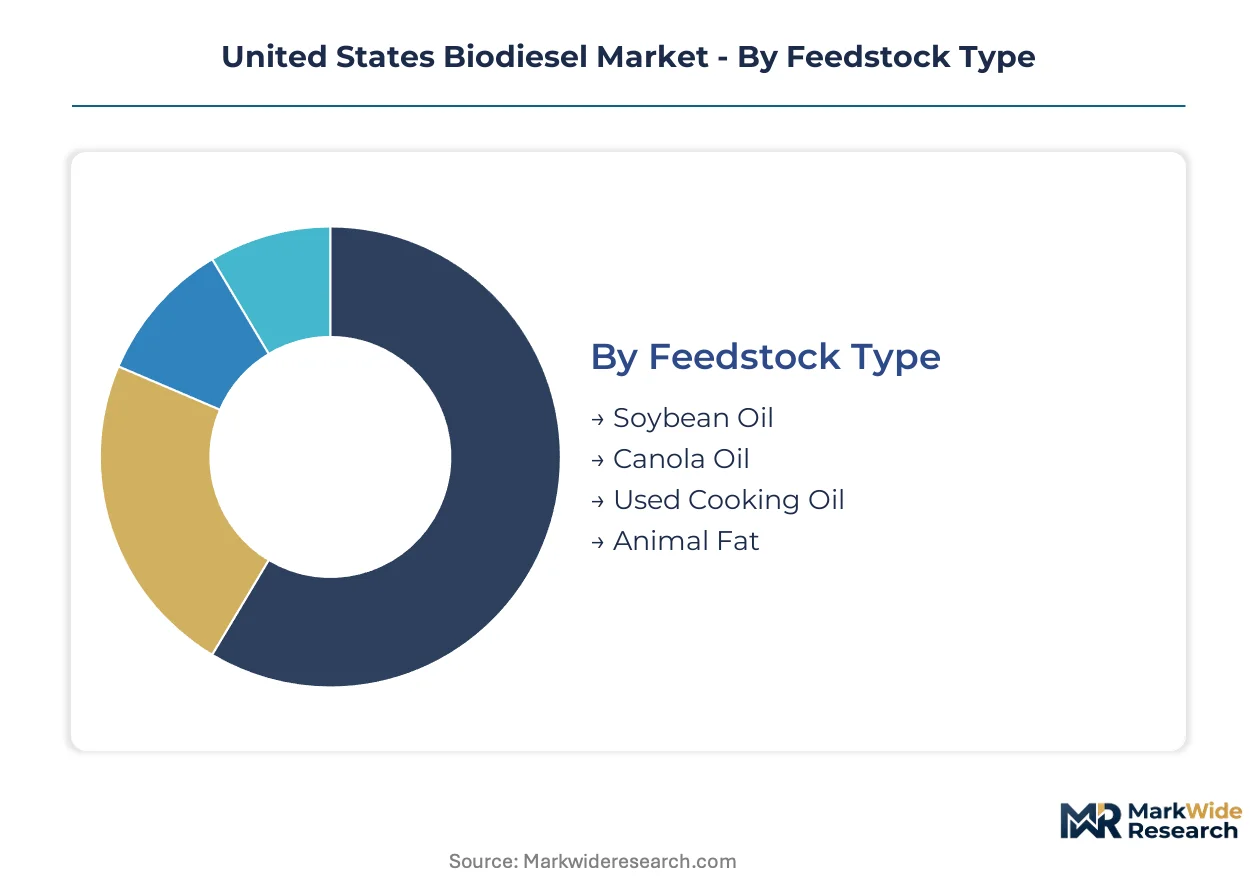
Segmentation in the United States biodiesel market reveals how feedstock economics, production pathways, and end-use specifications create distinct competitive arenas. Each dimension carries different margin profiles, regulatory exposure, and capital intensity requirements that shape strategic positioning across Iowa, Illinois, and adjacent supply corridors.
Feedstock Type:
The use-case spectrum spans commodity agriculture to waste stream valorization, with each feedstock carrying distinct carbon intensity scores, pretreatment requirements, and tax credit eligibility under IRS and California Air Resources Board frameworks.
- Soybean Oil:Crude degummed soybean oil dominates national production volumes through integrated crushing infrastructure at Archer Daniels Midland and Cargill facilities across the Upper Midwest. Iowa and Illinois processors rely on this feedstock for RIN generation certainty, though crush margin volatility transmits directly to blender economics.
- Used Cooking Oil:Yellow grease and trap grease aggregation from metropolitan Chicago and Des Moines restaurant networks is expanding fastest as collection logistics mature and free fatty acid pretreatment technologies improve. The segment commands LCFS credit premiums due to lower lifecycle carbon intensity scores.
- Canola Oil:Canadian import channels and domestic North Dakota crushing supply this higher-cetane alternative, primarily serving northern tier blenders seeking cold-flow performance advantages.
- Animal Fat:Tallow and poultry fat from integrated meatpacking operations offer low-cost feedstock for multi-feedstock facilities with acid esterification capabilities.
The dominant share belongs to Soybean Oil, while Used Cooking Oil is closing the gap fastest.
Application:
Cost tier differentiation separates high-volume transportation contracts from premium-priced thermal applications where carbon accounting drives procurement decisions.
- Transportation Fuels:B5 to B20 blending into on-road diesel pools constitutes the volume anchor, with fleet operators in Illinois municipal transit systems mandating minimum blend specifications. EPA RIN retirement obligations lock in baseline demand regardless of petroleum price cycles.
- Heating:Residential and commercial fuel oil displacement in New England and Mid-Atlantic markets commands seasonal premiums, with Bioheat branding programs establishing quality certification tiers.
- Industrial Usage:Marine, mining, and construction equipment operators are adopting B100 for stationary applications where engine warranty restrictions do not apply.
- Electricity Generation:Peaking power plants and industrial cogeneration facilities utilize biodiesel for renewable portfolio standard compliance in states with clean electricity mandates.
Transportation Fuels absorbs the majority of production volume, though Heating applications sustain the highest per-gallon margins.
Production Technology:
Technology maturity determines capital deployment timelines, with established transesterification routes competing against emerging thermochemical pathways for RIN qualification.
- Transesterification:Alkaline-catalyzed conversion of triglycerides to fatty acid methyl esters remains the incumbent technology, with continuous-flow designs dominating new capacity additions in Iowa.
- Lipid Extraction:Solvent and mechanical separation processes for algae and oilseed feedstocks are gaining traction as pretreatment steps for renewable diesel coprocessing.
- Pyrolysis:Thermochemical decomposition of biomass to bio-oil intermediates offers pathway diversification for facilities seeking 45Z credit qualification through novel carbon intensity scores.
- Fermentation:Microbial lipid production from sugar feedstocks remains pre-commercial, with pilot facilities targeting cellulosic RIN categories.
Transesterification retains installed capacity dominance, while Lipid Extraction is expanding most quickly as hydrotreater feedstock demand rises.
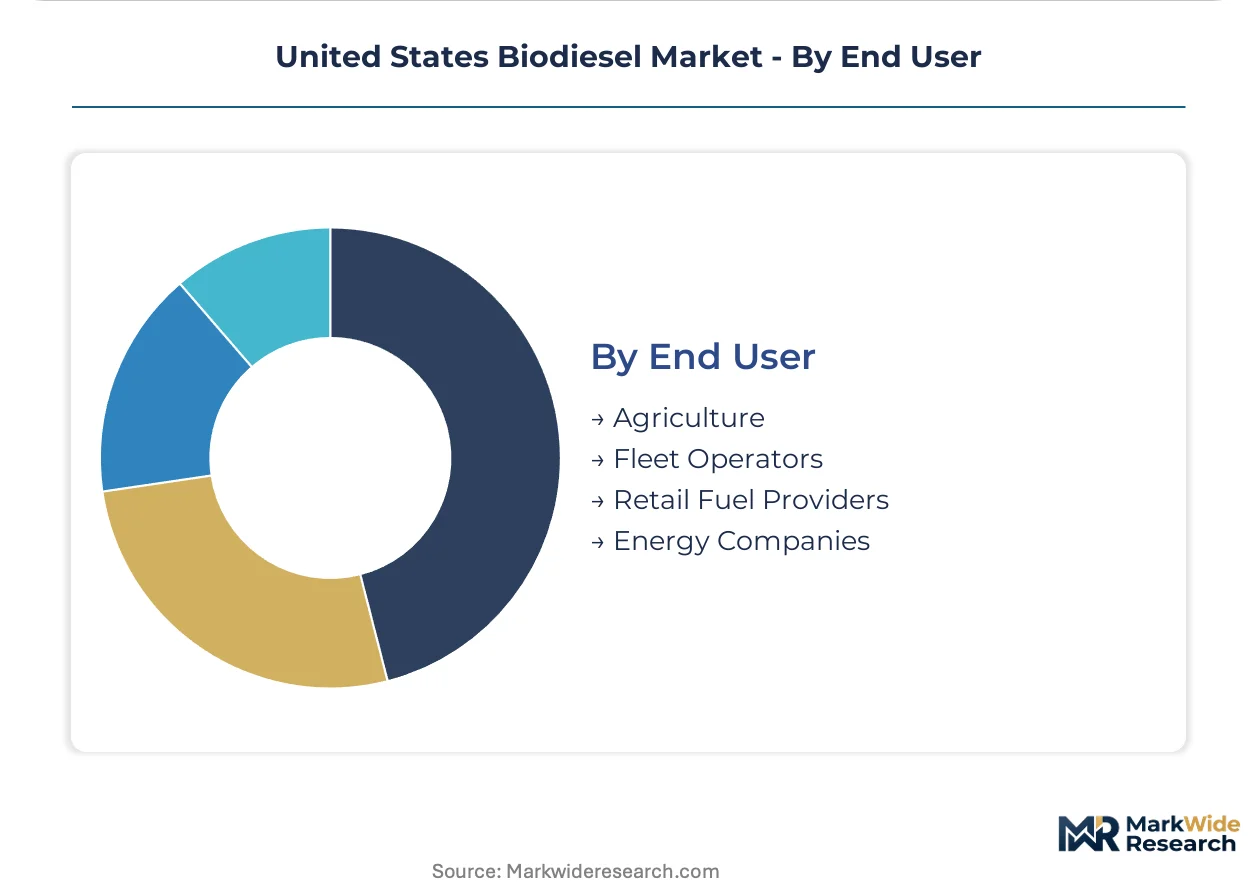
End User:
Customer type concentration creates divergent procurement patterns, from long-term offtake agreements with integrated energy companies to spot purchasing by fragmented retail fuel providers.
- Fleet Operators:Municipal transit authorities, private trucking fleets, and agricultural cooperatives in Illinois and Iowa are consolidating procurement around certified low-carbon-intensity fuel contracts bundling RIN retirement and Scope 3 emissions reporting.
- Energy Companies:Integrated petroleum refiners and renewable fuel marketers control terminal rack access, capturing blender tax credit economics through in-house trading operations.
- Agriculture:Farm cooperatives and grain elevators consume B20 for on-farm equipment, with some vertically integrated into crush-and-process operations.
- Retail Fuel Providers:Independent jobbers and convenience store chains occupy structurally thinner margin positions, constrained by rack pricing transparency and credit pass-through mechanics.
Fleet Operators command the deepest margin pool, while Retail Fuel Providers face persistent compression from upstream integration trends.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Processing capacity clusters along the Upper Midwest soybean belt, where crushing infrastructure and state-level incentives create concentrated supply corridors. Iowa and Illinois dominate national production, while adjacent states compete for feedstock origination and blending terminal access.
Iowa
Fleet procurement mandates from Des Moines municipal transit and agricultural cooperative demand anchor offtake volumes. The state's renewable fuel production tax credit sustains crush-and-process facility economics. Multi-feedstock processors in Mason City and Ames are expanding pretreatment capabilities for used cooking oil diversification.
Illinois
Chicago metropolitan grease trap aggregation networks supply the fastest-growing alternative feedstock channel. The Illinois Renewable Fuel Standard supplements federal RIN obligations with state-level blending requirements. Facilities in Peoria and Decatur leverage integrated soybean oil supply chains from adjacent Archer Daniels Midland crushing complexes.
Indiana
Refinery-adjacent renewable diesel co-processing investments at Whiting and Mount Vernon terminals are reshaping regional product flows. EPA RIN generation audits concentrate compliance activity in Indianapolis regulatory offices. Lafayette and Fort Wayne processors compete for Indiana soybean origination against Illinois buyers.
Minnesota
B20 minimum blend specifications for state fleet procurement create guaranteed demand pools for local producers. The Minnesota Department of Agriculture administers biodiesel quality assurance protocols that exceed federal standards. Mankato and Albert Lea facilities exploit railcar injection blending infrastructure for West Coast LCFS credit arbitrage.
Nebraska
Cattle rendering operations in Grand Island and Omaha supply low-cost animal fat feedstock for acid esterification facilities. The Nebraska Energy Office coordinates biodiesel distribution infrastructure grants for rural retail terminals. Hastings processors face winter cold-flow logistics constraints that limit northern tier market penetration without pour-point additive investments.
United States Biodiesel Market Key Industry Players
Integrated agribusiness conglomerates and petroleum refinery operators split the market between feedstock-origination control and distribution-terminal access. Crush-scale processors leverage backward integration into soybean supply chains, while fuel marketers capture blender tax credit economics through rack trading operations. The competitive terrain rewards multi-feedstock processing flexibility and RIN verification documentation systems. Capacity expansion and strategic partnerships constitute the dominant competitive moves.
Among integrated agribusiness operators, Renewable Energy Group, Archer Daniels Midland Company, and Cargill exemplify the feedstock-control archetype. Renewable Energy Group occupies a position representing multi-feedstock technology specialization. Archer Daniels Midland Company anchors the crush-scale tier with soybean processing integration. Cargill sits within farmer-producer network origination, securing supply through elevator relationships rather than captive crushing alone.
| Leading Market Players |
|---|
| Renewable Energy Group |
| Archer Daniels Midland Company |
| Cargill |
| Valero Energy Corporation |
| Ag Processing Inc |
| Neste Corporation |
| Marathon Petroleum Corporation |
| Flint Hills Resources |
| Bunge Limited |
| Others |
Cost & Logistics Intelligence
Des Moines-Mason City processing clusters concentrate soybean oil conversion capacity, transmitting crush margin volatility directly to blender rack economics across the Upper Midwest. This geographic concentration amplifies pricing power for integrated crush-and-process operators while constraining independent blenders to spot market exposure.
Pricing Analysis
EPA's Renewable Fuel Standard dictates the pricing tier structure through RIN generation premiums that stratify across pathway-certified, standard FAME, and spot market gallons. Price differentiation hinges on carbon intensity scores and LCFS credit eligibility, with California-bound shipments commanding substantial premiums over rack sales. Cost compression in standard FAME tier is intensifying because renewable diesel co-processing erodes equipment-based moats. Fleet operators show least price sensitivity due to mandated procurement specifications, while retail fuel providers face persistent margin compression from credit pass-through mechanics.
Supply Chain Analysis
Extended payment terms from Archer Daniels Midland and Cargill crushing complexes anchor working capital structures for downstream processors. Feedstock sourcing draws from Iowa, Illinois, and Indiana soybean origination territories, with used cooking oil aggregation expanding through Chicago metropolitan networks. Supply chain risk centers on weather-induced logistics interruptions across concentrated Midwest corridors. Distribution runs through railcar injection terminals enabling pipeline-integrated delivery without dedicated tankage at every destination.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fleet operator procurement consolidation around certified low-carbon-intensity fuel contracts has shifted buyer power toward integrated producers capable of documentation transparency. This concentration fragments spot market liquidity for non-integrated blenders.
For Market Incumbents: Build feedstock traceability moats through blockchain-enabled carbon intensity documentation systems that satisfy 45Z credit qualification requirements. Renewable diesel co-processing at petroleum refineries threatens standalone FAME equipment economics, necessitating backward integration into used cooking oil pretreatment capabilities or hydrotreater partnerships. Prioritize RIN verification auditing infrastructure to capture compliance service premiums from smaller producers lacking enterprise systems. For New Entrants and Emerging Players: Establish a beachhead in municipal fleet procurement contracts where sustainability officers specify pathway-certified supply bundling RIN retirement and Scope 3 reporting. Used cooking oil aggregation in secondary metropolitan markets offers penetrable white space against established Chicago-Des Moines networks. Target railcar injection blending partnerships with unit train terminals to bypass dedicated tankage capital requirements. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors multi-feedstock processors with hydrotreater access over standalone transesterification assets facing renewable diesel convergence. Long-term viability hinges on facilities capable of documenting lifecycle carbon intensity through approved pathways for 45Z credit stacking. Watch EPA RIN price volatility as inflection indicator for capacity commitment timing and hedging strategy returns.| Strategic Initiative | Industry Significance |
|---|---|
| Multi-Feedstock Pretreatment Expansion | Used cooking oil diversification captures LCFS premiums and hedges soybean oil volatility. |
| Hydrotreater Co-Processing Partnership | Renewable diesel pathways maximize RIN generation per feedstock gallon against FAME compression. |
| Railcar Injection Terminal Access | Pipeline-integrated distribution enables West Coast LCFS arbitrage without destination tankage. |
| Blockchain Carbon Traceability Implementation | 45Z credit qualification demands documentation transparency that fragmented producers cannot supply. |
| Municipal Fleet Contract Consolidation | Illinois and Iowa transit authorities anchor volume through mandated B20 minimum specifications. |
Research Approach
Operator-level perspectives from biodiesel plant managers, fleet procurement officers, crush facility supply chain directors, and EPA compliance consultants anchored the qualitative base. Primary interview data combined with secondary validation from EIA biofuel production statistics, EPA RIN generation reports, and FERC terminal rack pricing disclosures. Bottom-up facility capacity modeling and top-down RIN obligation demand triangulation established volume reconciliation.
Scenario-bracketing around RIN price volatility bands and feedstock cost spread assumptions structured the analytical framework across the projection horizon. Segmentation dimensions modeled include feedstock type, production technology pathway, end-use application, and state-level regulatory cluster. CAGRs derived from capacity deployment timelines and obligation mandate trajectories. Industry-specific forecast inputs incorporated crush margin forecasts and LCFS credit market dynamics.
Sensitivities concentrate around EPA mandate stringency revisions, soybean oil price spike duration, and renewable diesel capacity absorption rates. Forecasts reflect documented assumptions on RIN generation parity across production pathways. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Biofuels Market
Biofuels
Brazil Biofuel Market
Biofuels
Biodiesel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Biofuel Ethanol Market
Biofuels
Europe Biodiesel Market
Biofuels
Europe Biofuel Market
Biofuels
Second Generation Biofuels Market
Biofuels
Bioethanol Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Next Generation Biofuels Market