
 Rotating Machines for Biofuels Market | 2026-2036
Rotating Machines for Biofuels Market Size, Share, and Industry Trends Forecast 2026-2036
Rotating Machines for Biofuels Market Analytics
Multi-source procurement for precision-engineered rotating components is hardening across the biofuels supply chain. MAN Energy Solutions leverages its turbomachinery heritage to dominate large-scale biogas upgrading installations. Caterpillar Inc. anchors the North American market with generator sets engineered for biodiesel blending flexibility. John Deere sustains agricultural-to-refinery integration through mechanical processing equipment tied to ethanol crop logistics.
Rotating machines for biofuels encompass turbines, generators, compressors, and pumps engineered to withstand corrosive fuel chemistries, high particulate loads, and variable thermal cycles inherent to biodiesel, ethanol, biogas, and algal oil streams. These units convert biomass-derived energy into mechanical or electrical output while maintaining efficiency across fluctuating feedstock quality. Turbines and generators occupy the largest installed base due to their centrality in cogeneration and grid-export configurations at biofuel refineries. Compressors represent the fastest-expanding segment, driven by biogas upgrading and carbon capture integration at anaerobic digestion facilities. Pumps retain mature margin pools in biodiesel transesterification and ethanol distillation, where material specifications for sealing and corrosion resistance command premium pricing.
The EPA enforces Renewable Fuel Standard blending mandates that directly shape rotating machine specifications for ethanol and biodiesel throughput capacity. EMA and REACH compliance in Europe imposes material and emissions standards on turbomachinery deployed in biogas and algal oil processing, while Brazil's national biofuel regulator governs bagasse cogeneration equipment certifications for sugar-ethanol mills. Stakeholders must monitor regulatory calibration of lifecycle carbon intensity thresholds, as these thresholds will determine which feedstock-technology combinations justify capital deployment in rotating infrastructure.
Market Dynamics
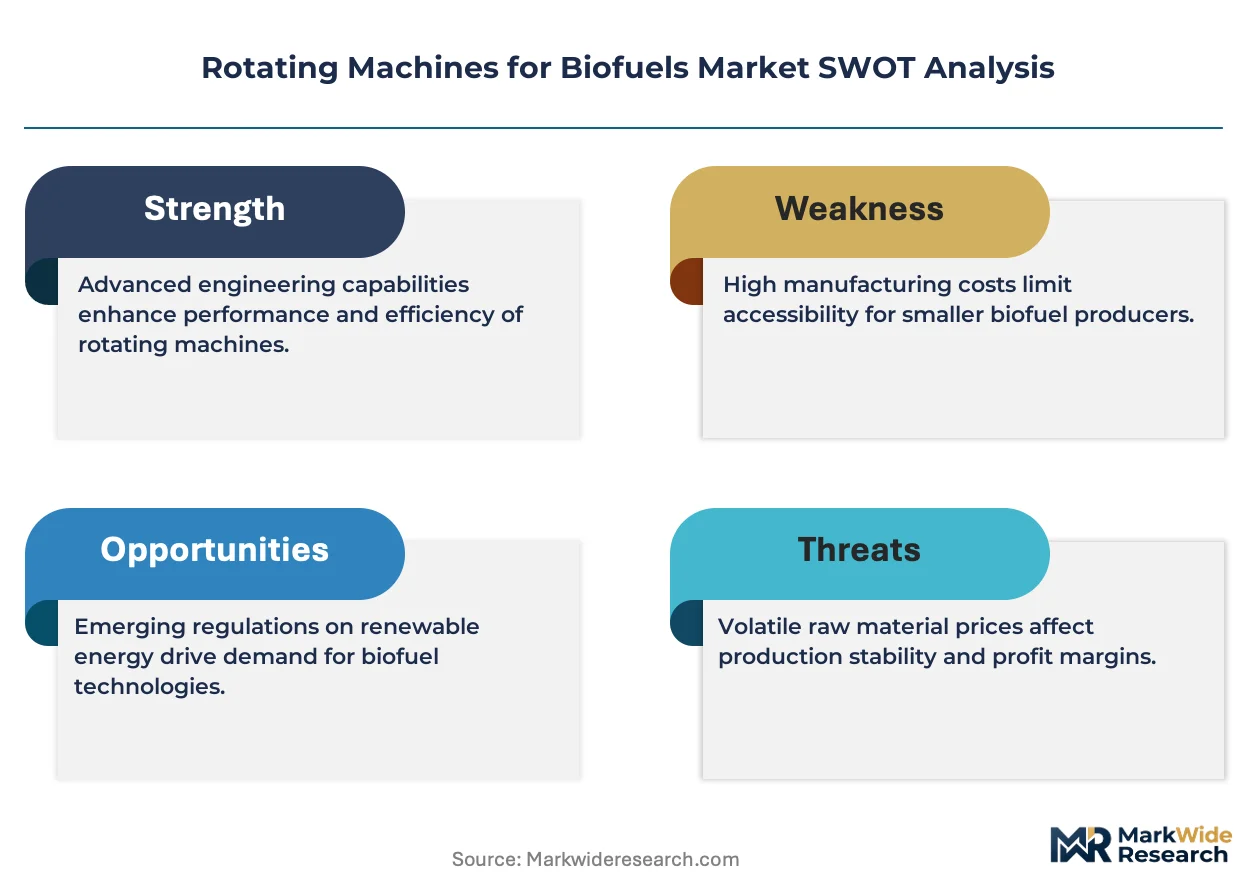
Refinery operators face mounting pressure to process variable feedstock chemistries while the EPA's Renewable Fuel Standard tightens ethanol blend mandates, forcing rotating machine specifications toward higher corrosion resistance and thermal cycling tolerance.
Growth Catalysts
- Bagasse Cogeneration Retrofits:Brazilian sugar-ethanol mills upgrade aging steam turbines to capture surplus electricity from sugarcane residue, driven by national biofuel regulator certification requirements for grid-export eligibility.
- REACH Material Standards:ECHA compliance mandates in Europe accelerate adoption of duplex stainless steel and ceramic coatings in biogas compressor housings to prevent sulfide stress cracking.
- Biogas Upgrading Infrastructure:Anaerobic digestion facilities across Germany and Denmark deploy membrane separation compressors to inject biomethane into natural gas grids, creating sustained demand for oil-free compression technology.
Market Restraints
- Nickel Alloy Cost Volatility:Hastelloy and Inconel price swings for turbine blade castings compress margins on large-scale ethanol plant expansions, particularly in Midwest US corn-belt installations.
- Specialized Foundry Concentration:Precision casting capacity for superalloy turbomachinery components clusters in Germany and Japan, exposing project timelines to single-source bottlenecks.
- Biodiesel Cold-Flow Limitations:Saturated fatty acid methyl esters crystallize below cloud point temperatures, restricting pump and seal material choices in Nordic and Canadian climates.
Strategic Opportunities
- Algal Oil Processing Gap:First-generation algal biorefineries in Spain and Portugal require custom high-shear pumps and centrifugal separators engineered for lipid extraction from saline microalgae cultures.
- Carbon Capture Integration:Post-combustion amine scrubbing at biogas facilities creates demand for corrosion-resistant CO₂ compression trains, with Denmark's energy agency offering capital grants for pilot installations.
- Digital Twin Convergence:Vibration monitoring platforms fused with predictive maintenance algorithms enable ethanol plants to extend generator overhaul intervals, reducing unplanned downtime costs.
Industry Challenges
- Turbomachinery Specialist Shortage:Field service engineers trained in magnetic bearing alignment and dry gas seal commissioning remain scarce relative to deployment timelines for biogas upgrading projects.
- Multi-Standard Certification Burden:Equipment destined for export markets must simultaneously satisfy ASME pressure vessel codes, ATEX explosion protection directives, and INMETRO conformity assessment for Brazilian sugar-ethanol complexes.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Rotating Machines for Biofuels Market |
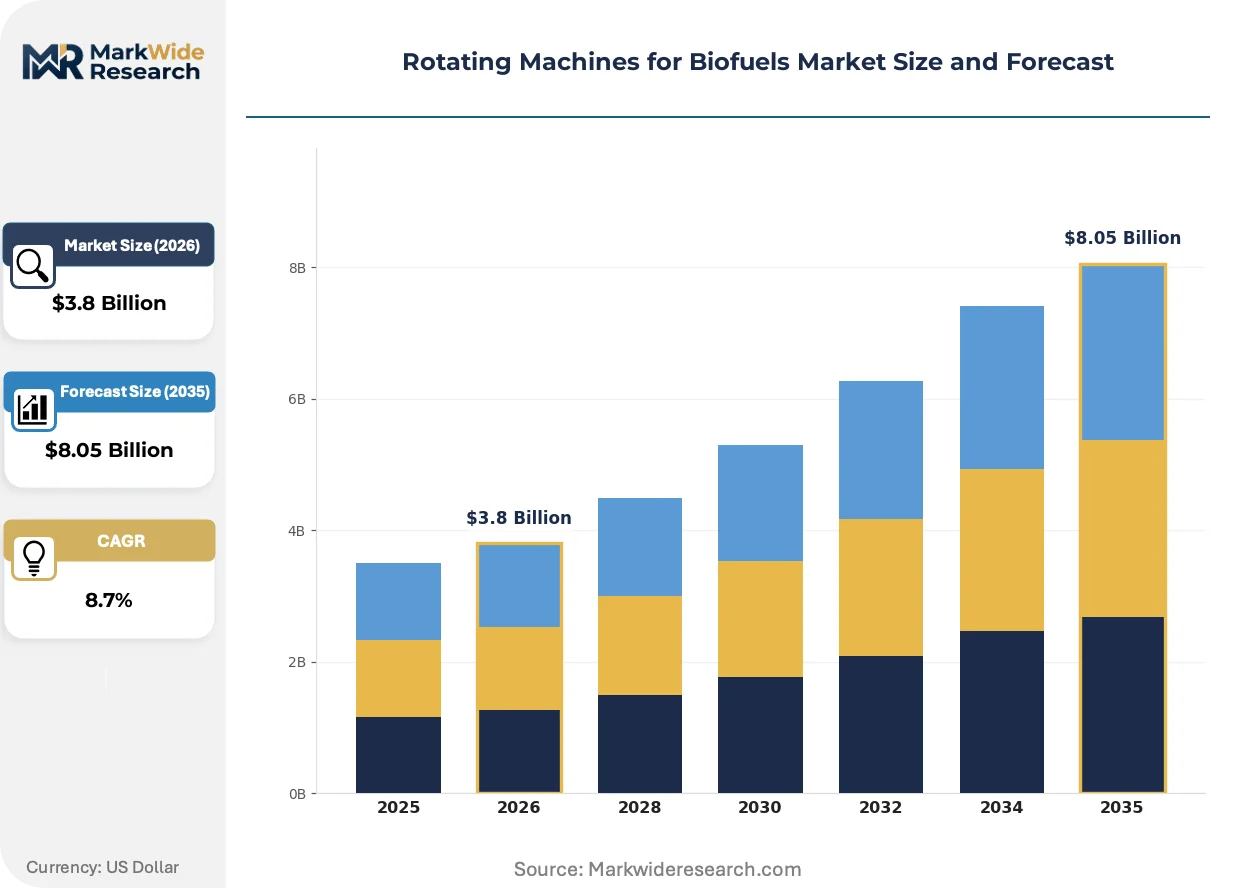
| Market Size in 2026 | $3.8 Billion |
| Market Size in 2035 | $8.05 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Machine Type: Turbines, Generators, Compressors, Pumps Fuel Type: Biodiesel, Ethanol, Biogas, Algal Oil End User: Energy Producers, Biofuel Refineries, Agricultural Operations, Waste Management Technology: Thermal Conversion, Mechanical Processing, Anaerobic Digestion, Hydrothermal Liquefaction |
| Companies Covered | Caterpillar Inc., Komatsu Ltd., John Deere, Kubota Corporation, JCB, CNH Industrial, Volvo Construction Equipment, MAN Energy Solutions, AGCO Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Rotating Machines for Biofuels Market Evolving Landscape
Equipment manufacturers are converging digital instrumentation with advanced metallurgy to extend service intervals in corrosive biofuel environments. Three developments are compressing traditional maintenance cycles and procurement patterns.
Magnetic bearing technology is unifying rotor support and condition monitoring functions in high-speed biogas compressors. Danish and German upgrading facilities deploy these oil-free systems to eliminate contamination risks in biomethane grid injection. The technology is compressing maintenance windows from annual overhauls to five-year inspection cycles, reshaping aftermarket revenue models for OEM service divisions.
The EPA's Renewable Fuel Standard blending mandate escalation is tightening throughput specifications for ethanol plant turbines and generators. Refinery operators must now demonstrate sustained performance across E15-E85 blend flexibility without derating. Midwest US corn-ethanol clusters respond by retrofitting existing steam turbines with variable inlet guide vanes and upgraded blade coatings.
Refinery procurement teams are consolidating vendor relationships around integrated service agreements spanning equipment supply, installation, and predictive maintenance. This bundling displaces fragmented sourcing of separate mechanical, electrical, and automation packages. The shift is most visible in Brazilian sugar-ethanol mills, where mill operators negotiate single-source contracts for bagasse-fired turbine-generator sets with embedded remote monitoring subscriptions.
Rotating Machines for Biofuels Market Segmentation
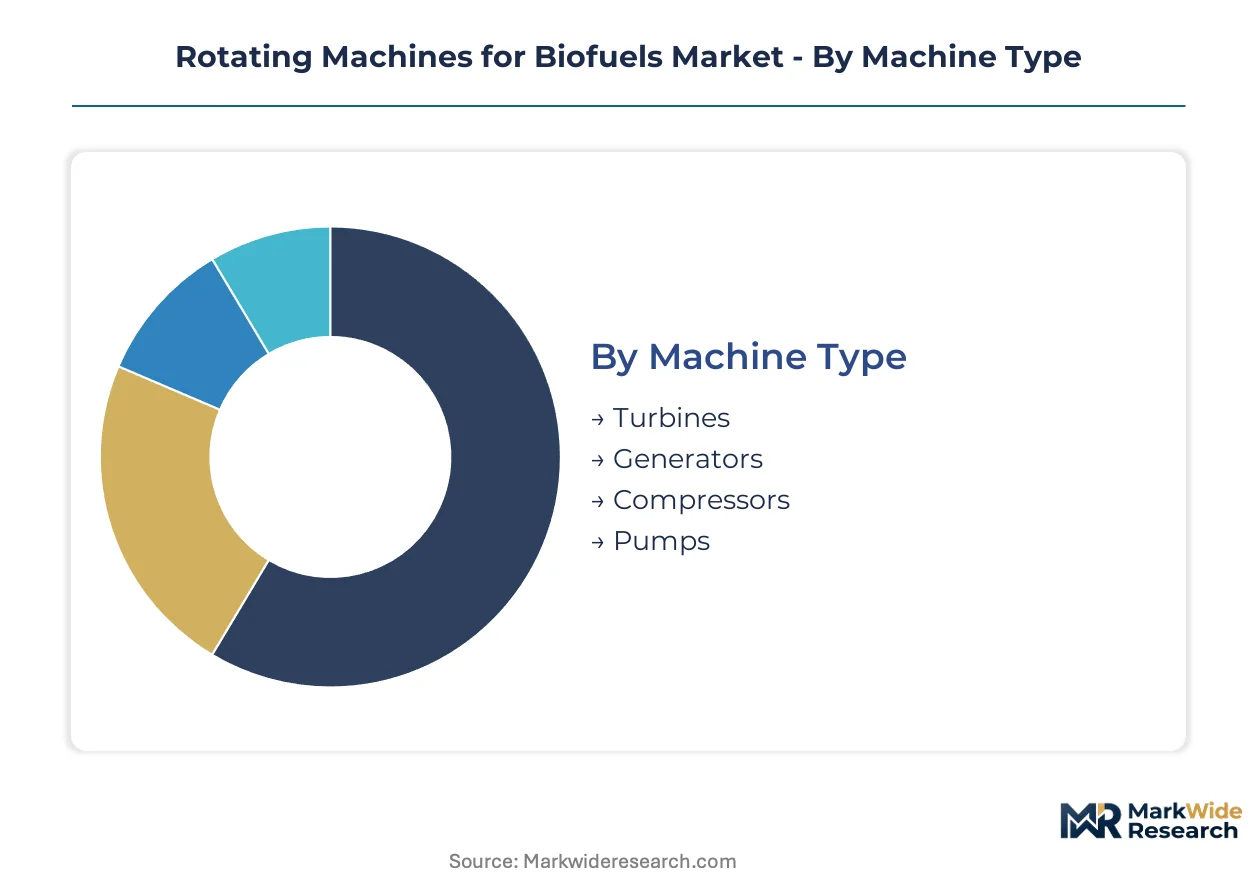
Segmentation in rotating machines for biofuels exposes divergent material specifications and duty cycles across fuel chemistries and processing intensities. Procurement teams calibrate capital allocation against corrosion resistance requirements, thermal cycling frequency, and grid-export eligibility thresholds.
Machine Type:
Rotational speed, bearing configuration, and sealing architecture separate equipment classes for biofuel service environments.
- Turbines:Steam and gas turbine configurations dominate bagasse cogeneration installations at Brazilian sugar-ethanol mills, where blade coatings must withstand high-velocity steam erosion from combustion of fibrous agricultural residue. Retrofit demand concentrates in São Paulo state as mills seek grid-export certification from the national biofuel regulator.
- Generators:Synchronous generators engineered for variable frequency output anchor ethanol plant electrical infrastructure, with permanent magnet designs gaining traction for efficiency in Midwest US corn-belt facilities facing EPA-mandated blend flexibility requirements.
- Compressors:Oil-free screw and centrifugal compressors serve biogas upgrading trains in Denmark and Germany, where membrane separation systems inject biomethane into natural gas distribution networks.
- Pumps:Positive displacement and centrifugal pumps handle biodiesel transesterification and ethanol distillation, with duplex stainless steel construction mandatory for sealing integrity against corrosive fatty acid methyl esters.
Turbines lead on scale; compressors lead on momentum.
Fuel Type:
Feedstock chemistry dictates metallurgical specifications and thermal management protocols across installed equipment bases.
- Biodiesel:Saturated fatty acid methyl esters crystallize below cloud point temperatures, restricting pump and seal material choices in Nordic and Canadian climates where cold-flow properties dominate equipment specification.
- Ethanol:Corn and sugarcane fermentation streams require turbines and generators rated for sustained performance across E15-E85 blend flexibility without derating, with variable inlet guide vanes retrofitting existing Midwest US steam infrastructure.
- Biogas:Anaerobic digestion facilities across Germany deploy membrane separation compressors for biomethane grid injection, with sulfide stress cracking resistance mandated under ECHA REACH material standards.
- Algal Oil:Saline microalgae cultures in Spanish and Portuguese first-generation biorefineries demand custom high-shear pumps and centrifugal separators engineered for lipid extraction from halophilic feedstocks.
Ethanol leads on scale; algal oil leads on momentum.
End User:
Operational scale and regulatory exposure shape procurement sophistication and service contract structures.
- Energy Producers:Utility-scale operators prioritize grid synchronization capability and export metering compliance, with long-term power purchase agreements driving 25-year equipment lifecycle planning.
- Biofuel Refineries:Integrated processing facilities consolidate vendor relationships around single-source contracts spanning turbine-generator supply, installation, and predictive maintenance subscriptions.
- Agricultural Operations:Farm-scale biogas installations favor modular compressor skids with remote monitoring capabilities to offset limited on-site technical staffing.
- Waste Management:Municipal anaerobic digestion projects emphasize corrosion-resistant CO₂ compression trains for post-combustion amine scrubbing, with Denmark's energy agency offering capital grants for pilot carbon capture integration.
Biofuel refineries lead on scale; waste management leads on momentum.
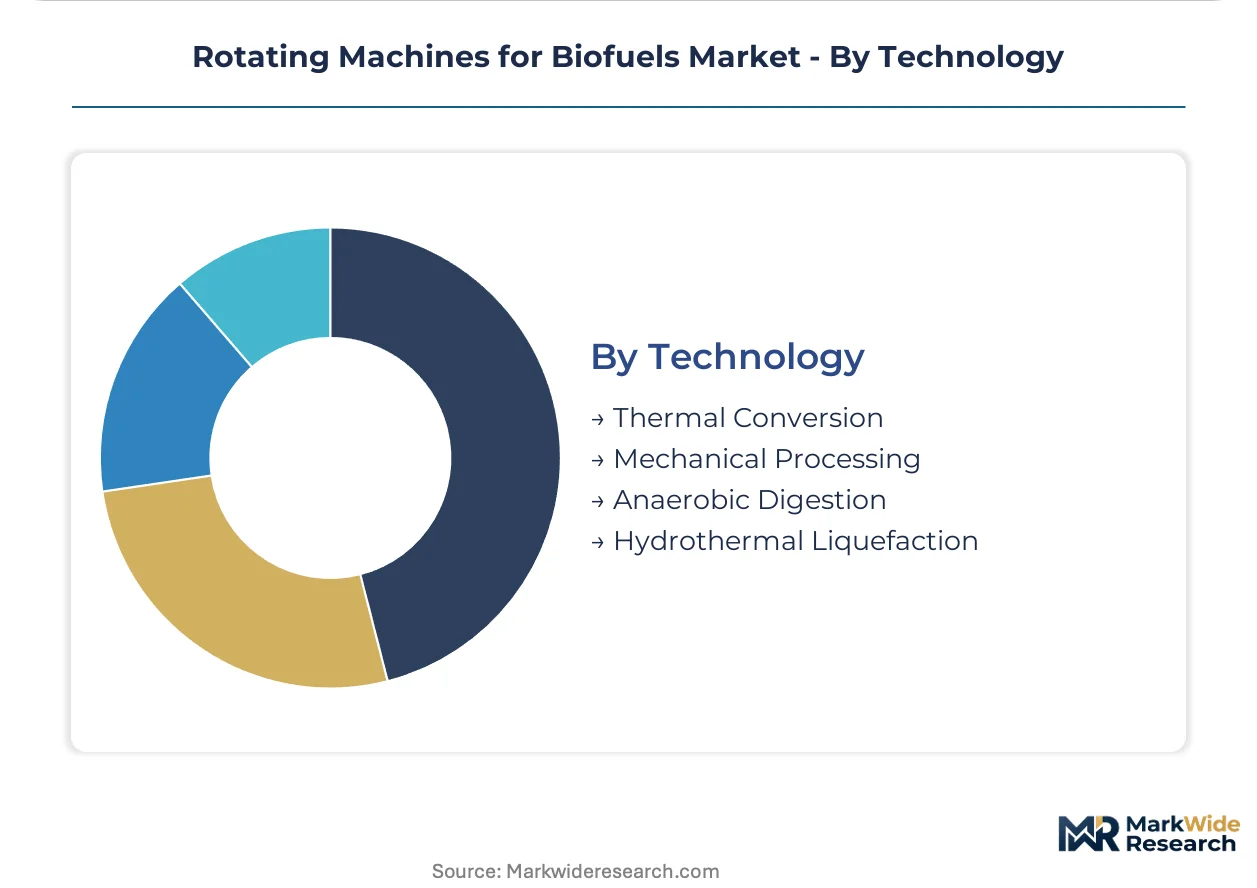
Technology:
Conversion pathway selection determines rotating machine duty cycles and contamination risk profiles.
- Thermal Conversion:Combustion-based systems deploy steam turbines for bagasse and agricultural residue power generation, with superalloy blade castings required for high-temperature steam paths.
- Mechanical Processing:Crushing, pressing, and extraction equipment integrates pumps and compressors for oilseed and sugarcane feedstock preparation, with John Deere sustaining agricultural-to-refinery integration through mechanical processing equipment tied to ethanol crop logistics.
- Anaerobic Digestion:Biogas facilities leverage oil-free compression technology for biomethane upgrading, with magnetic bearing systems eliminating contamination risks in grid injection applications.
- Hydrothermal Liquefaction:High-pressure thermal processing of wet biomass streams requires specialized pumps rated for supercritical water conditions, with limited commercial deployment outside pilot installations.
Thermal conversion leads on scale; hydrothermal liquefaction leads on momentum.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian sugar-ethanol mills anchor installed capacity for bagasse cogeneration turbines, while German biogas clusters and US corn-belt refineries concentrate demand for compressors and generators. Regulatory mandates in each jurisdiction calibrate equipment specifications for corrosion resistance and blend flexibility.
United States
Midwest corn-ethanol plants retrofit steam turbines with variable inlet guide vanes to meet EPA Renewable Fuel Standard blending mandates. The EPA enforces E15-E85 flexibility requirements without derating. Iowa and Illinois ethanol clusters drive generator demand for permanent magnet synchronous designs.
Brazil
São Paulo state sugar-ethanol mills upgrade aging steam turbines for grid-export certification under national biofuel regulator standards. Bagasse cogeneration retrofits capture surplus electricity from sugarcane residue. The national biofuel regulator governs equipment certifications for export eligibility.
Germany
Anaerobic digestion facilities across Lower Saxony and Bavaria deploy membrane separation compressors for biomethane grid injection. ECHA REACH compliance mandates duplex stainless steel and ceramic coatings to prevent sulfide stress cracking. Danish-German border biogas clusters sustain oil-free compression technology demand.
Denmark
Biogas upgrading installations leverage magnetic bearing compressors to eliminate contamination risks in biomethane injection. The Danish energy agency offers capital grants for pilot carbon capture integration with corrosion-resistant CO₂ compression trains. Jutland anaerobic digestion facilities anchor Nordic demand.
Canada
Biodiesel cold-flow limitations in Prairie Provinces restrict pump and seal material choices for saturated fatty acid methyl esters crystallizing below cloud point temperatures. Health Canada and PMRA oversee biofuel processing equipment standards. Alberta and Saskatchewan biodiesel refineries specify low-temperature pump architectures.
Rotating Machines for Biofuels Market Competitive Landscape
Global majors compete with regional champions across turbomachinery heritage and agricultural equipment integration. The market structures around three tiers: diversified industrial conglomerates with energy divisions, specialized turbomachinery OEMs, and agricultural machinery suppliers with refinery-adjacent processing lines. Consolidation pressures concentrate precision casting capacity for superalloy components in Germany and Japan. Competitive moves center on single-source service contract bundling and predictive maintenance platform integration.
Within the diversified industrial tier, Caterpillar Inc. and MAN Energy Solutions exemplify contrasting geographic anchoring and heritage specializations. John Deere occupies a position bridging agricultural operations and refinery mechanical processing. Komatsu Ltd. and Kubota Corporation represent Japanese machinery fabricators with construction and agricultural equipment lineages. Volvo Construction Equipment and JCB anchor European construction-equipment-derived positioning. CNH Industrial and AGCO Corporation exemplify agricultural-equipment-first structures with biofuel-adjacent capabilities.
| Leading Market Players |
|---|
| Caterpillar Inc. |
| Komatsu Ltd. |
| John Deere |
| Kubota Corporation |
| JCB |
| CNH Industrial |
| Volvo Construction Equipment |
| MAN Energy Solutions |
| AGCO Corporation |
| Others |
Value Network & Pricing Analysis
Refinery procurement consolidation around single-source service contracts is compressing vendor margins and forcing OEMs to absorb upstream alloy cost volatility. This buyer-driven bundling concentrates pricing power with integrated turbomachinery suppliers capable of underwriting long-term maintenance commitments.
Pricing Analysis
Input-cost pass-through from nickel alloy volatility governs turbine blade casting quotations, with Hastelloy and Inconel price swings compressing margins on large-scale ethanol plant expansions. Pricing stratifies across premium, standard, and economy tiers based on corrosion resistance certification and after-sales service bundling. Cost compression in the standard tier is intensifying because Brazilian mills negotiate embedded remote monitoring subscriptions. Agricultural operations show highest price sensitivity; utility-scale energy producers accept premium pricing for grid synchronization capability.
Supply Chain Analysis
Direct-to-OEM channels handle hyperscale refinery demand, while regional distributors serve farm-scale biogas installations with modular compressor skids. Precision casting capacity for superalloy turbomachinery components clusters in Germany and Japan, drawing from specialized foundries with limited expansion capability. Raw material dependencies rest on nickel alloy feedstock, duplex stainless steel, and ceramic coating substrates. Single-source vulnerability in superalloy blade casting exposes project timelines to bottlenecks. Distribution runs through integrated service agreements displacing fragmented mechanical, electrical, and automation sourcing.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Margin expansion in rotating machines for biofuels rests on digital service monetization and premium-tier shifts toward corrosion-resistant specifications mandated by ECHA REACH and EPA blending requirements.
For Market Incumbents: Deepen captive supply of superalloy casting capacity through backward integration into German and Japanese foundry partnerships, insulating against single-source bottlenecks that threaten large-scale ethanol project timelines. Lock in long-term service contracts with Brazilian sugar-ethanol mills before magnetic bearing technology commoditizes predictive maintenance offerings. Prioritize certification investment for INMETRO conformity assessment to defend grid-export eligibility positioning.
For New Entrants and Emerging Players: Specialized turbomachinery service firms offer the most penetrable channel for biogas upgrading projects starved of field engineers trained in magnetic bearing alignment. Target anaerobic digestion facilities in Denmark and Germany with oil-free compression technology differentiated by five-year inspection cycles versus annual overhauls. Pursue joint development agreements with algal oil biorefineries in Spain and Portugal for custom high-shear pump applications.
For Investors and Strategic Acquirers: Asymmetric upside sits with precision casting specialists holding superalloy expertise for turbine blade applications, as foundry concentration creates scarcity value for ethanol plant expansion capacity. Long-term viability centers on equipment-as-a-service revenue models displacing transactional hardware sales. Monitor EPA Renewable Fuel Standard calibration announcements as inflection indicators for Midwest corn-belt retrofit demand.
| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Superalloy Casting | German and Japanese foundry partnerships secure blade supply for ethanol turbine retrofits. |
| Integrated Service Agreement Bundling | Brazilian mills consolidate vendor relationships around single-source contracts with embedded monitoring. |
| Magnetic Bearing Technology Deployment | Danish biogas facilities adopt oil-free systems eliminating contamination risks in grid injection. |
| REACH Compliance Certification Investment | ECHA mandates accelerate duplex stainless steel adoption in biogas compressor housings. |
| Predictive Maintenance Platform Integration | Vibration monitoring algorithms extend generator overhaul intervals at Midwest ethanol plants. |
Research Methodology
Coverage spans North America, Europe, and South America, with primary inputs from each region combined with secondary validation. Primary interviews engaged refinery procurement directors, turbomachinery OEM product managers, EPC contractors specializing in biofuel installations, and aftermarket service heads at agricultural equipment distributors. Secondary sources included EPA Renewable Fuel Standard docket filings, ECHA REACH substance registrations, Brazilian national biofuel regulator certification databases, and customs trade data for nickel alloy imports. Bottom-up equipment shipment tracking triangulates against top-down refinery capacity expansion announcements.
Rate-of-change decomposition separates volume growth from price-mix effects across the projection horizon. Segmentation dimensions modeled include machine type, fuel chemistry, end-user operational scale, and conversion pathway technology. CAGRs derive from equipment replacement cycles, regulatory mandate phase-ins, and feedstock availability projections. Industry-specific inputs incorporate EPA blend mandate escalation timelines, ECHA material standard adoption curves, and Brazilian grid-export certification queue data.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to nickel alloy price volatility, foundry capacity expansion decisions, and regulatory calibration of lifecycle carbon intensity thresholds. Outputs reflect documented assumptions around refinery retrofit spending plans and biogas upgrading deployment rates. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Biodiesel Market
Biofuels
Second Generation Biofuels Market
Biofuels
United States Biodiesel Market
Biofuels
Europe Biofuel Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Biofuels Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Europe Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Brazil Biofuel Market
Biofuels
Bioethanol Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Global Bioliquid Heat and Power Generation Market