
 Brazil Biofuel Market | 2026-2036
Brazil Biofuel Market Size, Share, and Industry Trends Forecast 2026-2036
Brazil Biofuel Market Outlook
Product bundling of ethanol with carbon credit certificates is pivoting procurement decisions for large fleet buyers. Raízen S.A. leverages its integrated sugarcane-to-ethanol network to anchor supply security for fuel distributors. BP Bunge Bioenergia S.A. competes through scale advantages across the Center-South producing belt. GranBio specializes in cellulosic ethanol technology, positioning its proprietary enzymatic process as a hedge against first-generation feedstock volatility.
Brazil biofuel denotes liquid or gaseous fuels derived from biomass feedstocks through fermentation, transesterification, or thermochemical conversion, meeting ANP-specified density and purity thresholds for blending with conventional fossil fuels. Its primary purpose is to reduce greenhouse gas emissions in combustion engines while displacing petroleum imports in the domestic energy matrix. Ethanol from sugarcane dominates installed production capacity, though renewable diesel from waste cooking oil represents the fastest-expanding margin pool as hydrotreatment investments mature. Biodiesel from soybean oil sustains steady offtake through mandatory B-15 blending mandates, while biogas from agricultural residues remains underdeveloped relative to its feedstock availability.
ANP blending mandates, RenovaBio carbon intensity targets, and CONAMA air quality standards collectively shape product specifications and market access conditions for biofuel producers. ANVISA and the national petroleum regulator enforce fuel quality protocols that determine which feedstock-technology combinations qualify for tax incentives. Stakeholders must monitor policy adjustments to the RenovaBio decarbonization credit mechanism and the evolution of advanced biofuel certification pathways to align capital allocation with regulatory reward structures.
Market Dynamics
RenovaBio's carbon credit mechanism is restructuring procurement economics for Brazilian fuel distributors, rewarding verified low-carbon intensity scores with tradable decarbonization credits that offset blending compliance costs.
Growth Catalysts
- ANP blending mandates:Mandatory B-15 biodiesel and E-27 ethanol floors lock in baseline offtake regardless of fossil fuel price volatility, insulating producers from demand collapse.
- São Paulo state investment concentration:Second-generation ethanol capacity clusters around Piracicaba and Ribeirão Preto, leveraging existing sugarcane crushing infrastructure and skilled agronomy labor pools.
- Fleet electrification lag:Heavy-duty road freight and agricultural machinery remain diesel-dependent, extending the addressable window for renewable diesel and biodiesel substitution.
Market Restraints
- Sugarcane bagasse supply concentration:Center-South harvest cycles create 180-day feedstock windows, forcing cellulosic ethanol plants to idle or store biomass at cost.
- Soybean oil price linkage:Biodiesel margins compress when Chicago Board of Trade soy oil futures spike, as feedstock represents 75-80% of production cost structure.
- ANP certification latency:Novel feedstock-technology combinations face 18-24 month approval timelines, freezing capital deployment until pathway eligibility is confirmed.
Strategic Opportunities
- Biogas from agricultural residues:São Paulo and Minas Gerais livestock operations generate methane-rich manure streams currently vented, representing uncaptured energy value.
- RenovaBio credit arbitrage:Producers achieving carbon intensity scores below the sectoral baseline can bank excess CBIOs for sale to importers or obligated distributors.
- Hydrotreated vegetable oil export:Renewable diesel meeting EU RED III sustainability criteria accesses premium Northwest European bunkering markets.
Industry Challenges
- Enzyme engineering talent scarcity:Cellulosic ethanol operations require PhD-level biochemists familiar with C5/C6 sugar co-fermentation, a specialization concentrated at UNICAMP and USP.
- CONAMA air quality retrofit compliance:Existing distilleries must install scrubbers and anaerobic digesters to meet 2025 particulate and effluent standards, requiring capex without incremental revenue.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Brazil Biofuel Market |
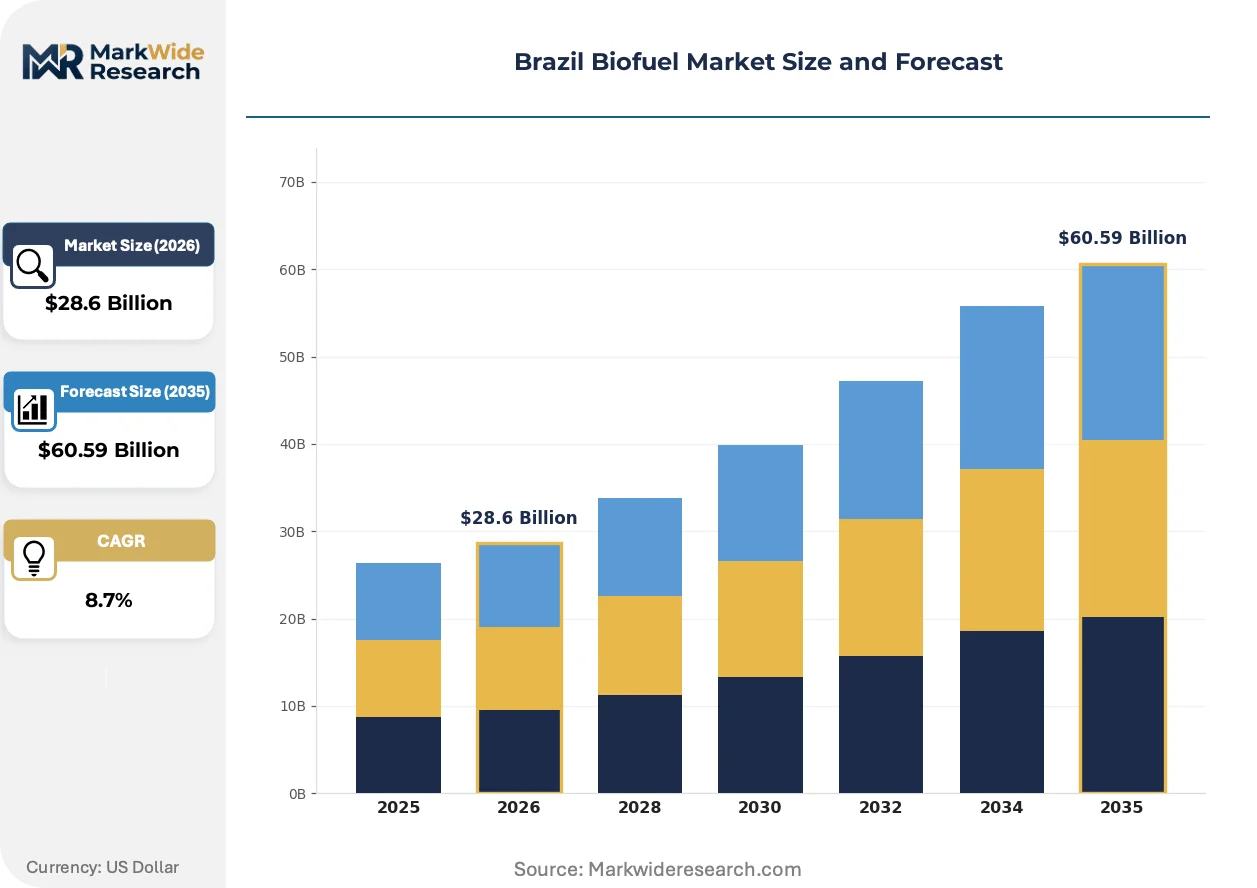
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $60.59 Billion |
| CAGR (2026 – 2036) | 8.7% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Ethanol, Biodiesel, Renewable Diesel, Biogas Feedstock: Sugarcane, Soybean, Corn, Waste Cooking Oil Distribution Channel: Retail, Wholesale, Direct Supply, Online End User: Transportation, Industrial, Residential, Agricultural |
| Companies Covered | Atvos Agroindustrial, GranBio, Raízen S.A., BP Bioenergy, ECB Group, BP Bunge Bioenergia S.A., Copersucar S.A., Zeon, Petrobras Biocombustíveis S.A., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Brazil Biofuel Market Strategic Shifts
Digital carbon accounting platforms are penetrating Brazilian biofuel certification, replacing spreadsheet-based lifecycle analysis with blockchain-verified traceability that accelerates RenovaBio credit issuance.
Cellulosic ethanol technology is converging with sugarcane biorefinery retrofit economics. Raízen and GranBio deploy proprietary enzyme cocktails to unlock C5 sugars from bagasse hemicellulose, raising ethanol yield per hectare by 40% without expanding cultivation footprint. Major fuel distributors now require second-generation content in procurement tenders, compressing first-generation-only suppliers into commodity pricing tiers.
ANP Resolution 19/2023 established a certification pathway for renewable diesel produced via coprocessing and standalone hydrotreatment, enabling soybean oil and waste fats to access diesel blending pools beyond the B-15 cap. Refiners in Paraná and Rio Grande do Sul are reconfiguring hydrotreaters originally built for crude oil desulfurization. This regulatory opening positions renewable diesel as the fastest-expanding biofuel category through 2030.
Fleet operators are consolidating procurement under long-term offtake agreements with fixed carbon intensity premiums. Large road transport and agribusiness buyers bypass wholesale fuel distributors, contracting directly with ethanol mills for tanker-lot deliveries with embedded RenovaBio credit transfer. This disintermediation concentrates in Mato Grosso grain corridors and São Paulo sugarcane belts, where logistics density supports direct supply relationships.
Brazil Biofuel Market Segmentation
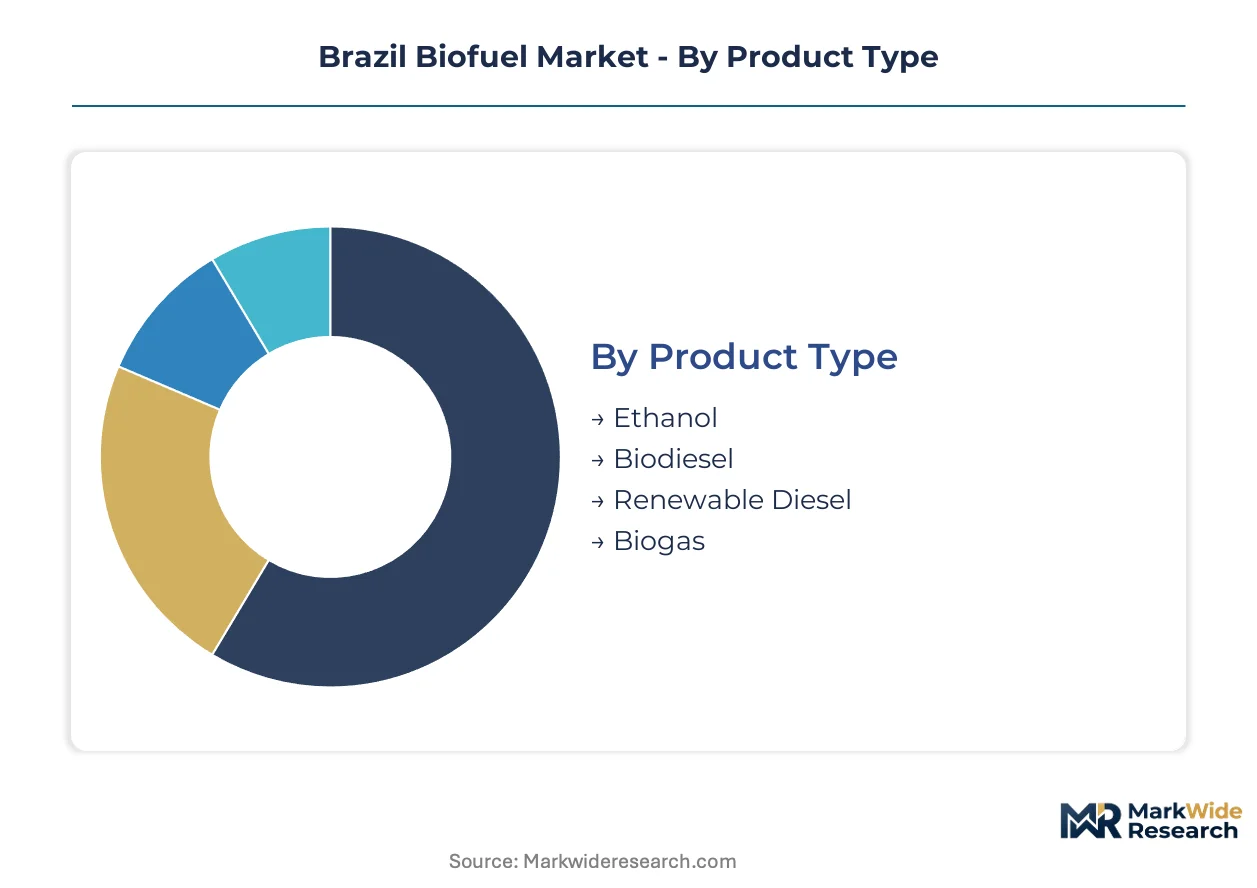
Brazil's biofuel segmentation reflects the interplay between ANP blending mandates and feedstock geography. Each category channels capital toward distinct margin pools, from sugarcane ethanol's scale economies to biogas's underdeveloped residue streams.
Product Type:
Buyers differentiate by carbon intensity scores under RenovaBio, with lower-carbon products commanding credit-linked premiums.
- Ethanol:Hydrous and anhydrous grades refined from sugarcane juice or molasses meet ANP density specifications for E-27 gasoline blending. São Paulo state's Center-South belt concentrates installed capacity, though harvest seasonality forces storage cost absorption during inter-crop periods.
- Biodiesel:Fatty acid methyl ester produced via transesterification of vegetable oils, primarily soybean, satisfies mandatory B-15 diesel blending. Mato Grosso crushers anchor supply chains, with margins compressing when Chicago Board of Trade soy oil futures spike.
- Renewable Diesel:Hydrotreated vegetable oil and waste fats processed through standalone or coprocessing routes access diesel pools beyond biodiesel blend caps. Paraná refiners retrofit hydrotreaters to capture this regulatory opening.
- Biogas:Methane-rich biogas from anaerobic digestion of agricultural residues remains underdeveloped relative to feedstock availability in São Paulo and Minas Gerais livestock corridors.
Volume sits with ethanol; growth tilts toward renewable diesel.
Feedstock:
Feedstock choice locks producers into distinct cost structures and carbon intensity profiles that determine RenovaBio credit eligibility.
- Sugarcane:First-generation juice fermentation dominates, while bagasse cellulosic routes unlock C5/C6 sugars for yield expansion. Piracicaba and Ribeirão Preto clusters concentrate second-generation investment.
- Soybean:Oil crushing margins in Mato Grosso and Rio Grande do Sul determine biodiesel economics, with price linkage to international futures creating margin volatility.
- Corn:Emerging ethanol pathway in Mato Grosso do Sul leverages grain surplus, though ANP certification timelines delay commercial scale-up.
- Waste Cooking Oil:Collection networks in São Paulo and Rio de Janeiro metropolitan areas supply hydrotreatment units with lower-carbon intensity feedstock than virgin oils.
Scale concentrates in sugarcane; steepest expansion trajectory belongs to waste cooking oil.
Distribution Channel:
Channel selection reflects buyer scale and credit transfer complexity, with large fleet operators bypassing intermediaries.
- Retail:Service stations and fuel resellers handle consumer-facing ethanol and biodiesel sales under ANP price monitoring.
- Wholesale:Fuel distributors aggregate tanker-lot volumes for regional delivery, embedding RenovaBio credit transfers in standard contracts.
- Direct Supply:Grain corridor fleet operators and agribusiness buyers contract directly with mills for ethanol offtake with fixed carbon intensity premiums.
- Online:Digital platforms for carbon credit trading and biofuel procurement remain nascent, constrained by ANP documentation requirements.
Wholesale handles baseline volume; direct supply is gaining share fastest.
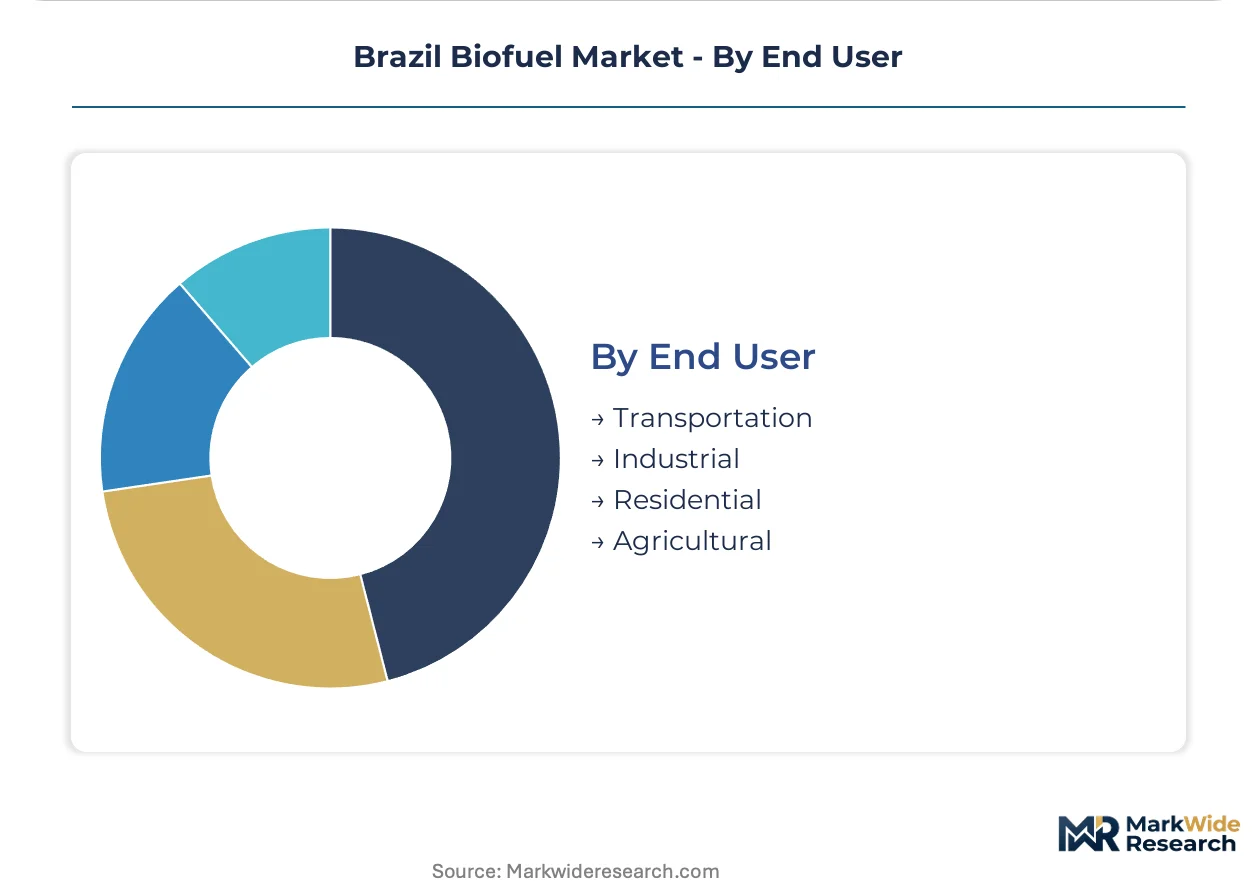
End User:
End-use segmentation tracks diesel dependence versus electrification vulnerability, with heavy-duty applications extending biofuel relevance.
- Transportation:Road freight fleets in Mato Grosso grain corridors and São Paulo distribution networks drive ethanol and renewable diesel offtake under fleet decarbonization targets.
- Industrial:Manufacturing boilers and process heat applications in Minas Gerais mining and metals sectors absorb fuel oil substitutes.
- Residential:Limited penetration outside bottled LPG substitution trials in rural Northeast communities.
- Agricultural:Tractor and harvester fleets remain diesel-dependent, with biodiesel and renewable diesel capturing machinery fuel demand.
Transportation anchors current demand; agricultural machinery extends the addressable window longest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
São Paulo's Center-South sugarcane belt anchors national production through tax-advantaged special economic zones and crushing infrastructure density. State-level RenovaBio implementation varies across producing regions, creating divergent investment climates for mill operators and fuel distributors.
São Paulo
Piracicaba and Ribeirão Preto clusters concentrate second-generation ethanol investment leveraging existing bagasse streams. ANP blending mandates lock in baseline offtake for Center-South mills regardless of fossil fuel price swings. Raízen S.A. and GranBio deploy proprietary enzyme platforms across São Paulo's sugarcane biorefinery network.
Minas Gerais
Livestock corridors generate methane-rich manure streams currently vented rather than captured for biogas production. State environmental regulators enforce CONAMA air quality standards that shape distillery scrubber investments. Triângulo Mineiro grain terminals anchor biodiesel distribution for agricultural machinery fleets.
Mato Grosso
Soybean crushing margins determine biodiesel economics for diesel-dependent grain haulage fleets. RenovaBio carbon credit transfers concentrate in Sorriso and Lucas do Rio Verde logistics hubs. Direct supply contracts between mills and fleet operators bypass wholesale fuel distributors.
Paraná
Refiners retrofit hydrotreaters originally built for crude oil desulfurization to capture renewable diesel regulatory openings. ANP Resolution 19/2023 enables standalone and coprocessing pathways for soybean oil and waste fats. Curitiba metropolitan area collection networks supply lower-carbon intensity feedstock than virgin oils.
Rio Grande do Sul
Soybean oil price linkage to Chicago Board of Trade futures creates margin volatility for biodiesel producers. State-level agronomy research centers support feedstock diversification trials beyond dominant oilseed crops. Pelotas and Porto Alegre industrial zones host hydrotreatment capacity expansion.
Brazil Biofuel Market Competitive Environment
Diversified conglomerates compete with focused pure-play specialists across distinct margin pools in Brazilian biofuel production. The vendor base stratifies into three tiers: integrated agribusiness-to-energy conglomerates, standalone ethanol mill operators, and technology licensors specializing in cellulosic conversion. Strategic moves concentrate on backward integration into captive feedstock supply and portfolio diversification across first- and second-generation pathways.
Within the integrated conglomerate tier, Raízen S.A. and BP Bunge Bioenergia S.A. occupy positions anchored by scale advantages across the Center-South producing belt. GranBio exemplifies the technology-specialist archetype, positioning proprietary enzymatic processes as hedges against first-generation feedstock volatility. These three S.A.-structured entities represent divergent competitive approaches: crushing network control, refinery retrofit integration, and biochemical platform licensing.
| Leading Market Players |
|---|
| Atvos Agroindustrial |
| GranBio |
| Raízen S.A. |
| BP Bioenergy |
| ECB Group |
| BP Bunge Bioenergia S.A. |
| Copersucar S.A. |
| Zeon |
| Petrobras Biocombustíveis S.A. |
| Others |
Value Chain & Pricing Dynamics
Chicago Board of Trade soy oil futures cascade through Brazilian biodiesel economics, compressing margins when feedstock spikes and forcing producers toward alternative feedstocks or long-term offtake contracts that lock in carbon credit premiums.
Pricing Analysis
Margin tightening in biodiesel reflects soybean oil price linkage to international futures, with feedstock representing 75-80% of production cost structure. Contract-based long-term offtake agreements with fixed carbon intensity premiums dominate procurement for large fleet operators, while spot market transactions serve smaller distributors. Price differentiation hinges on RenovaBio carbon intensity scores and volume scale, with sub-baseline CI producers banking excess CBIOs for arbitrage. Agricultural machinery buyers show highest price sensitivity due to diesel substitution economics, while São Paulo-based fuel distributors with credit transfer capabilities absorb premiums.
Supply Chain Analysis
Sugarcane bagasse supply rests on Center-South harvest cycles that create 180-day feedstock windows, forcing cellulosic ethanol plants to idle or store biomass at cost. Raw material dependencies include sugarcane juice and molasses for first-generation ethanol, soybean oil for biodiesel transesterification, and waste cooking oil for hydrotreatment units. Single-source vulnerability concentrates in Mato Grosso soybean crushing corridors, where Chicago futures volatility transmits directly to domestic margins. Distribution runs through wholesale fuel distributors aggregating tanker-lot volumes, though direct supply contracts between mills and fleet operators are gaining share fastest in grain corridor logistics hubs.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Enzyme engineering talent scarcity in cellulosic ethanol operations props pricing for producers with captive PhD-level biochemist teams, creating defendable moats as ANP certification timelines delay competitor entry.
For Market Incumbents: Anchor supply security through backward integration into captive sugarcane crushing networks and bagasse storage infrastructure that buffers 180-day harvest windows. Defend against renewable diesel entrants by accelerating second-generation ethanol yield expansion through proprietary enzyme platforms, while securing long-term offtake agreements with Mato Grosso grain haulage fleets that bypass wholesale distributor intermediation. For New Entrants and Emerging Players: ANP Resolution 19/2023 in Brazil opens a window for renewable diesel producers via standalone and coprocessing hydrotreatment pathways. Target Paraná refinery retrofits and Curitiba waste cooking oil collection networks as the most penetrable white-space, leveraging lower-carbon intensity feedstock than virgin oils to capture premium Northwest European bunkering markets through EU RED III sustainability criteria alignment. For Investors and Strategic Acquirers: Distressed-cycle entries favor cellulosic ethanol technology licensors with proprietary enzymatic processes in São Paulo state. Long-term viability hinges on RenovaBio credit arbitrage capacity and ANP certification pipeline velocity. Watch ANP approval timelines for novel feedstock-technology combinations as the inflection indicator for capital deployment acceleration.| Strategic Initiative | Industry Significance |
|---|---|
| Second-Generation Ethanol Capacity Buildout | Raízen and GranBio deploy proprietary enzyme platforms to unlock C5 sugars from bagasse hemicellulose, raising yield per hectare. |
| Renewable Diesel Hydrotreater Retrofit | Paraná refiners reconfigure units originally built for crude oil desulfurization to capture ANP Resolution 19/2023 regulatory opening. |
| Long-Term Offtake Agreement Structuring | Fleet operators in Mato Grosso grain corridors contract directly with mills for tanker-lot deliveries with embedded RenovaBio credit transfer. |
| Backward Integration into Bagasse Storage | Cellulosic ethanol producers invest in biomass storage infrastructure to buffer 180-day Center-South harvest cycle idling costs. |
| Digital Carbon Accounting Platform Deployment | Blockchain-verified traceability replaces spreadsheet-based lifecycle analysis to accelerate RenovaBio credit issuance timelines. |
Study Parameters
Multi-period observation of ANP blending mandate compliance rates, RenovaBio carbon credit issuance volumes, and Center-South sugarcane crush statistics anchored the trend analysis, supplemented by interviews with ethanol mill operations directors, fuel distributor procurement leads, fleet operator sustainability officers, and ANP regulatory affairs specialists. Secondary validation drew from ANP resolution filings, CONAMA air quality standard updates, customs and trade data on soybean oil imports, and SEC 10-K disclosures from listed agribusiness conglomerates. Bottom-up capacity installation tracking triangulated against top-down fuel consumption forecasts from national energy matrix projections.
The input-output matrix framed ethanol, biodiesel, renewable diesel, and biogas production against feedstock availability, regulatory mandate floors, and carbon intensity scoring mechanisms across the modeling period. Segmentation dimensions included product type, feedstock source, distribution channel, and end-use application, with regional production hub clustering as an additional industry-specific layer. CAGRs were derived from installed capacity expansion curves, mandate trajectory enforcement, and fleet electrification lag assumptions. Forecast inputs incorporated sugarcane yield variability, soybean oil futures volatility, and hydrotreatment unit commissioning timelines.
The model assumes a particular technology adoption path for cellulosic ethanol commercialization; alternative pathways for enzymatic C5/C6 sugar co-fermentation would alter the outlook if ANP certification timelines compress or enzyme engineering talent scarcity eases. Forecasts reflect assumptions around RenovaBio credit market liquidity, ANP mandate enforcement consistency, and EU RED III sustainability criteria stability. A small set of triggers—ANP resolution amendments, CONAMA standard acceleration, and Chicago Board of Trade soy oil sustained spikes—warrants ongoing watch.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Europe Advanced Biofuel Market
Biofuels
United States Biodiesel Market
Biofuels
Europe Biofuel Market
Biofuels
Latin America Biodiesel Market
Biofuels
Bioethanol Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Next Generation Biofuels Market
Biofuels
Second Generation Biofuels Market
Biofuels
Europe Biodiesel Market
Biofuels
Biofuels Market
Biofuels
Biodiesel Market