
 United States Backup Power Systems Market | 2026-2036
United States Backup Power Systems Market Size, Share, and Industry Trends Forecast 2026-2036
United States Backup Power Systems Market Analytics
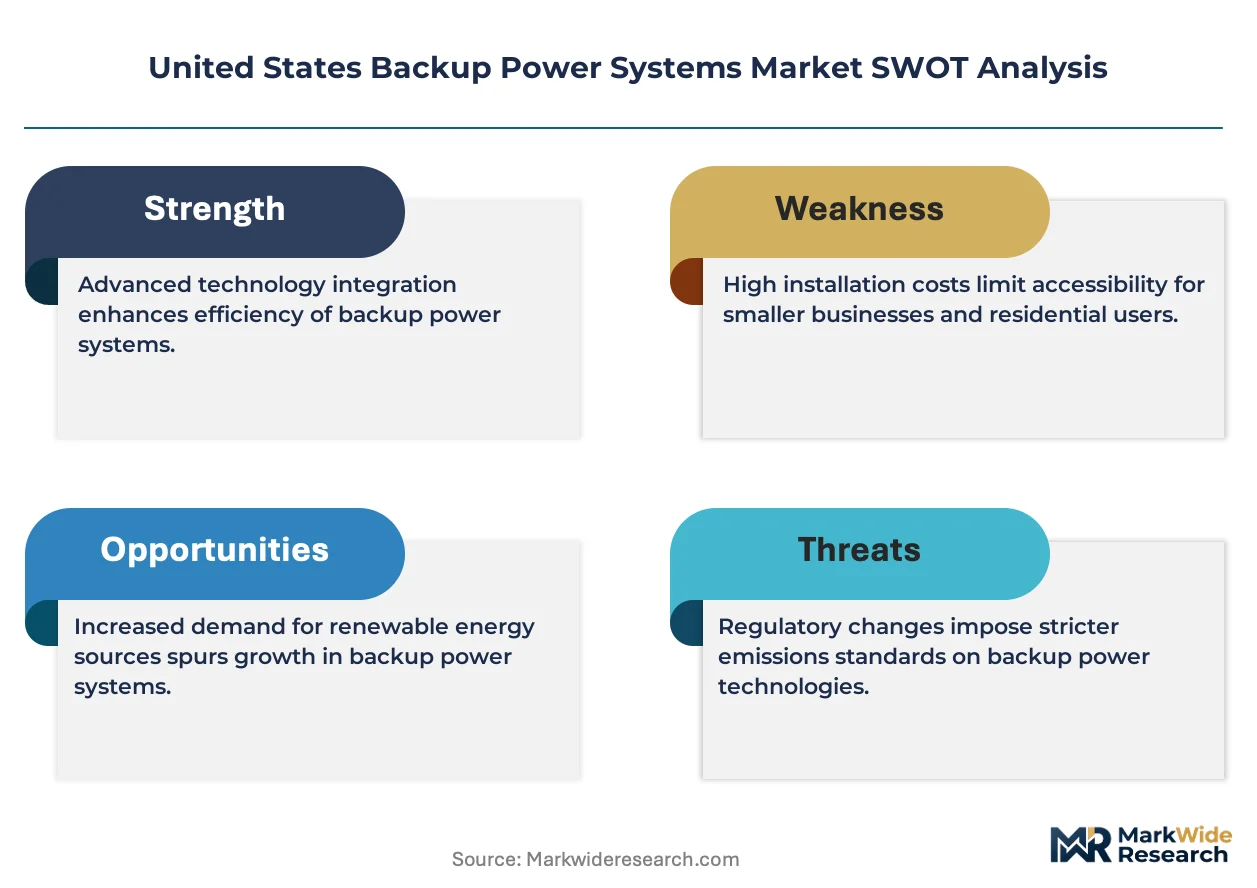
The Inflation Reduction Act is restructuring investment tax credit eligibility for battery-backed systems, raising capital requirements for market entry while favoring lithium-ion configurations. Cummins Inc. leverages its diesel generator heritage to defend industrial accounts. Generac Holdings Inc. anchors residential standby sales through installer channel control. Tesla differentiates via integrated solar-battery software stacks that reduce homeowner switching costs.
Backup power systems encompass electromechanical and chemical storage devices engineered to deliver instantaneous or near-instantaneous electrical output during grid interruption, with UPS systems targeting sub-20 millisecond transfer times for sensitive loads. Their primary purpose is eliminating downtime costs across facilities where power continuity carries safety or economic consequences. Diesel generators retain dominant installed base share in industrial settings, though lithium-ion battery systems capture fastest growth in commercial and healthcare segments where silent operation and emissions compliance carry premium value. Service-type revenue pools concentrate in maintenance contracts for natural gas standby units, where multi-year agreements lock in recurring margins.
EPA stationary engine emissions standards, OSHA workplace power safety mandates, and NFPA 110 emergency power supply system codes collectively shape product design, installation protocols, and inspection schedules across US jurisdictions. NHTSA rules on electric vehicle bidirectional charging introduce an emerging compliance dimension for residential backup integration. Stakeholders must monitor how state-level interconnection standards evolve as distributed battery assets proliferate behind the meter.
Market Dynamics
The Inflation Reduction Act is restructuring capital deployment across backup power systems, elevating lithium-ion battery configurations above diesel alternatives through tax credit eligibility tiers that disadvantage traditional generator architectures.
Growth Catalysts
- Grid reliability deterioration:Texas, Florida, and California utilities report escalating outage frequency, compelling healthcare facilities and data centers to accelerate procurement timelines for redundant power infrastructure.
- EPA Tier 4 Final emissions standards:Stationary engine certification requirements are tightening, creating replacement demand for pre-compliant diesel generator fleets in industrial and commercial installations.
- Silent operation premiums:Healthcare campuses and residential subdivisions are specifying battery-based systems to eliminate noise pollution constraints that previously limited generator placement options.
Market Restraints
- Lithium carbonate price volatility:Battery cell cost instability compresses margins for integrators and extends project quotation validity windows, freezing capital commitment decisions.
- Skilled technician scarcity:NFPA 110-certified installation and maintenance labor pools concentrate in Gulf Coast and Midwest industrial corridors, constraining deployment velocity in Mountain and Pacific Northwest states.
- Natural gas pipeline dependency:Standby generator fuel security requires proximity to utility gas distribution networks, excluding remote commercial sites and rural residential developments from specified solutions.
Strategic Opportunities
- Vehicle-to-home bidirectional charging:NHTSA rulemaking on EV export power standards is creating a residential backup channel that bypasses traditional generator and battery installer networks entirely.
- Microgrid-as-a-service contracting:Commercial real estate operators in storm-exposed Florida and Texas submarkets are adopting operational expenditure models that shift capital burden to third-party owners.
- Healthcare resilience mandates:Joint Commission accreditation standards are hardening emergency power supply system requirements for critical access hospitals, expanding addressable market for integrated battery-fuel cell architectures.
Industry Challenges
- Interconnection queue delays:Behind-the-meter battery deployments face 6-18 month utility approval timelines in California and Northeast ISO-NE territories, freezing project revenue recognition.
- Legacy generator fleet stranded asset risk:Industrial facilities with recently commissioned diesel units face accelerated obsolescence as state-level clean energy mandates tighten operational hour allowances.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Backup Power Systems Market |
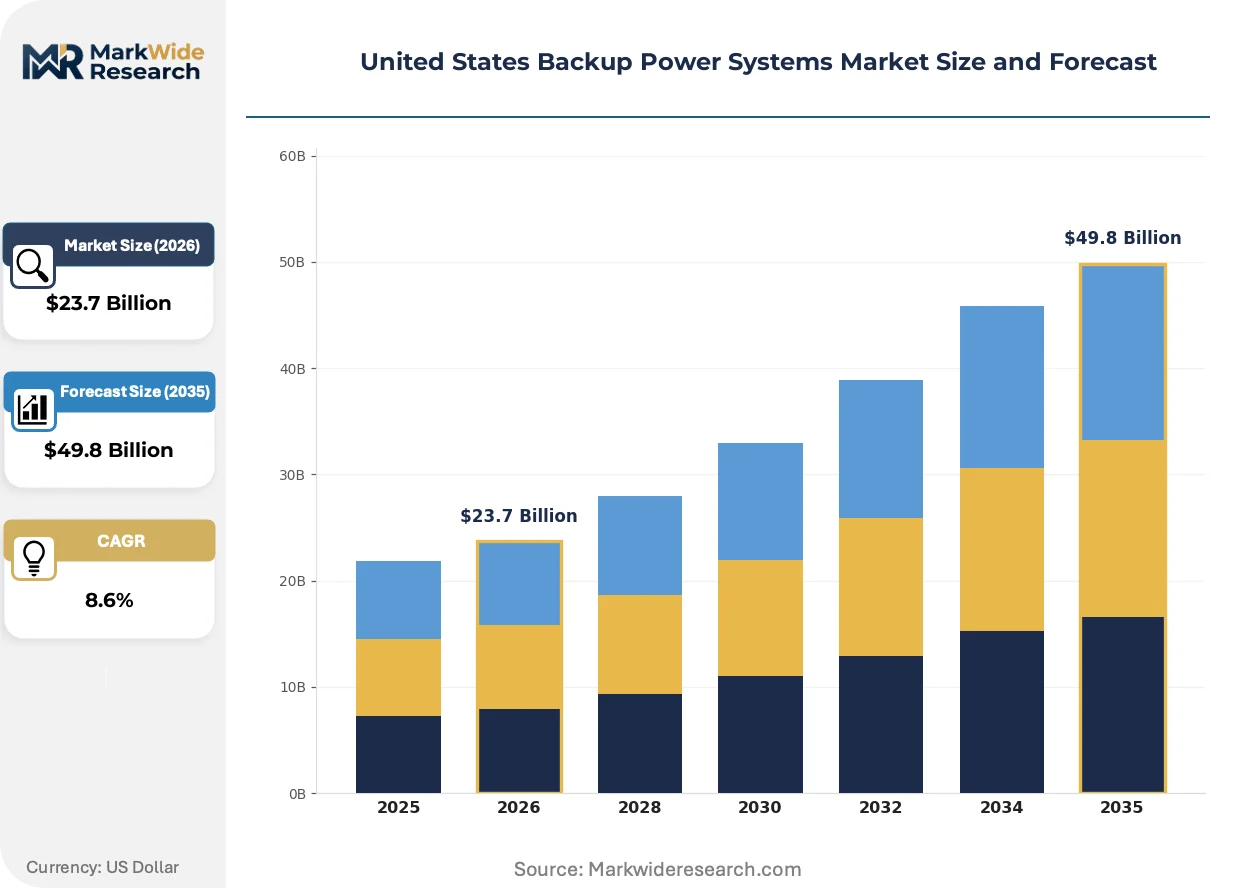
| Market Size in 2026 | $23.7 Billion |
| Market Size in 2035 | $49.8 Billion |
| CAGR (2026 – 2036) | 8.6% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Generators, UPS, Inverters, Fuel Cells End User: Residential, Commercial, Industrial, Healthcare Technology: Solar, Diesel, Natural Gas, Lithium-ion Service Type: Installation, Maintenance, Repair, Consulting |
| Companies Covered | Cummins Inc., Schneider Electric, Generac Holdings Inc., Tesla, Emerson Electric Co., Eaton Corporation plc, Kohler Co., ABB Limited, Caterpillar Inc., Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Backup Power Systems Market Evolving Landscape
Software-defined energy management is displacing hardware-centric system design across residential and commercial backup power, collapsing installation complexity while enabling remote orchestration of distributed assets.
Lithium iron phosphate battery architecture is modularizing commercial and industrial storage deployments, allowing healthcare facilities and data centers to scale capacity in 50-100 kWh increments without redundant power conversion equipment. Hospital engineering departments in Texas and Florida are adopting this approach to match generator replacement cycles to capital budget phasing. The technology is modularizing procurement patterns, fragmenting what were historically single large capital events into recurring technology refresh decisions.
EPA stationary engine emissions enforcement is intensifying product certification documentation requirements, compelling manufacturers to re-engineer exhaust aftertreatment systems and onboard diagnostics. Industrial generator OEMs are absorbing compliance engineering costs that compress mid-range product margins while creating competitive separation for entities with established certification infrastructure. The diesel generator segment is responding by consolidating supplier relationships to reduce testing burden duplication.
Installer channel consolidation is reshaping residential standby generator distribution, with regional electrical contractors acquiring smaller HVAC and generator specialists to capture recurring maintenance contract revenue. Homeowners in hurricane-exposed coastal counties are encountering fewer independent purchase options as manufacturer-direct certification programs tighten. Florida and Gulf Coast Texas submarkets exhibit the most pronounced channel concentration, where three installer networks control majority access to factory warranty activation.
United States Backup Power Systems Market Segmentation
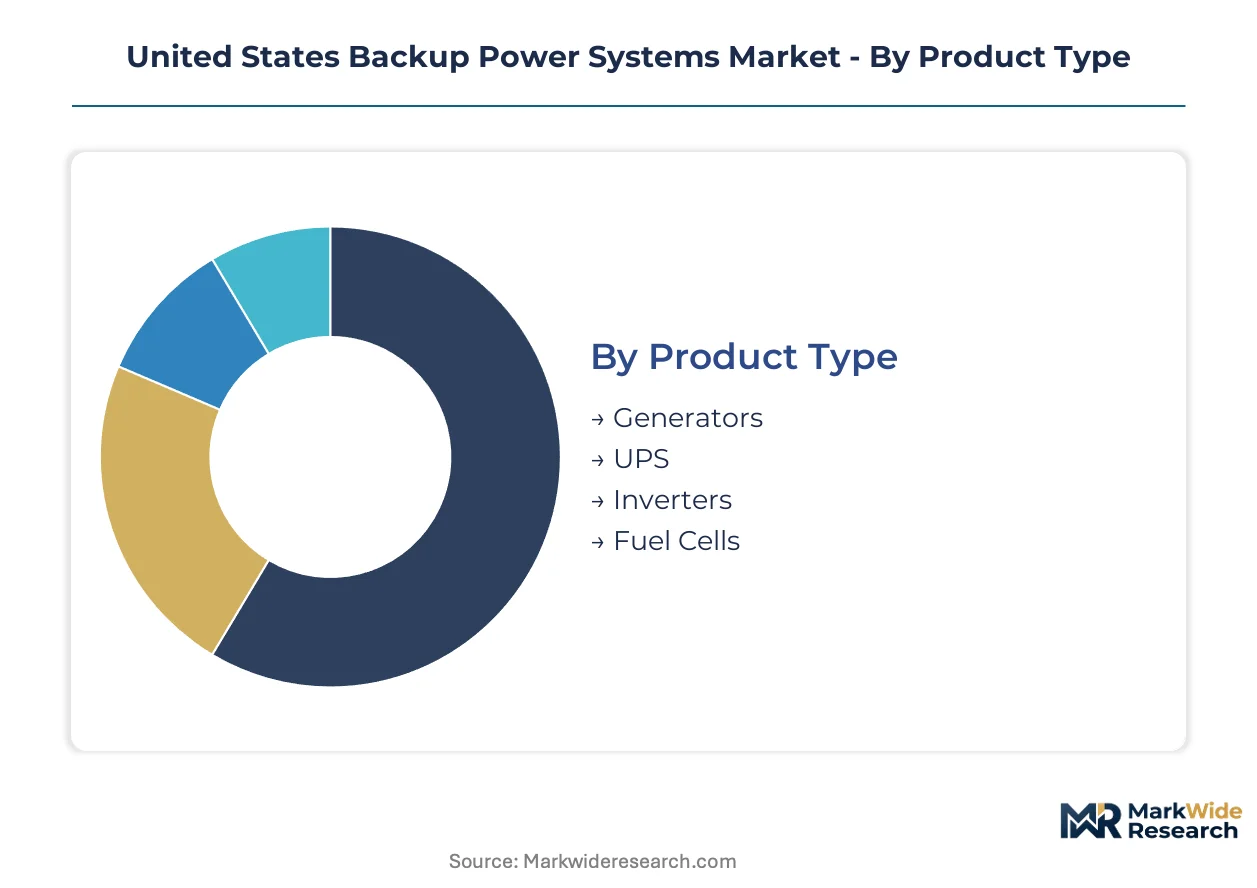
Backup power procurement patterns diverge sharply across facility types, fuel sources, and operational models. Understanding these axes clarifies why diesel generators retain industrial dominance while lithium-ion batteries capture healthcare and commercial expansion.
Product Type:
Electromechanical and chemical storage architectures serve distinct transfer-time requirements and load-sensitivity thresholds.
- Generators:Diesel and natural gas reciprocating engines deliver sustained multi-hour output for facilities where extended autonomy outweighs transfer speed. Texas data centers and Florida hospitals commission these for hurricane-season resilience despite EPA Tier 4 Final compliance costs.
- UPS:Double-conversion and line-interactive topologies guarantee sub-20 millisecond transfer for server racks, surgical suites, and semiconductor fabrication. California healthcare clusters specify these for sensitive imaging equipment where voltage sag tolerance approaches zero.
- Inverters:Power electronics convert DC battery or solar output to grid-synchronous AC, enabling behind-the-meter solar integration. Residential solar-plus-storage retrofits in storm-exposed counties drive procurement volume.
- Fuel Cells:Hydrogen and natural gas reformer systems deliver silent, zero-emission baseline power for urban healthcare campuses facing noise ordinances and air quality restrictions.
Generators lead on scale; fuel cells lead on momentum.
End User:
Facility criticality and downtime cost exposure determine specification stringency and maintenance contract attachment rates.
- Residential:Single-family and multifamily installations prioritize automatic transfer switches and natural gas fuel security. Florida coastal counties and Houston suburbs exhibit highest penetration as grid reliability concerns mount.
- Commercial:Retail, hospitality, and office deployments balance first-cost constraints against business interruption insurance requirements. Texas commercial real estate operators are adopting microgrid-as-a-service models to shift capital burden.
- Industrial:Manufacturing and process industries specify redundant generator-battery hybrids for production line continuity. Gulf Coast petrochemical corridors maintain largest installed diesel base.
- Healthcare:Joint Commission accreditation standards mandate NFPA 110-compliant emergency power supply systems with 96-hour fuel autonomy for critical access hospitals. California and Florida facilities are retrofitting battery-fuel cell hybrids to meet evolving resilience mandates.
Industrial installations anchor revenue volume; healthcare accounts expand most quickly.
Technology:
Fuel source selection reflects emissions compliance exposure, fuel security, and operational hour economics.
- Solar:Photovoltaic arrays paired with battery storage reduce grid dependency for daytime-peaking loads. California behind-the-meter deployments face 6-18 month interconnection queue delays.
- Diesel:Compression-ignition engines retain lowest first-cost and highest power density for industrial standby applications. EPA emissions enforcement is accelerating fleet replacement cycles.
- Natural Gas:Spark-ignited units eliminate on-site fuel storage for facilities with pipeline access. Gulf Coast and Northeast corridor installations dominate where utility distribution networks are dense.
- Lithium-ion:Lithium iron phosphate chemistry enables silent, emissions-free operation with modular scalability. Texas and Florida healthcare campuses specify these for generator replacement phasing.
Diesel retains installed base dominance; lithium-ion gains share fastest.
Service Type:
Revenue model differentiation separates capital equipment vendors from recurring service providers.
- Installation:Electrical contractor and manufacturer-certified technician labor for system commissioning and interconnection approval. NFPA 110-certified labor scarcity constrains deployment velocity in Mountain states.
- Maintenance:Scheduled inspection, fluid analysis, and load-bank testing contracts lock in multi-year recurring margins. Natural gas standby units generate highest contract attachment rates.
- Repair:Emergency response and component replacement for out-of-warranty systems. Hurricane-season demand spikes in Florida and Texas strain technician availability.
- Consulting:Resilience auditing, fuel security assessment, and microgrid design services for commercial and healthcare operators navigating evolving interconnection standards.
Installation commands upfront revenue; maintenance delivers margin stability.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Certified technician pools concentrate along the Gulf Coast and Midwest industrial corridors, anchoring deployment capacity for generator-battery hybrid installations. Texas, Florida, and California dominate procurement volume as grid reliability deterioration accelerates replacement cycles. State-level interconnection standards and emissions mandates are fragmenting regulatory compliance burdens across jurisdictions.
Texas
Hurricane-season resilience mandates and data center expansion are driving redundant power infrastructure procurement in Dallas-Fort Worth and Houston. ERCOT grid instability following winter storm events tightened facility backup requirements for healthcare and petrochemical operators. EPA Tier 4 Final compliance deadlines are accelerating diesel generator fleet turnover in Gulf Coast industrial clusters.
Florida
Storm-related outage frequency and Joint Commission accreditation standards are compelling hospital battery-fuel cell retrofits in Miami-Dade and Tampa Bay metros. NFPA 110-certified installation labor scarcity constrains deployment velocity in Panhandle counties. The state's natural gas distribution network density limits standby generator specification options in rural residential developments.
California
Behind-the-meter battery deployments face 6-18 month utility interconnection queue delays in ISO-NE territories and Pacific Coast zones. OSHA workplace power safety mandates and state-level clean energy hour allowances are stranding recently commissioned diesel assets. Silicon Valley data centers and Los Angeles healthcare campuses are specifying lithium iron phosphate systems for silent operation compliance.
Southeast
Georgia and Carolinas manufacturing corridors are adopting microgrid-as-a-service contracting to shift capital burden from operational expenditure constraints. Regional electrical contractor consolidation is tightening installer channel access for residential standby generator procurement. NHTSA vehicle-to-home bidirectional charging rulemaking is creating alternative backup pathways in Atlanta and Charlotte suburbs.
Mountain West
Remote commercial sites and rural residential developments lack natural gas pipeline proximity, excluding specified standby solutions in Colorado and Arizona growth corridors. Skilled technician scarcity relative to Gulf Coast baselines extends project timelines for healthcare facility emergency power upgrades. Solar-plus-storage retrofits are capturing share where grid dependency reduction carries insurance premium value.
United States Backup Power Systems Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across the backup power systems landscape, creating tiered competitive dynamics. The vendor base organizes around three strategic archetypes: integrated power management conglomerates with broad electrical infrastructure portfolios, generator heritage specialists defending industrial accounts through service network density, and battery-native entrants leveraging software-defined energy management. Consolidation activity concentrates in installer channel acquisition to capture recurring maintenance contract revenue, while technology licensing partnerships accelerate lithium-ion system certification timelines.
Within the integrated infrastructure tier, Cummins Inc. and Schneider Electric exemplify divergent strategic positioning around electromechanical versus power electronics architectures. Among residential standby specialists, Generac Holdings Inc. anchors installer channel control in hurricane-exposed coastal markets. Tesla occupies a distinct position through integrated solar-battery software stacks that reduce homeowner switching costs and bypass traditional generator distribution networks.
| Leading Market Players |
|---|
| Cummins Inc. |
| Schneider Electric |
| Generac Holdings Inc. |
| Tesla |
| Emerson Electric Co. |
| Eaton Corporation plc |
| Kohler Co. |
| ABB Limited |
| Caterpillar Inc. |
| Others |
Value Network & Pricing Analysis
EPA Tier 4 Final emissions certification gates qualified supply for premium-tier diesel generator procurement, compressing margins for uncertified manufacturers while elevating pricing power for Tier 4-compliant OEMs serving healthcare and data center accounts. This environmental mandate fragments the supplier base into certified and non-certified tiers, with certified suppliers commanding service contract premiums.
Pricing Analysis
Bundled installation-and-maintenance contracts dominate the residential standby generator segment, while unbundled equipment-only transactions prevail in industrial diesel procurement. Price differentiation rests on NFPA 110 certification tier and factory-authorized installer network density. Cost compression in mid-range diesel units is intensifying because EPA aftertreatment engineering burdens concentrate compliance costs on lower-volume product lines. Commercial real estate operators exhibit highest price sensitivity; critical access hospitals demonstrate lowest sensitivity due to Joint Commission accreditation requirements.
Supply Chain Analysis
Reverse-logistics flows for lithium-ion battery refurbishment and diesel generator remanufacturing are anchoring aftermarket parts networks in Texas and Florida service hubs. Manufacturing concentration centers on China for battery cells, South Korea for power electronics, and the United States for EPA-certified engine assembly. Raw material dependencies span lithium carbonate from South American brine operations, rare earth elements for permanent magnet generators, and steel castings for engine blocks. Single-source vulnerability in lithium hydroxide refining drives supply chain risk. Distribution runs through manufacturer-certified electrical contractor networks with factory warranty activation control.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market presents margin-expansion potential through lithium iron phosphate cost curves and premium-tier battery-fuel cell hybrid configurations for healthcare resilience mandates.
For Market Incumbents: Deepen NFPA 110-certified technician network density in Mountain West and Pacific Northwest corridors to preempt emerging regional competitors. Acquire regional electrical contractors in Florida and Texas to lock in recurring maintenance contract revenue pools. Battery-native entrants threaten traditional generator incumbents through software-defined energy management bypass of installer channels. For New Entrants and Emerging Players: Rural residential developments beyond natural gas pipeline networks represent an underserved buyer archetype with unmet standby power needs. Target solar-plus-storage retrofits in Colorado and Arizona growth corridors where grid dependency reduction carries insurance premium value. Pursue vehicle-to-home bidirectional charging partnerships with automotive OEMs to bypass traditional generator distribution entirely. For Investors and Strategic Acquirers: Roll-up economics work for regional electrical contractor platforms because installer channel consolidation in hurricane-exposed counties creates scarcity value for factory warranty activation rights. The five-to-ten-year viability window favors platforms with EPA certification infrastructure and multi-state service footprints. Monitor NHTSA vehicle-to-home export power rulemaking as inflection indicator for residential backup channel disruption.| Strategic Initiative | Industry Significance |
|---|---|
| NFPA 110 Certification Investment | EPA Tier 4 Final compliance creates competitive separation for certified OEMs in healthcare procurement. |
| Installer Channel Acquisition | Factory warranty activation control in Florida and Texas locks in recurring maintenance contract margins. |
| Lithium Iron Phosphate Scale-Up | Modular 50-100 kWh increments match hospital capital budget phasing in Texas and Florida campuses. |
| Vehicle-to-Home Partnership | NHTSA bidirectional charging standards enable residential backup bypass of traditional generator networks. |
| Microgrid-as-a-Service Launch | Operational expenditure models shift capital burden for Texas and Florida commercial real estate operators. |
Research Methodology
Direct dialogue with hospital engineering directors, electrical contractor principals, EPA compliance officers, and utility interconnection planners anchored qualitative findings, cross-validated against EIA power outage databases, FERC interconnection queue filings, NFPA code revision records, and SEC 10-K disclosures from publicly traded generator and battery OEMs. Bottom-up facility-level procurement tracking and top-down market sizing triangulated volume estimates.
Segment-level projections across product type, end user, technology, and service type dimensions informed value outputs across the analysis window. CAGRs derived from fitted growth curves incorporating EPA compliance deadline impacts, lithium carbonate price volatility scenarios, and state-level clean energy mandate trajectories. Modeled inputs included ERCOT grid reliability indices, Joint Commission accreditation standard revisions, and NHTSA rulemaking timelines.
Underlying measurement precision varies by segment; diesel generator installed base estimates carry tighter precision than emerging fuel cell deployment figures. Forecasts reflect assumptions around IRA tax credit continuity, EPA enforcement intensity, and interconnection queue clearance rates. Practitioners should monitor lithium carbonate futures curves, NHTSA final rule publication, and state-level net metering reforms for early signals.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Energy & Power
Disposable Batteries Market
Energy & Power
Sodium Sulfur (Nas) Battery for Energy Storage Market
Energy & Power
Liquid-Immersed Transformers Market
Energy & Power
Germany Electric Vehicle Battery Manufacturing Equipment Market
Energy & Power
Industrial and Residential Heating Market
Energy & Power
Green Energy Lighting Market
Energy & Power
Digital Power Utility Market
Energy & Power
Nuclear Fuel Fabrication Market
Energy & Power
India Gensets Market
Energy & Power
India Natural Gas Market
Energy & Power
Cathodic Protection Market
Energy & Power
United Arab Emirates Oil and Gas Downstream Market
Energy & Power
United States Distribution Transformer Market
Energy & Power
City Gas Distribution Market
Energy & Power
South-East Asia DC Distribution Network Market
Energy & Power
United States Positive Displacement Pumps Market