
 United States Bunker Fuel Market | 2026-2036
United States Bunker Fuel Market Size, Share, and Industry Trends Forecast 2026-2036
United States Bunker Fuel Market Analytics
Multi-source procurement is decoupling from traditional single-refiner relationships across the United States bunker fuel supply base. Exxon Mobil Corporation leverages its integrated Gulf Coast refining network to secure marine fuel offtake agreements. World Fuel Services competes through its distributed bunkering infrastructure at strategic port locations. Phillips 66 anchors its position via pipeline-connected storage terminals serving West Coast vessel traffic.
Bunker fuel denotes residual and distillate marine fuels burned in main and auxiliary engines aboard oceangoing vessels, with specifications governed by ISO 8217 standards for viscosity, density, and sulfur content. The product serves as the primary energy input for international shipping propulsion and onboard power generation. IFO380 and ULSFO dominate volume flows along major trade lanes, while MGO commands premium positioning in emission control areas where sulfur limits tighten. The application split reveals Shipping as the mature volume anchor, with Offshore platforms generating higher per-unit margins due to remote delivery logistics and specialized fuel handling requirements.
EPA enforcement of the North American Emission Control Area, Coast Guard fuel quality inspection protocols, and California Air Resources Board marine fuel rules collectively reshape product formulation and compliance costs. These frameworks elevate demand for ULSFO and MGO while phasing out non-compliant high-sulfur residual streams. Stakeholders must track regulatory harmonization between federal sulfur standards and state-level carbon intensity programs to anticipate product mix shifts and infrastructure investment timing.
Market Dynamics
IMO sulfur caps and EPA marine diesel standards are compressing residual fuel demand while accelerating distillate uptake across US port complexes. Container lines now face compliance cost structures that reshape procurement relationships and terminal infrastructure requirements.
Growth Catalysts
- IMO 2020 Sulfur Regulations:The global sulfur cap mandates 0.5% maximum fuel sulfur content, forcing vessel operators toward ULSFO and MGO blends. Compliance drives sustained demand for low-sulfur marine gasoil along the Gulf Coast.
- Container Shipping Expansion:Major carriers are expanding trans-Pacific and intra-Americas routes, concentrating bunkering activity at Houston-Galveston and Los Angeles-Long Beach. Port infrastructure investments support higher throughput volumes.
- Dual-Fuel Engine Technology:LNG-capable and methanol-ready propulsion systems create parallel demand for alternative marine fuels. Shipyards report rising orders for vessels with flexible fuel architecture.
Market Restraints
- Crude Price Volatility:Residual fuel oil pricing tracks Brent and WTI benchmarks with minimal lag, compressing blender margins during supply shocks. Refiners face input cost instability that transfers to marine fuel pricing.
- Gulf Coast Refining Concentration:Over 60% of US marine fuel production clusters within Texas-Louisiana refining corridors. Hurricane disruption or unplanned maintenance creates regional supply vulnerability.
- High-Sulfur Fuel Oil Displacement:Scrubber installation economics weakened post-2020, stranding HSFO storage assets. Terminal operators face stranded infrastructure write-downs and conversion capital requirements.
Strategic Opportunities
- California Low-Carbon Fuel Standard:CARB marine fuel rules create credit generation opportunities for renewable diesel and biofuel blends. Compliance pathways reward early adopters with LCFS credit monetization.
- Pacific Northwest Port Development:Tacoma and Seattle terminals lack integrated bunkering infrastructure comparable to Southern California. Greenfield storage and barge loading investments capture Asia-Pacific trade lane volumes.
- Digital Bunker Procurement Platforms:Real-time pricing and automated contract execution reduce procurement friction for tramp shipping operators. Technology vendors are penetrating the fragmented spot market segment.
Industry Challenges
- Marine Chemist Certification Bottlenecks:Fuel quality testing and bunker surveyor capacity constraints delay vessel turnaround times. Port authorities report inspection queue backlogs during peak shipping seasons.
- Legacy Storage Terminal Retrofitting:Converting HSFO tanks to ULSFO service requires cleaning, lining replacement, and segregation infrastructure. Capex commitments strain independent terminal operator balance sheets.
- ISO 8217 Specification Interpretation Variance:Disputes over cat fines, viscosity, and sulfur measurement methodologies generate off-spec claims and arbitration costs. Surveyor standardization remains incomplete across US ports.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | United States Bunker Fuel Market |
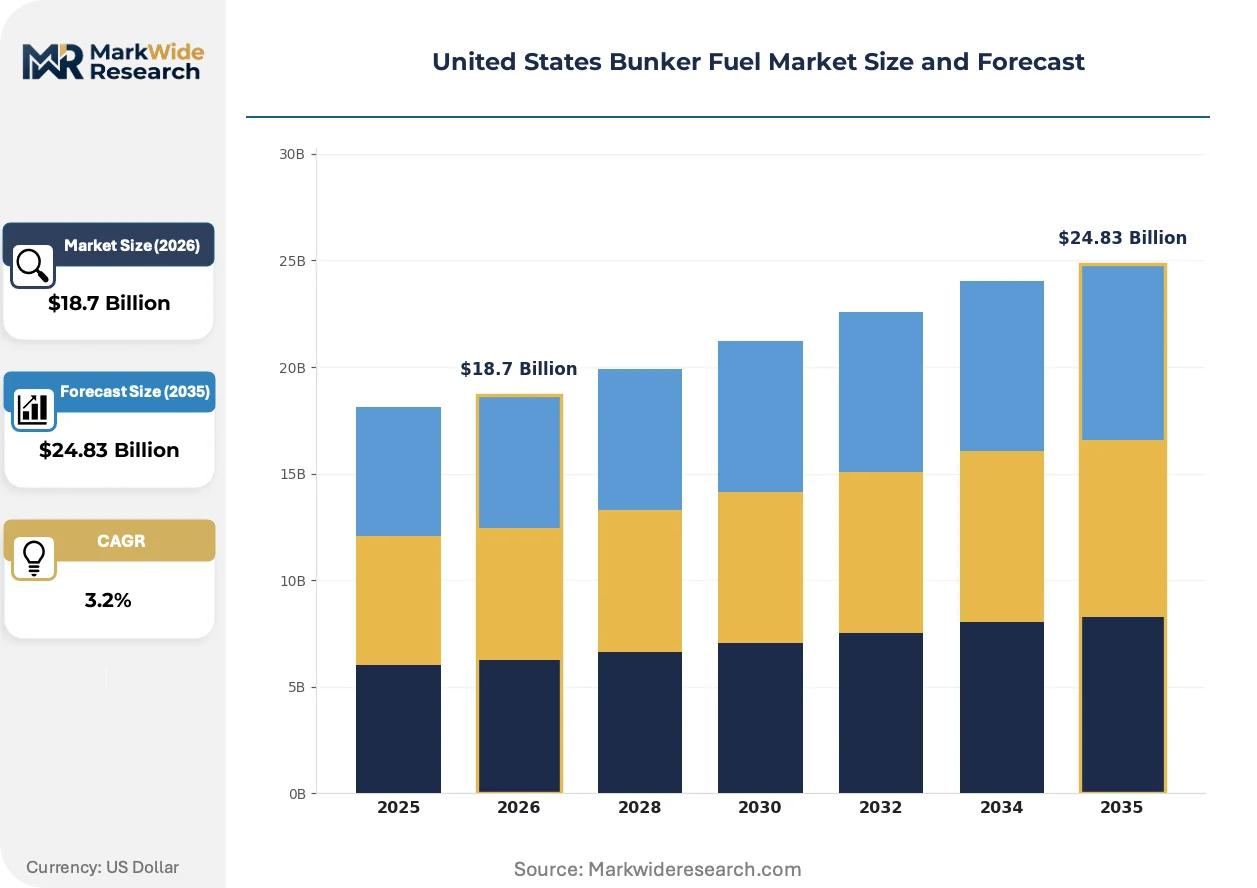
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $24.83 Billion |
| CAGR (2026 – 2036) | 3.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Fuel Type: IFO380, IFO180, MGO, ULSFO Application: Shipping, Offshore, Fishing, Power Generation Distribution Channel: Direct Sales, Brokers, Online Platforms, Bunkering Services End User: Commercial Vessels, Tankers, Cargo Ships, Offshore Platforms |
| Companies Covered | Exxon Mobil Corporation, Shell Plc, Chevron Corporation, BP Plc, TotalEnergies SE, World Fuel Services, Phillips 66, NuStar Energy, Peninsula Petroleum, Others |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
United States Bunker Fuel Market Evolving Landscape
Digital fuel management systems and alternative propulsion pathways are restructuring how marine energy is procured, stored, and consumed across American waterways. Three developments merit particular attention.
Mass flow meters for bunker delivery measurement are consolidating custody transfer standards across US ports. Houston and Los Angeles-Long Beach terminals now mandate MFM-equipped barges for commercial deliveries. Shipping lines gain quantity certainty while suppliers reduce dispute resolution costs. The technology is consolidating market share among integrated suppliers with capital deployment capacity.
EPA enforcement of the North American Emission Control Area tightens sulfur limits to 0.1% within 200 nautical miles of US coasts. Refiners must maintain segregated low-sulfur production streams with dedicated logistics. Distillate marine gasoil captures volume from residual blends in coastal trades, with California Air Resources Board rules adding carbon intensity screening.
Long-term offtake contracting is displacing spot market exposure for major container lines. Maersk, MSC, and CMA CGM seek 12-36 month supply agreements with fixed differentials to Brent. Procurement teams prioritize supply security over price optimization given regulatory compliance requirements. The shift concentrates contract volumes with integrated refiners possessing dedicated marine fuel production units.
United States Bunker Fuel Market Segmentation
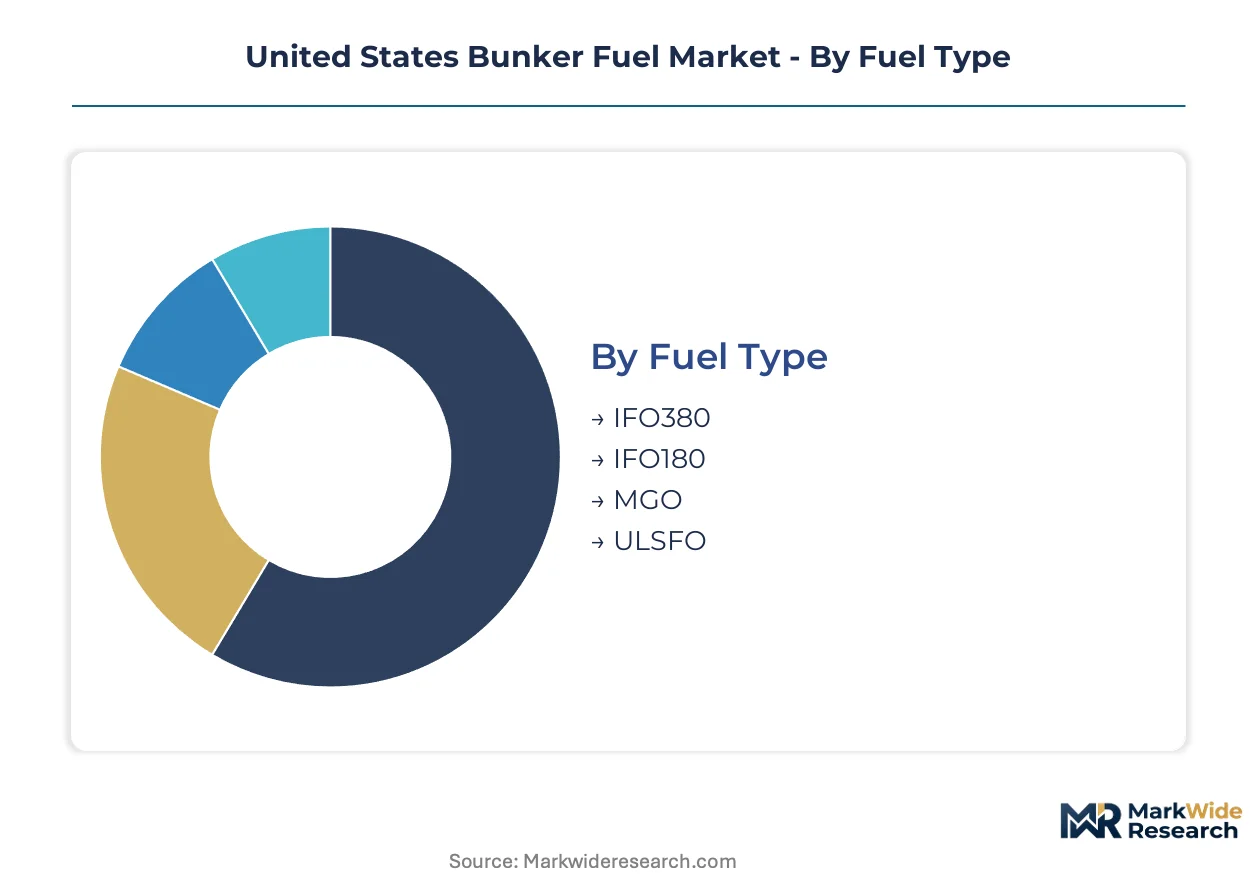
Bunker fuel procurement in the United States demands precise segmentation matching vessel specifications to regulatory requirements. Fuel type selection directly determines compliance with EPA marine diesel standards and IMO sulfur caps across coastal and inland waterway operations.
Fuel Type:
Residual grades dominate standalone engine combustion while distillates serve dual-use applications requiring emission control area compliance.
- IFO380:High-viscosity residual fuel oil with maximum 3.5% sulfur content prior to IMO 2020, now primarily consumed by scrubber-fitted vessels in international trades. Houston-Galveston terminals handle the largest IFO380 volumes for deep-sea container lines operating outside North American ECAs.
- MGO:Distillate marine gasoil meeting 0.1% sulfur limits within 200 nautical miles of US coasts under EPA enforcement. Los Angeles-Long Beach harbor traffic drives concentrated MGO demand where California Air Resources Board rules layer additional carbon intensity requirements.
- ULSFO:Blended low-sulfur residual-distillate hybrid achieving 0.5% global sulfur cap without exhaust gas cleaning systems.
- IFO180:Lower-viscosity residual variant for medium-speed engines requiring reduced preheating infrastructure.
IFO380 leads volumes today; MGO is gaining share fastest.
Application:
Commercial shipping generates baseline throughput while offshore operations command specialized logistics premiums.
- Shipping:Container lines, bulk carriers, and tankers constitute the core demand base for US bunker fuel procurement. Trans-Pacific route expansion concentrates activity at Gulf Coast and Southern California port complexes where vessel calls exceed 15,000 annually.
- Offshore:Drilling platforms and production facilities in the Gulf of Mexico require marine fuels delivered via specialized bunker barges to remote mooring locations. Remote logistics inflate per-unit margins compared to alongside deliveries at commercial terminals.
- Fishing:Commercial fleets operating from Pacific Northwest and New England ports consume distillate grades for engine reliability in cold-start conditions.
- Power Generation:Coastal industrial facilities and island grids utilize residual marine fuels in stationary power applications.
Shipping anchors absolute consumption; offshore applications deliver the steepest margin expansion trajectory.
Distribution Channel:
Procurement complexity varies from direct refiner relationships to fragmented spot market intermediation.
- Direct Sales:Integrated refiners contract directly with major container lines for 12-36 month offtake agreements with fixed Brent differentials. Exxon Mobil and Phillips 66 leverage dedicated marine fuel production units to secure these relationships.
- Bunkering Services:Terminal operators and fuel suppliers coordinate physical delivery alongside vessels at berth or via barge transfer at anchorage. Houston and Los Angeles-Long Beach mandate mass flow meter-equipped barges for custody transfer certainty.
- Brokers:Independent intermediaries match tramp shipping operators with available supply across fragmented port networks.
- Online Platforms:Digital procurement systems automate spot market price discovery and contract execution for smaller fleet operators.
Direct sales capture the largest contract volumes; online platforms are climbing the fastest as digital adoption penetrates the spot market.
End User:
Vessel scale and operational profile determine fuel grade selection and delivery logistics requirements.
- Cargo Ships:Container vessels and general cargo operators face the strictest emission compliance deadlines under IMO and EPA frameworks. Dual-fuel engine retrofits and newbuilds are expanding LNG and methanol-ready architectures alongside conventional bunker demand.
- Commercial Vessels:Cruise lines and ferry operators concentrate demand at specific turnaround ports where bunkering windows align with passenger schedules.
- Tankers:Crude and product tankers trading between US Gulf Coast refining centers and global markets require high-volume, rapid turnaround fueling.
- Offshore Platforms:Fixed and floating production facilities in federal waters depend on marine fuel supply chains extending beyond commercial port infrastructure.
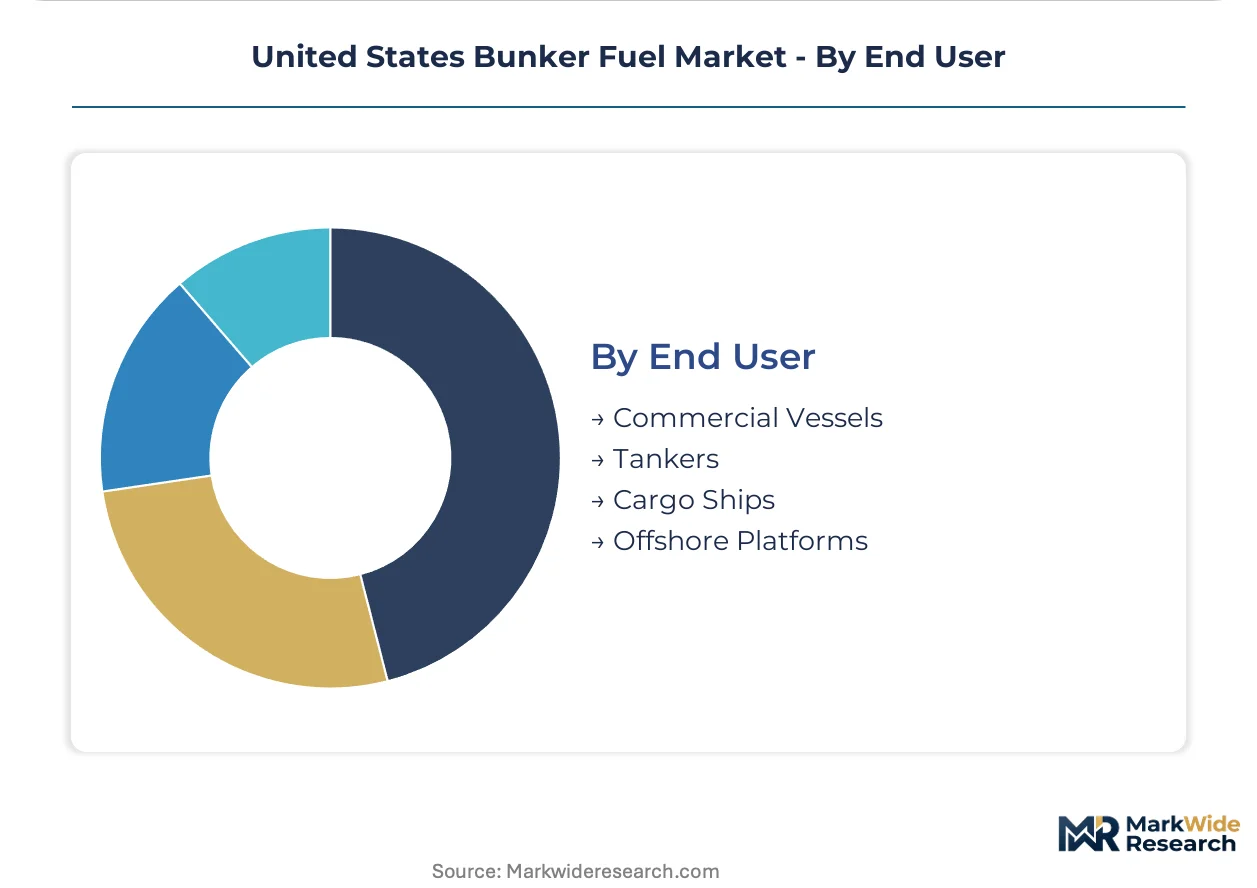
Cargo ships dominate fuel offtake today; offshore platforms are expanding most quickly on a percentage basis.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The Houston-Galveston port complex anchors United States bunker fuel demand, handling over 15,000 vessel calls annually while California's twin ports enforce stricter sulfur and carbon regulations that reshape product specifications across the Pacific trade lane.
Texas Gulf Coast
Refinery concentration along the Houston Ship Channel produces the majority of domestic marine fuel supply. EPA marine diesel standards and Coast Guard fuel quality inspection protocols govern terminal operations. Corpus Christi and Beaumont-Port Arthur storage clusters expand barge loading capacity to capture container line traffic.
Southern California
Los Angeles-Long Beach harbor traffic concentrates MGO demand for emission control area compliance. California Air Resources Board marine fuel rules layer carbon intensity requirements atop federal sulfur caps. Terminal operators invest in mass flow meter infrastructure to reduce custody transfer disputes.
Pacific Northwest
Tacoma and Seattle terminals lack integrated bunkering infrastructure comparable to Southern California ports. State-level environmental regulations push vessel operators toward lower-carbon fuel alternatives. Grays Harbor and Columbia River facilities develop greenfield storage to capture Asia-Pacific trade volumes.
Southeast Atlantic
Florida and Georgia port complexes serve cruise line and container carrier demand with seasonal traffic spikes. PortMiami and Savannah harbor authorities coordinate bunkering windows with passenger schedules. Jacksonville and Charleston terminals upgrade pipeline connections to regional refining centers.
Northeast Corridor
New York-New Jersey harbor facilities handle residual fuel blending for international trades outside North American ECAs. State environmental agencies enforce sulfur limits consistent with federal EPA frameworks. Boston and Philadelphia terminals specialize in distillate marine gasoil for coastal shipping routes.
United States Bunker Fuel Market Competitive Landscape
Established producers occupy the standard tier; emerging entrants pursue alternative marine fuel certification and digital procurement platforms. The United States bunker fuel supply base consolidates around integrated refiners with dedicated marine fuel production units and distributed terminal operators with barge delivery capabilities. Three archetypes dominate: Gulf Coast integrated refiners leveraging pipeline-connected storage, independent bunkering specialists with multi-port coverage, and trading houses facilitating spot market liquidity. Competitive intensity centers on long-term offtake contracting and mass flow meter infrastructure deployment.
Within the integrated refiner tier, Exxon Mobil Corporation and Chevron Corporation exemplify Gulf Coast production concentration with marine fuel offtake agreements. World Fuel Services occupies a position among independent bunkering specialists, coordinating physical delivery across fragmented port networks. These three entities anchor distinct competitive vectors: captive refining supply, distributed logistics infrastructure, and digital procurement intermediation.
| Leading Market Players |
|---|
| Exxon Mobil Corporation |
| Shell Plc |
| Chevron Corporation |
| BP Plc |
| TotalEnergies SE |
| World Fuel Services |
| Phillips 66 |
| NuStar Energy |
| Peninsula Petroleum |
| Others |
Value Network & Pricing Analysis
California Air Resources Board marine fuel rules gate both qualified supply and premium-tier pricing access, restricting terminal participation to operators with segregated low-sulfur storage and mass flow meter infrastructure. Refiners lacking CARB-compliant blending capacity face exclusion from the highest-margin West Coast contracts, while compliant suppliers capture sulfur-premium and carbon-credit stacking opportunities.
Pricing Analysis
Brent and WTI crude benchmarks transmit directly into marine fuel pricing through minimal lag, compressing blender margins during supply shocks. Contract-based long-term offtake with fixed differentials dominates procurement relationships for major container lines, while spot market exposure concentrates among tramp operators. Price differentiation rests on sulfur compliance grade and mass flow meter certification status, with California terminals commanding premiums over Gulf Coast supply. Cost compression in residual fuel blending is intensifying because scrubber-fitted vessel demand has weakened post-2020. Tramp shipping operators exhibit highest price sensitivity; integrated container lines prioritize supply security over optimization.
Supply Chain Analysis
Single-source vulnerability sits with Gulf Coast refining concentration, where over sixty percent of domestic marine fuel production clusters within Texas-Louisiana corridors. Crude oil feedstock, hydrogen for hydrodesulfurization, and specialized additives constitute critical input dependencies. Hurricane disruption or unplanned maintenance creates regional supply vulnerability with limited short-term substitution options. Distribution runs through pipeline-connected storage terminals serving vessel traffic at Houston-Galveston and Los Angeles-Long Beach, with barge transfer completing final-mile delivery.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The United States bunker fuel market functions as a stable compounder, with EPA and IMO sulfur enforcement driving steady demand migration toward low-sulfur distillates and compliant residual blends.
For Market Incumbents: Deepen backward integration into hydrogen supply and hydrodesulfurization capacity to defend margin position against merchant refinery competition. Secure long-term terminal storage leases at Houston-Galveston and Los Angeles-Long Beach to lock in throughput access. Invest in mass flow meter retrofitting ahead of Coast Guard mandate expansion to capture custody transfer standardization benefits. For New Entrants and Emerging Players: Digital procurement platforms offer the most penetrable entry vector, with spot market intermediation still fragmented across Pacific Northwest and Southeast Atlantic ports. Target independent terminal operators lacking automated contract execution capabilities. Develop API-connected pricing feeds and automated bunker delivery scheduling to differentiate from incumbent phone-and-fax workflows. For Investors and Strategic Acquirers: Valuations sit cheapest among independent bunkering specialists with underutilized storage assets in secondary port complexes. The five-to-ten year viability window favors operators with convertible tank infrastructure and CARB compliance pathways. Watch scrubber retrofit cancellation rates as an inflection indicator for residual fuel demand trajectory.| Strategic Initiative | Industry Significance |
|---|---|
| Low-Sulfur Storage Conversion | HSFO tank retrofitting to ULSFO service captures CARB and EPA compliance premiums at West Coast terminals. |
| Mass Flow Meter Deployment | MFM-equipped barge fleets reduce custody transfer disputes and consolidate market share among integrated suppliers. |
| Long-Term Offtake Contracting | Fixed-differential agreements with Brent benchmarks secure throughput for refiners with dedicated marine fuel units. |
| Digital Procurement Platform Launch | Automated spot market execution penetrates fragmented tramp shipping segments underserved by incumbent intermediaries. |
| Renewable Diesel Blending Certification | LCFS credit generation through biofuel blends creates margin stacking opportunities under California Air Resources Board rules. |
Research Methodology
Multiple input streams — primary interviews with marine fuel procurement officers, terminal operations managers, and Coast Guard inspection personnel, alongside secondary validation — were reconciled to construct supply-demand balances. Customs and trade data, EPA enforcement records, California Air Resources Board fuel certification databases, and SEC filings from integrated refiners provided volume and pricing benchmarks. Bottom-up terminal throughput estimates and top-down refinery production allocations were triangulated against vessel call data from Houston-Galveston and Los Angeles-Long Beach port authorities.
Data-stream reconciliation across the projection horizon applied fuel type, application, distribution channel, and end-user segmentation dimensions. CAGRs were derived from trend extrapolation of sulfur regulation compliance timelines and container shipping route expansion patterns. Modeled inputs included scrubber installation economics, dual-fuel engine order books from shipyards, and LCFS credit price trajectories affecting renewable diesel blending economics.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to IMO greenhouse gas strategy amendments and alternative marine fuel certification pathways. Forecasts reflect documented assumptions regarding regulatory enforcement intensity and vessel fleet turnover rates. Outcomes are best read as a band of plausibility, not a single trajectory.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Fuels
China LNG Market
Fuels
Global Methane Hydrate Market
Fuels
South America Bunker Fuel Market
Fuels
South Africa Bunker Fuel Market
Fuels
Oil Dispenser Market
Fuels
Underground Coal Gasification Market
Fuels
Renewable Fuel Quality and Regulatory Compliance Test Instruments Market
Fuels
Emulsified Fuel Market
Fuels
High-Temperature Industrial Burner Market
Fuels
Brazil LNG Market
Fuels
Global Gas Cylinder Market
Fuels
China Coal Market
Fuels
South America Aviation Fuel Market
Fuels
Refuse Derived Fuel Market
Fuels
Gas Pooling Mechanism Market
Fuels
North America Aviation Fuel Market