
 Biodiesel Market | 2026-2036
Biodiesel Market Size, Share, and Industry Trends Forecast 2026-2036
Biodiesel Market Analysis
The EU Green Deal is pivoting European fuel demand toward lower-carbon alternatives, with national blending mandates tightening across member states. Neste Corporation leverages its proprietary NEXBTL refining platform to sustain premium renewable diesel output from waste and residue feedstocks. Archer Daniels Midland Company anchors North American supply through its extensive oilseed processing network and downstream biorefinery assets. Renewable Energy Group differentiates via distributed production facilities that convert diverse feedstocks into ASTM D6751-compliant fuel.
Biodiesel comprises fatty acid methyl esters synthesized from renewable lipid sources through transesterification, yielding a drop-in diesel substitute with cetane ratings typically exceeding 51 and sulfur content below 15 ppm; its primary purpose is displacing petroleum diesel in compression-ignition engines while reducing net carbon dioxide emissions across the combustion cycle. Vegetable oils occupy the dominant raw material position due to established crushing infrastructure and consistent supply chains, though used cooking oil gathers momentum as the fastest-growing feedstock category driven by waste-to-value economics and lower indirect land-use change risk. Hydrogenation-based production methods command premium positioning for renewable diesel with superior cold-flow properties, while conventional transesterification retains cost leadership in commodity biodiesel segments.
The EPA administers the Renewable Fuel Standard that mandates annual renewable volume obligations for US refiners and importers, while the EU F-Gas Regulation and RED III framework establish progressively stringent greenhouse gas reduction thresholds for transport fuels sold across European member states. ASTM D6751 and EN 14214 specifications govern product quality, filterability, and storage stability, with non-compliant batches facing rejection at terminal racks and pipeline injection points. Stakeholders must monitor feedstock cost volatility, policy renewal timelines, and advanced biofuel credit trading dynamics to calibrate capacity investments and offtake contracting strategies.
Market Dynamics
The EU Green Deal's binding greenhouse gas reduction targets are compressing demand timelines across European transport fleets, forcing refinery infrastructure upgrades and feedstock procurement reconfigurations before 2030 mandates lock in.
Growth Catalysts
- EU F-Gas Regulation:Member states enforce progressively stringent transport fuel carbon intensity thresholds, compelling diesel distributors to secure certified biodiesel offtake contracts.
- Used cooking oil aggregation:Waste-to-value economics and lower indirect land-use change risk accelerate feedstock diversification beyond virgin vegetable oils.
- German refinery upgrades:National biofuel quotas and infrastructure investments concentrate demand acceleration in Europe's largest compression-ignition engine market.
Market Restraints
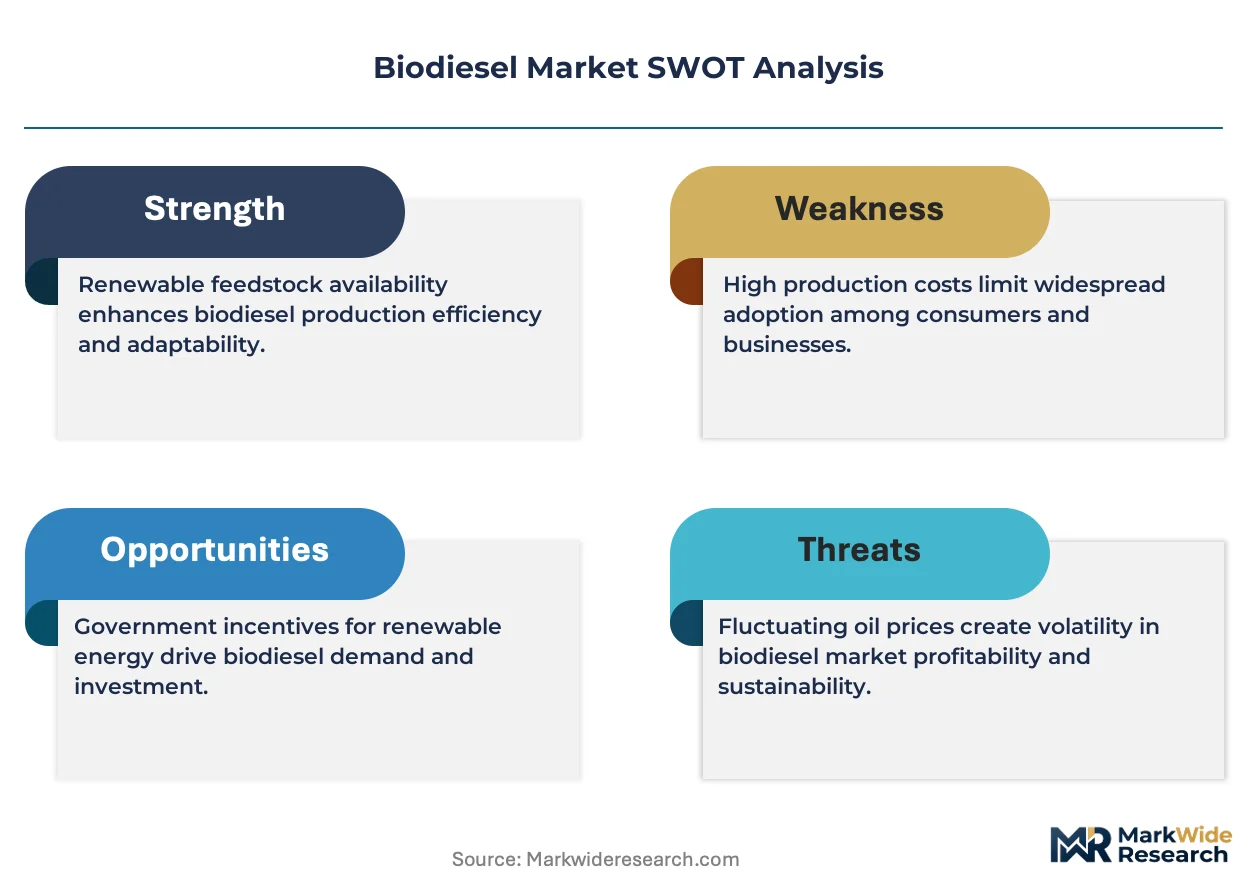
- Feedstock cost volatility:Rapeseed and soybean oil prices swing with agricultural commodity cycles, compressing blender margins during harvest shortfalls.
- Hydrogenation capacity concentration:Premium renewable diesel production clusters among integrated refiners with hydroprocessing assets, limiting supply elasticity.
- ASTM D6751 compliance friction:Non-compliant batches face immediate rejection at terminal injection points, creating quality assurance bottlenecks for smaller producers.
Strategic Opportunities
- India transport sector:National biofuel blending targets and expanding fleet dieselization create underpenetrated demand for ASTM D6751-compliant imports.
- Marine bunker fuels:International Maritime Organization sulfur regulations open new offtake channels for biodiesel-biogenic fuel oil blends in coastal shipping.
- Digital feedstock traceability:Blockchain-enabled supply chain verification meets emerging sustainability certification requirements from European fuel retailers.
Industry Challenges
- Transesterification process engineering:Skilled technician shortages constrain capacity expansion at distributed production facilities converting diverse waste streams.
- EN 14214 cold-flow property certification:Seasonal testing protocols and multi-jurisdiction approval timelines delay product release during peak demand windows.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biodiesel Market |
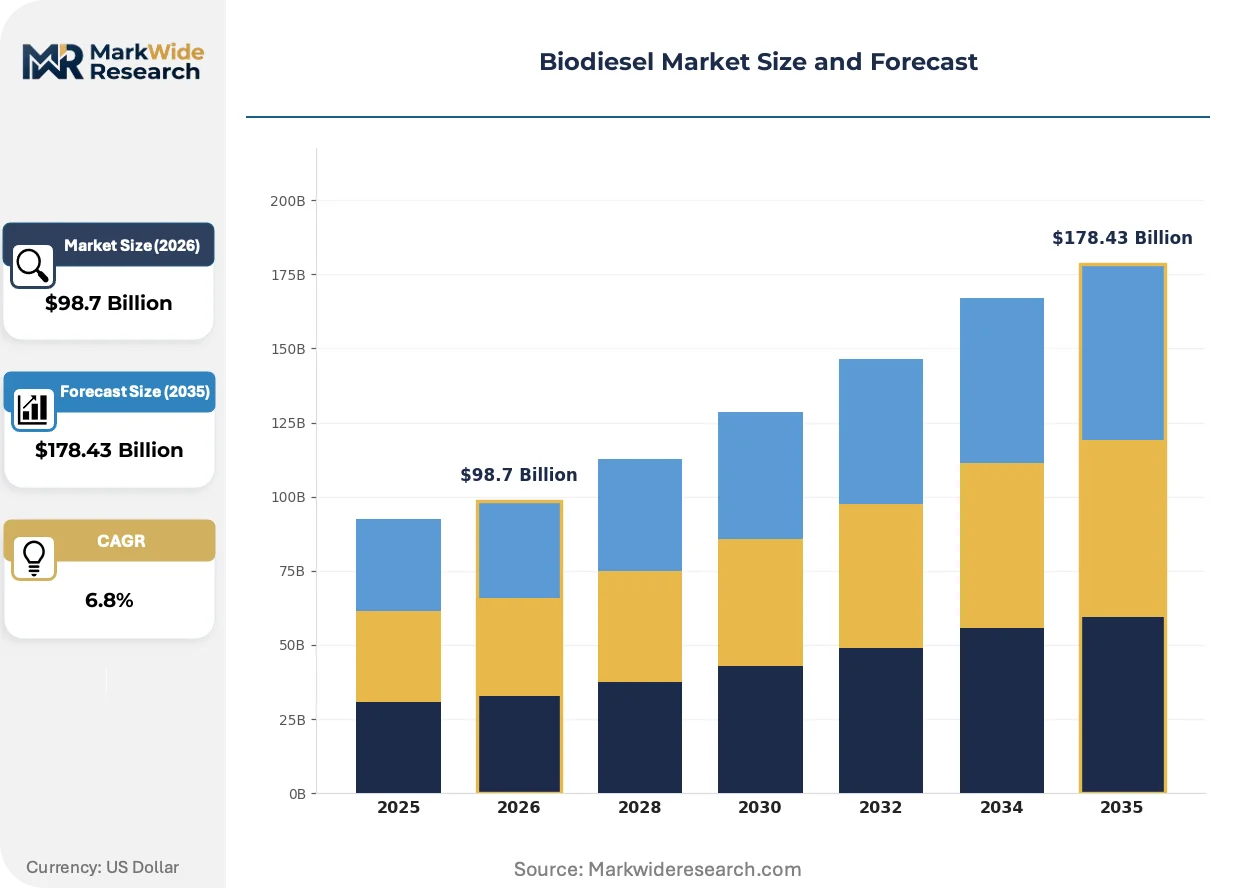
| Market Size in 2026 | $98.7 Billion |
| Market Size in 2035 | $178.43 Billion |
| CAGR (2026 – 2036) | 6.8% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Raw Material: Animal Fats, Vegetable Oils, Algae, Used Cooking Oil Production Method: Transesterification, Hydrogenation, Fermentation, Pyrolysis End User: Transportation, Power Generation, Industrial, Residential Distribution Channel: Direct Sales, Retail, Wholesale, Online |
| Companies Covered | Archer Daniels Midland Company, Neste Corporation, Cargill, Incorporated, Renewable Energy Group, Wilmar International Limited, Bunge Limited, Valero Energy Corporation, Louis Dreyfus Company, FutureFuel Corporation, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biodiesel Market Emerging Trajectories
Production technology divergence is splitting the market into premium hydrogenation-derived renewable diesel and commodity transesterification biodiesel, with feedstock flexibility and cold-flow performance becoming the primary competitive differentiators.
Hydrogenation-based renewable diesel production is overtaking conventional transesterification in cold-climate markets. Nordic and German fleet operators prioritize superior cloud-point performance for winter operability. This technology shift is compressing the addressable market for first-generation biodiesel in premium transport segments.
EPA Renewable Fuel Standard renewable volume obligations tighten annually, forcing US refiners to secure advanced biofuel credits or face compliance penalties. Obligated parties accelerate long-term offtake contracting with domestic biorefineries. The advanced biofuel credit trading market concentrates price discovery among integrated producers with multi-feedstock flexibility.
Fleet procurement departments now mandate third-party sustainability certification before contract execution, displacing price-only tender evaluation. Large transport operators in Germany and the Netherlands embed lifecycle carbon accounting into supplier scorecards. This behavioral shift is most visible in municipal bus fleet tenders across Benelux urban transit authorities.
Biodiesel Market Segmentation
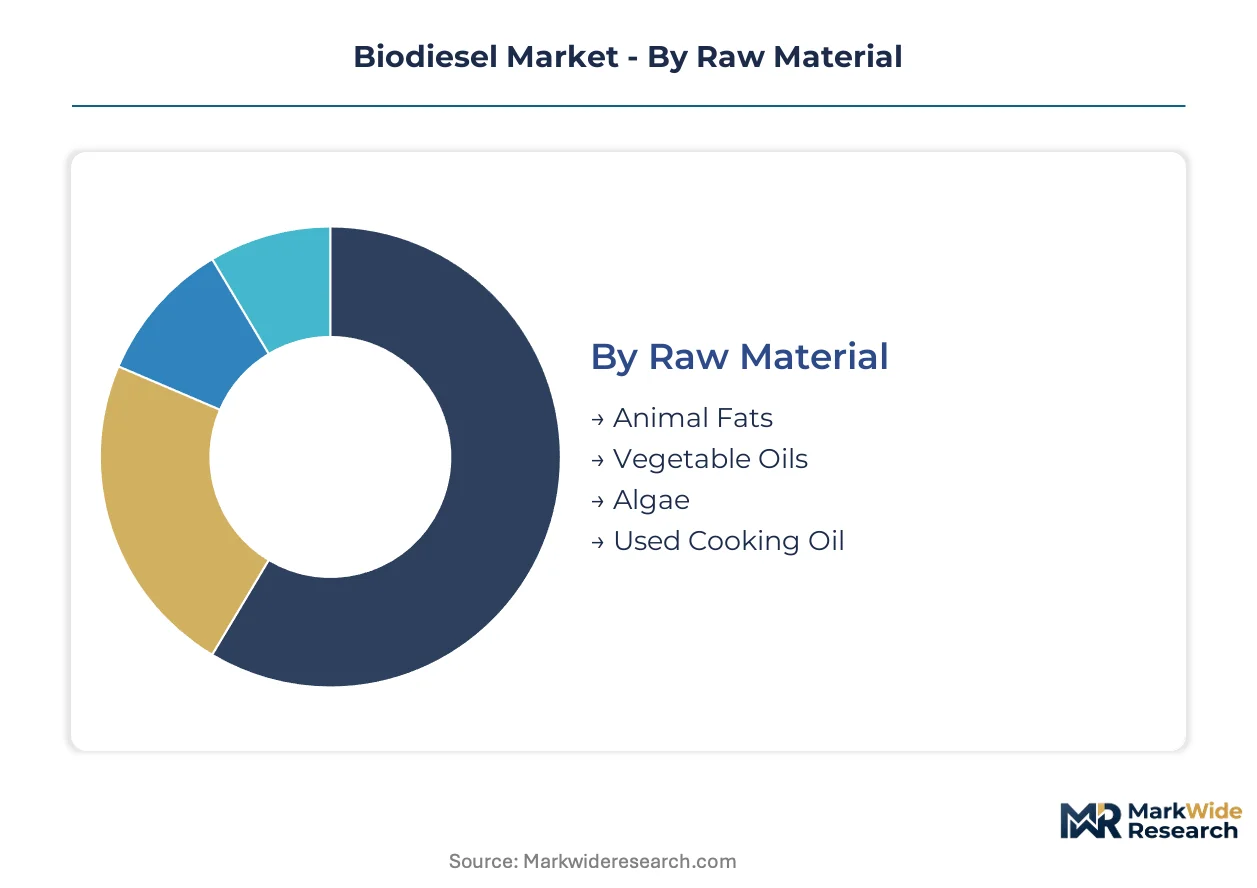
Biodiesel market segmentation reveals how feedstock economics, production technology, and end-use specifications create distinct competitive arenas. Each dimension shapes capital deployment decisions and margin structures differently.
Raw Material:
Supply concentration varies sharply across feedstock categories, with crushing infrastructure and waste aggregation networks determining regional cost competitiveness.
- Vegetable Oils:Rapeseed and soybean oils dominate commercial throughput due to established agricultural supply chains and consistent fatty acid profiles meeting EN 14214 specifications. German refiners anchor European demand, leveraging the country's oilseed processing density and biofuel quota enforcement to secure contracted offtake volumes.
- Used Cooking Oil:Waste-to-value economics and minimal indirect land-use change risk accelerate aggregation investments. Neste Corporation's Singapore facility exemplifies large-scale procurement from food service and industrial fryer networks across Southeast Asia.
- Animal Fats:Tallow and poultry fat supply concentrates in integrated meatpacking regions with rendering infrastructure.
- Algae:Cultivation remains pre-commercial despite superior oil yields per hectare.
Vegetable oils absorb the bulk of installed capacity; used cooking oil is expanding most quickly.
Production Method:
Technology selection locks in product specifications, cold-flow performance, and addressable market tiers.
- Hydrogenation:Hydroprocessed renewable diesel achieves cloud points below -20°C through saturation chemistry, enabling Nordic winter operability. Finnish and German fleet operators pay premiums for ASTM D975-compliant drop-in fuel that avoids blending infrastructure.
- Transesterification:Alkali-catalyzed esterification of triglycerides produces fatty acid methyl esters at lower capital intensity. US Midwest biorefineries exploit soybean oil proximity and EPA Renewable Fuel Standard credit economics to maintain cost leadership in commodity segments.
- Fermentation:Microbial lipid synthesis from cellulosic sugars remains at pilot scale.
- Pyrolysis:Thermal depolymerization of biomass oils yields inconsistent product quality.
Transesterification commands the greatest installed base; hydrogenation delivers the steepest expansion trajectory.
End User:
Customer specifications fragment across combustion environments, with sulfur limits and cetane requirements driving formulation differences.
- Transportation:Compression-ignition fleets in Germany and the Netherlands mandate third-party sustainability certification alongside EN 14214 compliance. Municipal bus operators in Rotterdam embed lifecycle carbon accounting into tender evaluations.
- Power Generation:Diesel-fired backup generators and remote microgrids absorb lower-specification biodiesel with relaxed cold-flow requirements.
- Industrial:Boiler fuel applications prioritize heat content over precise cetane ratings.
- Residential:Heating oil substitution concentrates in Northeast US markets with state-level bioheat mandates.
Transportation absorbs the bulk of premium-grade output; power generation is climbing the fastest as backup reliability demands diversify.
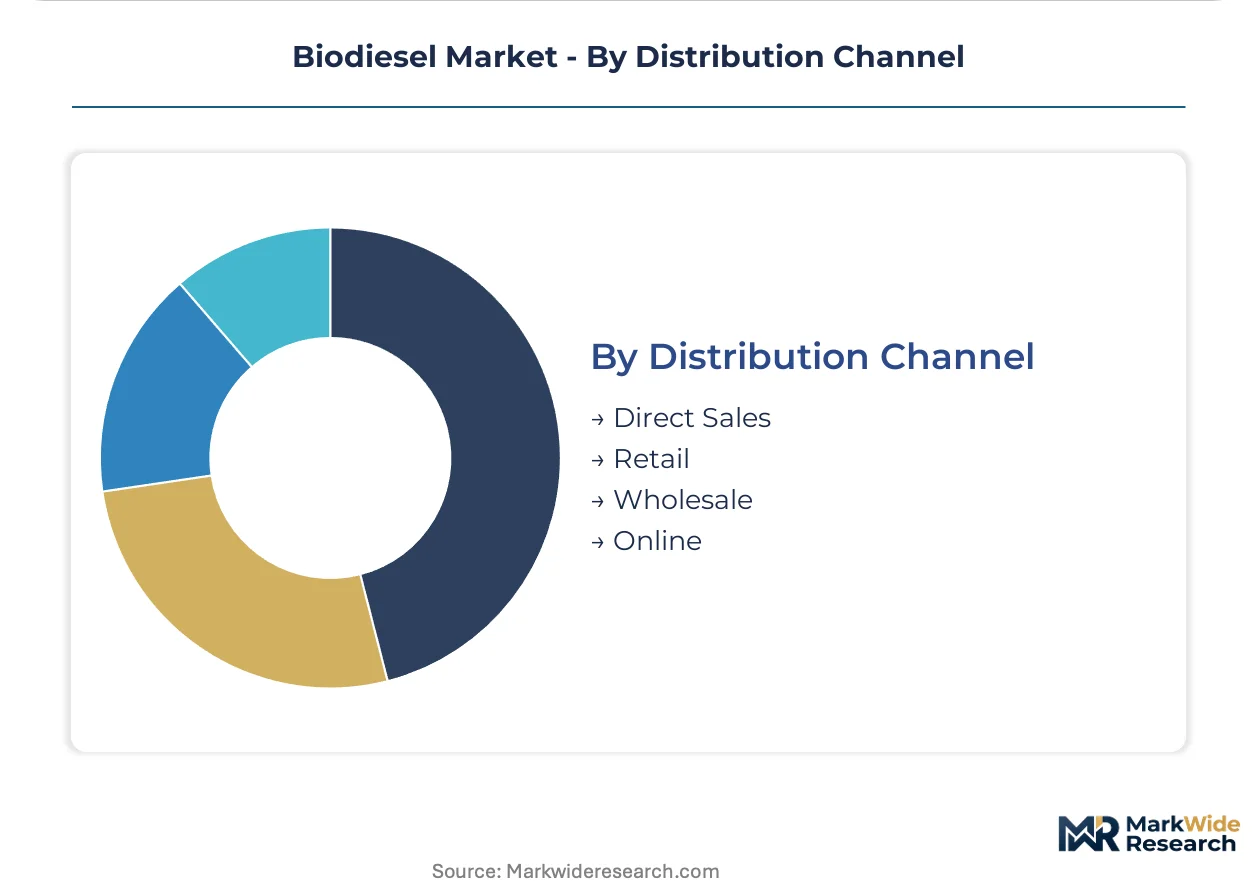
Distribution Channel:
Channel structure reflects batch size, certification requirements, and geographic proximity to production assets.
- Direct Sales:Long-term offtake contracts link biorefineries to obligated parties under the EPA Renewable Fuel Standard and EU RED III framework. Integrated oil companies secure pipeline injection slots through direct negotiation.
- Wholesale:Terminal rack purchases by fuel distributors enable blending flexibility across multiple origin points.
- Retail:Branded fuel stations offer B5-B20 blends to consumer diesel vehicle owners.
- Online:Digital platforms facilitate spot transactions for small-scale industrial buyers.
Direct sales absorb the bulk of contracted volume; wholesale is gaining share fastest as distributor consolidation accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Production capacity concentrates in agricultural heartlands with crushing infrastructure, while consumption clusters in jurisdictions with binding biofuel mandates. This geographic mismatch shapes trade flows and investment location decisions across the forecast horizon.
Germany
Fleet operators in Hamburg and the Ruhr industrial belt drive demand acceleration under the EU F-Gas Regulation's tightening carbon intensity thresholds. The national biofuel quota system enforces progressive blending obligations through 2030. Refinery infrastructure upgrades in Lower Saxony and North Rhine-Westphalia concentrate hydrogenation capacity expansion for premium renewable diesel output.
United States
Midwest soybean processing density and EPA Renewable Fuel Standard credit economics anchor transesterification capacity in Iowa and Illinois. Obligated parties under the renewable volume obligation framework secure long-term offtake contracts with domestic biorefineries. Houston-Galveston terminal complexes handle bulk biodiesel injection into diesel distribution networks serving Gulf Coast transport corridors.
Netherlands
Rotterdam's port infrastructure and storage terminals position the country as Europe's biodiesel import and blending hub. Municipal bus fleet tenders in Amsterdam and The Hague embed lifecycle carbon accounting and third-party sustainability certification requirements. The RED III framework's greenhouse gas reduction thresholds accelerate certified offtake contracting from Northwest European suppliers.
Singapore
Neste Corporation's facility exemplifies large-scale used cooking oil procurement from Southeast Asian food service networks. The Maritime and Port Authority's bunker fuel regulations open offtake channels for biodiesel-biogenic fuel oil blends in coastal shipping. Jurong Island's integrated refining cluster supports hydroprocessing investments for renewable diesel with superior cold-flow properties.
Brazil
Soybean crushing infrastructure in Mato Grosso and Paraná supplies feedstock for domestic biodiesel production meeting national blending mandates. The National Petroleum Agency enforces progressive biodiesel content requirements in diesel sold at retail stations. São Paulo's industrial diesel consumers absorb lower-specification biodiesel for captive power generation and heavy transport applications.
Biodiesel Market Vendor Landscape
The competitive structure tilts toward integrated agribusiness conglomerates with captive feedstock supply and downstream refining assets. Tiered positioning separates premium hydrogenation-derived renewable diesel producers from commodity transesterification operators. Three archetypes dominate: oilseed processors with biorefinery integration, standalone renewable fuel specialists, and integrated petroleum refiners diversifying into biofuels. Capacity expansion and strategic partnerships constitute the dominant competitive moves, with players securing long-term feedstock offtake agreements and pipeline injection slots.
Within the integrated agribusiness tier, Archer Daniels Midland Company and Cargill, Incorporated represent North American supply anchors through extensive oilseed processing networks. Neste Corporation exemplifies the premium renewable diesel specialist archetype with proprietary refining platforms. Renewable Energy Group occupies a position among distributed production specialists converting diverse feedstocks into ASTM D6751-compliant fuel.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| Neste Corporation |
| Cargill, Incorporated |
| Renewable Energy Group |
| Wilmar International Limited |
| Bunge Limited |
| Valero Energy Corporation |
| Louis Dreyfus Company |
| FutureFuel Corporation |
| Others |
Supply Flow & Price Mechanics
Rapeseed oil futures on the Euronext exchange cascade through biodiesel value chains into three distinct pricing tiers, with feedstock cost pass-through mechanics compressing blender margins when agricultural commodity cycles spike and premium hydrogenation-derived renewable diesel commanding cold-flow performance premiums in Nordic markets.
Pricing Analysis
Cold-flow operability metrics anchor value-based pricing in biodiesel procurement, with EN 14214 winter-grade certification and ASTM D975 drop-in compatibility driving price differentiation between hydrogenation-derived renewable diesel and conventional transesterification output. Price erosion runs through commodity biodiesel segments as soybean oil supply fluctuations from Brazilian harvests transmit volatility into US Midwest blender economics. Fleet operators in Germany and the Netherlands exhibit lowest price sensitivity due to mandated carbon intensity compliance requirements, while industrial boiler fuel buyers in Brazil absorb greatest price elasticity.
Supply Chain Analysis
Regional distribution centers in Rotterdam, Houston-Galveston, and Singapore anchor hub-and-spoke patterns for biodiesel terminal rack injection, with bulk storage capacity concentrating in port zones with pipeline connectivity to inland compression-ignition fleet depots. Feedstock procurement draws from soybean crushing corridors in Iowa and Illinois, rapeseed processing clusters in Lower Saxony, and used cooking oil aggregation networks across Southeast Asian food service sectors. Single-source vulnerability concentrates in hydrogenation catalyst supply chains tethered to specialty chemical producers. Distribution runs through long-term offtake contracts linking biorefineries to obligated parties under EPA Renewable Fuel Standard and EU RED III frameworks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock cost volatility and hydrogenation capacity concentration are forcing consolidation among transesterification-only operators lacking multi-feedstock flexibility or downstream integration.
For Market Incumbents: Anchor market position through backward integration into used cooking oil aggregation networks and rendering infrastructure, securing captive supply chains that insulate margin structures from agricultural commodity swings. Neste Corporation's Singapore procurement model demonstrates how food service waste stream control defends against virgin vegetable oil price spikes. Prioritize hydroprocessing asset investments in German and Nordic markets where cold-flow premiums justify capital deployment. For New Entrants and Emerging Players: The premium-to-economy price spread in Indian transport diesel offers white-space penetration for ASTM D6751-compliant imports, with national biofuel blending targets creating certified offtake demand absent domestic hydrogenation capacity. Marine bunker fuel applications represent a second penetrable segment, with International Maritime Organization sulfur regulations opening coastal shipping channels for biodiesel-biogenic fuel oil blends. Pursue digital feedstock traceability certification as a go-to-market differentiator for European fuel retailer sustainability requirements. For Investors and Strategic Acquirers: The window for entry favors integrated agribusiness conglomerates with oilseed crushing infrastructure and downstream biorefinery assets, as standalone renewable fuel specialists face margin compression from feedstock volatility. Mid-cap transesterification operators with distributed production footprints and multi-feedstock capabilities present acquisition targets for capacity rollup. Watch EPA renewable volume obligation tightening timelines and EU F-Gas Regulation enforcement intensity as inflection indicators for advanced biofuel credit pricing dynamics.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Aggregation Network Expansion | Used cooking oil procurement from Southeast Asian food service chains secures low-ILUC risk supply for EU RED III compliance. |
| Hydroprocessing Capacity Buildout | Cloud-point performance below -20°C unlocks Nordic winter operability premiums and ASTM D975 drop-in fuel positioning. |
| Long-term Offtake Contracting | EPA Renewable Fuel Standard obligated parties secure renewable volume obligation compliance through domestic biorefinery partnerships. |
| Third-party Sustainability Certification | ISCC and RSB verification meets German municipal bus fleet tender requirements embedding lifecycle carbon accounting. |
| Digital Supply Chain Traceability | Blockchain-enabled feedstock verification addresses emerging European fuel retailer sustainability audit protocols. |
Methodological Framework
USDA crop production reports, EIA biofuel statistics, and EU RED III regulatory filings formed the secondary backbone, supplemented by primary interviews with biorefinery operations managers, fuel distributor procurement leads, and fleet sustainability officers across German, Dutch, and US Midwest transport operators. Bottom-up capacity modeling triangulated against top-down demand projections from national biofuel quota enforcement timelines.
Historical trendline analysis of rapeseed and soybean oil price volatility informed feedstock cost assumptions across the projection horizon, with segmentation modeling spanning production method, feedstock category, end-use application, and geographic regulatory cluster. CAGRs derived from capacity expansion announcements and mandated blending obligation trajectories incorporated hydrogenation technology penetration rates and used cooking oil aggregation network buildout timelines.
Inputs from EPA renewable volume obligation databases and EU F-Gas Regulation implementation schedules were available through the study window; gaps in real-time feedstock spot pricing transparency introduce uncertainty bands around blender margin projections. Decision-makers should treat outputs as directional within the stated assumption set.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Europe Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Biofuels Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Europe Biofuel Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Latin America Biodiesel Market
Biofuels
Second Generation Biofuels Market
Biofuels
Brazil Biofuel Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Bioethanol Market
Biofuels
Biofuel Ethanol Market