
 GCC Algae Biofuel Prospects Market | 2026-2036
GCC Algae Biofuel Prospects Market Size, Share, and Industry Trends Forecast 2026-2036
GCC Algae Biofuel Prospects Market Foresight
Modular biorefinery configurations are expanding buyer choice across the GCC algae biofuel sector. Saudi Aramco leverages integrated pilot facilities to test photobioreactor scalability at scale. Masdar anchors its position through concentrated solar-powered algae cultivation systems in Abu Dhabi. Qeshm Microalgae Biorefinery competes on geographic proximity to maritime offtake corridors in the Persian Gulf.
GCC algae biofuel prospects encompass the cultivation, processing, and conversion of microalgae and cyanobacteria biomass into liquid transportation fuels and industrial hydrocarbons, typically requiring lipid content exceeding 20 percent dry weight and transesterification or hydrothermal liquefaction pathways. Photobioreactor technology dominates current capacity installations due to controlled contamination risk and higher cell density yields, while open pond systems retain cost advantages for bulk feedstock pre-cultivation. Transportation fuels command the largest application share given aviation and maritime decarbonization mandates, though power generation applications are gaining traction through co-firing trials with existing natural gas infrastructure.
The UAE's Ministry of Energy and Infrastructure, Saudi Arabia's Ministry of Energy, and Qatar's General Electricity and Water Corporation shape demand through renewable portfolio standards and green hydrogen co-production frameworks that privilege algae as a carbon feedstock. SAMR and SASO standards additionally govern fuel quality specifications and biorefinery emissions thresholds for regional market access. Stakeholders must monitor how Gulf state NOCs allocate capital between direct algae investments and third-party offtake agreements as feedstock security becomes the decisive competitive variable.
Market Dynamics
Photobioreactor deployment decisions across the Gulf are compressing project timelines as Saudi Aramco and Masdar race to secure feedstock offtake before aviation mandates harden. Capital allocation now hinges on lipid yield consistency rather than cultivation scale alone.
Growth Catalysts
- IATA Carbon Offset and Reduction Scheme:Aviation operators in the UAE and Saudi Arabia face binding emissions protocols that privilege algae-derived sustainable aviation fuel over conventional offsets.
- Photobioreactor lipid extraction:Controlled contamination environments achieve dry-weight lipid content exceeding 20 percent, meeting transesterification thresholds without open-pond dilution risk.
- Abu Dhabi concentrated solar integration:Masdar's solar-powered cultivation systems reduce energy input costs for thermal regulation in desert climates.
Market Restraints
- Nutrient input cost volatility:Nitrogen and phosphorus prices fluctuate with phosphate rock export restrictions from Moroccan and Chinese suppliers.
- Single-source equipment dependency:Photobioreactor glass tubing and LED spectrum arrays concentrate supply risk with German and Dutch precision manufacturers.
- Hydrothermal liquefaction capex barriers:Supercritical water processing requires pressure vessels rated above 22 megapascals, limiting fabricator options.
Strategic Opportunities
- Qatar maritime bunkering corridor:Port infrastructure at Ras Laffan offers geographic proximity to heavy fuel oil substitution demand from container shipping lines.
- Green hydrogen co-production frameworks:Algae biomass serves as carbon feedstock for electrolyzer integration under Saudi Vision 2030 industrial cluster mandates.
- Co-firing with natural gas turbines:Power generation applications gain traction through pilot trials with existing GCC combined-cycle infrastructure.
Industry Challenges
- Algae strain certification timelines:SAMR and SASO fuel quality specifications require multi-year stability testing for novel cyanobacteria variants.
- Photobioreactor scaling talent scarcity:Process engineers with hybrid expertise in both biological cultivation and chemical engineering command premium compensation.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | GCC Algae Biofuel Prospects Market |
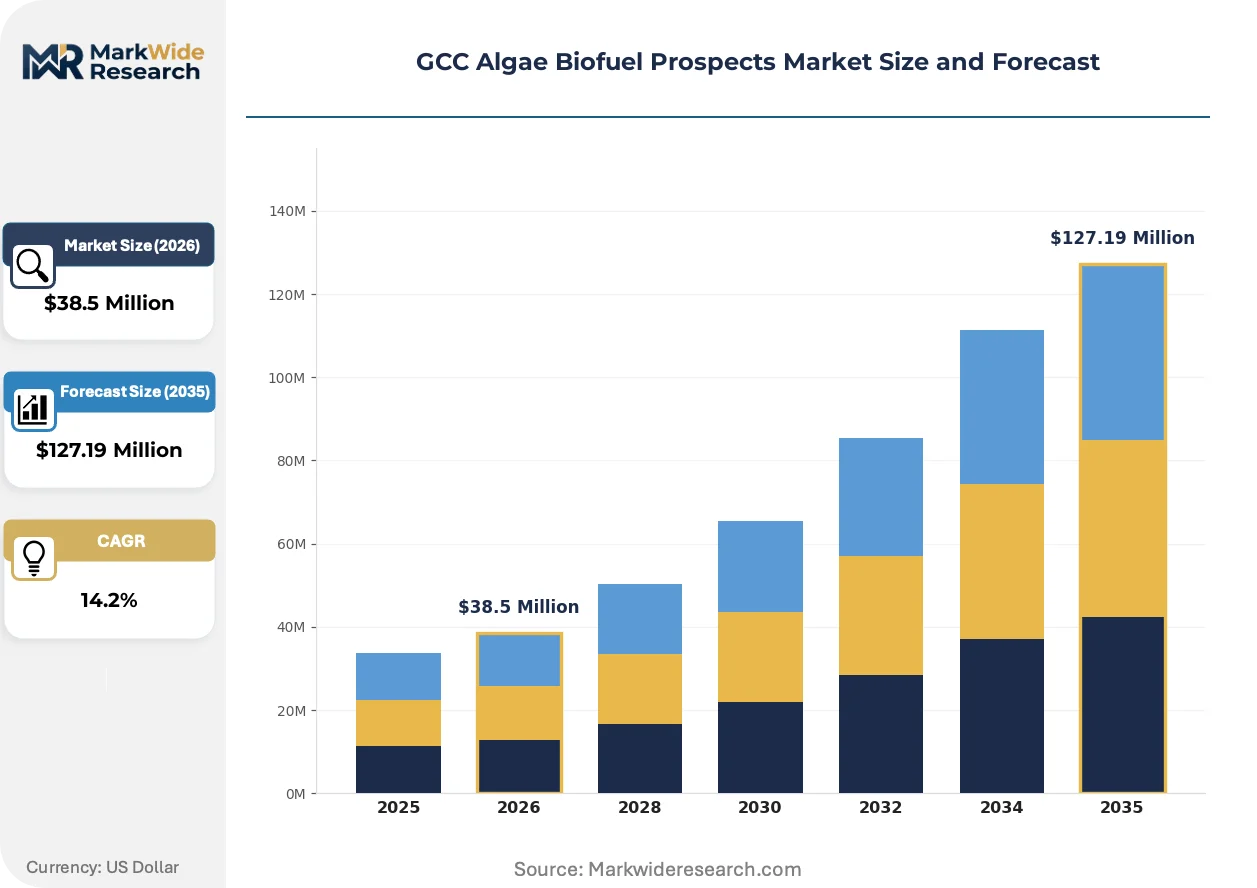
| Market Size in 2026 | $38.5 Million |
| Market Size in 2035 | $127.19 Million |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Microalgae, Macroalgae, Cyanobacteria, Mixed Cultures Technology: Photobioreactors, Open Ponds, Hybrid Systems, Closed Loop Systems Application: Transportation Fuels, Power Generation, Heating Solutions, Industrial Lubricants End User: Energy Producers, Chemical Manufacturers, Aviation Operators, Maritime Firms |
| Companies Covered | Saudi Aramco, TotalEnergies, Shell plc, ExxonMobil, Chevron, QatarEnergy, Masdar, Algenol Biotech, Qeshm Microalgae Biorefinery, Others |
| Regions Covered | GCC: Saudi Arabia, UAE, Qatar, Kuwait, Oman, Bahrain |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
GCC Algae Biofuel Prospects Market Shifts & Advancements
Algae biofuel production in the Gulf is pivoting from cultivation-centric competition to downstream conversion efficiency as lipid extraction technologies mature. Integration with existing petrochemical infrastructure now determines project viability more than biomass yield metrics.
Hydrothermal liquefaction is converging with supercritical CO2 extraction pathways to produce drop-in hydrocarbons compatible with existing refinery hydrotreaters. Saudi Aramco's pilot facilities are testing combined processing trains that accept variable lipid-content feedstock. This convergence is compressing the capital cost gap between algae-derived and fossil-derived middle distillates.
Saudi Arabia's Ministry of Energy and SASO have issued draft biofuel blending mandates that specify maximum nitrogen and oxygen content thresholds for aviation applications. Industrial consequence includes mandatory pre-treatment investments for producers using wet extraction methods. Maritime offtake corridors in the Persian Gulf are responding by demanding certificate-of-origin documentation aligned with SAMR traceability standards.
Long-term offtake contracting is displacing spot procurement for algae-derived sustainable aviation fuel as Emirates and Etihad seek supply security. Direct negotiations between state-backed energy ventures and airline procurement departments are replacing intermediary trading houses. This pattern is most visible in Abu Dhabi, where Masdar and Etihad have structured 10-year supply agreements with price collars tied to fossil jet fuel benchmarks.
GCC Algae Biofuel Prospects Market Segmentation
Segmentation in the GCC algae biofuel market reveals how cultivation methods, conversion pathways, and offtake contracts interlock to determine project economics. Understanding these divisions exposes where capital concentrates and which technology bets carry regulatory backing.
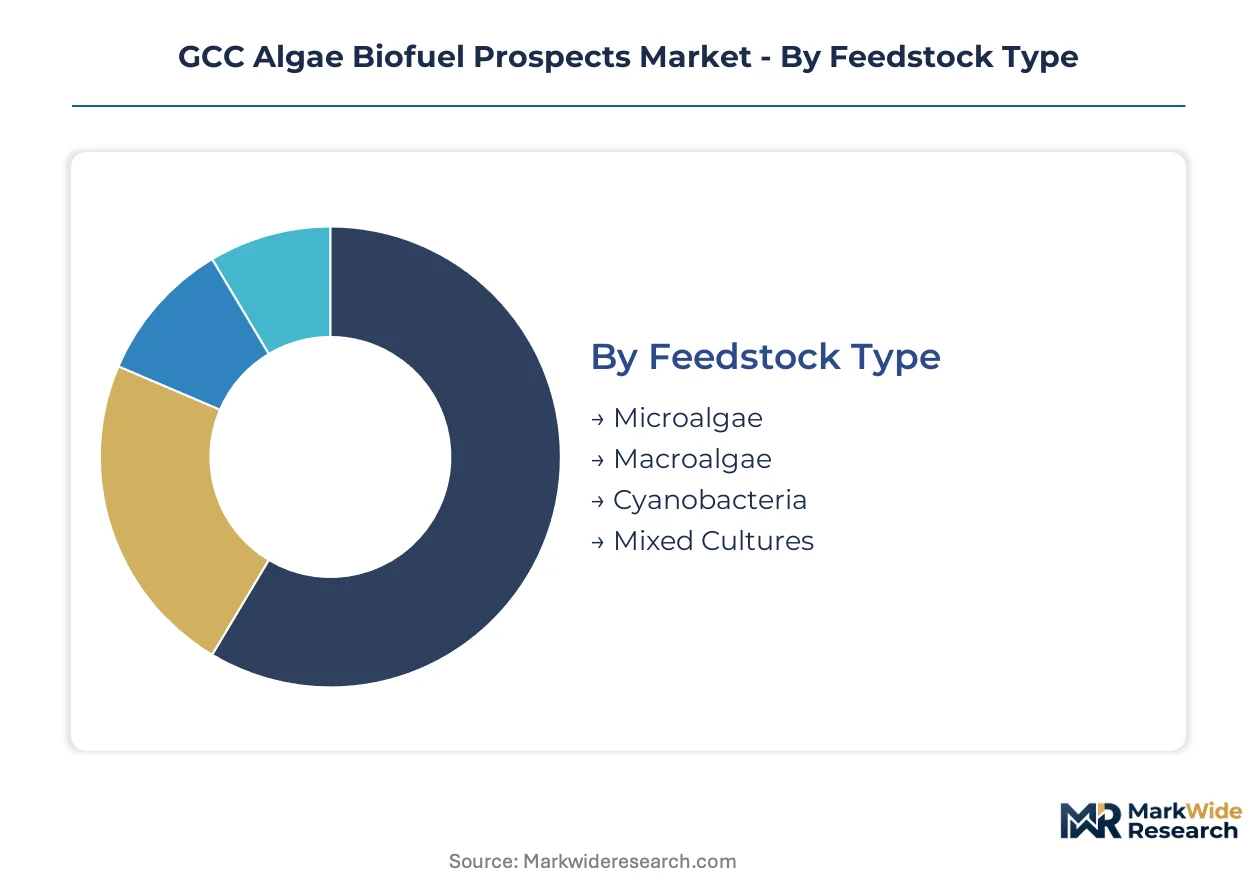
Feedstock Type:
Feedstock selection dictates lipid extraction efficiency and downstream compatibility with existing Gulf refinery infrastructure.
- Microalgae:Chlorella and Nannochloropsis strains achieve dry-weight lipid content exceeding 20 percent under controlled photobioreactor conditions. UAE aviation operators prioritize microalgae-derived sustainable aviation fuel for IATA compliance pathways.
- Macroalgae:Seaweed biomass offers saltwater cultivation advantages along the UAE and Saudi Arabian coastlines, though lower lipid yields require hydrothermal liquefaction rather than transesterification. Demand concentrates in maritime bunkering applications at Ras Laffan and Jebel Ali.
- Cyanobacteria:Engineered Synechocystis variants enable direct solar-to-fuel conversion without biomass harvesting stages.
- Mixed Cultures:Polyculture systems reduce contamination risk in open pond pre-cultivation phases at Qeshm facilities.
Microalgae leads on scale; cyanobacteria leads on momentum.
Technology:
Capital deployment patterns across the Gulf favor controlled environments over bulk cultivation, with project timelines compressing as feedstock security becomes decisive.
- Photobioreactors:Tubular and flat-panel configurations dominate Saudi Aramco and Masdar pilot investments, achieving cell densities ten times higher than open ponds while eliminating invasive species contamination. Abu Dhabi's concentrated solar integration reduces thermal regulation energy costs for these systems.
- Open Ponds:Raceway designs retain lowest capital cost per hectare for feedstock pre-cultivation, though evaporative water loss in desert climates requires continuous makeup from desalination sources.
- Hybrid Systems:Open pond bulk cultivation followed by photobioreactor finishing stages balances yield consistency against capital efficiency.
- Closed Loop Systems:Fully contained configurations with nutrient recycling address SAMR wastewater discharge thresholds for biorefinery permitting.
Photobioreactors command installed capacity; hybrid systems are climbing the fastest.
Application:
Application segmentation tracks how Gulf state energy mandates allocate decarbonization burden across transport, power, and industrial sectors.
- Transportation Fuels:Sustainable aviation fuel and marine diesel substitutes absorb the majority of current algae biofuel offtake, driven by Emirates and Etihad procurement commitments under IATA CORSIA protocols.
- Power Generation:Co-firing trials with natural gas combined-cycle turbines are gaining traction through Saudi Electricity Company pilot programs.
- Heating Solutions:Industrial process heat applications in Saudi petrochemical clusters utilize algae-derived fuel oil substitutes.
- Industrial Lubricants:High-value specialty products from algae wax esters serve precision manufacturing in UAE free zones.
Transportation fuels dominates contract volume; power generation shows steepest expansion trajectory.
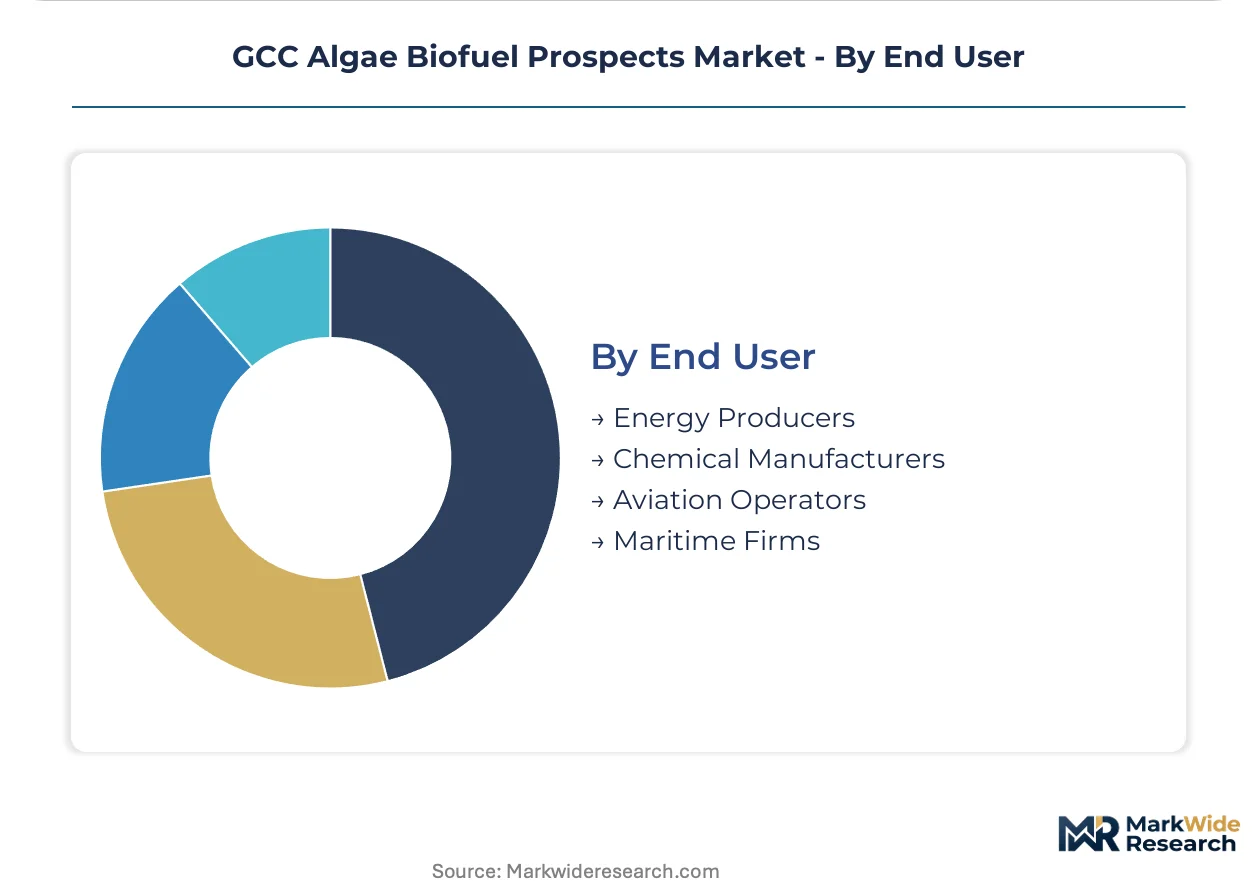
End User:
End user structure reflects how Gulf NOCs intermediate between algae producers and final offtake markets through integrated supply agreements.
- Energy Producers:State-backed ventures including Masdar and Saudi Aramco hold dominant positions as both cultivators and offtake aggregators, structuring ten-year supply agreements with price collars tied to fossil benchmarks.
- Chemical Manufacturers:SABIC and Borouge evaluate algae lipids as renewable feedstock for oleochemical production under Saudi Vision 2030 industrial cluster mandates.
- Aviation Operators:Emirates, Etihad, and Saudia negotiate direct procurement contracts bypassing intermediary trading houses.
- Maritime Firms:Container shipping lines at Jebel Ali and King Abdulaziz Port demand certificate-of-origin documentation aligned with SAMR traceability standards for heavy fuel oil substitution.
Energy producers anchor supply security; aviation operators are gaining share fastest.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
The GCC algae biofuel sector traces its commercial origins to Abu Dhabi's 2009 Masdar initiative, which established the region's first integrated photobioreactor pilot. State-backed energy ventures in the UAE and Saudi Arabia subsequently scaled cultivation infrastructure to serve aviation decarbonization mandates.
United Arab Emirates
Etihad Airways and Emirates have structured decade-long sustainable aviation fuel procurement agreements with Masdar. The country's Ministry of Energy and Infrastructure enforces renewable portfolio standards that privilege algae-derived feedstocks. Abu Dhabi's concentrated solar-powered cultivation clusters anchor production capacity.
Saudi Arabia
Saudi Aramco operates integrated pilot facilities testing photobioreactor scalability for aviation offtake. The Ministry of Energy and SASO have issued draft biofuel blending mandates specifying nitrogen and oxygen content thresholds. Industrial clusters in the Eastern Province host hydrothermal liquefaction trials.
Qatar
QatarEnergy evaluates algae biomass for maritime bunkering substitution at Ras Laffan port infrastructure. The General Electricity and Water Corporation shapes demand through green hydrogen co-production frameworks. Doha-based ventures target heavy fuel oil replacement for container shipping lines.
Oman
Oman's coastal geography supports macroalgae cultivation trials for lower-lipid feedstock applications. The national energy regulator promotes industrial diversification away from crude dependency. Salalah port infrastructure offers proximity to Indian Ocean maritime corridors.
Kuwait
Kuwait Petroleum Corporation assesses algae biofuel integration within existing refinery hydrotreater configurations. The Ministry of Electricity and Water pilots co-firing trials with natural gas combined-cycle turbines. Shuaiba industrial zone concentrates early-stage cultivation research.
GCC Algae Biofuel Prospects Market Competitive Landscape
The competitive structure tilts toward state-backed national oil companies with captive offtake agreements. Saudi Aramco and QatarEnergy leverage integrated energy infrastructure to compress project development timelines. Three archetypes dominate: NOC-affiliated cultivators, independent biorefinery specialists, and international oil company pilot ventures. Capacity expansion and strategic partnerships with aviation operators constitute the primary competitive moves.
Among state-affiliated ventures, Saudi Aramco exemplifies the NOC-integrated archetype through its photobioreactor pilot investments. Masdar occupies a parallel position in the UAE as a cultivator-aggregator structuring long-term supply security. International oil companies including Shell plc and TotalEnergies represent the pilot-venture tier, testing algae-derived hydrocarbon compatibility with existing refinery infrastructure.
| Leading Market Players |
|---|
| Saudi Aramco |
| TotalEnergies |
| Shell plc |
| ExxonMobil |
| Chevron |
| QatarEnergy |
| Masdar |
| Algenol Biotech |
| Qeshm Microalgae Biorefinery |
| Others |
Supply & Pricing Matrix
Captive upstream integration into photobioreactor manufacturing and nutrient recycling anchors both supply security and pricing power for state-backed energy ventures across the Gulf. This structural choice compresses input cost volatility while enabling long-term offtake contracting at price collars tied to fossil jet fuel benchmarks.
Pricing Analysis
Long-term contract-based offtake agreements dominate procurement patterns, with pricing stratifies across IATA CORSIA-certified premium tiers, standard compliance grades, and economy bulk volumes without certificate-of-origin documentation. Price differentiation rests on lipid yield consistency and SAMR traceability certification. Cost compression in economy-grade feedstock runs through open-pond cultivation competition. Aviation operators show lowest price sensitivity given regulatory compliance mandates, while maritime bunkering buyers exhibit highest elasticity.
Supply Chain Analysis
Freight costs for photobioreactor glass tubing and LED spectrum arrays from German and Dutch precision manufacturers concentrate supply risk in maritime corridors through Rotterdam and Hamburg. Production gravity centers on the UAE, Saudi Arabia, and Qatar, with feedstock cultivation drawing from Abu Dhabi concentrated solar clusters and Eastern Province industrial zones. Raw material dependencies include phosphate-based nutrients, desalinated water inputs, and supercritical pressure vessel steel. Single-source equipment vulnerability from European specialty fabricators threatens project timelines. Distribution runs through state-backed NOC aggregator networks directly to aviation and maritime offtake points.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
This market functions as a regulatory compounder where IATA CORSIA protocol tightening creates irreversible demand pull for certified sustainable aviation fuel.
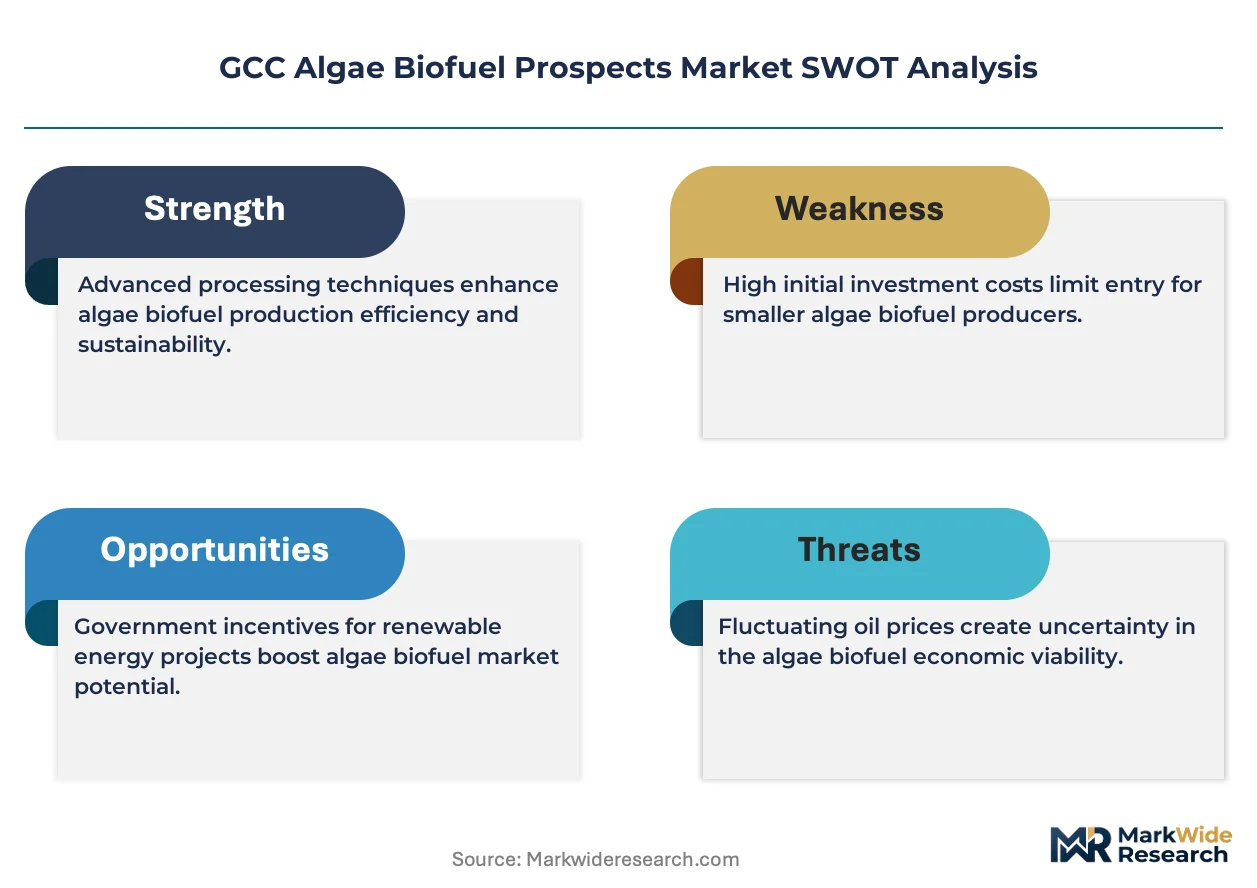
For Market Incumbents: Acquire stranded photobioreactor capacity in secondary Gulf locations to preempt emerging biorefinery specialists from securing feedstock position. Consolidation around nutrient recycling intellectual property addresses phosphate import dependency threatening margin stability. Direct airline procurement relationships bypass intermediary trading houses before spot markets mature. For New Entrants and Emerging Players: Premium-to-economy pricing gaps in maritime bunkering applications without aviation-grade certification requirements offer white-space entry. Qatar's Ras Laffan corridor presents the most penetrable geography given nascent algae-derived heavy fuel oil substitution. Co-location with existing desalination infrastructure reduces capital intensity versus greenfield photobioreactor deployment. For Investors and Strategic Acquirers: Roll-up economics work for hybrid-system technology specialists because project timelines compress as feedstock security becomes the decisive competitive variable. Five-to-ten year viability hinges on integration with existing petrochemical hydrotreater infrastructure rather than standalone biorefinery construction. Watch for Saudi Aramco and Masdar capital allocation shifts between direct cultivation investments and third-party offtake agreements as the inflection signal.| Strategic Initiative | Industry Significance |
|---|---|
| Photobioreactor Capacity Buildout | Masdar and Saudi Aramco pilot investments test scalability before aviation mandates harden. |
| Long-term Supply Agreement | Etihad and Emirates decade-long procurement contracts displace spot market development. |
| Backward Integration into Nutrient Recycling | Closed-loop systems address SAMR wastewater discharge thresholds for biorefinery permitting. |
| Green Certification Program | IATA CORSIA compliance pathways privilege algae-derived sustainable aviation fuel over conventional offsets. |
| Technology Licensing | Hydrothermal liquefaction convergence with supercritical CO2 extraction reduces capital cost gaps with fossil distillates. |
Research Methodology
Multiple input streams — structured interviews with biorefinery process engineers, aviation procurement directors, and maritime fuel supply specialists; regulatory filing analysis from SAMR and SASO; and customs trade data on photobioreactor equipment imports — were reconciled through bottom-up cultivation capacity modeling and top-down fuel demand projection. Secondary validation drew from IATA emissions protocol documentation, Saudi Vision 2030 industrial cluster mandates, and UAE Ministry of Energy renewable portfolio standards.
Historical capacity deployment patterns were cross-referenced against expert panel assessments of lipid extraction technology maturation across the projection horizon. Segmentation dimensions modeled include feedstock type, cultivation technology configuration, conversion pathway, application sector, and end-user archetype. CAGRs were derived from supply-demand balance analysis incorporating aviation mandate phase-in schedules and maritime bunkering substitution elasticities. Industry-specific inputs encompass photobioreactor yield consistency data and hydrothermal liquefaction capex benchmarks.
Caveats apply where phosphate export restrictions from Moroccan and Chinese suppliers or photobioreactor scaling talent scarcity could materially shift the outlook. Forecasts reflect assumptions about regulatory enforcement timelines and aviation operator procurement commitment durability. Stakeholders should weight assumptions against their own operating context.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Europe Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Global Advanced Biofuel Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Biodiesel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
United States Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Second Generation Biofuels Market
Biofuels
Latin America Biodiesel Market
Biofuels
Biofuels Market
Biofuels
Brazil Biofuel Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Bioethanol Market
Biofuels
Europe Advanced Biofuel Market