
 Europe Advanced Biofuel Market | 2026-2036
Europe Advanced Biofuel Market Size, Share, and Industry Trends Forecast 2026-2036
Europe Advanced Biofuel Market Foresight
Waste oils are broadening feedstock economics for European advanced biofuel producers, displacing virgin vegetable oil dependence and improving lifecycle carbon scores. Neste Oyj leverages its Rotterdam refinery to anchor renewable diesel supply across Northwest Europe. TotalEnergies SE sustains integrated biorefinery investments in France and Belgium. Verbio SE specializes in agricultural residue-to-ethanol pathways, occupying a distinct position in Central European supply chains.
Advanced biofuels comprise liquid transportation fuels produced from non-food biomass feedstocks through thermochemical or biochemical conversion, meeting strict sustainability criteria under EU legislation with greenhouse gas emission reductions of at least 65% versus fossil comparators. These fuels serve hard-to-electrify sectors including aviation, maritime shipping, and heavy-duty road transport where energy density requirements exclude battery alternatives. Biodiesel and renewable hydrocarbons lead current European production volumes, reflecting mature transesterification and hydrotreatment infrastructure. Fermentation-based ethanol from agricultural residues is expanding fastest, though hydrothermal liquefaction of algae feedstocks holds concentrated R&D investment and future margin potential.
The EU Green Deal, ReFuelEU Aviation regulation, and Renewable Energy Directive sustainability criteria collectively mandate escalating blending shares and enforce strict land-use change protections that filter market access. ECHA administers REACH compliance for novel conversion catalysts and process chemicals, while national regulators in Germany, France, and the Netherlands implement transposed monitoring and verification systems. Stakeholders must track feedstock certification bottlenecks and policy harmonization gaps between member state incentive schemes as the decisive variables shaping competitive positioning.
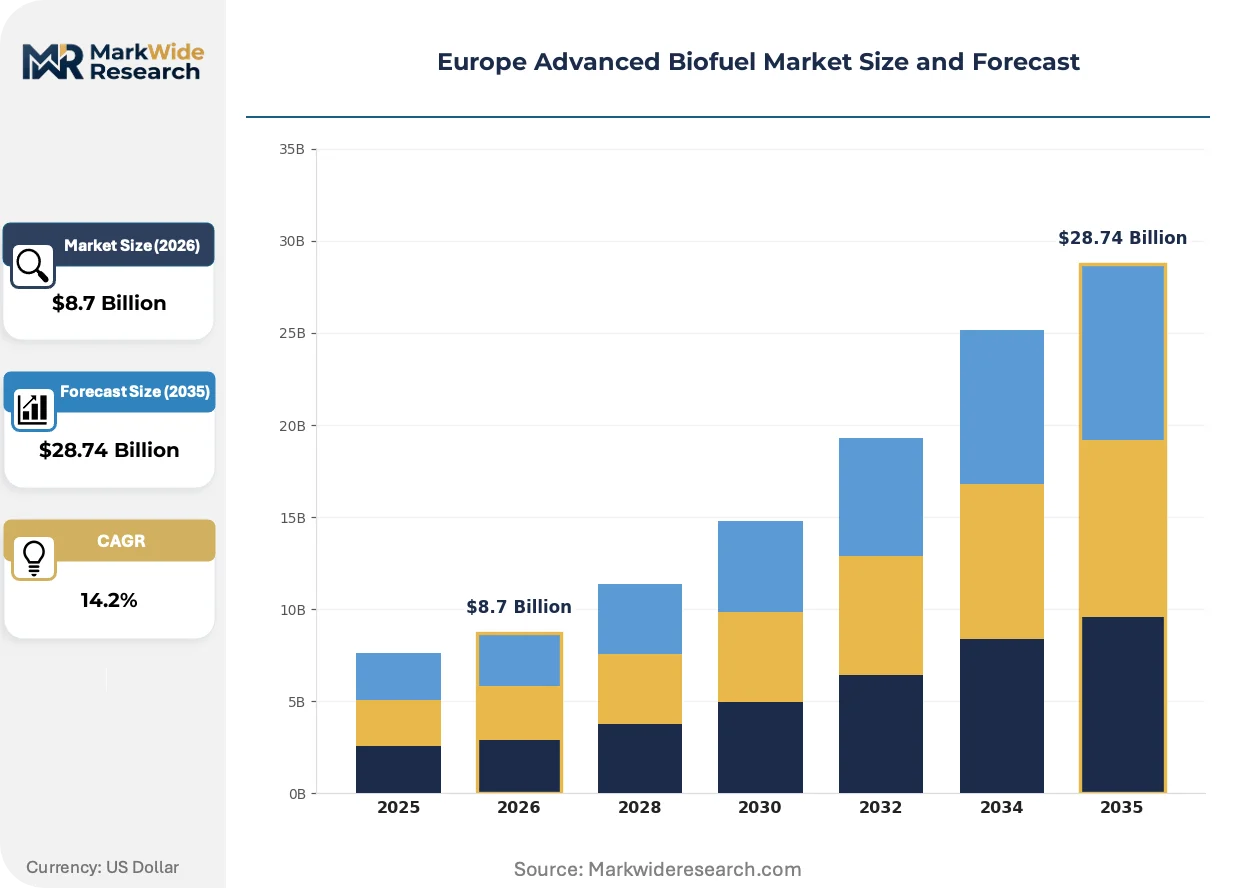
Market Dynamics
ReFuelEU Aviation mandates are compressing offtake timelines for European carriers, forcing fuel buyers to secure certified sustainable aviation fuel volumes ahead of infrastructure readiness. This regulatory pull is restructuring procurement relationships between airlines, refiners, and feedstock aggregators across Northwest Europe.
Growth Catalysts
- EU Green Deal blending obligations:Escalating renewable energy targets for transport create guaranteed offtake channels for advanced biofuel producers meeting lifecycle carbon thresholds.
- Waste oil feedstock economics:Used cooking oil and animal fat supply chains are displacing virgin vegetable oil dependence, improving margins and sustainability scores for hydrotreatment pathways.
- Aviation sector electrification limits:Battery energy density constraints in long-haul flight ensure liquid hydrocarbon demand persists, concentrating buyer investment in drop-in sustainable aviation fuel.
Market Restraints
- Feedstock certification bottlenecks:EU Renewable Energy Directive sustainability criteria create verification backlogs that delay market access for novel waste stream suppliers.
- Refining capacity concentration:Northwest European clusters in Rotterdam and Antwerp control hydrotreatment infrastructure, limiting geographic diversification of production.
- Fossil jet fuel price volatility:Crude oil benchmark swings compress renewable fuel premium capture, undermining project finance certainty for greenfield biorefineries.
Strategic Opportunities
- Central European agricultural residue pathways:Poland and Hungary hold underutilized straw and corn stover volumes suitable for cellulosic ethanol expansion.
- Maritime shipping fuel switching:The FuelEU Maritime regulation opens new demand for renewable diesel and methanol in Baltic and North Sea vessel operations.
- Power-to-liquid convergence:Electrofuel synthesis combining green hydrogen with captured carbon is creating synthetic kerosene supply options for aviation offtakers.
Industry Challenges
- Biochemical process engineering talent scarcity:Specialized expertise in anaerobic digestion and enzymatic hydrolysis remains concentrated among a limited pool of European research institutions.
- Multi-standard certification complexity:Producers must simultaneously satisfy ISCC EU, RSB, and national scheme requirements, extending compliance timelines.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Europe Advanced Biofuel Market |
| Market Size in 2026 | $8.7 Billion |
| Market Size in 2035 | $28.74 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodiesel, Ethanol, Butanol, Renewable Hydrocarbons Feedstock: Algae, Agricultural Residues, Waste Oils, Wood Chips Technology: Fermentation, Gasification, Transesterification, Hydrothermal Liquefaction End User: Transportation, Industrial, Power Generation, Residential Heating |
| Companies Covered | Neste Oyj, TotalEnergies SE, Shell plc, BP plc, Abengoa Bioenergy, Clariant Produkte GmbH, UPM-Kymmene Oyj, Verbio SE, Greenergy International Ltd, Others |
| Regions Covered | Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Europe Advanced Biofuel Market Shifts & Advancements
Digital feedstock traceability systems are penetrating European advanced biofuel supply chains, replacing paper-based chain-of-custody documentation with blockchain-verified provenance records from collection point to refinery gate.
Continuous hydrotreatment reactor technology is automating renewable diesel quality control, enabling real-time adjustment of cetane and cold-flow properties. Neste's Rotterdam facility has deployed sensor arrays that reduce laboratory testing cycles from hours to minutes. This automation is compressing batch rejection rates and enabling just-in-time blending for aviation offtakers with strict fuel specifications.
The EU's ReFuelEU Aviation regulation is mandating annual sustainable aviation fuel percentage increases, binding fuel suppliers to blending obligations that rise through 2035. Airlines face penalties for non-compliance, redirecting procurement budgets toward certified supply contracts. German and French flag carriers are responding by signing multi-year offtake agreements with biorefiners, locking in volumes before production capacity scales.
Consolidation among European waste oil collectors is reshaping feedstock access for independent refiners. Large aggregators are integrating backward into used cooking oil collection networks, bypassing traditional merchant suppliers. This concentration is most visible in the Netherlands, where port-adjacent collectors now supply Rotterdam refining clusters through dedicated pipeline connections rather than truck-based delivery.
Europe Advanced Biofuel Market Segmentation
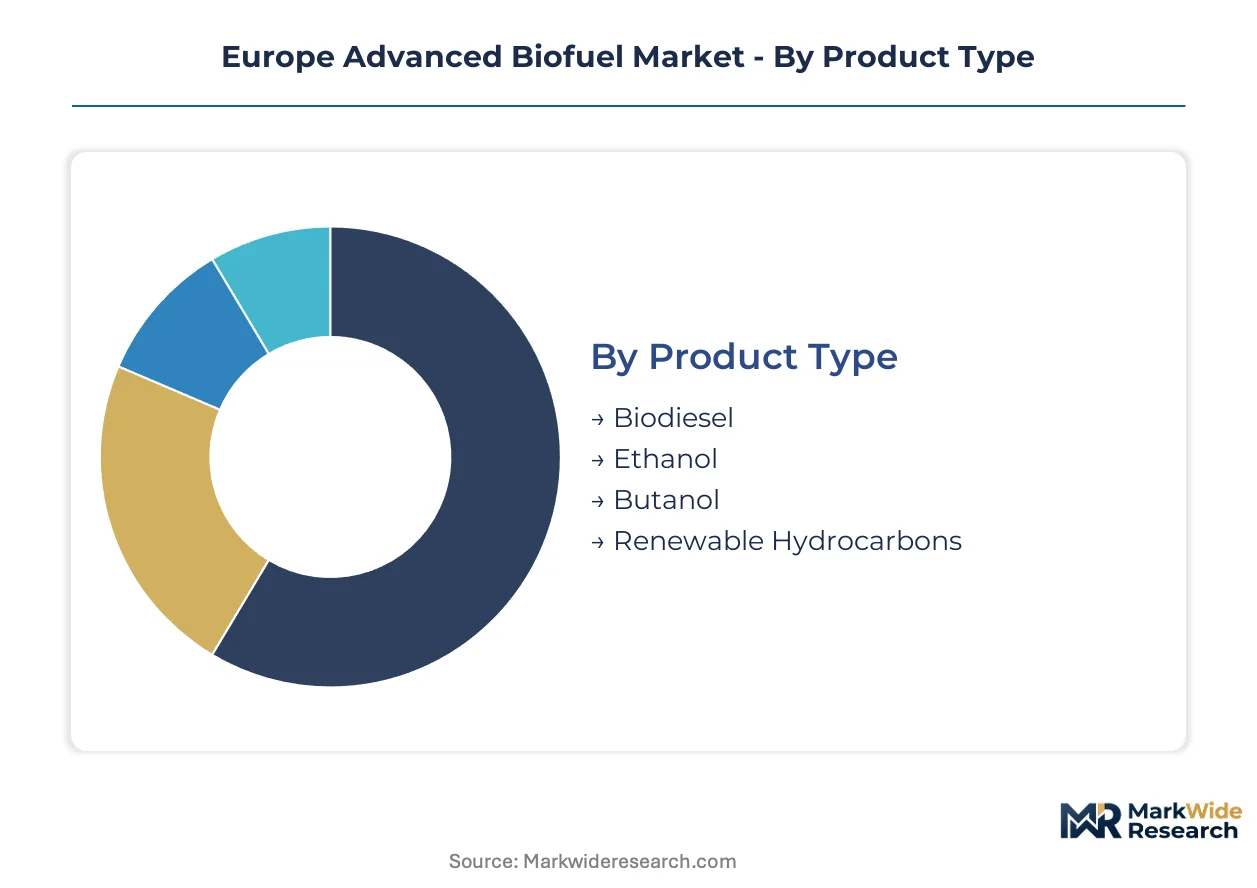
European advanced biofuel producers allocate capital across distinct pathways with divergent equipment requirements, feedstock security needs, and offtake contract structures. Segmentation reveals where refining investments concentrate and which conversion technologies attract project finance.
Product Type:
Capital intensity varies sharply across fuel categories, with hydrotreatment facilities demanding substantially higher upfront investment than fermentation infrastructure.
- Biodiesel:Fatty acid methyl esters produced through transesterification of waste oils or virgin vegetable oils, meeting EN 14214 specifications for diesel engine compatibility. Demand concentrates in German and French road freight fleets where blending mandates enforce offtake, though cold-flow property limitations restrict Nordic winter applications.
- Renewable Hydrocarbons:Drop-in paraffinic fuels manufactured via hydrotreatment and isomerization, achieving full fossil fuel substitution without engine modification. Aviation offtakers in the Netherlands and Belgium are contracting dedicated volumes ahead of ReFuelEU Aviation enforcement deadlines.
- Ethanol:Fermentation-derived alcohol from lignocellulosic or starch feedstocks, blended into gasoline pools at 10-85% concentrations. Verbio SE operates Central Europe's largest cellulosic ethanol capacity.
- Butanol:Higher alcohol with superior energy density versus ethanol, suitable for direct gasoline blending or chemical feedstock applications. Limited commercial scale in Europe pending cost-competitive production pathways.
Biodiesel absorbs the bulk of installed capacity; renewable hydrocarbons are expanding most quickly.
Feedstock:
Feedstock selection determines project location economics, with port-adjacent refiners optimizing for imported waste oil flows while inland producers target agricultural residue aggregation.
- Waste Oils:Used cooking oil and animal fat streams collected from food service and rendering operations, offering superior lifecycle carbon scores under EU RED criteria. Rotterdam and Antwerp refining clusters have secured dedicated pipeline supply from consolidated Dutch collectors.
- Agricultural Residues:Straw, corn stover, and cereal husks available across Poland, Hungary, and Romania with limited competing uses. Cellulosic ethanol developers face harvest seasonality and baling logistics costs that erode delivered feedstock economics.
- Wood Chips:Forest residue and sawmill byproducts suitable for gasification or pyrolysis pathways, concentrated in Nordic and Baltic timber processing regions.
- Algae:Photosynthetic microorganisms cultivated in photobioreactors or open ponds, offering theoretical yields exceeding terrestrial crops. European production remains at pilot scale with concentrated R&D investment in Portugal and Spain.
Waste oils dominate current supply contracts; agricultural residues are climbing the fastest as cellulosic conversion technology matures.
Technology:
Technology choice locks producers into specific feedstock-flexibility tradeoffs and operating cost structures that persist across facility lifecycles.
- Transesterification:Mature chemical process converting triglycerides to fatty acid esters using methanol and base catalysts, operational at lower pressure and temperature than hydrotreatment alternatives. Dominates European biodiesel infrastructure with established engineering contractor networks.
- Fermentation:Biochemical conversion of sugars to ethanol or butanol via microbial cultures, requiring pretreatment investment for lignocellulosic feedstocks. Central European producers are scaling enzymatic hydrolysis capacity for agricultural residue processing.
- Gasification:Thermochemical partial oxidation of solid biomass to syngas for Fischer-Tropsch synthesis or methanol production. Commercial deployment limited by tar formation challenges and high capital intensity.
- Hydrothermal Liquefaction:Wet biomass processing under subcritical water conditions to produce biocrude for upgrading, attracting development interest for algae and waste stream applications.
Transesterification retains the greatest installed base; fermentation is gaining share fastest through cellulosic ethanol capacity additions.
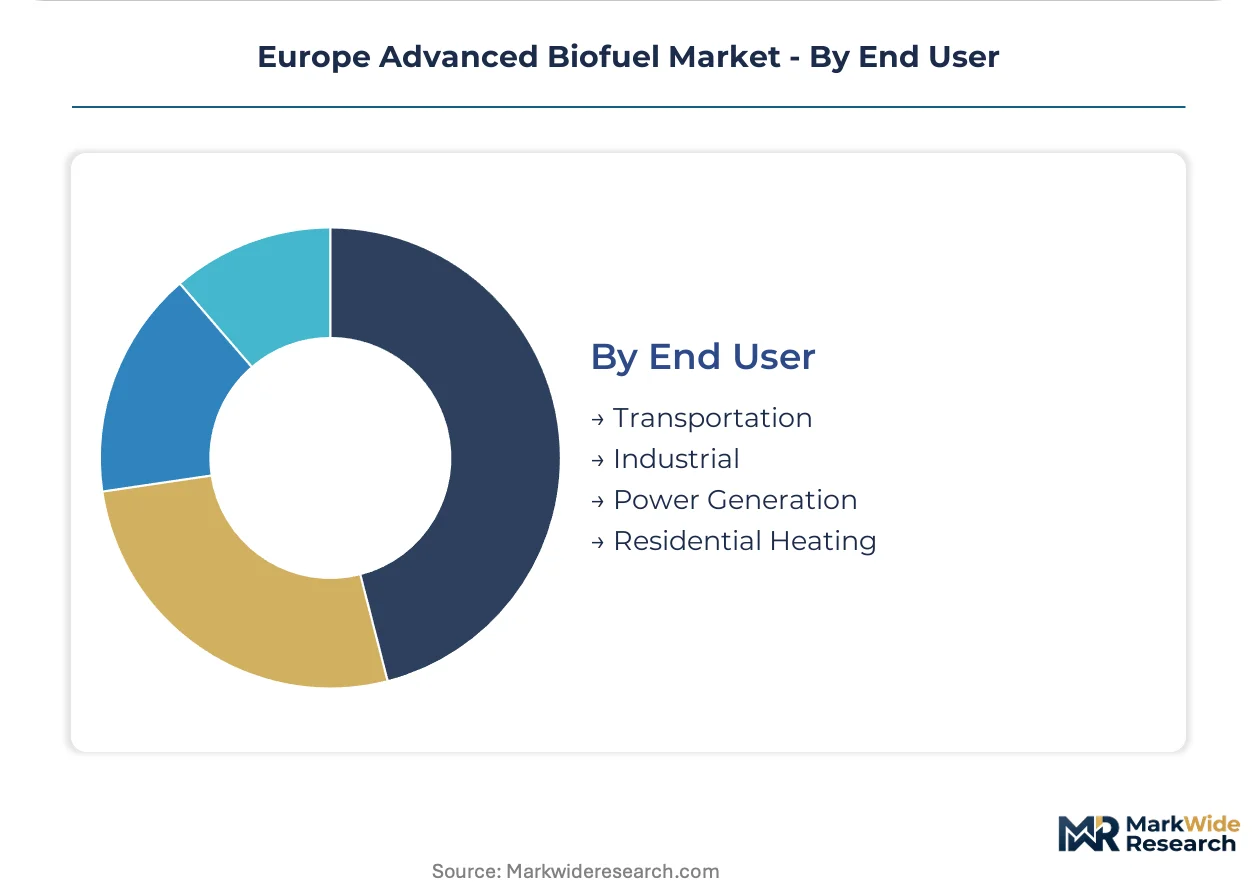
End User:
End-use segmentation separates markets with binding regulatory mandates from discretionary demand segments exposed to fossil fuel price competition.
- Transportation:Road, aviation, and maritime fuel applications governed by EU RED blending obligations and sector-specific regulations like ReFuelEU Aviation and FuelEU Maritime. German and French enforcement systems verify compliance through national registries.
- Industrial:Process heat and combined heat-and-power applications in cement, steel, and chemical sectors seeking renewable fuel substitution for coal and natural gas. Limited penetration outside carbon pricing exposed installations.
- Power Generation:Dedicated biomass electricity and district heating plants, primarily in Nordic countries with established forest residue supply chains.
- Residential Heating:Premium biofuel oil for building-scale boilers, concentrated in rural German and Austrian markets with limited natural gas grid access.
Transportation commands the dominant share of production allocation; industrial offtake is accelerating fastest under tightening EU ETS compliance costs.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Demand for advanced biofuels concentrates in Germany, France, and the Netherlands where refining infrastructure, policy incentives, and aviation sector procurement align. National enforcement systems under EU directives create divergent compliance timelines and certification burdens across member states.
Germany
Road freight electrification limits and aviation decarbonization targets drive German biofuel procurement. The Bundesamt für Wirtschaft und Ausfuhrkontrolle administers sustainability verification under transposed EU RED rules. Verbio SE operates cellulosic ethanol capacity in Saxony-Anhalt, supplying domestic blending pools.
France
French flag carriers are accelerating sustainable aviation fuel contracting ahead of ReFuelEU Aviation deadlines. TotalEnergies SE sustains integrated biorefinery investments in Normandy and Provence-Alpes-Côte d'Azur. La Mède biorefinery near Marseille anchors renewable diesel output for Mediterranean shipping routes.
Netherlands
Rotterdam's port-adjacent refining cluster controls Northwest European hydrotreatment capacity for renewable hydrocarbons. Neste Oyj leverages its Rotterdam facility to supply aviation offtakers across the region. Dutch waste oil collectors have consolidated backward into dedicated pipeline supply networks.
Belgium
Antwerp's refining infrastructure supports renewable diesel production for Benelux road and maritime applications. The Flemish environmental regulator implements feedstock traceability requirements stricter than federal minimums. Port of Antwerp-Bruges biorefinery investments target FuelEU Maritime compliance for North Sea vessel operators.
Poland
Underutilized agricultural residue volumes in Greater Poland and Lower Silesia attract cellulosic ethanol project development. National blending mandates for transport fuels exceed EU minimum renewable energy targets. Warsaw-based developers are securing straw and corn stover supply contracts from regional farming cooperatives.
Europe Advanced Biofuel Market Competitive Landscape
Capacity expansion dominates the current landscape as producers race to secure feedstock contracts and offtake agreements before regulatory deadlines tighten. The market structure consolidates around integrated energy majors with existing refining assets and specialized agricultural residue processors with distinct geographic positioning. Two strategic archetypes prevail: hydrotreatment operators leveraging port infrastructure for waste oil supply, and fermentation specialists controlling inland feedstock aggregation networks. M&A activity and strategic partnerships represent the dominant competitive moves, with waste oil collector consolidation reshaping feedstock access.
Among Nordic integrated operators, Neste Oyj and UPM-Kymmene Oyj represent the hydrotreatment archetype with Rotterdam-anchored supply chains. Verbio SE exemplifies the agricultural residue specialist model with Central European fermentation capacity. French energy majors including TotalEnergies SE occupy positions bridging both archetypes through diversified biorefinery portfolios.
| Leading Market Players |
|---|
| Neste Oyj |
| TotalEnergies SE |
| Shell plc |
| BP plc |
| Abengoa Bioenergy |
| Clariant Produkte GmbH |
| UPM-Kymmene Oyj |
| Verbio SE |
| Greenergy International Ltd |
| Others |
Supply & Pricing Matrix
Family-owned waste oil collectors rolled up through private equity backing now control Rotterdam pipeline access, tightening feedstock supply discipline and compressing spot market volatility for independent refiners lacking long-term offtake coverage.
Pricing Analysis
Volume contract premiums diverge sharply from spot market realizations as ReFuelEU Aviation mandates force airlines into multi-year offtake commitments. Certification tier under EU RED and ISCC EU schemes drives price differentiation between mass-balance and segregated supply chains. Pricing pressure stems from fossil jet fuel benchmark swings that erode renewable fuel premium capture. Road freight operators exhibit highest price sensitivity due to thin margins, while aviation buyers absorb premiums to secure compliance volumes.
Supply Chain Analysis
ISCC EU and RSB certification gating filters market access for novel waste stream suppliers, creating verification backlogs that delay production ramp. Supply concentrates in the Netherlands, Belgium, and Germany where port-adjacent refining clusters anchor hydrotreatment capacity. Raw material flows draw from used cooking oil networks, animal fat rendering operations, and agricultural residue aggregation in Poland and Hungary. Single-source vulnerability runs through consolidated Dutch waste oil collectors with dedicated pipeline connections. Distribution runs through barge and rail networks serving Northwest European blending terminals.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Feedstock certification bottlenecks and capital intensity barriers are forcing weaker independent refiners toward distressed exit, positioning integrated energy majors and specialized agricultural residue processors to consolidate market share.
For Market Incumbents: Deploy backward integration into waste oil collection networks to secure pipeline supply access and displace merchant feedstock dependence. Neste's Rotterdam facility demonstrates how captive supply infrastructure defends margin position against spot market volatility. TotalEnergies' integrated biorefinery model in France offers template for combining hydrotreatment scale with feedstock control. Counter the threat of power-to-liquid electrofuel convergence by locking aviation offtakers into long-term renewable hydrocarbon contracts ahead of synthetic kerosene scale-up. For New Entrants and Emerging Players: Capture undercontracted agricultural residue volumes in Poland and Hungary where Verbio SE has proven cellulosic ethanol economics. The cellulosic fermentation pathway remains penetrable for developers securing straw and corn stover supply contracts from regional farming cooperatives. Maritime shipping applications under FuelEU Maritime regulation offer secondary demand channel with less contested offtake than aviation. Lead with distributed production models co-located with feedstock sources to minimize logistics cost erosion. For Investors and Strategic Acquirers: Distressed-cycle entries favor agricultural residue specialists with secured feedstock contracts in Central Europe, where project development timelines lag regulatory mandate acceleration. Long-term viability hinges on technology diversification across thermochemical and biochemical pathways rather than single-conversion bets. Watch for inflection in power-to-liquid project financing commitments as signal of synthetic fuel competitive threat to conventional advanced biofuel margins.| Strategic Initiative | Industry Significance |
|---|---|
| Backward Integration into Feedstock Collection | Neste's Dutch pipeline networks demonstrate how captive waste oil supply secures margin against spot volatility. |
| Multi-pathway Technology Diversification | TotalEnergies combines hydrotreatment and fermentation assets to hedge against single-conversion technology risk. |
| Long-term Aviation Offtake Lock-in | German and French flag carriers are contracting dedicated renewable hydrocarbon volumes ahead of ReFuelEU deadlines. |
| Central European Residue Aggregation Scale-up | Verbio SE's straw supply contracts in Saxony-Anhalt validate inland feedstock control for cellulosic ethanol. |
| Maritime Fuel Certification Investment | Antwerp-Bruges biorefinery targeting FuelEU Maritime compliance opens Baltic and North Sea vessel demand. |
Research Methodology
EU RED implementation documents, ECHA REACH registration databases, and national biorefinery permit filings formed the secondary backbone for regulatory and capacity mapping. Primary interviews with biorefinery operations managers, aviation fuel procurement officers, waste oil collection network coordinators, and agricultural residue supply aggregators validated feedstock flow assumptions and offtake contract structures. Customs data on waste oil trade flows and national renewable energy registry disclosures provided volume triangulation against bottom-up facility capacity estimates.
Historical production trendlines across hydrotreatment and fermentation pathways informed baseline capacity utilization assumptions over the projection horizon. The analytical framework modeled segmentation across fuel type, feedstock category, conversion technology, and end-use sector with geographic disaggregation at member state level. CAGRs derived from policy-mandated blending obligation trajectories rather than demand elasticity assumptions. Forecast inputs incorporated ReFuelEU Aviation enforcement timelines and FuelEU Maritime regulatory phase-in schedules as demand drivers.
Forecast confidence holds firmest in the near-window; longer-horizon outcomes carry greater sensitivity to electrofuel cost reduction trajectories and waste oil feedstock competition from renewable diesel expansion in North America. Model assumptions reflect transposed EU RED sustainability criteria and national enforcement system implementation schedules. A model refresh is warranted upon material change in power-to-liquid project financing commitments or feedstock certification scheme harmonization between member states.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
United States Biodiesel Market
Biofuels
Brazil Biofuel Market
Biofuels
Europe Biofuel Market
Biofuels
Latin America Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Europe Biodiesel Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Biodiesel Market
Biofuels
Bioethanol Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Second Generation Biofuels Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Biofuels Market
Biofuels
Biofuel Ethanol Market
Biofuels
Global Advanced Biofuel Market