
 Clean Coal Technologies Sales Market | 2026-2036
Clean Coal Technologies Sales Market Size, Share, and Industry Trends Forecast 2026-2036
Clean Coal Technologies Sales Market Insights
Utility procurement concentration is hardening across state-backed generation portfolios in Asia. Siemens Energy AG anchors European technology exports through turbine-integrated gasification packages. Mitsubishi Electric dominates advanced control systems for supercritical boiler optimization. Shanghai Electric Group leverages domestic manufacturing scale to compete on deployment cost at multiple coastal facilities.
Clean coal technologies encompass combustion, gasification, and emissions-control systems engineered to reduce sulfur dioxide, nitrogen oxides, mercury, and carbon dioxide output from coal-based energy conversion. Integrated gasification combined cycle plants operate at thermal efficiencies exceeding 45 percent while enabling pre-combustion carbon capture. Supercritical technology leads installed capacity globally due to decades of operational validation at scale. Carbon capture utilization represents the fastest-growing product segment as policy frameworks attach compliance value to permanent sequestration. Steel production applications command premium pricing given the sector's limited fuel-switching alternatives and concentrated buyer base.
The US EPA enforces Mercury and Air Toxics Standards that mandate activated carbon injection or fabric filter upgrades at existing units. China's MEE administers ultra-low emissions requirements driving flue gas desulfurization retrofits at provincial power clusters. India's CEA mandates minimum thermal efficiency thresholds that favor supercritical and ultra-supercritical newbuilds over subcritical legacy assets. Stakeholders must monitor how carbon border adjustment mechanisms reshape competitiveness between regions with divergent retrofit timelines.
Market Dynamics
Ultra-supercritical boiler retrofits are compressing deployment timelines as China's MEE enforces ultra-low emissions standards across provincial power clusters. State-backed utilities now prioritize thermal efficiency thresholds over incremental flue-gas upgrades.
Growth Catalysts
- Ultra-Low Emissions Mandates:China's MEE requirements are accelerating flue gas desulfurization retrofits at coal-fired facilities in Shandong and Shanxi provinces. State Grid procurement now specifies integrated pollution control systems.
- Steel Sector Demand:Blast furnace operators in India and China face limited fuel-switching options, driving premium pricing for carbon capture utilization systems in metallurgical applications.
- Pre-Combustion Carbon Capture:Integrated gasification combined cycle technology enables hydrogen co-production while meeting thermal efficiency thresholds above 45 percent at newbuild power stations.
Market Restraints
- Capital Intensity:Ultra-supercritical turbine islands require specialized nickel-alloy forgings concentrated among Japanese and German metallurgical suppliers.
- Input Cost Volatility:Activated carbon injection systems face activated carbon price swings tied to coconut shell supply disruptions in Southeast Asian processing hubs.
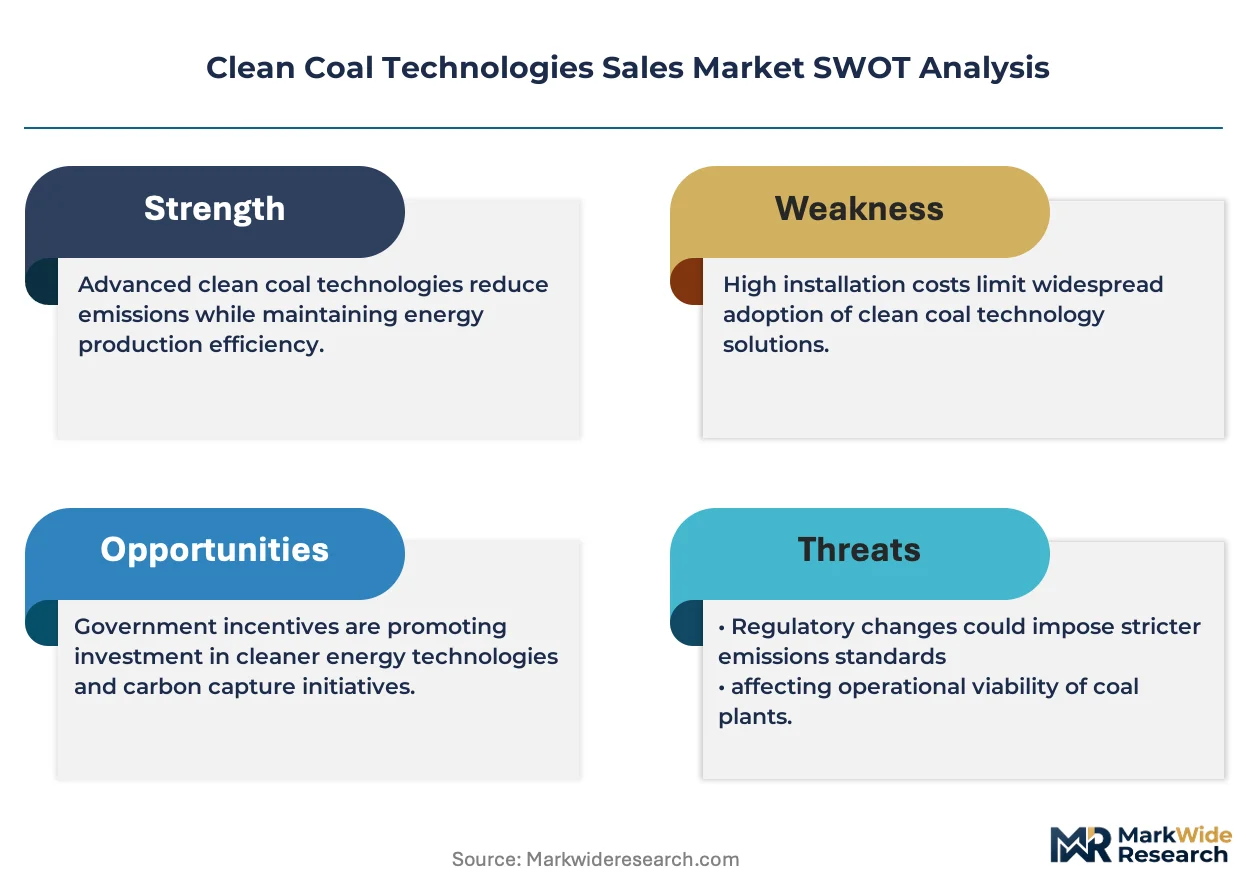
- Substitution Pressure:Utility-scale battery storage and renewable capacity additions are displacing baseload coal procurement in OECD power markets.
Strategic Opportunities
- Underpenetrated Retrofit Markets:Indonesia's state utility PLN operates subcritical assets averaging 35 percent thermal efficiency, creating white space for supercritical boiler conversions.
- Blue Hydrogen Production:Gasification systems with carbon capture utilization enable ammonia synthesis feedstock supply to fertilizer complexes in India's eastern coastal corridor.
- EU Carbon Border Adjustment:The mechanism creates compliance value for sequestration-equipped coal-derived products exported to European steel and chemical buyers.
Industry Challenges
- Welding Certification Bottlenecks:ASME Section IX qualified welders for supercritical pressure boundaries face 18-month training pipelines, constraining field deployment capacity.
- Legacy Control System Integration:Digital twin implementations for boiler optimization require protocol translation from 1990s-era distributed control architectures at existing plants.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Clean Coal Technologies Sales Market |
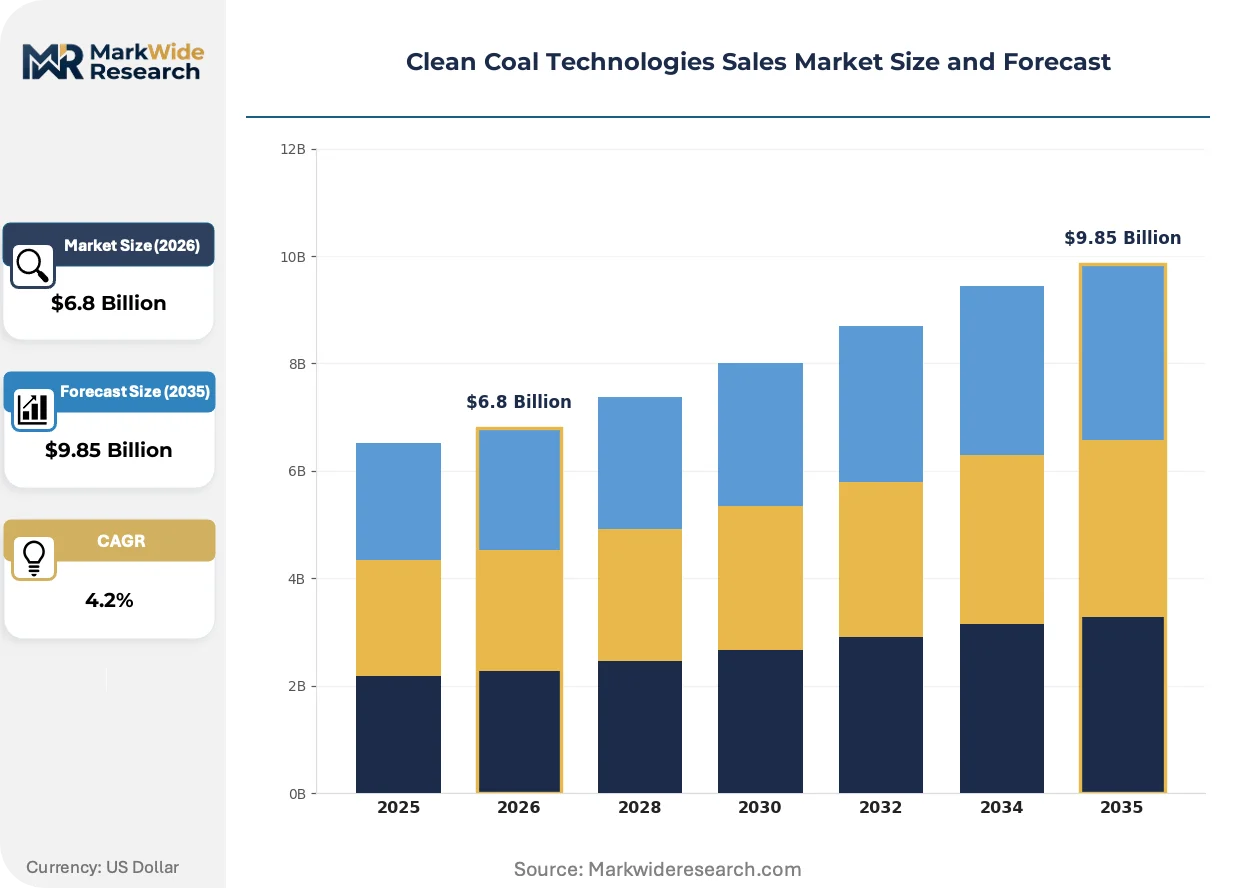
| Market Size in 2026 | $6.8 Billion |
| Market Size in 2035 | $9.85 Billion |
| CAGR (2026 – 2036) | 4.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Integrated Gasification Combined Cycle, Supercritical Technology, Circulating Fluidized Bed, Carbon Capture Utilization Application: Power Generation, Steel Production, Cement Manufacturing, Chemical Processing End User: Utilities, Manufacturing Plants, Industrial Facilities, Government Projects Deployment: Onshore, Offshore, Co-location, Remote |
| Companies Covered | General Electric Company, Siemens Energy AG, Royal Dutch Shell PLC, Mitsubishi Electric, Shanghai Electric Group, Alstom SA, KBR Inc., Harbin Electric Company Limited, Clean Coal Technologies Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Clean Coal Technologies Sales Market Trends and Innovations
Digital twin deployment for combustion optimization is compressing operational variance at coal-fired units. Three convergent forces are restructuring technology procurement patterns across generation portfolios.
Advanced process control software is consolidating operational decision-making at supercritical facilities. Siemens and Mitsubishi Electric systems now automate combustion tuning, feedwater regulation, and emissions balancing through machine learning models trained on decade-long operational datasets. Chinese utilities at coastal facilities are adopting these platforms fastest, compressing the competitive window for manual optimization services.
The US EPA Mercury and Air Toxics Standards are forcing activated carbon injection and fabric filter upgrades at legacy units built before 1990. Compliance deadlines cluster in 2025-2028, concentrating engineering procurement among specialized emissions control contractors. Midwestern power pools with aging subcritical assets face the steepest retrofit cost curves.
Steel producers are unbundling technology procurement from EPC contracts, directly sourcing gasification island packages and carbon capture modules. This disintermediation compresses margins for integrated project developers while opening direct sales channels for component specialists. The pattern is most visible in China's Shandong province, where private steel groups now issue separate tenders for syngas conditioning and CO2 compression trains.
Clean Coal Technologies Sales Market Segmentation
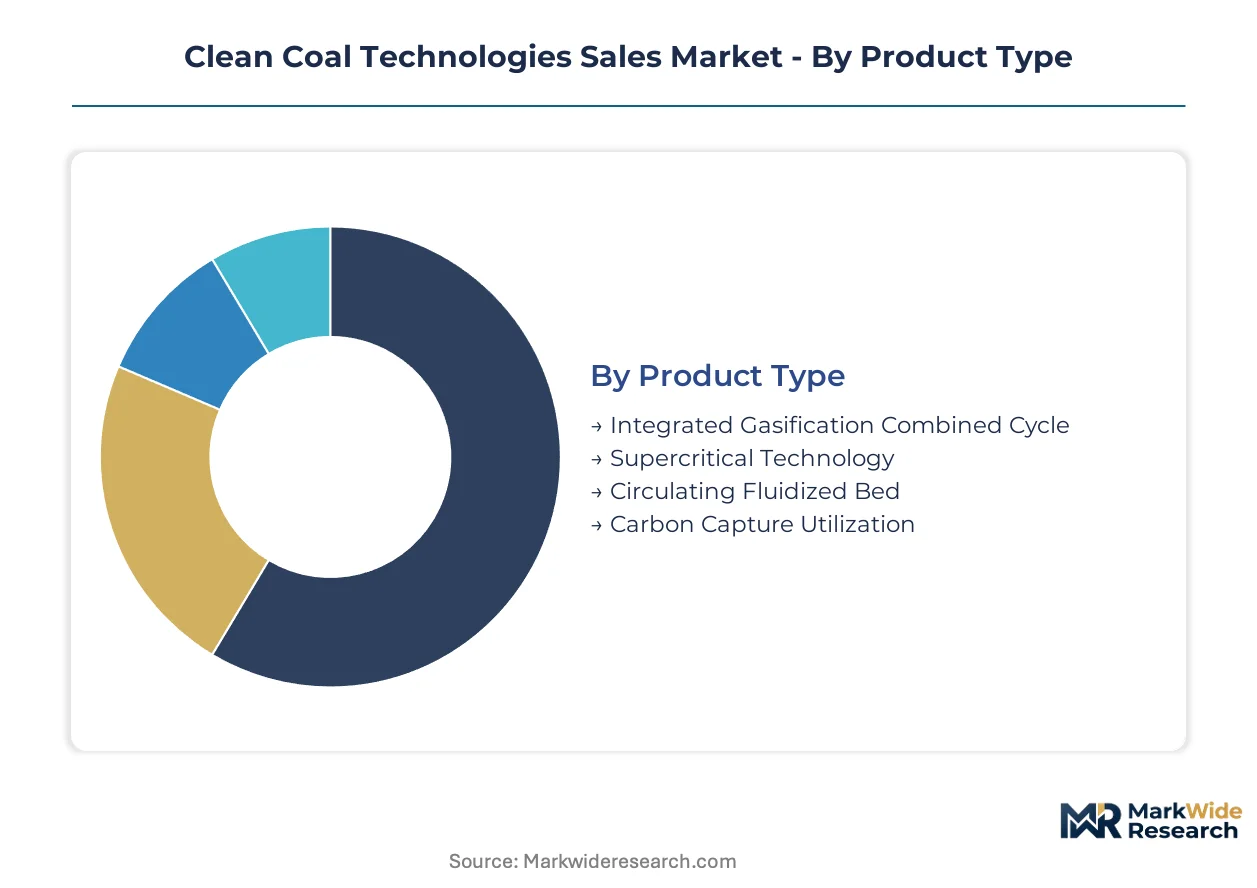
Technology procurement in clean coal diverges sharply between standardized utility-scale installations and customized industrial configurations. Segmentation reveals how deployment economics, regulatory pressure, and fuel flexibility requirements reshape vendor prioritization across generation and process heat applications.
Product Type:
Standardization dominates at the utility end of the spectrum, while industrial gasification demands bespoke engineering for feedstock variability and syngas conditioning.
- Integrated Gasification Combined Cycle:Systems combine coal gasification with combined-cycle turbines to achieve thermal efficiencies above 45 percent while enabling pre-combustion carbon capture. Procurement concentrates at state-backed utilities in China and India where baseload reliability requirements override renewable intermittency concerns.
- Supercritical Technology:Boiler-turbine configurations operate above water's critical pressure point, eliminating phase separation and boosting thermal efficiency into the 40-45 percent range. China's provincial power clusters under MEE ultra-low emissions mandates account for the bulk of current retrofit demand.
- Circulating Fluidized Bed:Combustion technology suited for low-grade coal and biomass co-firing with inherent sulfur capture capability.
- Carbon Capture Utilization:Post-combustion solvent absorption and pre-combustion separation systems for permanent sequestration or industrial reuse.
Most installed capacity flows through Supercritical Technology. Expansion is steepest in Carbon Capture Utilization.
Application:
Volume scales inversely with customization depth — power generation rewards replication, while steel and chemicals demand site-specific integration.
- Power Generation:Ultra-supercritical retrofits and newbuilds dominate procurement volumes, with China's State Grid specifying integrated pollution control systems at coastal and inland provincial facilities. India's CEA-mandated efficiency thresholds favor supercritical technology over subcritical legacy assets at NTPC complexes.
- Steel Production:Blast furnace operators in China and India deploy gasification with carbon capture for direct reduced iron production where fuel-switching alternatives remain economically constrained. Metallurgical applications command premium pricing due to concentrated buyer bases and limited substitution options.
- Cement Manufacturing:Pre-calciner integration of oxy-fuel combustion for process heat and clinker production.
- Chemical Processing:Syngas-to-ammonia and syngas-to-methanol pathways for fertilizer and industrial chemical feedstocks.
Power Generation absorbs the largest equipment volumes. Steel Production delivers the highest margin per installed megawatt.
End User:
Procurement authority fragments across centralized state utilities and decentralized industrial operators with diverging risk tolerances.
- Utilities:State-backed generation companies in China, India, and Indonesia drive standardized supercritical and IGCC procurement through sovereign-backed financing. State Grid Corporation and NTPC Limited issue technology-specific tenders with domestic content requirements.
- Manufacturing Plants:Steel and cement producers in China's Shandong province increasingly unbundle gasification island procurement from EPC contracts, sourcing syngas conditioning and CO2 compression trains directly.
- Industrial Facilities:Chemical complexes and refineries seeking hydrogen co-production from gasification assets.
- Government Projects:Demonstration plants and research facilities testing advanced combustion and capture configurations.
Utilities command the largest project scale. Manufacturing Plants are gaining procurement autonomy fastest.
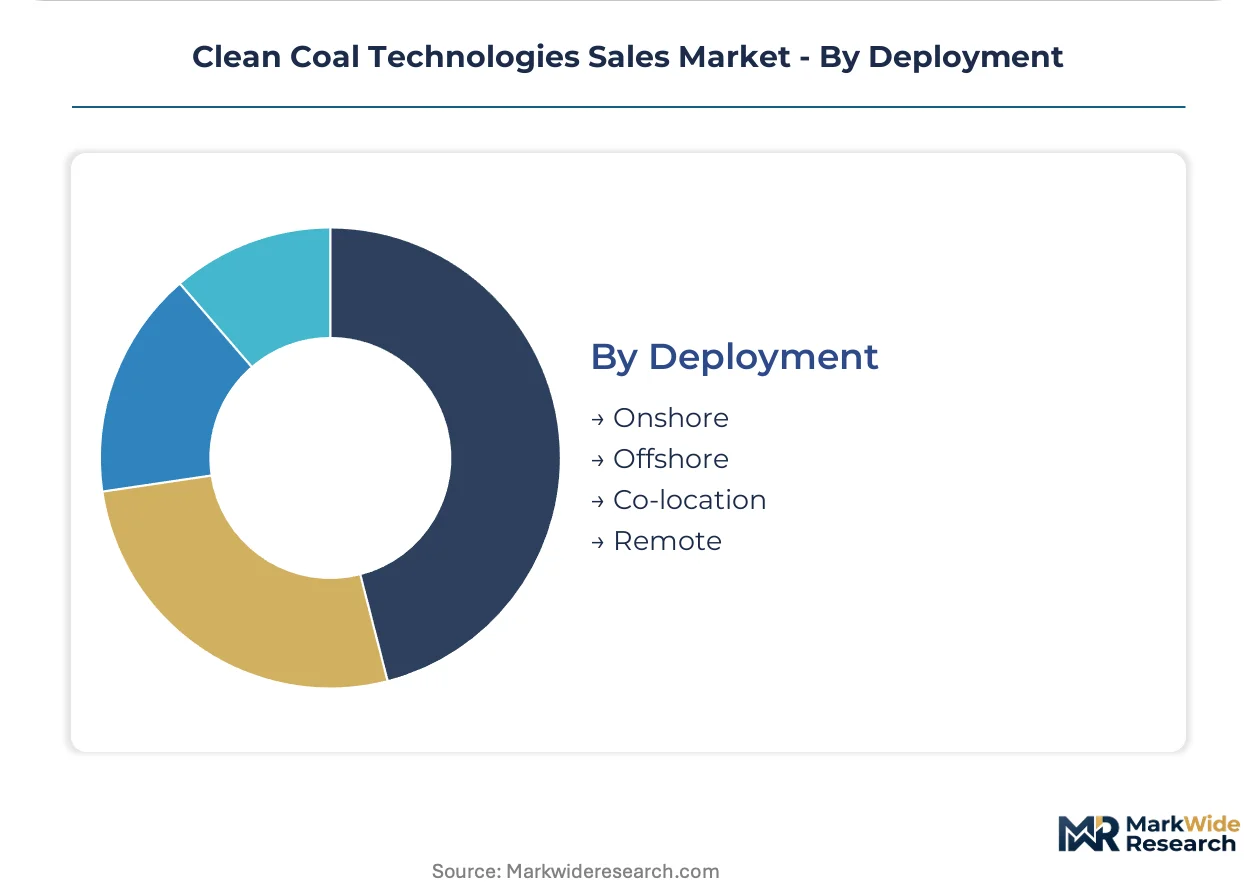
Deployment:
Site constraints and infrastructure availability determine whether projects access grid interconnection, industrial offtake agreements, or captive power arrangements.
- Onshore:Conventional utility installations at existing coal corridors with established transmission infrastructure and cooling water access. China's coastal provinces and India's eastern generation clusters concentrate deployment.
- Offshore:Floating or coastal platform-mounted gasification for remote industrial zones and islanded grids.
- Co-location:Integrated steel-chemical-power complexes where syngas, steam, and CO2 streams serve multiple processes.
- Remote:Captive mine-mouth generation for isolated industrial zones lacking pipeline natural gas alternatives.
Onshore deployment retains the deepest project pipeline. Co-location configurations are expanding most quickly as industrial symbiosis policies tighten.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Specialized welding certification programs in Germany and advanced control systems engineering in Japan anchor the technical workforce supporting clean coal deployment. Talent concentration in high-pressure metallurgy and gasification process design shapes regional competitive positioning.
China
State Grid Corporation's procurement of ultra-supercritical retrofits drives equipment demand across Shandong and Shanxi provincial clusters. The MEE's ultra-low emissions standards mandate integrated pollution control systems at coastal generation facilities. Qingdao and Yantai manufacturing corridors host domestic turbine island fabrication serving State Grid tenders.
United States
Midwestern power pools with pre-1990 subcritical assets face concentrated EPA Mercury and Air Toxics Standards compliance deadlines through 2028. The EPA mandates activated carbon injection or fabric filter upgrades at legacy units. Ohio River Valley coal corridors concentrate engineering procurement among specialized emissions control contractors.
India
NTPC Limited's state-run generation complexes drive supercritical newbuild demand under CEA-mandated thermal efficiency thresholds. The CEA mandates minimum efficiency standards favoring ultra-supercritical technology over subcritical legacy assets. Eastern coastal corridors from Odisha to West Bengal host ammonia synthesis feedstock projects linking gasification to fertilizer complexes.
Germany
Siemens Energy AG anchors European technology exports through turbine-integrated gasification packages to Asian utilities. German metallurgical suppliers concentrate specialized nickel-alloy forging capacity for ultra-supercritical pressure boundaries. Ruhr industrial clusters retain process engineering expertise supporting carbon capture module integration.
Indonesia
PLN's subcritical fleet averaging 35 percent thermal efficiency creates white space for supercritical boiler conversions. State utility procurement channels sovereign-backed financing toward efficiency retrofits. Java-Bali generation clusters concentrate deployment timelines as baseload demand rises.
Clean Coal Technologies Sales Market Competitive Landscape
Diversified conglomerates compete with focused pure-play specialists across technology procurement tiers. The market structure consolidates around integrated project developers with captive manufacturing capacity and component specialists with direct sales channels. Three archetypes dominate: state-backed industrial groups with domestic content requirements, European-Japanese technology licensors with metallurgical supply control, and emissions-control contractors with regulatory compliance expertise. Strategic moves concentrate on unbundling EPC contracts to access direct component sales and securing ASME-qualified welding capacity through training pipeline investments.
Among the named players, Siemens Energy AG and Mitsubishi Electric occupy positions reflecting distinct competitive vectors. Siemens Energy AG exemplifies the European technology licensor archetype with integrated turbine-gasification packaging. Mitsubishi Electric represents the advanced control systems specialist tier with machine learning-based combustion optimization platforms. Shanghai Electric Group anchors the state-backed industrial group category with domestic manufacturing scale advantages at Chinese coastal facilities.
| Leading Market Players |
|---|
| General Electric Company |
| Siemens Energy AG |
| Royal Dutch Shell PLC |
| Mitsubishi Electric |
| Shanghai Electric Group |
| Alstom SA |
| KBR Inc. |
| Harbin Electric Company Limited |
| Clean Coal Technologies Inc. |
| Others |
Pricing and Supply Chain Analysis
China's MEE ultra-low emissions mandates gate qualified supply for premium-tier clean coal systems, restricting turbine island procurement to vendors with ASME-certified welding capacity and domestic content compliance. State-backed utilities in Shandong and Shanxi provinces now pay efficiency premiums for supercritical retrofits that smaller industrial buyers cannot access, compressing margin structures at the economy tier.
Pricing Analysis
The bundled-versus-unbundled service split now dominates procurement economics across generation portfolios. EPC-integrated contracts at Chinese coastal facilities command project-based pricing with 15-20 year service attachments, while steel producers in Shandong province increasingly source gasification islands and CO2 compression trains separately through direct component sales. Price differentiation hinges on ASME Section IX welding certification and thermal efficiency guarantees above 45 percent. Cost compression in standard supercritical equipment is intensifying because Shanghai Electric and Harbin Electric compete on domestic manufacturing scale. State utilities remain least price-sensitive due to sovereign-backed financing, while private steel groups negotiate aggressively on syngas conditioning modules.
Supply Chain Analysis
Dual-sourcing requirements now permeate procurement specifications at NTPC and State Grid, mandating qualified secondary suppliers for nickel-alloy forgings and advanced control systems. Geographic supply concentration centers on Germany and Japan for specialized turbine components, China for domestic boiler fabrication, and India for emerging pressure vessel capacity. Raw material dependencies include Indonesian thermal coal for gasification feedstock, coconut shell activated carbon for emissions control, and specialized nickel alloys from Japanese metallurgical suppliers. Single-source vulnerability concentrates in ASME-certified welding labor with 18-month training pipelines. Distribution runs through state utility tender channels and direct industrial procurement from unbundled EPC contracts.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The clean coal technologies market presents a late-cycle quality story as procurement shifts toward ultra-supercritical specifications with integrated carbon capture. State Grid and NTPC tenders now disqualify subcritical retrofits, elevating premium-tier vendors with pre-combustion capture capabilities.
For Market Incumbents: Lock in ASME-qualified welding capacity through dedicated training pipelines at Qingdao and Yantai manufacturing corridors. Secure backward integration into nickel-alloy forging supply through offtake agreements with Japanese metallurgical suppliers. Battery storage substitution in OECD markets threatens baseload coal margins; defend position by embedding digital twin combustion optimization into long-term service contracts at Chinese coastal facilities. For New Entrants and Emerging Players: Digital twin platforms for boiler optimization offer a technology-first wedge into the retrofit market. Target Indonesia's PLN subcritical fleet averaging 35 percent thermal efficiency, where supercritical conversions remain underpenetrated and procurement channels are less consolidated than China's state utility tenders. Partner with specialized emissions control contractors for EPA MATS compliance clusters in the US Midwest rather than competing head-to-head with integrated EPCs. For Investors and Strategic Acquirers: Roll-up economics work for emissions-control contractors with EPA regulatory expertise because compliance deadlines through 2028 concentrate retrofit demand among specialized engineering firms. Long-term viability rests on carbon capture utilization scale-up in steel and chemical applications where fuel-switching alternatives remain constrained. Watch the EU Carbon Border Adjustment Mechanism implementation as the inflection signal for sequestration-equipped coal-derived product premiums.| Strategic Initiative | Industry Significance |
|---|---|
| ASME Welding Certification Investment | Training pipeline expansion unlocks field deployment capacity for supercritical pressure boundaries at State Grid facilities. |
| Digital Twin Platform Integration | Machine learning combustion optimization compresses operational variance for Mitsubishi Electric and Siemens control system deployments. |
| Carbon Capture Module Licensing | Technology transfer agreements enable ammonia synthesis feedstock supply to India's eastern coastal fertilizer complexes. |
| Domestic Manufacturing Scale-Up | Shanghai Electric leverages Qingdao fabrication corridors to compete on deployment cost at multiple Chinese coastal facilities. |
| Unbundled Component Sales Channel | Direct procurement of syngas conditioning systems bypasses integrated EPC margins for Shandong steel producers. |
Research Methodology
Quantitative tracking and qualitative interviews ran in parallel throughout the study window, combining primary discussions with utility planning officers, EPC project developers, steel procurement directors, and emissions control contractors with secondary validation. Secondary sources included EIA power generation data, IEA clean coal technology reports, China MEE regulatory filings, and SEC disclosures from listed equipment manufacturers. Bottom-up project pipeline analysis across Shandong, Shanxi, and eastern Indian generation clusters triangulated against top-down market sizing from technology shipment records.
Comparable-period anchoring linked the projection horizon to historical deployment cycles from supercritical retrofits and IGCC newbuilds across the analysis window. Segmentation dimensions modeled included technology type, application sector, end-user procurement authority, and deployment configuration. CAGRs derived from equipment order backlogs, tender award timelines, and efficiency mandate implementation schedules. Industry-specific inputs incorporated MEE ultra-low emissions compliance deadlines, EPA MATS retrofit clustering, and CEA thermal efficiency threshold enforcement.
The model holds under sustained regulatory enforcement of emissions standards and efficiency mandates; deviation in carbon border adjustment implementation timelines or accelerated battery storage cost declines would shift the outlook materially. Forecasts assume continued state utility procurement concentration and sovereign-backed financing availability for baseload generation assets.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Emerging Energy Technologies
Europe Clean Coal Technologies Market
Emerging Energy Technologies
Cryogenic Technology Market
Emerging Energy Technologies
Global Microreactor Technology Market
Emerging Energy Technologies
Multi Energy Systems Market
Emerging Energy Technologies
Global Power-To-X Market
Emerging Energy Technologies
Energy Transition Market
Emerging Energy Technologies
Advanced Energy Market
Emerging Energy Technologies
Clean Technology Market
Emerging Energy Technologies
Nanotechnology in Energy Market
Emerging Energy Technologies
Decarbonization Market
Emerging Energy Technologies
Methanation Technology Market
Emerging Energy Technologies
United States Clean Coal Technologies Market