
 Global Advanced Biofuel Market | 2026-2036
Global Advanced Biofuel Market Size, Share, and Industry Trends Forecast 2026-2036
Global Advanced Biofuel Market Analysis
Aftermarket carbon credit monetization is narrowing as a standalone profit center as compliance markets mature and credit prices stabilize. Neste Corporation leverages its Singapore refinery expansion to dominate renewable diesel supply into California's LCFS market. POET LLC anchors its position through backward integration into corn stover collection across the US Midwest. Chevron competes by extending its traditional refining expertise into co-processing biomass at existing Gulf Coast facilities.
Advanced biofuels comprise liquid transportation fuels derived from lignocellulosic biomass, algae, or waste feedstocks processed through thermochemical or biochemical pathways to achieve greenhouse gas reductions exceeding conventional biofuels by at least fifty percent. These fuels serve primarily as drop-in replacements for petroleum-derived gasoline, diesel, and jet fuel within existing engine and infrastructure configurations. Biodiesel refined from algae feedstock captures premium margins due to its superior energy density and minimal land-use competition with food crops. Ethanol produced via biochemical conversion of agricultural residues sustains volume leadership across transportation end-use applications. Thermochemical gasification pathways for wood waste represent the fastest-growing technology segment as project developers seek feedstock flexibility beyond lipid-based inputs.
The US EPA administers the Renewable Fuel Standard with nested obligations for cellulosic and advanced biofuel volumes, while the EU Renewable Energy Directive imposes greenhouse gas intensity thresholds that effectively exclude conventional crop-based fuels from premium tier recognition. California's Air Resources Board operates the Low Carbon Fuel Standard as a de facto national benchmark through credit price transparency and stringency ratcheting. Stakeholders must monitor feedstock certification scheme fragmentation across jurisdictions to avoid compliance disqualification and stranded production capacity.
Market Dynamics
Aviation fuel blending mandates from ICAO member states are compressing deployment timelines for hydroprocessed esters and fatty acids, forcing refiners to secure feedstock contracts ahead of infrastructure completion.
Growth Catalysts
- ICAO Carbon Offsetting and Reduction Scheme:Binding aviation emission targets are pulling hydroprocessed esters and fatty acids into commercial jet fuel specifications across European and North American routes.
- California LCFS credit price transparency:Predictable carbon credit valuation is attracting private capital into West Coast renewable diesel capacity expansions.
- Gasification of wood waste:Thermochemical conversion pathways are unlocking stranded forestry residues as viable cellulosic feedstock outside traditional lipid supply chains.
Market Restraints
- Feedstock cost volatility:Used cooking oil and animal fat spot prices swing with protein meal and oleochemical demand, squeezing refinery margin predictability.
- Singapore-Jakarta supply corridor concentration:Over half of Asia-Pacific hydroprocessed ester capacity clusters within a single maritime shipping lane, exposing buyers to port congestion risk.
- EU Renewable Energy Directive GHG intensity thresholds:Stringent lifecycle carbon accounting disqualifies many conventional crop-based pathways from premium tier recognition.
Strategic Opportunities
- Indonesia palm oil mill effluent capture:Untapped wastewater lipid streams offer low-cost feedstock for integrated biorefineries serving domestic biodiesel mandates.
- Algae cultivation in arid zones:Photobioreactor deployments in Saudi Arabia and UAE are bypassing agricultural land-use constraints entirely.
- Co-processing at Gulf Coast refineries:Existing fluid catalytic cracking units can accept biomass-derived pyrolysis oil with minimal retrofit capital.
Industry Challenges
- Feedstock certification fragmentation:ISCC, RSB, and Bonsucro scheme incompatibilities are forcing producers to maintain parallel audit trails for multi-jurisdiction sales.
- Biochemical enzyme stability:Cellulase cocktail performance degrades across variable lignocellulosic compositions, requiring continuous strain optimization.
- Jet fuel ASTM D7566 approval timelines:Novel alcohol-to-jet pathways face multi-year qualification testing before airline offtake agreements materialize.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Global Advanced Biofuel Market |
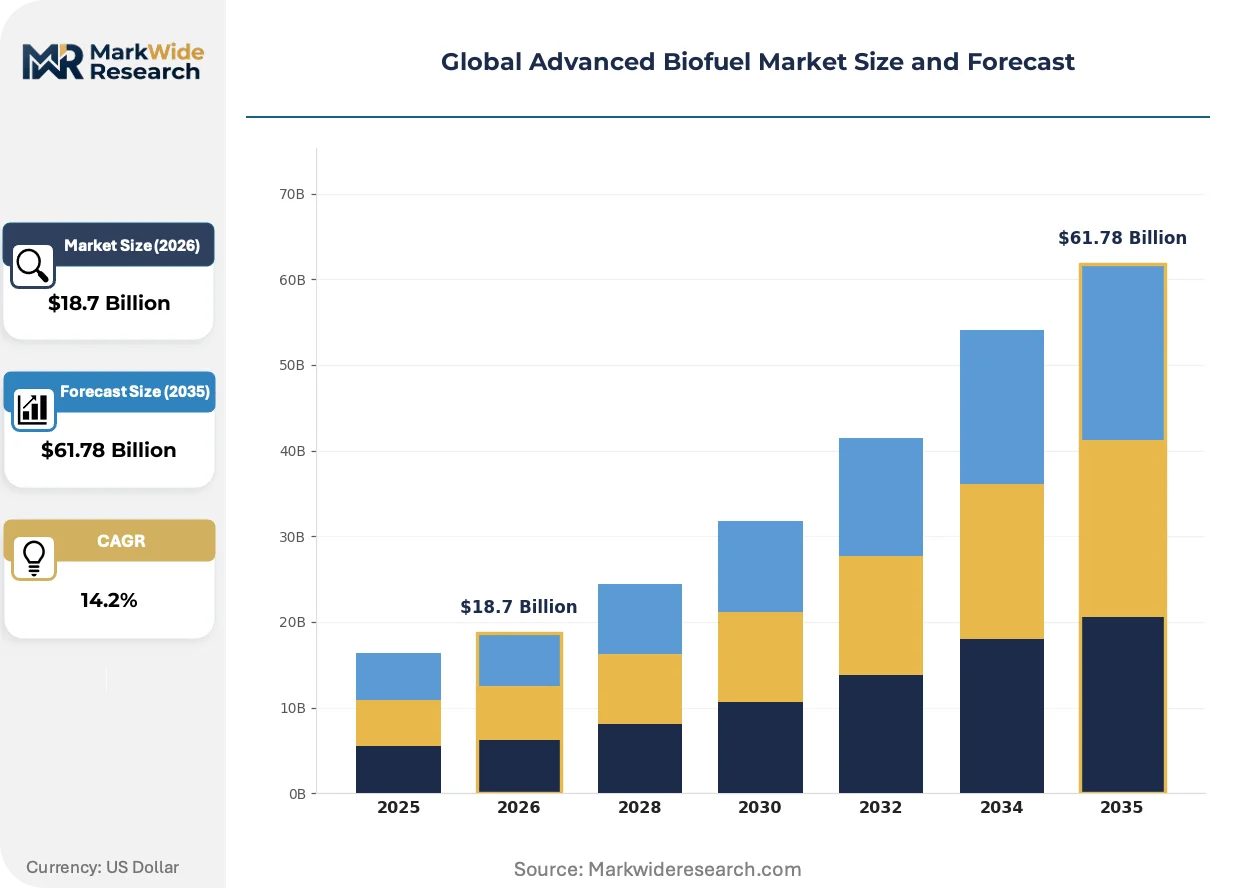
| Market Size in 2026 | $18.7 Billion |
| Market Size in 2035 | $61.78 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Product Type: Biodiesel, Ethanol, Biogas, Butanol Feedstock: Algae, Agricultural Residues, Wood Waste, Energy Crops Technology: Thermochemical, Biochemical, Fermentation, Extraction End User: Transportation, Industrial, Residential, Power Generation |
| Companies Covered | Chevron, Neste Corporation, Shell, POET LLC, Gevo, TotalEnergies, ExxonMobil, Clariant, BP, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Global Advanced Biofuel Market Emerging Trajectories
Refinery technology choices are hardening into competitive moats as capital deployment commitments lock in feedstock flexibility for decades. Process intensification and modular unit designs are compressing project development cycles.
Electrofuel synthesis combining green hydrogen with captured carbon dioxide is rendering obsolete standalone biomass gasification for aviation fuel production. European flag carriers are piloting power-to-liquid offtake agreements with Nordic electrolyzer operators. This pathway eliminates agricultural land-use constraints entirely while meeting ICAO's most stringent carbon intensity benchmarks.
REACH authorization requirements for novel catalyst chemistries are extending European biorefinery commissioning timelines by eighteen to thirty-six months. ECHA's persistent organic pollutant screening is forcing reformulation of hydroprocessing catalysts previously standard in petroleum refining. German and Dutch project developers are front-loading regulatory consultation to avoid stranded engineering investments.
Fleet operators are consolidating fuel procurement under sustainability-linked tender clauses that preference certified low-carbon intensity supply. Major US trucking carriers now bundle renewable diesel contracts with carbon accounting services from third-party verifiers. This behavior is most visible in California's drayage and long-haul segments where LCFS credit stacking amplifies total cost differentials.
Global Advanced Biofuel Market Segmentation
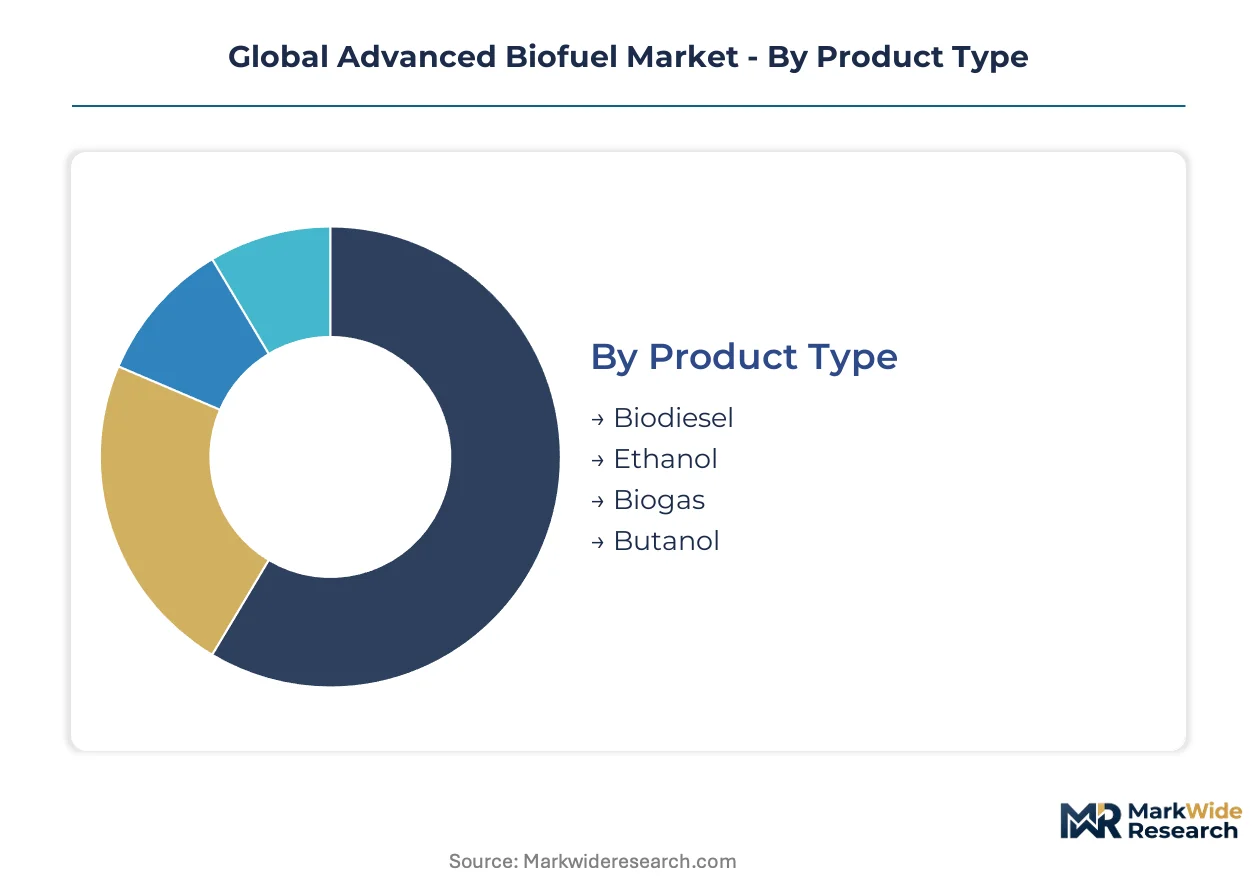
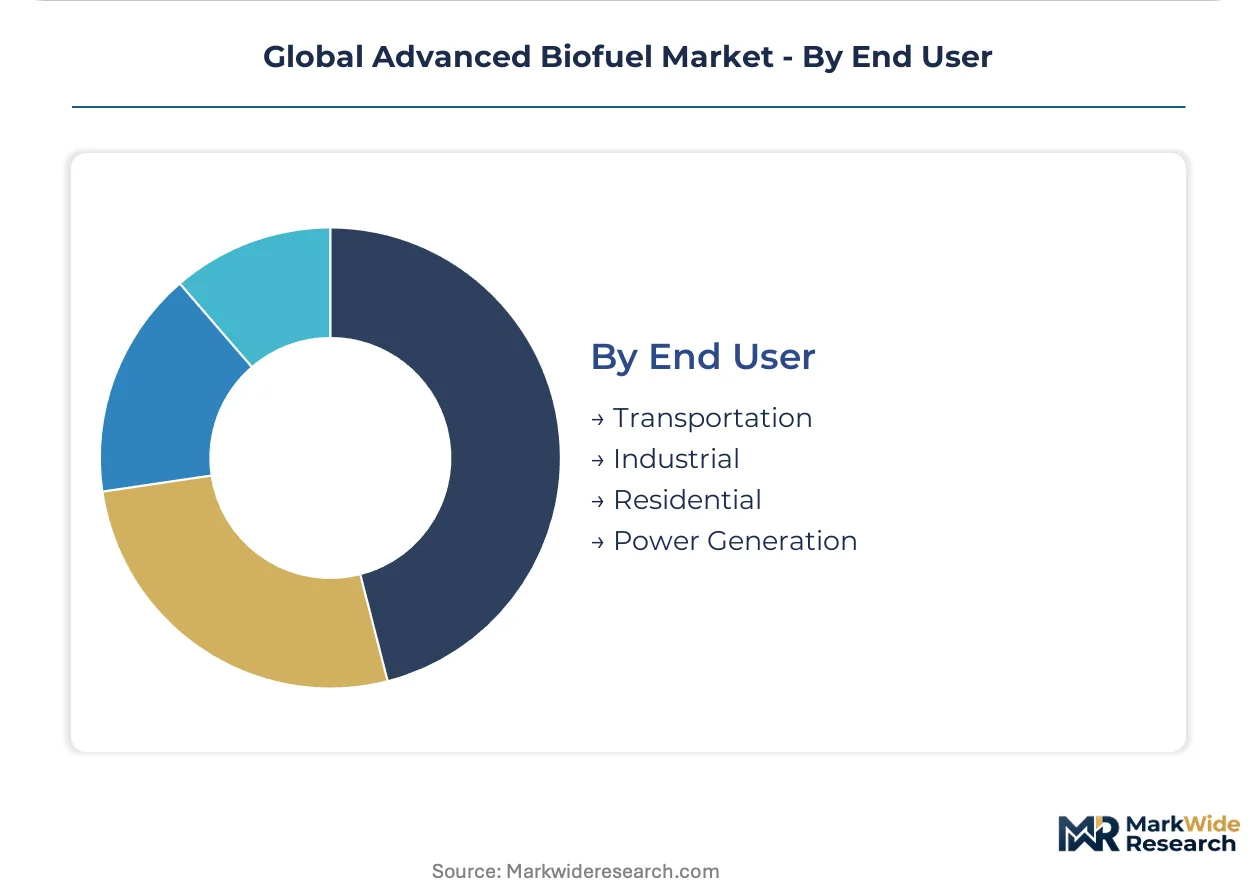
Advanced biofuel market segmentation reveals distinct competitive arenas where feedstock flexibility, technology maturity, and regulatory qualification determine margin capture. Product type and feedstock categories anchor investment decisions, while technology pathways and end-user concentration shape capacity deployment timelines.
Product Type:
Mature liquid fuel categories dominate near-term revenue, while emerging molecules carve niche positions through performance premiums.
- Biodiesel:Hydroprocessed esters and fatty acids refined from lipid feedstocks achieve drop-in compatibility with conventional diesel engines. Demand concentrates in California's heavy-duty trucking corridors where LCFS credit stacking amplifies cost competitiveness against petroleum diesel.
- Ethanol:Cellulosic ethanol produced via biochemical conversion of agricultural residues meets EPA Renewable Fuel Standard nested obligations for advanced biofuel volumes. US Midwest biorefineries anchor supply into E15 blending mandates across state fuel markets.
- Biogas:Upgraded biomethane serves industrial thermal applications and compressed natural gas vehicle fleets.
- Butanol:Higher alcohols offer superior energy density for gasoline blending; limited commercial scale constrains adoption.
Biodiesel handles the majority of throughput; ethanol is the fastest mover on share.
Feedstock:
Cost tier differentiation separates premium lipid streams from volume cellulosic inputs.
- Algae:Photobioreactor cultivation in arid zones delivers lipid productivity rates exceeding terrestrial crops by an order of magnitude. UAE and Saudi Arabia project developers bypass agricultural land-use constraints entirely while targeting aviation fuel specifications.
- Agricultural Residues:Corn stover and wheat straw collection networks across the US Midwest supply POET LLC's backward-integrated logistics. EPA cellulosic volume mandates create guaranteed offtake floors for this feedstock category.
- Wood Waste:Forestry residues and sawmill byproducts unlock thermochemical gasification pathways.
- Energy Crops:Dedicated perennial grasses and short-rotation woody crops remain pre-commercial at scale.
Agricultural residues handle the majority of throughput; algae is gaining share fastest.
Technology:
Application-specific processing requirements favor thermochemical flexibility for heterogeneous feedstocks versus biochemical precision for sugar streams.
- Thermochemical:Gasification and pyrolysis pathways convert lignocellulosic biomass into synthesis gas or bio-oil intermediates. Wood waste developers in Finland and Sweden deploy fluidized bed reactors to achieve feedstock flexibility beyond lipid constraints.
- Biochemical:Enzymatic hydrolysis and fermentation routes dominate agricultural residue processing. Cellulase cocktail optimization remains continuous as variable lignin content degrades conversion efficiency across feedstock batches.
- Fermentation:Anaerobic digestion platforms serve wet organic waste streams.
- Extraction:Mechanical and solvent-based lipid recovery from algae and oilseed crops.
Biochemical handles the majority of throughput; thermochemical is climbing the fastest.
End User:
Customer type concentration varies by fuel specification stringency and carbon accounting requirements.
- Transportation:Aviation, marine, and road freight operators drive demand for certified low-carbon intensity fuels. ICAO member state blending mandates compress deployment timelines for hydroprocessed esters in commercial jet specifications.
- Industrial:Process heat and combined heat-and-power applications consume biogas and solid biofuel streams.
- Residential:Heating oil substitutions remain marginal in advanced biofuel penetration.
- Power Generation:Utility-scale biomass cofiring faces competition from solar and wind capacity additions.
Transportation handles the majority of throughput; industrial is expanding most quickly.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil and Indonesia exhibit the highest price elasticity as palm oil and sugarcane feedstock costs fluctuate with commodity cycles. European and North American purchasers absorb premium pricing for certified low-carbon intensity supply driven by binding blending mandates.
United States
California's heavy-duty trucking corridors drive renewable diesel offtake as LCFS credit stacking amplifies cost competitiveness against petroleum diesel. The EPA administers nested volume obligations for cellulosic and advanced biofuels under the Renewable Fuel Standard. POET LLC anchors Midwest supply through backward integration into corn stover collection networks across Iowa and South Dakota.
Brazil
Sugarcane ethanol producers face margin compression as global sugar prices divert crush volumes toward sweetener markets. The national biofuel policy RenovaBio assigns carbon intensity scores that determine compliance credit generation rates. São Paulo state concentrates bagasse-fired cogeneration capacity serving second-generation ethanol pilot facilities.
Germany
Industrial biogas upgrading facilities serve compressed natural gas vehicle fleets under federal mobility transition programs. ECHA's REACH authorization requirements extend biorefinery commissioning timelines through persistent organic pollutant screening of novel catalyst chemistries. The Hamburg cluster hosts fluidized bed gasification developers targeting forestry residue conversion.
Indonesia
Palm oil mill effluent capture offers low-cost lipid feedstock for integrated biorefineries serving domestic biodiesel mandates. The Ministry of Energy and Mineral Resources enforces progressively higher blending ratios for fatty acid methyl ester in transportation fuel. The Singapore-Jakarta maritime corridor concentrates hydroprocessed ester refining capacity exposed to port congestion risk.
United Arab Emirates
Photobioreactor deployments in arid zones bypass agricultural land-use constraints while targeting aviation fuel specifications. The national oil company partners with Nordic electrolyzer operators on power-to-liquid pilot agreements. Abu Dhabi hosts algae cultivation facilities leveraging year-round solar irradiance for lipid productivity rates exceeding terrestrial crops.
Global Advanced Biofuel Market Vendor Landscape
Capability concentration sits with integrated oil majors possessing legacy refining expertise and feedstock procurement infrastructure; scale advantage sits with specialized renewable fuel producers with dedicated biorefinery assets and certification scheme mastery. The market structure reveals a tiered competitive map where petroleum incumbents compete against pure-play biofuel specialists and agricultural processors extending into downstream fuel production. Three strategic archetypes dominate: petroleum majors leveraging co-processing at existing facilities, dedicated renewable fuel specialists with standalone biorefinery networks, and agribusiness conglomerates integrating crop collection into fuel output. Competitive moves center on feedstock contract locking ahead of infrastructure completion and regulatory qualification racing for novel conversion pathways.
Within the petroleum major tier, Chevron and Shell exemplify incumbents extending traditional refining infrastructure into biomass co-processing. Neste Corporation and POET LLC occupy positions as dedicated renewable fuel specialists with distinct geographic anchoring—Neste leveraging Singapore refinery expansion for California LCFS supply, POET integrating Midwest agricultural residue collection. Gevo represents the emerging technology pathway archetype targeting alcohol-to-jet qualification.
| Leading Market Players |
|---|
| Chevron |
| Neste Corporation |
| Shell |
| POET LLC |
| Gevo |
| TotalEnergies |
| ExxonMobil |
| Clariant |
| BP |
| Others |
Supply Flow & Price Mechanics
Feedstock certification fragmentation across ISCC, RSB, and Bonsucro schemes determines both the premium spread between certified and uncertified supply tiers and the geographic clustering of biorefinery investments. Refiners accepting multi-jurisdiction sales absorb parallel audit costs that compress margins on standard-grade output while amplifying returns for dual-certified premium streams.
Pricing Analysis
Aftermarket carbon credit monetization drives lifetime value through LCFS credit stacking and nested RIN generation rather than standalone fuel margins. Three-tier pricing structure across certified low-carbon, standard renewable, and conventional blendstock levels reflects California Air Resources Board stringency ratcheting and EPA nested obligation tiers. Pricing pressure stems from used cooking oil and animal fat spot volatility swinging with protein meal demand, squeezing margin predictability for hydroprocessed esters. Fleet operators in California's drayage segments absorb premium pricing for certified supply, while Indonesian domestic buyers exhibit highest sensitivity to palm oil commodity cycles.
Supply Chain Analysis
Extended payment terms from Singapore-Jakarta corridor refiners to Indonesian palm oil mill operators compress working capital cycles for integrated biorefineries. Feedstock procurement concentrates in the United States, Brazil, and Indonesia, with lipid streams drawing from palm oil mill effluent capture and corn stover collection networks. Supply chain risk rests on single-maritime-lane concentration exposing hydroprocessed ester capacity to port congestion. Distribution runs through California heavy-duty trucking corridors and European aviation fueling infrastructure anchored to ICAO member state mandates.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Scarcity of ASTM D7566 qualification expertise and feedstock certification scheme mastery constrains capacity deployment timelines and concentrates margin capture among early movers. Biorefinery developers lacking parallel audit trail capabilities face stranded production capacity as multi-jurisdiction sales become table stakes.
For Market Incumbents: Entrench position through backward integration into corn stover collection networks across Iowa and South Dakota, mirroring POET LLC's captive supply model. Lock long-term offtake agreements with California fleet operators ahead of Singapore refinery capacity coming online. Defend against electrofuel pathway displacement by accelerating hydroprocessed ester deployment timelines for aviation blending mandates. For New Entrants and Emerging Players: Pursue algae cultivation in UAE and Saudi Arabia arid zones where photobioreactor deployments bypass agricultural land-use constraints entirely. Target power-to-liquid pilot agreements with Nordic electrolyzer operators as European flag carriers consolidate procurement under sustainability-linked tender clauses. Lead with carbon intensity benchmarking services bundled with fuel supply to differentiate from commodity traders. For Investors and Strategic Acquirers: The market sits at a feedstock-contract-locking phase that favors developers with secured lipid streams and regulatory qualification momentum. Five-to-ten year viability hinges on ICAO CORSIA enforcement stringency and EU RED GHG threshold ratcheting. Watch for alcohol-to-jet pathway ASTM approval timelines as inflection indicator for technology pathway winners.| Strategic Initiative | Industry Significance |
|---|---|
| Feedstock Contract Locking | Secures used cooking oil and palm oil mill effluent streams ahead of Singapore-Jakarta corridor capacity expansions. |
| Dual Certification Investment | Enables ISCC-RSB parallel audit trails for California LCFS and EU RED premium tier recognition. |
| Co-Processing Retrofit | Leverages existing Gulf Coast fluid catalytic cracking units for biomass-derived pyrolysis oil acceptance. |
| Algae Cultivation Scale-Up | Deploys photobioreactors in UAE arid zones targeting aviation fuel specifications with year-round solar irradiance. |
| Power-to-Liquid Partnership | Combines green hydrogen with captured carbon dioxide for ICAO's most stringent carbon intensity benchmarks. |
Methodological Framework
The analysis maps hydroprocessed esters, cellulosic ethanol, thermochemical gasification pathways, and electrofuel synthesis, each validated through biorefinery project developers, fuel procurement officers at aviation and trucking fleet operators, and certification scheme auditors. Primary interviews with EPA regulatory affairs specialists, California Air Resources Board compliance officers, and EU RED implementation consultants combined with secondary validation through EIA biofuel production data, ICAO CORSIA implementation documents, EPA RIN generation reports, and EU RED delegated act amendments. Bottom-up capacity buildout tracking and top-down mandate obligation modeling provided triangulation across volume estimates.
Assumptions held fixed include ICAO member state binding aviation emission targets, EPA nested volume obligations for cellulosic and advanced categories, and California LCFS stringency ratcheting schedules across the analysis window. Segmentation dimensions modeled encompass fuel type, feedstock category, conversion technology, and end-use concentration with geographic regulatory cluster overlays. CAGRs derived from capacity deployment timelines, feedstock availability curves, and mandate obligation trajectories. Industry-specific inputs include enzyme cocktail performance degradation rates across variable lignocellulosic compositions and novel catalyst REACH authorization timeline distributions.
The forecast holds incumbent behavior within observed patterns; aggressive moves by petroleum majors into standalone biorefinery construction or pure-play specialists into electrofuel synthesis would shift outcomes beyond modeled ranges. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Bioethanol Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Europe Biofuel Market
Biofuels
Biofuel Ethanol Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Latin America Biodiesel Market
Biofuels
Europe Biodiesel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Brazil Biofuel Market
Biofuels
Biodiesel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Biofuels Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
United States Biodiesel Market