
 Second Generation Biofuels Market | 2026-2036
Second Generation Biofuels Market Size, Share, and Industry Trends Forecast 2026-2036
Second Generation Biofuels Market Outlook
Cellulosic ethanol hydrolysis is rewriting the cost structure of fuel production from agricultural residues. POET-DSM Advanced Biofuels LLC leverages its Liberty facility to demonstrate continuous enzymatic processing at commercial scale. Clariant AG anchors its Sunliquid technology platform across European straw supply chains. GranBio competes in Brazilian bagasse conversion with proprietary pre-treatment systems that reduce enzyme loading.
Second generation biofuels are liquid or gaseous fuels manufactured from lignocellulosic biomass, algae, or waste oils through thermochemical or biochemical pathways, typically yielding energy densities of 26-33 MJ per liter depending on the fuel oxygenate content. These fuels serve primarily as drop-in replacements or high-blend components in transportation and power generation systems requiring reduced lifecycle carbon intensity. Lignocellulosic biomass dominates feedstock flows due to abundant agricultural residue availability and minimal food-fuel competition, while gasification routes attract capital for their flexibility in producing both Fischer-Tropsch diesel and renewable syngas. Fermentation platforms occupy the most mature margin pool, though pyrolysis-based bio-oil upgrading is gaining traction in chemical feedstock applications where hydrogenation economics improve.
The EPA's Renewable Fuel Standard and the EU Green Deal's transport decarbonization targets shape demand by mandating escalating volumes of advanced biofuels with verified greenhouse-gas reductions. Brazil's ANP enforces RenovaBio carbon intensity scoring that directly ties fuel certification to market access, while India's BIS develops lignocellulosic ethanol standards under its ethanol blending program. Stakeholders must monitor enzyme cost curves and offtake contract structures as the gap between pilot-scale yields and commercial reliability determines which production platforms secure sustained capital deployment.
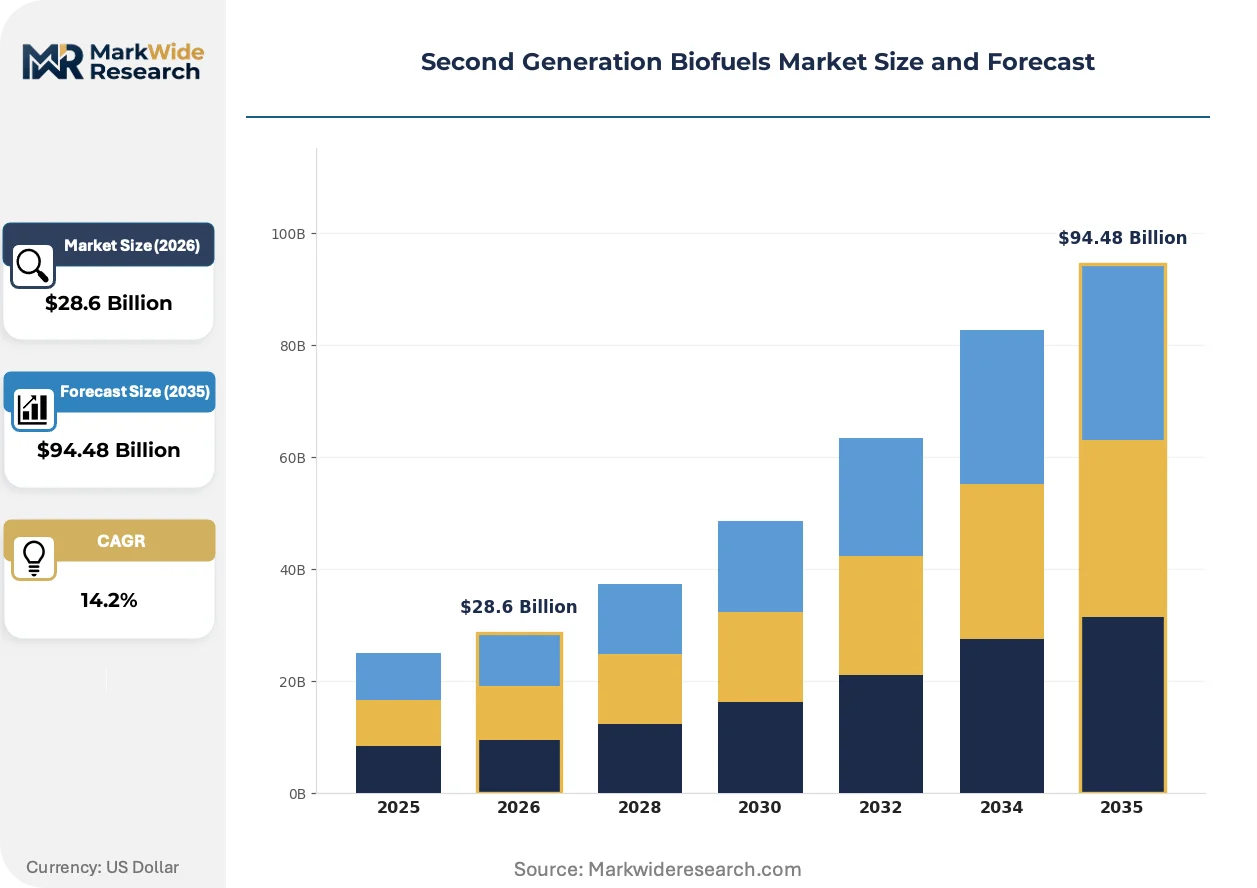
Market Dynamics
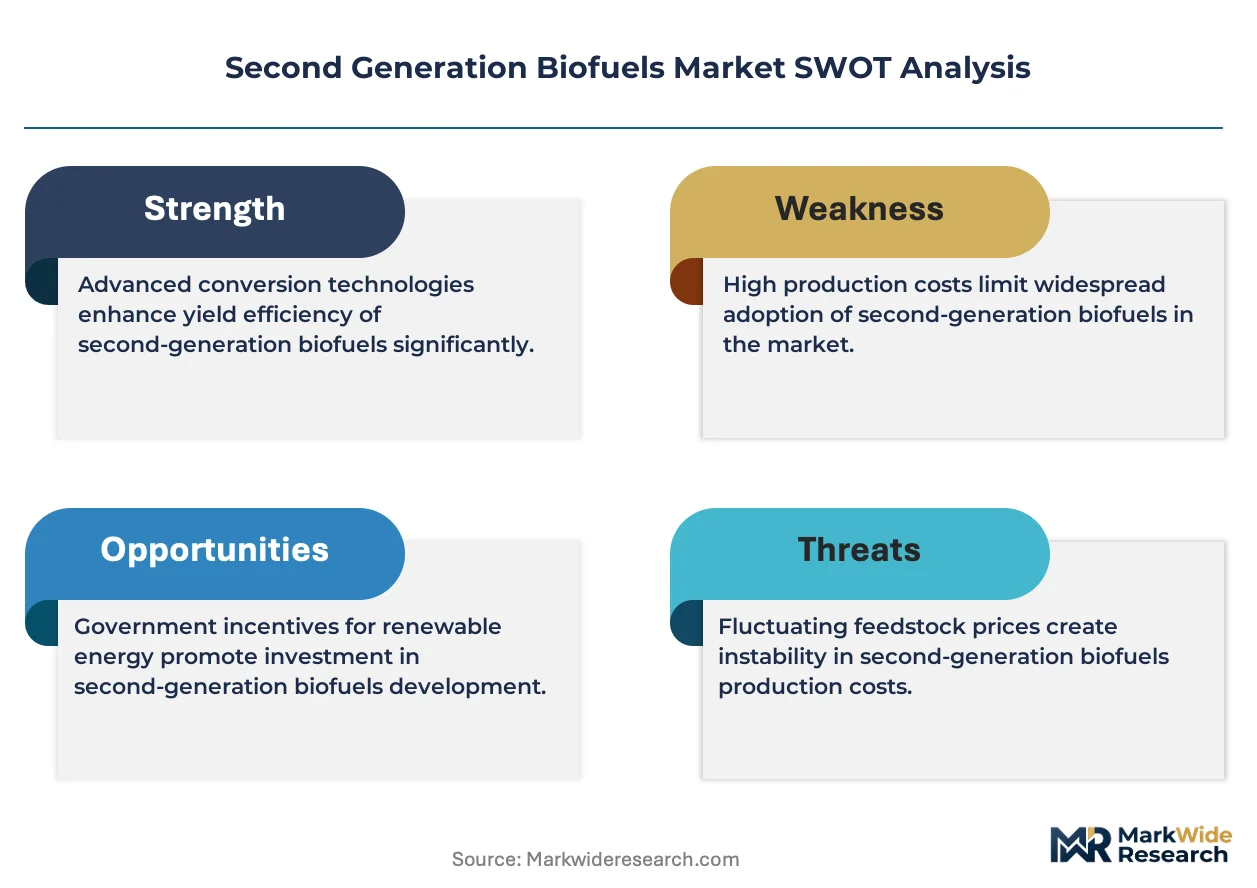
Enzyme cost curves and carbon intensity certification thresholds are compressing margins for first-generation producers while rewarding lignocellulosic platforms that achieve commercial-scale hydrolysis yields. The EU Green Deal's tightening transport fuel standards and Brazil's RenovaBio scoring system are accelerating capital migration toward bagasse and straw conversion infrastructure.
Growth Catalysts
- EU Green Deal transport decarbonization mandates:Escalating carbon intensity thresholds for road and aviation fuels are compelling fuel distributors to source certified low-CI ethanol and Fischer-Tropsch diesel from lignocellulosic origins.
- Bagasse-to-ethanol infrastructure buildout:Brazilian sugarcane processors are retrofitting mills with continuous enzymatic hydrolysis trains, drawing project finance from European trading houses seeking offtake security.
- Cellulosic aviation fuel offtake agreements:Airlines facing CORSIA compliance deadlines are signing long-term purchase contracts for hydroprocessed esters and fatty acids derived from agricultural residues.
Market Restraints
- Enzyme loading cost volatility:Cellobiase and cellulase cocktail expenses constitute 30-40% of variable production costs, with pricing tied to microbial fermentation capacity concentrated in Danish and Chinese supply chains.
- Feedstock collection radius limitations:Agricultural residue density economics restrict viable sourcing to 50-80 kilometer radii around processing facilities, constraining plant scale in North American corn belt regions.
- Pyrolysis bio-oil upgrading capex intensity:Hydrogenation and zeolite cracking units for bio-oil refining require front-loaded capital deployment that exceeds fermentation platform costs by significant multiples.
Strategic Opportunities
- Indian ethanol blending program expansion:BIS lignocellulosic ethanol standards under development will unlock demand from state-owned oil marketing companies seeking 20% blending compliance without food-fuel competition.
- Algae-to-fuel thermochemical convergence:Integration of hydrothermal liquefaction with existing petroleum refinery hydrogen networks offers pathway diversification for coastal processing clusters.
- Straw supply chain aggregation platforms:Digital contracting tools for European wheat and rice straw procurement are reducing collection coordination costs for Clariant Sunliquid licensees.
Industry Challenges
- Continuous enzymatic processing reliability:Maintaining 90+ day fermentation run times without contamination events requires specialized biochemical engineering talent scarce outside Brazilian and Dutch technical institutes.
- LCFS certification timeline compression:California Air Resources Board pathway verification for novel feedstock-process combinations extends 18-24 months, delaying revenue recognition for new facility startups.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Second Generation Biofuels Market |
| Market Size in 2026 | $28.6 Billion |
| Market Size in 2035 | $94.48 Billion |
| CAGR (2026 – 2036) | 14.2% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Sugarcane, Waste Oil, Lignocellulosic Biomass, Algae Production Process: Gasification, Fermentation, Pyrolysis, Hydrolysis End User Sector: Transportation, Power Generation, Industrial, Agricultural Application Area: Heating, Electricity Generation, Biofuel Blending, Chemical Feedstocks |
| Companies Covered | Algenol Biofuels, Clariant AG, Fiberight LLC, GranBio, Ineos Group, POET-DSM Advanced Biofuels LLC, Reliance Industries, DuPont, Orsted A/S, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Second Generation Biofuels Market Strategic Shifts
Process intensification and regulatory carbon accounting precision are forcing technology choices that separate scalable platforms from pilot-scale casualties. The competitive frontier now sits at the interface of biochemical engineering and certified supply chain traceability.
Consolidated bioprocessing using engineered thermophilic bacteria is collapsing the capital cost differential between separate hydrolysis and fermentation stages. Aviation fuel buyers in the EU and California are prioritizing offtake from facilities demonstrating consolidated operations, as the technology eliminates discrete enzyme production units and reduces tankage requirements. This compression is enabling project developers to pursue smaller-scale distributed processing models near feedstock origins rather than centralized hub configurations.
The EU Green Deal's revised Renewable Energy Directive introduces stricter sustainability criteria for biomass sourcing, including land-use change safeguards and forest biomass exclusion clauses. Fuel suppliers must now demonstrate chain-of-custody documentation from field to tank, with third-party verification against EN 16709 standards. European road transport and aviation sectors are responding by consolidating procurement around vertically integrated processors with captive feedstock supply agreements.
Long-term offtake contracting with indexed carbon credit mechanisms is displacing spot market purchasing for certified low-CI fuels. Airlines and marine operators are locking in 10-15 year supply agreements that bundle physical fuel delivery with verified emissions reduction certificates, transferring price risk to producers. This pattern is most pronounced in Nordic markets where national carbon neutrality targets for 2035 accelerate fuel switching timelines.
Second Generation Biofuels Market Segmentation
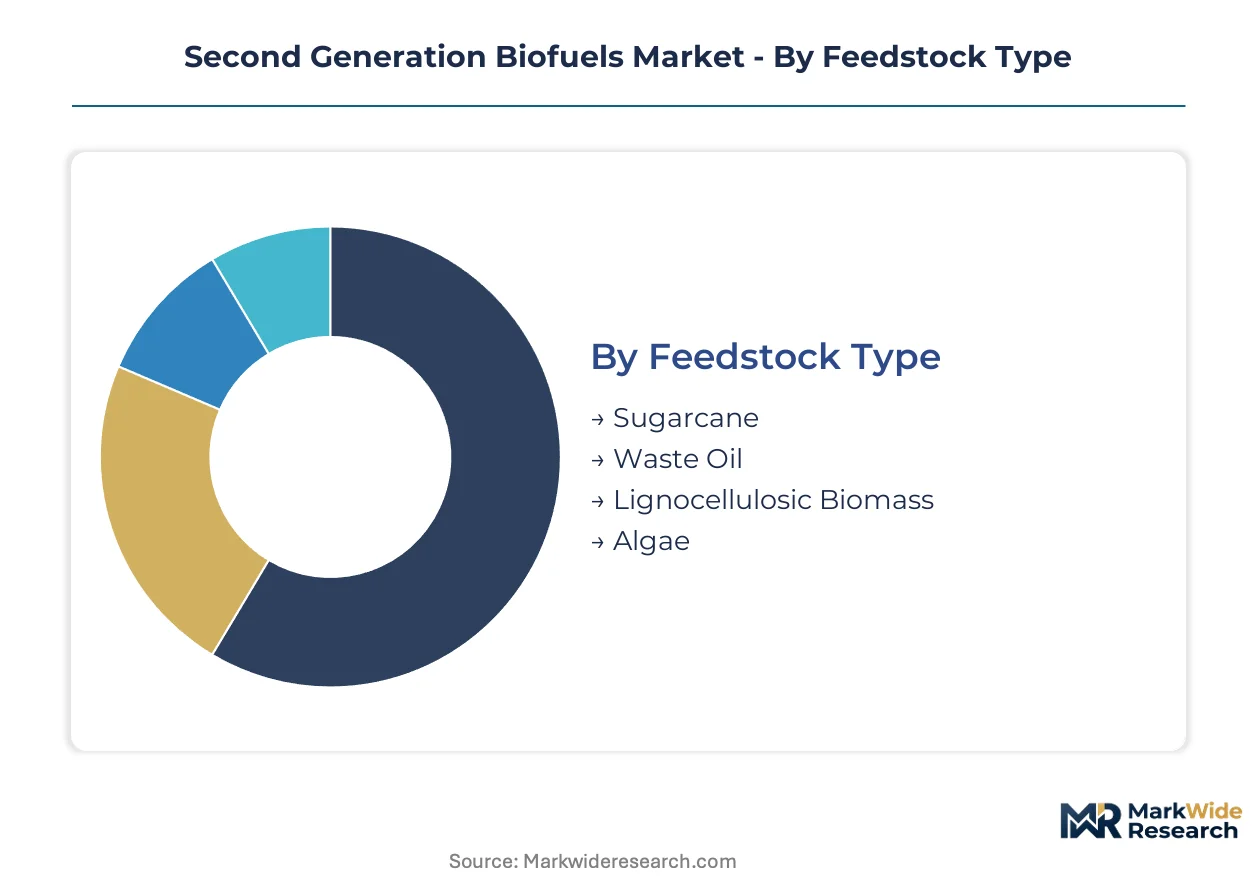
Second generation biofuels demand fragments across feedstock availability, process economics, and end-use certification requirements. Each segmentation axis carries distinct margin profiles and capital intensity thresholds that determine which production platforms attract sustained project finance.
Feedstock Type:
After-sales service intensity varies sharply by feedstock, with lignocellulosic platforms requiring continuous enzyme optimization support and algae operations demanding specialized cultivation monitoring.
- Lignocellulosic Biomass:Agricultural residues including wheat straw, rice husks, and corn stover supply the dominant feedstock flow for commercial cellulosic ethanol. Brazilian bagasse-to-ethanol retrofits and European straw processing clusters anchor demand, driven by EU Green Deal carbon intensity thresholds that exclude first-generation sources from advanced biofuel quotas.
- Sugarcane:Bagasse and cane trash provide established collection infrastructure and year-round supply continuity. Brazilian mills leverage existing logistics networks for RenovaBio-certified ethanol production, though enzyme loading costs constrain margin expansion relative to first-generation juice fermentation.
- Algae:Microalgal lipid and carbohydrate content offers non-arable land cultivation with superior areal productivity metrics. Hydrothermal liquefaction pathways attract coastal processing investments where refinery hydrogen integration reduces upgrading capex.
- Waste Oil:Used cooking oil and animal fats supply hydroprocessed ester feedstock for aviation fuel certification. Limited collection volumes and competing oleochemical demand restrict scale-up potential outside established urban waste recovery networks.
Lignocellulosic biomass holds the largest share; momentum sits with algae as thermochemical integration improves.
Production Process:
Process selection determines equipment supplier relationships and long-term technical service contracts, with fermentation platforms requiring sustained enzyme vendor partnerships.
- Fermentation:Enzymatic hydrolysis followed by microbial conversion of C5 and C6 sugars yields cellulosic ethanol at commercial scale. POET-DSM Liberty facility and Clariant Sunliquid licensees demonstrate continuous operation reliability, though contamination management demands specialized biochemical engineering talent.
- Gasification:Thermochemical conversion of lignocellulosic feedstock to syngas enables Fischer-Tropsch diesel and renewable methane production. Capital intensity exceeds biochemical routes but offers feedstock flexibility and drop-in fuel compatibility without oxygenate limitations.
- Hydrolysis:Acid or enzymatic cleavage of cellulose and hemicellulose into fermentable sugars represents the critical rate-limiting step. Cellobiase cocktail costs constitute 30-40% of variable production expenses, with pricing tied to Danish and Chinese microbial fermentation capacity.
- Pyrolysis:Rapid thermal decomposition in oxygen-limited environments produces bio-oil requiring subsequent hydrogenation or zeolite cracking. Upgrading unit capex exceeds fermentation platform costs significantly, limiting deployment to chemical feedstock applications where hydrogenation economics improve.
Fermentation dominates installed capacity; gasification is climbing the fastest as aviation fuel offtake agreements prioritize Fischer-Tropsch pathways.
End User Sector:
Sector-specific fuel certification requirements shape technical service intensity, with transportation buyers demanding chain-of-custody documentation and power generators prioritizing combustion performance guarantees.
- Transportation:Road and aviation fuel distributors source certified low-carbon intensity ethanol and renewable diesel to comply with EU Green Deal mandates and California LCFS requirements. Airlines facing CORSIA deadlines sign long-term offtake contracts bundling physical delivery with verified emissions reduction certificates.
- Power Generation:Stationary combustion applications utilize biogas and renewable syngas from lignocellulosic gasification. Grid operators in Nordic markets prioritize fuel switching timelines aligned with national carbon neutrality targets for 2035.
- Industrial:Process heat and combined heat-and-power applications consume solid biomass and bio-oil derivatives. Cement and steel producers explore biochar integration for emissions reduction where electrification proves technically infeasible.
- Agricultural:On-farm biogas production from crop residues and manure supplies localized energy demand. Mechanization of residue collection and anaerobic digestion units requires equipment financing tailored to seasonal cash flow patterns.
Transportation commands the dominant revenue share; power generation is expanding most quickly as district heating networks convert to renewable gas.
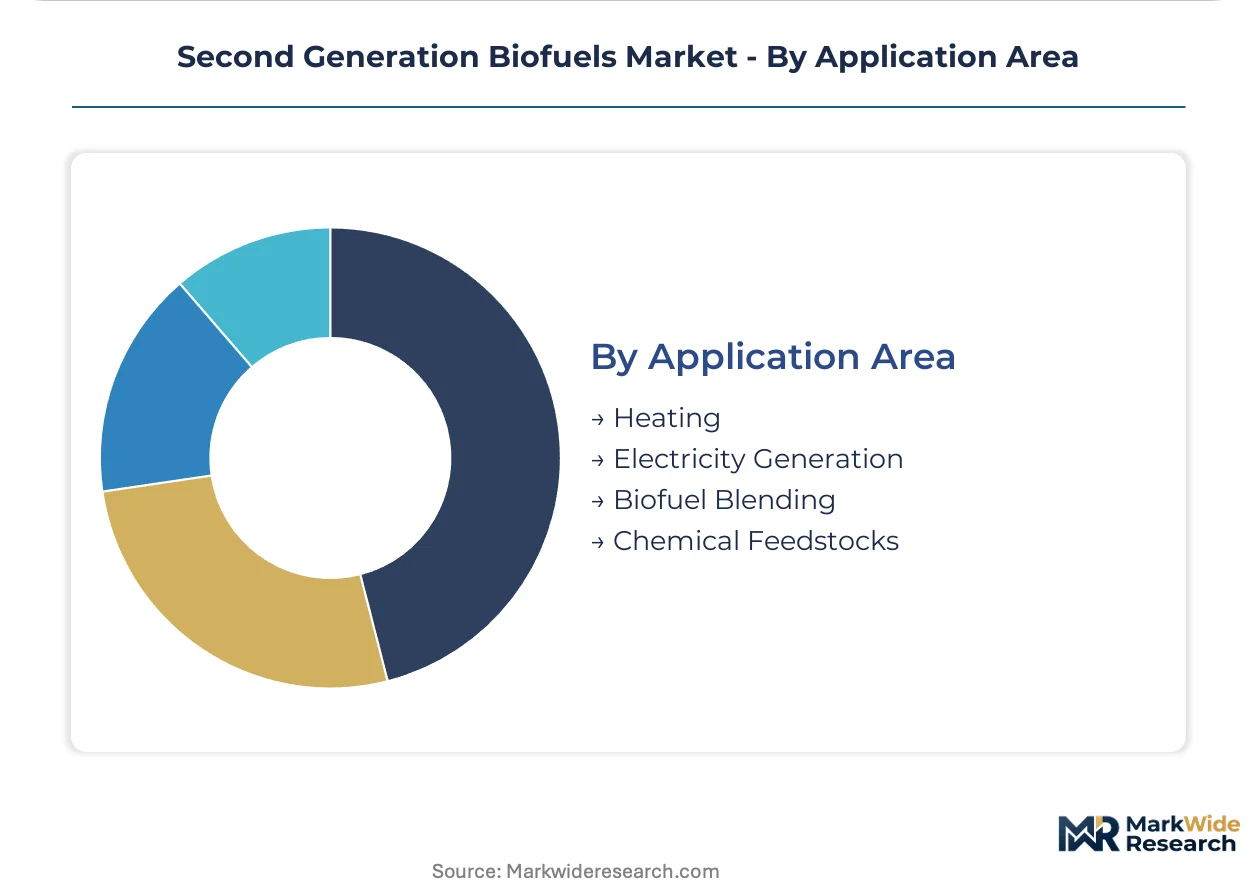
Application Area:
Application-specific performance standards determine aftermarket technical support requirements, with biofuel blending operations needing continuous quality monitoring and chemical feedstock buyers demanding specification consistency.
- Biofuel Blending:Drop-in replacement fuels and high-blend components integrate with existing petroleum distribution infrastructure. India's state-owned oil marketing companies prepare for 20% ethanol blending compliance under developing BIS lignocellulosic standards.
- Chemical Feedstocks:Bio-based platform chemicals including bioethylene and renewable aromatics substitute for petroleum-derived equivalents. Pyrolysis bio-oil upgrading to BTX fractions attracts investment where refinery hydrogen networks enable cost-competitive hydrogenation.
- Electricity Generation:Grid-scale renewable power from biomass combustion and biogas engines serves baseload and dispatchable capacity requirements. Feed-in tariff structures and carbon pricing mechanisms determine project economics across European and Asian markets.
- Heating:Residential and commercial biomass boilers and renewable gas networks displace fossil fuel consumption. Building stock efficiency retrofits and heat pump competition constrain growth in temperate climate zones.
Biofuel blending represents the largest application segment; chemical feedstocks show the steepest expansion trajectory as petrochemical decarbonization accelerates.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Brazilian bagasse-to-ethanol exports flow primarily to European trading houses seeking RenovaBio-certified supply under EU Green Deal mandates. This trade corridor anchors the industry's geographic concentration while drawing project finance into São Paulo state processing clusters.
United States
Cellulosic ethanol offtake from POET-DSM Liberty facility supplies California LCFS compliance markets and aviation fuel distributors. EPA Renewable Fuel Standard mandates escalate advanced biofuel volume obligations annually. The Iowa processing cluster demonstrates continuous enzymatic hydrolysis at commercial scale for road fuel blending.
Brazil
Sugarcane processors retrofit mills with enzymatic hydrolysis trains to convert bagasse into RenovaBio-scored ethanol. ANP certification ties carbon intensity ratings directly to market access for fuel distributors. São Paulo state concentration attracts European trading house capital seeking long-term offtake security.
Germany
Clariant Sunliquid licensees process wheat straw across Brandenburg and Saxony supply chains for EU RED-certified ethanol. The EU Green Deal's revised sustainability criteria enforce chain-of-custody documentation from field to tank. Leipzig-area processing clusters integrate with regional district heating networks converting to renewable gas.
India
State-owned oil marketing companies prepare lignocellulosic ethanol procurement under developing BIS standards for 20% blending compliance. The ethanol blending program expansion prioritizes agricultural residue conversion without food-fuel competition. Maharashtra and Karnataka bagasse processing clusters draw equipment financing from domestic processors.
China
Coastal processing investments explore hydrothermal liquefaction integration with petroleum refinery hydrogen networks. Dual carbon goals accelerate thermochemical pathway development for aviation fuel precursors. Shandong Peninsula clusters test algae-to-fuel convergence with existing chemical industry infrastructure.
Second Generation Biofuels Market Competitive Environment
On the supply side, the industry is consolidating around vertically integrated processors with captive feedstock agreements and continuous operation capabilities. The competitive structure fragments between fermentation platform operators, thermochemical pathway developers, and integrated trading houses securing offtake. Three archetypes dominate: enzyme technology licensors, bagasse retrofit specialists, and aviation fuel certification aggregators. Capacity expansion and strategic partnerships constitute the dominant competitive moves as producers seek to lock in long-term supply contracts with indexed carbon credit mechanisms.
Within the enzyme technology licensor tier, Clariant AG and POET-DSM Advanced Biofuels LLC exemplify platforms demonstrating commercial-scale hydrolysis reliability. Among Brazilian retrofit specialists, GranBio occupies a position anchored to São Paulo state bagasse supply chains. These three entities represent the convergence of biochemical engineering capability with certified supply chain traceability that separates scalable platforms from pilot-scale casualties.
| Leading Market Players |
|---|
| Algenol Biofuels |
| Clariant AG |
| Fiberight LLC |
| GranBio |
| Ineos Group |
| POET-DSM Advanced Biofuels LLC |
| Reliance Industries |
| DuPont |
| Orsted A/S |
| Others |
Value Chain & Pricing Dynamics
Enzyme cost volatility constitutes the dominant risk vector compressing margin spreads across production tiers while simultaneously dictating supply chain geography. Danish and Chinese microbial fermentation capacity concentration forces procurement managers to balance long-term enzyme supply contracts against spot market exposure, with carbon intensity certification premiums widening the pricing gap between certified and uncertified offtake streams.
Pricing Analysis
The first-generation to second-generation pricing gap reflects enzyme loading premiums and RenovaBio carbon intensity scoring differentials. Contract-based long-term offtake agreements dominate, with pricing stratifying across RenovaBio-certified premium, EU RED-compliant standard, and uncertified economy tiers. Cost compression in the standard tier is intensifying because Brazilian bagasse processors are scaling enzymatic hydrolysis trains, squeezing margins for first-generation producers. State-owned oil marketing companies in India exhibit highest price sensitivity due to blending mandate compliance pressures, while European aviation fuel buyers show lowest sensitivity given CORSIA deadline rigidity.
Supply Chain Analysis
Danish enzyme suppliers and Chinese microbial fermentation houses hold concentrated toll manufacturing capacity for cellulase cocktails. Feedstock supply anchors in Brazil, Germany, and India, with equipment fabrication drawing from German and Chinese engineering centers. The supply chain rests on agricultural residue density economics constraining viable collection radii to 50-80 kilometers. Single-source vulnerability pervades the cellobiase supply tier. Distribution runs through vertically integrated processors with captive feedstock agreements rather than merchant spot markets.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Fragmentation across certification standards and feedstock geographies creates niche entry points for specialized operators. The EU Green Deal's transport decarbonization mandates are splintering demand into region-specific compliance buckets that favor localized processing capacity.
For Market Incumbents: Insulate margin position by securing captive bagasse supply agreements in São Paulo state processing clusters and accelerating RenovaBio certification investment ahead of ANP threshold tightening. Enzyme cost volatility from Danish supply chain concentration represents the primary margin threat; backward integration into on-site enzyme production or long-term tolling contracts with alternative microbial fermentation capacity provides defensive leverage. For New Entrants and Emerging Players: Maharashtra and Karnataka bagasse processing clusters in India represent the most penetrable entry point, with state-owned oil marketing companies seeking lignocellulosic ethanol supply for 20% blending compliance under developing BIS standards. Coastal algae-to-fuel thermochemical convergence in China offers secondary white-space where hydrothermal liquefaction integration with petroleum refinery hydrogen networks reduces upfront capex barriers. A licensing partnership with established enzyme technology platforms accelerates time-to-certification. For Investors and Strategic Acquirers: The market sits at a commercial-scale validation phase that favors vertically integrated processors with demonstrated continuous operation reliability. Long-term viability over the next decade hinges on consolidation around platforms achieving 90+ day fermentation run times without contamination events. Acquisition targets should demonstrate captive feedstock supply agreements and indexed carbon credit mechanisms in offtake contracts. The signal to watch is California Air Resources Board pathway verification timeline compression for novel feedstock-process combinations.| Strategic Initiative | Industry Significance |
|---|---|
| Long-term Offtake Agreement | Airlines facing CORSIA deadlines lock in 10-15 year supply bundling physical delivery with verified emissions reduction certificates. |
| Backward Integration into Enzyme Production | POET-DSM Liberty facility demonstrates how on-site cellulase manufacturing reduces variable cost exposure to Danish supply chains. |
| RenovaBio Certification Investment | ANP carbon intensity scoring directly ties fuel certification to Brazilian market access for distributors. |
| Bagasse Processing Retrofit | GranBio's proprietary pre-treatment systems reduce enzyme loading in São Paulo state sugarcane mills. |
| Straw Supply Chain Aggregation Platform | Clariant Sunliquid licensees in Brandenburg leverage digital contracting tools to reduce wheat straw collection coordination costs. |
Study Parameters
Two parallel data streams informed the analysis: primary field engagement with biofuel procurement officers at European trading houses, biochemical engineering leads at enzymatic hydrolysis facilities, ANP regulatory affairs specialists, and aviation fuel sustainability directors; and secondary validation against EPA Renewable Fuel Standard volume obligation data, EU RED implementation reports, ANP RenovaBio certification databases, and BIS lignocellulosic ethanol standard development documents. Bottom-up capacity buildout tracking across Brazilian, German, Indian, and Chinese processing clusters was triangulated against top-down demand modeling from transport sector decarbonization mandates.
Forecast inputs span feedstock type segmentation, production process technology tiers, end-user sector demand patterns, and application area certification requirements across the projection horizon. Modeled dimensions include lignocellulosic biomass versus algae feedstock origins, fermentation versus gasification process economics, transportation versus power generation end-use splits, and biofuel blending versus chemical feedstock application trajectories. CAGRs were derived from facility-level capacity announcements, offtake contract volumes, and regulatory mandate escalation schedules. Enzyme cost curve trajectories and carbon intensity certification timeline compression served as industry-specific forecast sensitivity inputs.
Practitioners should monitor enzyme supply contract renegotiation cycles, ANP RenovaBio threshold adjustments, and California LCFS pathway verification backlogs for early signals of forecast revision. Assumptions underlying capacity utilization rates, contamination event frequencies, and agricultural residue collection cost inflation may shift materially. Quarterly review of announced offtake contract indexed pricing terms and European trading house capital deployment into Brazilian processing clusters is advised to detect inflection.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Brazil Biofuel Market
Biofuels
Biodiesel Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Next Generation Biofuels Market
Biofuels
Biofuel Ethanol Market
Biofuels
United States Biodiesel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Bioethanol Market
Biofuels
Europe Biofuel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Europe Biodiesel Market
Biofuels
Latin America Biodiesel Market
Biofuels
Sweet Sorghum Ethanol Market