
 Biofuels Market | 2026-2036
Biofuels Market Size, Share, and Industry Trends Forecast 2026-2036
Biofuels Market Intelligence
The proliferation of project finance models for large-scale biorefinery construction is reshaping competitive positioning among producers. This capital-intensive environment favors established agricultural processors like Archer Daniels Midland Company, which leverages its vast feedstock supply chain. POET LLC competes on its specialized bioethanol production scale and operational efficiency. Neste Corporation differentiates through its focus on renewable diesel and sustainable aviation fuel derived from waste and residue feedstocks.
Biofuels are liquid or gaseous fuels derived from renewable biological materials, known as biomass. Production relies on distinct pathways like the fermentation of sugars into bioethanol or the transesterification of vegetable oils into biodiesel. While bioethanol from corn and sugarcane dominates road transportation fuel volumes, biodiesel from waste oils is gaining share. The emerging biojet fuel category, targeting the aviation sector, represents a critical area for future growth and investment.
Government mandates are fundamental to market structure, with the US Environmental Protection Agency's Renewable Fuel Standard setting annual volume obligations. The EU's Renewable Energy Directive (RED) establishes blending targets and strict sustainability criteria. Brazil's RenovaBio program incentivizes decarbonization through a national credit-based system. Navigating these diverse and evolving policy landscapes is the central strategic challenge for producers and investors.
Market Dynamics
The central dynamic shaping the biofuels market is the global regulatory push for decarbonization in transportation, creating mandated demand that technology and agricultural supply chains are racing to fulfill. This creates a direct link between policy frameworks and investment in new production capacity.
Growth Catalysts
- Policy Mandates:Government requirements, such as the US Renewable Fuel Standard and Brazil's RenovaBio program, compel the blending of biofuels into the conventional fuel supply, creating a guaranteed and growing market for producers.
- Aviation Sector Decarbonization:The global airline industry’s commitment to reducing its carbon footprint is a primary demand driver for sustainable aviation fuels (SAF), a high-value product category offering significant growth potential.
- Feedstock Diversification:Technological progress in processing non-food biomass, including cellulosic materials and waste oils, expands the available resource base and mitigates competition with food production for land and crops.
Market Restraints
- Feedstock Cost Volatility:The price of key inputs like corn, sugarcane, and vegetable oils is subject to unpredictable fluctuations from weather events, global food demand, and agricultural policy, directly impacting producer margins. * Infrastructure and Fleet Incompatibility: Higher-level biofuel blends can require specialized storage, handling infrastructure, and vehicle engine modifications, which limits their immediate, widespread adoption without significant capital investment.
- Food vs. Fuel Controversy:Persistent debate over the use of agricultural land and food crops for fuel production influences public perception and can lead to less favorable regulatory frameworks or the removal of subsidies.
Strategic Opportunities
- Marine Biofuels:Stricter international maritime emissions standards from the IMO are creating a new, large-scale market for biofuels like renewable diesel and bio-LNG as a compliant alternative to high-sulfur fuel oil for shipping.
- Advanced Biorefineries:Integrating carbon capture and storage (CCS) with biofuel production facilities enables the creation of carbon-negative fuels, which can command premium prices and access lucrative carbon credit markets.
- Waste-to-Fuel Pathways:Development of technologies to convert municipal solid waste, agricultural residues, and industrial off-gases into fuel provides access to a low-cost, aggregated feedstock stream with strong policy support.
Industry Challenges
- Capital Intensity of Biorefineries:The construction of new, large-scale production facilities is extremely capital-intensive, presenting a high barrier to entry and making financing for novel, unproven technologies particularly difficult to secure.
- Supply Chain Logistics:Managing the collection, storage, and transportation of geographically dispersed, low-density biomass feedstocks to a centralized processing plant poses a significant and costly logistical hurdle for producers.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofuels Market |
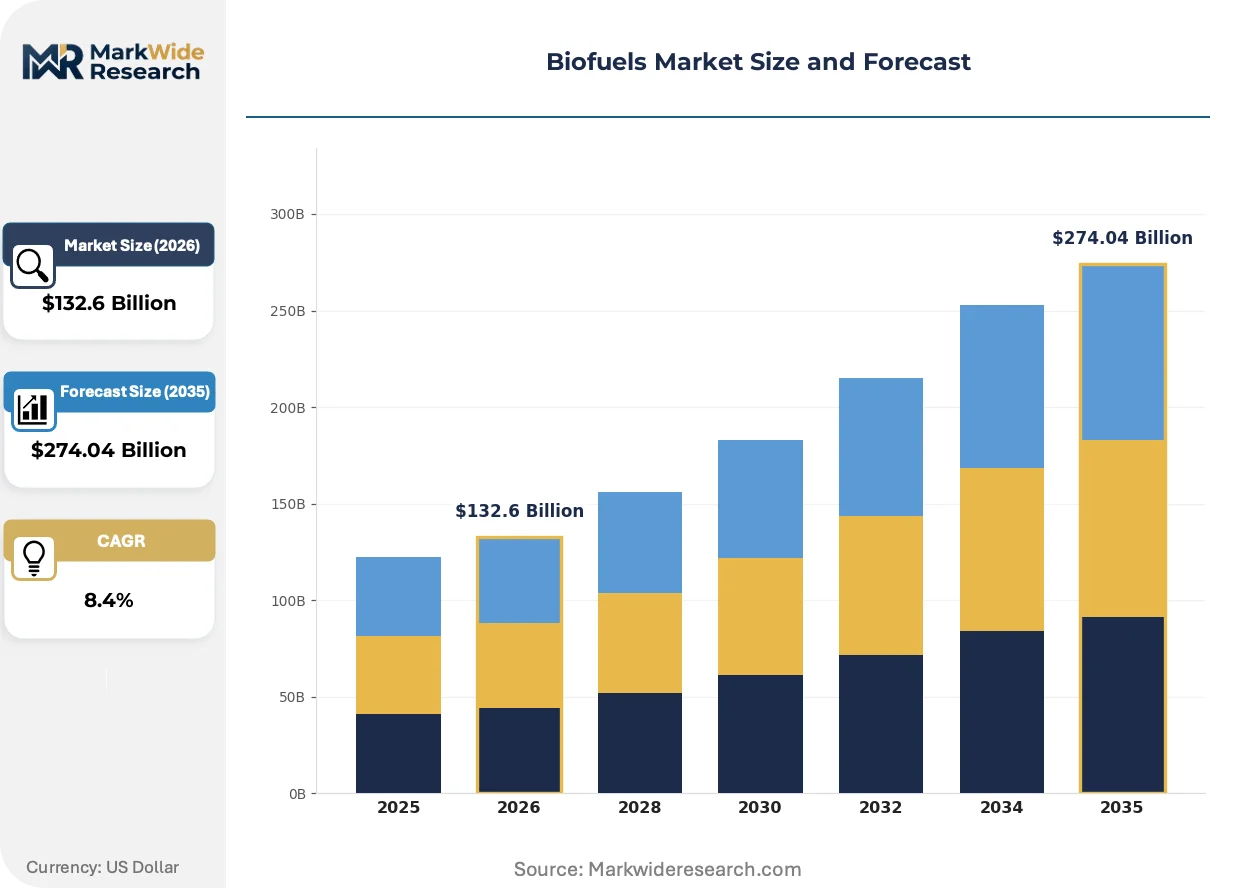
| Market Size in 2026 | $132.6 Billion |
| Market Size in 2035 | $274.04 Billion |
| CAGR (2026 – 2036) | 8.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Type: Bioethanol, Biodiesel, Biogas, Biojet Fuel, Biomethanol Feedstock Source: Sugarcane, Corn, Soybean Oil, Algae, Wood Residues, Waste Oils End Use Industry: Transportation, Power Generation, Marine, Aviation, Chemical Manufacturing Production Technology: Fermentation, Transesterification, Gasification, Pyrolysis, Hydroprocessing |
| Companies Covered | Archer Daniels Midland Company, POET LLC, Neste Corporation, Renewable Energy Group, Inc., Valero Energy Corporation, Petrobras, Royal Dutch Shell plc, Cargill, Incorporated, Green Plains Inc., Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofuels Market Strategic Shifts & Innovations
The transition from first-generation, crop-based fuels to advanced biofuels derived from waste and cellulosic biomass is reshaping the industry's entire value chain. This shift is driven by a convergence of technological breakthroughs, stricter sustainability criteria in regulations, and evolving corporate procurement strategies.
Hydroprocessed Esters and Fatty Acids (HEFA) technology converts waste lipids like used cooking oil and animal fats into high-purity renewable diesel and sustainable aviation fuel. The aviation and heavy-duty transport sectors are rapidly increasing their uptake of these drop-in fuels to meet decarbonization targets. This advancement is rendering obsolete the sole reliance on virgin vegetable oils for high-quality biodiesel, shifting value toward efficient waste collection networks.
Europe's Renewable Energy Directive (RED) establishes stringent lifecycle greenhouse gas emission standards and sustainability criteria for biofuels sold within the EU. This policy directly impacts feedstock sourcing by penalizing fuels derived from high carbon-stock land, such as deforested areas. Producers who historically relied on feedstocks like palm oil are now forced to reconfigure their supply chains toward waste and residue-based inputs to maintain market access.
Airlines are increasingly signing long-term offtake agreements for sustainable aviation fuel (SAF) years before it is produced. This forward-purchasing model circumvents traditional spot markets for jet fuel, providing the revenue certainty required to secure financing for new biorefinery projects. This procurement shift is most visible in North America and Europe, where carriers face intense regulatory and investor pressure to secure future SAF supplies.
Biofuels Market Segmentation
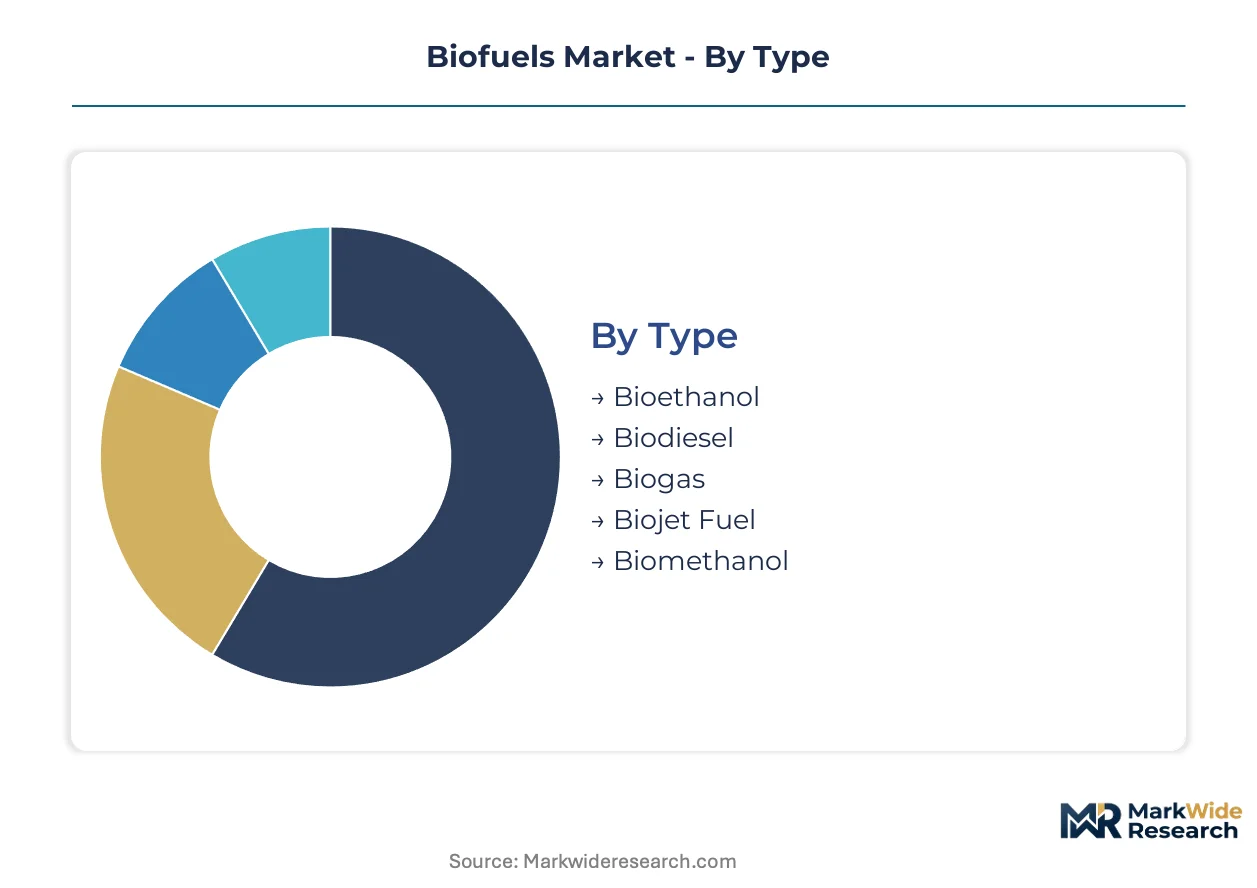
The biofuels market segments across diverse types, feedstock sources, end-use industries, and production technologies. Understanding this segmentation is crucial for producers to align investment with evolving demand patterns and for policymakers to design effective decarbonization strategies. Each segment presents distinct opportunities and challenges.
Type:
The spectrum of biofuel types addresses various energy demands, ranging from established road transportation fuels to emerging solutions for aviation and industrial applications.
- Bioethanol:This alcohol fuel is predominantly produced through the fermentation of sugars from corn or sugarcane. It serves as a primary blending component in gasoline for road vehicles across the US and Brazil, significantly reducing carbon emissions.
- Biojet Fuel:Also known as Sustainable Aviation Fuel (SAF), this category includes various fuel types suitable for jet engines. Airlines in Europe and North America are actively securing long-term supplies to meet stringent decarbonization targets.
- Biodiesel:A fatty acid methyl ester (FAME) produced from vegetable oils or animal fats, commonly used in diesel engines.
- Biogas:A gaseous fuel generated from the anaerobic digestion of organic matter, primarily utilized for power generation and heating.
- Biomethanol:A renewable alcohol derived from biomass or waste, offering potential as a marine fuel or chemical feedstock.
The dominant share belongs to Bioethanol, while Biojet Fuel is expanding most quickly due to aviation sector commitments.
Feedstock Source:
Supply concentration for biofuels heavily influences regional production capabilities and cost structures, with agricultural economies often dictating feedstock availability and pricing.
- Corn:A primary feedstock for bioethanol production, particularly dominant in the United States due to extensive agricultural infrastructure. Its price volatility directly impacts producer margins.
- Waste Oils:This category includes used cooking oil and animal fats, which are critical for producing renewable diesel and SAF. European and North American producers prioritize these feedstocks due to strong sustainability credentials.
- Sugarcane:A highly efficient feedstock for bioethanol, primarily concentrated in Brazil, supporting its national fuel mandates.
- Soybean Oil:A significant feedstock for biodiesel production, especially in North and South America.
- Algae:An emerging, non-food feedstock offering high yields and minimal land use, still in early commercialization stages.
- Wood Residues:Cellulosic biomass from forestry and timber processing, used in advanced biofuel pathways.
Corn currently holds the largest volume share, but Waste Oils are rapidly gaining market traction due to policy support for advanced biofuels.
End Use Industry:
The application focus for biofuels spans various sectors, with each industry presenting unique requirements for fuel specifications and infrastructure compatibility.
- Transportation:This segment encompasses road vehicles, where bioethanol and biodiesel are blended with conventional fuels. Government mandates in countries like the US and Brazil drive significant demand volumes.
- Aviation:The aviation sector relies on sustainable aviation fuels (SAF) to meet ambitious decarbonization goals. Long-term offtake agreements by major airlines in Europe underpin new production capacity.
- Power Generation:Biofuels like biogas and biomass are combusted to produce electricity and heat, particularly in regions with strong renewable energy targets.
- Marine:The shipping industry is exploring biofuels such as renewable diesel and bio-LNG to comply with international emissions regulations from the IMO.
- Chemical Manufacturing:Biofuels can serve as renewable feedstocks for producing various biochemicals and bioplastics, reducing reliance on fossil resources.
The Transportation sector consumes the largest proportion of biofuels, while Aviation is demonstrating the steepest expansion trajectory.
Production Technology:
The maturity level of production technologies dictates scalability and efficiency, impacting the cost-effectiveness and environmental footprint of various biofuel pathways.
- Fermentation:This established biological process converts sugars into bioethanol using yeast or bacteria. It represents a mature technology with widespread commercial application, especially in the US and Brazil.
- Hydroprocessing:A catalytic process that converts vegetable oils, animal fats, and waste lipids into renewable diesel and sustainable aviation fuel. This technology yields high-quality, drop-in fuels with growing adoption in Europe.
- Transesterification:A chemical reaction used to produce biodiesel from vegetable oils or animal fats.
- Gasification:Converts solid biomass into syngas, which can then be processed into liquid fuels or used for power generation.
- Pyrolysis:Thermochemical decomposition of biomass at high temperatures in the absence of oxygen, yielding bio-oil.
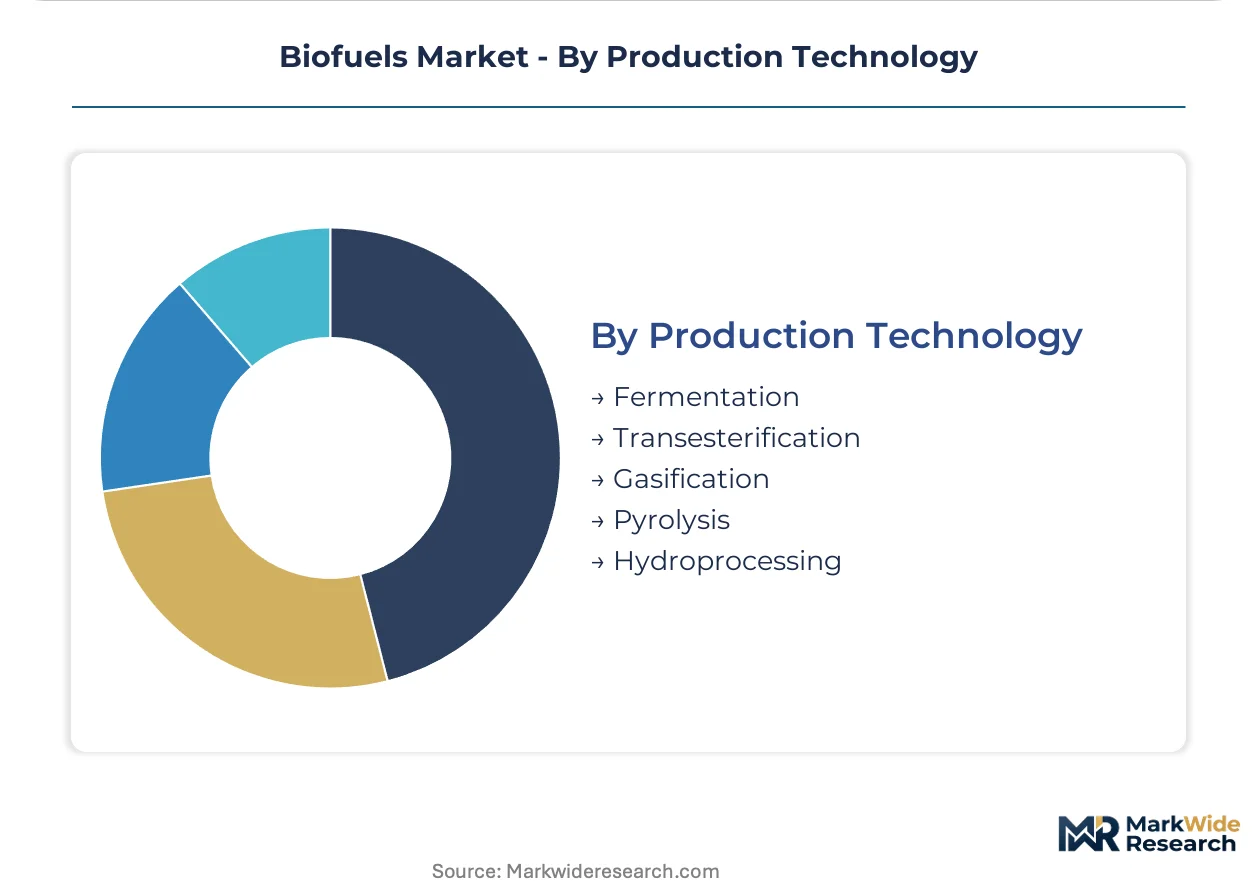
Fermentation remains the most prevalent production method, with Hydroprocessing climbing the fastest due to demand for advanced renewable diesel and SAF.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Regional pricing-power asymmetry exists between established agricultural biofuel producers like Brazil and emerging markets in Europe and Asia. This disparity reflects varied feedstock availability, processing capabilities, and the maturity of regulatory frameworks. Policy mandates in key economies drive localized demand patterns and investment in specific biofuel pathways.
United States
Demand for bioethanol and renewable diesel is robust, driven by the US Environmental Protection Agency's Renewable Fuel Standard. This policy sets annual volume obligations for biofuel blending into the national fuel supply. The Midwest, particularly states like Iowa and Illinois, forms a production gravity center for corn-based ethanol, benefiting from extensive agricultural infrastructure.
Brazil
Sugarcane-based ethanol dominates the transportation fuel sector, supported by the national RenovaBio program which incentivizes decarbonization. This program creates a credit-based system rewarding lower carbon intensity fuels. São Paulo state anchors the primary production and processing cluster for sugarcane ethanol, leveraging significant land resources and established biorefineries.
Germany
The European Union's Renewable Energy Directive (RED) strongly influences biofuel consumption and sustainability criteria, prioritizing advanced biofuels from waste and residues. Germany's national policies align with RED, fostering demand for renewable diesel and sustainable aviation fuel. The Rhine-Ruhr region and northern port cities are developing hubs for advanced biorefinery projects and waste oil processing.
India
Expanding energy demand and national decarbonization goals are catalyzing interest in biofuels, particularly bioethanol for gasoline blending. The Indian government's Ethanol Blending Program aims to reduce crude oil imports and agricultural waste. States like Uttar Pradesh and Maharashtra are key agricultural centers, positioning them for increased ethanol production from sugarcane and other feedstocks.
China
China's strategic push for energy security and environmental protection fuels interest in biofuels, with a focus on bioethanol and advanced pathways. Government policies support the development of non-food cellulosic ethanol and waste-to-fuel technologies. The eastern coastal provinces, with their industrial clusters and waste generation, are emerging as sites for new advanced biorefinery investments.
Biofuels Market Key Industry Players
Platform integrators command the system tier; component specialists sit upstream in the biofuels value chain. The market structure exhibits a tiered consolidation, with large agricultural processors and energy companies holding significant feedstock and distribution advantages. Strategic archetypes include integrated agricultural giants, specialized biofuel producers, and diversified energy companies.
Integrated agricultural processors, such as Archer Daniels Midland Company, exemplify a strategy leveraging vast feedstock supply chains and existing processing infrastructure. Specialized bioethanol producers, like POET LLC, occupy a position focused on scale and operational efficiencies within specific biofuel pathways. Neste Corporation represents a diversified energy company differentiating through its focus on renewable diesel and sustainable aviation fuel derived from waste and residue feedstocks.
| Leading Market Players |
|---|
| Archer Daniels Midland Company |
| POET LLC |
| Neste Corporation |
| Renewable Energy Group, Inc. |
| Valero Energy Corporation |
| Petrobras |
| Royal Dutch Shell plc |
| Cargill, Incorporated |
| Green Plains Inc. |
Cost & Logistics Intelligence
Corn concentration in the United States and sugarcane in Brazil anchor significant biofuel production, directly influencing global bioethanol pricing and the profitability of downstream blending operations. This supply concentration impacts feedstock availability for other regions.
Pricing Analysis
Configured-to-order pricing for sustainable aviation fuels (SAF) and renewable diesel commands a premium over standard commodity bioethanol due to stringent certification requirements. Price differentiation stems from feedstock sustainability credentials and the carbon intensity score of the final product. Pricing pressure stems from unpredictable feedstock cost volatility, particularly for agricultural commodities like corn and vegetable oils. The road transportation sector, heavily reliant on bioethanol and biodiesel, exhibits higher price sensitivity compared to the aviation sector prioritizing SAF to meet decarbonization targets.
Supply Chain Analysis
Feedstock cost volatility, driven by weather events and global food demand, presents a significant supply chain risk for biofuel producers. Geographic supply concentrates in the United States for corn-based ethanol and Brazil for sugarcane ethanol, while Europe increasingly sources waste oils and animal fats. Raw material dependencies center on agricultural crops like corn, sugarcane, and soybeans, alongside waste lipids. The distribution model primarily involves blending biofuels into conventional fuel supplies through existing infrastructure or direct long-term offtake agreements for specialized fuels.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
The biofuels market presents a fragmentation opportunity, with aviation sector decarbonization creating distinct niches for sustainable aviation fuels. This shift encourages specialized production pathways and regional supply chain optimization.
For Market Incumbents:Entrench existing market share through strategic investments in advanced biorefining technologies capable of processing diverse feedstocks. Secure long-term feedstock supply contracts to mitigate the threat of commodity price volatility and ensure operational stability. Expand capacity in key agricultural regions like the US Midwest to leverage existing infrastructure. Pursue vertical integration into waste feedstock aggregation to control supply and enhance sustainability credentials.
For New Entrants and Emerging Players:Underpenetration in marine biofuels offers a significant white-space target for new entrants focusing on renewable diesel and bio-LNG. Target waste-to-fuel pathways in regions with strong regulatory support, such as European port cities with robust waste collection networks. The most penetrable segment lies in specialized, high-value fuels like SAF, where long-term offtake agreements provide revenue certainty. A compelling go-to-market angle involves developing carbon-negative fuel solutions by integrating carbon capture and storage technologies.
For Investors and Strategic Acquirers:Capital is best deployed toward companies with proven advanced biorefining technologies and established waste feedstock supply chains for long-term viability. Focus on targets demonstrating strong intellectual property in cellulosic or waste-to-fuel conversion. The long-term viability of the market is anchored in global decarbonization mandates, ensuring sustained demand over the next decade. A critical signal to watch is the increasing volume of long-term SAF offtake agreements, indicating market maturity and investment security.
| Strategic Initiative | Industry Significance |
|---|---|
| Invest in Advanced Biorefineries | Enhances feedstock flexibility and enables production of high-value sustainable aviation fuels. |
| Secure Long-Term Feedstock Contracts | Mitigates price volatility risks for agricultural inputs like corn and sugarcane. |
| Develop Carbon Capture Integration | Creates carbon-negative fuels, accessing premium pricing and carbon credit markets. |
| Expand Waste-to-Fuel Production | Diversifies feedstock sources and aligns with stricter sustainability criteria in Europe. |
| Forge SAF Offtake Agreements | Provides revenue certainty essential for financing new capital-intensive biorefinery projects. |
Research Approach
A standing panel of biorefinery plant managers, feedstock procurement specialists, airline sustainability officers, and government policy analysts provided ongoing calibration throughout the research process. This primary insight was rigorously combined with secondary validation from sources including EPA RFS data, EU RED reports, IEA biofuel statistics, and company sustainability reports. The analysis employed both bottom-up and top-down triangulation to ensure data robustness.
The analytical framework utilized scenario-bracketing to model market evolution across the projection horizon. Segmentation dimensions modeled included biofuel type, feedstock source, end-use industry, production technology, and carbon intensity score. Compound annual growth rates were derived by integrating historical trends, current policy projections, and anticipated technological adoption rates. Key industry-specific forecast inputs included mandated biofuel blending obligations and sustainable aviation fuel production targets.
The forecast holds incumbent behavior within observed patterns; aggressive moves by major energy companies or rapid technological breakthroughs would shift outcomes. Forecasts reflect assumptions regarding regulatory stability and global economic conditions. Continuous validation against operating reality is the recommended discipline.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Brazil Biofuel Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Biodiesel Market
Biofuels
Europe Biodiesel Market
Biofuels
Second Generation Biofuels Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Biofuel Ethanol Market
Biofuels
Latin America Biodiesel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
United States Biodiesel Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Next Generation Biofuels Market
Biofuels
South-East Asia Biodiesel Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
Bioethanol Market