
 Biofuel Ethanol Market | 2026-2036
Biofuel Ethanol Market Size, Share, and Industry Trends Forecast 2026-2036
Biofuel Ethanol Market Insights
Platform licensing for cellulosic conversion technology is tilting toward integrated biorefinery operators with captive feedstock access. POET LLC leverages its vertical network of corn ethanol plants to anchor downstream bioproduct diversification. Archer Daniels Midland Company sustains one of the largest fermentation-based production footprints in North America. Valero Energy competes through its petroleum-ethanol hybrid refining model, blending fuel distribution with biofuel manufacturing scale.
Biofuel ethanol denotes a renewable oxygenate fuel produced primarily through yeast fermentation of starch or sugar feedstocks, yielding a minimum purity of 99% ethyl alcohol by volume before denaturing for commercial use. Its primary industrial purpose centers on octane enhancement and carbon monoxide emission reduction when blended with gasoline at ratios ranging from E10 to E85. Corn feedstock dominates existing capacity, though cellulosic sources are gaining structural attention as enzyme cost curves flatten and lignocellulosic pretreatment yields improve. Transportation application leads volume absorption, while power generation represents a smaller but expanding outlet for stationary engine fuel substitution.
The U.S. EPA administers Renewable Fuel Standard volume obligations that directly determine domestic blending mandates and compliance credit pricing. Brazil's ANP enforces RenovaBio carbon intensity targets, while the EU Green Deal and F-Gas Regulation shape import eligibility and sustainability certification requirements for European market access. Stakeholders must monitor feedstock cost volatility against policy certainty timelines when committing capital to next-generation production platforms.
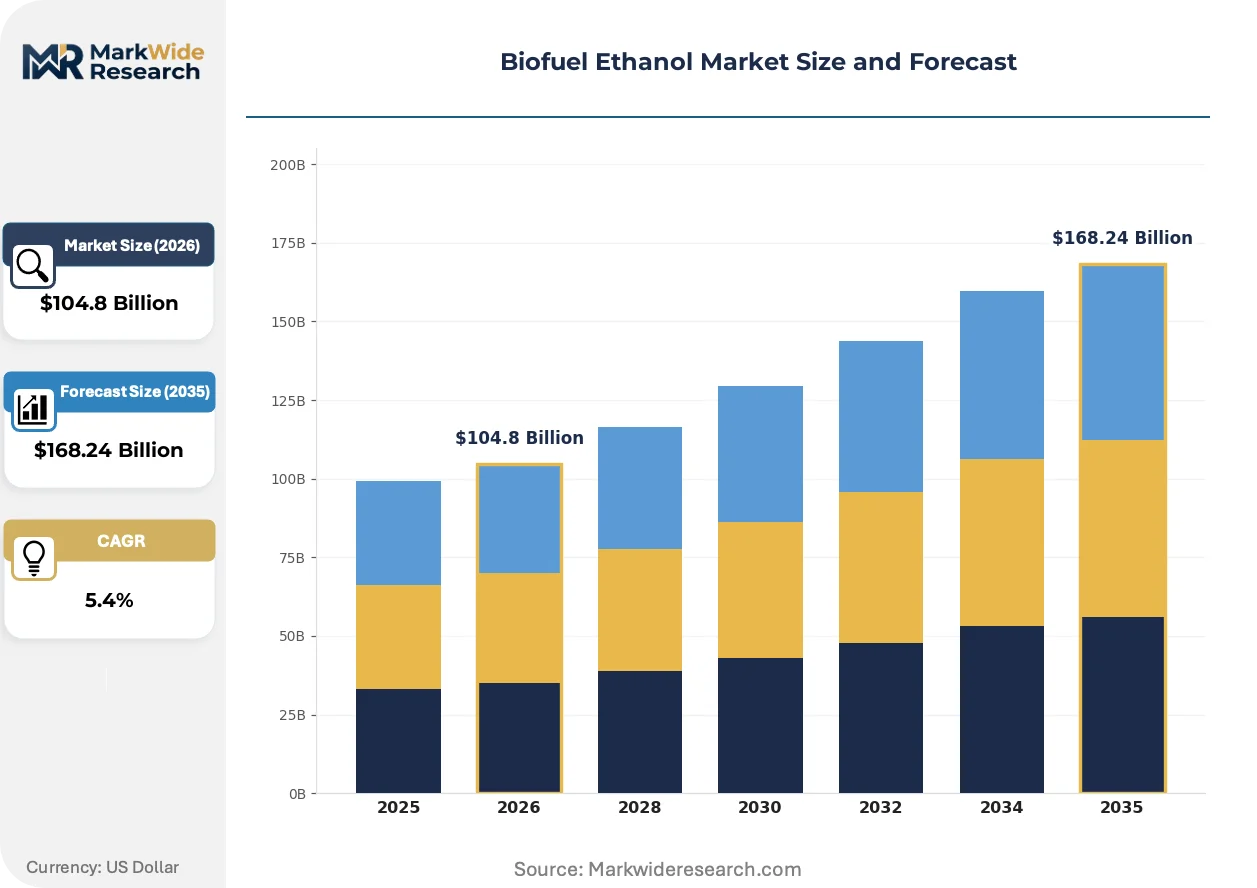
Market Dynamics
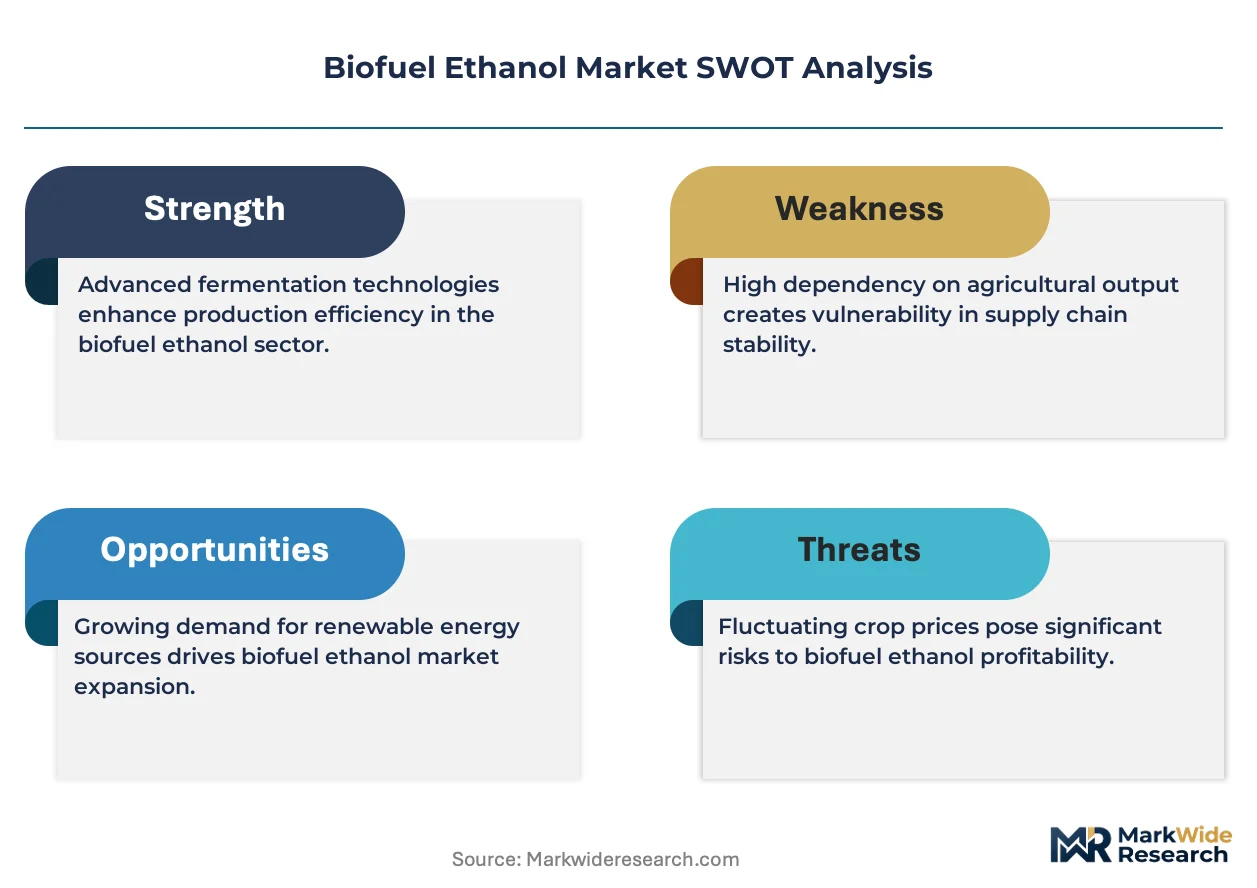
Cellulosic conversion economics are tightening the competitive perimeter around first-generation ethanol producers, forcing capital redeployment toward enzyme efficiency and feedstock flexibility rather than scale expansion alone.
Growth Catalysts
- RenovaBio carbon intensity targets:Brazil's ANP enforcement mechanism creates compliance-driven offtake for certified low-carbon ethanol, redirecting investment toward process efficiency upgrades and methane capture systems.
- Sugarcane bagasse valorization:Second-generation processing streams in Sao Paulo state are unlocking lignocellulosic conversion at commercial scale, expanding feedstock utilization rates without acreage expansion.
- E15 blending authorization:The U.S. EPA's year-round sales permission for higher ethanol blends is opening gasoline station infrastructure retrofits and flex-fuel vehicle compatibility investments across Midwest distribution networks.
Market Restraints
- Corn price volatility:Drought cycles and fertilizer cost spikes in Illinois and Iowa directly compress crush margins for dry-mill operators dependent on single-feedstock configurations.
- Cellulosic enzyme cost structure:Cellobiohydrolase and endoglucanase formulations remain prohibitively expensive for standalone biorefinery economics, constraining next-generation capacity announcements.
- Gasoline demand plateau:Electric vehicle penetration in California and New York is eroding the addressable pool for liquid fuel blending, capping long-term volume growth assumptions.
Strategic Opportunities
- Sustainable aviation fuel qualification:ASTM D7566 certification pathways for alcohol-to-jet processing are opening offtake contracts with Delta and United Airlines seeking scope 3 emissions reductions.
- Carbon capture and sequestration integration:45Q tax credit eligibility for fermentation CO2 capture is incentivizing pipeline partnerships with Dakota and Illinois storage formations.
- Marine fuel substitution:IMO 2020 sulfur regulations are positioning ethanol as a marine gasoline blendstock for coastal vessel operators in Rotterdam and Singapore bunkering hubs.
Industry Challenges
- Enzyme biochemist talent scarcity:Commercial-scale cellulosic operations require specialized protein engineering expertise concentrated at limited Midwest research universities, constraining workforce scaling.
- RIN price volatility management:Renewable Identification Number credit trading fluctuations complicate multi-year offtake contract structuring and project finance underwriting.
Report Scope
MarkWide Research| Attributes | Details |
|---|---|
| Report Title | Biofuel Ethanol Market |
| Market Size in 2026 | $104.8 Billion |
| Market Size in 2035 | $168.24 Billion |
| CAGR (2026 – 2036) | 5.4% |
| Historical Year | 2020-2024 |
| Base Year | 2025 |
| Forecast Period | 2026-2036 |
| Segmentation | Feedstock Type: Corn, Sugarcane, Cellulosic, Wheat Production Technology: Fermentation, Enzymatic Hydrolysis, Gasification, Anaerobic Digestion Application: Transportation, Power Generation, Industrial Use, Chemical Manufacturing Distribution Channel: Direct Sales, Wholesale, Retail, Online |
| Companies Covered | POET LLC, Archer Daniels Midland Company, Valero Energy, Green Plains Inc., Cargill, Alto Ingredients Inc., Raizen, Tereos, Verbio Vereinigte Bioenergie AG, Others |
| Regions Covered | North America: US, Canada, Mexico Europe: Germany, Italy, France, UK, Spain, Denmark, Sweden, Austria, Belgium, Finland, Turkey, Poland, Russia, Greece, Switzerland, Netherlands, Norway, Portugal, Rest of Europe Asia Pacific: China, Japan, India, South Korea, Indonesia, Malaysia, Kazakhstan, Taiwan, Vietnam, Thailand, Philippines, Singapore, Australia, New Zealand, Rest of Asia Pacific South America: Brazil, Argentina, Colombia, Chile, Peru, Rest of South America Middle East & Africa: Saudi Arabia, UAE, Qatar, South Africa, Israel, Kuwait, Oman, North Africa, West Africa, Rest of MEA |
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Biofuel Ethanol Market Trends and Innovations
Process intensification and digital control systems are compressing unit capital costs while regulatory carbon accounting is rewriting feedstock sourcing protocols across major producing jurisdictions.
Continuous enzymatic hydrolysis systems are digitizing pretreatment reactor operations, enabling real-time viscosity monitoring and enzyme dosing optimization. POET and ADM pilot facilities in Iowa and Nebraska are deploying these platforms to reduce residence times and improve cellulose-to-glucose conversion yields. The structural consequence is digitizing the boundary between first-generation and second-generation process economics, accelerating hybrid facility designs.
The EU F-Gas Regulation and delegated acts under the Renewable Energy Directive are imposing sustainability certification requirements on imported ethanol, mandating verified greenhouse gas savings and land-use change documentation. European fuel distributors are now screening Brazilian and U.S. supply against these criteria, redirecting trade flows toward certified low-carbon pathways. This regulatory layer most affects sugarcane ethanol shipments to Rotterdam and Hamburg, forcing mill-level traceability investments.
Fleet operators and fuel retailers are consolidating procurement around long-term fixed-price contracts with embedded carbon intensity guarantees, displacing spot market purchasing. Marathon Petroleum and BP Products North America are structuring these agreements directly with biorefinery operators, bypassing traditional merchant intermediaries. This pattern is most visible in California's Low Carbon Fuel Standard compliance market, where credit stacking and book-and-claim accounting favor direct producer relationships.
Biofuel Ethanol Market Segmentation
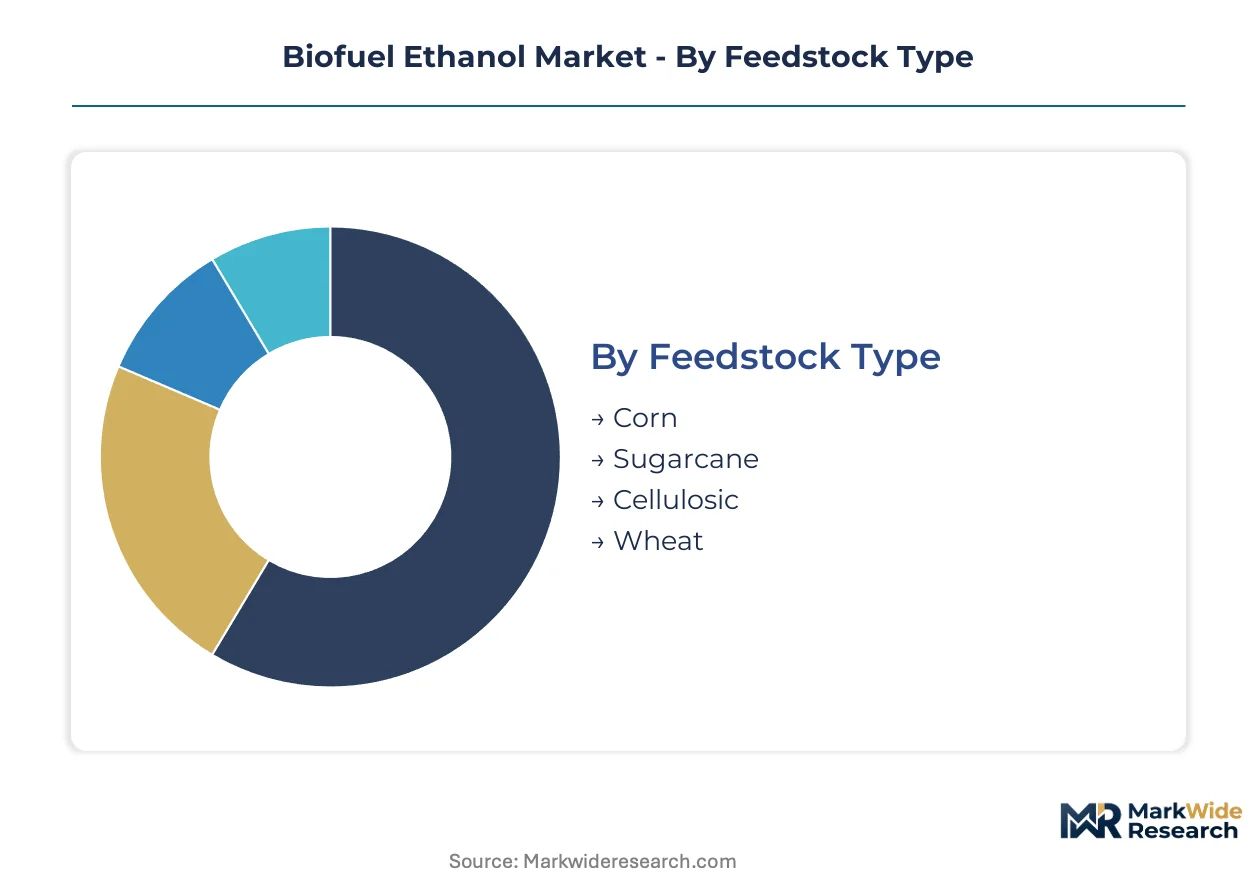
Feedstock chemistry and production technology determine carbon intensity scores that gate regulatory compliance across major blending markets. Application mix shifts between transportation fuel and industrial offtake reshape margin structures and capital deployment timelines for biorefinery operators.
Feedstock Type:
The use-case spectrum spans high-volume starch conversion for established fuel blending and emerging lignocellulosic pathways targeting aviation and marine fuel qualification.
- Corn:Starch-based dry-mill fermentation dominates installed capacity across the U.S. Midwest, with Illinois and Iowa crush margins directly tethered to fertilizer cost cycles and EPA Renewable Fuel Standard volume obligations.
- Sugarcane:Cane juice and molasses fermentation in Brazil's Sao Paulo state delivers the lowest carbon intensity ethanol commercially available, securing preferential access to California's Low Carbon Fuel Standard credit markets and EU import quotas.
- Cellulosic:Agricultural residue and energy crop conversion remains enzyme-constrained, with commercial-scale operations concentrated around POET-DSM joint ventures and Beta Renewables licensing in the U.S. and Italy.
- Wheat:European biorefineries in France and Germany deploy wheat starch as a regional alternative to corn, with Mercosur trade dynamics influencing feedstock switching decisions.
Established volume favors corn; emerging adoption favors cellulosic pathways.
Production Technology:
Cost tier differentiation separates mature fermentation infrastructure from capital-intensive next-generation platforms requiring enzyme or thermochemical breakthroughs.
- Fermentation:Yeast-based sugar-to-ethanol conversion at 99.5% purity represents the baseline economics against which all alternative pathways compete, with ADM and Valero operating the largest North American fermentation footprints.
- Enzymatic Hydrolysis:Cellulase cocktails break lignocellulosic bonds prior to fermentation, with Novozymes and DuPont licensing enzyme packages that still comprise 40-50% of second-generation operating costs.
- Gasification:Thermochemical syngas routes enable municipal solid waste and woody biomass conversion, though commercial scale remains limited to Enerkem and LanzaTech demonstration facilities.
- Anaerobic Digestion:Wet organic waste streams produce biogas upgradable to ethanol via methanol intermediates, with European agricultural digesters exploring this pathway for manure valorization.
Fermentation retains margin dominance; enzymatic hydrolysis claims the steepest expansion trajectory contingent on protein engineering cost reduction.
Application:
Volume concentration in road transport fuel blending is diversifying toward aviation and marine displacement as electrification erodes gasoline demand in California and New York.
- Transportation:E10 and E15 gasoline blending absorbs the majority of global output, with Brazil's flex-fuel fleet and U.S. Midwest distribution infrastructure anchoring offtake density.
- Power Generation:Stationary engine fuel substitution for diesel gensets is expanding in rural India and Southeast Asian island grids where grid connectivity remains unreliable.
- Industrial Use:Boiler fuel and process heat applications in food processing and textile manufacturing leverage ethanol's clean combustion profile where natural gas infrastructure is absent.
- Chemical Manufacturing:Ethylene dehydration for polyethylene production and solvent applications compete with petrochemical routes, with Braskem's bio-based polyethylene in Brazil demonstrating commercial viability.
Transportation commands current volume; chemical manufacturing offers the highest value-per-liter upside.
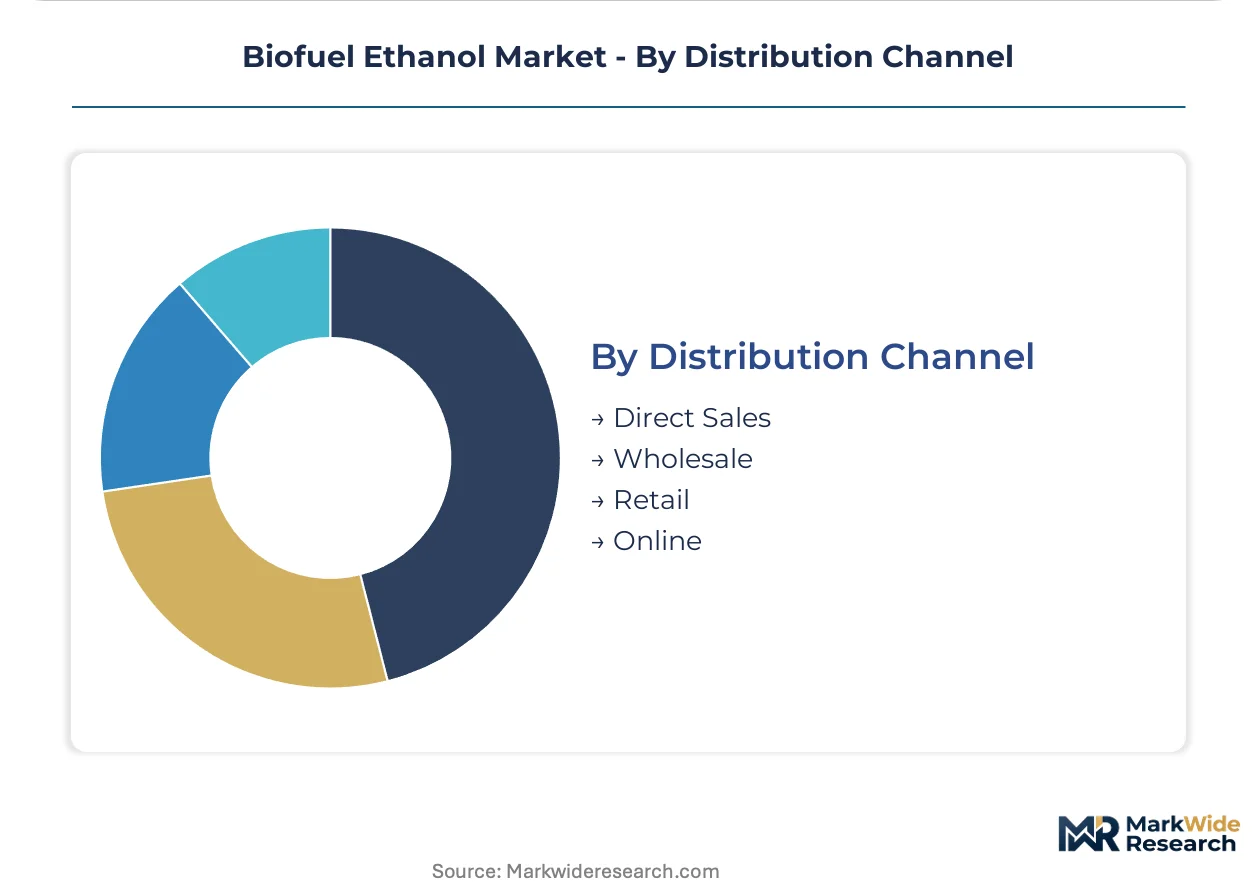
Distribution Channel:
Customer type stratification reflects the divergence between compliance-driven fleet procurement and spot market liquidity for merchant ethanol trading.
- Direct Sales:Long-term offtake contracts between biorefineries and obligated parties—Marathon Petroleum, BP Products North America—bypass intermediaries and embed carbon intensity guarantees required for LCFS compliance.
- Wholesale:Terminal and rack sales through Houston and Rotterdam storage hubs enable arbitrage between Brazilian, U.S., and European price benchmarks.
- Retail:Branded E85 pump networks and flex-fuel station retrofits in the U.S. Midwest serve consumer vehicle fleets, with sheetz and Casey's General Stores expanding ethanol-compatible infrastructure.
- Online:Digital procurement platforms for industrial and chemical buyers remain nascent, with spot price transparency limited relative to petroleum product exchanges.
Direct sales concentrate value capture; wholesale maintains liquidity for price discovery.
Need this report tailored to your region?
Request specific countries, segments, or companies — tailored to your requirements.
Regional Outlook
Buyers in Brazil exhibit the lowest price elasticity, absorbing premiums for certified low-carbon ethanol under RenovaBio compliance. U.S. Midwest purchasers show moderate sensitivity, responding to crush margin compression through operational adjustments. European importers demonstrate the highest elasticity, switching between Brazilian and U.S. supply based on carbon intensity certification costs.
United States
Midwest corn belt concentration drives volume, with Illinois and Iowa processing plants consuming over 40 percent of domestic corn supply for ethanol production. EPA Renewable Fuel Standard volume obligations determine annual blending mandates and compliance credit pricing. POET LLC operates integrated biorefinery networks across South Dakota and Iowa, anchoring first-generation capacity expansion.
Brazil
Sao Paulo state flex-fuel fleet penetration exceeds 80 percent, creating inelastic demand for hydrous ethanol at retail pumps. ANP RenovaBio carbon intensity targets redirect investment toward methane capture and process efficiency upgrades. Raizen and Tereos operate integrated sugarcane mills in the Ribeirão Preto cluster, expanding bagasse-fired cogeneration capacity.
Germany
Wheat-based biorefineries in Lower Saxony and Baden-Württemberg serve regional fuel blending and chemical manufacturing offtake. EU Renewable Energy Directive delegated acts impose sustainability certification requirements on domestic and imported supply. VERBIO Vereinigte Bioenergie AG operates multi-feedstock facilities in Saxony-Anhalt, integrating agricultural residue processing.
India
Maharashtra and Uttar Pradesh sugar mills pivot toward ethanol production under the Ethanol Blended Petrol program, targeting 20 percent blending by 2025. Ministry of Petroleum and Natural Gas procurement tenders fix offtake prices, reducing price volatility for distilleries. Pune-based processing clusters expand molasses and grain-based capacity to meet state-level supply commitments.
Canada
Saskatchewan and Alberta wheat and corn supply chains feed prairie biorefineries serving provincial renewable fuel mandates. Environment and Climate Change Canada Clean Fuel Regulations establish carbon intensity benchmarks for liquid transportation fuels. Greenfield capacity announcements in Manitoba target export positioning toward U.S. Midwest distribution terminals.
Biofuel Ethanol Market Competitive Landscape
Capability concentration sits with integrated biorefinery operators possessing captive feedstock networks; scale advantage sits with petroleum-ethanol hybrid refiners leveraging existing fuel distribution infrastructure. The market structure tiers between first-generation dry-mill specialists and second-generation technology licensors. Strategic archetypes include vertical feedstock integrators, fermentation-scale operators, and carbon-capture platform developers. Dominant competitive moves encompass biorefinery retrofit investments and direct offtake contract structuring with obligated fuel distributors.
Among North American ethanol specialists, POET LLC, Archer Daniels Midland Company, and Valero Energy occupy positions across the capability-scale spectrum. POET exemplifies the vertically integrated archetype through Midwest corn processing networks. Archer Daniels Midland represents fermentation-scale dominance with multi-feedstock operational flexibility. Valero anchors the petroleum-ethanol hybrid model, blending fuel distribution with biorefinery manufacturing scale.
| Leading Market Players |
|---|
| POET LLC |
| Archer Daniels Midland Company |
| Valero Energy |
| Green Plains Inc. |
| Cargill |
| Alto Ingredients Inc. |
| Raizen |
| Tereos |
| Verbio Vereinigte Bioenergie AG |
| Others |
Pricing and Supply Chain Analysis
Sao Paulo state's integrated sugarcane mill complexes anchor global ethanol supply concentration, translating feedstock proximity into pricing power over European importers facing EU F-Gas Regulation carbon intensity compliance costs. Crush margin dynamics in Brazil's Ribeirão Preto cluster directly transmit to Rotterdam and Hamburg spot benchmarks, while U.S. Midwest corn belt volatility feeds through EPA Renewable Fuel Standard credit pricing mechanisms.
Pricing Analysis
Long-term offtake contracts with embedded carbon intensity guarantees now drive lifetime value beyond spot commodity trading, with Marathon Petroleum and BP Products North America structuring direct producer relationships that bypass merchant intermediaries. Price differentiation rests on RenovaBio certification tiers and California Low Carbon Fuel Standard credit stacking eligibility, with Brazilian sugarcane ethanol commanding premiums over U.S. corn-based supply. Pricing pressure stems from electric vehicle penetration eroding gasoline blending pools in California and New York. Fleet operators demonstrate lowest price sensitivity due to compliance mandates; spot market traders show highest sensitivity to RIN volatility.
Supply Chain Analysis
Supplier-financing facilities extended by POET LLC and Archer Daniels Midland Company to captive corn growers in Illinois and Iowa stabilize feedstock flows through harvest price volatility. Geographic supply concentrates in Brazil, the United States, and India, with Maharashtra and Uttar Pradesh sugar mills expanding under Ethanol Blended Petrol program procurement tenders. Raw material dependencies center on corn starch, sugarcane juice and molasses, and cellulosic enzyme formulations. Supply chain risk manifests as single-source vulnerability for Novozymes and DuPont enzyme packages comprising 40-50 percent of second-generation operating costs. Distribution runs through Houston and Rotterdam storage hubs enabling arbitrage between Brazilian, U.S., and European price benchmarks.
Get the full picture before you read further.
Download a free sample with table of contents, companies, segments, and methodology.
Analyst Recommendations
Carbon capture and sequestration integration services represent the fastest-expanding recurring-revenue layer, with 45Q tax credit eligibility for fermentation CO2 capture outpacing hardware margin growth across the analysis window.
For Market Incumbents: Harden biorefinery retrofit investments against cellulosic conversion economics tightening the competitive perimeter, prioritizing enzyme efficiency partnerships with Novozymes over scale expansion alone. Deepen upstream control over corn supply networks in South Dakota and Iowa to defend crush margins against drought-cycle volatility threatening Illinois and Iowa dry-mill operators. For New Entrants and Emerging Players: Establish a beachhead in sustainable aviation fuel qualification pathways, where ASTM D7566 certification gaps create penetrable white space for alcohol-to-jet processing ventures. Target marine fuel substitution applications in Rotterdam and Singapore bunkering hubs, leveraging IMO 2020 sulfur regulations positioning ethanol as coastal vessel blendstock. For Investors and Strategic Acquirers: Mid-cycle technology positioning favors integrated biorefinery operators with captive feedstock access and carbon capture platform development capabilities over standalone fermentation-scale players. Acquisition targets should demonstrate verified greenhouse gas savings documentation for EU Renewable Energy Directive compliance. The signal to watch is RenovaBio carbon intensity target enforcement tightening, redirecting capital toward methane capture systems and process efficiency upgrades.| Strategic Initiative | Industry Significance |
|---|---|
| Cellulosic Conversion Retrofit | Enzymatic hydrolysis deployment at POET-DSM joint ventures bridges first and second-generation economics. |
| Carbon Capture Integration | 45Q tax credit eligibility drives pipeline partnerships with Dakota and Illinois storage formations. |
| RenovaBio Certification Investment | ANP carbon intensity compliance secures preferential California LCFS credit market access. |
| Direct Offtake Contract Structuring | Marathon Petroleum and BP Products North America bypass intermediaries for LCFS compliance. |
| Sustainable Aviation Fuel Qualification | ASTM D7566 pathways open Delta and United Airlines scope 3 emissions reduction contracts. |
Research Methodology
Findings reconcile primary fieldwork against secondary review of EPA Renewable Fuel Standard volume obligation filings, ANP RenovaBio compliance databases, and EU F-Gas Regulation delegated acts. Primary interviews with biorefinery operations managers, fuel procurement officers at obligated parties, enzyme technology licensing directors, and carbon accounting verification specialists combined with customs trade data and SEC 10-K disclosures from integrated petroleum-ethanol hybrid refiners. Bottom-up capacity assessments across Illinois, Iowa, and Sao Paulo state facilities triangulated against top-down demand modeling for E10, E15, and E85 blending pools.
Forecast inputs include feedstock cost curves for corn and sugarcane, enzyme price trajectories for cellobiohydrolase and endoglucanase formulations, and regulatory volume obligation schedules across the projection horizon. Segmentation dimensions span feedstock chemistry, production technology maturity, application mix between transportation and chemical manufacturing, and distribution channel structure. CAGRs derive from scenario-weighted blending mandate trajectories and electrification erosion rates for gasoline demand.
Sensitivities concentrate around EPA volume obligation revisions, ANP enforcement intensity for carbon intensity targets, and cellulosic enzyme cost breakthrough timelines. Forecasts reflect documented assumptions on policy continuity and technology cost curves. Macroeconomic, regulatory, or technological deviation would prompt revision.
Need Custom Data?
Can't find what you're looking for? Our analysts can build a custom report tailored to your exact requirements.
1,000+
Global Clients
150+
Countries Covered
65,000+
Reports Available
Frequently Asked Questions
Why Work With MWR
Trusted by 1,000+ businesses across 150+ countries for high-stakes market decisions.
Ready to access intelligence that moves business?
Browse Reports →Trusted by Global Leaders
From Fortune-level organizations to global SMEs, we provide intelligence for high-stakes decisions.
Multi-Language Support
Research available in French, German, Spanish, Chinese, and more.
ISO & IAF Certified
Globally aligned quality standards ensuring methodological discipline and data integrity.
Competitive Relevance
Free inclusion of 3–4 additional companies of your choice in every report.
Customized Insights
Tailored intelligence for market entry, niche expansion, or competitive benchmarking.
Post-Sale Assistance
Dedicated coordination to help interpret findings and address queries post-delivery.
Cutting-Edge Methods
Structured data collection, advanced analytics, and expert validation for reliable forecasts.
Value for Investment
Credible, structured intelligence at a cost that makes strategic sense.
What Our Clients Say
My team needed the real numbers on AI spending for our Reinvention Services work. MarkWide delivered. No fluff, just a clear look at where the money is actually going. It saved us about three weeks of guesswork.
Accenture
We recently leaned on MarkWide Research for a deep dive into the evolving snacking habits within Southeast Asia. Their report on the premium biscuit segment was exceptionally detailed, providing us with the specific consumer sentiment data we needed to refine our regional flavor strategy. It wasn't just a data dump; the cultural nuances they captured helped us avoid several localization pitfalls.
Mondelez
Director of Global Consumer Insights
For a recent engagement in the automotive sector, we needed rigorous, independent verification of EV battery recycling capacities. MWR delivered a report that made our work easier. Their ability to segment the competitive landscape by chemical composition and regional throughput was exactly the kind of 'hard-to-find' intel that our team was looking for.
BCG
We were looking for a report on Xcelerator ecosystem's potential and got in touch with MarkWide's team through one of my old colleagues who worked with them in the past. Their research team was incredibly polite and were always available for us which was important for my team as this was a custom project. Their methodology for tracking industrial IoT adoption gave our R&D heads the clarity needed to prioritize our next-gen sensor development.
Siemens
Head of Industrial Digitalization
During a recent M&A project, we needed a fast, reliable breakdown of the Fintech landscape in Southeast Asia. MarkWide came through with a report that was actually readable and focused on the metrics that matter. It saved my team a good week of primary research, which, given our timelines, was a massive win.
KPMG
Advisory Partner
We tapped MarkWide Research for a deep dive into the ESG reporting software market. At Deloitte, our clients expect us to have the most current insights, and this report didn't disappoint. It provided a breakdown of the competitive field that was far more detailed than what we were expecting.
Deloitte
Lead Consultant, Sustainability Services
For our semiconductor division at Samsung, the supply chain forecast from MarkWide was incredibly useful. It provided a realistic outlook on raw material availability that helped us refine our production timelines. No fluff, just the data we needed to make a tough call.
Samsung
The value for our organization comes from three things: depth of research, specificity of segments and being easy to work with. As important as the first two are, the third can't be underestimated. MarkWide Research, maybe more than any other research vendor, wants to know what is top of mind for our team and what big questions we are grappling to answer. Their customer first approach and high value engagement model have given us great analysis and excellent value for money.
3M
I can share that it was a positive experience wherein MarkWide Research demonstrated flexibility to adapt to our needs and delivered an excellent report that fits all our requirements. Personally, I liked the timely follow up by the team and we will definitively reach out in case more research support is required.
VITO
Related Reports
Biofuels
Europe Biodiesel Market
Biofuels
Rotating Machines for Biofuels Market
Biofuels
United States Biodiesel Market
Biofuels
Europe Biofuel Market
Biofuels
Global Bioliquid Heat and Power Generation Market
Biofuels
Biodiesel Market
Biofuels
Second Generation Biofuels Market
Biofuels
Global Advanced Biofuel Market
Biofuels
Sweet Sorghum Ethanol Market
Biofuels
Brazil Biofuel Market
Biofuels
Bioethanol Market
Biofuels
Europe Advanced Biofuel Market
Biofuels
Latin America Biodiesel Market
Biofuels
GCC Algae Biofuel Prospects Market
Biofuels
Next Generation Biofuels Market
Biofuels
Biofuels Market